
 Wireless Phone Chargers Market | 2026-2036
Wireless Phone Chargers Market Size, Share, and Industry Trends Forecast 2026-2036
Wireless Phone Chargers Market Outlook
China is tilting the supply base toward high-volume coil and ferrite substrate output for wireless power assemblies. Samsung Electronics Co., Ltd. leverages its Galaxy device ecosystem to anchor proprietary fast-charging pad sales across retail channels. Anker Innovations Technology Co., Ltd. competes on cost-engineered multi-coil designs that occupy the mid-tier accessory segment globally.
Wireless phone chargers transfer electrical energy via electromagnetic induction between a transmitter coil in a charging pad and a receiver coil in a handheld device, typically operating at frequencies between 110-205 kHz for Qi-compliant systems with power outputs ranging from 5W to 50W. Fast chargers command premium positioning as smartphone OEMs embed higher-wattage receivers, while multi-device chargers capture expanding household and workspace deployments where consumers power phones, earbuds, and watches simultaneously. Solar chargers remain a niche segment constrained by panel efficiency and form-factor limitations in portable applications.
The FCC in the United States regulates radio-frequency emissions from wireless charging equipment under Part 15 rules, while the EU Radio Equipment Directive and CE marking framework govern electromagnetic compatibility and safety standards for products sold across member states. China's MIIT administers radio transmission approvals under GB standards that align with international Qi specifications but impose additional national testing protocols. Stakeholders must monitor evolving interoperability standards between Qi and AirFuel as OEMs weigh proprietary fast-charge protocols against universal compatibility investments.
Market Dynamics
Automotive integration of Qi pads into vehicle center consoles is pulling coil assembly demand toward tier-one automotive suppliers, compressing lead times and forcing charger OEMs to qualify under AEC-Q200 stress-test protocols.
Growth Catalysts
- EU Radio Equipment Directive:The electromagnetic compatibility mandate for wireless power transmitters sold across member states is accelerating certification investments by pad manufacturers seeking unified market access.
- Multi-device household penetration:Consumers now power phones, earbuds, and watches simultaneously, expanding addressable unit volumes for multi-coil charging stations in residential and workspace deployments.
- Ferrite substrate concentration:China's dominance in high-volume coil and ferrite output is driving procurement scale economies for global pad assemblers.
Market Restraints
- Copper and ferrite price volatility:Coil winding and magnetic shielding materials face commodity swings that compress margin buffers for mid-tier accessory producers.
- Single-source geography risk:Over-dependence on East Asian ferrite substrate foundries exposes supply continuity to regional logistics disruptions.
- AirFuel interoperability friction:The competing resonant charging standard fragments R&D investment and confuses consumer purchasing decisions.
Strategic Opportunities
- India manufacturing incentives:The PLI scheme for electronics assembly offers tariff advantages for pad producers establishing coil-winding operations in Gujarat and Tamil Nadu.
- Healthcare device integration:FDA-cleared portable medical monitors are embedding wireless receivers, opening regulated channels with premium pricing tolerance.
- Retail channel unbundling:Direct-to-consumer brands are bypassing big-box electronics chains through subscription bundling with smartphone trade-in programs.
Industry Challenges
- RF engineer scarcity:Coil design optimization for multi-device magnetic field management requires specialized electromagnetic simulation expertise that competes with 5G base station projects.
- Qi certification backlog:The Wireless Power Consortium's test lab queue extends fulfillment timelines for new product introductions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Wireless Phone Chargers Market |
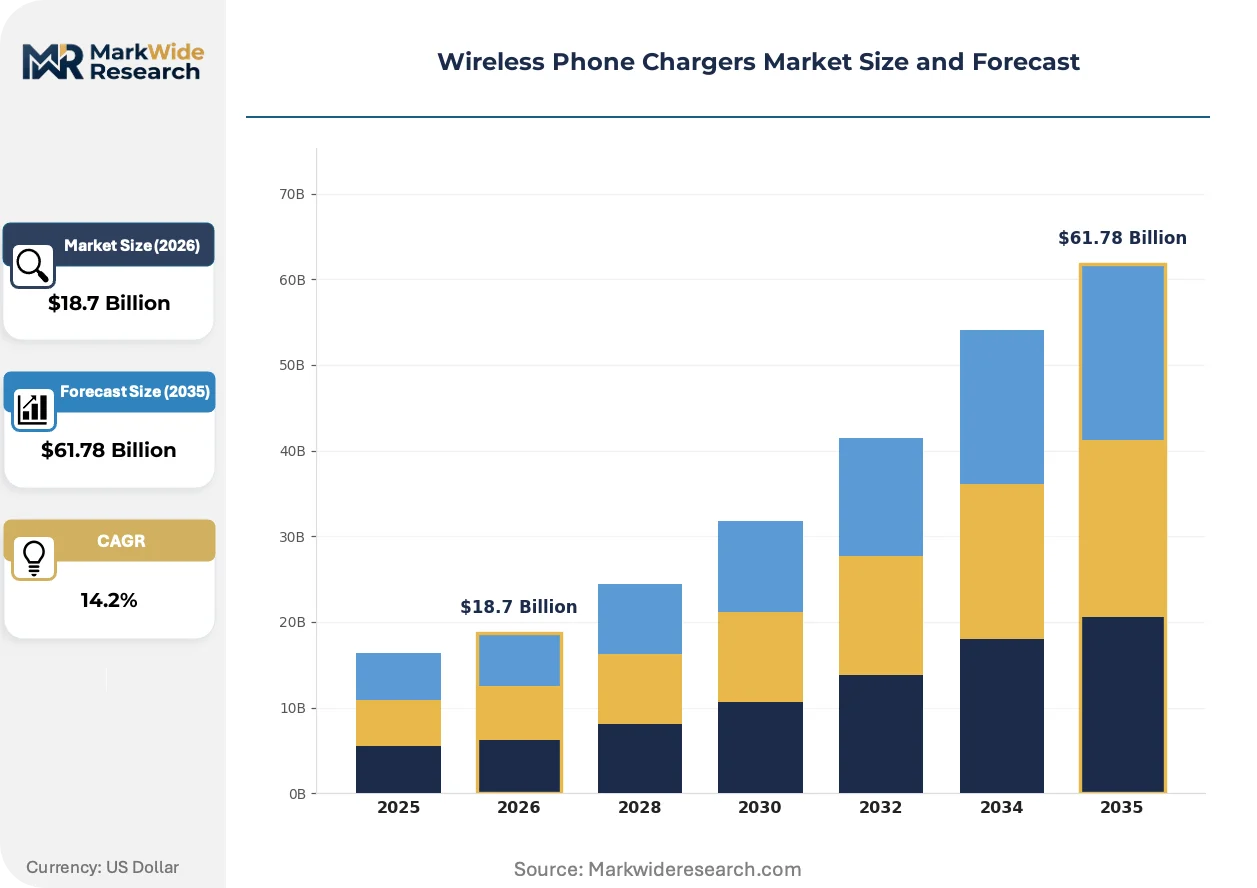
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $61.78 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Standard Chargers, Fast Chargers, Solar Chargers, Multi-Device Chargers Technology: Qi, Powermat, Rezence, AirFuel End User: Residential, Commercial, Industrial, Retail Distribution Channel: Online Retailers, Specialty Stores, Supermarkets, Direct Sales |
| Companies Covered | Samsung Electronics Co., Ltd., Apple Inc., Qualcomm Incorporated, Texas Instruments, Inc., Sony Corporation, Belkin International, Inc., Powermat Technologies Ltd., WiTricity Corporation, Anker Innovations Technology Co., Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Wireless Phone Chargers Market Strategic Shifts
Magnetic alignment systems and adaptive frequency tuning are compressing charging inefficiencies while regulatory pressure on electromagnetic emissions intensifies design constraints across all power tiers.
GaN semiconductors in transmitter power stages are digitizing thermal management and conversion efficiency in 50W-class fast chargers. Samsung and Apple ecosystem buyers are adopting these designs at premium price points. The shift is digitizing what previously required analog compensation networks into software-configurable power profiles.
China's MIIT is tightening GB standard radio transmission approvals for wireless power equipment, adding national electromagnetic field exposure tests beyond baseline Qi certification. Domestic pad manufacturers are absorbing six-to-eight week additional approval cycles. The policy most affects exporters targeting both Chinese consumer retail and automotive OEM supply chains.
Enterprise procurement teams are consolidating vendor relationships for workspace charging furniture, replacing fragmented IT accessory purchasing with facility-wide installation contracts. Steelcase and Herman Miller distribution channels are capturing this spend. North American corporate campus retrofits represent the most visible geography for this consolidation pattern.
Wireless Phone Chargers Market Segmentation
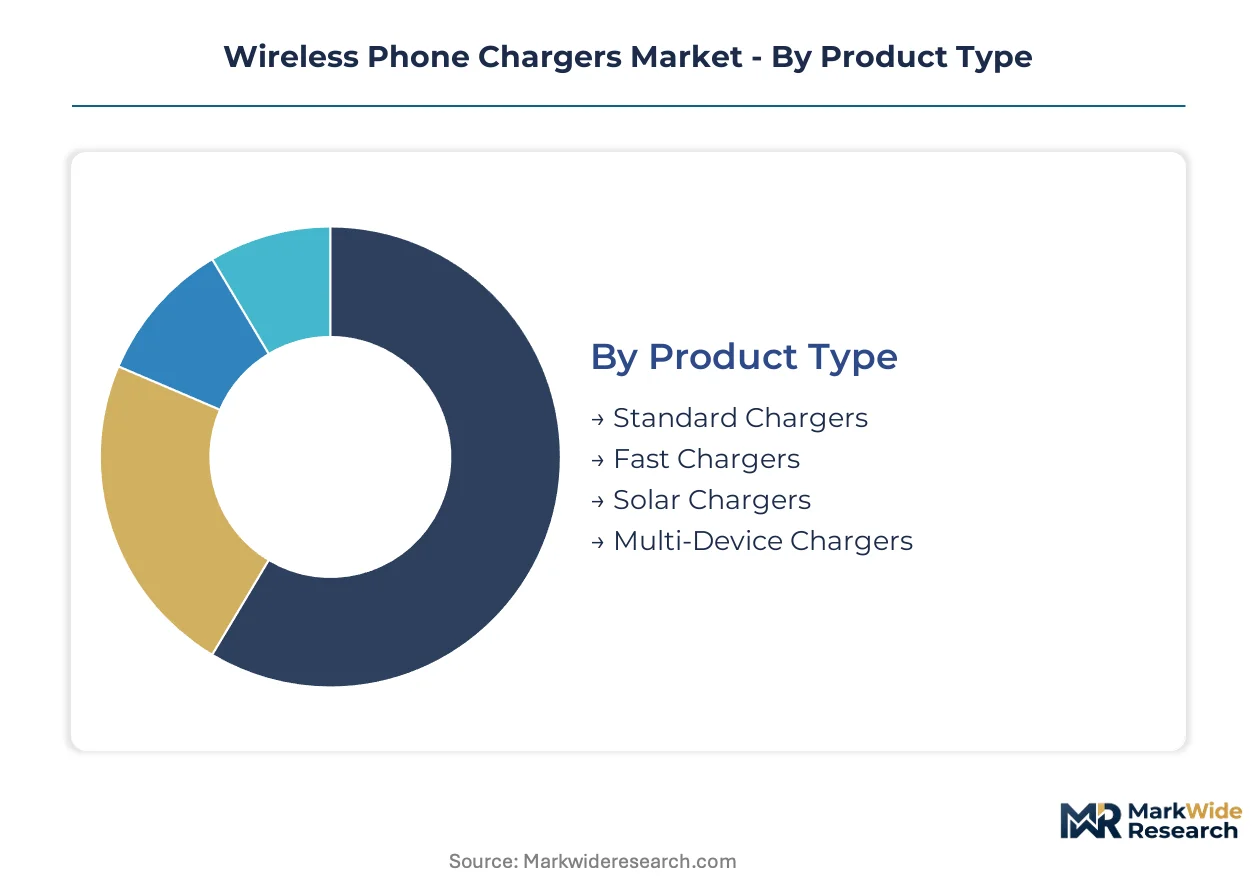
Wireless phone charger segmentation reveals how power output specifications, protocol standards, and procurement channels partition revenue streams. Manufacturers calibrate coil designs and certification investments differently across each dimension.
Product Type:
Cost tier differentiation separates commodity pads from premium thermal-managed systems with active cooling.
- Fast Chargers:GaN power stages and adaptive frequency tuning enable 50W output with controlled thermal profiles. Samsung and Apple ecosystem buyers absorb premium pricing for these designs. Magnetic alignment systems reduce placement sensitivity in vehicle console integrations.
- Multi-Device Chargers:Three-coil arrays with independent field management power phones, earbuds, and watches simultaneously. Workspace furniture procurement teams specify these for corporate campus retrofits in the United States.
- Standard Chargers:5W-15W Qi baseline designs dominate retail accessory shelves with minimal margin buffers.
- Solar Chargers:Panel efficiency constraints limit adoption to outdoor recreation niches with extended off-grid requirements.
Fast chargers hold installed capacity. Multi-device chargers are rotating up the share rankings.
Technology:
Protocol maturity determines interoperability investment requirements and certification queue positioning.
- Qi:The Wireless Power Consortium's 110-205 kHz induction specification commands universal smartphone OEM integration. FCC Part 15 and EU Radio Equipment Directive compliance frameworks anchor around Qi test protocols.
- AirFuel:Resonant charging at 6.78 MHz enables spatial freedom but fragments R&D budgets with competing coil architectures.
- Powermat:Early coffee shop and furniture deployments persist in legacy hospitality infrastructure.
- Rezence:Magnetic resonance variants from the AirFuel Alliance face Qi certification backlog advantages.
Qi maintains protocol dominance. AirFuel is climbing the fastest as automotive OEMs evaluate spatial freedom benefits.
End User:
Customer type dictates volume scale, pricing tolerance, and regulatory exposure thresholds.
- Residential:Individual consumers purchase single-pad and multi-device stations through Amazon and direct-to-consumer channels. Subscription bundling with smartphone trade-in programs is capturing this segment.
- Commercial:Steelcase and Herman Miller distribution channels supply workspace charging furniture to North American corporate campuses under facility-wide installation contracts.
- Industrial:Ruggedized pads with IP ratings serve manufacturing floor deployments where dust and moisture exposure require sealed coil housings.
- Retail:Electronics chains and carrier stores position impulse-purchase pads adjacent to smartphone displays with minimal sales assistance.
Commercial contracts anchor enterprise revenue. Residential direct-to-consumer is expanding most quickly through ecosystem bundling.
Distribution Channel:
Channel selection determines margin capture and brand control intensity for pad manufacturers.
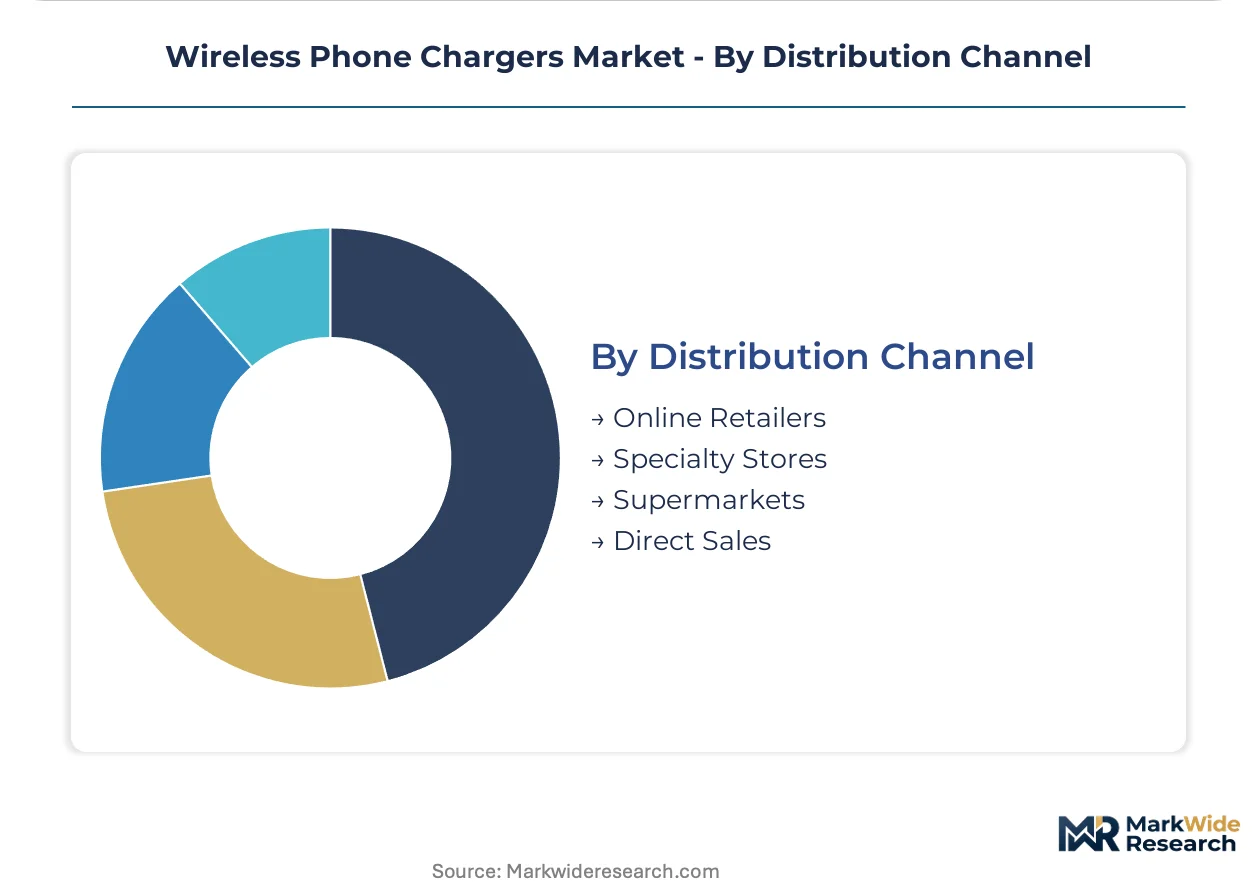
- Online Retailers:Amazon and Alibaba platforms aggregate mid-tier accessory brands with algorithmic search placement determining visibility. Anker competes here on cost-engineered multi-coil designs.
- Specialty Stores:Electronics chains like Best Buy and MediaMarkt provide tactile evaluation environments for premium fast-charger demonstrations.
- Supermarkets:Mass merchandisers stock commodity 5W pads as impulse purchases with minimal technical differentiation.
- Direct Sales:Samsung's Galaxy ecosystem anchors proprietary fast-charging pad sales through owned retail and carrier partnerships.
Online retailers hold installed capacity. Direct sales is rotating up the share rankings through ecosystem lock-in strategies.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
MIIT's GB standard radio transmission approvals in China create the regulatory baseline that other jurisdictions reference for electromagnetic field exposure testing. The EU Radio Equipment Directive and FCC Part 15 rules in the United States establish parallel compliance frameworks that manufacturers must navigate simultaneously. Coil assembly procurement and ferrite substrate sourcing concentrate in specific industrial clusters across four major economies.
United States
Automotive OEMs in Detroit and Silicon Valley are embedding Qi pads into vehicle center consoles, pulling coil demand toward tier-one suppliers. The FCC regulates radio-frequency emissions under Part 15 rules with specific absorption rate testing for consumer devices. Austin and Dallas semiconductor clusters are producing GaN power stages for 50W-class fast chargers with software-configurable thermal profiles.
China
Shenzhen and Dongguan electronics assemblers dominate high-volume coil winding and ferrite substrate output for global pad manufacturers. MIIT administers GB standard radio transmission approvals with additional electromagnetic field exposure tests beyond baseline Qi certification. The Yangtze River Delta manufacturing belt is absorbing six-to-eight week approval cycle extensions for domestic pad producers targeting automotive OEM supply chains.
Germany
Automotive suppliers in Stuttgart and Munich are qualifying coil assemblies under AEC-Q200 stress-test protocols for vehicle console integrations. The EU Radio Equipment Directive mandates electromagnetic compatibility testing for all wireless power transmitters sold across member states. The Baden-Württemberg industrial corridor is compressing lead times for tier-one suppliers serving premium vehicle manufacturers.
India
Electronics manufacturers in Gujarat and Tamil Nadu are establishing coil-winding operations under the PLI scheme for assembly tariff advantages. The country's national electronics regulator administers radio equipment approvals aligned with international Qi specifications. The Delhi-NCR corridor is emerging as a procurement hub for mid-tier accessory brands supplying South Asian retail channels.
South Korea
Seoul-based device OEMs are anchoring proprietary fast-charging pad sales through ecosystem lock-in strategies. The national radio regulator enforces electromagnetic compatibility standards that mirror FCC and EU frameworks with additional local testing protocols. The Busan-Ulsan manufacturing belt is shipping multi-coil designs for Galaxy device ecosystem bundling across Asia-Pacific retail channels.
Wireless Phone Chargers Market Competitive Environment
Capability concentration sits with one tier; scale advantage sits with another, creating a bifurcated structure where GaN power stage designers and high-volume coil assemblers occupy distinct competitive positions. The vendor base separates into ecosystem-locked premium brands, cost-engineered mid-tier specialists, and automotive-qualified tier-one suppliers. Three strategic archetypes dominate: proprietary protocol anchors, multi-coil commodity assemblers, and resonant charging technology licensors. Capacity expansion in Indian PLI zones and strategic partnerships between semiconductor foundries and pad OEMs represent the dominant competitive moves.
Within the ecosystem-locked tier, Samsung Electronics Co., Ltd. and Apple Inc. occupy positions that exemplify proprietary fast-charge protocol strategies. Anker Innovations Technology Co., Ltd. represents the cost-engineered mid-tier archetype competing on multi-coil design efficiency. These three entities anchor the competitive structure without exhaustively mapping the vendor landscape.
| Leading Market Players |
|---|
| Samsung Electronics Co., Ltd. |
| Apple Inc. |
| Qualcomm Incorporated |
| Texas Instruments, Inc. |
| Sony Corporation |
| Belkin International, Inc. |
| Powermat Technologies Ltd. |
| WiTricity Corporation |
| Anker Innovations Technology Co., Ltd. |
| Others |
Value Chain & Pricing Dynamics
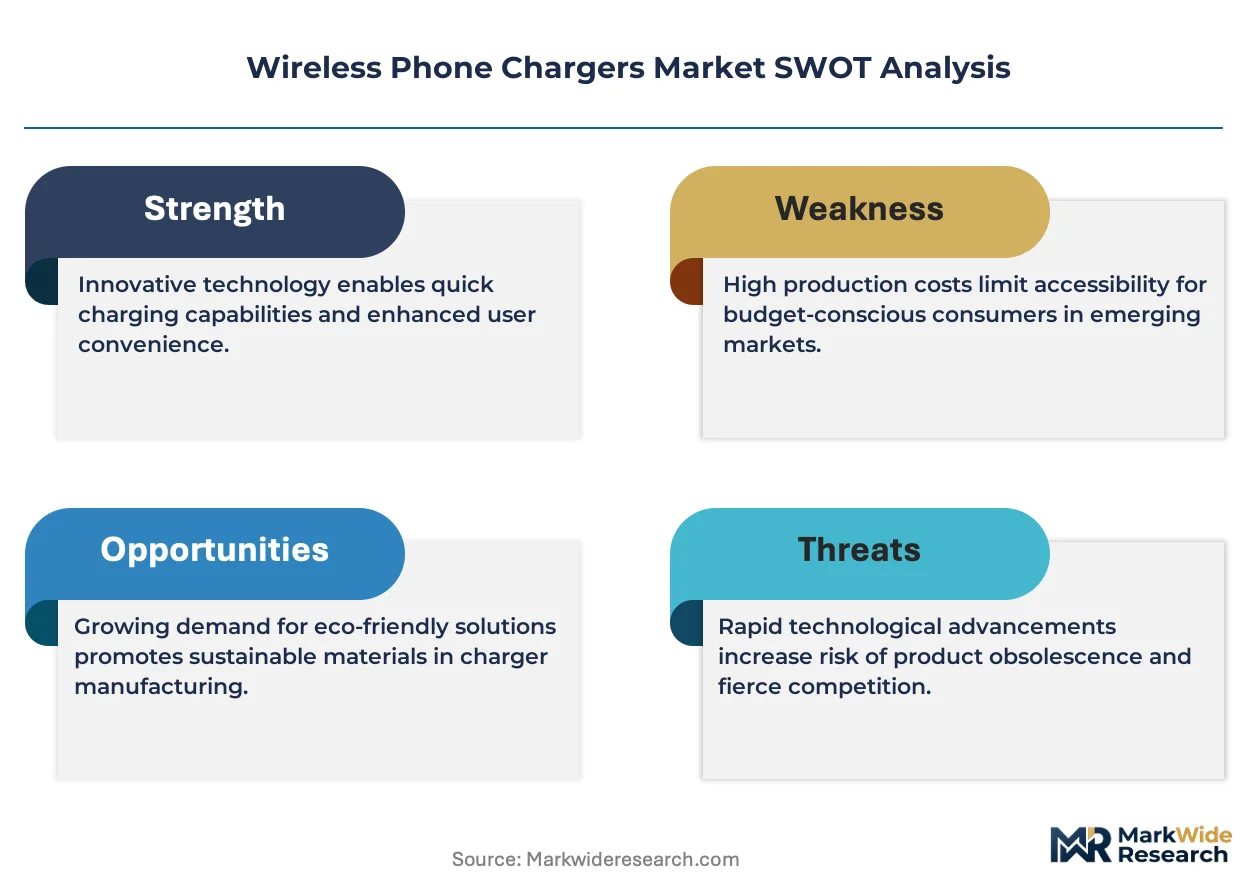
Single-source geography risk in East Asian ferrite substrate foundries determines both pricing tier spreads and supply chain shape, compressing margin buffers for mid-tier accessory producers while forcing premium brands toward captive coil sourcing or automotive qualification investments.
Pricing Analysis
Chinese-manufactured pads command 30-40% price discounts against German and South Korean equivalents due to ferrite substrate cost advantages and labor arbitrage in Shenzhen-Dongguan clusters. Three-tier pricing structure across premium, standard, and economy levels separates GaN-enabled 50W fast chargers with active cooling from baseline 5W-15W Qi pads and commodity unbranded units. Pricing pressure stems from copper and ferrite commodity volatility that erodes mid-tier producer margins. Residential direct-to-consumer buyers exhibit highest price sensitivity, while automotive OEM procurement teams absorb premium positioning for AEC-Q200 qualified assemblies.
Supply Chain Analysis
Export-control regimes on semiconductor manufacturing equipment constrain GaN power stage flows from US and Dutch suppliers into Chinese pad assemblers, fragmenting procurement strategies. Coil winding and ferrite substrate production concentrate in China, South Korea, and Taiwan, with India emerging under PLI scheme incentives. Raw material dependencies center on copper magnet wire, manganese-zinc ferrite cores, and GaN-on-silicon wafers. Single-source vulnerability in Yangtze River Delta ferrite foundries exposes continuity to regional logistics disruptions. Distribution runs through Amazon and Alibaba platforms for mid-tier brands, Samsung-owned retail for ecosystem-locked premium units, and Steelcase-Herman Miller channels for workspace furniture contracts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is shifting toward consolidated enterprise procurement teams replacing fragmented IT accessory purchasing with facility-wide installation contracts, fragmenting pricing power among charger OEMs.
For Market Incumbents: Build certification moats around Qi and automotive AEC-Q200 qualifications to defend against emerging multi-coil commodity assemblers from India. Deepen backward integration into ferrite substrate sourcing or establish captive coil-winding operations in Gujarat PLI zones to offset East Asian supply concentration risk. Channel control through direct-to-consumer subscription bundling with smartphone trade-in programs anchors ecosystem lock-in against Anker's algorithmic search placement dominance on Amazon. For New Entrants and Emerging Players: Establish a beachhead in healthcare device integration where FDA-cleared portable medical monitors embed wireless receivers, opening regulated channels with premium pricing tolerance absent in saturated consumer retail. Target India's Delhi-NCR corridor as the most penetrable geography for mid-tier accessory brands supplying South Asian retail channels. A go-to-market angle through hospital system partnerships for clinical-grade charging furniture bypasses big-box electronics chain gatekeeping. For Investors and Strategic Acquirers: The market sits at a standardization-consolidation phase that favors automotive-qualified tier-one suppliers over undifferentiated pad assemblers. Long-term viability across the next decade hinges on GaN power stage design capability and multi-device magnetic field management expertise. Acquisition target archetypes include coil design houses with electromagnetic simulation talent competing against 5G base station projects for RF engineers. The signal to watch is Qi certification backlog duration at Wireless Power Consortium test labs as an indicator of new product introduction velocity.| Strategic Initiative | Industry Significance |
|---|---|
| GaN Power Stage Integration | Samsung and Apple ecosystem buyers absorb premium pricing for software-configurable thermal profiles. |
| Automotive AEC-Q200 Qualification | Tier-one suppliers in Stuttgart and Munich compress lead times for vehicle console integrations. |
| India PLI Manufacturing Footprint | Gujarat and Tamil Nadu coil-winding operations capture tariff advantages for global pad assemblers. |
| Healthcare Device Partnership | FDA-cleared portable medical monitors open regulated channels with premium pricing tolerance. |
| Direct-to-Consumer Subscription Bundling | Smartphone trade-in programs bypass big-box electronics chains for ecosystem lock-in. |
Study Parameters
Demand-side practitioners and supply-side operators were both consulted across primary interview programs with automotive OEM procurement managers, tier-one coil assembly suppliers, retail channel category buyers, and RF design engineers at pad manufacturers. Secondary validation drew from FCC Part 15 equipment authorization databases, EU Radio Equipment Directive notification files, Wireless Power Consortium certification registries, and MIIT GB standard approval records. Bottom-up coil shipment estimates from Shenzhen and Dongguan assemblers were triangulated against top-down automotive electronics content forecasts and consumer accessory retail audit data.
Calibration against historical Qi certification volumes and GaN power stage penetration rates anchored the analytical framework across the projection horizon. Segmentation dimensions modeled include product type tier, protocol standard, end-user category, and distribution channel intensity. CAGRs were derived from installed base growth assumptions for multi-device household penetration and automotive integration rates. Industry-specific forecast inputs center on copper and ferrite commodity price trajectories and Wireless Power Consortium test lab capacity expansion plans.
Stress conditions across raw material cost spikes, regional logistics disruptions, and protocol standard fragmentation were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions around Qi-AirFuel interoperability evolution and MIIT approval cycle durations. Cross-checking against automotive OEM electronics procurement disclosures and hyperscaler smartphone ecosystem bundling announcements is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Wireless Technologies
Industrial Wireless Transmitter Market
Wireless Technologies
North America in-Building Wireless Market
Wireless Technologies
Wigig Market
Wireless Technologies
Public Safety Wireless Communication and Municipal Wireless Communication Market
Wireless Technologies
Multefire Market
Wireless Technologies
Fixed LTE Wireless Broadband Market
Wireless Technologies
Mobile Signal Booster Market
Wireless Technologies
Voice Over Wifi Market
Wireless Technologies
Wireless Smart Home Market
Wireless Technologies
Optical Wireless Communication and Li-Fi Market
Wireless Technologies
LTE and 5G Market
Wireless Technologies
Global Bluetooth Audio Codec Market
Wireless Technologies
APAC Small Cell 5G Market
Wireless Technologies
Wireless Paging Systems Market
Wireless Technologies
Asia-Pacific Wi-Fi 6 Market
Wireless Technologies
Light Fidelity Market