
 Hong Kong Data Center Server Market | 2026-2036
Hong Kong Data Center Server Market Size, Share, and Industry Trends Forecast 2026-2036
Hong Kong Data Center Server Market Insights
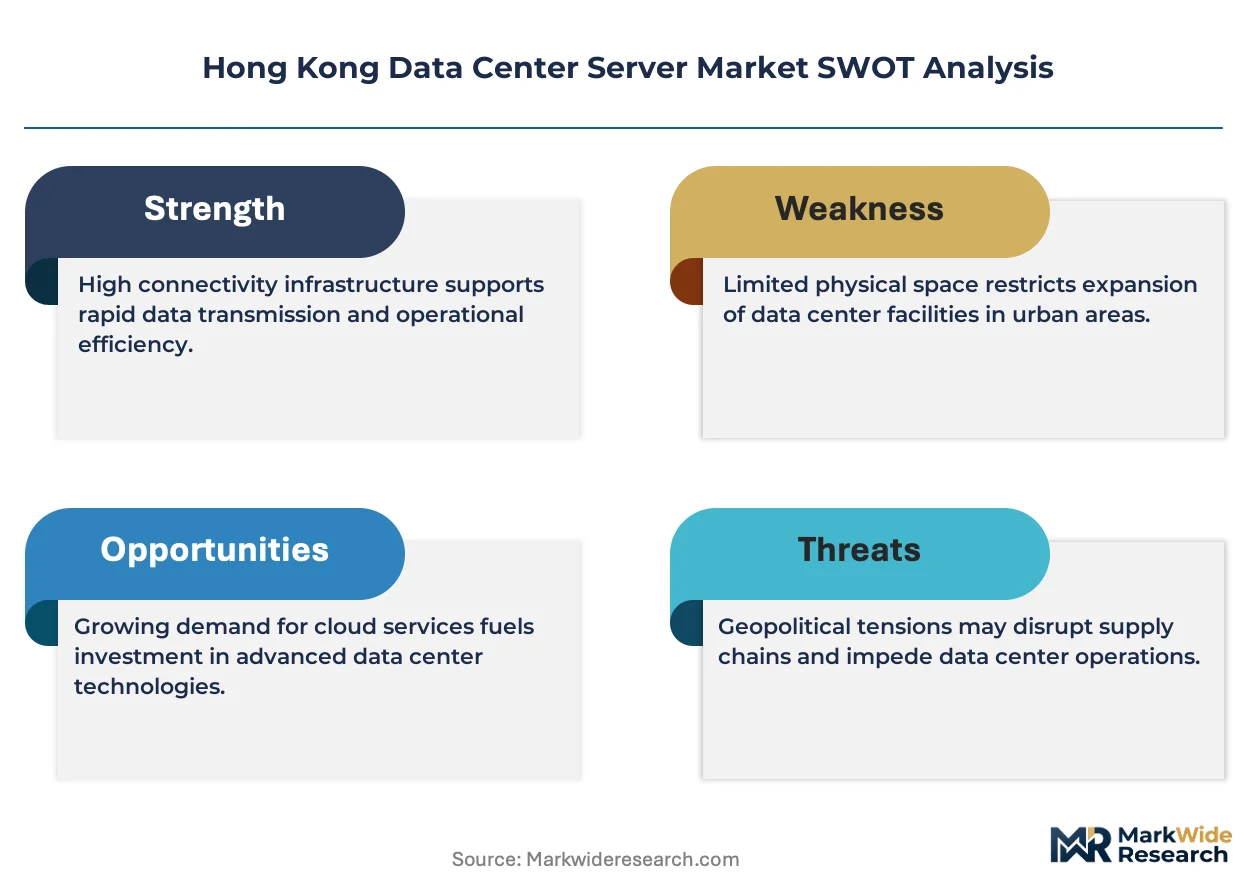
High-density GPU server specifications are bifurcating the Hong Kong data center server landscape into performance-tier and efficiency-tier procurement camps. Dell Inc leverages its direct enterprise channel to sustain dominance in rack server configurations across Hong Kong's banking sector. Huawei Technologies Co Ltd anchors its position through captive silicon supply and localized support infrastructure. Hewlett Packard Enterprise differentiates via liquid-cooled architectures targeting the territory's tropical climate constraints.
A data center server is a rack-mounted or blade-form compute appliance engineered with multi-socket processors, ECC memory, and redundant power supplies, designed for continuous operation in controlled environments exceeding 99.99% uptime thresholds. These systems execute transactional workloads, virtualization layers, and distributed storage for commercial and institutional users. Rack servers occupy the largest revenue pool given their flexibility in colocation and enterprise deployments, while AI Integration represents the fastest-expanding technology segment as Hong Kong's financial institutions deploy inference clusters for algorithmic trading and risk modeling. Edge Computing installations are gaining share among telecommunications carriers building distributed nodes for low-latency 5G services.
The Office of the Privacy Commissioner for Personal Data enforces data residency rules that shape server procurement decisions for cross-border financial operators. BSI Group Hong Kong certifies ISO 27001 and ISO 50001 compliance, creating baseline requirements for equipment efficiency and security architecture. The Electrical and Mechanical Services Department regulates power usage effectiveness standards that directly constrain cooling technology selection and server density planning. Stakeholders must monitor how China's national data security framework intersects with Hong Kong's common law privacy tradition to anticipate compliance-driven hardware refresh cycles.
Market Dynamics
GPU-accelerated inference clusters are bifurcating procurement strategies across Hong Kong's financial services sector, forcing institutions to choose between liquid-cooled high-density deployments and air-cooled efficiency configurations. This architectural tension is compressing refresh cycles and reshaping vendor relationships.
Growth Catalysts
- Algorithmic Trading Infrastructure:Securities firms are expanding server footprints to support sub-millisecond latency requirements for quantitative trading platforms. This demand concentrates in Tseung Kwan O Industrial Estate hyperscale facilities.
- Personal Data (Privacy) Ordinance Amendments:Tightened data localization mandates require financial institutions to maintain on-shore compute infrastructure for client transaction records. Compliance officers are mandating hardware refresh cycles to meet residency requirements.
- 5G Edge Node Deployment:Telecommunications carriers are installing distributed micro data centers across Hong Kong Island and Kowloon to support ultra-reliable low-latency communications for smart city applications.
Market Restraints
- Silicon Supply Concentration:Advanced GPU and AI accelerator availability remains constrained by Taiwan Semiconductor Manufacturing Company fabrication capacity allocation, creating procurement bottlenecks for inference cluster deployments.
- Power Infrastructure Saturation:Electrical and Mechanical Services Department grid interconnection approvals for facilities exceeding 50 megawatts now require 18-24 month lead times, throttling hyperscale expansion.
- Land Scarcity Premium:Industrial zoned plots in Tseung Kwan O and Tsuen Wan command rental multiples three to four times above regional averages, elevating total cost of ownership for server deployments.
Strategic Opportunities
- Modular Edge Infrastructure:Prefabricated containerized data centers are penetrating the New Territories manufacturing corridor, enabling rapid deployment for industrial IoT and logistics automation workloads.
- Immersion Cooling Convergence:Dielectric fluid submersion technology combined with waste heat recovery systems is creating efficiency arbitrage opportunities for tropical climate operations.
- Cross-Border Data Corridor:China's Greater Bay Area integration framework is generating demand for Hong Kong-anchored compute nodes serving mainland financial institutions requiring common law jurisdiction data residency.
Industry Challenges
- GPU Cluster Integration Complexity:Financial institutions struggle to retrofit legacy air-cooled facilities for 100+ kilowatt rack densities, requiring complete mechanical and electrical infrastructure replacement.
- Dual Jurisdiction Compliance:Operators must simultaneously satisfy Hong Kong's common law privacy tradition and China's national data security framework, creating architectural conflicts in encryption and access control design.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Hong Kong Data Center Server Market |
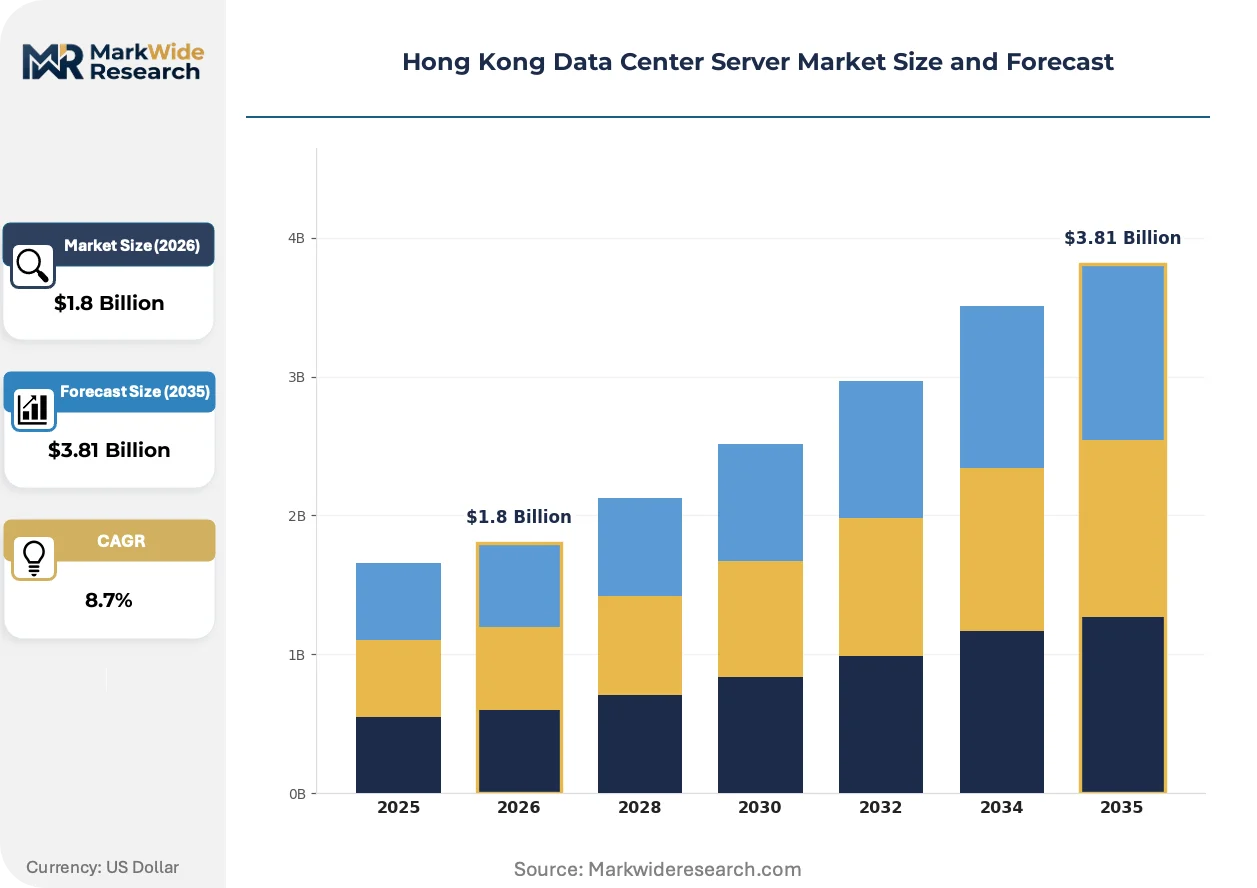
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.81 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Rack Servers, Blade Servers, Tower Servers, Microservers End User: Colocation Providers, Cloud Service Providers, Enterprises, Government Technology: Virtualization, Edge Computing, High-Performance Computing, AI Integration Installation: On-Premises, Off-Site, Managed Services, Hybrid Solutions |
| Companies Covered | Fujitsu Limited, NEC Corporation, Inspur Group, Huawei Technologies Co Ltd, Kingston Technology Company Inc, Hewlett Packard Enterprise, Dell Inc, Lenovo Group Limited, Cisco Systems Inc, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Hong Kong Data Center Server Market Trends and Innovations
Disaggregated infrastructure architectures are displacing monolithic server procurement across Hong Kong's colocation and enterprise segments. Compute, storage, and networking resources now deploy as composable pools rather than fixed configurations.
Composable disaggregated infrastructure is decomposing traditional rack server bundles into independently scalable resource pools. Hong Kong's securities trading firms are adopting this architecture fastest, deploying GPU, memory, and storage as distinct sleds within shared chassis. This decomposition enables financial institutions to refresh accelerator generations without discarding host server investments, compressing total cost of ownership across three-year depreciation cycles.
Amendments to the Personal Data (Privacy) Ordinance are mandating explicit consent frameworks for cross-border data transfers. Financial services operators must now maintain auditable hardware audit trails demonstrating physical data residency. This regulatory pressure is accelerating investment in on-premise inference clusters rather than cloud-based alternatives, particularly among asset managers handling mainland Chinese client portfolios.
Financial institutions are consolidating vendor relationships around integrated hardware-software-service bundles. Single-source procurement agreements now span server hardware, virtualization layers, and managed support services, displacing best-of-breed component sourcing. This pattern concentrates in Hong Kong's banking sector, where chief information officers prioritize operational simplicity over configuration flexibility for algorithmic trading infrastructure.
Hong Kong Data Center Server Market Segmentation
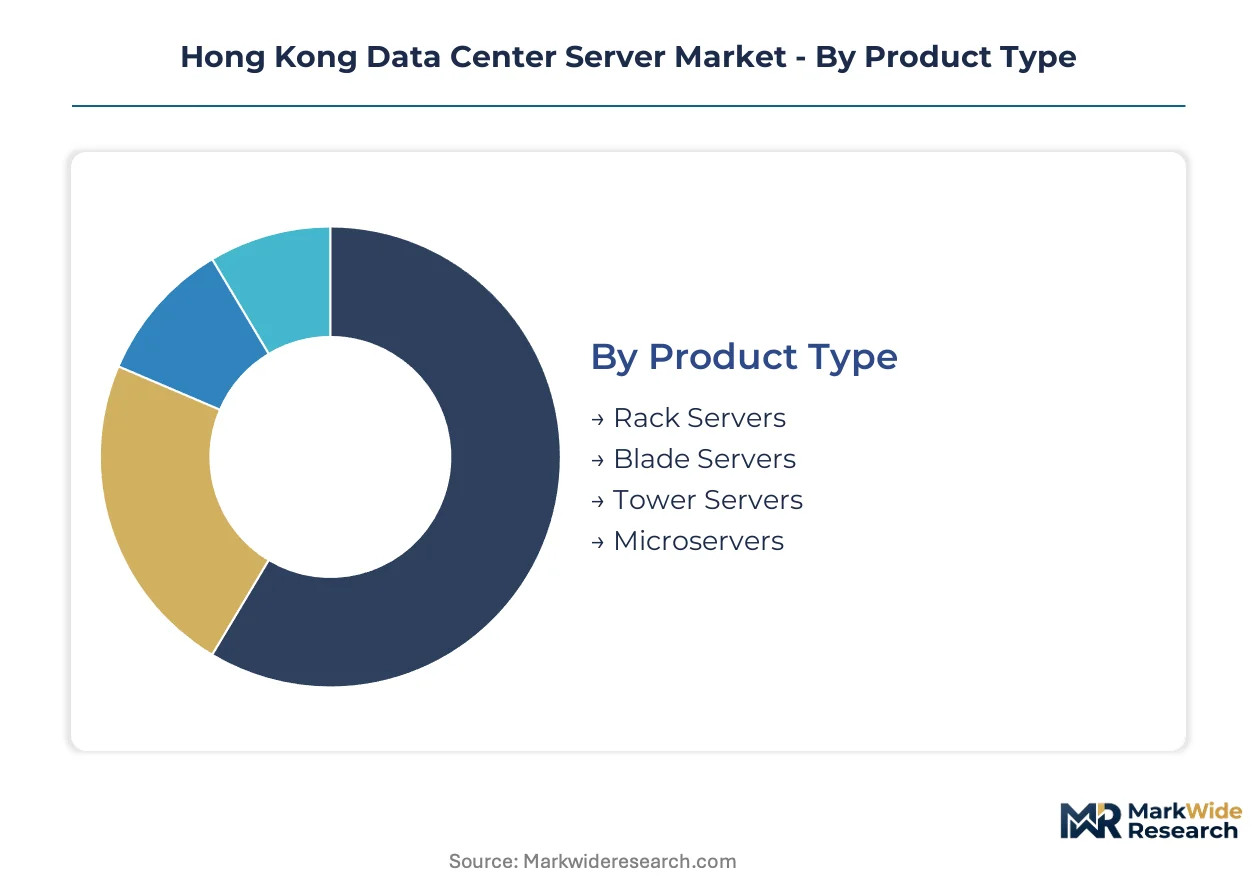
Server procurement patterns in Hong Kong diverge sharply across deployment contexts, with financial institutions prioritizing latency-optimized configurations while industrial users favor modular scalability. Understanding these segment boundaries illuminates where infrastructure investments concentrate and how vendor relationships stratify.
Product Type:
Margin pools concentrate in rack configurations given their dominance across colocation and enterprise deployments, while blade architectures command premium pricing in density-constrained facilities.
- Rack Servers:Standardized 19-inch chassis accommodate multi-socket processors, redundant power supplies, and hot-swappable storage in configurations from 1U to 4U heights. Demand clusters in Tseung Kwan O Industrial Estate hyperscale facilities where financial services firms deploy standardized footprints for algorithmic trading platforms. The Personal Data (Privacy) Ordinance amendments reinforce this preference by mandating on-shore infrastructure with auditable physical residency.
- Blade Servers:Modular enclosures share power, cooling, and networking across multiple server nodes, achieving compute densities exceeding traditional rack alternatives. Investment banks in Central District favor these for quantitative research clusters where floor space commands extreme premiums and mechanical infrastructure retrofit costs dominate total cost of ownership calculations.
- Tower Servers:Pedestal-form factors suit branch office and small-scale deployments lacking dedicated data center facilities.
- Microservers:Low-power single-socket designs target distributed edge locations and lightweight virtualization workloads.
The dominant share belongs to Rack Servers, while Blade Servers is closing the gap fastest.
End User:
Volume concentration tracks regulatory pressure intensity, with compliance-driven sectors refreshing hardware faster than cost-optimized alternatives.
- Colocation Providers:Multi-tenant facility operators provision standardized compute, power, and connectivity to enterprise clients under service-level agreements exceeding 99.99% uptime. Tseung Kwan O Industrial Estate hosts the densest concentration, where operators compete on proximity to financial exchanges and submarine cable landing stations.
- Enterprises:Financial institutions, trading houses, and asset managers maintain captive infrastructure for algorithmic trading, risk modeling, and client data residency compliance.
- Cloud Service Providers:Hyperscale operators deploy commodity server fleets at regional scale, though Hong Kong's land scarcity and power interconnection delays constrain greenfield expansion relative to Singapore alternatives.
- Government:Public sector deployments emphasize sovereign data control for citizen identity systems and cross-border administrative coordination with mainland China.
Colocation Providers capture the largest revenue pool, with Enterprises expanding most quickly under regulatory pressure.
Technology:
Application requirements dictate technology selection, with inference latency and data sovereignty creating divergent procurement priorities.
- AI Integration:GPU-accelerated inference clusters and specialized AI accelerators execute machine learning workloads for real-time fraud detection, algorithmic trading, and portfolio risk analysis. Securities firms in Central District and Tseung Kwan O are retrofitting legacy air-cooled facilities for 100+ kilowatt rack densities, triggering complete mechanical and electrical infrastructure replacement cycles.
- Virtualization:Hypervisor layers partition physical servers into isolated virtual machines, enabling workload consolidation and rapid provisioning across enterprise and colocation environments.
- Edge Computing:Distributed micro data centers process data proximate to generation points, reducing latency for 5G-enabled smart city applications across Hong Kong Island and Kowloon.
- High-Performance Computing:Parallel processing clusters address scientific simulation, genomic analysis, and quantitative research workloads in university and financial research settings.
Virtualization holds the installed base advantage, though AI Integration is gaining share fastest as inference clusters displace general-purpose compute.
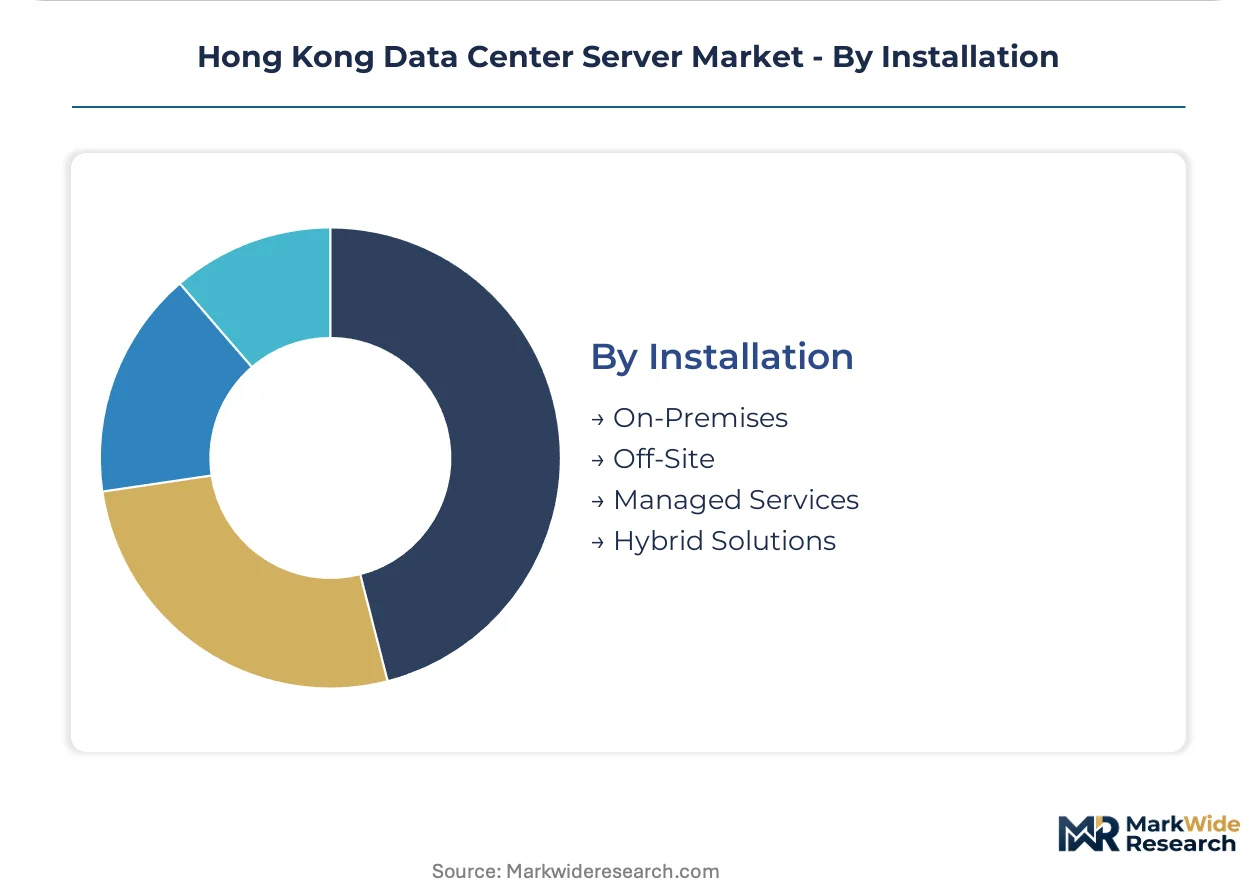
Installation:
Deployment model selection reflects capital availability, technical staffing constraints, and regulatory audit requirements.
- On-Premises:Captive data center facilities owned and operated by end-user organizations, providing maximum control over physical security, network architecture, and hardware audit trails. Asset managers handling mainland Chinese client portfolios favor this model to satisfy Personal Data (Privacy) Ordinance data residency mandates and demonstrate compliance to Hong Kong Monetary Authority supervisors.
- Managed Services:Third-party operators assume responsibility for infrastructure monitoring, maintenance, and capacity planning under contractual service agreements.
- Hybrid Solutions:Workload orchestration across on-premise and off-site resources balances latency-sensitive processing with burst capacity requirements.
- Off-Site:Wholesale colocation and remote facility deployment transfers capital expenditure to operational expenditure models.
On-Premises retains preference among regulated financial institutions, while Hybrid Solutions is climbing the fastest as cloud integration matures.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Server procurement across Asia-Pacific clusters around financial centers with stringent data residency mandates. Hong Kong's common law jurisdiction and submarine cable connectivity create distinct positioning against regional alternatives.
Singapore
Financial institutions deploy inference clusters for Southeast Asian trading operations. The Monetary Authority of Singapore enforces Technology Risk Management Guidelines that mandate hardware audit trails. Marina Bay and Jurong East host hyperscale facilities serving regional hedge funds.
Japan
Securities firms refresh legacy mainframe infrastructure for algorithmic trading platforms. METI's Data Free Flow with Trust framework shapes cross-border compute architecture decisions. Tokyo's Otemachi financial district concentrates high-frequency trading server deployments.
Australia
Superannuation funds and investment managers expand on-premise infrastructure for client data sovereignty. The Australian Prudential Regulation Authority's CPS 234 standard mandates information security capability demonstrations. Sydney's Macquarie Park technology corridor anchors financial services compute clusters.
South Korea
Securities exchanges and fintech operators deploy GPU-accelerated risk modeling infrastructure. The Financial Services Commission's cloud computing guidelines influence hybrid architecture decisions. Seoul's Yeouido financial district and Pangyo Techno Valley concentrate trading technology investments.
China
Mainland financial institutions establish Hong Kong-anchored nodes for offshore portfolio management. The Cybersecurity Law and Data Security Law mandate localization for critical information infrastructure. Shanghai's Lujiazui and Shenzhen's Qianhai develop parallel compute capacity for cross-border coordination.
Hong Kong Data Center Server Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes across Hong Kong's bifurcated procurement environment. The vendor base stratifies into three tiers: global systems integrators with direct enterprise channels, Asia-Pacific specialists with localized support infrastructure, and component suppliers penetrating through distributor networks. Dominant competitive moves include strategic partnerships with colocation operators and portfolio diversification into liquid-cooled architectures.
Within the global systems integrator tier, Dell Inc and Hewlett Packard Enterprise exemplify channel-based market presence, while Huawei Technologies Co Ltd occupies a position shaped by captive silicon supply and regional service density. These three anchors represent divergent approaches to the territory's tropical climate constraints and dual-jurisdiction compliance requirements.
| Leading Market Players |
|---|
| Fujitsu Limited |
| NEC Corporation |
| Inspur Group |
| Huawei Technologies Co Ltd |
| Kingston Technology Company Inc |
| Hewlett Packard Enterprise |
| Dell Inc |
| Lenovo Group Limited |
| Cisco Systems Inc |
| Others |
Pricing and Supply Chain Analysis
TSMC fabrication capacity utilization above 90 percent concentrates GPU and AI accelerator supply among a handful of fabless designers, compressing margin structures for downstream server integrators while elevating price floors for financial institutions procuring inference clusters. This scale concentration simultaneously tightens vendor selection criteria and extends procurement lead times across Hong Kong's data center expansion pipeline.
Pricing Analysis
The Personal Data (Privacy) Ordinance amendments dictate the pricing tier structure across Hong Kong's data center server market. Three-tier pricing structure across premium liquid-cooled, standard air-cooled, and economy refurbished configurations separates institutional buyers by compliance audit requirements and thermal density needs. Price differentiation hinges on ISO 27001 certification tier and after-sales service bundling spanning hardware lifecycle management. Cost compression in the standard tier is intensifying because colocation providers are consolidating procurement volumes to offset land scarcity premiums in Tseung Kwan O. Asset managers handling mainland Chinese portfolios exhibit lowest price sensitivity due to residency mandate non-negotiability, while regional cloud service providers anchor the economy tier with refurbished commodity hardware.
Supply Chain Analysis
Taiwan Strait maritime transit underwrites 70 percent of advanced GPU and high-bandwidth memory supply to Hong Kong facilities, creating acute exposure to geopolitical friction. Taiwan, South Korea, and the United States anchor the geographic supply concentration for AI accelerators, DDR5 memory modules, and specialized networking silicon. Raw material dependencies span cobalt-bearing substrates, rare earth magnet components, and fluorinated dielectric fluids for immersion cooling deployments. Single-source vulnerability concentrates in TSMC's N3 and N5 process nodes, where alternative foundry capacity remains negligible for financial-grade inference chips. Distribution runs through authorized distributor networks serving systems integrators, with direct enterprise channels capturing banking sector volumes.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is consolidating among Hong Kong's top-tier asset managers and securities houses, fragmenting procurement influence across a narrowing cohort of institutions with captive infrastructure mandates. This concentration elevates negotiation leverage for standardized rack configurations while compressing margins for vendors lacking direct enterprise relationships.
For Market Incumbents: Compound defensive positioning through captive silicon supply agreements and localized liquid-cooling engineering capabilities. Deepen backward integration into GPU accelerator sourcing to offset TSMC allocation constraints threatening refresh cycle commitments. Prioritize certification investment for ISO 50001 compliance to capture Electrical and Mechanical Services Department efficiency incentives. For New Entrants and Emerging Players: Lead with modular edge infrastructure targeting New Territories manufacturing corridors where industrial IoT deployments outpace hyperscale saturation. Penetrate the prefabricated containerized data center segment serving logistics automation workloads in Tsuen Wan and Yuen Long. Anchor go-to-market through managed services bundling that transfers capital expenditure burdens to operational expenditure models for mid-market enterprises. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among colocation operators with long-term anchor tenancy agreements exceeding 99.99 percent uptime SLAs. Long-term viability over the coming decade rests on immersion cooling technology portfolios and waste heat recovery system integration. Target vertically integrated specialists with captive dielectric fluid supply chains and Hong Kong-anchored service infrastructure. Monitor Personal Data (Privacy) Ordinance enforcement intensity as the critical inflection signal for on-premise inference cluster investment acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Liquid-Cooled Architecture Deployment | Addresses tropical climate constraints while enabling 100+ kilowatt rack densities for algorithmic trading. |
| Captive Silicon Supply Agreement | Secures TSMC allocation priority against GPU procurement bottlenecks constraining inference cluster expansion. |
| ISO 50001 Certification Investment | Unlocks Electrical and Mechanical Services Department incentives for power usage effectiveness compliance. |
| Modular Edge Infrastructure Expansion | Captures New Territories industrial IoT demand outside Tseung Kwan O land scarcity constraints. |
| Cross-Border Data Corridor Positioning | Leverages Greater Bay Area integration to serve mainland institutions requiring common law jurisdiction residency. |
Research Methodology
A spread of perspectives from data center facility operators, financial services chief information officers, colocation procurement leads, and semiconductor distribution specialists converged on the working assumptions underpinning this analysis. Primary interviews with infrastructure planning directors and hardware audit compliance officers combined with secondary validation against Electrical and Mechanical Services Department regulatory filings, Office of the Privacy Commissioner for Personal Data enforcement bulletins, and submarine cable landing station capacity disclosures. Bottom-up triangulation across server unit shipment estimates and top-down reconciliation against facility power interconnection approvals anchored volume and value outputs.
Segmentation dimensions modeled span product type, end-user category, technology integration level, and installation deployment mode across the projection horizon. Product type disaggregation separates rack, blade, tower, and microserver configurations. End-user stratification captures colocation providers, financial enterprises, cloud service providers, and government operators. Technology segmentation tracks AI integration, virtualization, edge computing, and high-performance computing adoption curves. CAGRs derived from historical shipment patterns adjusted for Personal Data (Privacy) Ordinance amendment impacts and 5G edge node deployment schedules. Forecast inputs incorporate GPU cluster integration complexity costs and dual-jurisdiction compliance architectural premiums.
Forecasts assume regulatory continuity in Hong Kong's common law privacy framework and China's national data security regime; material policy shifts would require re-modeling of cross-border data corridor demand assumptions. Specific risks that could revise projections include Taiwan Strait logistics disruption, Electrical and Mechanical Services Department grid interconnection approval delays beyond current 18-24 month baselines, and TSMC capacity allocation rebalancing toward mainland Chinese foundry customers. Practitioners should keep alternative scenarios live as Greater Bay Area integration frameworks and immersion cooling technology cost curves evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Data Center Infrastructure
Fault Tolerant Servers Market
Data Center Infrastructure
Denmark Data Center Market
Data Center Infrastructure
Russia Data Center Construction Market
Data Center Infrastructure
South Africa Data Center Power Market
Data Center Infrastructure
United States Data Center Server Market
Data Center Infrastructure
North America Green Data Center Market
Data Center Infrastructure
Belgium Data Center Market
Data Center Infrastructure
Vietnam Data Center Power Market
Data Center Infrastructure
Switzerland Data Center Power Market
Data Center Infrastructure
Sweden Data Center Server Market
Data Center Infrastructure
Saudi Arabia Data Center Construction Market
Data Center Infrastructure
Water Leak Detection System for Server Rooms and Data Centers Market
Data Center Infrastructure
Nigeria Data Center Power Market
Data Center Infrastructure
North America Data Center Rack Market
Data Center Infrastructure
Norway Data Center Construction Market
Data Center Infrastructure
Ireland Data Center Physical Security Market