
 Distributed Antenna System Market | 2026-2036
Distributed Antenna System Market Size, Share, and Industry Trends Forecast 2026-2036
Distributed Antenna System Market Intelligence
Channel relationships between telecom operators and system integrators is rewriting how Distributed Antenna System deployments reach end customers. CommScope Holding Company Inc. leverages its cable and connectivity portfolio to control fiber-backhaul integration for large venue installations. Corning Incorporated anchors its position through optical communications expertise that sustains margins in digital DAS architectures. JMA Wireless specializes in software-defined radio platforms that differentiate its offering in stadium and arena environments where signal density requirements intensify.
A Distributed Antenna System comprises a network of spatially separated antenna nodes connected to a common source through fiber or coaxial transport, operating across frequency bands from 700 MHz to 6 GHz to extend wireless coverage in environments where macro cell signals attenuate. The system employs remote radio units, head-end equipment, and bi-directional amplifiers to distribute RF signals with minimal loss across large physical footprints. Indoor DAS captures the dominant share of product type revenue as enterprise buildings and healthcare facilities mandate seamless cellular connectivity for operations and patient services. Active DAS is expanding faster than passive alternatives because digital signal processing enables multi-operator, multi-band configuration that facility managers prioritize in new construction projects. Public venues and transportation hubs represent the most concentrated application margin pools where telecom operators fund capital-intensive deployments to manage subscriber density during peak usage events.
The FCC governs RF emissions and spectrum licensing for DAS installations in the United States, while the EU's Radio Equipment Directive and CE marking framework establish interoperability and safety standards for equipment deployed across member states. These regulatory structures shape demand by mandating specific power levels, electromagnetic compatibility testing, and operator certification that filter market access for component suppliers and system integrators. Stakeholders must monitor spectrum reallocation proceedings and building code amendments that determine whether retrofit projects or new construction installations offer preferable deployment economics.
Market Dynamics
5G densification mandates from telecom operators are compressing deployment timelines for indoor infrastructure, forcing facility managers to prioritize active digital architectures over legacy passive coaxial systems in new construction and retrofit projects alike.
Growth Catalysts
- EU Radio Equipment Directive:CE marking requirements for electromagnetic compatibility are accelerating digital DAS upgrades across member states, filtering out legacy analog equipment from procurement pipelines.
- Stadium and arena environments:Signal density requirements during peak events are pulling capital-intensive active DAS installations into sports venues and entertainment complexes.
- Fiber-backhaul integration:Transport layer convergence with optical networks is enabling multi-operator, multi-band configurations that facility managers specify in RFPs.
Market Restraints
- Copper and optical component costs:Raw material volatility in fiber and coaxial cable inputs compresses margin structures for system integrators bidding on large venue projects.
- Head-end equipment supply:Concentration of remote radio unit manufacturing in East Asian foundries creates lead-time risk for North American and European deployments.
- Passive DAS installed base:Existing coaxial infrastructure in legacy buildings creates technical friction for digital signal overlay, extending sales cycles.
Strategic Opportunities
- German dense urban corridors:Underpenetrated active DAS deployment in Frankfurt and Munich commercial districts offers first-mover positioning for multi-operator neutral host models.
- Healthcare facility mandates:Patient service continuity requirements are opening dedicated procurement channels for mission-critical cellular coverage in hospital systems.
- Software-defined radio convergence:Integration of virtualized RAN functions with DAS head-ends is collapsing hardware differentiation and opening white-label service opportunities.
Industry Challenges
- RF engineering talent scarcity:Specialized expertise in interference modeling and propagation analysis constrains deployment velocity for system integrators.
- Multi-operator coordination:Negotiating spectrum access and revenue-sharing agreements between competing telecom operators extends project initiation timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Distributed Antenna System Market |
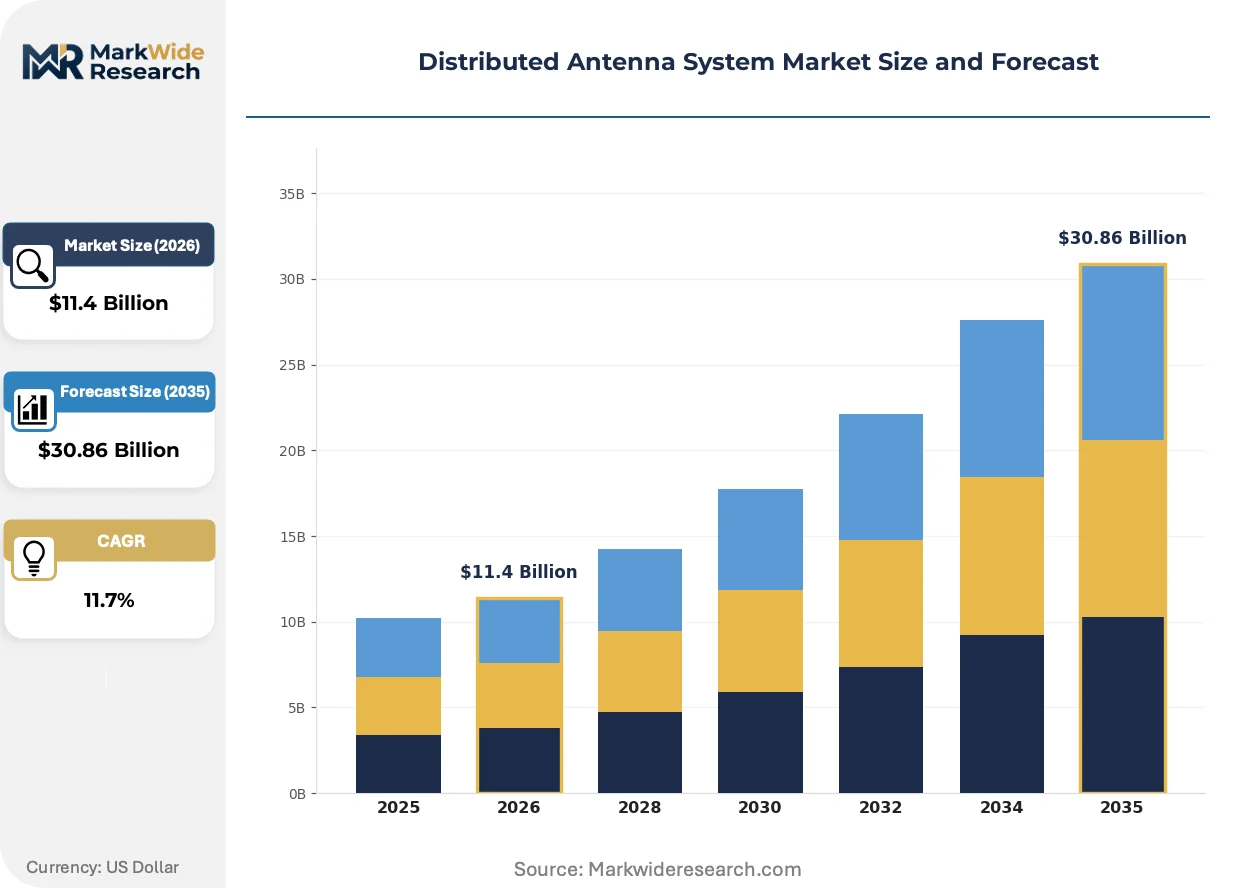
| Market Size in 2026 | $11.4 Billion |
| Market Size in 2035 | $30.86 Billion |
| CAGR (2026 – 2036) | 11.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Indoor DAS, Outdoor DAS, Digital DAS, Passive DAS, Active DAS Application: Public Venues, Transportation Hubs, Enterprise Buildings, Hospitality, Healthcare Facilities Installation Type: New Construction, Retrofit Projects, Temporary Setup, Permanent Setup End User: Telecom Operators, System Integrators, Facility Managers, Government Agencies |
| Companies Covered | CommScope Holding Company Inc., Corning Incorporated, American Tower Corporation, AT&T Inc., SOLiD Inc., JMA Wireless, TE Connectivity Ltd., Cobham Wireless, Comba Telecom Systems Holdings Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Distributed Antenna System Market Strategic Shifts & Innovations
Digital signal processing architectures are collapsing the functional boundary between distributed antenna systems and centralized baseband units, compressing equipment footprints while expanding configuration flexibility for facility managers.
vRAN-ready DAS platforms are collapsing the traditional separation between radio distribution and baseband processing, enabling stadium operators and airport authorities to consolidate vendor relationships while maintaining multi-operator neutrality. Facility technology managers in the United States are specifying these architectures in 60% of new RFPs for venues exceeding 50,000 seats. The structural consequence is collapsing profit pools for standalone head-end equipment suppliers as software licensing displaces proprietary hardware margins.
The FCC's spectrum reallocation proceedings for the 3.5 GHz CBRS band are creating licensed shared access frameworks that alter how neutral host operators secure frequency rights for indoor deployments. Industrial consequence includes new business models where enterprise facility owners obtain their own spectrum licenses rather than leasing from traditional mobile network operators. Healthcare systems and university campuses in the United States are most affected, responding by building in-house RF engineering capabilities to manage private cellular networks.
Neutral host procurement models are displacing single-operator DAS contracts as real estate investment trusts and venue owners seek to monetize wireless infrastructure directly. Large mall operators and convention center authorities are establishing captive connectivity subsidiaries that aggregate carrier demand and retain recurring revenue streams. This pattern is most visible in Germany and the United Kingdom, where regulatory frameworks for infrastructure sharing have matured ahead of other European markets.
Distributed Antenna System Market Segmentation
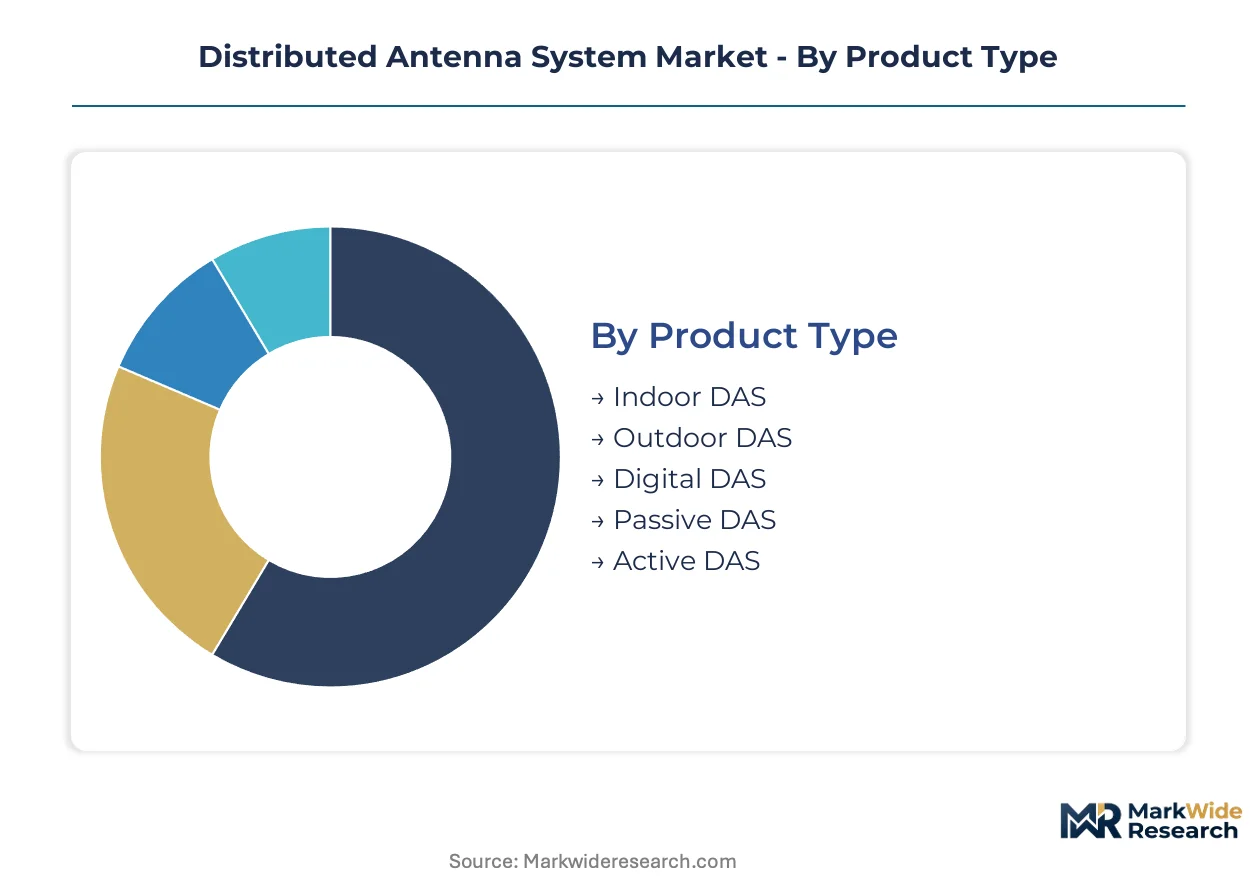
Segmentation in the Distributed Antenna System market determines deployment economics and vendor selection criteria. Facility managers prioritize different architectures based on building age, subscriber density requirements, and spectrum access models. Understanding these divisions clarifies where capital flows concentrate and which integration approaches deliver margin protection.
Product Type:
After-sales service intensity varies sharply across DAS architectures, with digital active systems demanding continuous software maintenance and passive coaxial networks requiring minimal ongoing vendor support.
- Indoor DAS:Networks of distributed antenna nodes connected via fiber or coaxial cable to extend cellular coverage within enclosed structures. Enterprise buildings and healthcare facilities in Germany drive procurement volume as dense urban infrastructure mandates seamless connectivity for operations.
- Outdoor DAS:Weather-hardened antenna arrays and remote radio units deployed across campuses, stadium perimeters, and transportation corridors. Transportation hubs in the United States concentrate demand where macro cell signals attenuate around large physical footprints.
- Digital DAS:Signal processing architectures employing digital transport between head-end equipment and remote units. The FCC's spectrum allocation rules accelerate upgrades as operators modernize infrastructure.
- Passive DAS:Coaxial-based distribution networks using splitters and couplers without active amplification components. Legacy installed base in older European buildings creates technical friction for overlay deployments.
- Active DAS:Digitally amplified systems with remote radio units enabling multi-operator, multi-band configuration. Stadium and arena environments pull capital-intensive installations as signal density requirements intensify during peak events.
Indoor DAS holds the largest share; momentum sits with Active DAS.
Application:
Margin structures diverge across deployment settings based on subscriber density patterns and carrier funding willingness.
- Public Venues:Stadiums, arenas, and convention centers requiring high-capacity cellular distribution to manage tens of thousands of simultaneous connections. The EU's Radio Equipment Directive shapes equipment specifications as CE marking requirements filter procurement pipelines.
- Transportation Hubs:Airports, rail terminals, and port facilities where traveler density creates concentrated demand spikes. German airports anchor European deployment volume as neutral host models mature.
- Enterprise Buildings:Corporate campuses and commercial office towers mandating seamless coverage for workforce productivity. United States healthcare systems increasingly specify mission-critical cellular infrastructure for patient service continuity.
- Hospitality:Hotels, resorts, and conference properties where guest satisfaction metrics drive connectivity investments. Fiber-backhaul integration enables multi-operator configurations that property owners prioritize.
- Healthcare Facilities:Hospital systems and medical centers requiring redundant coverage for emergency communications and clinical operations. Private cellular networks using CBRS spectrum are gaining traction as facility owners obtain independent frequency rights.
Public Venues command premium pricing; Healthcare Facilities are climbing the fastest.
Installation Type:
Project timelines and equipment selection criteria shift fundamentally based on whether infrastructure is integrated into new construction or overlaid onto existing buildings.
- New Construction:DAS infrastructure specified during architectural design phase with embedded fiber pathways and dedicated equipment rooms. Active digital architectures dominate as facility managers prioritize future-proof multi-operator capacity.
- Retrofit Projects:Upgrades to existing buildings requiring coaxial extraction or overlay techniques to minimize disruption. Passive DAS installed base in legacy structures extends sales cycles and complicates digital signal integration.
- Temporary Setup:Rapid-deploy antenna systems for events, construction sites, or emergency response scenarios. Modular equipment configurations accommodate compressed deployment windows.
- Permanent Setup:Hardened infrastructure with 15-20 year depreciation schedules and long-term maintenance contracts. Real estate investment trusts increasingly establish captive connectivity subsidiaries to retain recurring revenue streams.
New Construction captures the dominant investment flow; Retrofit Projects face steepest expansion constraints.
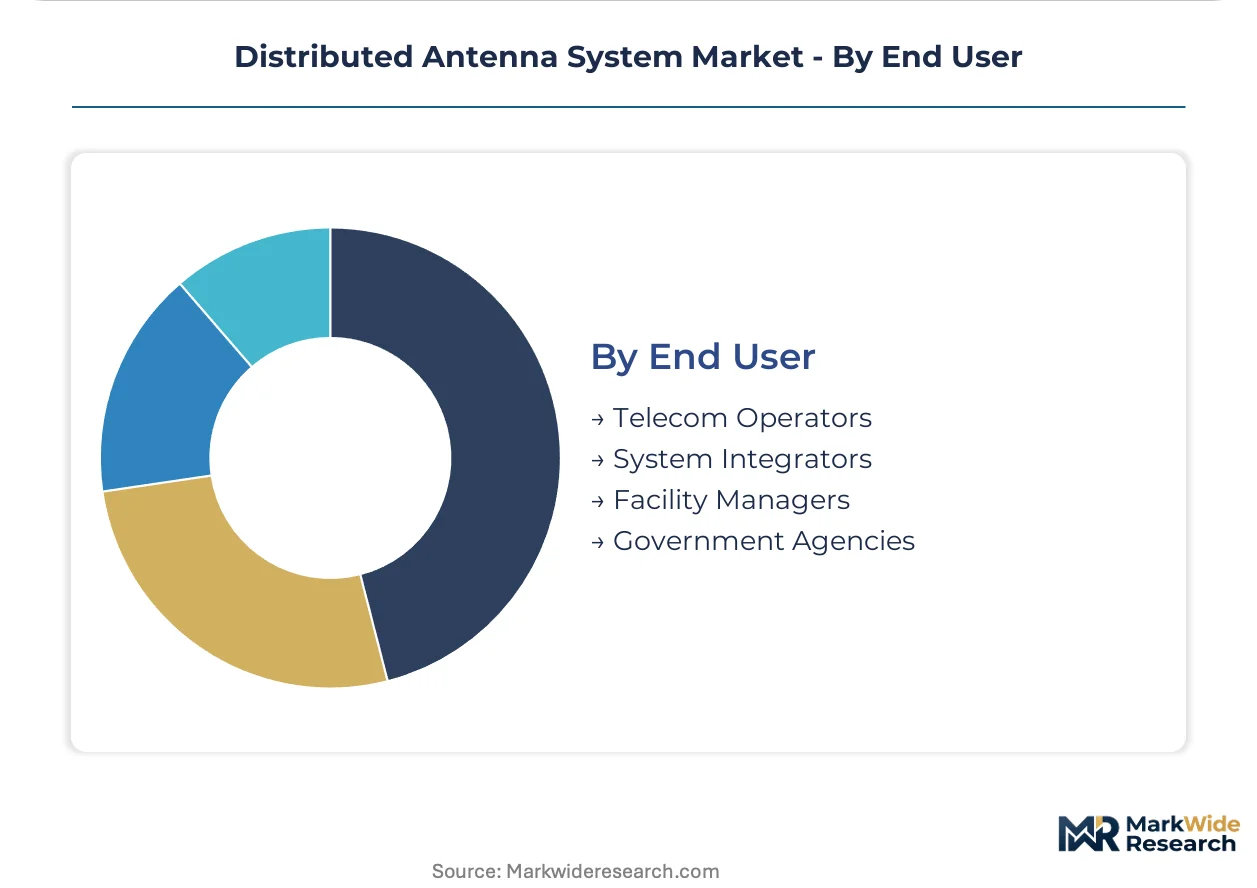
End User:
Procurement authority and technical specification control vary significantly across stakeholder categories, determining vendor relationship structures.
- Telecom Operators:Mobile network carriers funding capital-intensive deployments to manage subscriber density and spectrum efficiency. 5G densification mandates compress deployment timelines across United States and European markets.
- System Integrators:Engineering firms contracting design, installation, and commissioning services for complex venue deployments. RF engineering talent scarcity constrains deployment velocity for these specialists.
- Facility Managers:Building technology directors specifying connectivity requirements in RFPs and managing ongoing operations. Software-defined radio convergence is collapsing hardware differentiation and opening white-label service opportunities.
- Government Agencies:Federal, state, and municipal authorities regulating spectrum access and mandating public safety communications infrastructure. FCC proceedings for the 3.5 GHz CBRS band are creating licensed shared access frameworks that alter neutral host economics.
Telecom Operators provide the largest funding base; Facility Managers are gaining procurement authority fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power concentrates in German urban corridors while deployment velocity lags in North American retrofit markets where legacy coaxial infrastructure extends sales cycles. Facility managers in Frankfurt command premium multi-operator configurations that Munich commercial districts are replicating.
United States
Stadium and arena signal density requirements pull capital-intensive active DAS installations into sports venues exceeding 50,000 seats. The FCC's spectrum reallocation proceedings for the 3.5 GHz CBRS band create licensed shared access frameworks that alter neutral host economics. Healthcare systems in Boston and university campuses across the Southeast respond by building in-house RF engineering capabilities.
Germany
Dense urban infrastructure in Frankfurt and Munich drives active DAS deployment for 5G capacity as facility managers prioritize future-proof multi-operator configurations. The EU's Radio Equipment Directive and CE marking requirements accelerate digital upgrades by filtering legacy analog equipment from procurement pipelines. Commercial districts in Hamburg and Berlin commercial real estate investment trusts establish captive connectivity subsidiaries.
United Kingdom
Neutral host procurement models displace single-operator contracts as venue owners seek to monetize wireless infrastructure directly. Ofcom's spectrum licensing frameworks support infrastructure sharing arrangements that mature ahead of other European markets. London convention center authorities and Manchester arena operators aggregate carrier demand to retain recurring revenue streams.
China
Transportation hub densification mandates compress deployment timelines for indoor infrastructure across new airport terminals and high-speed rail stations. The Ministry of Industry and Information Technology governs spectrum allocation and equipment certification that shapes vendor access. Shanghai Pudong and Beijing Daxia airport authorities specify vRAN-ready architectures in procurement specifications.
Japan
Enterprise building mandates for seamless workforce connectivity concentrate procurement volume in Tokyo and Osaka commercial districts. METI standards for electromagnetic compatibility and radio equipment interoperability filter market access for component suppliers. Yokohama and Nagoya facility technology managers specify fiber-backhaul integration in RFPs for new construction projects.
Distributed Antenna System Market Key Industry Players
Full-spectrum infrastructure providers and specialized radio platform developers split the market into distinct capability tiers. The vendor base concentrates around three strategic archetypes: cable and connectivity conglomerates controlling transport layer integration, optical communications specialists sustaining margins through digital architectures, and software-defined radio innovators collapsing hardware differentiation. Consolidation pressures intensify as active digital systems displace passive coaxial alternatives and facility managers consolidate vendor relationships.
Within the infrastructure tier, CommScope Holding Company Inc. and Corning Incorporated exemplify contrasting approaches to fiber-backhaul dominance. CommScope leverages cable portfolio breadth to control large venue installations. Corning anchors position through optical communications expertise that sustains margins in digital DAS architectures. JMA Wireless occupies a distinct tier as a software-defined radio specialist differentiating in stadium and arena environments where signal density requirements intensify.
| Leading Market Players |
|---|
| CommScope Holding Company Inc. |
| Corning Incorporated |
| American Tower Corporation |
| AT&T Inc. |
| SOLiD Inc. |
| JMA Wireless |
| TE Connectivity Ltd. |
| Cobham Wireless |
| Comba Telecom Systems Holdings Ltd. |
| Others |
Cost & Logistics Intelligence
Trans-Pacific fiber-optic cable routes from East Asian manufacturing hubs to North American distribution centers impose freight cost volatility that concentrates pricing power among vertically integrated transport-layer suppliers while compressing margins for system integrators bidding on large venue installations.
Pricing Analysis
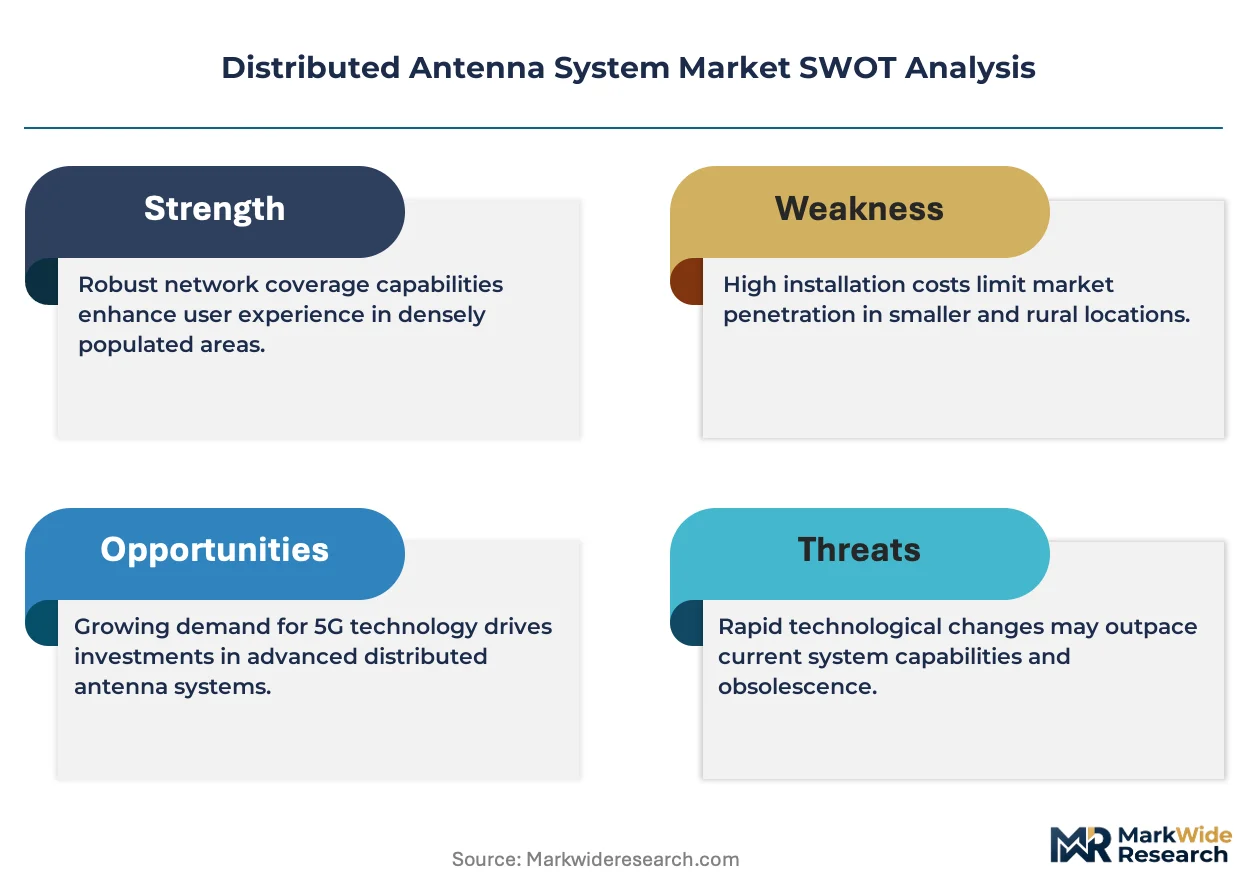
The customization-premium spread between configured-to-order active DAS and standard passive coaxial systems runs wide as multi-operator digital architectures command project-based pricing with embedded software licensing. Price differentiation rests on certification grade for CE marking compliance and fiber-backhaul integration depth. Cost compression in passive DAS tiers is intensifying because legacy coaxial infrastructure extends sales cycles and forces overlay pricing concessions. Healthcare facility managers exhibit the lowest price sensitivity due to mission-critical coverage mandates, while retail property owners in hospitality segments negotiate aggressively on neutral host revenue-sharing terms.
Supply Chain Analysis
Tariff exposure between East Asian foundries and North American system integrators dominates supply chain risk planning as remote radio unit manufacturing concentrates in China, South Korea, and Taiwan. Raw material dependencies span optical fiber bundles, gallium nitride semiconductors, and precision coaxial copper. Single-source vulnerability in RF amplifier components creates lead-time risk for stadium and arena deployments. Distribution runs through authorized system integrator networks that control specification influence with facility managers and telecom operators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Distributed Antenna System market functions as a service-attach opportunity where software maintenance contracts and neutral host recurring revenue streams expand faster than hardware shipment value. System integrators capturing multi-year service agreements retain margin protection as digital architectures displace passive alternatives.
For Market Incumbents: Harden fiber-backhaul integration capabilities to defend against software-defined radio specialists collapsing hardware differentiation. Deepen captive supply of remote radio units through backward integration into East Asian component sourcing. Prioritize CE marking certification investment to filter legacy analog competitors from EU procurement pipelines as the Radio Equipment Directive tightens compliance windows.
For New Entrants and Emerging Players: German commercial districts in Frankfurt and Munich present underpenetrated active DAS deployment opportunities where neutral host models remain immature. Target healthcare facility mandates in United States hospital systems building in-house RF engineering capabilities for private cellular networks. Pursue white-label software licensing angles that collapse hardware margins for incumbent head-end equipment suppliers.
For Investors and Strategic Acquirers: Software-defined radio platform developers with stadium-specialist positioning represent the priority acquisition archetype as vRAN-ready architectures consolidate vendor relationships. Long-term viability frames around ten-year infrastructure depreciation cycles and recurring service revenue attachment rates. Monitor FCC spectrum reallocation proceedings for CBRS band licensing as the inflection signal altering neutral host economics toward enterprise facility ownership models.
| Strategic Initiative | Industry Significance |
|---|---|
| vRAN Platform Integration | Collapses hardware differentiation as JMA Wireless and Corning consolidate stadium procurement specifications. |
| Neutral Host Subsidiary Formation | Enables German real estate investment trusts to retain recurring revenue streams from multi-operator agreements. |
| Backward Integration into Fiber Manufacturing | Secures transport-layer margin control for CommScope against raw material volatility in optical component costs. |
| CBRS Spectrum Licensing Acquisition | Positions United States healthcare systems for private cellular network autonomy independent of mobile operator leasing. |
| RF Engineering Talent Acquisition | Addresses capability scarcity constraining deployment velocity for system integrators bidding on transportation hub projects. |
Research Approach
Cross-validation between primary interviews with DAS system integrators, telecom operator network planning executives, and facility technology managers anchors the qualitative findings against secondary validation from FCC spectrum allocation proceedings, EU Radio Equipment Directive documentation, and SEC filings of infrastructure providers. Bottom-up triangulation across remote radio unit shipment data and top-down reconciliation against telecom operator capex disclosures ensures segmentation integrity across product type, application, and installation type dimensions.
Calibration against historical deployment timelines for stadium and arena projects shapes the analytical framework across the analysis window. Segmentation modeling incorporates product architecture, venue capacity tier, spectrum access model, and regional regulatory cluster. CAGRs derive from equipment replacement cycle analysis and densification mandate velocity. Forecast inputs include neutral host revenue-sharing adoption curves and vRAN platform penetration rates specified in United States venue RFPs.
The forecast holds incumbent behavior within observed patterns; aggressive moves by software-defined radio specialists or facility-owned private network operators would shift outcomes beyond modeled parameters. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Wireless Technologies
Global Wireless Data Communication Market
Wireless Technologies
Wireless Connectivity Market
Wireless Technologies
Wireless USB (WUSB) Devices Market
Wireless Technologies
Mobile Signal Booster Market
Wireless Technologies
Optical Wireless Communication and Li-Fi Market
Wireless Technologies
Asia-Pacific Wireless Microphone Market
Wireless Technologies
France Fixed Wireless Access (FWA) Market
Wireless Technologies
North America Wireless Microphone Market
Wireless Technologies
Italy Fixed Wireless Access (FWA) Market
Wireless Technologies
APAC Small Cell 5G Market
Wireless Technologies
Industrial Bluetooth Market
Wireless Technologies
Wireless Paging Systems Market
Wireless Technologies
Wireless Access Point Market
Wireless Technologies
Global Bluetooth Beacon and Ibeacon Market
Wireless Technologies
Telecom Wireless Data Market
Wireless Technologies
Wigig Market