
 Wireless Health and Fitness Devices Market | 2026-2036
Wireless Health and Fitness Devices Market Size, Share, and Industry Trends Forecast 2026-2036
Wireless Health and Fitness Devices Market Intelligence
The European Union's push for a circular economy, targeting electronic waste, is repositioning product design and end-of-life considerations. Apple leverages its integrated iOS ecosystem to drive widespread smartwatch adoption for health and fitness tracking. Garmin specializes in high-performance GPS sports watches, targeting dedicated athletes and outdoor enthusiasts. Oura differentiates with its ring-form factor, focusing intently on sleep and recovery analytics for wellness-conscious users.
Wireless health and fitness devices are wearable electronic sensors that collect and transmit biometric data using connectivity like Bluetooth. They use accelerometers and PPG sensors to monitor metrics for personal health management and athletic performance. Smartwatches command the device type segment, while fitness trackers maintain a strong presence due to affordability. Core applications such as activity tracking and sleep monitoring appeal broadly to end users from athletes to wellness enthusiasts.
Regulatory oversight from bodies like the US Food and Drug Administration (FDA) and China's NMPA becomes critical when devices make specific medical or diagnostic claims. In Europe, CE marking under the Medical Device Regulation (MDR) governs product safety and performance standards for all health-related wearables. The key strategic decision for manufacturers involves navigating the complex boundary separating consumer wellness gadgets from regulated medical devices.
Market Dynamics
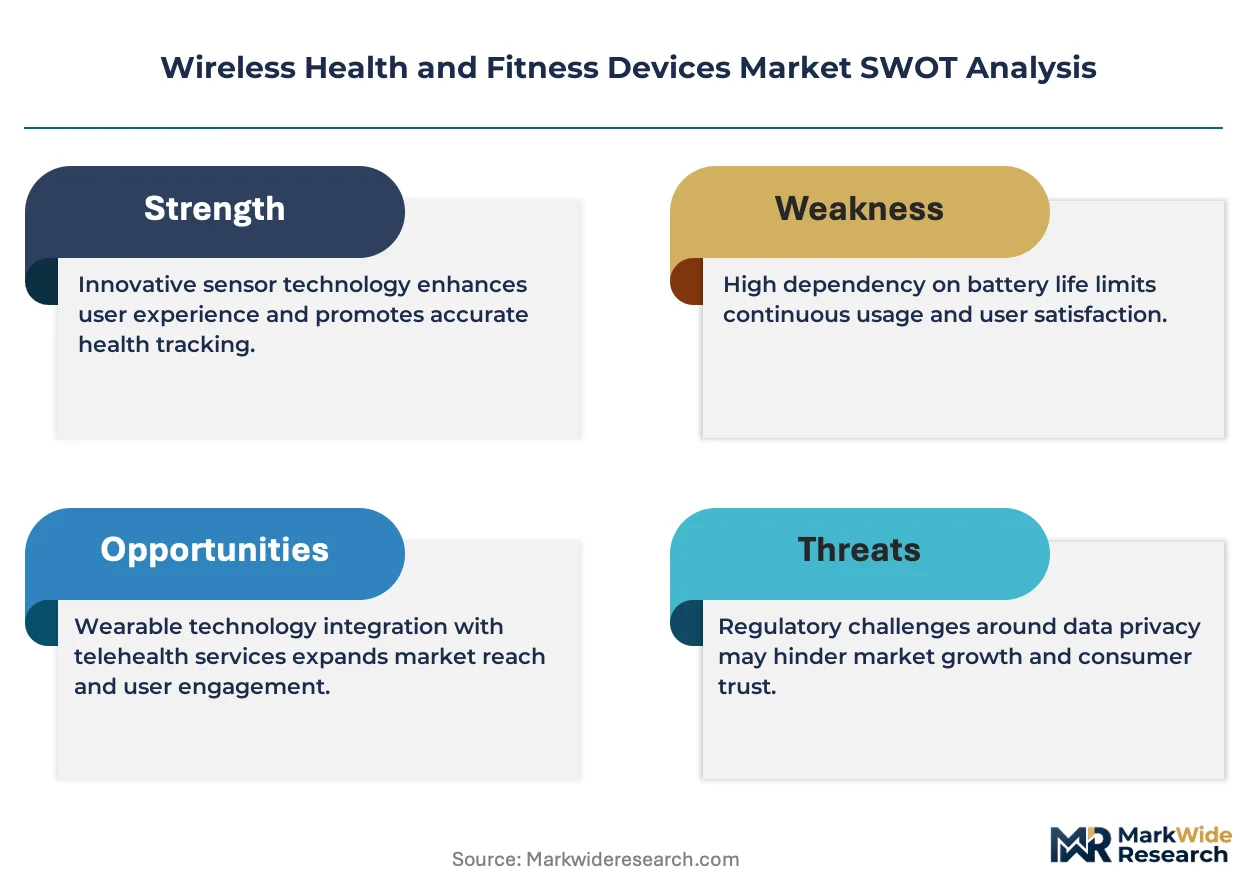
The central dynamic shaping the market is the strategic tension between producing consumer-grade wellness gadgets and developing regulated medical devices. This bifurcation influences feature sets, marketing claims, and the complex compliance pathways manufacturers must navigate, from FDA clearance in the United States to CE marking under the MDR in Europe.
Growth Catalysts
- Corporate Wellness Programs:The integration of wearable data into corporate wellness initiatives to monitor employee health and encourage physical activity is driving bulk device adoption by enterprises.
- Sensor Technology Advancement:Continuous improvements in the accuracy and capability of PPG sensors and accelerometers enhance the reliability of biometric data, boosting consumer confidence and application utility. *Proactive Health Culture: A strong consumer culture of proactive health management and personal data tracking, particularly concentrated in the United States, sustains high demand for personal fitness devices.
Market Restraints
- Data Privacy Regulations:Stringent data protection laws, notably the EU's General Data Protection Regulation (GDPR), impose significant compliance costs and constrain how personal health data can be collected, stored, and used.
- Battery Life Limitations:Limited battery longevity in feature-rich devices like smartwatches remains a significant technical barrier, hindering continuous monitoring and diminishing user convenience.
- Component Cost Structure:The high cost of miniaturized, high-precision components, including advanced biometric sensors and low-power processors, creates a floor for device pricing and limits mass-market affordability.
Strategic Opportunities
- Mental Wellness Monitoring:Expanding device capabilities beyond physical activity to include stress tracking, respiratory rate analysis, and sleep quality metrics opens new applications in mental and emotional wellbeing.
- Untapped Emerging Markets:Growing disposable incomes and rising health consciousness in countries across Southeast Asia and Latin America represent significant geographic expansion opportunities for device manufacturers.
- AI-Powered Personalization:Integrating artificial intelligence to provide users with predictive health insights and personalized coaching based on their biometric data offers a path for significant value differentiation.
Industry Challenges
- Medical Device Certification:Navigating the lengthy and resource-intensive regulatory pathways for medical-grade certifications, such as FDA de novo clearance or CE marking under MDR, presents a major operational hurdle.
- Data Interoperability:A lack of standardization for data formats and APIs creates significant friction in sharing health information between different wearable ecosystems, mobile apps, and clinical health platforms.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Wireless Health and Fitness Devices Market |
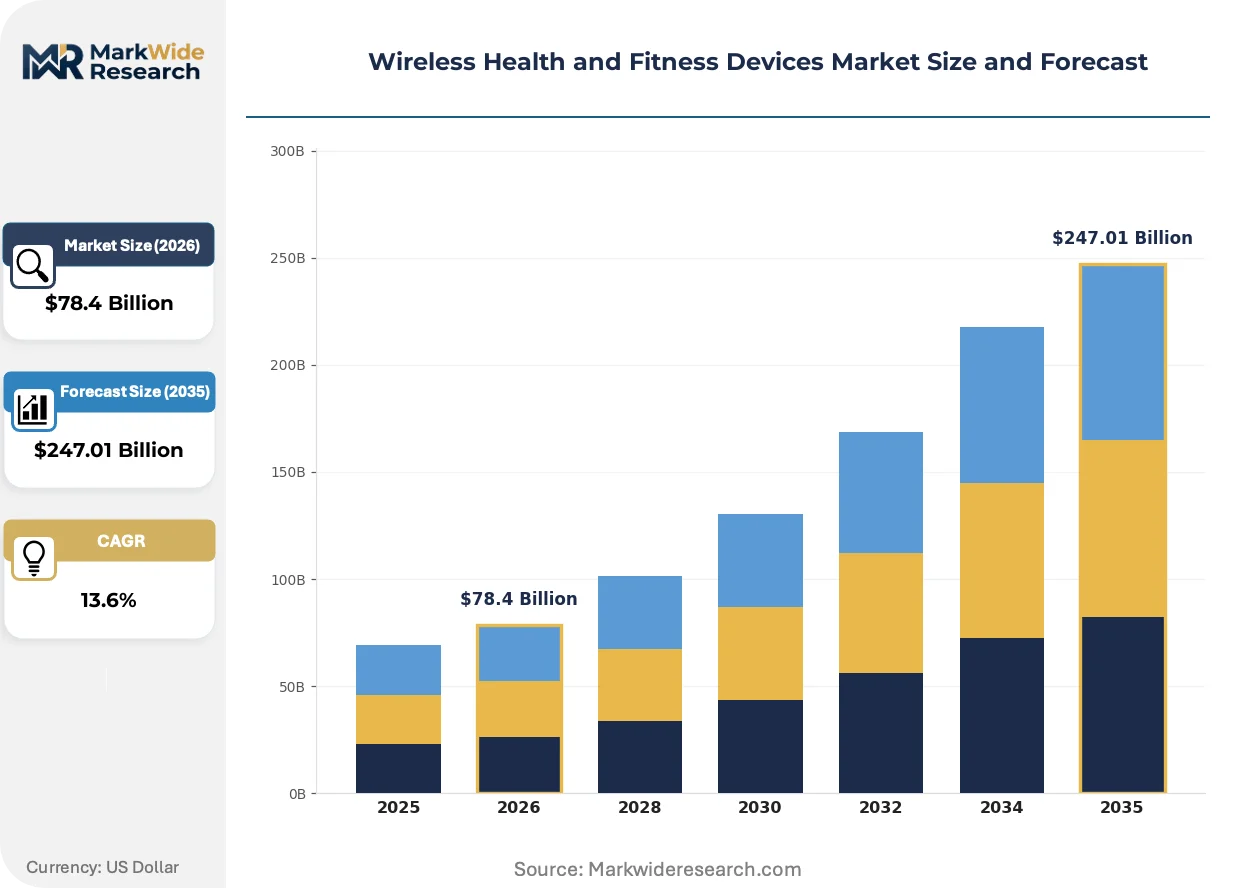
| Market Size in 2026 | $78.4 Billion |
| Market Size in 2035 | $247.01 Billion |
| CAGR (2026 – 2036) | 13.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Device Type: Fitness Trackers, Smartwatches, Heart Rate Monitors, GPS Sports Watches, Body Composition Scales Connectivity Technology: Bluetooth, Wi-Fi, NFC, ANT+, Zigbee Application: Activity Tracking, Sleep Monitoring, Heart Health, Calorie Counting, Stress Management, Personal Training End User: Athletes, Wellness Enthusiasts, Elderly Care, Corporate Fitness Programs, Gyms |
| Companies Covered | Fitbit, Whoop, Garmin, Google, Amazfit, Apple, Oura, Withings, Samsung, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Wireless Health and Fitness Devices Market Strategic Shifts & Innovations
Product evolution is defined by a clear pivot from basic activity quantification to predictive and holistic health monitoring. This shift is enabled by the fusion of multiple sensor inputs with sophisticated software algorithms, transforming wearables into personalized health management tools.
On-device artificial intelligence performs initial data analysis directly on the wearable, reducing reliance on cloud processing. Health-conscious consumers and athletes are adopting devices with this capability for enhanced privacy and immediate feedback. This technological shift is decentralizing health data processing, moving it from remote servers to the user's wrist and lowering dependency on constant connectivity.
Europe's Medical Device Regulation (MDR) has intensified scrutiny on wearables making health-related claims. The regulation mandates more rigorous clinical evidence and post-market surveillance for products to achieve and maintain CE marking. This primarily impacts smartwatch and advanced sensor manufacturers, forcing a choice between investing in costly clinical validation or marketing their products strictly as non-medical wellness devices.
A transition toward subscription-based services for advanced analytics and personalized coaching is gaining momentum. This model disrupts the conventional one-time hardware sale by creating recurring revenue streams from software-enabled insights. This trend is most visible in the sleep and recovery tracking segment, especially in North America and Europe, where users seek continuous performance optimization.
Wireless Health and Fitness Devices Market Segmentation
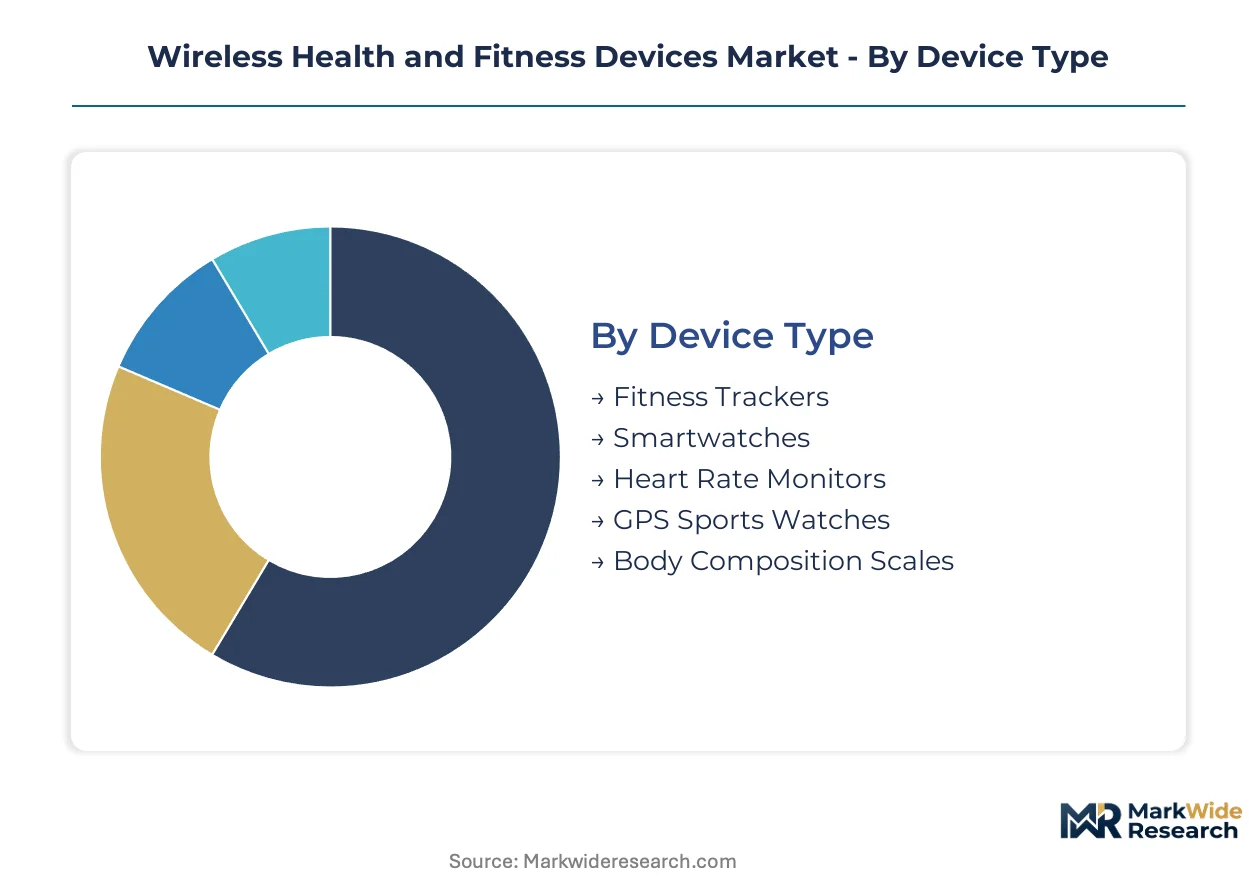
The Wireless Health and Fitness Devices Market segmentation reveals how diverse consumer needs and technological capabilities drive product development and market penetration. Understanding these distinct segments allows manufacturers to tailor features, connectivity options, and applications to specific user groups. This precise targeting optimizes product-market fit and enhances user engagement.
Device Type:
Consumer purchasing decisions for wireless health and fitness devices often hinge on the primary function and form factor that best integrates into their daily routines.
- Smartwatches:These multi-functional wrist-worn devices integrate advanced biometric sensors with communication and notification capabilities. Demand concentrates in developed markets, particularly the United States, driven by comprehensive health monitoring.
- GPS Sports Watches:Designed for dedicated athletes and outdoor enthusiasts, these specialized wearables offer precise location tracking and advanced performance metrics. Their demand is strong among runners and cyclists prioritizing accuracy and durability.
- Fitness Trackers:These devices primarily monitor physical activity, sleep patterns, and calorie expenditure for general wellness.
- Heart Rate Monitors:Dedicated sensors, often chest straps, provide continuous heart rate data for exercise intensity.
- Body Composition Scales:These smart scales measure weight, body fat percentage, and muscle mass, transmitting data to companion apps.
Volume sits with Fitness Trackers; growth tilts toward Smartwatches.
Connectivity Technology:
The application requirements for data transfer speed, range, and power consumption dictate the selection of connectivity technology within wireless health devices.
- Bluetooth:This short-range wireless technology is ubiquitous for pairing devices like smartwatches with smartphones, enabling efficient data synchronization with minimal power. Its widespread adoption is foundational.
- Wi-Fi:Offering higher bandwidth and longer range, Wi-Fi is crucial for devices requiring larger data uploads, such as smart scales transmitting detailed body composition analyses. It supports real-time data streaming.
- NFC:Near Field Communication facilitates secure, short-range data exchange for contactless payments and quick device pairing.
- ANT+:A low-power wireless protocol for fitness sensors, ANT+ connects heart rate monitors and power meters to sports watches.
- Zigbee:This low-power, mesh networking protocol is found in smart home ecosystems, offering potential for integrated health monitoring.
Interoperability requirements increasingly shape the adoption trajectory for new connectivity standards.
Application:
Different customer types, ranging from casual wellness enthusiasts to elite athletes, prioritize distinct application functionalities within their health and fitness devices.
- Activity Tracking:This foundational application records steps taken, distance covered, and active minutes, catering to a broad user base focused on general physical activity. Its simplicity drives engagement.
- Sleep Monitoring:Devices track sleep stages, duration, and quality through heart rate and movement sensors, appealing to users focused on recovery and overall health optimization. The Oura ring exemplifies this.
- Heart Health:Applications monitor heart rate variability, detect irregular rhythms, and provide ECG capabilities, often requiring regulatory oversight.
- Calorie Counting:This function estimates calorie expenditure based on activity levels, supporting weight management and dietary goals.
- Stress Management:Devices analyze physiological markers like heart rate variability to identify stress levels, offering guided breathing exercises.
- Personal Training:These applications provide guided workouts, performance analysis, and adaptive training plans for athletes.
The shift toward predictive analytics and personalized insights is intensifying across all application segments.
End User:
The volume of device adoption often correlates directly with the specific health objectives and purchasing power of distinct end-user demographics.
- Wellness Enthusiasts:This large consumer segment seeks devices for general health monitoring, personal improvement, and lifestyle tracking, driving broad market demand. Their motivation centers on proactive health management.
- Corporate Fitness Programs:Enterprises implement these programs to improve employee health and productivity, leading to bulk procurement of devices and biometric data integration. This segment represents a significant B2B channel.
- Athletes:Elite and amateur athletes utilize high-performance devices like GPS sports watches to optimize training and monitor responses.
- Elderly Care:Devices in this segment focus on fall detection, emergency alerts, and remote monitoring of vital signs.
- Gyms:Fitness centers integrate wearables into their ecosystems for personalized workout tracking and member engagement.
Tailored solutions addressing specific demographic needs and enterprise requirements are gaining traction.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Silicon Valley, California, serves as a primary innovation hub for wireless health and fitness devices, driving significant product development and consumer adoption. This area fosters a strong culture of proactive health management, sustaining high demand for personal fitness technology. Its technological ecosystem supports continuous innovation in sensor capabilities.
United States
United States consumers exhibit a strong culture of proactive health management and personal data tracking. The US Food and Drug Administration (FDA) regulates devices making specific medical or diagnostic claims. Silicon Valley, California, serves as a major hub for device innovation and software development.
Germany
German consumers prioritize high-quality health and fitness technology, supported by strong disposable incomes. Europe's Medical Device Regulation (MDR) governs product safety and performance standards for health-related wearables. Munich, Bavaria, hosts significant engineering talent and medical technology companies.
China
China's market experiences robust demand driven by rising health consciousness and increasing disposable incomes. The National Medical Products Administration (NMPA) becomes critical for devices making specific medical claims. Shenzhen, Guangdong, functions as a global manufacturing hub for electronic devices.
Japan
Japanese consumers show high adoption rates for technology, particularly for health management in an aging population. The Pharmaceuticals and Medical Devices Agency (PMDA) oversees the regulatory approval process for medical-grade wearables. Tokyo, within the Kanto region, acts as a center for consumer electronics innovation and advanced sensor research.
Brazil
Brazil's market for wireless health devices benefits from a growing middle class and increasing health awareness. The Agência Nacional de Vigilância Sanitária (ANVISA) regulates health products and medical devices within the country. São Paulo, in the Southeast region, serves as a significant consumer market and distribution hub for technology.
Wireless Health and Fitness Devices Market Key Industry Players
The competitive structure tilts toward a bifurcated landscape, featuring both large consumer electronics conglomerates and specialized health technology firms. This market sees significant differentiation between wellness-focused gadgets and regulated medical devices. Strategic archetypes include integrated ecosystem providers, high-performance sports specialists, and niche wellness innovators. Companies engage in portfolio diversification and technology licensing to broaden their market reach.
Within the integrated ecosystem provider tier, Apple Inc. exemplifies a strategy leveraging existing consumer technology platforms for widespread adoption in health tracking. Garmin Ltd. occupies a position among high-performance sports specialists, offering precise tracking solutions for dedicated athletes and outdoor enthusiasts. Oura Health Oy anchors the niche wellness innovators, focusing intently on sleep and recovery analytics through its unique ring form factor. These firms represent distinct approaches to product development, catering to varied consumer segments and driving market evolution through specialized offerings.
| Leading Market Players |
|---|
| Fitbit |
| Whoop |
| Garmin |
| Amazfit |
| Apple |
| Oura |
| Withings |
| Samsung |
| Others |
Cost & Logistics Intelligence
Corporate wellness programs' bulk procurement of devices represents a significant demand-side pressure, compelling manufacturers to scale production and manage component costs effectively. This directly influences volume-based pricing strategies and the overall cost structure of devices in the market.
Pricing Analysis
Value derived from continuous biometric data underpins pricing across the Wireless Health and Fitness Devices Market. A hybrid pricing model combines a one-time hardware sale with subscription services for advanced analytics and personalized coaching. Price differentiation stems from CE marking certification for medical claims and the brand premium associated with established players like Apple and Garmin. Cost compression in the fitness tracker segment intensifies due to commoditization and high component volumes. Wellness enthusiasts exhibit higher price sensitivity, while corporate fitness programs and dedicated athletes prioritize features and data accuracy over initial cost.
Supply Chain Analysis
Regulatory mandates like the EU's Medical Device Regulation (MDR) influence sourcing decisions for components intended for health-related claims. Geographic supply concentration for manufacturing centers in China, while advanced sensor research and development often occur in the United States and Germany. The market relies heavily on specialized inputs such as advanced biometric sensors, low-power microprocessors, and specialized battery cells. A structural supply chain risk involves single-source vulnerability for critical sensor components, impacting production continuity. Distribution primarily runs through direct-to-consumer online channels and major electronics retailers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The market for wireless health and fitness devices is supply-constrained, particularly in the production of medical-grade sensors. The specialized manufacturing processes and stringent regulatory hurdles for these components limit supply, maintaining higher prices for certified devices.
For Market Incumbents: Anticipate increased regulatory scrutiny from bodies like the FDA and Europe's MDR, necessitating significant investment in clinical validation. Deepen vertical integration into specialized sensor manufacturing to mitigate supply chain risks and control costs. Acquire AI-powered analytics startups to enhance personalized insight capabilities, countering the threat from niche wellness players. Investment in CE marking and FDA clearance for advanced diagnostic features remains a critical lever for market expansion.
For New Entrants and Emerging Players: Underserved wellness enthusiasts in emerging markets represent a significant opportunity for affordable, feature-rich devices. Target mental wellness monitoring applications and AI-powered personalized coaching in regions like Southeast Asia. Entry-level fitness trackers with basic biometric tracking offer a penetrable market segment due to their affordability. A subscription-based model for personalized insights provides a viable go-to-market angle, fostering continuous user engagement and recurring revenue.
For Investors and Strategic Acquirers: The window for entry favors strategic acquirers targeting companies with proven AI algorithms for predictive health insights. The market sustains growth over the next 5-10 years, driven by proactive health management trends and technological advancements. Firms specializing in sleep and recovery analytics or those with strong intellectual property in sensor fusion represent attractive acquisition targets. Successful FDA de novo clearance or MDR certification for novel diagnostic functionalities serves as a key signal to watch for inflection.
| Strategic Initiative | Industry Significance |
|---|---|
| Invest in Medical Device Certification | Securing FDA or CE marking enables devices to make diagnostic claims, expanding market access. |
| Develop AI-Powered Personalization | Integrating AI offers predictive health insights, enhancing user engagement and value differentiation. |
| Expand into Emerging Markets | Tapping into rising disposable incomes and health consciousness in regions like Southeast Asia diversifies revenue. |
| Vertical Integration in Sensor Production | Gaining upstream control over key biometric sensor manufacturing mitigates supply chain risks. |
| Launch Subscription Service for Analytics | Shifting to recurring revenue models provides stable income and fosters continuous user engagement. |
Research Approach
Multi-period observation of device adoption rates and sensor technology advancements anchored the trend analysis, supplemented by interviews with industry stakeholders. Primary research involved device engineers, product managers, regulatory affairs specialists, and corporate wellness program managers. Secondary data sources included national health statistics, patent databases, trade association reports, and regulatory body publications like FDA guidance. A comprehensive bottom-up and top-down triangulation approach validated market sizing and growth projections.
An input-output matrix framework structured the quantitative analysis, projecting market dynamics across the analysis window. This framework modeled segmentation dimensions including device type, connectivity technology, application, end user, and regional regulatory environment. Compound Annual Growth Rates (CAGRs) were derived from historical growth patterns and projected adoption curves. Key industry-specific forecast inputs included sensor accuracy improvements and regulatory approval timelines for new features.
Revisions become necessary when unforeseen regulatory shifts or significant component supply disruptions materialize. Forecasts reflect assumptions regarding technological evolution, consumer behavior, and economic stability. Shifts in consumer privacy preferences or new competitive entries could alter market trajectories. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Wearable Fitness Technology
Body Sensors Market
Wearable Fitness Technology
Breathing Wear Market
Wearable Fitness Technology
Global Consumer Smart Wearable Market
Wearable Fitness Technology
Sports Headbands Market
Wearable Fitness Technology
Wearable Sensors Market
Wearable Fitness Technology
Wearable Fitness Tracker Market
Wearable Fitness Technology
Sports Technology Market
Wearable Fitness Technology
North America Smart Watch Market
Wearable Fitness Technology
Pocket Pedometers Market
Wearable Fitness Technology
Swim Watches Market
Wearable Fitness Technology
North America Wearable Sensors Market
Wearable Fitness Technology
Smart Wearable Equipment Market
Wearable Fitness Technology
Smart Insole Market
Wearable Fitness Technology
Stress Tracking Devices Market
Wearable Fitness Technology
Wearable Inertial Sensors Market
Wearable Fitness Technology
Smart Fitness Watches Market