
 Global Consumer Smart Wearable Market | 2026-2036
Global Consumer Smart Wearable Market Size, Share, and Industry Trends Forecast 2026-2036
Global Consumer Smart Wearable Market Foresight
The gap between dedicated fitness hardware and full-featured smartwatches is narrowing as sensor miniaturization and edge AI converge on single-wrist platforms. Apple leverages its semiconductor design pipeline to sustain vertical integration from silicon to software. Samsung Electronics anchors global manufacturing scale across multiple wearable form factors. Xiaomi Corporation competes aggressively on cost-optimized hardware with stripped-down operating systems.
Consumer smart wearables are body-worn electronic devices incorporating microelectromechanical sensors, biometric photodetectors, and low-power wireless chipsets to capture physiological and environmental data for real-time feedback or cloud-synced analysis. Their primary commercial purpose spans preventive health surveillance, athletic performance optimization, and ambient computing interfaces. Smartwatches dominate absolute revenue contribution due to premium pricing and cellular-enabled independence from smartphones. Fitness trackers retain volume leadership in emerging markets where price sensitivity shapes purchasing behavior. Hearables represent the fastest-expanding margin pool as active noise cancellation and hearing-aid functionality converge under FDA over-the-counter hearing aid regulations.
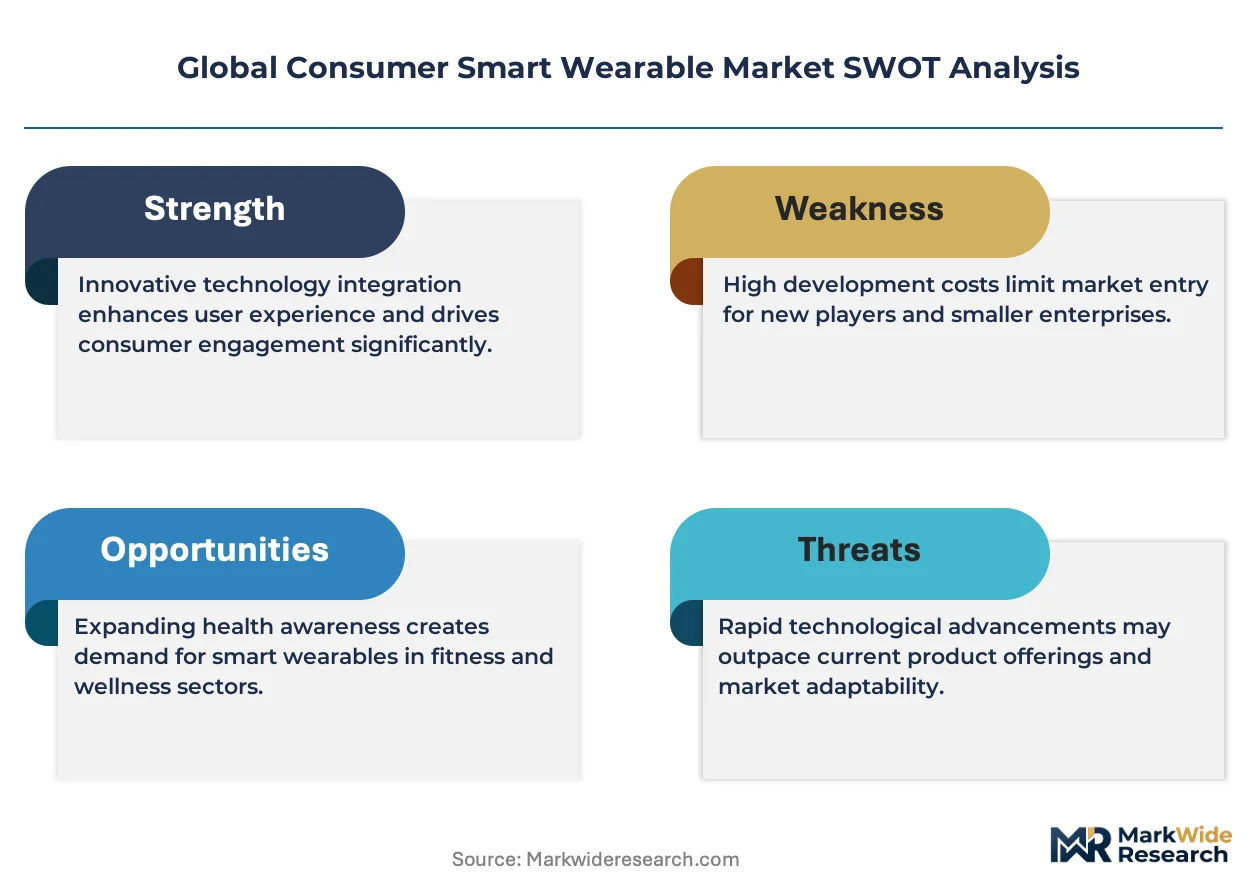
FDA clearance pathways for blood glucose prediction and atrial fibrillation detection are elevating clinical-grade accuracy requirements across the industry. EMA's Medical Device Regulation and the EU AI Act impose combined conformity obligations on algorithm-driven health insights sold in European markets. China's NMPA and GB standards mandate cybersecurity certifications for networked medical functions in domestically sold devices. Stakeholders must monitor whether regulatory divergence between Washington, Brussels, and Beijing fragments firmware development into region-locked variants or drives unified global platforms.
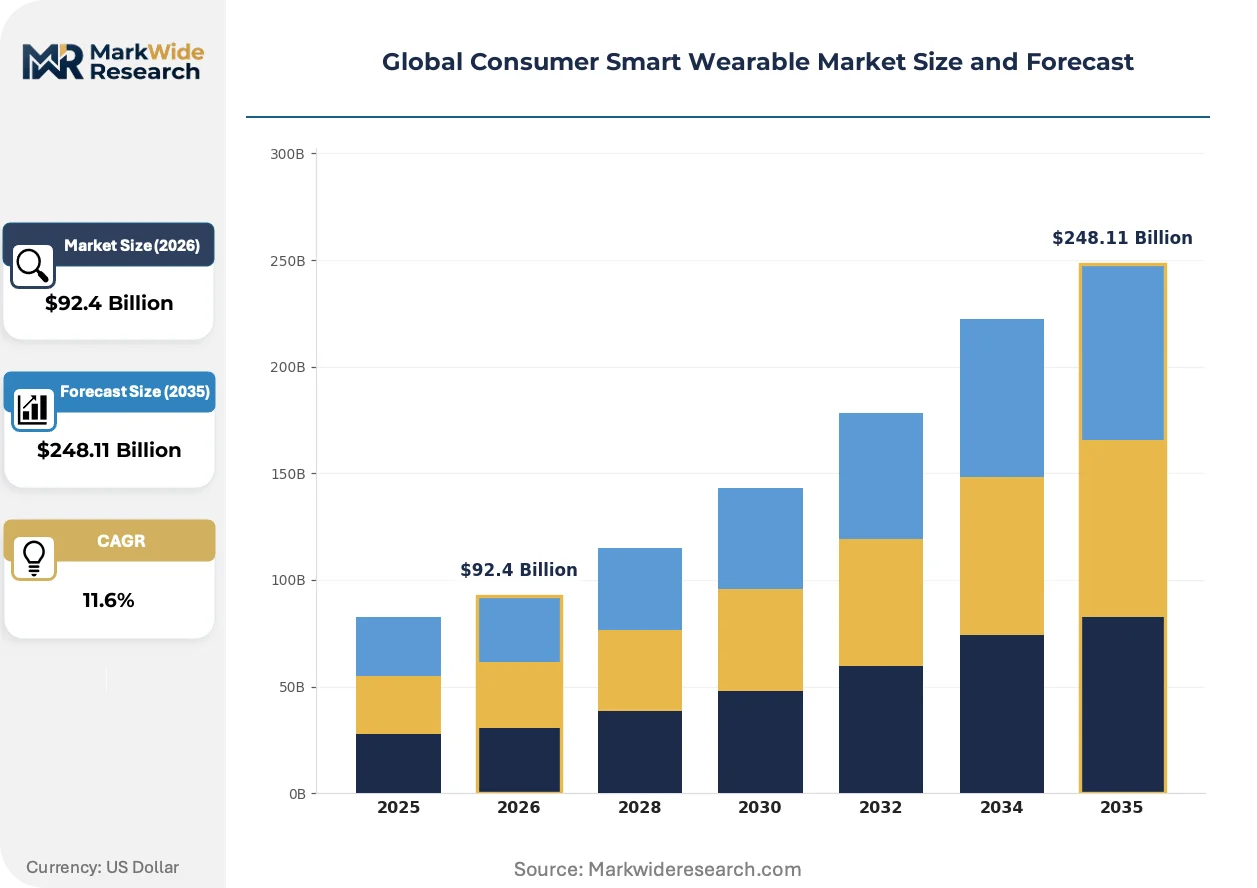
Market Dynamics
Algorithmic transparency mandates from Brussels, Washington, and Beijing are forcing firmware architectures to bifurcate into region-specific compliance variants, raising development costs while fragmenting the addressable user base for unified global platforms.
Growth Catalysts
- FDA De Novo Pathways:Clearance frameworks for atrial fibrillation detection and blood glucose prediction are elevating clinical-grade sensor accuracy requirements, pulling medical device capabilities into consumer-priced hardware.
- Preventive Care Pivot:Chronic disease management among elderly populations is shifting from episodic treatment to continuous physiological surveillance, expanding the addressable demographic for health-monitoring wearables.
- Edge AI Convergence:On-device neural processing units are enabling real-time biometric analysis without cloud dependency, satisfying GDPR data-localization requirements while reducing latency for critical health alerts.
Market Restraints
- Lithium-Polymer Cost Volatility:Battery chemistry price swings constrain margin stability in sub-premium form factors where component costs dominate bill-of-materials calculations.
- Foundry Concentration Risk:Advanced semiconductor fabrication for biometric photodetectors concentrates among Taiwan-based and South Korea-based suppliers, exposing production schedules to geopolitical friction.
- EU AI Act Compliance Friction:Algorithmic transparency documentation requirements for biometric data processing impose documentation burdens that slow firmware release cycles and inflate legal review costs.
Strategic Opportunities
- India Preventive Health Infrastructure:Digital health mission investments and rising smartphone penetration create white space for cost-optimized fitness trackers with localized chronic disease management protocols.
- Hearing-Aid Convergence:FDA over-the-counter hearing aid regulations are collapsing the boundary between consumer audio devices and medical hearing assistance, opening margin expansion in aging populations.
- Photoplethysmography-ECG Fusion:Combined optical and electrical cardiac sensing is enabling new arrhythmia detection modalities that satisfy both consumer wellness and clinical screening use cases.
Industry Challenges
- Biomedical Algorithm Validation Talent Scarcity:Shortages of engineers capable of bridging signal processing and clinical evidence generation are extending FDA submission preparation timelines.
- Multi-Jurisdiction Certification Complexity:Simultaneous pursuit of FDA 510(k), EMA MDR, and NMPA approvals requires parallel documentation streams that strain regulatory affairs bandwidth.
- Legacy Hospital EMR Integration:Consumer device data formats lack standardized interoperability with Epic and Cerner systems, limiting physician adoption of patient-generated health data.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Consumer Smart Wearable Market |
| Market Size in 2026 | $92.4 Billion |
| Market Size in 2035 | $248.11 Billion |
| CAGR (2026 – 2036) | 11.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Smartwatches, Fitness Trackers, Smart Glasses, Hearables, Smart Clothing Technology: Bluetooth Low Energy, Wi-Fi, NFC, GPS, Cellular Application: Health Monitoring, Sports & Fitness, Lifestyle Management, Communication, Navigation End User: Tech Enthusiasts, Athletes, Elderly, Students, Professionals |
| Companies Covered | Apple, Samsung Electronics, Huawei Technologies, Garmin, Xiaomi Corporation, Google, Zepp Health Corporation, Withings, Polar Electro, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Consumer Smart Wearable Market Shifts & Advancements
Sensor miniaturization and on-device intelligence are collapsing functional boundaries between discrete wearable categories, creating new competitive arenas where medical accuracy, consumer aesthetics, and ambient computing interfaces converge.
Photoplethysmography arrays with multi-wavelength LED configurations are hybridizing continuous SpO2 monitoring with hydration and stress biomarker estimation. Athletic performance specialists and remote patient monitoring programs are adopting these fused sensing stacks ahead of general wellness consumers. The technology is hybridizing previously separate device categories—pulse oximeters, stress trackers, and sleep monitors—into single-wrist platforms that compress average revenue per user capture timelines.
The EU AI Act's risk-classification framework for biometric inference algorithms is mandating conformity assessment procedures that previously applied only to medical devices. Manufacturers must now document training data provenance and algorithmic decision logic for health insights sold in European markets. Fitness-oriented smartwatches with blood oxygen or heart rate variability features face the steepest compliance ramps, with several vendors pursuing notified body partnerships ahead of enforcement deadlines.
Enterprise wellness programs are unbundling hardware procurement from subscription analytics, forcing vendors to prove standalone software value. Self-insured employers in the United States are piloting outcomes-linked contracts where device deployment costs tie to measured biometric improvement rather than per-employee fees. This purchasing model is most visible among Fortune 500 manufacturing and logistics employers seeking to compress workers compensation claims through musculoskeletal strain prevention.
Global Consumer Smart Wearable Market Segmentation
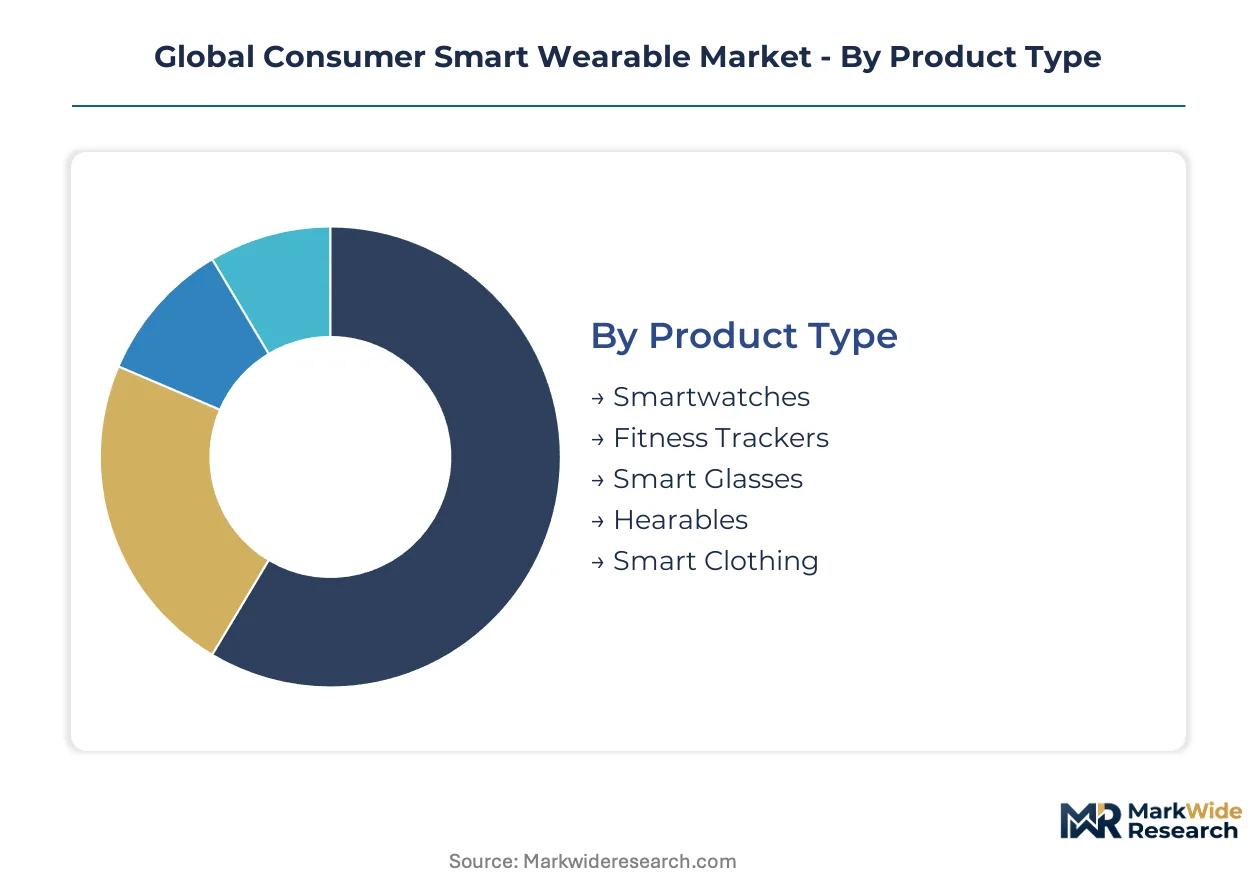
Segmentation in the consumer smart wearable market reveals how sensor miniaturization and connectivity convergence are collapsing historical boundaries between medical devices, fitness equipment, and ambient computing platforms. Understanding these divides helps vendors calibrate hardware specifications against distinct regulatory thresholds and purchasing decision frameworks.
Product Type:
Smartwatches and fitness trackers anchor opposite ends of the use-case spectrum, while hearables and smart glasses represent emerging form factors where medical-grade functionality and consumer audio/visual experiences intersect.
- Smartwatches:Full-featured wrist-worn computers integrating multi-wavelength photoplethysmography, electrochemical glucose sensors, and cellular basebands for smartphone-independent operation. Demand concentrates among elderly users in Germany and the United States where FDA-cleared atrial fibrillation detection satisfies preventive care reimbursement incentives.
- Fitness Trackers:Stripped-down biometric bands optimized for step counting, sleep staging, and basic heart rate monitoring through reduced-complexity operating systems. Volume leadership persists in India and Southeast Asia where sub-premium price points align with first-time wearable adoption curves.
- Smart Glasses:Optical waveguide displays combined with camera arrays and bone-conduction audio for heads-up navigation and remote assistance workflows. Enterprise logistics pilots in the United States and Japan are validating hands-free picking and assembly guidance applications.
- Hearables:In-ear devices fusing active noise cancellation with FDA over-the-counter hearing aid amplification under emerging acoustic classification rules. Aging demographics across Japan, Germany, and the United States are collapsing the boundary between consumer audio and clinical hearing assistance.
- Smart Clothing:Textile-integrated electromyography and temperature sensors woven into athletic apparel and clinical compression garments. Professional sports teams in Australia and rehabilitation clinics in Switzerland are piloting continuous biomechanical strain monitoring.
Established volume favors fitness trackers; emerging adoption favors hearables.
Technology:
Connectivity architecture selection determines power budgets, data sovereignty compliance, and real-time responsiveness for critical health alerts.
- Bluetooth Low Energy:Dominant short-range protocol enabling multi-day battery life through asymmetric radio duty cycling and simplified pairing with smartphones. Ubiquitous deployment across all price tiers makes this the default connectivity layer for biometric data offload.
- Wi-Fi:Higher-throughput wireless standard supporting firmware over-the-air updates and cloud-synced sleep staging analysis without smartphone tethering. Premium smartwatches in the United States leverage Wi-Fi for home-based continuous glucose monitor data bridging.
- NFC:Near-field contactless interface enabling payment tokenization and medical device pairing through tap-to-authenticate workflows. Transit payment integration in South Korea and Japan drives inclusion in mid-tier wrist-worn devices.
- GPS:Satellite positioning for route tracking, geofenced safety alerts, and fall detection location transmission. Outdoor fitness enthusiasts and elderly wandering-risk populations in rural Germany and Australia represent concentrated demand pockets.
- Cellular:Embedded LTE/5G basebands eliminating smartphone dependency for emergency services contact and real-time remote patient monitoring data streaming. Elderly users with limited technology literacy in the United States and Japan absorb premium hardware costs for independence assurance.
Bluetooth Low Energy dominates shipment volumes; cellular connectivity commands the steepest hardware premium expansion.
Application:
Application segmentation tracks how physiological sensing capabilities are migrating from athletic optimization toward clinical screening and chronic disease prevention.
- Health Monitoring:Continuous cardiac rhythm surveillance, blood oxygen saturation tracking, and sleep apnea screening with algorithmic outputs approaching clinical-grade sensitivity. FDA De Novo clearances for atrial fibrillation and blood glucose prediction are elevating accuracy requirements across this entire application category.
- Sports & Fitness:VO2 max estimation, recovery readiness scoring, and training load balancing for amateur and professional athletes. Triathlon and marathon communities in Australia and the United States drive demand for multi-sport GPS tracking and lactate threshold approximation.
- Lifestyle Management:Stress biomarker detection, hydration estimation, and circadian rhythm coaching for wellness-oriented consumers without diagnosed conditions. Corporate wellness programs in Germany and the United States are unbundling hardware from subscription analytics in this segment.
- Communication:Voice calling, notification triage, and quick-reply messaging through wrist-worn or ear-worn interfaces. Productivity-focused professionals in urban China and the United States prioritize seamless smartphone handoff and calendar integration.
- Navigation:Turn-by-turn directions, points-of-interest discovery, and geofenced safety alerts through haptic feedback and audio cues. Tourism applications and elderly wandering prevention in Japan and Switzerland represent distinct demand concentrations.
Health monitoring commands the highest regulatory compliance burden; sports and fitness maintains the broadest geographic penetration.
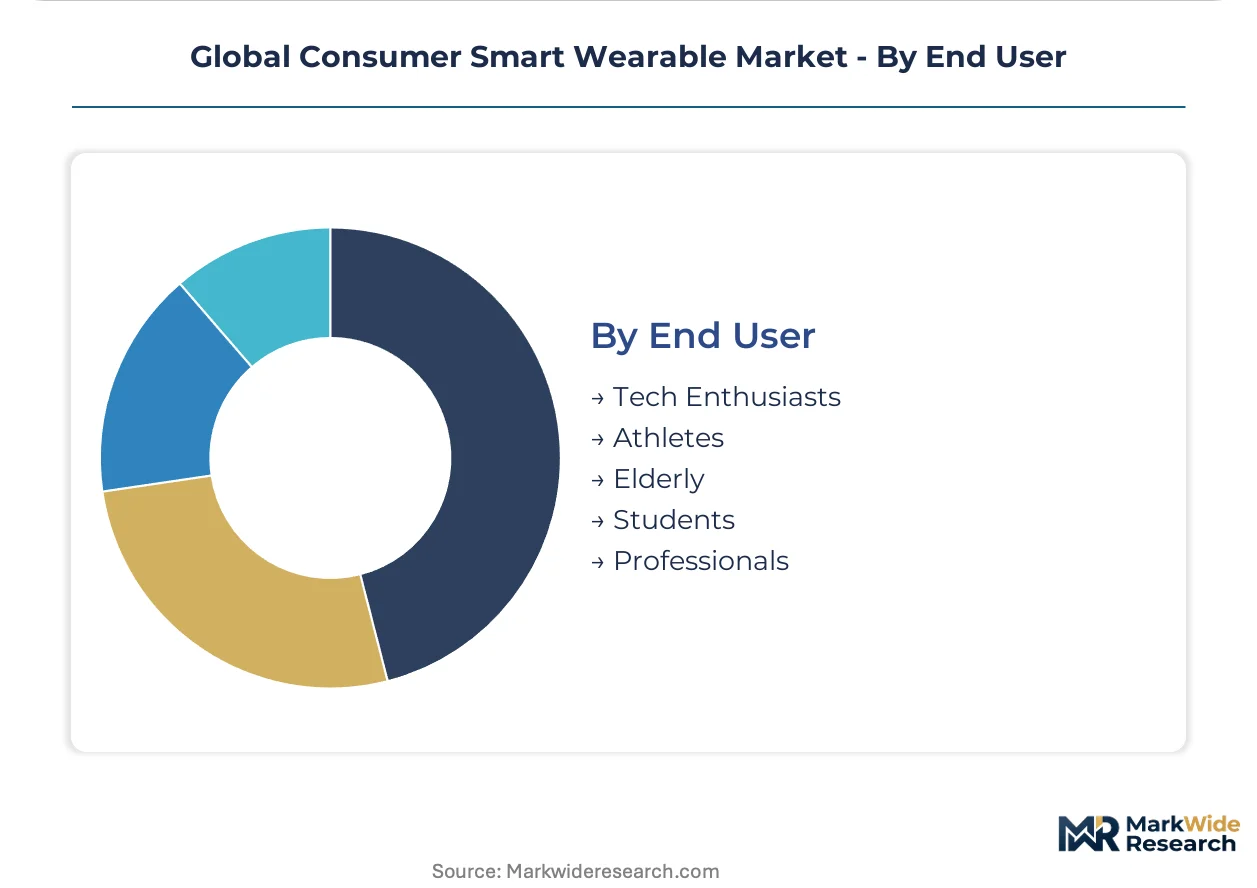
End User:
End user segmentation exposes divergent willingness-to-pay thresholds and feature prioritization across demographic and psychographic profiles.
- Tech Enthusiasts:Early adopters prioritizing cutting-edge sensor arrays, developer API access, and seamless ecosystem integration across multiple device categories. This cohort in the United States and South Korea absorbs premium pricing for first-mover feature availability.
- Athletes:Performance-obsessed users demanding validated training metrics, durability under extreme conditions, and sport-specific form factor optimization. Triathletes and trail runners in Australia and Switzerland represent concentrated demand for ruggedized GPS watches with extended battery endurance.
- Elderly:Aging populations requiring simplified interfaces, fall detection with automatic emergency contact, and FDA-cleared cardiac monitoring for physician trust. Preventive care pivots in Germany, Japan, and the United States are expanding this addressable demographic fastest.
- Students:Price-sensitive younger users prioritizing notification management, music control, and social connectivity over medical-grade sensing. Educational pricing programs and parental purchase influence shape this segment in China and India.
- Professionals:Workplace-focused users seeking calendar integration, discreet notification filtering, and enterprise security compliance for BYOD policies. Financial services and consulting employers in the United Kingdom and Singapore are piloting wellness-linked device subsidies.
Elderly users represent the fastest-expanding margin pool; students anchor volume leadership in emerging market penetration.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export-import dynamics in consumer smart wearables reveal concentrated manufacturing in East Asian electronics clusters against premium consumption in Western healthcare markets. The United States and Germany absorb high-margin clinical-grade devices while China and Vietnam anchor component assembly and final integration.
United States
FDA De Novo clearances for atrial fibrillation detection and blood glucose prediction drive demand for clinical-grade smartwatches among Medicare Advantage populations. The 21st Century Cures Act mandates interoperability standards that push Epic and Cerner integration roadmaps. Silicon Valley semiconductor design houses and Boston digital health clusters concentrate algorithm development for elderly fall detection.
China
NMPA cybersecurity certifications and GB standards for networked medical functions reshape firmware architectures for domestic market entry. Dual carbon goals accelerate lithium-polymer recycling mandates across Shenzhen and Dongguan manufacturing zones. Xiaomi and Huawei anchor cost-optimized production while Shanghai-based AI labs advance edge neural processing for biometric analysis.
Germany
EMA Medical Device Regulation conformity assessments elevate documentation burdens for algorithmic health insights sold in European markets. Preventive care reimbursement incentives under statutory health insurance expand elderly adoption of continuous cardiac monitoring. Munich and Stuttgart industrial clusters concentrate precision photodetector fabrication for automotive-grade sensor migration into wearables.
India
Digital Health Mission infrastructure investments and PLI scheme subsidies for electronics manufacturing create white space for cost-optimized fitness trackers. CDSCO streamlined medical device rules accelerate local clinical trial pathways. Bangalore and Hyderabad software clusters develop localized chronic disease management protocols for diabetes and hypertension surveillance.
Japan
METI aging society technology roadmaps prioritize fall detection and wandering prevention for rural elderly populations. PMDA harmonization efforts with FDA streamline approval pathways for combined consumer-medical devices. Tokyo and Osaka precision manufacturing clusters miniaturize electrochemical sensors for hearable glucose monitoring integration.
Global Consumer Smart Wearable Market Competitive Landscape
On the supply side, the industry is consolidating around vertically integrated semiconductor-to-software pipelines while fragmenting across specialized sensor vendors and regional assembly networks. Three strategic archetypes dominate: ecosystem platform owners controlling silicon design and health data infrastructure; scale manufacturers optimizing cost-engineered hardware for emerging market volume; and clinical-grade specialists pursuing FDA-cleared medical device positioning. Competitive moves center on backward integration into biometric photodetector fabrication and strategic partnerships with hospital EMR vendors for physician trust.
Within the ecosystem platform tier, Apple exemplifies captive semiconductor design extending from custom neural engines through health data encryption. Samsung Electronics anchors multi-form-factor manufacturing scale across smartwatches, hearables, and fitness bands. Xiaomi Corporation occupies the cost-optimized volume position, stripping down operating systems to hit sub-premium price points in India and Southeast Asia.
| Leading Market Players |
|---|
| Apple |
| Samsung Electronics |
| Huawei Technologies |
| Garmin |
| Xiaomi Corporation |
| Zepp Health Corporation |
| Withings |
| Polar Electro |
| Others |
Supply & Pricing Matrix
Shenzhen and Dongguan manufacturing clusters absorb lithium-polymer cost volatility through multi-tier supplier hedging, translating upstream chemistry price swings into segmented downstream pricing power. Foundry concentration in Taiwan and South Korea for biometric photodetectors compresses margin buffers at the premium tier while forcing cost-engineered tiers toward stripped-down sensor configurations.
Pricing Analysis
Next-generation cellular-enabled smartwatches command hardware premiums against prior-generation Bluetooth-tethered devices and emerging economy-tier fitness bands without baseband integration. Three-tier pricing structure across premium, standard, and economy levels stratifies by FDA certification status and cellular independence, with premium tiers absorbing neural processing unit costs while economy tiers sacrifice algorithmic accuracy for bill-of-materials containment. Cost compression in sub-premium form factors is intensifying because lithium-polymer chemistry price swings dominate component economics. Students and first-time adopters in India and Southeast Asia exhibit the steepest price sensitivity, whereas elderly Medicare Advantage populations in the United States absorb clinical-grade premiums for independence assurance.
Supply Chain Analysis
Tariff exposure between the United States and China dominates supply chain risk calculus for firmware-locked regional variants required by divergent AI Act and GDPR compliance mandates. Component fabrication concentrates in Taiwan, South Korea, and Vietnam, with final assembly drawing from Shenzhen, Dongguan, and Ho Chi Minh City manufacturing zones. Raw material dependencies center on lithium-cobalt oxide cathodes, multi-wavelength LED photodetectors, and advanced packaging substrates for neural processing units. Single-source vulnerability in Taiwan-based foundries for sub-7nm biometric sensor fabrication threatens production continuity during geopolitical friction. Distribution runs through enterprise wellness program procurement offices, consumer electronics retail chains, and direct-to-elderly telehealth platform partnerships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Hardware margins are compressing toward single-digit percentages while subscription analytics and remote patient monitoring service layers expand at multiples of device revenue growth. Vendors must restructure commercial models around recurring biometric data services rather than transactional wrist-worn unit sales.
For Market Incumbents: Pre-empt FDA De Novo clearance bottlenecks by accelerating biomedical algorithm validation hiring in Boston and Silicon Valley digital health clusters before submission timelines extend further. Backward integration into photodetector fabrication secures supply continuity against Taiwan foundry concentration risk. Defensive patent filings around photoplethysmography-ECG fusion architectures block emerging specialist entrants from arrhythmia detection positioning. For New Entrants and Emerging Players: India's Digital Health Mission infrastructure investments create the most penetrable white space for cost-optimized fitness trackers with localized diabetes and hypertension protocols. CDSCO streamlined medical device rules accelerate clinical trial pathways relative to FDA timelines. Enterprise wellness program unbundling trends favor software-only entrants proving standalone analytics value without hardware subsidy dependence. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors clinical-grade specialists with FDA-cleared cardiac monitoring and Epic EMR integration roadmaps over consumer wellness generalists facing EU AI Act compliance friction. Long-term viability hinges on physician trust conversion and reimbursement code capture rather than feature velocity. The signal to watch is Medicare Advantage preventive care incentive expansion for continuous glucose monitoring and fall detection reimbursement.| Strategic Initiative | Industry Significance |
|---|---|
| FDA De Novo Clearance Pathway | Elevates atrial fibrillation detection accuracy requirements across consumer-priced hardware tiers. |
| Notified Body Partnership | Accelerates EU AI Act conformity assessments for biometric inference algorithms in European markets. |
| Hospital EMR Integration | Enables physician adoption of patient-generated health data through Epic and Cerner interoperability. |
| Edge AI Neural Processing Investment | Satisfies GDPR data-localization mandates while reducing latency for critical health alerts. |
| Enterprise Wellness Program Partnership | Captures outcomes-linked contracts tying device deployment to measured biometric improvement. |
Research Methodology
Two parallel data streams informed the analysis: structured primary interviews with wearable device engineering leads, regulatory affairs specialists at FDA and EMA, hospital biomedical engineers, and enterprise wellness program procurement officers; and secondary validation against FDA 510(k) and De Novo filing databases, EMA Medical Device Regulation submission records, NMPA cybersecurity certification registries, and SEC 10-K component cost disclosures. Bottom-up triangulation across sensor bill-of-materials estimates and top-down reconciliation against cellular baseband shipment data anchored volume and value projections.
Forecast inputs span product type segmentation across smartwatches, fitness trackers, hearables, and smart glasses; connectivity architecture differentiation from Bluetooth Low Energy through cellular; application migration from sports and fitness toward health monitoring; and end-user demographic expansion among elderly populations. CAGRs were derived from regression analysis of historical adoption curves adjusted for regulatory enforcement timelines and reimbursement policy shifts. Edge AI processing capability diffusion and lithium-polymer cost volatility curves served as primary sensitivity inputs across the projection horizon.
The forecast holds incumbent behavior within observed patterns; aggressive moves by ecosystem platform owners into captive photodetector fabrication or hospital EMR acquisition would shift outcomes beyond modeled ranges. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Wearable Fitness Technology
Sports Technology Market
Wearable Fitness Technology
Sports Headbands Market
Wearable Fitness Technology
Global Weight Management Devices Market
Wearable Fitness Technology
Pedometer Market
Wearable Fitness Technology
Wearable Band Market
Wearable Fitness Technology
Wearable Inertial Sensors Market
Wearable Fitness Technology
Wearable Fitness Tracker Market
Wearable Fitness Technology
Australia Wearables Market
Wearable Fitness Technology
Smart Wearable Gloves Market
Wearable Fitness Technology
Global GPS Watch Tracker Market
Wearable Fitness Technology
Stress Tracking Devices Market
Wearable Fitness Technology
GPS Watches for Kids Market
Wearable Fitness Technology
Flexible Wearable Device Market
Wearable Fitness Technology
Smart Fitness Watches Market
Wearable Fitness Technology
Wearable Motion Sensors Market
Wearable Fitness Technology
Global Smart Wearable Fitness and Sports Devices Market