
 Sports Analytics Solutions Market | 2026-2036
Sports Analytics Solutions Market Size, Share, and Industry Trends Forecast 2026-2036
Sports Analytics Solutions Market Analytics
Mid-market collegiate athletic departments are redrawing procurement patterns for sports analytics solutions as budget allocations shift from traditional scouting toward data-driven performance programs. Catapult Group International Ltd leverages wearable biomechanics expertise to dominate elite team contracts across contact sports. Hudl sustains broad market penetration through accessible video-analysis platforms designed for high school and amateur programs. IBM Corporation anchors enterprise-scale deployments with AI-powered cognitive computing layers that process multimodal game data.
Sports analytics solutions encompass integrated software and hardware systems that capture, process, and visualize athletic performance metrics through sensor fusion, computer vision algorithms, and statistical modeling engines. These platforms serve commercial purposes spanning competitive optimization, broadcast enhancement, and revenue generation through personalized fan experiences. Cloud-based deployment leads structural growth due to elastic compute requirements during live events and seasonality patterns. Performance analysis occupies the deepest margin pools where proprietary algorithms create switching costs for professional clients. Player tracking applications accelerate fastest as computer vision costs decline and real-time edge processing matures.
FCC guidelines on wireless spectrum allocation shape wearable transmission protocols in US professional leagues, while GDPR compliance requirements in Europe constrain cross-border athlete data flows and biometric storage architectures. ISO standards for sports technology interoperability increasingly influence procurement specifications for league-wide platform standardization. Stakeholders must monitor evolving jurisdictional data sovereignty frameworks that fragment cloud architecture decisions across multi-territory league operations.
Market Dynamics
Real-time edge processing architectures are compressing decision latency in professional sports, forcing infrastructure investments that privilege milliseconds over cost optimization. Cloud elasticity during live events now dictates platform selection criteria across collegiate and professional tiers.
Growth Catalysts
- Computer vision cost curves:Declining sensor hardware expenses enable mass deployment of optical tracking systems across mid-market athletic departments previously priced out of automated analysis.
- FCC spectrum allocation frameworks:Wireless transmission protocols for wearable devices gain regulatory clarity in US professional leagues, accelerating biometric data capture without interference constraints.
- Biometric monitoring mandates:Player associations in contact sports negotiate collective bargaining provisions requiring predictive injury modeling, institutionalizing analytics procurement as operational necessity rather than competitive advantage.
Market Restraints
- GDPR biometric storage constraints:European athlete data flows face cross-border friction, fragmenting cloud architecture decisions for multi-territory league operations and inflating compliance overhead.
- Edge hardware supply concentration:Specialized GPU and TPU components for real-time video processing concentrate among Taiwanese and South Korean foundries, exposing deployment timelines to geopolitical supply shocks.
- Legacy system integration debt:Decades of proprietary scouting databases resist API standardization, forcing expensive middleware layers that erode SaaS margin structures for analytics vendors.
Strategic Opportunities
- High school athletic federations:Underpenetrated amateur programs in Texas, Florida, and California represent scalable subscription volume as video-analysis platforms democratize downward from collegiate tiers.
- ISO interoperability standards:Emerging league-wide procurement specifications create first-mover advantages for vendors achieving certification ahead of mandated standardization cycles.
- Generative AI and broadcast convergence:Automated highlight generation and personalized fan experiences unlock revenue streams beyond competitive optimization, attracting media-rights holders as new buyer segments.
Industry Challenges
- Data science talent scarcity:Sports-specific biomechanics expertise commands premium compensation, constraining vendor scaling and forcing reliance on generalist ML engineers with steep domain-learning curves.
- Algorithmic audit requirements:Player unions and insurers demand explainable injury-prediction models, complicating proprietary black-box architectures that vendors resist disclosing.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Sports Analytics Solutions Market |
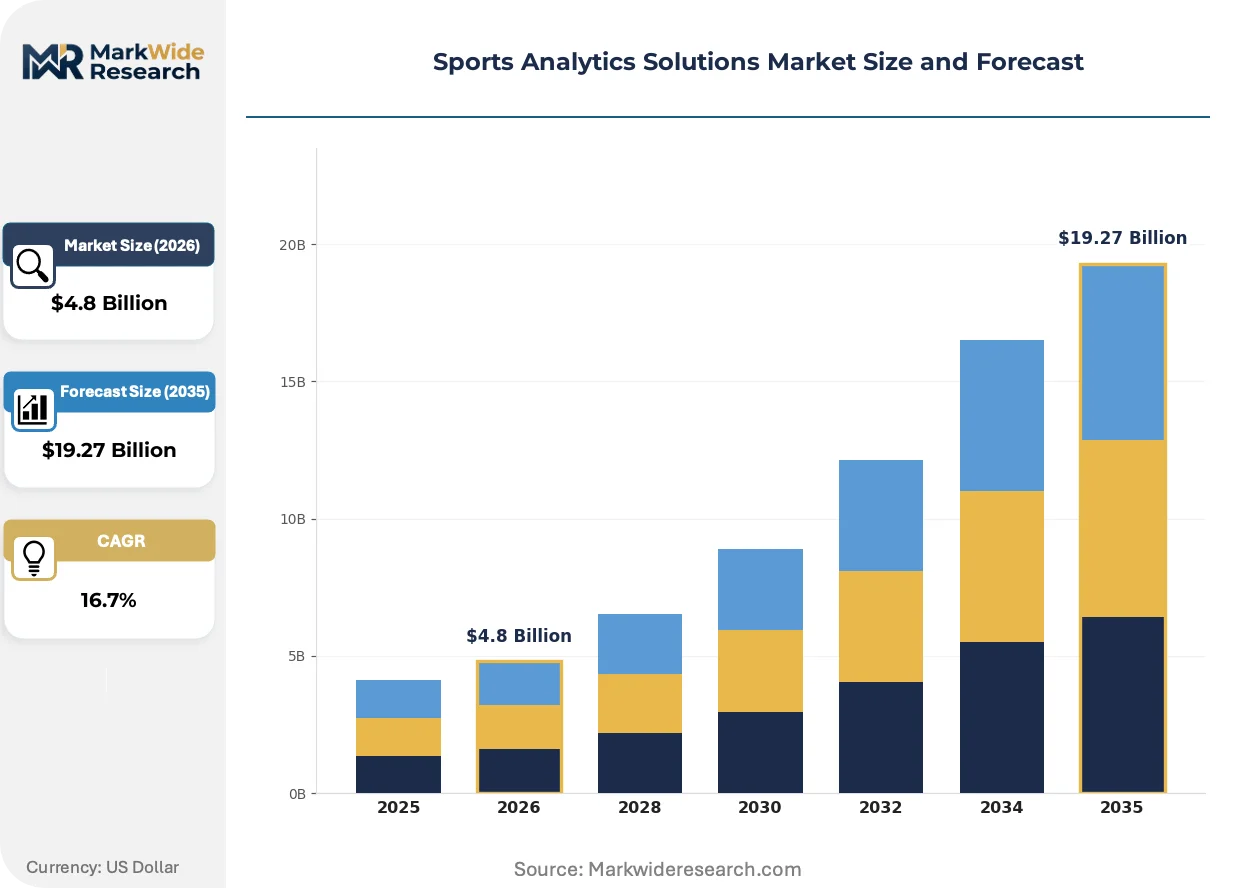
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $19.27 Billion |
| CAGR (2026 – 2036) | 16.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Performance Analysis, Fan Engagement, Team Management, Injury Prevention Deployment: On-Premise, Cloud-Based, Hybrid, Software as a Service End User: Sports Teams, Leagues, Coaches, Media Outlets Application: Player Tracking, Game Strategy, Fan Experience, Data Visualization |
| Companies Covered | IBM Corporation, SAP SE, SAS Institute Inc., Catapult Group International Ltd, Sportradar Group, Hudl, Stats Perform, Oracle Corporation, Deltatre S.p.A., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Sports Analytics Solutions Market Evolving Landscape
Sensor fusion architectures are redefining performance capture granularity, compressing the gap between laboratory-grade biomechanics and field-deployable hardware. Three convergent developments dominate vendor roadmaps and procurement specifications.
Wearable inertial measurement units are miniaturizing below 10-gram thresholds while preserving nine-axis precision, enabling non-intrusive deployment in protective equipment previously hostile to bulky electronics. National Football League equipment managers now mandate sub-5mm profile constraints for shoulder-pad integration. This form-factor compression is miniaturizing the addressable market downward from elite professionals to collegiate programs with stricter comfort and safety protocols.
EU AI Act risk-classification frameworks are imposing algorithmic transparency obligations on predictive injury systems deployed in European football leagues. Vendors must document training data provenance and model drift monitoring for systems influencing athlete employment decisions. German Bundesliga clubs are responding by segregating biometric processing within EU-sovereign cloud regions, fragmenting previously unified global architectures.
Collegiate athletic departments are consolidating vendor relationships around integrated platform suites, abandoning point-solution procurement that stitched video analysis, wearables, and recruiting databases through brittle integrations. This bundling preference advantages full-stack providers over specialized best-of-breed vendors. The consolidation pattern is most visible in NCAA Power Five conferences where procurement committees now prioritize single-contract accountability over functional optimization.
Sports Analytics Solutions Market Segmentation
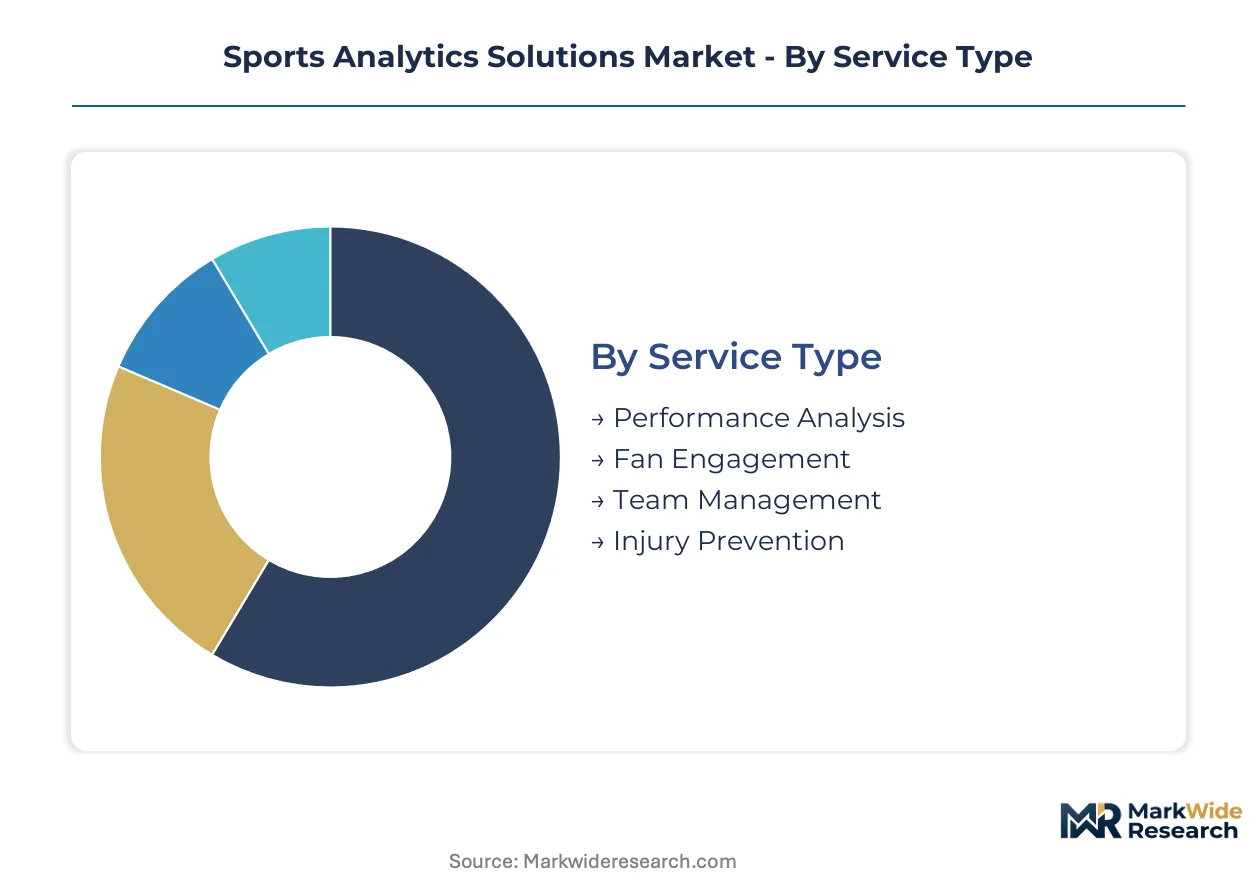
Sports analytics solutions fragment across four structural dimensions that determine procurement priorities. Service type dictates whether buyers prioritize competitive optimization or commercial revenue generation. Deployment architecture shapes compliance burdens and total cost of ownership across collegiate and professional tiers.
Service Type:
GDPR biometric storage constraints in Europe and FCC spectrum clarity in the United States create divergent regulatory pathways for each service category.
- Performance Analysis:Proprietary algorithms process multimodal game data through computer vision and sensor fusion architectures. Professional football clubs in England and Germany concentrate procurement here, driven by collective bargaining mandates for predictive workload management. Established volume favors Performance Analysis; emerging adoption favors Fan Engagement.
- Fan Engagement:Personalized content delivery and automated highlight generation leverage generative AI for broadcast enhancement. Media rights holders in the United States and streaming platforms in Brazil represent expanding demand centers as revenue diversification accelerates.
- Team Management:Integrated recruiting databases and roster optimization tools consolidate fragmented scouting workflows. NCAA Power Five conferences favor bundled platform suites over point solutions.
- Injury Prevention:Biomechanical monitoring and predictive modeling systems face algorithmic audit demands from player unions. ISO interoperability standards increasingly influence procurement specifications for league-wide deployments.
Established volume favors Performance Analysis; emerging adoption favors Fan Engagement.
Deployment:
Cost tier differentiation separates enterprise franchises from mid-market athletic departments with elastic compute requirements.
- Cloud-Based:Elastic infrastructure scales during live events and seasonality peaks without capital expenditure. Collegiate programs in Texas and Florida migrate here as video-analysis platforms democratize downward from elite tiers. Cloud-Based solutions are gaining share fastest as edge processing costs decline.
- Software as a Service:Subscription models reduce upfront procurement barriers for high school athletic federations. California and Florida amateur programs represent scalable volume as accessibility improves.
- Hybrid:Segregated architectures process sensitive biometric data within EU-sovereign regions while leveraging global compute for non-critical workloads. German Bundesliga clubs mandate this configuration.
- On-Premise:Legacy scouting databases and proprietary algorithms resist cloud migration due to security protocols. Established NFL franchises maintain these deployments for competitive secrecy.
Subscription economics dominate mid-market procurement; hybrid architectures satisfy multi-territory compliance.
End User:
Customer type determines functional requirements from real-time tactical decision-making to long-term strategic planning.
- Sports Teams:Wearable biomechanics and video-analysis platforms optimize individual athlete development. Professional contact sports organizations concentrate spending on injury-prediction systems with explainable model architectures.
- Leagues:Standardized data protocols and broadcast enhancement tools unify competitive integrity across franchises. ISO certification requirements shape vendor selection for league-wide platform procurement.
- Coaches:Mobile-optimized interfaces and rapid video tagging accelerate sideline decision latency. Collegiate and high school tiers prioritize intuitive workflows over algorithmic sophistication.
- Media Outlets:Automated content generation and personalized fan experiences unlock revenue streams beyond traditional broadcast rights. Streaming platforms represent the steepest expansion trajectory.
Franchise spending anchors platform development; media partnerships open adjacent revenue pools.
Application:
Technology maturity separates laboratory-grade precision from field-deployable accessibility across use cases.
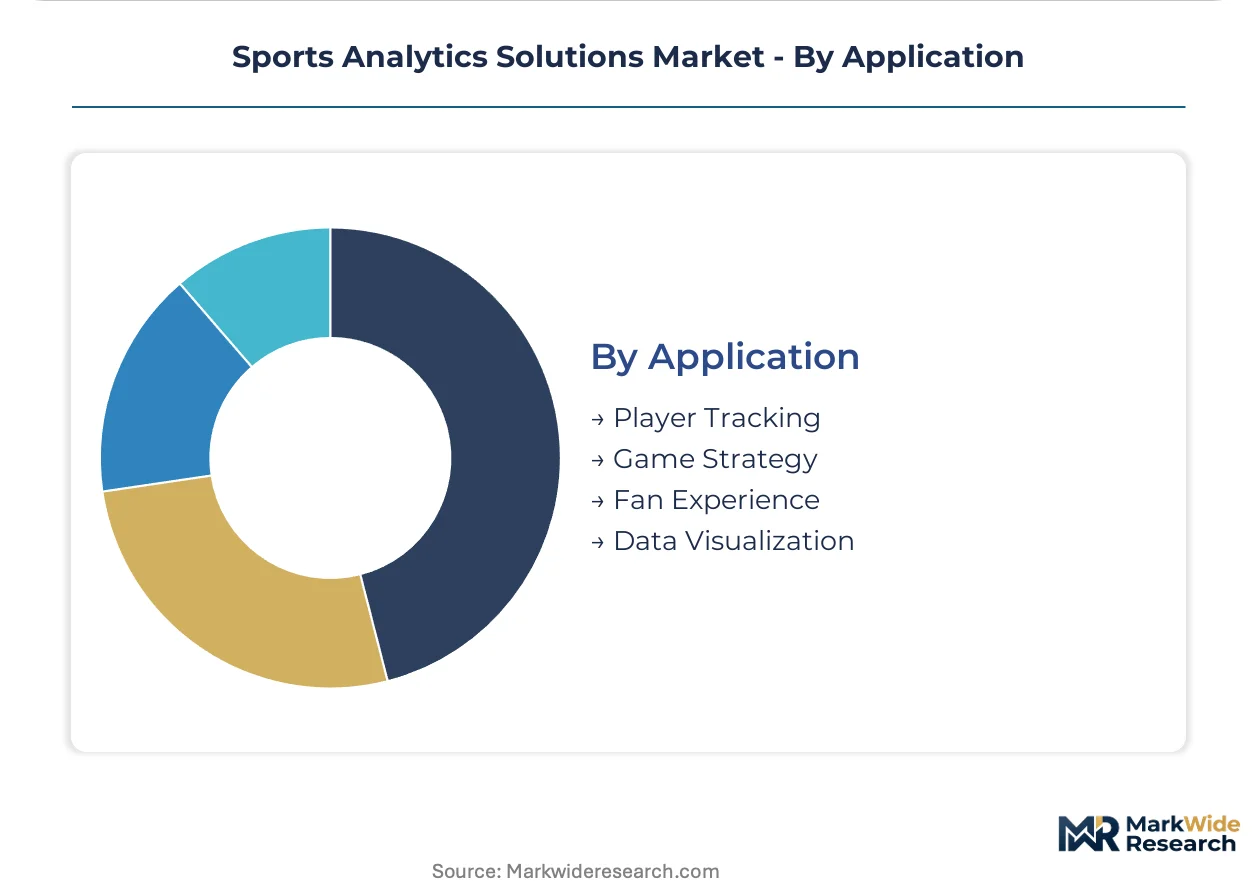
- Player Tracking:Miniaturized inertial measurement units below 10-gram thresholds enable non-intrusive deployment in protective equipment. NFL equipment managers now mandate sub-5mm profile constraints for shoulder-pad integration.
- Game Strategy:Real-time edge processing compresses decision latency during live competition. Cloud elasticity during events dictates infrastructure selection criteria.
- Fan Experience:Generative AI automates highlight curation and personalized content delivery. Broadcast convergence attracts media-rights holders as new buyer segments.
- Data Visualization:Statistical modeling engines translate complex biomechanical outputs into actionable coaching insights. Mid-market collegiate departments prioritize accessibility over customization depth.
Tracking hardware miniaturization accelerates adoption; visualization tools democratize access across budget tiers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Professional franchises and collegiate athletic departments concentrate procurement in mature sports economies with established league structures and regulatory clarity for biometric data capture.
United States
Major league franchises drive enterprise-scale deployments of AI-powered cognitive computing layers for multimodal game data processing. FCC guidelines on wireless spectrum allocation provide regulatory certainty for wearable transmission protocols in professional leagues. The Dallas-Fort Worth metroplex anchors concentrated demand from NCAA Power Five programs and NFL franchises investing in real-time edge processing infrastructure.
Germany
Bundesliga clubs command predictive workload management systems with explainable model architectures for player unions. EU AI Act risk-classification frameworks impose algorithmic transparency obligations on injury-prediction systems influencing employment decisions. Munich and Dortmund host segregated biometric processing within EU-sovereign cloud regions, fragmenting previously unified global architectures for multi-territory league operations.
United Kingdom
Premier League football clubs concentrate spending on proprietary algorithms with switching costs for competitive optimization. GDPR compliance requirements constrain cross-border athlete data flows and biometric storage architectures. London's sports technology cluster houses vendors serving both elite professional contracts and broadcast enhancement tools for media rights holders.
Australia
Contact sports organizations mandate miniaturized inertial measurement units for non-intrusive deployment in protective equipment. ISO standards for sports technology interoperability increasingly influence procurement specifications for league-wide platform standardization. Sydney and Melbourne anchor vendor development centers targeting Asia-Pacific expansion with regulatory-compliant hybrid cloud architectures.
Brazil
Streaming platforms and media rights holders represent expanding demand centers for automated highlight generation and personalized fan experiences. Emerging league-wide procurement specifications create first-mover advantages for vendors achieving certification ahead of mandated standardization cycles. São Paulo's sports media cluster attracts broadcast convergence investments from international analytics providers seeking Latin American volume.
Sports Analytics Solutions Market Competitive Landscape
Player mix skews toward full-stack platform providers with integrated hardware-software capabilities, though specialized best-of-breed vendors retain pockets of defensible positioning in video analysis and wearable biomechanics. Tiered competitive dynamics separate enterprise-scale cognitive computing deployments from accessible subscription models serving amateur tiers. Two strategic archetypes dominate: vertically integrated performance technology specialists and cloud-native broadcast enhancement platforms. Competitive moves concentrate on M&A for sensor fusion capabilities and strategic partnerships with media rights holders for revenue diversification beyond athletic departments.
Within the enterprise cognitive computing tier, IBM Corporation anchors deployments with AI-powered processing architectures. Catapult Group International Ltd exemplifies the wearable biomechanics specialist archetype through elite team contracts across contact sports. Hudl occupies a position within the accessible platform segment serving high school and amateur programs with video-analysis tools designed for intuitive workflows.
| Leading Market Players |
|---|
| IBM Corporation |
| SAP SE |
| SAS Institute Inc. |
| Catapult Group International Ltd |
| Sportradar Group |
| Hudl |
| Stats Perform |
| Oracle Corporation |
| Deltatre S.p.A. |
| Others |
Value Network & Pricing Analysis
Optical sensor substitution for wearable inertial units is redrawing component sourcing maps from Taiwanese foundries toward Chinese vision-hardware clusters while compressing per-unit platform economics for collegiate athletic departments previously priced out of automated tracking systems.
Pricing Analysis
Cost-plus contracts with semiconductor price indexation dominate enterprise deployments to NFL franchises and NCAA Power Five programs. Three-tier pricing structure across premium, standard, and economy levels separates full-stack platform suites from point-solution vendors and amateur-accessible subscriptions. Cost compression in the high school tier is intensifying because video-analysis platforms democratize downward from collegiate procurement patterns. Collegiate athletic departments exhibit highest price sensitivity due to budget committee oversight, while enterprise franchises prioritize latency performance over cost optimization.
Supply Chain Analysis
Extended lead times for specialized GPU and TPU components now stretch eighteen to twenty-four months for real-time edge processing hardware. Manufacturing concentrates in Taiwan, South Korea, and mainland China for advanced semiconductor fabrication. Component sourcing draws from gallium arsenide substrates, precision optics, and low-power wireless chipsets. Single-source vulnerability concentrates in Taiwanese foundry capacity for sub-7nm process nodes. Distribution runs through direct vendor relationships with franchise technology officers and collegiate procurement committees, bypassing traditional IT channel partners.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is shifting toward consolidated procurement committees in NCAA Power Five conferences, which now mandate single-contract accountability over best-of-breed functional optimization across video analysis, wearables, and recruiting databases.
For Market Incumbents: Shield proprietary algorithm portfolios through ISO interoperability certification investments that embed switching costs before mandated standardization cycles take effect. Deepen in-house production of miniaturized inertial measurement units below 10-gram thresholds to offset foundry concentration risk. Cloud-native broadcast enhancement platforms represent the most threatening entrant archetype as media-rights holders diversify revenue beyond athletic departments. For New Entrants and Emerging Players: Anchor in high school athletic federations across Texas, Florida, and California where subscription economics and intuitive mobile workflows remain underpenetrated by incumbent complexity. Amateur programs with sub-$50,000 annual technology budgets represent the most penetrable segment. A SaaS-tiered pricing model with rapid-deployment onboarding sequences offers the clearest go-to-market angle against entrenched collegiate-focused vendors. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed wearable biomechanics specialists holding elite team contracts but lacking full-stack platform breadth. Long-term viability over a multi-year horizon hinges on convergence toward integrated suites rather than point-solution persistence. The signal to watch is collective bargaining provisions mandating predictive injury modeling, which institutionalize analytics procurement as operational necessity rather than discretionary competitive advantage.| Strategic Initiative | Industry Significance |
|---|---|
| Sensor Fusion Capability Acquisition | Computer vision cost curves enable mass deployment of optical tracking across mid-market athletic departments. |
| EU-Sovereign Cloud Architecture Deployment | GDPR biometric storage constraints and EU AI Act transparency obligations fragment previously unified global processing architectures. |
| Media-Rights Holder Partnership Formation | Automated highlight generation unlocks revenue streams beyond competitive optimization for streaming platforms. |
| ISO Interoperability Certification Investment | League-wide procurement specifications create first-mover advantages ahead of mandated standardization cycles. |
| Edge Processing Infrastructure Buildout | Real-time decision latency requirements privilege milliseconds over cost optimization during live events. |
Research Methodology
Desk research of SEC filings from publicly traded sports technology vendors, hyperscaler capex disclosures for cloud infrastructure, and FCC spectrum allocation proceedings preceded structured interviews with collegiate athletic directors, professional franchise technology officers, sports data scientists, and wearable hardware procurement leads. Secondary validation drew from NCAA budget committee reports, player association collective bargaining documents, and ISO standards development records. Bottom-up segment sizing triangulated against top-down market envelope estimates from cloud service provider vertical revenue disclosures.
Variance decomposition across service type, deployment architecture, end user category, and application technology maturity shaped the analytical framework over the projection horizon. Modeled dimensions encompassed performance analysis versus fan engagement service lines, cloud-based versus hybrid versus on-premise deployment patterns, and player tracking versus game strategy versus data visualization applications. CAGRs were derived from elasticity-adjusted adoption curves and infrastructure investment trajectories. Forecast inputs incorporated computer vision hardware cost decline rates and regulatory compliance burden estimates for multi-territory league operations.
Material uncertainties — supply chain disruption in Taiwanese semiconductor foundries, collective bargaining renegotiation timelines, and jurisdictional data sovereignty framework evolution — sit outside the modeled envelope. Forecasts reflect documented assumptions about edge processing cost trajectories and amateur-tier subscription conversion rates. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Sports Analytics
Youth Sports Software Market
Sports Analytics
North America Fantasy Sports Market
Sports Analytics
Daily Fantasy Sports Market
Sports Analytics
Global Player Tracking Market
Sports Analytics
Europe Sports Analytics Market
Sports Analytics
Sports Analytics Market
Sports Analytics
Middle East and Africa Sports Analytics Market
Sports Analytics
Fantasy Sports Market
Sports Analytics
Player Tracking System Market
Sports Analytics
Asia-Pacific Sports Analytics Market
Sports Analytics
India Fantasy Sports Market