
 Pocket Pedometers Market | 2026-2036
Pocket Pedometers Market Size, Share, and Industry Trends Forecast 2026-2036
Pocket Pedometers Market Analytics
Chinese OEM component clusters is realigning final assembly economics for entry-level digital units. Fitbit leverages proprietary motion algorithms to sustain premium positioning in North American specialty retail. Garmin anchors its outdoor heritage into ruggedized smart pedometer variants for trail runners. Xiaomi competes on manufacturing scale, flooding online retail channels with sub-dollar analog alternatives that dominate emerging market volume.
A pocket pedometer is a portable, battery-powered motion sensor device that counts steps via piezoelectric or MEMS accelerometer mechanisms, typically displaying cumulative activity on an LCD or paired smartphone interface. Its primary commercial purpose is quantifying ambulatory movement for personal fitness management, insurance incentive programs, and clinical gait analysis. Bluetooth-enabled models now lead value generation by streaming continuous data streams to health platforms, while analog variants retain stubborn cost advantages in senior care facilities and developing rural clinics. Step counting remains the functional baseline, though sleep monitoring features are carving out disproportionate margin pools through subscription software tie-ins.
FDA clearance pathways for software-as-medical-device claims are tightening algorithm validation requirements for US-bound smart pedometers. Japan's METI enforces JIS standards for electromagnetic compatibility that filter out low-quality imports from Southeast Asian assembly houses. The EU AI Act and GDPR jointly pressure European vendors to localize biometric data processing rather than routing step patterns through offshore cloud infrastructure. Stakeholders must decide whether to absorb compliance costs through premium pricing or cede regulated segments to regionally entrenched competitors.
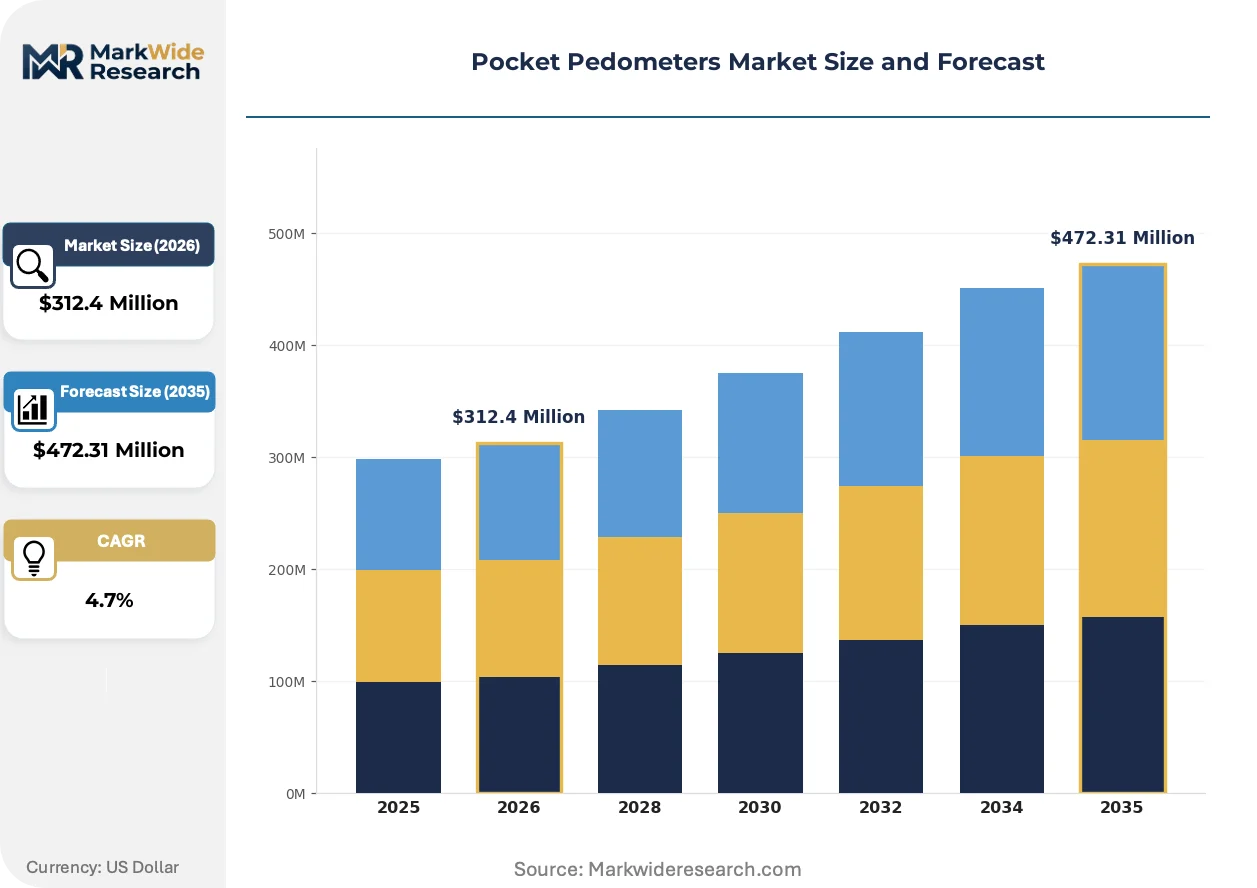
Market Dynamics
Bluetooth Low Energy integration is compressing power thresholds for always-on step counting, enabling continuous biometric streaming without daily charging cycles. This silicon efficiency gain is restructuring device economics and opening subscription revenue models previously locked to premium smartwatch tiers.
Growth Catalysts
- Corporate Wellness Mandates:Self-insured employers in the United States are deploying step-counting incentives through HIPAA-compliant platforms. Insurance premium reductions tied to activity thresholds are expanding device procurement volumes.
- Japan's METI JIS Standards:Electromagnetic compatibility certifications are filtering low-quality imports from Southeast Asian assembly houses. Domestic manufacturers gain protected shelf space in aging prefecture pharmacies.
- Piezoelectric Mechanism Miniaturization:Thinner ceramic sensors are enabling credit-card form factors. Wearable integration into employee ID badges and insurance cards is accelerating.
Market Restraints
- MEMS Accelerometer Supply Concentration:Taiwanese foundry capacity constraints are extending lead times for motion-sensing components. Foundry prioritization favors automotive and smartphone contracts.
- EU AI Act Biometric Processing:GDPR-mandated data localization is forcing cloud architecture rebuilds. Offshore step-pattern analytics face compliance discontinuation costs.
- Smartphone Native Step Counting:iOS Health and Android Google Fit are displacing dedicated hardware among price-sensitive casual users. Device commoditization pressures entry-margin pools.
Strategic Opportunities
- Germany's Preventive Health Networks:Regional insurer consortiums are prescribing pedometers for diabetes management. Reimbursement codes are creating institutional procurement channels.
- Sleep-Monitoring Subscription Tie-ins:Software-as-medical-device claims are carving margin pools beyond hardware sales. Algorithm validation investments are gating premium positioning.
- Clinical Gait Analysis:Orthopedic rehabilitation centers are adopting calibrated units for post-surgical mobility tracking. Medical-grade certification opens reimbursement-protected segments.
Industry Challenges
- FDA 510(k) Software Validation:Algorithm-as-device pathways are tightening clinical evidence requirements. Diagnostic claim submissions face extended review timelines.
- Multi-Protocol Firmware Integration:Simultaneous support for Bluetooth, ANT+, and proprietary health platform APIs is fragmentating engineering resources. Legacy code maintenance consumes release velocity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Pocket Pedometers Market |
| Market Size in 2026 | $312.4 Million |
| Market Size in 2035 | $472.31 Million |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Digital, Analog, Smart, Bluetooth-Enabled Feature: Step Counting, Calorie Tracking, Distance Measurement, Sleep Monitoring End User: Athletes, Fitness Enthusiasts, Seniors, Health Enthusiasts Distribution Channel: Online Retail, Specialty Stores, Supermarkets, Fitness Centers |
| Companies Covered | Fitbit, Garmin, Xiaomi, Omron, Huawei Technologies, WeLoop, Lifesense Group, NIKE, Jawbone, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Pocket Pedometers Market Evolving Landscape
Edge computing architectures are relocating step-pattern analysis from cloud servers onto device silicon. This migration is compressing latency for real-time coaching feedback and reducing data transmission costs for always-on wearables.
On-device machine learning inference is decentralizing algorithm execution from smartphone apps to pedometer firmware. Senior care facilities in Japan's Hokkaido and Aichi prefectures are piloting these units for fall-risk prediction without Wi-Fi dependency. Local processing eliminates HIPAA cloud-transfer vulnerabilities while enabling continuous monitoring in rural clinic dead zones.
The EU AI Act's biometric classification rules are forcing European vendors to re-architect data flows. Step-pattern analytics must now process within regional cloud boundaries rather than routing through Asian infrastructure. German and French health platforms are absorbing compliance costs through premium-tier pricing, ceding economy segments to regionally entrenched competitors.
Direct-to-employer procurement is displacing retail channel dominance for bulk device deployment. United States self-insured corporations are negotiating thousand-unit contracts bypassing Amazon and specialty fitness retailers. This channel compression is visible most acutely in manufacturing and logistics verticals where OSHA wellness mandates intersect with insurance cost containment programs.
Pocket Pedometers Market Segmentation
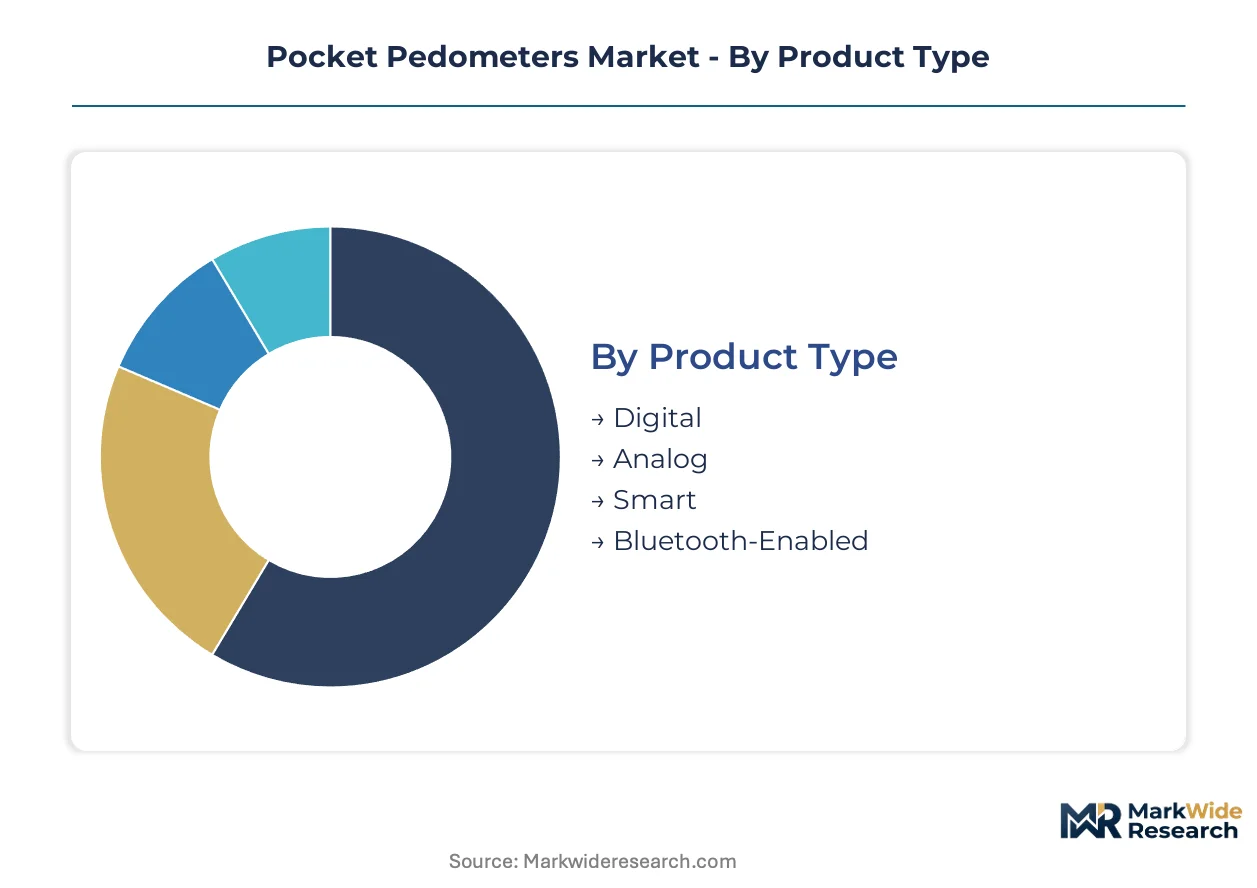
Pocket pedometers fragment across four distinct category axes. Product architecture determines power consumption and connectivity economics. Feature depth separates subscription-enabled premium tiers from disposable hardware. End-user targeting dictates channel strategy and reimbursement pathways. Distribution format shapes margin capture and brand positioning.
Product Type:
Customization spans from bare-bone mechanical units to firmware-programmable sensor platforms, with standardization concentrated in mid-tier digital variants.
- Digital:LCD-display units with piezoelectric or basic MEMS accelerometer cores. Demand concentrates in Japan's aging prefectures where METI JIS certification protects domestic pharmacy channels from uncertified imports.
- Smart:Firmware-programmable devices with on-device machine learning inference for real-time coaching. Expansion accelerates in Germany's preventive health networks where regional insurer consortiums prescribe units for diabetes management with full reimbursement codes.
- Analog:Mechanical pendulum mechanisms without electronic components. Retains stubborn cost advantages in developing rural clinics and senior care facilities with limited electrical infrastructure.
- Bluetooth-Enabled:BLE 5.0+ silicon enabling continuous biometric streaming to paired smartphones. Power threshold compression is restructuring device economics toward subscription revenue models.
Most installed capacity flows through Digital. Expansion is steepest in Smart.
Feature:
Functional depth correlates directly with margin tier, from commodity step counting to algorithm-validated medical claims.
- Step Counting:Baseline accelerometer function using piezoelectric ceramic or MEMS tilt detection. Volume concentrates in corporate wellness bulk procurement where OSHA mandates intersect with self-insured employer cost containment.
- Sleep Monitoring:Multi-axis movement pattern analysis with heart rate variability correlation. FDA 510(k) software validation requirements are gating premium positioning through clinical-grade algorithm claims.
- Calorie Tracking:Basal metabolic rate estimation fused with ambulatory intensity metrics. Personal fitness management apps drive integration demand.
- Distance Measurement:Stride-length calibration against GPS or manual input. Trail runner segments in ruggedized outdoor variants anchor this feature tier.
Step Counting captures the highest unit volumes. Sleep Monitoring is climbing the fastest on a value-per-unit basis.
End User:
Customer archetypes split between performance-optimized athletes and compliance-driven clinical populations.
- Seniors:Fall-risk prediction and medication adherence integration. Japan's Hokkaido and Aichi prefectures pilot edge-computing units with local processing eliminating HIPAA cloud-transfer vulnerabilities.
- Fitness Enthusiasts:Continuous biometric streaming with social platform integration. Direct-to-employer procurement channels are displacing Amazon and specialty fitness retailers for bulk deployment.
- Athletes:Calibrated units for post-surgical mobility tracking in orthopedic rehabilitation centers. Medical-grade certification opens reimbursement-protected segments.
- Health Enthusiasts:Preventive monitoring with insurance incentive tie-ins. iOS Health and Android Google Fit displacement pressures dedicated hardware adoption.
Seniors represent the most stable installed base. Fitness Enthusiasts are gaining share fastest through corporate channel compression.
Distribution Channel:
Channel selection determines whether margin accrues to hardware manufacturers or platform intermediaries.
- Online Retail:E-commerce platforms with algorithmic recommendation engines. Xiaomi manufacturing scale dominates this channel with sub-dollar analog alternatives flooding emerging market volume.
- Specialty Stores:Curated fitness retailers with trained staff and premium positioning. Fitbit proprietary motion algorithms sustain North American specialty retail presence against direct-to-consumer erosion.
- Supermarkets:Mass merchandising with impulse-purchase placement. Entry-margin pools face smartphone native step-counting displacement among price-sensitive casual users.
- Fitness Centers:Facility-integrated deployment with membership bundling. Corporate wellness mandates in United States manufacturing and logistics verticals drive thousand-unit contract negotiation bypassing traditional retail.
Online Retail channels the highest unit throughput. Fitness Centers are expanding most quickly on a contract-value basis.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are redistributing pocket pedometer assembly across jurisdictions with divergent electromagnetic compatibility and data localization mandates. Compliance cost differentials between developed certification regimes and emerging manufacturing bases are accelerating final-assembly migration.
United States
Self-insured employers in manufacturing and logistics verticals drive thousand-unit procurement contracts tied to OSHA wellness mandates. FDA 510(k) software validation requirements tighten algorithm evidence standards for diagnostic claims. Greater Boston hosts clinical gait analysis startups calibrating units for post-surgical mobility tracking.
Germany
Regional insurer consortiums prescribe smart pedometers for diabetes management with full reimbursement codes under preventive health networks. EU AI Act biometric classification rules force data localization within regional cloud boundaries. Baden-Württemberg medical device clusters absorb compliance costs through premium-tier pricing strategies.
Japan
METI enforces JIS electromagnetic compatibility standards that filter low-quality imports from Southeast Asian assembly houses. Aging prefectures including Hokkaido and Aichi pilot edge-computing units with local fall-risk prediction processing. Domestic manufacturers gain protected pharmacy shelf space in senior care corridors.
China
MIIT oversees GB standards for wearable device radio transmission that shape export qualification protocols. Shenzhen and Dongguan component clusters realign final assembly economics for entry-level digital units. Sub-dollar analog alternatives flood online retail channels across emerging market volume tiers.
South Korea
MFDS medical device regulations create parallel pathways for wellness versus diagnostic-grade step counters. Seoul Capital Area electronics conglomerates leverage captive MEMS foundry relationships for motion-sensing component supply. Daegu-Gyeongbuk health platforms integrate continuous biometric streaming into national insurance incentive architectures.
Pocket Pedometers Market Competitive Landscape
Chinese producers anchor the scale-driven tier; Japanese and German specialists hold certification-protected premium positions. The vendor base fragments across four distinct capability clusters: algorithm developers, manufacturing-scale operators, medical-grade certifiers, and platform-integrated service providers. Consolidation pressure concentrates among firmware-programmable smart device makers facing multi-protocol engineering complexity. Dominant competitive moves include direct-to-employer channel compression and edge-computing architecture licensing.
Within the algorithm-development tier, Fitbit and Garmin exemplify proprietary motion-software positioning against commoditized hardware. Xiaomi occupies a scale-manufacturing archetype leveraging component cluster proximity for cost compression. Omron represents the medical-grade certification pathway with institutional reimbursement channel access.
| Leading Market Players |
|---|
| Fitbit |
| Garmin |
| Xiaomi |
| Omron |
| Huawei Technologies |
| WeLoop |
| Lifesense Group |
| NIKE |
| Jawbone |
| Others |
Value Network & Pricing Analysis
MEMS accelerometer engineering talent concentrated in Hsinchu Science Park and Seoul Capital Area generates labor-cost differentials that widen pricing-tier spreads between firmware-programmable smart units and entry-level digital variants. Shenzhen assembly economics compress entry-margin pools while Baden-Württemberg certification investments sustain premium positioning.
Pricing Analysis
Distributor margin layers absorb 15-25 points before specialty retail markup, compressing manufacturer capture unless direct-to-employer channels bypass intermediaries entirely. Three-tier pricing structure across premium, standard, and economy levels separates FDA-validated sleep-monitoring subscriptions from METI-certified digital units and uncertified analog imports. Cost compression in economy tiers stems from smartphone native step-counting displacement among casual users. Corporate wellness procurement shows lowest price sensitivity; emerging market online retail exhibits highest.
Supply Chain Analysis
Workforce availability constraints in Taiwanese foundries and South Korean MEMS fabrication facilities are extending component lead times for motion-sensing silicon. Final assembly draws from China, Vietnam, and Mexico for tariff-advantaged export qualification. Raw material dependencies center on piezoelectric ceramics, lithium coin cells, and BLE 5.0+ radio modules. Single-source vulnerability concentrates in Taiwanese accelerometer wafer supply. Distribution runs through direct-to-employer procurement, e-commerce platforms, and institutional reimbursement channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in pocket pedometers rests on Bluetooth Low Energy silicon cost-down curves and sleep-monitoring subscription tier migration. Premium positioning is accelerating as algorithm validation investments gate medical-grade claims.
For Market Incumbents: Hedge against smartphone native step-counting displacement by deepening proprietary motion-software moats and securing FDA 510(k) software-as-medical-device clearances. Absorb compliance costs through direct-to-employer channel control rather than retail margin sharing. Vertical integration into edge-computing firmware development protects against commoditization. For New Entrants and Emerging Players: Rural senior care facilities in Japan's aging prefectures represent underserved buyer archetypes with limited electrical infrastructure and HIPAA cloud-transfer vulnerabilities. Clinical gait analysis partnerships with orthopedic rehabilitation centers offer white-space penetration. Germany's preventive health network reimbursement codes provide institutional go-to-market traction. For Investors and Strategic Acquirers: Corporate wellness platform operators are the most active acquirer in this space, seeking firmware-programmable device capabilities to complement HIPAA-compliant incentive architectures. Long-term viability favors algorithm-validated subscription models over hardware-only transactional revenue. Watch FDA software validation backlog clearance rates as inflection indicator for premium-tier acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Edge-Computing Architecture Licensing | Enables fall-risk prediction in Japan's Hokkaido senior care facilities without Wi-Fi dependency. |
| FDA 510(k) Software Validation Investment | Opens reimbursement-protected clinical gait analysis segments in orthopedic rehabilitation centers. |
| Direct-to-Employer Channel Compression | Bypasses Amazon and specialty fitness retailers for thousand-unit corporate wellness contracts. |
| EU AI Act Data Localization Compliance | Forces cloud architecture rebuilds that German and French vendors absorb through premium-tier pricing. |
| Piezoelectric Mechanism Miniaturization | Enables credit-card form factors for employee ID badge and insurance card integration. |
Research Methodology
Bottom-up end-user modeling reconciled against top-down supply-side tracking forms the analytical core of this study. Primary interviews with MEMS foundry procurement managers, corporate wellness program directors, hospital biomedical engineers, and pharmacy chain category buyers combine with secondary validation from FDA 510(k) filings, METI JIS certification databases, EU MDR technical documentation, and customs trade records. Triangulation across these sources ensures segmentation integrity.
Historical trendline analysis of Bluetooth Low Energy silicon cost curves and corporate wellness procurement volumes anchors projection frameworks. Modeled dimensions span product architecture, feature depth, end-user archetype, and distribution channel across the analysis window. CAGRs derive from fitted growth curves adjusted for regulatory approval timelines and reimbursement code expansion patterns. Forecast inputs include MEMS foundry capacity allocation priorities and smartphone native step-counting displacement rates.
Underlying measurement precision varies by segment; smart pedometer subscription revenue and clinical gait analysis volumes carry tighter precision than analog unit emerging market estimates. Forecasts reflect assumptions about FDA software validation throughput and EU AI Act enforcement intensity. Practitioners should monitor Taiwanese foundry utilization rates and corporate wellness mandate legislative activity for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Wearable Fitness Technology
Swim Watches Market
Wearable Fitness Technology
Wearable Fitness Technology Market
Wearable Fitness Technology
North America Smart Watch Market
Wearable Fitness Technology
Wearable Band Market
Wearable Fitness Technology
Australia Wearables Market
Wearable Fitness Technology
Wearable Sensors Market
Wearable Fitness Technology
North America Wearable Sensors Market
Wearable Fitness Technology
Thermal Comfort Wearables Market
Wearable Fitness Technology
Global Smart Wearable Fitness and Sports Devices Market
Wearable Fitness Technology
Global Blood Flow Restriction Band Market
Wearable Fitness Technology
Wearable Devices Market
Wearable Fitness Technology
Global Consumer Smart Wearable Market
Wearable Fitness Technology
Sports Technology Market
Wearable Fitness Technology
Body Sensors Market
Wearable Fitness Technology
Smart Sports Wearables Market
Wearable Fitness Technology
Fitness Tracker for Heart Rate Market