
 Sports Headbands Market | 2026-2036
Sports Headbands Market Size, Share, and Industry Trends Forecast 2026-2036
Sports Headbands Market Insights
Asset-light licensing and contract manufacturing is narrowing the capital barrier for new entrants in sports accessories. Under Armour leverages its direct-to-consumer platform to control pricing and inventory velocity. Nike sustains global brand recognition through athlete endorsements and uniform partnerships. Halo Headband specializes in sweat-management technology for endurance athletes, occupying a defensible niche against broader lifestyle competitors.
Sports headbands are textile accessories engineered with moisture-wicking fibers, elastic recovery specifications typically between 40-80%, and compression fit parameters designed to manage perspiration and stabilize hair during physical exertion. Polyester-spandex blends dominate commercial production due to superior stretch retention and rapid drying performance compared to cotton alternatives. Elastic Bands and Performance Bands command premium positioning among team buyers, while Sweatbands anchor volume sales in individual fitness channels. Application demand clusters around Running and Basketball, where repetitive motion and high exertion rates create functional requirements that casual use segments do not replicate.
The US Consumer Product Safety Commission monitors textile flammability standards for athletic wear, while the EU REACH regulation governs chemical content in skin-contact fabrics. China's GB standards and the national textile regulator SAMR enforce fiber labeling and safety testing for imported accessories. Stakeholders must monitor evolving chemical restriction lists and regional labeling mandates to maintain market access across jurisdictions.
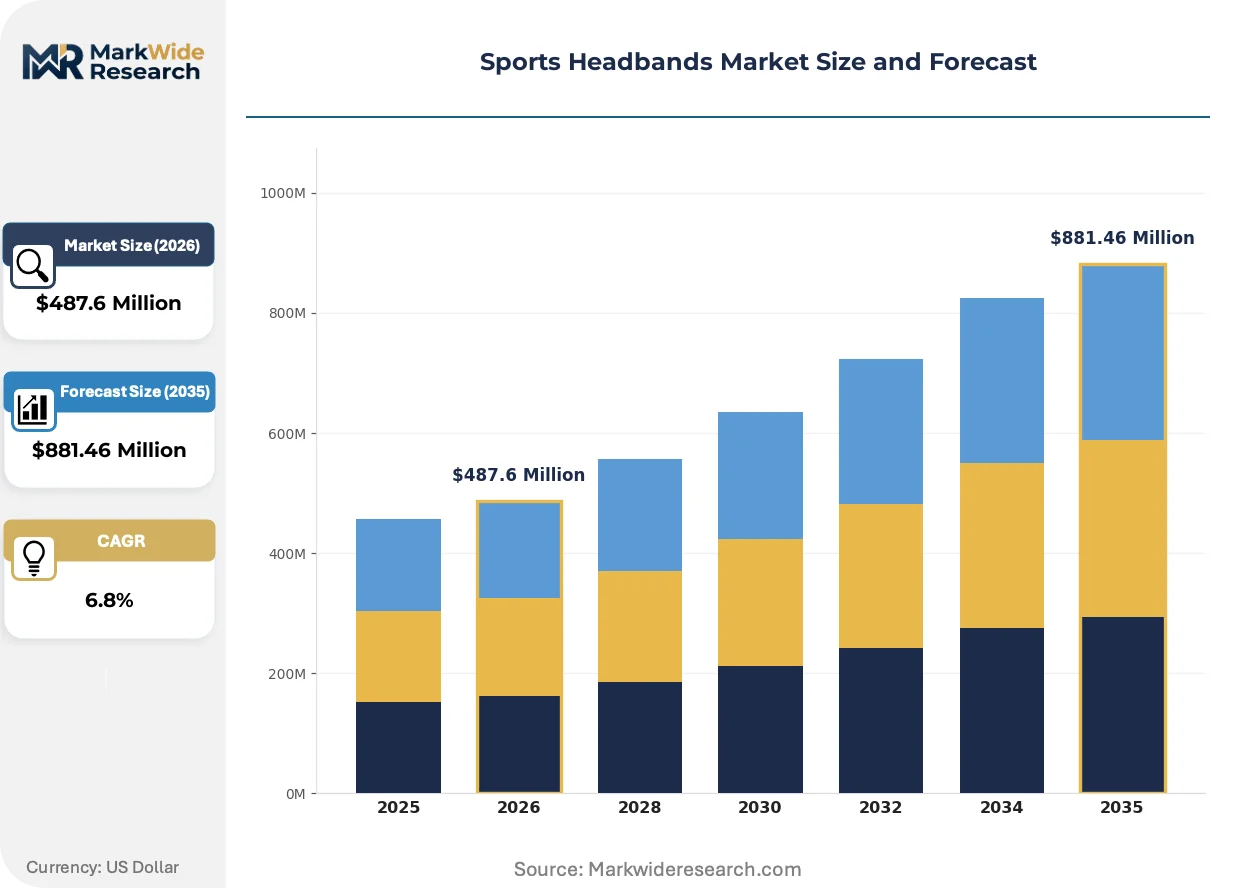
Market Dynamics
Youth basketball leagues in the United States are expanding accessory procurement budgets while REACH chemical restrictions in the European Union reshape material sourcing requirements for textile-contact products. This dual pressure from demand concentration and regulatory tightening defines current market structure.
Growth Catalysts
- REACH Chemical Framework:The EU's restriction of certain dye compounds in skin-contact fabrics is accelerating substitution toward certified synthetic blends that command premium positioning in team procurement channels.
- Youth Sports League Expansion:Organized basketball programs across the United States are standardizing headband requirements in uniform policies, creating institutional demand pull absent in individual fitness segments.
- Moisture-Wicking Fiber Innovation:Advanced polyester-spandex blends with 40-80% elastic recovery specifications are displacing cotton alternatives in endurance running applications where sweat management determines repurchase rates.
Market Restraints
- Petrochemical Input Volatility:Polyester and spandex production depends on crude oil derivatives, exposing margins to energy price swings that contract manufacturers cannot fully hedge.
- Asian Supply Concentration:Bulk textile weaving and cut-and-sew operations cluster in China's eastern provinces, creating single-source vulnerability for brands without diversified production footprints.
- Technical Performance Ceiling:Current fiber engineering approaches maximum wicking velocity for non-specialized price tiers, limiting differentiation through material innovation alone.
Strategic Opportunities
- Direct-to-Consumer Platform Expansion:Athletic brands with owned digital channels bypass wholesale margin compression and capture first-party data on fit preferences and replacement cycles.
- Medical-Wellness Convergence:Compression headband specifications developed for migraine management and temperature regulation open adjacent revenue streams beyond traditional sports positioning.
- State-Level Procurement Mandates:California and Texas school athletic associations are implementing standardized protective equipment guidelines that include hair stabilization accessories for contact sports participation.
Industry Challenges
- Compliance Timeline Compression:Brands must reformulate dye chemistries and re-certify fiber blends against evolving REACH restriction lists while maintaining existing inventory velocity.
- Skill Scarcity in Technical Textiles:Formulation chemists with expertise in skin-contact elastic recovery specifications command premium compensation, constraining mid-tier manufacturer R&D bandwidth.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Sports Headbands Market |
| Market Size in 2026 | $487.6 Million |
| Market Size in 2035 | $881.46 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Elastic Bands, Sweatbands, Headwraps, Performance Bands Material: Cotton, Polyester, Nylon, Spandex Application: Running, Cycling, Yoga, Basketball Customer Type: Athletes, Fitness Enthusiasts, Casual Users, Teams |
| Companies Covered | Under Armour, Alo Yoga, Nike, Halo Headband, Smartwool, Adidas, Buff, Steriger, JUNK Brands, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Sports Headbands Market Trends and Innovations
Material science advances and regulatory chemistry restrictions are compressing traditional product lifecycles while digital commerce infrastructure enables direct brand-buyer relationships that bypass legacy wholesale structures.
Seamless knitting technology is collapsing the distinction between performance and lifestyle headband categories by enabling variable compression zones within single-piece construction. Marathon and triathlon participants are adopting these unified-design products at accelerating rates, forcing specialty brands to abandon their segmented SKU strategies or cede shelf space to integrated-platform competitors.
REACH Annex XVII updates on skin-sensitizing disperse dyes are forcing reformulation of dark-pigmented polyester blends used in team uniform coordination. Manufacturers serving European school and club markets are shifting toward solution-dyed fibers that embed color during extrusion rather than post-knitting baths, increasing capital intensity but securing regulatory continuity.
Team athletic directors are consolidating accessory purchasing through centralized e-procurement portals that specify performance certifications and elastic recovery parameters upfront. This specification-driven buying pattern displaces coach-driven discretionary purchases at sporting goods retail, concentrating volume with vendors holding pre-approved supplier status in district purchasing systems across Texas, Florida, and Ohio scholastic leagues.
Sports Headbands Market Segmentation
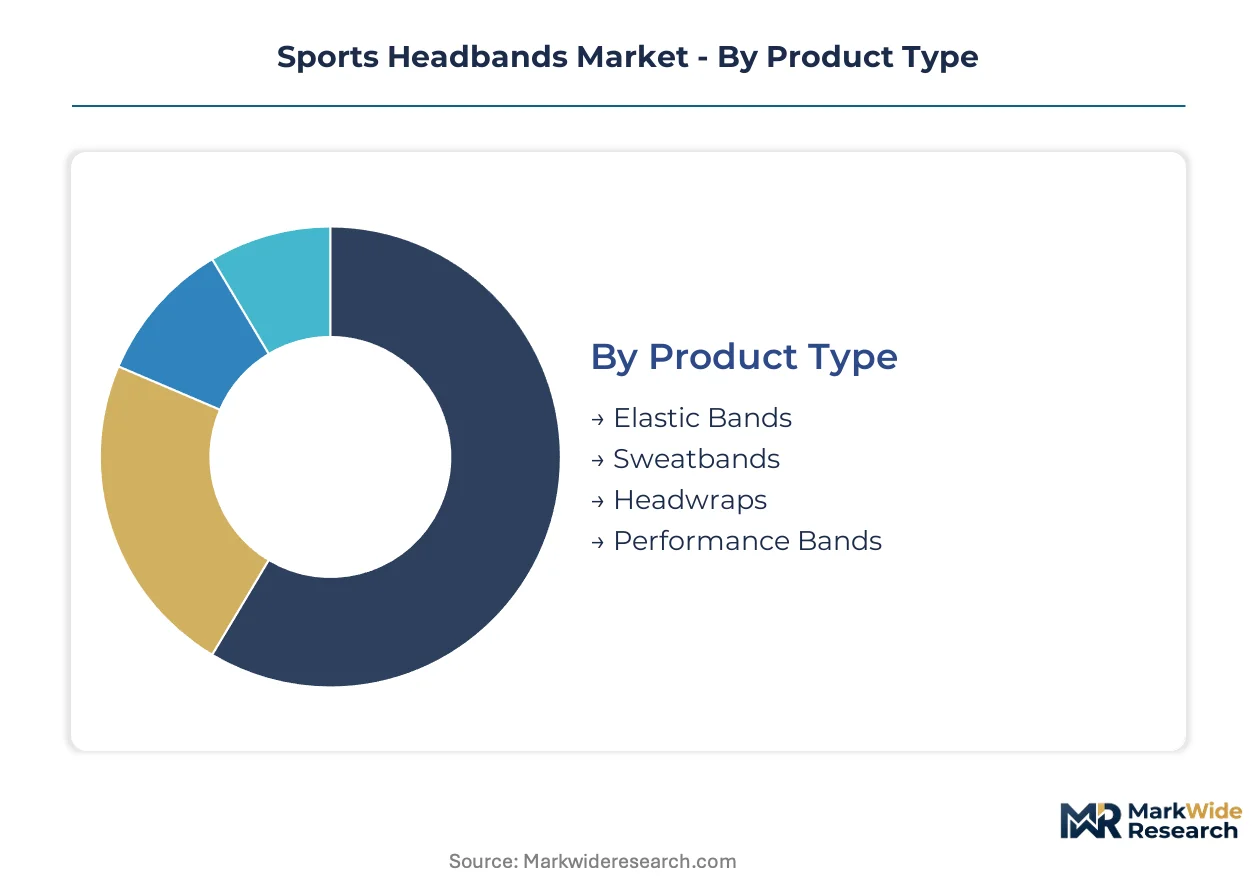
Headband segmentation reflects divergent performance requirements across endurance sports versus team athletics. Material composition and elastic recovery specifications separate premium positioning from commodity volume tiers.
Product Type:
Cost tier stratification separates institutional procurement from individual discretionary purchases.
- Elastic Bands:Basic stretch-fiber construction with 40-60% elastic recovery serves youth leagues and recreational fitness. Texas and Florida school districts specify these for standardized uniform compliance.
- Performance Bands:Engineered with graduated compression zones and moisture-wicking polyester-spandex blends exceeding 70% elastic recovery. Marathon and triathlon participants drive replacement cycles through sweat-degradation thresholds.
- Sweatbands:Terry-loop cotton or synthetic pile construction targets basketball and tennis where forehead perspiration management is primary.
- Headwraps:Wider fabric coverage with tie or Velcro closure systems serves yoga practitioners and casual lifestyle positioning.
Performance Bands hold installed capacity. Elastic Bands is rotating up the share rankings.
Material:
Application requirements dictate fiber selection against chemical compliance timelines.
- Polyester:Solution-dyed filament variants bypass REACH Annex XVII dye restrictions while delivering sub-30-minute dry times. European team procurement is consolidating around certified synthetic blends.
- Spandex:Elastane content between 8-20% provides compression fit specifications that cotton cannot replicate. Endurance running segments specify minimum stretch retention after 50+ wash cycles.
- Cotton:Natural fiber absorption exceeds synthetic alternatives but suffers compression set degradation and slower drying performance.
- Nylon:Higher tenacity than polyester with superior abrasion resistance for repeated helmet-contact sports.
Polyester dominates current formulation. Spandex is climbing the fastest.
Application:
Volume concentration varies by exertion intensity and institutional standardization.
- Running:Individual replacement cycles accelerate with mileage-based wear. Moisture-wicking performance determines brand loyalty in marathon training segments.
- Basketball:Youth league uniform mandates in California and Ohio create institutional demand pull absent in individual fitness channels.
- Cycling:Helmet compatibility and sweat-drip prevention specifications drive aerodynamic thin-profile designs.
- Yoga:Studio retail placement favors aesthetic coordination over technical performance metrics.
Basketball holds installed capacity. Running is gaining share fastest.
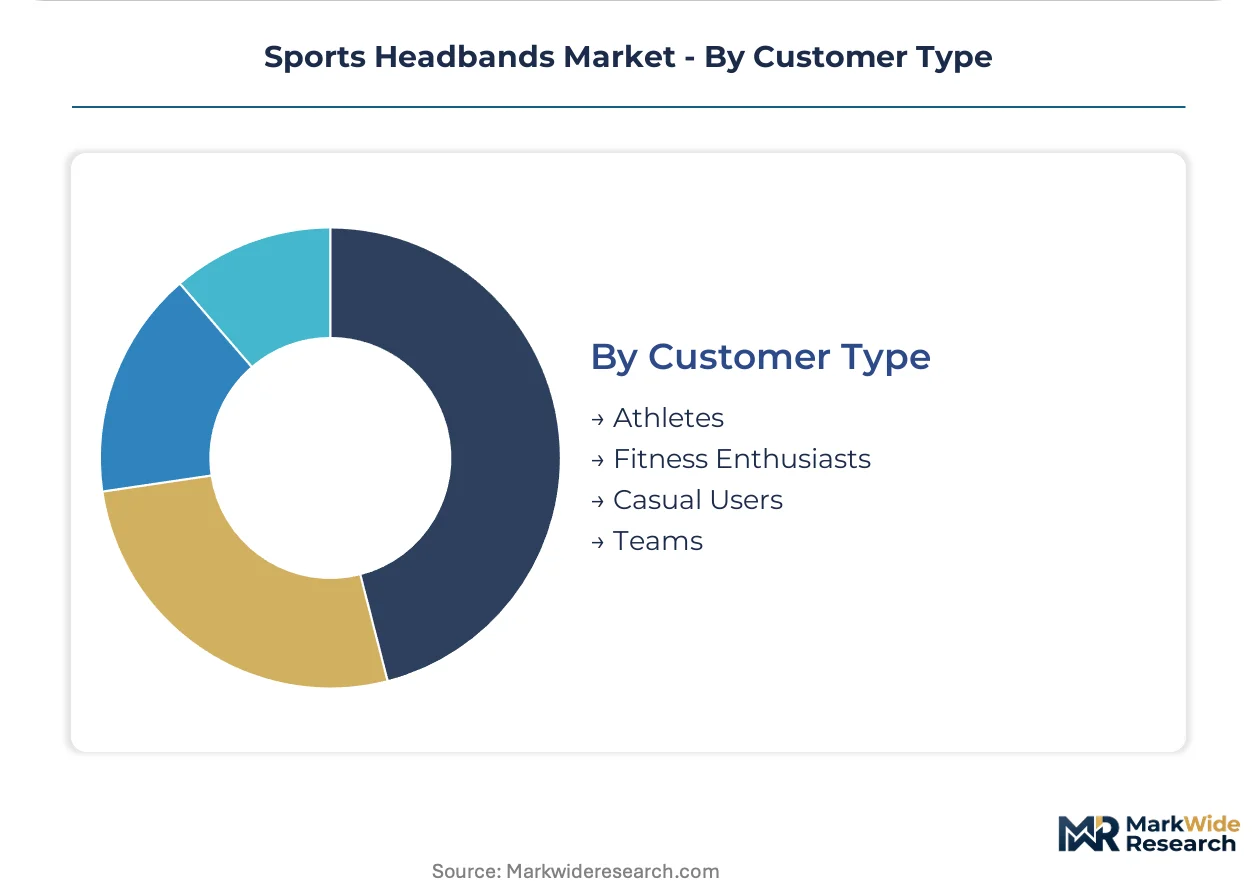
Customer Type:
Procurement authority separates centralized purchasing from discretionary retail selection.
- Teams:Athletic directors specify performance certifications and elastic recovery parameters through e-procurement portals. District-level supplier pre-approval concentrates volume with compliant vendors.
- Athletes:Competitive participants prioritize sweat-management technology and compression fit over price positioning.
- Fitness Enthusiasts:Regular gym attendance drives replacement cycles without institutional procurement scale.
- Casual Users:Lifestyle positioning and color coordination dominate purchase criteria with minimal performance requirements.
Teams hold installed capacity. Athletes is rotating up the share rankings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Premium pricing power concentrates in the United States where youth league standardization drives institutional procurement, while European markets absorb REACH compliance costs through solution-dyed fiber premiums. Asian manufacturing clusters compete on volume efficiency but lack brand equity capture.
United States
California and Texas school athletic associations mandate standardized hair stabilization accessories for contact sports participation, institutionalizing volume demand absent in individual retail channels. The US Consumer Product Safety Commission monitors textile flammability standards for athletic wear compliance. Dallas-Fort Worth hosts concentrated procurement coordination for scholastic districts across the Southwest.
Germany
REACH Annex XVII restrictions on skin-sensitizing disperse dyes accelerate manufacturer migration toward solution-dyed polyester blends for team uniform coordination. ECHA enforcement timelines compress reformulation cycles for brands serving European school markets. Stuttgart's technical textile cluster specializes in elastic recovery specification testing for endurance sports applications.
China
GB standards and SAMR fiber labeling mandates govern export-oriented production in Zhejiang and Guangdong provinces. The national textile regulator enforces safety testing protocols that determine market access for imported accessories. Ningbo's cut-and-sew operations supply bulk volume to North American team procurement channels under contract manufacturing arrangements.
Japan
METI guidelines on functional textile claims shape marketing compliance for moisture-wicking performance assertions. JIS standards specify elastic retention testing protocols that differentiate premium positioning from commodity tiers. Osaka's sportswear design houses develop compression specifications for marathon and triathlon distribution networks.
Australia
TGA oversight of therapeutic claims creates regulatory boundaries for compression headbands marketed toward migraine management applications. State-level sporting associations in Victoria and New South Wales specify performance certification requirements for institutional procurement. Melbourne's endurance sports retail channels drive replacement cycles through mileage-based wear thresholds.
Sports Headbands Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream in elastic fiber and seamless knitting equipment. The market structures around three tiers: global athletic apparel conglomerates with direct-to-consumer infrastructure, technical specialists occupying defensible niches, and contract manufacturers serving private-label volume. Consolidation pressure operates through e-procurement portal pre-approval requirements that favor vendors with district-level supplier status. Dominant competitive moves include backward integration into solution-dyed fiber production and geographic diversification of cut-and-sew operations beyond eastern China.
Among global athletic apparel platforms, Nike and Under Armour exemplify divergent channel strategies. Nike sustains positioning through athlete endorsement networks and uniform partnership anchoring. Under Armour leverages owned digital infrastructure to control pricing velocity and capture first-party replacement cycle data. Within technical specialization, Halo Headband occupies a position in sweat-management technology for endurance segments where performance specifications exceed lifestyle positioning requirements.
| Leading Market Players |
|---|
| Under Armour |
| Alo Yoga |
| Nike |
| Halo Headband |
| Smartwool |
| Adidas |
| Buff |
| Steriger |
| JUNK Brands |
| Others |
Pricing and Supply Chain Analysis
Shanghai-Ningbo container freight corridors shape cost dynamics across polyester-spandex headband production, compressing margins for undifferentiated contract manufacturers while enabling premium pricing for REACH-certified solution-dyed fiber suppliers serving European team procurement channels.
Pricing Analysis
Industrial OEM buyers anchor a three-tier pricing structure across premium, standard, and economy levels. Price differentiation stems from elastic recovery certification tier and volume procurement scale, with Texas school districts commanding lowest unit costs through centralized e-procurement. Cost compression in the economy tier intensifies because petrochemical input volatility erodes contract manufacturer margins. Youth league athletic directors exhibit highest price sensitivity, while marathon specialty retailers demonstrate lowest sensitivity due to performance specification requirements.
Supply Chain Analysis
Export-control scrutiny on advanced seamless knitting equipment limits technology transfer to emerging manufacturing hubs, concentrating production expertise in China's Zhejiang and Guangdong provinces. Raw material flows draw from Saudi petrochemical feedstock, Korean spandex filament, and Taiwanese solution-dyed polyester. Single-source vulnerability pervades eastern China's cut-and-sew cluster, where district-level supplier pre-approval requirements lock out unqualified competitors. Distribution runs through direct-to-consumer platforms and scholastic e-procurement portals, bypassing traditional sporting goods retail.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
REACH Annex XVII chemical restrictions are accelerating fiber formulation disruption, compressing product lifecycles for legacy dye-house operations while opening premium positioning for compliant synthetic blend suppliers.
For Market Incumbents: Entrench district-level supplier status in Texas, Florida, and Ohio scholastic purchasing systems before REACH compliance timelines eliminate non-certified competitors. Deepen backward integration into solution-dyed polyester production to secure raw material continuity against dye-chemistry reformulation cycles. Control channel position through owned digital infrastructure that captures replacement cycle data and bypasses wholesale margin compression. For New Entrants and Emerging Players: Build out medical-wellness convergence positioning targeting migraine management and temperature regulation applications, where compression specifications command pricing premiums absent in saturated team sports channels. Penetrate California and Texas school athletic associations through state-level procurement mandate alignment. Pursue direct-to-consumer launch with subscription-based replacement cycle fulfillment for endurance running segments. For Investors and Strategic Acquirers: Technical textile specialists with REACH-certified formulation capabilities and elastic recovery testing infrastructure represent priority acquisition targets. Long-term viability hinges on regulatory compliance continuity across evolving chemical restriction lists and e-procurement portal pre-approval consolidation. Watch for REACH Annex XVII expansion announcements as inflection indicators requiring portfolio repositioning.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Solution-Dyed Fiber | REACH Annex XVII compliance secures European school market access against dye-house competitors. |
| District-Level Supplier Pre-Approval | Texas and Ohio e-procurement portals concentrate volume with certified vendors, displacing retail channels. |
| Direct-to-Consumer Platform Launch | Owned digital infrastructure captures first-party replacement cycle data from marathon and triathlon participants. |
| Medical-Wellness Product Extension | Compression specifications for migraine management open adjacent revenue streams beyond traditional sports positioning. |
| Geographic Diversification of Cut-and-Sew | Vietnam and Indonesia capacity reduces single-source exposure to China's eastern province concentration. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with athletic directors at Texas and California school districts, polyester formulation chemists at Zhejiang textile mills, procurement managers at marathon specialty retailers, and seamless knitting equipment technicians. Secondary validation drew from US Consumer Product Safety Commission flammability standards documentation, ECHA REACH Annex XVII restriction lists, Chinese SAMR fiber labeling mandates, and Japanese METI functional textile claim guidelines. Bottom-up volume estimates from district-level procurement data triangulated against top-down market sizing from trade flow analysis.
Calibration against historical elastic band and performance band shipment patterns anchored the analytical framework across the projection horizon. Segmentation dimensions modeled included product type tier, material composition grade, application intensity level, and customer procurement authority. CAGRs were derived from replacement cycle velocity analysis and institutional mandate adoption curves. Industry-specific forecast inputs incorporated REACH compliance timeline compression and youth league uniform standardization momentum.
Stress conditions across petrochemical price volatility, REACH restriction list expansion, and e-procurement portal consolidation were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding solution-dyed fiber adoption rates and district supplier pre-approval penetration. Material shifts in EU chemical restriction scope or US scholastic procurement mandate geography would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Wearable Fitness Technology
Smart Insole Market
Wearable Fitness Technology
Wearable Band Market
Wearable Fitness Technology
Smart Sports Wearables Market
Wearable Fitness Technology
Thermal Comfort Wearables Market
Wearable Fitness Technology
Wearable Motion Sensors Market
Wearable Fitness Technology
Sports Technology Market
Wearable Fitness Technology
Wearable Devices Market
Wearable Fitness Technology
Global GPS Watch Tracker Market
Wearable Fitness Technology
Global Consumer Smart Wearable Market
Wearable Fitness Technology
Wearable Patch Market
Wearable Fitness Technology
Flexible Wearable Device Market
Wearable Fitness Technology
Pedometer Market
Wearable Fitness Technology
Stress Tracking Devices Market
Wearable Fitness Technology
Smart Fitness Watches Market
Wearable Fitness Technology
Fitness Tracker Market
Wearable Fitness Technology
Fitness Tracker for Heart Rate Market