
 Wearable Sensors Market | 2026-2036
Wearable Sensors Market Size, Share, and Industry Trends Forecast 2026-2036
Wearable Sensors Market Intelligence
The bundling of multiple sensor types, such as accelerometers and gyroscopes, into single integrated modules is repositioning buyer choice toward system-level solutions. Robert Bosch leverages its expertise in MEMS technology to offer compact, multi-sensor packages for consumer electronics. STMicroelectronics specializes in low-power microcontrollers and sensors, targeting battery-operated wearable devices. Texas Instruments competes with a broad portfolio of analog and embedded processing components for medical and fitness applications.
Wearable sensors are electronic components designed to be integrated into clothing, accessories, or devices worn on the body. These devices often utilize MEMS technology or optical sensing principles to convert physical motion or biological signals into digital data for analysis. Demand from medical monitoring applications for continuous patient tracking provides a stable revenue base for the market. Within product types, heart rate sensors and accelerometers remain foundational components, while electrochemical sensors for biomarker detection represent a high-growth frontier.
Regulatory frameworks, including the FDA's oversight in the United States and the EU's Medical Device Regulation (MDR), govern market access for clinical-grade wearables. Compliance with standards like ISO 13485 for quality management systems is essential for manufacturers targeting healthcare providers. Stakeholder success will hinge on navigating the complex requirements for data security and achieving clinical validation for new sensing modalities.
Market Dynamics
The market's structure is being defined by the convergence of consumer electronics and clinical healthcare. This dynamic is driven by persistent demand for continuous monitoring of chronic conditions, enabled by ongoing advances in MEMS and optical sensing technologies.
Growth Catalysts
- Remote Patient Monitoring:The expansion of remote patient monitoring (RPM) programs in countries like the United States is creating a stable demand base for clinically certified sensors used in chronic disease management.
- Regulatory Harmonization:The EU's Medical Device Regulation (MDR) creates a clearer pathway for clinical-grade wearables, boosting confidence among European healthcare providers and system integrators.
- Sensor Miniaturization:Advances in MEMS technology enable the creation of smaller, more power-efficient sensors, allowing for integration into new form factors like smart patches, rings, and textiles.
Market Restraints
- Clinical Validation Costs:The high cost and long timelines associated with clinical trials and achieving certifications like ISO 13485 create significant barriers to entry for companies targeting the medical-grade market.
- Power Consumption:Battery life remains a primary technical constraint, limiting the duration of continuous data collection, particularly for multi-sensor devices used for complex health tracking.
- Smartphone Cannibalization:The integration of basic sensing capabilities, such as heart rate and step counting, into standard smartphones presents a substitution threat for standalone, single-function wearable devices.
Strategic Opportunities
- Electrochemical Sensing:Non-invasive electrochemical sensors for continuous glucose or lactate monitoring represent a high-growth frontier, with the potential to disrupt traditional patient care protocols for diabetes.
- Underpenetrated Geographies:India's expanding digital health initiatives and growing middle class offer a large, untapped market for affordable fitness and wellness wearables outside of North America and China.
- On-Device AI:Combining optical sensors with AI-driven algorithms on the device enables real-time detection of conditions like atrial fibrillation, creating new value beyond simple raw data collection.
Industry Challenges
- Data Privacy Compliance:Navigating fragmented data security regulations, such as GDPR in Europe and HIPAA in the United States, complicates the design and deployment of cloud platforms for multi-regional health data.
- System Interoperability:Ensuring seamless data exchange between sensors from different manufacturers and existing electronic health record (EHR) systems remains a major operational hurdle for healthcare providers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Wearable Sensors Market |
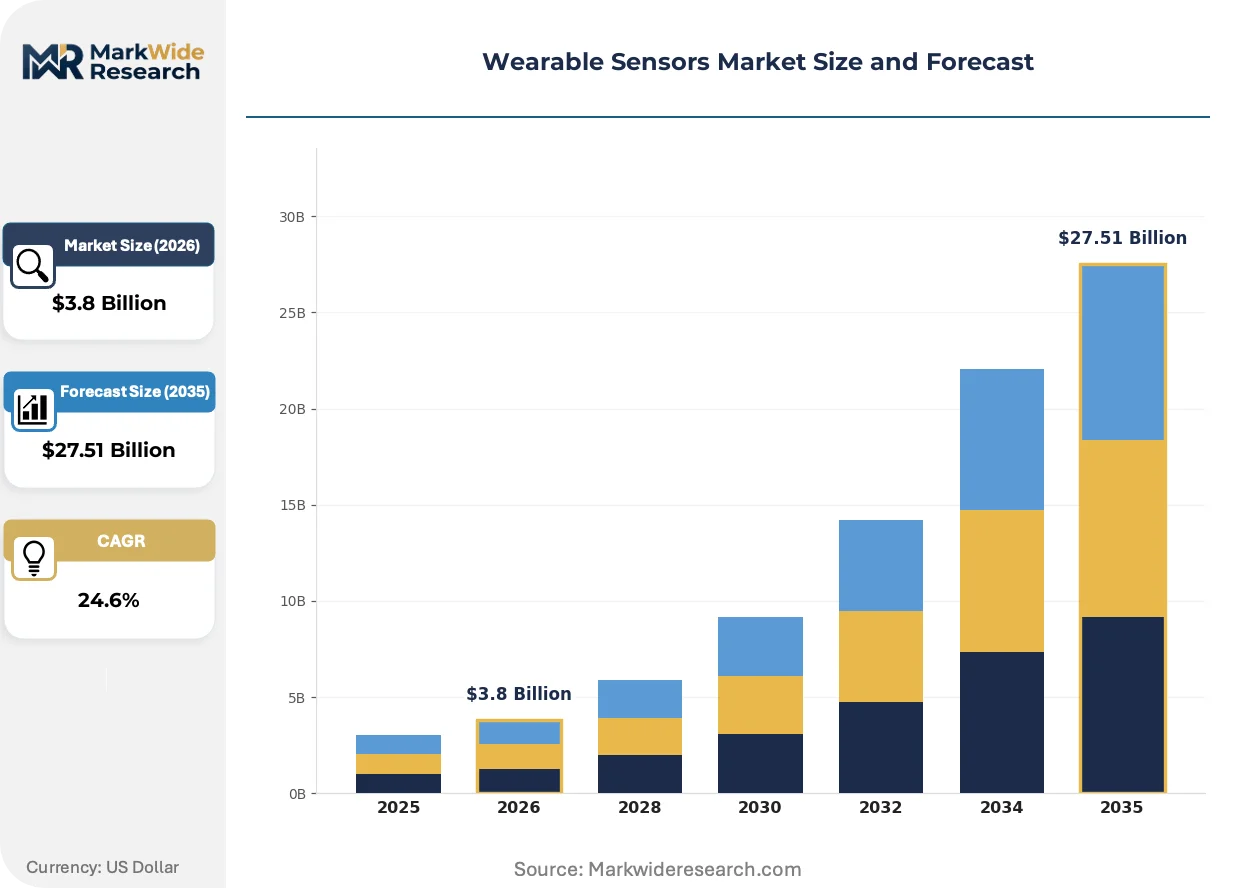
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $27.51 Billion |
| CAGR (2026 – 2036) | 24.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Accelerometers, Gyroscopes, Magnetometers, Heart Rate Sensors, Temperature Sensors Application: Fitness Tracking, Medical Monitoring, Industrial Safety, Sports Performance, Military Training End User: Healthcare Providers, Fitness Enthusiasts, Manufacturing Operators, Defense Personnel, Sports Teams Technology: Optical Sensors, Piezoelectric Sensors, Electrochemical Sensors, Capacitive Sensors, Thermal Sensors |
| Companies Covered | STMicroelectronics, Infineon Technologies, Texas Instruments, NXP Semiconductors, Analog Devices, TE Connectivity, Broadcom, Robert Bosch, TDK Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Wearable Sensors Market Strategic Shifts & Innovations
The shift from providing discrete data points to delivering continuous, contextual health insights is reshaping the value proposition of wearable sensors. This evolution demands higher sensor fusion capabilities and on-device processing to translate raw signals into actionable health alerts and predictive analytics.
Multi-Sensor Fusion
Multi-sensor modules integrate components like accelerometers, gyroscopes, and magnetometers into a single, compact package. Consumer electronics and medical device manufacturers are rapidly adopting these modules to reduce device size, design complexity, and power consumption. This hardware integration is converging with sophisticated sensor fusion software, enabling more complex applications like precise activity recognition and clinical-grade fall detection algorithms.
Regulatory Fast-Tracks for Digital Health
Regulatory frameworks like the FDA's Digital Health Innovation Action Plan are creating streamlined pre-certification pathways for software as a medical device (SaMD). This policy accelerates market access for companies developing the advanced algorithms that interpret sensor data for diagnostic purposes. Consequently, firms targeting the US clinical market are prioritizing investment in software development and clinical validation over hardware differentiation alone.
Shift to Holistic Health Platforms
Enterprise buyers in corporate wellness and professional sports are moving away from purchasing basic fitness trackers toward adopting platforms that offer holistic physiological monitoring. This change de-emphasizes single-metric devices in favor of integrated systems that track stress, sleep quality, and recovery metrics. This demand pattern is most visible in North America and Europe, where organizations use such data to manage workforce health and optimize athletic performance.
Wearable Sensors Market Segmentation
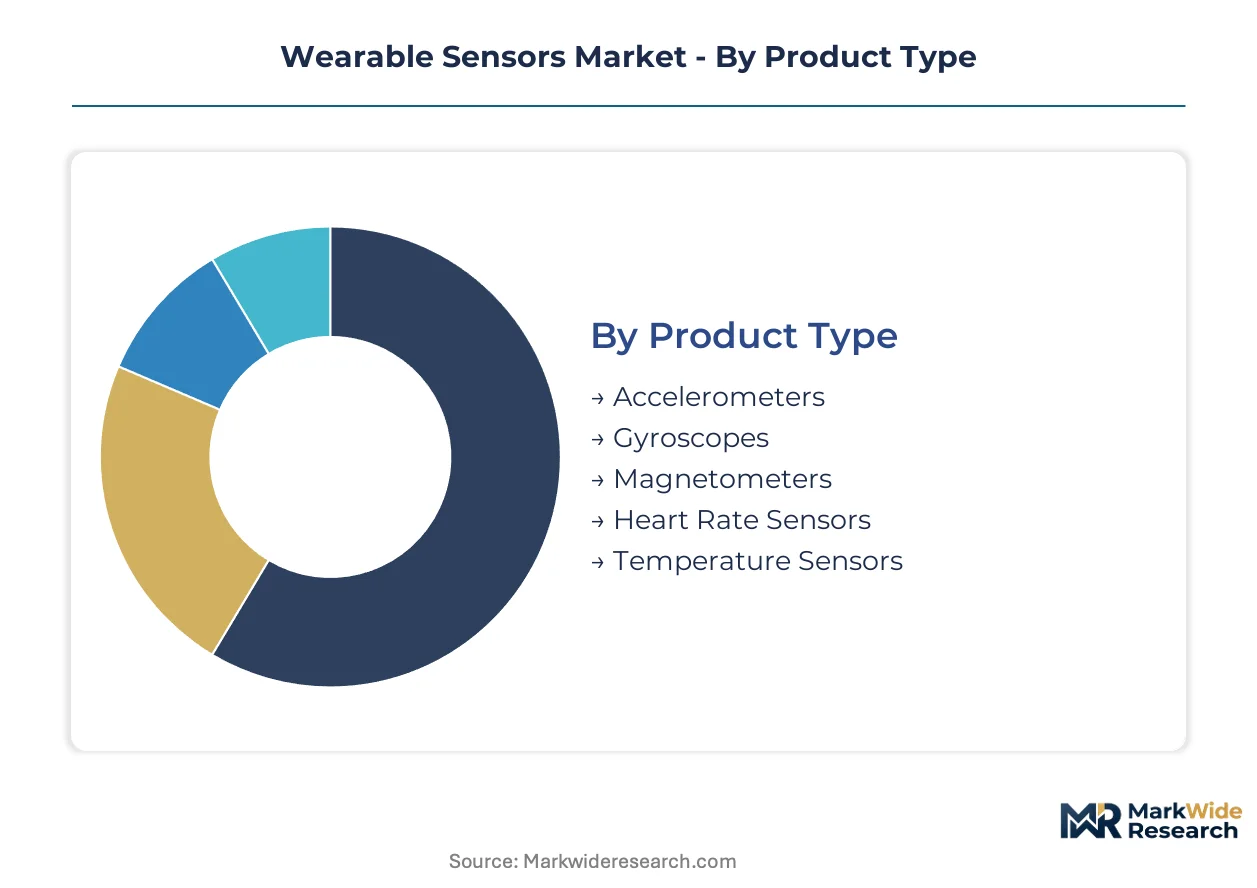
The wearable sensors market segments reflect the diverse technical capabilities and end-use applications driving innovation and adoption. Understanding these distinct categories provides clarity on where value creation and technological advancements are most concentrated. This granular view helps stakeholders identify specific growth vectors and competitive landscapes within the broader market.
Product Type:
The market for wearable sensors is defined by the specific function and underlying technology of each product type, dictating their utility across various applications.
- Accelerometers:These sensors measure acceleration forces, enabling detection of motion, orientation, and vibration. Demand concentrates in consumer electronics like smartwatches and fitness trackers for activity monitoring across the United States and China.
- Gyroscopes:Gyroscopes detect angular velocity and rotation, complementing accelerometers for comprehensive motion tracking. These are critical for navigation and precise gesture recognition in advanced wearables.
- Magnetometers:Magnetometers measure magnetic fields, providing compass functionality and enhancing location accuracy. They are often integrated into multi-sensor modules for outdoor navigation.
- Heart Rate Sensors:These components measure cardiac activity, typically via optical (PPG) or electrical (ECG) methods. Demand for continuous heart rate monitoring is strong in medical monitoring and fitness applications globally.
- Temperature Sensors:These sensors detect body temperature changes, crucial for health monitoring and early detection of fever or physiological stress.
Mature deployment sits with Accelerometers. Newer deployment is concentrated in Temperature Sensors.
Application:
The diverse applications of wearable sensors delineate distinct market segments, each driven by specific user needs and regulatory requirements.
- Fitness Tracking:This segment involves monitoring physical activity, calorie expenditure, and sleep patterns for general health and wellness. High consumer adoption in North America and Europe drives demand for accessible and user-friendly devices.
- Medical Monitoring:Wearable sensors in this category provide continuous tracking of vital signs and physiological parameters for chronic disease management and remote patient care. Regulatory frameworks like the FDA's oversight impact market access for these clinical-grade devices.
- Industrial Safety:Sensors used in industrial settings monitor environmental hazards or worker biometrics to prevent accidents and ensure compliance.
- Sports Performance:This application focuses on optimizing athletic training, tracking performance metrics, and preventing injuries for professional and amateur athletes.
- Military Training:Wearables in military contexts monitor physiological stress, fatigue, and environmental conditions to enhance soldier readiness and safety.
Medical Monitoring applications are expanding most quickly, while Fitness Tracking maintains a substantial installed base.
End User:
Customer types delineate the market based on the primary beneficiaries and operational environments for wearable sensor deployment across various sectors.
- Healthcare Providers:Hospitals, clinics, and remote care services utilize wearable sensors for patient diagnostics, continuous monitoring, and post-discharge follow-up. Compliance with HIPAA in the United States is paramount for data security.
- Fitness Enthusiasts:Individuals focused on personal health, exercise, and wellness adopt wearable devices for tracking activity, sleep, and basic physiological data. This segment shows high volume demand in the United States and China.
- Manufacturing Operators:Workers in industrial environments use wearables for safety monitoring, ergonomic assessment, and task efficiency improvements.
- Defense Personnel:Military and security forces deploy specialized wearable sensors for mission-critical physiological monitoring and environmental awareness.
- Sports Teams:Professional and collegiate sports organizations leverage wearables to monitor athlete performance, recovery, and injury risk.
Demand for wearable sensors concentrates among Healthcare Providers and Fitness Enthusiasts, reflecting broad adoption patterns.
Technology:
The underlying scientific principles of sensor operation categorize technologies within the wearable sensors market, influencing device capabilities and accuracy.
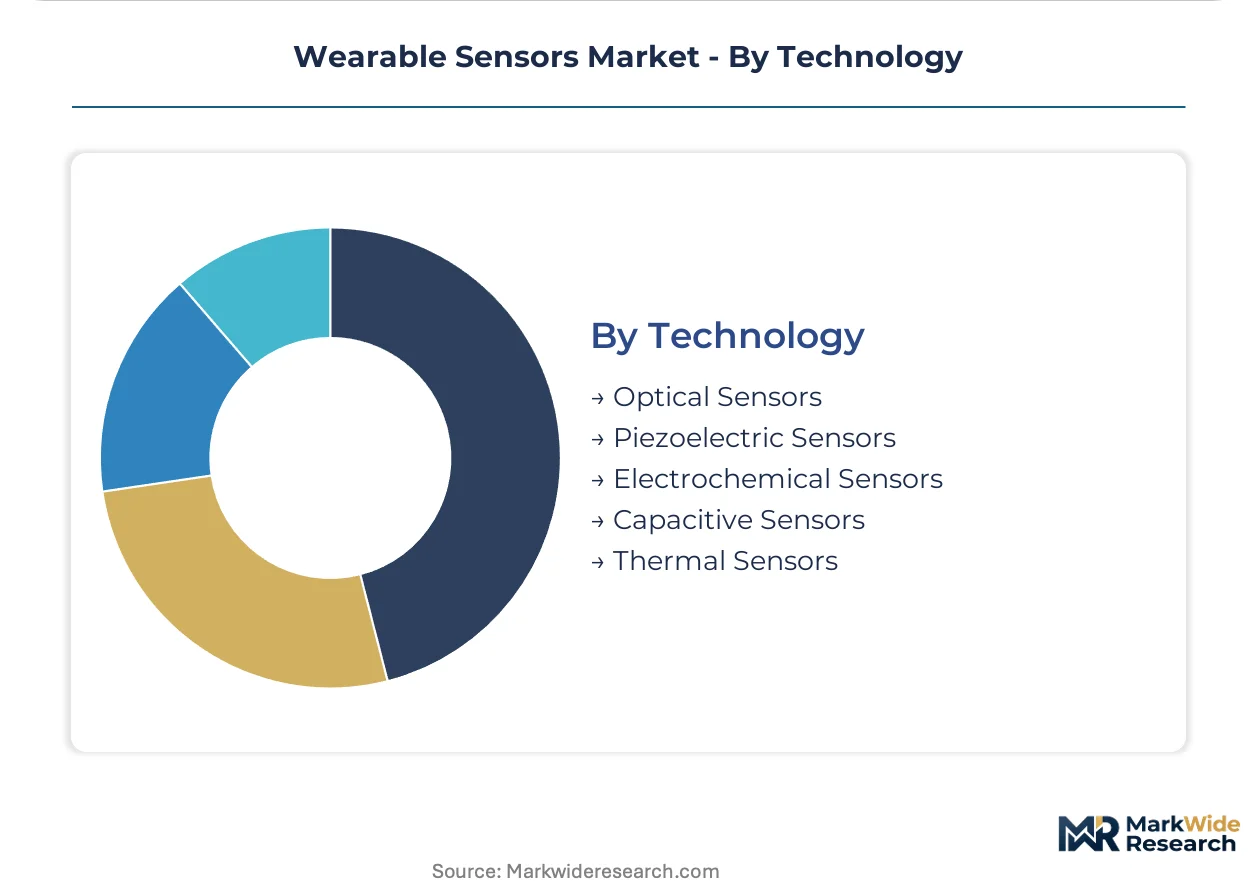
- Optical Sensors:These sensors primarily use light to measure physiological parameters, such as heart rate variability and blood oxygen levels. They are widely adopted in consumer fitness trackers and smartwatches.
- Piezoelectric Sensors:These components generate an electrical charge in response to mechanical stress or pressure, useful for motion detection and impact sensing. They find applications in specialized medical and industrial wearables.
- Electrochemical Sensors:These devices detect specific chemical compounds or ions, enabling non-invasive monitoring of biomarkers like glucose or lactate. This technology represents a high-growth frontier for chronic disease management.
- Capacitive Sensors:Capacitive sensors measure changes in electrical capacitance, often employed for touch interfaces, proximity detection, and some biometric measurements.
- Thermal Sensors:These sensors measure temperature through infrared radiation or thermistors, used for continuous body temperature monitoring in medical and wellness applications.
Innovation in wearable sensor technology is currently focused on Electrochemical Sensors, while Optical Sensors remain widely deployed across numerous devices.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Guangdong-Hong Kong-Macau Greater Bay Area, a prominent special economic zone, drives significant concentration in wearable sensor manufacturing and innovation. This region's advanced electronics ecosystem supports the production of miniaturized components and integrated sensor modules. Its influence extends globally, impacting supply chains and fostering technological advancements in wearable devices.
United States
Demand for wearable sensors in the United States stems from extensive remote patient monitoring programs and a large fitness tracking consumer base. The FDA's regulatory oversight shapes market access for clinical-grade devices, emphasizing data accuracy and patient safety. Silicon Valley in California remains a hub for sensor technology development and health tech startups.
China
China's market for wearable sensors is fueled by its massive consumer electronics industry and a growing segment of fitness enthusiasts. The NMPA regulates medical wearable devices, ensuring compliance with national health standards. Shenzhen, a major manufacturing center, drives innovation in compact and affordable sensor production.
Germany
Germany exhibits strong demand for industrial safety wearables and advanced medical monitoring solutions. The EU's Medical Device Regulation (MDR) provides a clear framework for market entry, boosting investor confidence. The Stuttgart region, with its robust automotive and MEMS industries, contributes significantly to sensor research and manufacturing.
India
India's expanding digital health initiatives and a rising middle class are creating a substantial market for affordable fitness and wellness wearables. The PLI scheme supports domestic electronics manufacturing, including sensor components. Bengaluru, a leading IT and health tech hub, sees increasing investment in wearable sensor applications.
Japan
Japan's demand for wearable sensors is driven by its aging population, requiring continuous elderly care monitoring, and its sophisticated consumer electronics sector. The PMDA oversees medical device approvals, ensuring high quality and safety standards. Tokyo remains a center for advanced sensor research and development in consumer and medical applications.
Wearable Sensors Market Key Industry Players
Diversified conglomerates compete with focused pure-play specialists, creating a complex market structure for wearable sensors. Component suppliers often integrate vertically, offering complete system-level solutions rather than discrete sensors. Strategic partnerships between hardware manufacturers and software analytics firms dominate competitive moves, alongside continuous portfolio diversification into new application areas.
Integrated component suppliers like Robert Bosch and STMicroelectronics exemplify the market's shift towards multi-sensor packages for consumer electronics and medical devices. Texas Instruments also occupies a position as a broad portfolio provider, offering analog and embedded processing components essential for advanced wearable applications. These companies anchor the supply of foundational sensor technologies, leveraging their established manufacturing capabilities and R&D investments.
| Leading Market Players |
|---|
| STMicroelectronics |
| Infineon Technologies |
| Texas Instruments |
| NXP Semiconductors |
| Analog Devices |
| TE Connectivity |
| Broadcom |
| Robert Bosch |
| TDK Corporation |
| Others |
Cost & Logistics Intelligence
Diversified conglomerates, leveraging extensive capital, dictate wearable sensor supply behavior and influence pricing discipline. This structure impacts market access for pure-play specialists.
Pricing Analysis
Cost-down pressure on basic accelerometers accelerates as consumer electronics manufacturers demand lower unit prices. The dominant pricing model remains per-unit transactional for individual components, shifting to value-based for integrated system-level solutions. Price differentiation stems from certification level, such as FDA approval, and customization for specific medical applications. Fitness enthusiasts exhibit high price sensitivity for basic wearables, while healthcare providers prioritize performance and regulatory compliance.
Supply Chain Analysis
Dual-sourcing requirements for critical wearable sensor components are becoming standard practice among major OEMs to mitigate supply disruptions. Geographic supply concentrates in China for high-volume manufacturing, with specialized R&D and production in Germany and the United States. The industry relies heavily on MEMS wafers, specialized optical components, and low-power microcontrollers. Geopolitical tensions impacting global shipping lanes represent a significant structural risk. Distribution runs through direct sales channels to large consumer electronics and medical device manufacturers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The wearable sensors market is poised for consolidation, driven by escalating clinical validation costs and complex regulatory frameworks. These pressures disproportionately impact smaller, less capitalized players, forcing strategic exits or acquisitions.
For Market Incumbents: Anchor market share by expanding multi-sensor fusion capabilities into integrated system-level solutions. Strategic acquisitions of specialized software analytics firms can counter the threat of smartphone cannibalization for basic sensing functions. Invest heavily in ISO 13485 certification to reinforce clinical-grade credentials. This secures long-term partnerships with healthcare providers.
For New Entrants and Emerging Players: Non-invasive electrochemical sensing for biomarker detection offers a technology-first wedge into chronic disease management. Target continuous glucose monitoring and lactate tracking as white-space opportunities. India's expanding digital health initiatives present the most penetrable geography for affordable fitness wearables. A go-to-market angle involves partnering with local healthcare platforms.
For Investors and Strategic Acquirers: Distressed-cycle entries favor specialized MEMS developers in regions like Germany or the United States. The market exhibits strong long-term viability, particularly for clinical monitoring applications over the next decade. Acquisition targets should focus on companies with proprietary sensing technologies and established regulatory compliance. The signal to watch is an increase in FDA fast-track approvals for novel sensing modalities.
| Strategic Initiative | Industry Significance |
|---|---|
| Invest in On-Device AI Integration | Enables real-time detection of conditions like atrial fibrillation, creating new value beyond simple raw data collection. |
| Pursue FDA Pre-certification Pathways | Accelerates market access for advanced algorithms interpreting sensor data for diagnostic purposes in the US. |
| Expand Electrochemical Sensor R&D | Positions firms to disrupt traditional patient care protocols for diabetes through non-invasive glucose monitoring. |
| Forge Healthcare Provider Partnerships | Ensures seamless data exchange and system interoperability with existing electronic health record (EHR) systems. |
| Develop Multi-Sensor Fusion Modules | Reduces device size, design complexity, and power consumption for consumer electronics and medical devices. |
Research Approach
Independent corroboration across regulatory filings, industry association reports, and academic publications underwrites the qualitative findings. This approach combined primary interviews with medical device engineers, healthcare procurement managers, and MEMS technology developers. Secondary validation involved analysis of FDA filings, EU MDR guidelines, and customs trade data. Both bottom-up and top-down triangulation methods ensured data accuracy.
The analytical framework anchored the forecast window to comparable historical reference periods for market evolution projections. Segmentation dimensions modeled included product type, application, end user, technology, and regional regulatory frameworks. Compound annual growth rates were derived from historical trends and projected market dynamics. Key inputs included MEMS technology miniaturization and remote patient monitoring program expansion.
Several conditions sit outside the modeled scope, including unforeseen geopolitical events or rapid shifts in consumer preferences. Forecasts reflect specific assumptions regarding technological advancements and regulatory stability. Deviation in medical device regulatory policy would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Wearable Fitness Technology
Wearable Inertial Sensors Market
Wearable Fitness Technology
Smart Fitness Trackers Market
Wearable Fitness Technology
Wearable Fitness Technology Market
Wearable Fitness Technology
Smart Insole Market
Wearable Fitness Technology
United States Wearable Sensors Market
Wearable Fitness Technology
Breathing Wear Market
Wearable Fitness Technology
Global Blood Flow Restriction Band Market
Wearable Fitness Technology
Wearable Patch Market
Wearable Fitness Technology
Wearable Physiotherapy Market
Wearable Fitness Technology
Pocket Pedometers Market
Wearable Fitness Technology
Stress Tracking Devices Market
Wearable Fitness Technology
Smart Wearable Equipment Market
Wearable Fitness Technology
Smart Fitness Watches Market
Wearable Fitness Technology
Thermal Comfort Wearables Market
Wearable Fitness Technology
Swim Watches Market
Wearable Fitness Technology
Australia Wearables Market