
 Sports Technology Market | 2026-2036
Sports Technology Market Size, Share, and Industry Trends Forecast 2026-2036
Sports Technology Market Intelligence
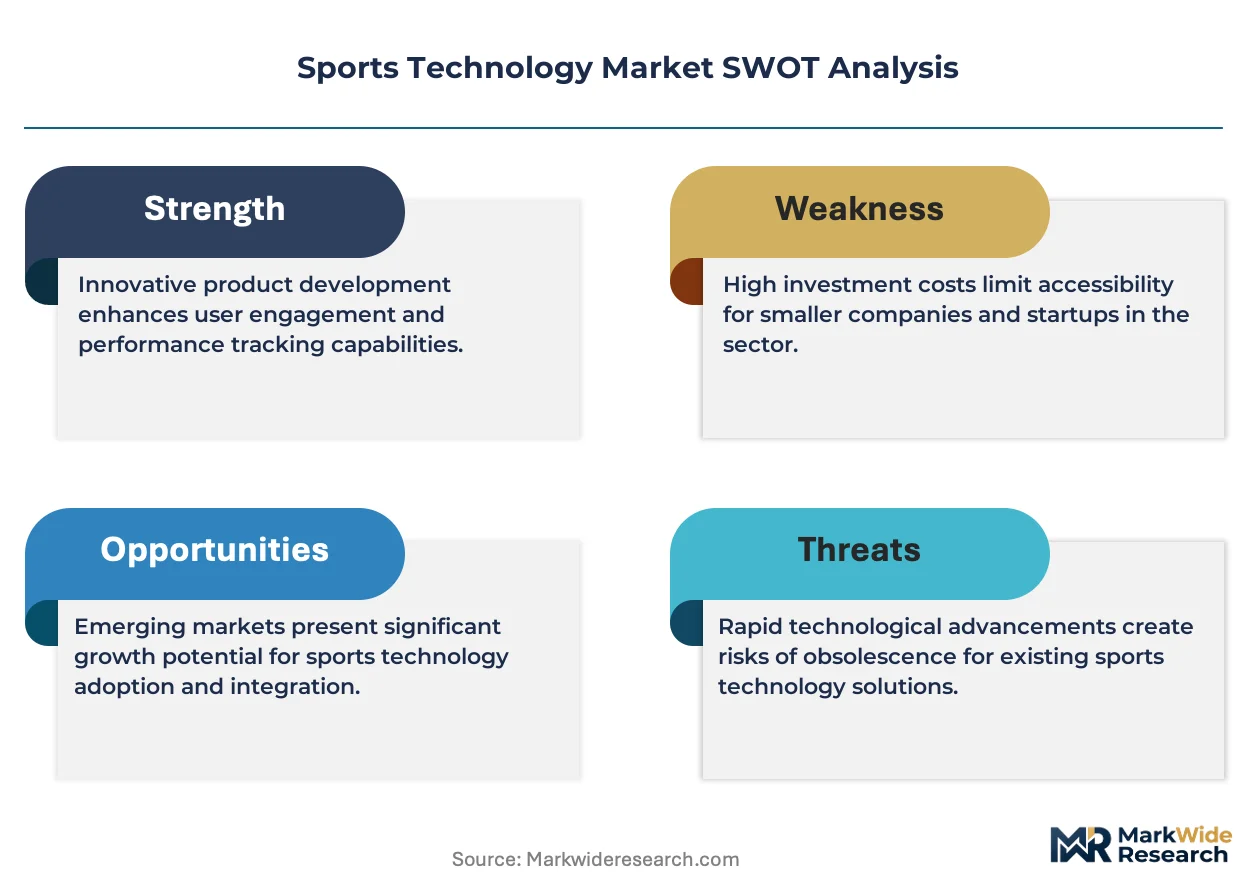
Direct-to-consumer digital platforms is reshaping how sports technology reaches end users, bypassing traditional retail and institutional procurement channels. Hawk-Eye dominates broadcast and officiating technology through its proprietary camera-tracking systems. Genius Sports leverages its official data partnerships with major leagues to control premium distribution pipelines. WHOOP sustains subscriber loyalty through continuous biometric monitoring and recovery analytics.
Sports technology encompasses hardware, software, and data systems engineered to measure, analyze, and enhance athletic performance, typically incorporating sensor arrays sampling at frequencies between 100 Hz and 1000 Hz for motion capture and physiological monitoring. These systems serve commercial purposes spanning elite team operations, consumer fitness optimization, and wagering integrity. Wearable Devices leads product type revenue as athletes and teams prioritize continuous biometric streaming. Performance Analytics Software captures expanding margin pools as AI Analytics integration deepens predictive capabilities for injury prevention and game strategy. Smart Footwear remains nascent but occupies a distinctive position in gait analysis and load management applications.
FDA oversight governs wearable medical claims in the United States, while GDPR compliance constrains biometric data processing across European deployments. ISO standards for measurement accuracy and IEC protocols for sensor interoperability establish baseline technical requirements that shape product development cycles. Stakeholders must monitor evolving regulatory frameworks for algorithmic decision-making in athlete selection and wagering markets.
Market Dynamics
AI analytics integration is compressing decision cycles across professional sports organizations, forcing hardware vendors to embed predictive algorithms directly into sensor firmware or surrender margin to pure-play software providers.
Growth Catalysts
- FDA wearable medical claims pathway:Clearance for continuous glucose monitoring and cardiac arrhythmia detection in athlete populations expands reimbursable use cases beyond fitness into clinical sports medicine.
- Professional team procurement:Franchise analytics departments now mandate API-accessible data streams, creating pull-through demand for interoperable sensor ecosystems.
- Sensor fusion architectures:Combining inertial measurement units with UWB positioning and computer vision is raising tracking fidelity thresholds for contract renewal decisions.
Market Restraints
- GDPR biometric processing constraints:European deployments face 72-hour breach notification requirements and purpose limitation rules that increase compliance overhead for cross-border athlete data transfers.
- Camera component supply concentration:Specialized high-frame-rate image sensors for motion capture systems source predominantly from Taiwanese foundries, exposing broadcast technology vendors to geopolitical supply disruption.
- Lithium-polymer battery thermal limitations:Wearable form factors restrict cell capacity, capping sampling frequency and transmission duty cycles below theoretical sensor capabilities.
Strategic Opportunities
- India PLI scheme for electronics manufacturing:Production-linked incentives for wearable device assembly create cost-competitive export capacity for biometric hardware targeting price-sensitive amateur athletic segments.
- Wagering integrity data services:Official league data partnerships represent captive distribution channels with multi-year exclusivity terms and regulatory moats against unauthorized feed competitors.
- Computer vision and edge AI convergence:On-device neural processing units are enabling real-time biomechanical analysis without cloud latency, opening venue-based deployment models independent of consumer smartphone ownership.
Industry Challenges
- Embedded firmware engineering talent scarcity:Sports technology vendors compete with automotive and aerospace sectors for engineers capable of optimizing real-time sensor fusion at sub-watt power budgets.
- ISO measurement accuracy certification timelines:Validation protocols for new motion capture algorithms require 12-18 months of third-party testing, delaying product launches against faster-moving software competitors.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Sports Technology Market |
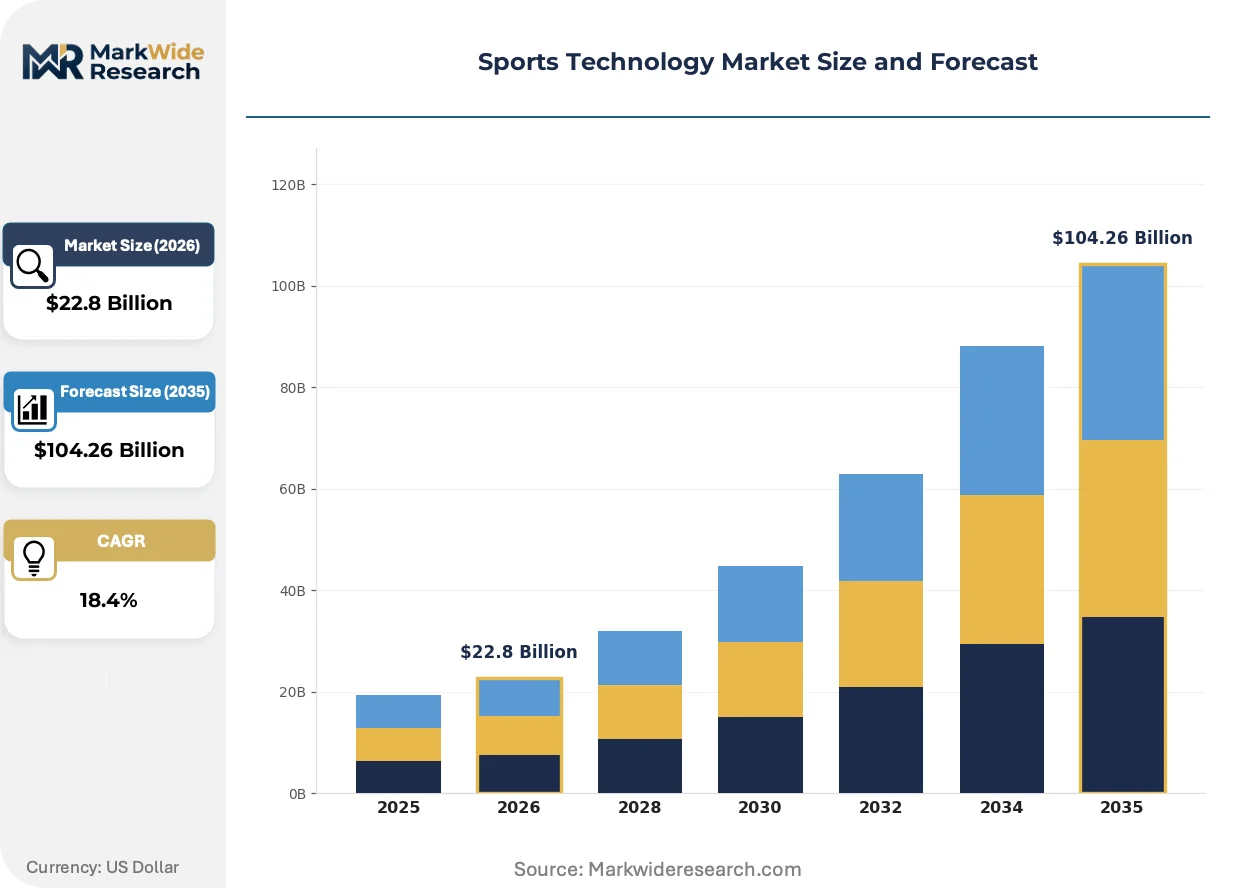
| Market Size in 2026 | $22.8 Billion |
| Market Size in 2035 | $104.26 Billion |
| CAGR (2026 – 2036) | 18.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Wearable Devices, Performance Analytics Software, Training Equipment, Smart Footwear Application: Fitness Tracking, Injury Prevention, Skill Development, Game Strategy End User: Professional Athletes, Coaches, Fitness Enthusiasts, Sports Teams Technology: AI Analytics, IoT Sensors, Virtual Reality, Biomechanics |
| Companies Covered | DraftKings, Kitman Labs, Hawk-Eye, Sportable, Plantiga, Genius Sports, SeatGeek, Orreco, WHOOP, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Sports Technology Market Strategic Shifts & Innovations
Digital twin technology is virtualizing athlete preparation workflows, compressing the boundary between physical training and simulated competition environments while creating new data asset categories.
Motion capture systems is virtualizing traditional biomechanics laboratories. Elite soccer and basketball franchises now deploy markerless camera arrays sampling at 300 Hz for full-squad training analysis. Portable deployment kits are displacing fixed-site gait analysis centers, collapsing the addressable market for dedicated sports science facilities into software-subscription economics.
The EU AI Act risk classification framework is imposing conformity assessment requirements on automated athlete selection algorithms. High-risk designation for systems influencing professional contract decisions mandates human oversight protocols and training data documentation. German Bundesliga clubs and French Olympic training centers are front-running compliance by establishing algorithmic audit committees ahead of enforcement deadlines.
Amateur athletic clubs are consolidating purchasing through league-level data consortiums rather than individual team procurement. This buyer aggregation is compressing vendor margins while demanding standardized data formats for cross-team benchmarking. The shift is most advanced in United States collegiate athletics, where conference-level agreements now cover biometric monitoring for multiple universities under unified contract terms.
Sports Technology Market Segmentation
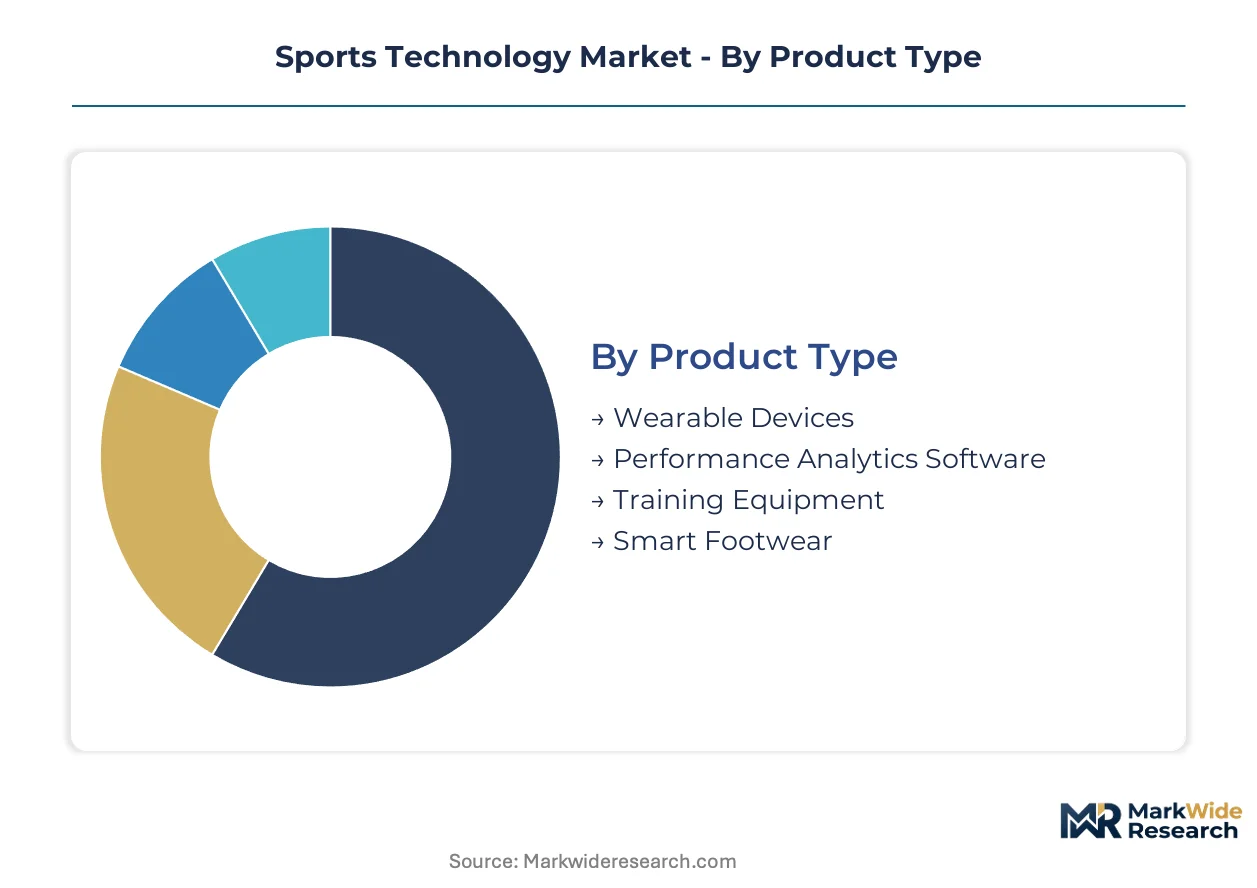
Segmentation in sports technology reveals divergent value capture strategies across hardware, software, and data layers. Product architecture choices determine whether vendors compete on sensor manufacturing margins or recurring SaaS revenue pools.
Product Type:
Mature hardware segments coexist with emerging software categories reshaping revenue mix across vendor portfolios.
- Wearable Devices:Continuous biometric monitors incorporating inertial measurement units and optical heart rate sensors at 100-1000 Hz sampling frequencies. Professional sports teams in the United States and Germany drive procurement for load management and recovery optimization, though lithium-polymer thermal constraints cap transmission duty cycles below theoretical sensor capabilities.
- Performance Analytics Software:Cloud-based platforms processing sensor fusion data through machine learning pipelines for injury prediction and tactical modeling. Franchise analytics departments now mandate API-accessible data streams, creating pull-through demand that compresses hardware margins while expanding recurring revenue pools.
- Training Equipment:Sensor-embedded apparatus including smart resistance systems and reaction training tools.
- Smart Footwear:Pressure-mapping insoles and gait analysis systems for load distribution monitoring.
Wearable Devices retains volume leadership; Performance Analytics Software holds the steepest expansion curve.
Application:
Cost tier differentiation separates enterprise-grade team deployments from consumer subscription models.
- Fitness Tracking:Consumer-facing biometric monitoring for amateur athletic optimization and wellness metrics.
- Injury Prevention:Predictive algorithms analyzing movement patterns and physiological load markers to forecast soft-tissue risk. Elite soccer and basketball franchises deploy markerless camera arrays sampling at 300 Hz, collapsing the addressable market for dedicated sports science facilities into software-subscription economics.
- Skill Development:Motion capture feedback systems for technique refinement in individual sports disciplines.
- Game Strategy:Real-time tactical analysis platforms integrating player tracking data with opponent pattern recognition. Bundesliga clubs and French Olympic training centers front-run EU AI Act compliance by establishing algorithmic audit committees for automated selection systems ahead of enforcement deadlines.
Fitness Tracking captures the broadest installed base; Game Strategy commands the highest per-seat pricing.
End User:
Customer type fragmentation creates distinct procurement channels from institutional RFPs to direct-to-consumer app stores.
- Professional Athletes:Individual biometric monitoring contracts with performance optimization specialists.
- Coaches:Squad-level analytics dashboards for training load distribution and tactical preparation.
- Fitness Enthusiasts:Amateur consumers purchasing through direct-to-consumer digital platforms bypassing traditional retail channels.
- Sports Teams:Franchise-level procurement consolidating multiple athlete subscriptions under unified contract terms. United States collegiate athletics conferences now cover biometric monitoring for multiple universities under single agreements, compressing vendor margins while demanding standardized data formats.
Sports Teams dominate enterprise revenue; Fitness Enthusiasts represent the largest addressable population.
Technology:
Supply concentration in semiconductor foundries shapes which technology layers achieve cost-competitive scale.
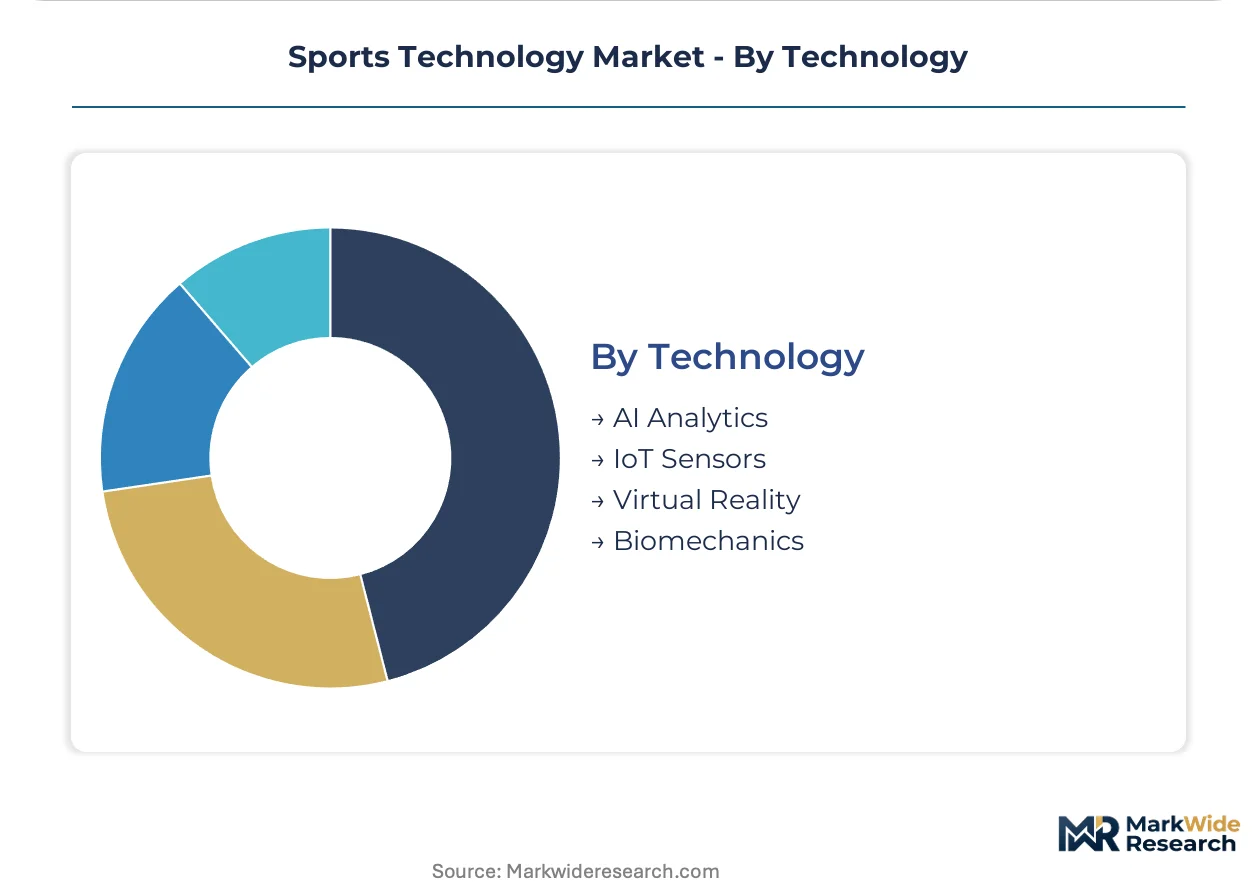
- AI Analytics:Predictive algorithms embedded in sensor firmware or delivered through cloud inference APIs. AI analytics integration is compressing decision cycles across professional sports organizations, forcing hardware vendors to embed predictive algorithms directly or surrender margin to pure-play software providers.
- IoT Sensors:Distributed device networks transmitting biometric and positional data through low-latency protocols.
- Virtual Reality:Immersive training environments simulating competition scenarios for cognitive preparation.
- Biomechanics:Motion capture and force plate analysis for movement efficiency optimization. ISO measurement accuracy certification protocols require 12-18 months of third-party testing, delaying product launches against faster-moving software competitors.
AI Analytics captures expanding margin pools; IoT Sensors provides the foundational data infrastructure.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power concentrates in the United States and Germany where franchise procurement budgets absorb premium hardware-software bundles, while India and Brazil compete on export manufacturing cost curves. The United States commands per-seat analytics pricing at three to five times emerging market equivalents. Germany enforces GDPR biometric processing constraints that inflate compliance overhead for cross-border athlete data transfers.
United States
Professional sports franchises and collegiate athletics conferences drive enterprise procurement for load management systems and predictive injury analytics. FDA clearance pathways for continuous glucose monitoring and cardiac arrhythmia detection in athlete populations expand reimbursable use cases beyond fitness into clinical sports medicine. Boston and San Francisco anchor venture capital deployment into sports technology startups, with markerless camera array deployments concentrated in NBA and NFL training facilities.
Germany
Bundesliga clubs mandate API-accessible data streams for squad-level analytics, creating pull-through demand for interoperable sensor ecosystems. The EU AI Act risk classification framework imposes conformity assessment requirements on automated athlete selection algorithms, with German clubs establishing algorithmic audit committees ahead of enforcement deadlines. Munich and Berlin host sports science research clusters where ISO measurement accuracy certification protocols require 12-18 months of third-party testing for new motion capture algorithms.
China
MIIT standards for wearable device interoperability shape domestic product development cycles, while dual carbon goals accelerate lithium-polymer battery thermal management investments. The Yangtze River Delta concentrates electronics manufacturing capacity for high-frame-rate image sensors used in broadcast motion capture systems. Shenzhen-based hardware vendors compete on sensor fusion architectures combining inertial measurement units with UWB positioning for venue-based deployment models.
India
The PLI scheme for electronics manufacturing creates cost-competitive export capacity for biometric hardware targeting price-sensitive amateur athletic segments. Amateur athletic clubs consolidate purchasing through league-level data consortiums rather than individual team procurement, compressing vendor margins while demanding standardized data formats. Karnataka and Tamil Nadu host wearable device assembly clusters serving price-sensitive fitness enthusiast segments across South Asia and Africa.
Brazil
Football club academies deploy portable motion capture kits for youth player development, displacing fixed-site gait analysis centers with software-subscription economics. ANVISA oversight governs wearable medical claims for cardiac monitoring in professional athlete populations. São Paulo anchors Latin American distribution for direct-to-consumer digital platforms bypassing traditional retail channels for fitness tracking devices.
Sports Technology Market Key Industry Players
Platform integrators command the system tier; component specialists sit upstream capturing sensor manufacturing margins while surrendering recurring revenue pools to pure-play software providers. The vendor base stratifies across three tiers: broadcast technology incumbents with proprietary camera-tracking systems, wearable device manufacturers competing on biometric sampling fidelity, and data analytics platforms monetizing official league partnerships. Dominant competitive moves include strategic partnerships for official data distribution rights and embedded firmware engineering acquisitions to secure real-time sensor fusion capabilities.
Within the platform integrator tier, Hawk-Eye and Genius Sports exemplify divergent defensive strategies against software margin compression. Hawk-Eye occupies a position anchored in broadcast and officiating technology through proprietary camera-tracking systems. Genius Sports represents the data partnership archetype, leveraging official league relationships to control premium distribution pipelines. WHOOP sits within the direct-to-consumer subscription tier, sustaining subscriber loyalty through continuous biometric monitoring positioning.
| Leading Market Players |
|---|
| DraftKings |
| Kitman Labs |
| Hawk-Eye |
| Sportable |
| Plantiga |
| Genius Sports |
| SeatGeek |
| Orreco |
| WHOOP |
| Others |
Cost & Logistics Intelligence
Taiwanese foundry concentration for high-frame-rate image sensors exposes broadcast technology vendors to geopolitical supply disruption, compressing hardware margins while widening the spread between premium configured-to-order systems and standard subscription tiers. This single-source dependency for motion capture components forces vendors to absorb tariff volatility or pass through cost increases to franchise buyers with locked procurement budgets.
Pricing Analysis
The customization-premium spread separates API-configured enterprise bundles from off-the-shelf fitness subscriptions. Three-tier pricing structure across premium, standard, and economy levels captures franchise analytics departments, collegiate conference consortiums, and individual fitness enthusiasts respectively. Price differentiation rests on ISO measurement accuracy certification and FDA wearable medical claims clearance. Cost compression in the amateur athletic segment is intensifying because league-level data consortiums aggregate purchasing power across multiple clubs. Fitness enthusiasts exhibit highest price sensitivity; professional sports franchises demonstrate lowest sensitivity due to reimbursable clinical use case expansion.
Supply Chain Analysis
Contract-manufacturing concentration sits with Taiwanese foundries for specialized image sensors, Chinese Yangtze River Delta clusters for electronics assembly, and Indian PLI scheme facilities for cost-competitive wearable device export capacity. Raw material dependencies include lithium-polymer battery cells, inertial measurement unit semiconductors, and optical heart rate sensor components. Single-source vulnerability for high-frame-rate image sensors creates procurement chokepoints for broadcast motion capture systems. Distribution runs through direct-to-consumer digital platforms, franchise-level RFP channels, and league-level data consortium procurement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating through conference-level and league-level procurement aggregation, fragmenting individual team decision authority into collective bargaining structures that compress vendor margins.
For Market Incumbents: Insulate recurring revenue pools by embedding predictive algorithms directly into sensor firmware rather than surrendering margin to pure-play software providers. Pursue backward integration into inertial measurement unit semiconductor sourcing to reduce exposure to Taiwanese foundry concentration. Lock in official league data partnerships with multi-year exclusivity terms before wagering integrity regulatory frameworks mature. For New Entrants and Emerging Players: Establish a beachhead in amateur athletic club segments where league-level data consortiums have not yet consolidated purchasing power. Target price-sensitive fitness enthusiast populations across India and Brazil through direct-to-consumer digital platforms bypassing traditional retail markups. Lead with computer vision and edge AI convergence for venue-based deployment models independent of consumer smartphone ownership. For Investors and Strategic Acquirers: The market sits at a technology-integration phase that favors embedded firmware engineering capabilities over pure software plays. Long-term viability over the coming decade hinges on securing real-time sensor fusion talent capable of optimizing sub-watt power budgets. Target acquisition archetypes include markerless motion capture specialists and algorithmic audit compliance platforms. Watch for EU AI Act enforcement deadlines as inflection indicators for automated athlete selection algorithm demand.| Strategic Initiative | Industry Significance |
|---|---|
| Embedded Firmware Acquisition | Secures real-time sensor fusion capabilities before automotive and aerospace sectors exhaust engineering talent pools. |
| Official League Data Partnership | Creates captive distribution channels with regulatory moats against unauthorized wagering feed competitors. |
| India PLI Scheme Manufacturing Footprint | Builds cost-competitive export capacity for biometric hardware targeting price-sensitive amateur segments. |
| EU AI Act Compliance Platform | Positions for mandatory algorithmic audit requirements affecting Bundesliga and Olympic training center procurement. |
| Direct-to-Consumer Platform Launch | Bypasses traditional retail channels to capture fitness enthusiast subscriptions with higher lifetime value economics. |
Research Approach
Demand-side practitioners and supply-side operators were both consulted across professional sports franchise analytics departments, collegiate athletics conference procurement officers, wearable device firmware engineers, and broadcast technology integration specialists. Secondary validation drew from FDA 510(k) filings for wearable medical claims, MIIT standards documentation for Chinese wearable interoperability, EU AI Act regulatory drafts, and ISO measurement accuracy certification protocols. Bottom-up sensor shipment estimates and top-down franchise procurement budget analysis were triangulated to anchor volume and value outputs.
Calibration against historical franchise technology spending patterns and collegiate athletics conference contract disclosures shaped the analytical framework across the analysis window. Segmentation dimensions modeled include product architecture tier, end-user procurement channel, application use case, and regional regulatory cluster. CAGRs were derived from logistic diffusion curves fitted to wearable device adoption rates and software subscription renewal patterns. Forecast inputs incorporated lithium-polymer battery thermal constraint evolution and AI inference cost decline trajectories.
Sensitivities concentrate around Taiwanese foundry supply disruption, EU AI Act enforcement timeline acceleration, and collegiate athletics conference procurement consolidation velocity. Forecasts reflect documented assumptions regarding sensor fusion architecture adoption curves and wagering integrity regulatory framework maturation. Quarterly review of FDA wearable medical claim clearance cadence and ISO certification backlog duration is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Wearable Fitness Technology
Smart Fitness Watches Market
Wearable Fitness Technology
Wearable Physiotherapy Market
Wearable Fitness Technology
Fitness Tracker for Heart Rate Market
Wearable Fitness Technology
Wearable Fitness Technology Market
Wearable Fitness Technology
Global Blood Flow Restriction Band Market
Wearable Fitness Technology
Smart Wearable Gloves Market
Wearable Fitness Technology
Smart Sports Bracelet Market
Wearable Fitness Technology
Body Sensors Market
Wearable Fitness Technology
Global Consumer Smart Wearable Market
Wearable Fitness Technology
Wearable Fitness Tracker Market
Wearable Fitness Technology
Smart Insole Market
Wearable Fitness Technology
Smart Wearable Equipment Market
Wearable Fitness Technology
Pocket Pedometers Market
Wearable Fitness Technology
Global GPS Watch Tracker Market
Wearable Fitness Technology
Smart Fitness Trackers Market
Wearable Fitness Technology
Wearable Devices in Sports Market