
 North America Sports Drink Market | 2026-2036
North America Sports Drink Market Size, Share, and Industry Trends Forecast 2026-2036
North America Sports Drink Market Analytics
Buyer concentration among collegiate athletic programs and professional sports franchises is expanding as institutional procurement standardizes around electrolyte-replacement protocols. PepsiCo, Inc. leverages its Gatorade institutional partnerships to sustain dominance in team sports channels. The Coca-Cola Company anchors its position through Powerade's Olympic and FIFA sponsorship infrastructure. Monster Beverage Corporation differentiates via performance-oriented sub-brands targeting CrossFit and endurance athlete communities.
Sports drinks are formulated aqueous beverages containing carbohydrates, electrolytes, and functional additives designed to restore fluid balance and fuel substrate during or after physical exertion, typically manufactured through hot-fill or aseptic processing with osmolality calibrated between 270 and 330 mOsm/kg for optimal gastric emptying. Isotonic formulations occupy the mature volume core due to established palatability and proven absorption kinetics, while protein-fortified variants represent the fastest-growing product type as recovery-window science penetrates consumer education. Powder pack formats are capturing margin pools through lower shipping weights and customizable dosing flexibility in home and gym environments.
The FDA governs sports drink labeling and nutrient content claims under federal food regulations, while Health Canada mandates bilingual nutrition labeling and caffeine thresholds that shape cross-border product differentiation. USDA school nutrition standards constrain formulation options for youth-targeted lines, creating compliance-driven R&D allocation. Stakeholders must monitor evolving state-level sugar taxation proposals and sodium disclosure mandates that could recalibrate formulation priorities and channel economics.
Market Dynamics
NCAA hydration guideline revisions are institutionalizing electrolyte-replacement protocols across collegiate athletic programs, converting discretionary beverage procurement into mandatory compliance spend and reshaping vendor qualification criteria.
Growth Catalysts
- USDA school nutrition standards:Mandated sodium and sugar ceilings for K-12 environments are forcing R&D investment in compliant youth formulations, creating captive demand channels with multi-year contract lock-in.
- CrossFit and endurance athlete communities:Protein-fortified recovery beverages are capturing share among high-frequency training cohorts in California and Texas metropolitan fitness corridors.
- Hot-fill aseptic processing:Extended shelf-life capabilities without preservative additives are enabling clean-label positioning in premium convenience retail segments.
Market Restraints
- High-fructose corn syrup price volatility:Input cost swings compress margin stability for mid-tier formulations dependent on commodity sweetener bases.
- Health Canada bilingual labeling mandates:Cross-border SKU fragmentation raises inventory carrying costs and complicates unified North American supply chain planning.
- Plain water and coconut water substitution:Low-cost hydration alternatives constrain price elasticity in casual recreational user segments.
Strategic Opportunities
- Ontario metropolitan corridors:Underpenetrated fitness enthusiast density in Toronto and Ottawa suburbs offers whitespace for premium isotonic positioning.
- Powder pack e-commerce channels:Direct-to-consumer subscription models bypass traditional retail slotting fees and capture recurring revenue pools.
- State-level sugar taxation proposals:Anticipatory reformulation toward stevia and monk fruit blends creates first-mover advantage in jurisdictions with pending legislation.
Industry Challenges
- Sports nutritionist certification requirements:Institutional procurement teams now demand vendor staff hold ISSN or CISSN credentials, narrowing qualified salesforce pools.
- Legacy ERP integration with DTC fulfillment:Batch-coded powder pack customization requires real-time inventory orchestration that strains existing manufacturing software stacks.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Sports Drink Market |
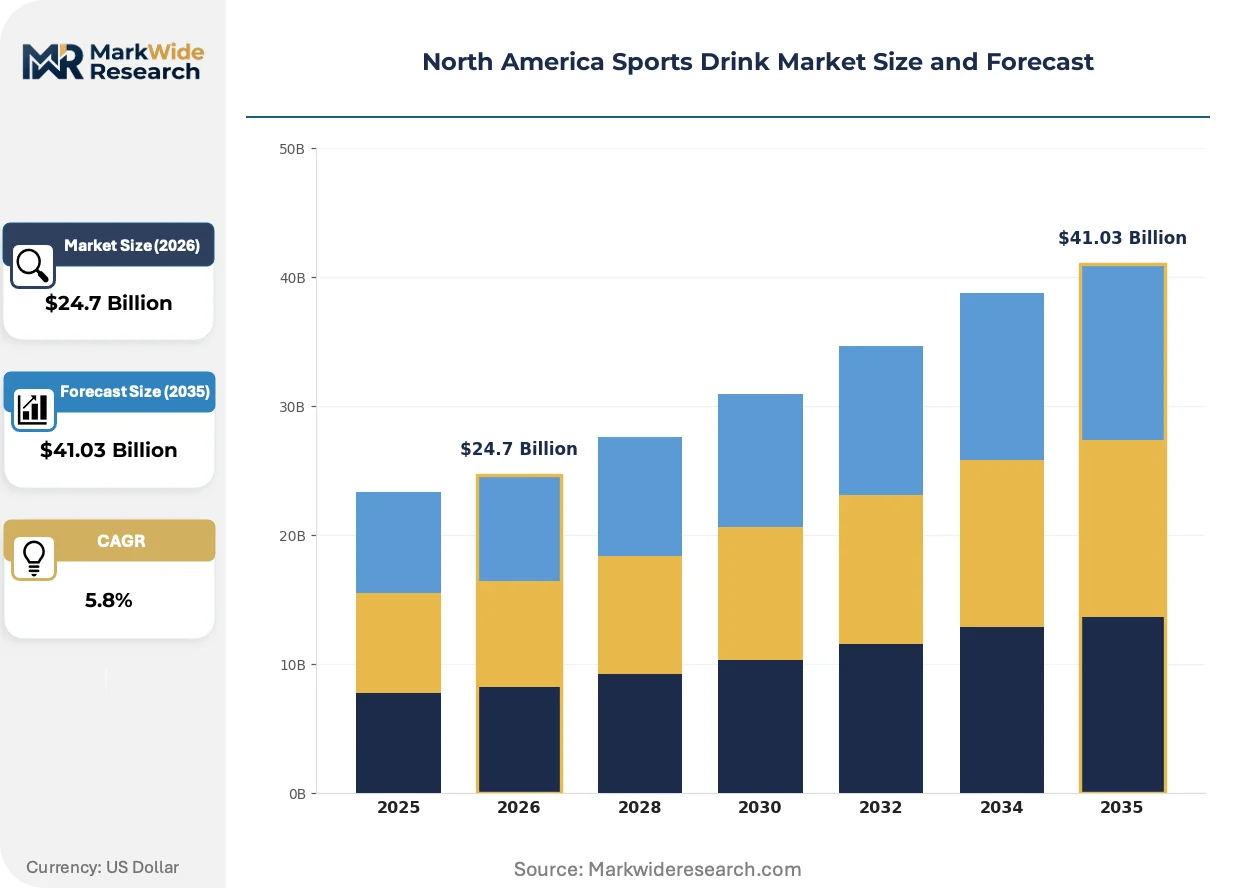
| Market Size in 2026 | $24.7 Billion |
| Market Size in 2035 | $41.03 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Isotonic, Hypotonic, Hypertonic, Protein Flavor: Citrus, Berry, Tropical, Grape Packaging Type: Bottle, Can, Powder Pack, Tetra Pak End User: Athletes, Fitness Enthusiasts, Casual Drinkers, Kids |
| Companies Covered | Red Bull GmbH, Keurig Dr Pepper, Inc., PepsiCo, Inc., Bluetriton Brands Holdings, Inc., Abbott Laboratories, The Coca-Cola Company, Celsius Holdings Inc., Congo Brands, Monster Beverage Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Sports Drink Market Evolving Landscape
Formulation science and channel architecture are diverging from mass-market homogeneity toward precision-segmented delivery systems and compliance-optimized composition.
Microbiome-targeted prebiotic fiber fortification is decentralizing the recovery beverage value proposition beyond simple electrolyte replacement. Collegiate athletic programs in Texas are piloting gut-health-optimized formulations for athlete immune resilience. This biotechnology convergence is compressing the addressable market for conventional carbohydrate-only products.
FDA nutrient content claim enforcement under updated food labeling rules is tightening permissible hydration efficacy statements. Manufacturers must now substantiate electrolyte concentration claims through clinical validation, elevating R&D compliance costs. Youth-targeted lines face the steepest reformulation burden as sodium disclosure thresholds tighten.
Subscription-based personalized hydration profiling is replacing transactional retail purchasing among high-frequency training cohorts. Mobile-connected sweat-testing devices transmit electrolyte loss data to algorithmic replenishment recommendations. California fitness enthusiasts are driving adoption velocity through wearable integration and auto-replenishment logistics.
North America Sports Drink Market Segmentation
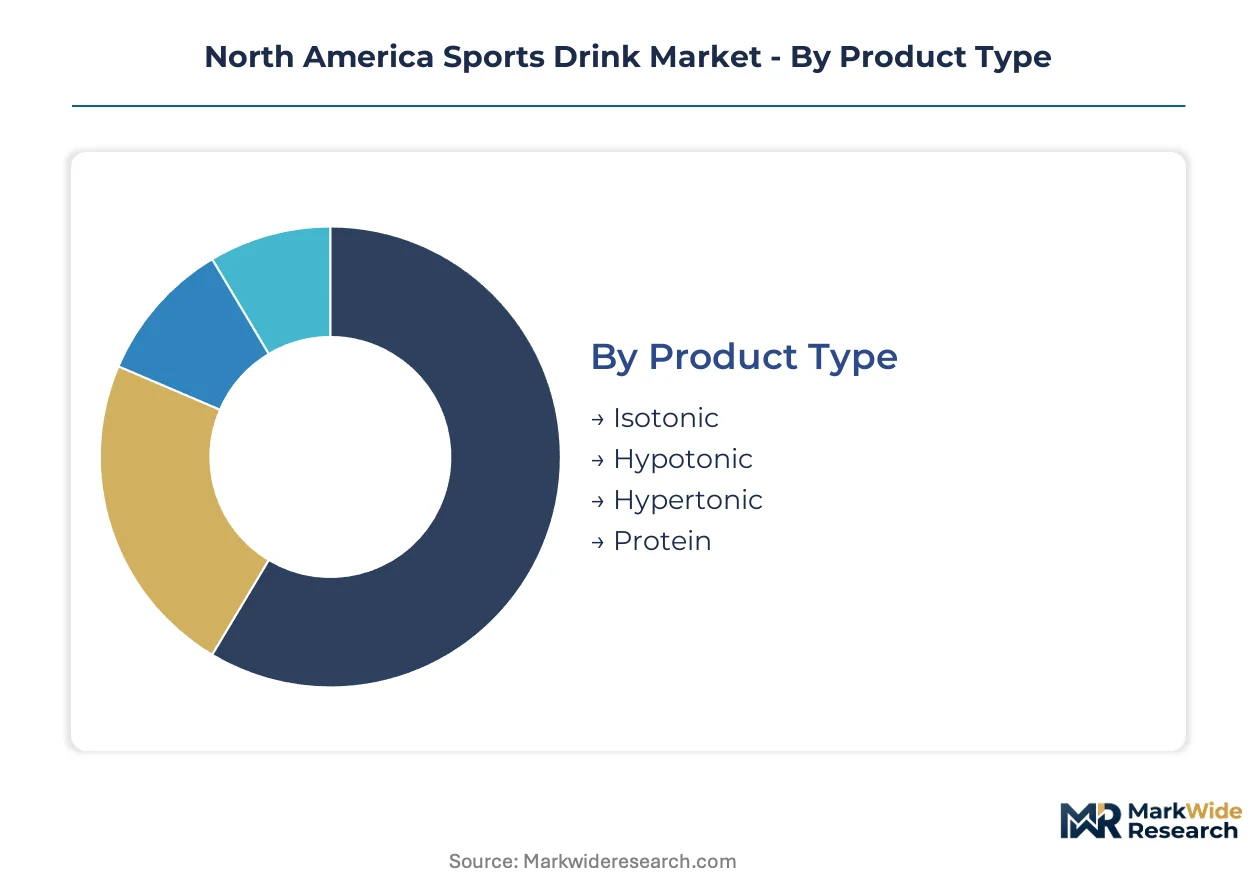
Sports drink manufacturers allocate capital across divergent production technologies, formulation chemistries, and channel infrastructures. Segmentation discipline determines which product architectures justify aseptic line investment versus hot-fill flexibility.
Product Type:
Capital intensity peaks with protein-fortified variants requiring specialized emulsion stability and extended shelf-life validation.
- Isotonic:Formulated to 270-330 mOsm/kg osmolality matching human plasma for rapid gastric emptying. Demand concentrates among collegiate athletic programs in Texas and California responding to NCAA hydration protocol mandates.
- Protein:Whey or plant-based isolates delivered in ready-to-drink emulsions demanding UHT processing and cold-chain integrity. Recovery-window science penetration among CrossFit communities in Ontario metropolitan corridors drives formulation R&D allocation.
- Hypotonic:Reduced carbohydrate density for rapid fluid absorption without caloric load. Marathon and triathlon cohorts in Florida favor pre-race hydration protocols.
- Hypertonic:Elevated carbohydrate concentration for post-exertion glycogen replenishment. Cycling teams and endurance coaching programs specify concentrated delivery formats.
Most installed capacity flows through isotonic formulations. Expansion is steepest in protein-fortified variants.
Flavor:
Flavor architecture determines raw material procurement geography and clean-label positioning costs.
- Citrus:Lemon-lime and orange profiles dominate institutional procurement contracts through established palatability benchmarks. Lemon-lime anchors Gatorade's collegiate channel dominance with decades of athlete sensory validation.
- Berry:Acai, blueberry, and mixed berry variants command premium shelf positioning in Whole Foods and Sprouts retail sets. Pacific Northwest ingredient sourcing supports antioxidant marketing claims.
- Tropical:Coconut water hybrid formulations target casual recreational users seeking exotic positioning without artificial colorants.
- Grape:Legacy flavor profile sustaining volume in youth-targeted lines constrained by USDA school nutrition sodium ceilings.
Citrus captures the largest volume share through institutional lock-in. Berry profiles are climbing the fastest through premium convenience channel expansion.
Packaging Type:
Packaging selection dictates distribution economics, sustainability compliance, and consumption occasion targeting.
- Bottle:PET and rPET formats dominate convenience retail and gas station impulse purchase environments. California's recycled content mandates are forcing resin sourcing reconfiguration for in-state production.
- Powder Pack:Single-serve sachets and bulk canisters enable customizable dosing and reduced shipping weight. Direct-to-consumer subscription models in Texas fitness corridors bypass traditional retail slotting fees.
- Can:Aluminum formats gain share in music festival and outdoor event channels where glass breakage liability constrains bottle deployment.
- Tetra Pak:Aseptic carton technology extends ambient shelf life for club store multi-packs and emergency preparedness retail sets.
Bottle infrastructure represents the largest capital deployment. Powder pack formats are gaining share fastest through e-commerce subscription velocity.
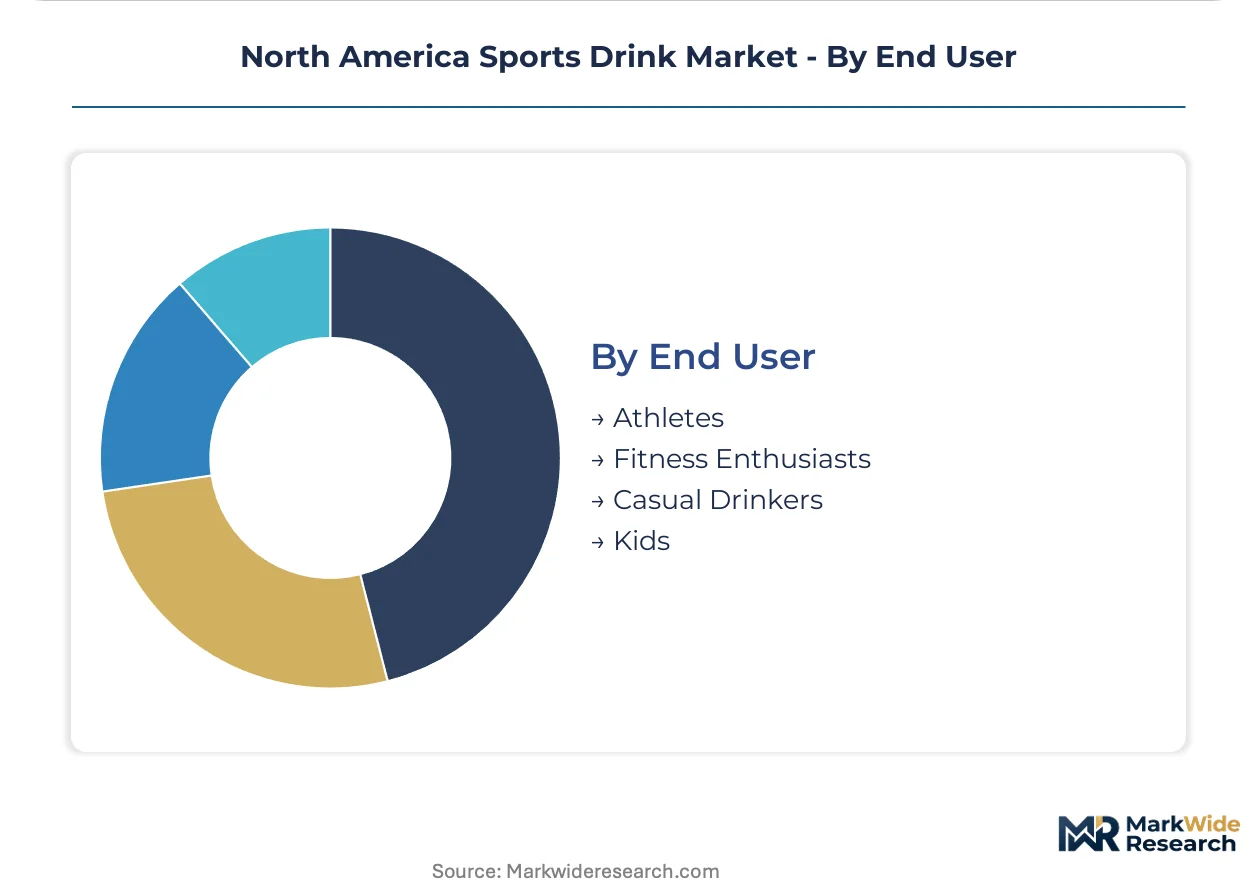
End User:
End-user segmentation determines regulatory compliance burden, marketing claim permissibility, and channel access requirements.
- Athletes:Collegiate, Olympic, and professional sports programs demanding electrolyte-replacement protocols with clinical validation documentation. NCAA guideline revisions have converted discretionary procurement into mandatory compliance spend.
- Fitness Enthusiasts:High-frequency training cohorts in California, Texas, and Ontario metropolitan corridors driving protein-fortified recovery beverage adoption. Wearable-integrated personalized hydration profiling is displacing transactional retail purchasing.
- Casual Drinkers:Recreational users seeking flavored hydration alternatives to plain water. Price elasticity constraints intensify competition from coconut water and enhanced water substitutes.
- Kids:K-12 school nutrition programs governed by USDA sodium and sugar ceilings. Reformulation investments target captive demand channels with multi-year district contract structures.
Athlete segments anchor institutional revenue stability. Fitness enthusiast cohorts are expanding most quickly through subscription personalization technology.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The United States generates substantially higher sports drink volume than Canada, though both markets face tightening regulatory constraints on sodium and sugar content that favor reformulation investment.
United States
Texas and California metropolitan fitness corridors concentrate protein-fortified recovery beverage demand among CrossFit and endurance athlete communities. The FDA governs labeling and nutrient content claims under federal food regulations, while USDA school nutrition standards constrain K-12 formulation options. NCAA hydration guideline revisions across Texas collegiate athletic programs have converted discretionary procurement into mandatory compliance spend.
Canada
Ontario's Toronto and Ottawa suburbs present whitespace for premium isotonic positioning among underpenetrated fitness enthusiast density. Health Canada mandates bilingual nutrition labeling and caffeine thresholds that shape cross-border product differentiation and raise inventory carrying costs. British Columbia's clean-label consumer preferences accelerate stevia and monk fruit blend adoption in advance of pending provincial sugar taxation.
Mexico
Mexico City metropolitan area and Nuevo León industrial corridors anchor manufacturing capacity serving both domestic consumption and North American export channels. The country's national food safety regulator enforces labeling standards that increasingly align with US FDA requirements to facilitate trade integration. Jalisco's Guadalajara metro zone concentrates distribution infrastructure for Pacific Coast fitness market penetration.
North America Sports Drink Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across a consolidated North American sports drink structure. Three to four multinational beverage holding companies anchor team sports and institutional channels through established electrolyte-replacement protocols, while smaller performance-oriented specialists target subscription-based fitness enthusiast segments. Strategic archetypes include institutional-contract dominators, endurance-community specialists, and clean-label premium insurgents. Dominant competitive moves center on anticipatory reformulation toward natural sweeteners and direct-to-consumer powder pack subscription models.
Within the institutional-contract tier, PepsiCo, Inc. and The Coca-Cola Company exemplify scale-driven channel control through collegiate athletic and Olympic sponsorship infrastructure. Monster Beverage Corporation occupies a specialist position targeting high-frequency training cohorts with performance-oriented sub-brand architecture. These three entities collectively represent the competitive spectrum from mass-market hydration dominance to precision-segmented recovery beverage positioning.
| Leading Market Players |
|---|
| Red Bull GmbH |
| Keurig Dr Pepper, Inc. |
| PepsiCo, Inc. |
| Bluetriton Brands Holdings, Inc. |
| Abbott Laboratories |
| The Coca-Cola Company |
| Celsius Holdings Inc. |
| Congo Brands |
| Monster Beverage Corporation |
| Others |
Value Network & Pricing Analysis
California's recycled content mandates for PET packaging are gating qualified supply and premium-tier pricing access, as manufacturers must reconfigure resin sourcing to maintain California retail presence while absorbing compliance-driven cost premiums.
Pricing Analysis
Capacity additions in Texas and Ontario are reshaping price floors for powder pack formats, compressing margins for mid-tier isotonic brands dependent on commodity sweetener bases. Three-tier pricing structure across premium, standard, and economy levels separates clean-label stevia formulations from conventional high-fructose corn syrup variants from private-label alternatives. Pricing pressure stems from coconut water substitution in casual recreational segments. K-12 institutional buyers exhibit highest price sensitivity due to multi-year contract lock-in, while fitness enthusiasts show lowest sensitivity through subscription personalization.
Supply Chain Analysis
ISSN and CISSN certification requirements for vendor salesforces are gating institutional procurement participation, narrowing qualified supplier pools. Manufacturing concentrates in the United States, Mexico, and Canada. Raw material dependencies include high-fructose corn syrup, whey protein isolates, and stevia extract. Single-source vulnerability runs through specialized aseptic processing equipment. Distribution runs through collegiate athletic program contracts, convenience retail chains, and direct-to-consumer subscription platforms.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The North America sports drink market functions as a stable compounder, with NCAA hydration guideline revisions converting discretionary procurement into mandatory compliance spend across collegiate athletic programs.
For Market Incumbents: Deepen electrolyte-replacement protocol documentation to defend against emerging clean-label insurgents. Lock in multi-year collegiate athletic contracts before sodium disclosure mandates tighten. Expand backward integration into stevia and monk fruit supply to preempt state-level sugar taxation. For New Entrants and Emerging Players: Begin with Ontario metropolitan corridor whitespace where fitness enthusiast density remains underpenetrated. Target powder pack direct-to-consumer subscription models to bypass retail slotting fees. Leverage wearable-integrated hydration profiling as differentiation against mass-market incumbents. For Investors and Strategic Acquirers: Roll-up economics work for specialized performance-oriented sub-brands because institutional procurement teams demand certified sports nutritionist credentials that constrain qualified acquisition targets. Five-to-ten-year viability hinges on anticipatory reformulation capabilities. Watch for FDA enforcement actions on nutrient content claims as inflection indicator.| Strategic Initiative | Industry Significance |
|---|---|
| Anticipatory Reformulation | Stevia and monk fruit blend development creates first-mover advantage in jurisdictions with pending sugar taxation. |
| Direct-to-Consumer Launch | Powder pack subscription models bypass traditional retail slotting fees and capture recurring revenue pools. |
| Certification Investment | ISSN and CISSN credentialing for salesforces gates institutional procurement participation under NCAA guidelines. |
| Distribution Channel Expansion | Ontario metropolitan corridors offer whitespace for premium isotonic positioning among underpenetrated fitness enthusiasts. |
| Sustainability Repositioning | California recycled content mandates force resin sourcing reconfiguration for in-state production compliance. |
Research Methodology
Direct dialogue with sports nutritionists, collegiate athletic procurement directors, beverage brand managers, and convenience retail category buyers grounds qualitative findings. Secondary validation draws from FDA food labeling regulations, Health Canada bilingual labeling standards, USDA school nutrition guidelines, NCAA hydration protocol documents, and Nielsen retail audit data. Bottom-up volume modeling triangulates against top-down category spend analysis.
Segmentation outputs across product type, flavor profile, packaging format, and end-user category enable granular demand decomposition throughout the forecast period. CAGRs derive from regression analysis against historical volume trajectories and elasticity-adjusted price evolution. Industry-specific forecast inputs include NCAA guideline adoption curves and state-level sugar taxation proposal tracking.
Caveats apply where FDA nutrient content claim enforcement actions or Health Canada regulatory revisions could materially shift the outlook. Forecasts reflect documented assumptions on collegiate athletic program procurement conversion rates and fitness enthusiast subscription adoption velocity. A model refresh is warranted upon material change in state-level sugar taxation legislative progress.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Sports Nutrition
Europe Protein Based Sports Drinks Market
Sports Nutrition
Hydration Products Market
Sports Nutrition
Asia-Pacific Sports Nutrition Market
Sports Nutrition
Sports Hydration Market
Sports Nutrition
United States Sports Nutrition Market
Sports Nutrition
Middle East and Africa Sports Nutrition Market
Sports Nutrition
Cricket Protein Powder Market
Sports Nutrition
ACF Supplements Market
Sports Nutrition
United States Weight Management Market
Sports Nutrition
Asia-Pacific Sports Drink Market
Sports Nutrition
Global Gummy Supplements Market
Sports Nutrition
Sports Nutrition Ingredients Market
Sports Nutrition
Weight Management Supplements Market
Sports Nutrition
Middle East Sports Drinks Market
Sports Nutrition
Global Sexual Enhancement Supplements Market
Sports Nutrition
GCC Sports Nutrition Market