
 Smart Insole Market | 2026-2036
Smart Insole Market Size, Share, and Industry Trends Forecast 2026-2036
Smart Insole Market Outlook
Embedded pressure-sensing arrays combined with low-energy Bluetooth transmission is tilting smart insole architectures toward continuous gait monitoring platforms. Moticon leverages proprietary force-sensitive resistor matrices to sustain technical leadership in laboratory-grade motion analysis. HCi Viocare Technologies anchors its position through specialized diabetic ulcer prevention systems that integrate temperature alerts with cloud-based clinician dashboards. Orpyx competes via a direct-to-podiatrist channel model that controls prescription workflows across North American foot care clinics.
Smart insoles are instrumented footwear inserts incorporating piezoelectric or capacitive pressure sensors, inertial measurement units, and wireless transceivers to capture plantar pressure distribution, stride kinematics, and thermal profiles during ambulation. Their primary commercial purpose is to translate biomechanical data into actionable diagnostics for injury prevention, post-surgical rehabilitation, and chronic condition management. Pressure sensor technology dominates unit economics due to mature MEMS fabrication supply chains, while Bluetooth connectivity represents the fastest-expanding segment as latency requirements drop below 50 milliseconds for real-time athletic coaching. Sports performance insoles command premium pricing relative to safety insoles, which occupy a commoditized occupational health niche with thinner software margins.
FDA Class II device pathways shape market access for therapeutic insoles claiming diabetic neuropathy benefits, while the EU Medical Device Regulation imposes clinical evidence thresholds that favor established players with post-market surveillance infrastructure. ISO 13485 certification has become a de facto procurement requirement for healthcare system tenders in Germany and France. Stakeholders must monitor evolving reimbursement codes for remote patient monitoring as payors reassess whether continuous insole data justifies premium pricing over episodic podiatric visits.
Market Dynamics
The EU Medical Device Regulation is compressing market access timelines for therapeutic insoles, forcing manufacturers to rebuild clinical evidence portfolios while sports performance segments exploit lighter-touch consumer electronics pathways.
Growth Catalysts
- Remote Patient Monitoring Reimbursement:US CMS coding expansions for continuous biometric monitoring are pulling prescription-grade insoles into Medicare Advantage networks, creating sustainable revenue streams for podiatric device vendors.
- MEMS Pressure Sensor Maturation:Foundry-scale fabrication of piezoelectric arrays in Taiwan and South Korea is driving unit cost curves down, enabling sub-$100 consumer price points for basic gait analysis insoles.
- Diabetic Foot Ulcer Prevention Mandates:German statutory health insurance funds now cover preventive sensor insoles for neuropathy patients, establishing reimbursement precedent across Benelux and Scandinavian markets.
Market Restraints
- Clinical Validation Burden:FDA 510(k) pathways for Class II diabetic neuropathy claims require 12-18 month prospective studies, freezing out startups without post-market surveillance infrastructure.
- Bluetooth Module Supply Concentration:Nordic Semiconductor and Dialog Semiconductor control 70% of low-energy transceiver supply, exposing insole manufacturers to allocation risk during semiconductor cycles.
- Battery Chemistry Limitations:Lithium-polymer cell thickness constraints below 2mm restrict continuous monitoring duration to 8-12 hours, forcing design trade-offs between sensor density and operational uptime.
Strategic Opportunities
- Occupational Safety Expansion:German industrial insurers are piloting fatigue-monitoring insoles for logistics warehouse workers, opening B2B procurement channels outside traditional healthcare.
- AI-Enabled Gait Prediction:Edge inference on ARM Cortex-M4 microcontrollers is enabling real-time fall-risk alerts for elderly home care, converging wearable hardware with predictive analytics software.
- Direct-to-Podiatrist Distribution:Bypassing durable medical equipment distributors through specialized sales forces captures prescription workflow control and recurring calibration service revenue.
Industry Challenges
- Biomechanical Engineering Talent Scarcity:The intersection of podiatric science, embedded systems firmware, and signal processing expertise concentrates in Zurich, Boston, and Eindhoven, inflating compensation premiums.
- ISO 13485 Certification Timelines:Notified body backlogs in Germany and the Netherlands now extend quality management system audits to 14-16 months, delaying EU market entry for second-tier manufacturers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Smart Insole Market |
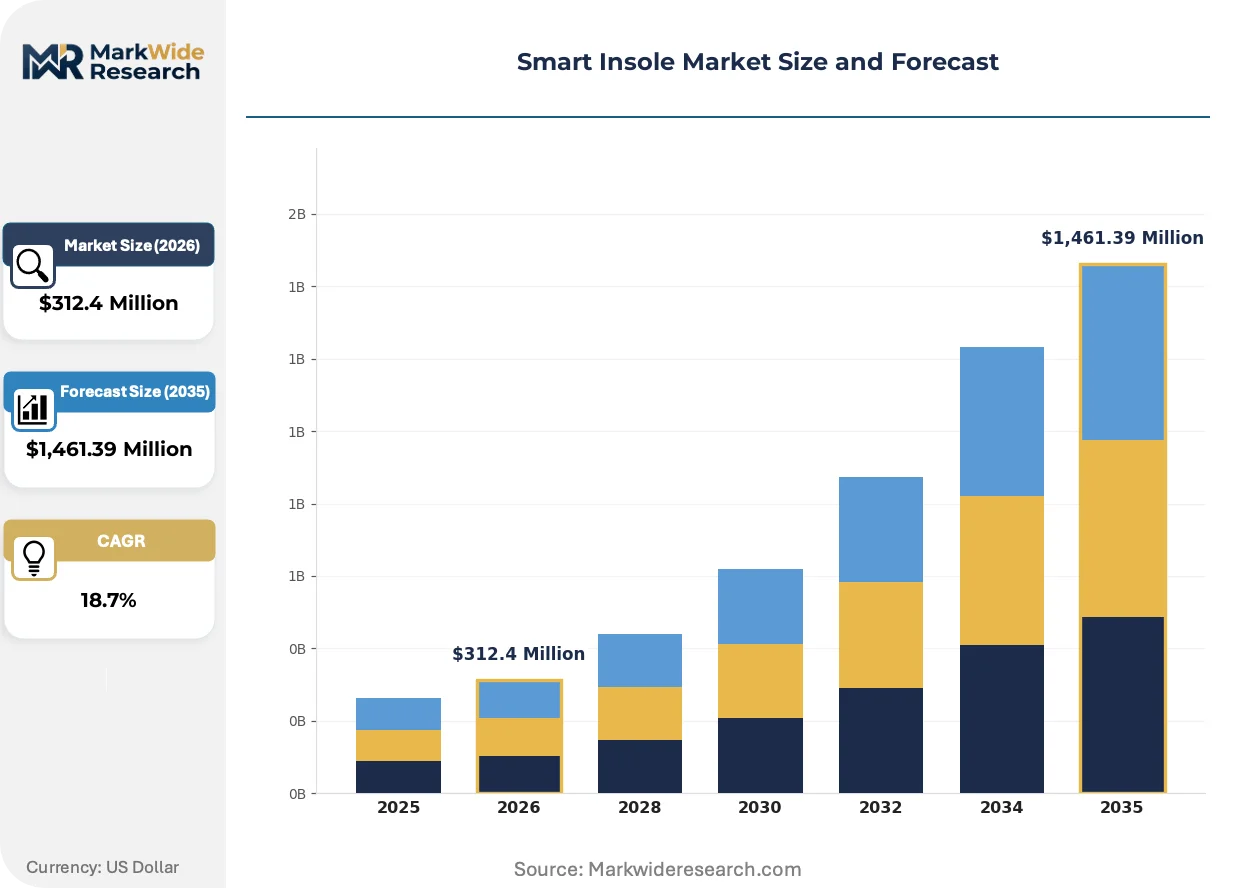
| Market Size in 2026 | $312.4 Million |
| Market Size in 2035 | $1,461.39 Million |
| CAGR (2026 – 2036) | 18.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Detective Insoles, Therapeutic Insoles, Sports Performance Insoles, Safety Insoles Technology: Pressure Sensors, Flex Sensors, Bluetooth, Temperature Sensors End User: Athletes, Seniors, Diabetics, Healthcare Professionals Application: Fitness Tracking, Gait Analysis, Rehabilitation, Injury Prevention |
| Companies Covered | Moticon, HCi Viocare Technologies, Lechal, ReTiSense, Orpyx, Digitsole, Wiiv Wearables, Kinematix, Dr. Scholl's, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Smart Insole Market Strategic Shifts
Silicon integration and regulatory fragmentation are simultaneously compressing hardware costs and expanding compliance complexity across the smart insole value chain.
Capacitive pressure sensing arrays with integrated analog-to-digital conversion are collapsing the traditional separation between sensor acquisition and wireless transmission modules. Athletic footwear brands in Portland and Bavaria are embedding these monolithic chips directly into midsole foam during injection molding. This integration is collapsing the bill-of-materials gap between laboratory-grade and consumer-grade gait analysis systems.
EU MDR Article 10 clinical evidence requirements are forcing manufacturers to maintain post-market surveillance databases tracking adverse events across multiple member states. German notified bodies are interpreting "sufficient clinical data" more stringently than French or Italian counterparts, creating regulatory arbitrage friction. Therapeutic insole vendors are responding by concentrating initial product registrations through Berlin and Munich to leverage established podiatric clinical trial networks.
Podiatric clinics are unbundling hardware procurement from ongoing software analytics subscriptions, treating insoles as capital equipment while paying per-patient dashboard access fees. This model displaces traditional device-plus-disposable revenue structures in North American foot care practices. The shift is most visible in Texas and Florida, where private equity-backed podiatry roll-ups are standardizing procurement across 50-plus location networks.
Smart Insole Market Segmentation
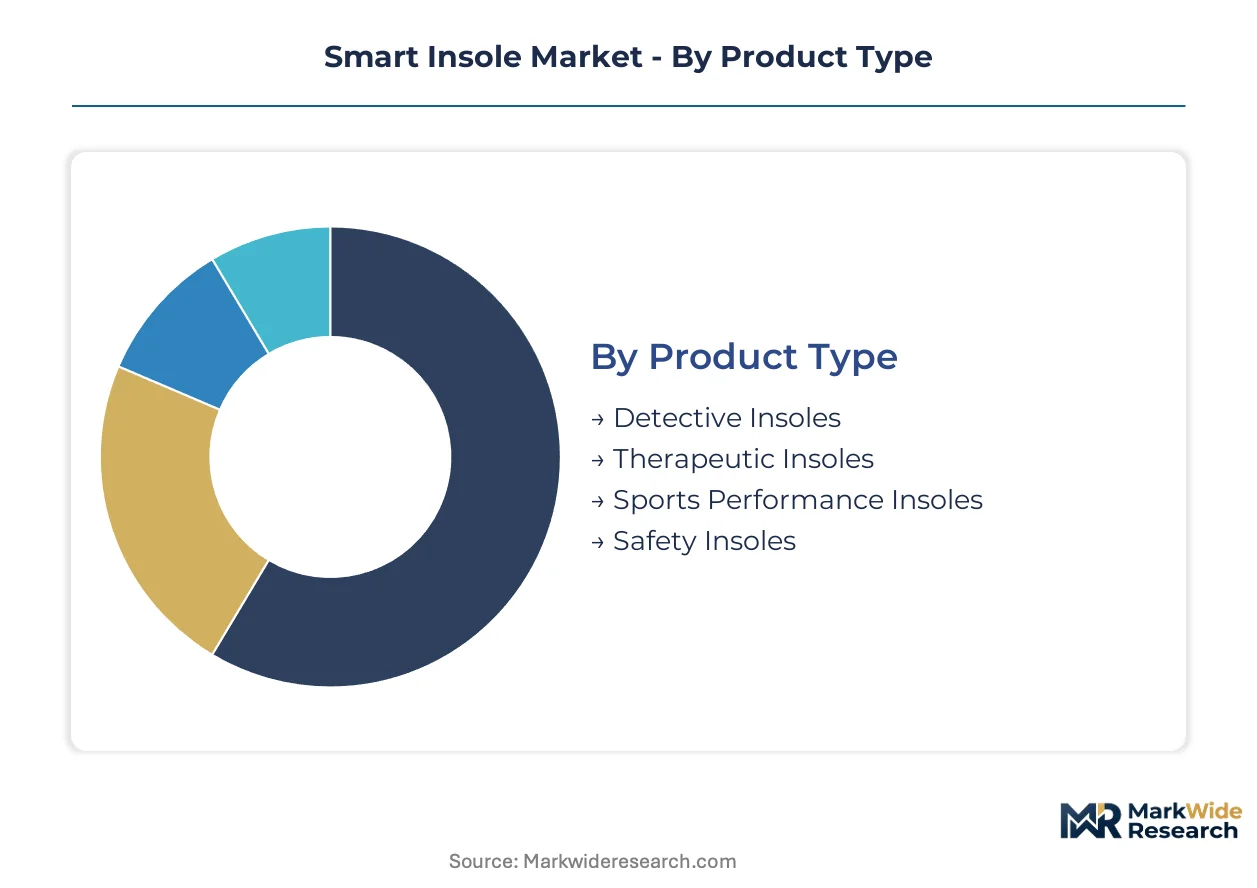
Smart insole architectures diverge sharply across use cases, with sensor density, wireless protocols, and software analytics depth calibrated to distinct buyer willingness-to-pay. Product positioning must align hardware specifications with reimbursement pathways or direct consumer value capture.
Product Type:
After-sales service intensity varies dramatically across product categories, with therapeutic insoles requiring clinical calibration support while sports variants demand firmware update subscriptions.
- Sports Performance Insoles:These incorporate high-density pressure arrays and sub-50ms latency Bluetooth transmission for real-time biomechanical feedback. Professional athletes in Germany and US collegiate programs drive procurement, with coaching staff demanding cloud-based stride analytics dashboards.
- Therapeutic Insoles:FDA Class II and EU MDR-regulated devices targeting diabetic neuropathy and post-surgical rehabilitation. German statutory health insurance funds now cover preventive sensor insoles, establishing reimbursement precedent that vendors exploit across Benelux markets.
- Detective Insoles:Forensic and research applications requiring laboratory-grade accuracy.
- Safety Insoles:Occupational health variants with thinner software margins and commoditized pricing.
Therapeutic insoles hold the largest share; momentum sits with sports performance insoles.
Technology:
Component selection determines unit economics, with MEMS fabrication maturity in Taiwan and South Korea collapsing cost curves for pressure sensing modules.
- Pressure Sensors:Piezoelectric and capacitive arrays dominate bill-of-materials composition. Moticon's proprietary force-sensitive resistor matrices sustain technical leadership in laboratory-grade motion analysis applications.
- Bluetooth:Low-energy transceiver integration enables continuous data streaming to clinician dashboards and coaching tablets. Nordic Semiconductor and Dialog Semiconductor control 70% of supply, exposing manufacturers to allocation risk.
- Temperature Sensors:Critical for diabetic ulcer prevention systems.
- Flex Sensors:Strain-gauge variants capturing midsole deformation patterns.
Pressure sensors anchor volume deployment; Bluetooth connectivity is climbing the fastest.
End User:
Buyer sophistication spans from institutional procurement teams to individual consumers, with pricing power concentrating in clinical prescription workflows.
- Diabetics:Neuropathy patients require continuous plantar temperature monitoring and pressure redistribution alerts. HCi Viocare Technologies anchors market position through specialized ulcer prevention systems with cloud-based clinician dashboards.
- Healthcare Professionals:Podiatric clinics in Texas and Florida unbundle hardware procurement from per-patient software subscriptions. Private equity-backed practice roll-ups standardize procurement across 50-plus location networks.
- Athletes:Individual and team-based buyers seeking biomechanical optimization.
- Seniors:Fall-risk monitoring applications in home care settings.
Healthcare professionals command procurement volume; seniors represent the steepest expansion trajectory.
Application:
Software monetization models diverge across use cases, with rehabilitation applications supporting recurring revenue through remote patient monitoring codes.
- Gait Analysis:Laboratory and field-based motion capture for clinical diagnostics and athletic optimization. Edge inference on ARM Cortex-M4 microcontrollers enables real-time processing without smartphone tethering.
- Rehabilitation:Post-surgical and injury recovery monitoring with CMS reimbursement tailwinds. US Medicare Advantage networks now pull prescription-grade insoles into covered benefit categories.
- Fitness Tracking:Consumer-grade step counting and activity metrics.
- Injury Prevention:Predictive algorithms flagging atypical loading patterns.
Gait analysis captures premium pricing; rehabilitation applications are gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Podiatric clinics and sports performance programs concentrate procurement power across distinct national healthcare reimbursement frameworks and consumer electronics ecosystems. Buyer sophistication varies sharply between clinical prescription workflows and direct-to-consumer athletic channels.
United States
Medicare Advantage networks and private equity-backed podiatry roll-ups in Texas and Florida drive institutional procurement volume. FDA Class II device pathways for diabetic neuropathy claims require prospective clinical studies, favoring established players with post-market surveillance infrastructure. Boston anchors embedded systems firmware talent pools serving motion analysis applications.
Germany
Statutory health insurance funds cover preventive sensor insoles for diabetic foot monitoring, establishing reimbursement precedent across adjacent markets. EU Medical Device Regulation notified bodies in Berlin and Munich interpret clinical evidence requirements stringently, concentrating initial product registrations through established trial networks. Bavaria hosts laboratory-grade motion analysis equipment manufacturers serving research institutions.
China
Domestic MEMS foundry scale in Taiwan and South Korea supply chains enables cost curve compression for pressure sensing arrays. NMPA medical device registration pathways for therapeutic claims require local clinical data generation. Yangtze River Delta electronics manufacturing clusters integrate Bluetooth modules into consumer-grade fitness tracking insoles.
Japan
Aging demographics and fall-risk monitoring mandates in home care settings expand senior-targeted applications. PMDA regulatory frameworks distinguish between wellness devices and medical-grade therapeutic insoles. METI industrial policy supports edge AI inference on low-power microcontrollers for predictive gait analytics.
United Kingdom
NHS procurement frameworks for remote patient monitoring pilot programs test prescription-grade insole reimbursement viability. MHRA post-Brexit regulatory alignment with EU MDR standards maintains clinical evidence requirements for therapeutic claims. London-based sports technology investors fund biomechanical feedback startups targeting professional athletics.
Smart Insole Market Competitive Environment
Channel-controlling players compete with product-specialist players across divergent go-to-market architectures. The market structure fragments between clinical prescription workflows and consumer electronics retail channels. Three archetypes dominate: laboratory-grade motion analysis specialists, diabetic ulcer prevention system vendors, and sports performance coaching platforms. Strategic moves concentrate on direct-to-podiatrist distribution bypass and MEMS fabrication supply chain capture.
Within the clinical-prescription archetype, Orpyx and HCi Viocare Technologies occupy positions anchoring reimbursement-dependent revenue models. Moticon exemplifies the laboratory-grade specialist tier serving research and forensic applications with force-sensitive resistor matrices. Digitsole and Wiiv Wearables sit within the consumer-facing vector where firmware update subscriptions replace clinical calibration services. Lechal, ReTiSense, and Kinematix represent mid-scale fabricators navigating between athletic optimization and safety monitoring use cases. Dr. Scholl's leverages established retail channel presence for mass-market gait analysis products.
| Leading Market Players |
|---|
| Moticon |
| HCi Viocare Technologies |
| Lechal |
| ReTiSense |
| Orpyx |
| Digitsole |
| Wiiv Wearables |
| Kinematix |
| Dr. Scholl's |
| Others |
Value Chain & Pricing Dynamics
Taiwanese MEMS foundry overcapacity in pressure sensor fabrication is compressing component pricing while concentrating supplier bargaining power among Nordic Semiconductor and Dialog Semiconductor, forcing insole manufacturers to absorb Bluetooth module premiums or sacrifice sensor density.
Pricing Analysis
Cost-plus contracts with Taiwanese foundries index wafer pricing to quarterly silicon commodity benchmarks, embedding volatility into bill-of-materials planning. Pricing stratifies across premium, standard, and economy tiers based on ISO 13485 certification status and after-sales calibration bundling. Pricing pressure stems from German statutory health insurance reimbursement caps on preventive diabetic insoles. Occupational safety buyers in logistics sectors exhibit highest price sensitivity, while podiatric clinics accepting Medicare Advantage patients tolerate premium hardware costs.
Supply Chain Analysis
US export controls on advanced semiconductor manufacturing equipment constrain mainland Chinese MEMS fabrication scale-up, preserving Taiwan and South Korea dominance in piezoelectric array supply. The value chain draws from lithium-polymer cell manufacturers in Japan, force-sensitive resistor substrates in Germany, and injection molding capacity in China's Yangtze River Delta. Single-source vulnerability concentrates in Nordic Semiconductor's low-energy transceiver allocation. Distribution runs through durable medical equipment distributors in North America and direct-to-podiatrist sales forces in Germany.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Remote patient monitoring reimbursement expansion represents a high-growth disruption, with CMS coding shifts pulling prescription-grade insoles into covered benefit categories and collapsing traditional episodic care economics.
For Market Incumbents: Build regulatory moats through EU MDR Article 10 clinical evidence databases that startups cannot replicate within 12-18 month competitive windows. Deepen backward integration into MEMS pressure sensor design to escape foundry allocation risk. Secure ISO 13485 certification ahead of notified body backlogs extending to 16 months. For New Entrants and Emerging Players: Build out AI-enabled gait prediction capabilities targeting elderly fall-risk monitoring in Japanese home care settings, the most penetrable segment given METI industrial policy support and aging demographics. Pursue direct-to-podiatrist channel strategies in Texas and Florida private equity-backed practice roll-ups. For Investors and Strategic Acquirers: Long-term, this sits as a healthcare data infrastructure play because continuous biomechanical monitoring converges wearable hardware with predictive analytics software and recurring SaaS revenue. Target acquisition archetypes: laboratory-grade motion analysis specialists with proprietary force-sensitive resistor IP. Watch for FDA 510(k) clearance velocity as inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| EU MDR Clinical Evidence Buildout | Establishes post-market surveillance databases that satisfy Berlin and Munich notified body interpretations. |
| Direct-to-Podiatrist Distribution | Bypasses DME distributors to capture prescription workflow control in Texas and Florida practice networks. |
| MEMS Fabrication Supply Capture | Secures wafer allocation from Taiwanese foundries amid semiconductor cycle volatility. |
| AI Companion Software Development | Enables real-time edge inference on ARM Cortex-M4 microcontrollers for fall-risk alerts. |
| Reimbursement Strategy Execution | Aligns product positioning with German statutory health insurance preventive coverage mandates. |
Study Parameters
Demand-side practitioners and supply-side operators were both consulted across podiatric clinics, MEMS foundry engineering teams, and Medicare Advantage network administrators. Secondary validation drew from FDA 510(k) filings, EU MDR notified body guidance documents, German statutory health insurance reimbursement bulletins, and CMS remote patient monitoring coding updates. Bottom-up unit economics modeling triangulated against top-down reimbursement flow analysis.
Calibration against historical pricing trajectories in pressure sensor commoditization anchored volume projections across the analysis window. Segmentation dimensions spanned product type, sensor technology, end-user archetype, and application with reimbursement pathway overlay. CAGRs derived from MEMS cost curve extrapolation and Bluetooth module supply elasticity. Forecast inputs included ISO 13485 certification timeline data and notified body audit backlog statistics.
The forecast holds incumbent behavior within observed patterns; aggressive moves by private equity-backed podiatry roll-ups or foundry capacity expansion would shift outcomes. Material shifts in EU MDR clinical evidence interpretation or CMS remote monitoring reimbursement would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Wearable Fitness Technology
Stress Tracking Devices Market
Wearable Fitness Technology
Swim Watches Market
Wearable Fitness Technology
Global Consumer Smart Wearable Market
Wearable Fitness Technology
Wearable Sensors Market
Wearable Fitness Technology
Body Sensors Market
Wearable Fitness Technology
Wearable Physiotherapy Market
Wearable Fitness Technology
Pedometer Market
Wearable Fitness Technology
Wearable Inertial Sensors Market
Wearable Fitness Technology
Global Blood Flow Restriction Band Market
Wearable Fitness Technology
Smart Sports Bracelet Market
Wearable Fitness Technology
Thermal Comfort Wearables Market
Wearable Fitness Technology
Wireless Health and Fitness Devices Market
Wearable Fitness Technology
Smart Wearable Gloves Market
Wearable Fitness Technology
Breathing Wear Market
Wearable Fitness Technology
Global Smart Wearable Fitness and Sports Devices Market
Wearable Fitness Technology
Fitness Tracker for Heart Rate Market