
 United States Sports Drink Market | 2026-2036
United States Sports Drink Market Size, Share, and Industry Trends Forecast 2026-2036
United States Sports Drink Market Analytics
FDA nutrition labeling reform is shifting the cost-of-entry calculus for sports drink manufacturers by forcing reformulation of legacy recipes high in added sugars. PepsiCo, Inc. leverages its Gatorade portfolio and extensive bottling infrastructure to sustain shelf dominance across mass retail channels. The Coca-Cola Company anchors its position through Powerade's exclusive partnerships with collegiate athletic conferences and professional leagues. BodyArmor differentiates through coconut water-based formulations and premium positioning that commands higher price points in convenience stores.
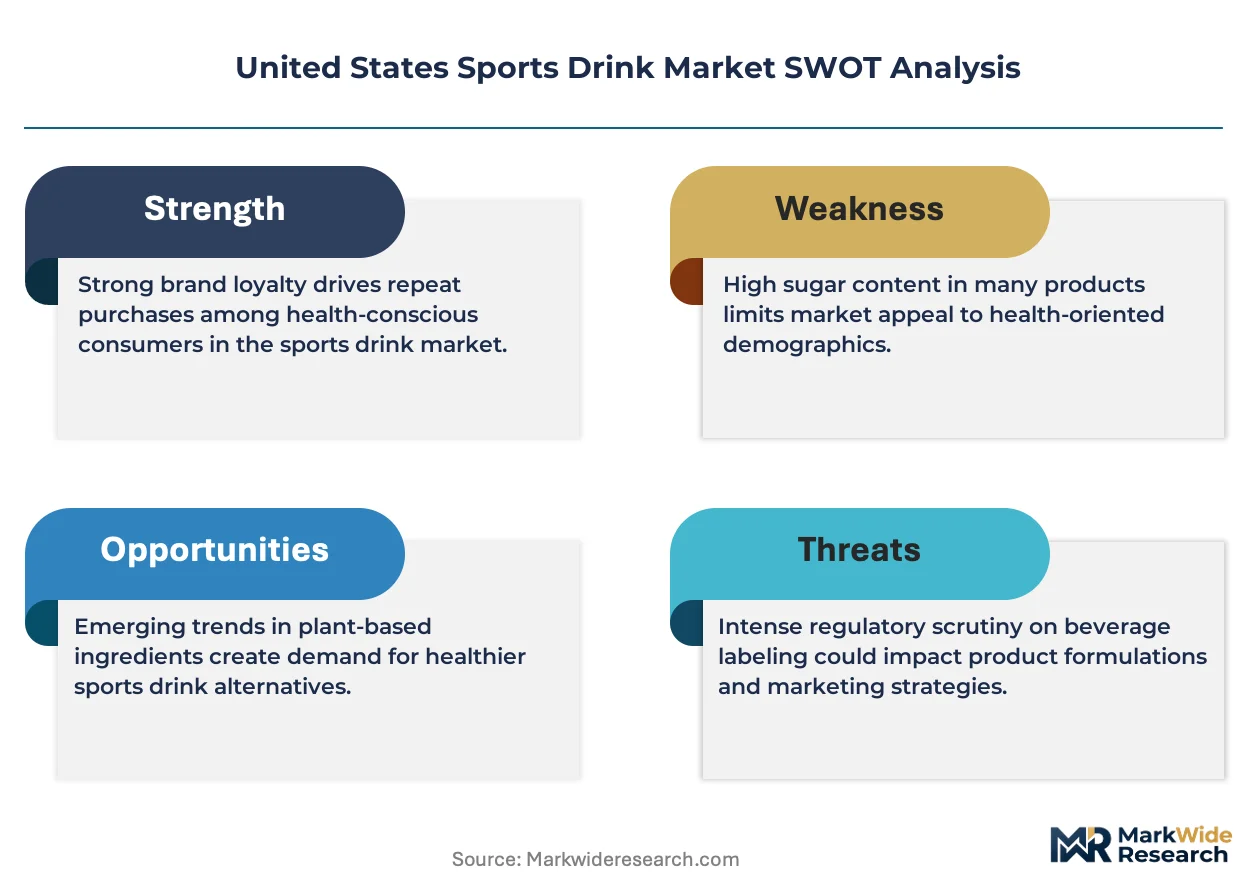
United States sports drinks are functional beverages engineered to replenish electrolytes, carbohydrates, and fluids lost during physical exertion, typically containing sodium, potassium, and magnesium in concentrations between 200-700 mg per serving to accelerate gastric emptying and intestinal absorption. Their primary commercial purpose centers on hydration optimization and performance recovery for active consumers across amateur and professional athletics. Electrolyte formulations lead the product type landscape due to established clinical validation and universal applicability across exertion levels, while protein-infused variants represent the fastest-growing segment as resistance training participation expands among aging demographics. Distribution through sports venues captures the highest margin pool per unit given captive audience dynamics and immediate consumption triggers, though online platforms are gaining structural importance for subscription-based replenishment models.
USDA organic certification standards and FDA GRAS determinations for novel sweeteners jointly shape permissible ingredient decks and label claims, creating compliance barriers for imported formulations. State-level sugar taxes in jurisdictions like Philadelphia and Seattle add localized cost complexity that national brands must absorb or pass through. Stakeholders must monitor evolving FDA guidance on permitted health claims related to exercise performance, as any restriction on "electrolyte replacement" messaging would force fundamental repositioning of core product value propositions.
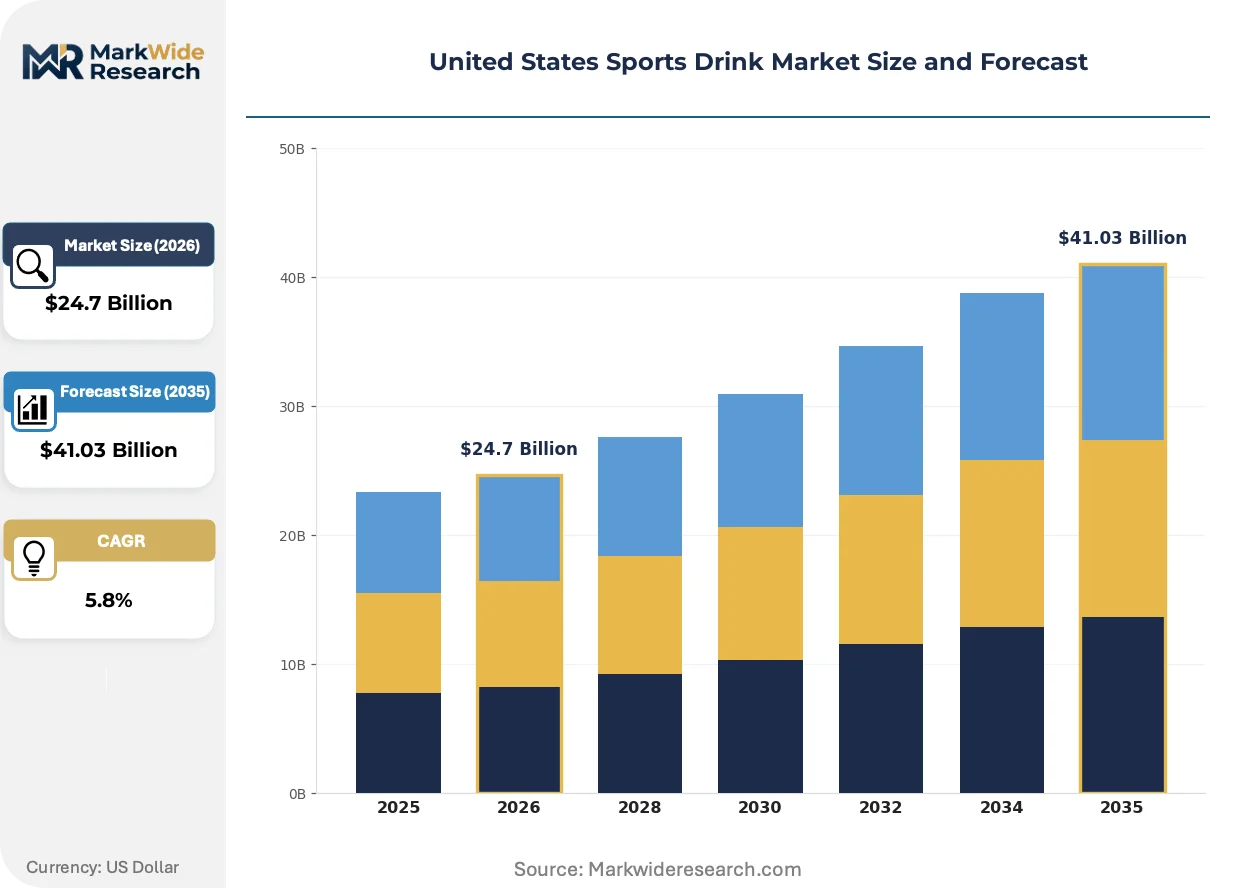
Market Dynamics
FDA nutrition labeling reform is forcing wholesale reformulation of legacy sports drink recipes, compressing margins for manufacturers dependent on added sugars while creating first-mover advantages for brands with clean-label portfolios already in market.
Growth Catalysts
- Post-pandemic fitness normalization:Sustained exercise habit formation among remote workers has expanded the addressable consumer base beyond traditional athletes into casual wellness seekers.
- USDA organic certification pathways:Streamlined approval processes for novel natural sweeteners are accelerating product development cycles for cleaner formulations.
- Sports venue density concentration:California, Texas, and Florida host disproportionate professional and collegiate athletic infrastructure, creating localized demand amplification through captive consumption environments.
Market Restraints
- Input cost volatility:Coconut water supply instability from Southeast Asian sourcing regions squeezes gross margins for premium positioning brands dependent on this base ingredient.
- Regulatory friction:Philadelphia and Seattle sugar tax regimes fragment pricing architecture, forcing national brands to absorb localized cost penalties or sacrifice volume in high-density urban markets.
- Technical limitation:Electrolyte bioavailability degradation in shelf-stable protein-infused formulations constrains product development for the fastest-growing functional segment.
Strategic Opportunities
- Subscription replenishment models:Direct-to-consumer platforms bypass traditional retail slotting fees while capturing recurring revenue streams from fitness enthusiasts with predictable consumption patterns.
- Aging demographic resistance training:Protein-infused variants targeting adults over 55 represent underpenetrated white space with higher willingness-to-pay for recovery positioning.
- State-level athletic infrastructure investment:Texas high school sports facility expansion creates captive venue distribution opportunities in the second-largest state market.
Industry Challenges
- Reformulation capex intensity:FDA-compliant recipe redevelopment requires specialized beverage chemistry talent scarce outside established CPG hubs.
- GRAS determination timelines:Novel sweetener approval delays extend product launch windows, compressing competitive response speed to shifting consumer preferences.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | United States Sports Drink Market |
| Market Size in 2026 | $24.7 Billion |
| Market Size in 2035 | $41.03 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Electrolyte, Protein, Energy, Nutrient End User: Athletes, Fitness Enthusiasts, Recreational Users, Seniors Distribution Channel: Retail Stores, Online Platforms, Sports Venues, Gyms Ingredients: Natural Flavors, Artificial Sweeteners, Vitamins, Minerals |
| Companies Covered | Electrolit, Biolyte, PepsiCo, Inc., Monster Beverage Corporation, Mas+ by Messi, The Coca-Cola Company, BodyArmor, Keurig Dr Pepper, Inc., Prime Hydration, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
United States Sports Drink Market Evolving Landscape
Electrolyte delivery systems are undergoing functional transformation as manufacturers engineer faster gastric emptying profiles, while regulatory pressure on sugar content accelerates sweetener technology substitution across all price tiers.
Microencapsulation technology for electrolyte stabilization is electrifying formulation possibilities by enabling extended shelf life without preservative additives. Functional beverage R&D teams at mid-tier manufacturers are adopting these systems at accelerating pace to close the gap with legacy brands. The technology is compressing the traditional advantage held by established players with superior distribution infrastructure.
FDA updated nutrition labeling requirements for added sugars are forcing fundamental packaging redesign and supply chain reconfiguration across the category. Manufacturers must now disclose sugar content with enhanced prominence, eliminating the ability to obscure carbohydrate sources in ingredient decks. Premium-positioned brands with existing low-sugar formulations are capturing shelf space from reformulation-lagged competitors in California and Florida convenience channels.
Subscription-based replenishment purchasing is displacing single-serve impulse buying among dedicated fitness enthusiasts with predictable training schedules. Amazon and specialized athletic nutrition platforms are capturing this behavioral shift through auto-replenishment algorithms tied to workout logging applications. This pattern concentrates most visibly in Texas metropolitan areas with high CrossFit and endurance sport participation density.
United States Sports Drink Market Segmentation
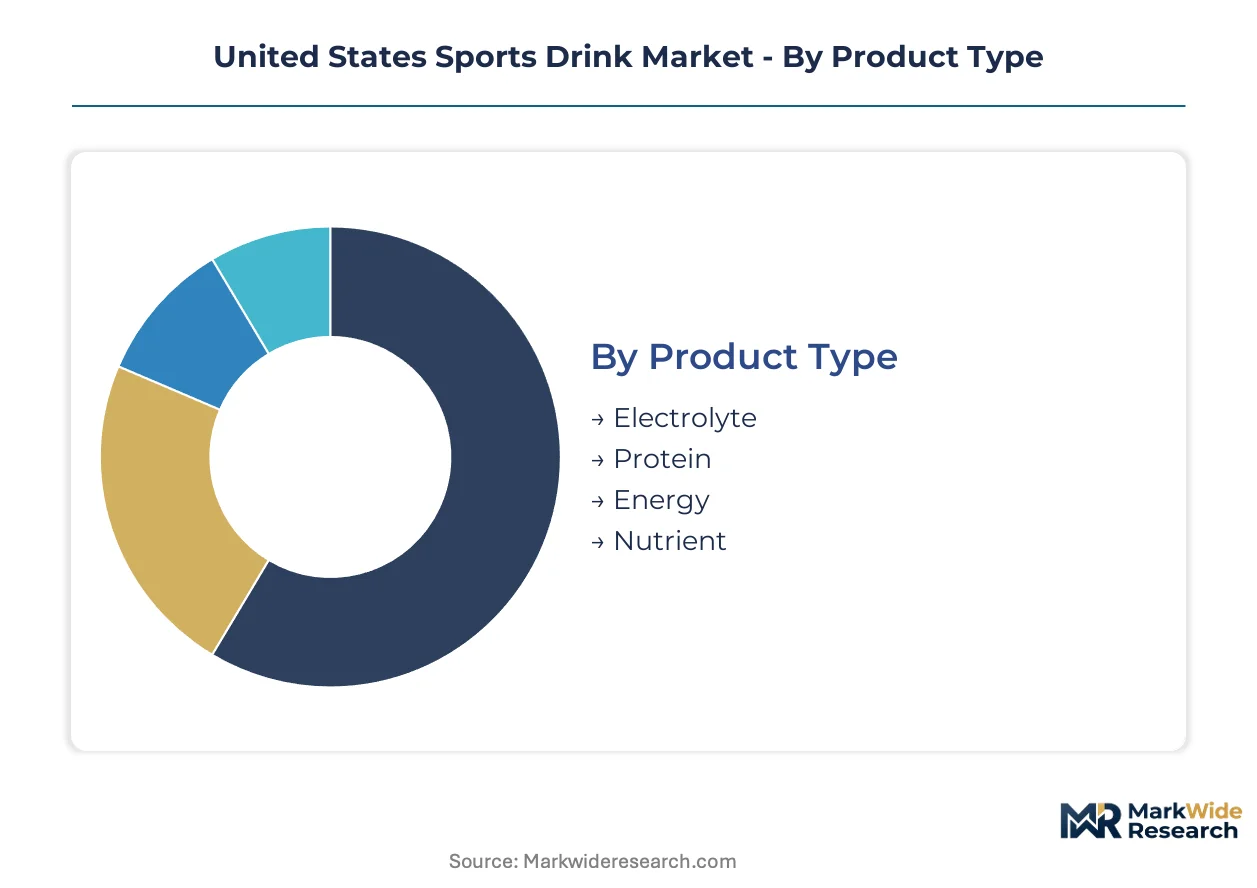
Segmentation in the United States sports drink market reveals divergent growth trajectories tied to consumption occasion and purchase channel. Manufacturers align formulation investments and distribution spending against these divides to capture margin pools with distinct competitive dynamics.
Product Type:
Performance goals dictate formulation chemistry and price tolerance across consumer cohorts.
- Electrolyte:Sodium-potassium-magnesium blends between 200-700 mg per serving accelerate gastric emptying and intestinal absorption. Demand concentrates in Texas and Florida high school athletics programs where heat stress drives immediate consumption. FDA labeling reform favors established low-sugar recipes in this segment.
- Protein:Shelf-stable protein infusion targets resistance training recovery with elevated amino acid density. California fitness enthusiasts over 55 drive fastest expansion as aging demographics prioritize muscle maintenance. Technical constraints on electrolyte bioavailability degradation constrain formulation innovation.
- Energy:Caffeine-enhanced variants bridge sports hydration and energy drink categories. Convenience store placement in metropolitan Texas clusters captures commuter and pre-workout occasions.
- Nutrient:Vitamin-fortified positioning appeals to wellness-oriented casual consumers. USDA organic certification pathways accelerate development cycles for cleaner label variants.
Electrolyte formulations lead on scale; protein variants lead on momentum.
End User:
Training intensity and frequency shape volume commitment and brand loyalty patterns.
- Athletes:Collegiate and professional competitors require rapid rehydration validated by clinical studies. Exclusive venue partnerships in California, Texas, and Florida professional sports infrastructure create captive distribution.
- Fitness Enthusiasts:Post-pandemic remote workers with solidified exercise habits represent the expanding addressable base. Subscription replenishment through Amazon and specialized athletic platforms displaces impulse purchasing in Texas CrossFit-dense metros.
- Recreational Users:Weekend warriors and casual team sports participants drive seasonal volume spikes. Price sensitivity limits premium positioning acceptance.
- Seniors:Adults over 55 pursuing resistance training recovery show elevated willingness-to-pay for protein-enhanced positioning. Underpenetrated white space offers margin expansion opportunity.
Fitness enthusiasts anchor volume growth; seniors present the steepest expansion trajectory.
Distribution Channel:
Channel selection determines margin capture and consumption trigger proximity.
- Retail Stores:Mass grocery and convenience channels sustain volume through impulse placement. PepsiCo's Gatorade leverages bottling infrastructure for shelf dominance.
- Online Platforms:Direct-to-consumer auto-replenishment algorithms tied to workout logging applications capture predictable consumption. Amazon subscription models bypass traditional slotting fees.
- Sports Venues:Captive audience dynamics at professional and collegiate events yield highest margin per unit. California, Texas, and Florida venue density amplifies localized demand.
- Gyms:Immediate post-workout consumption triggers drive premium price acceptance. Protein-infused variants gain traction in resistance training facilities.
Retail stores dominate absolute volume; online platforms are gaining structural importance fastest.
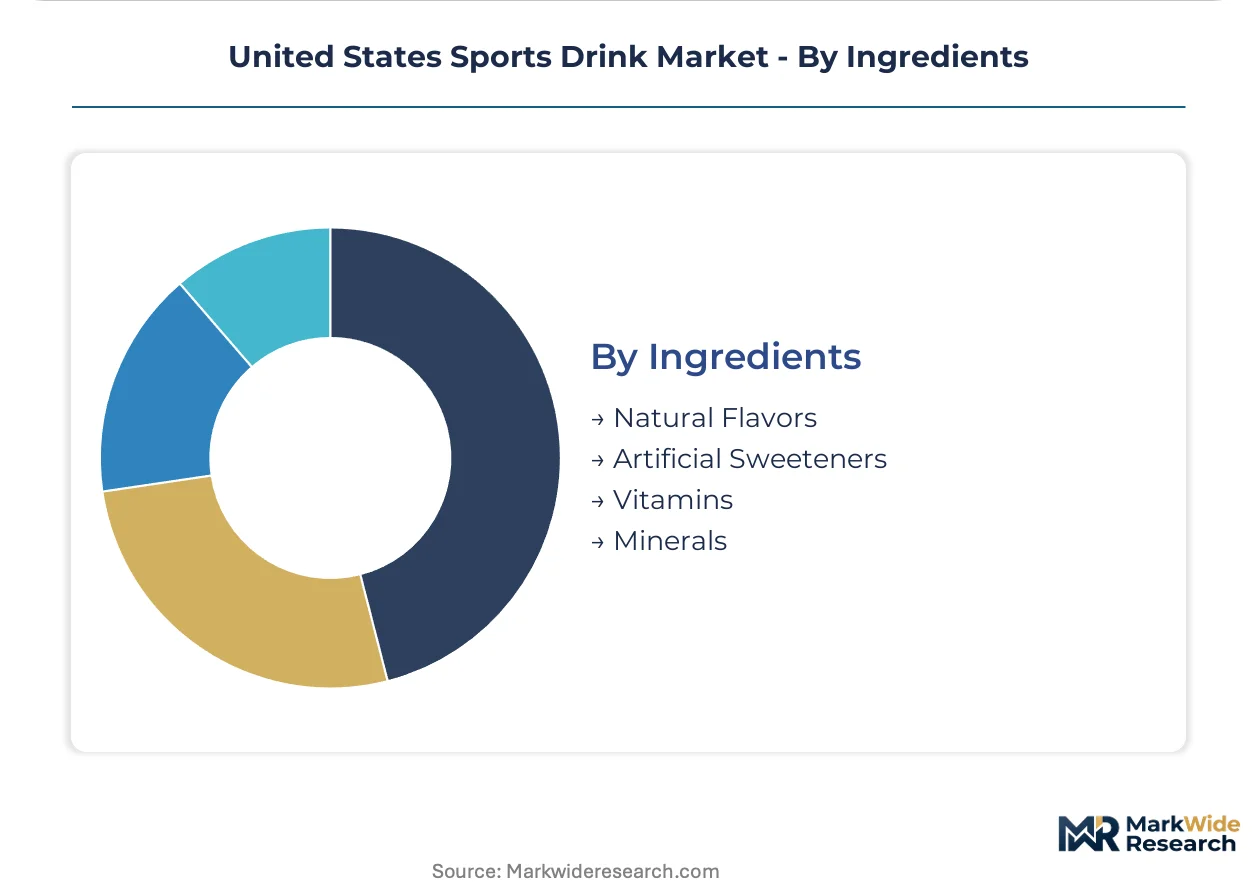
Ingredients:
Regulatory compliance and clean-label positioning reshape permissible formulation decks.
- Natural Flavors:Plant-derived taste systems align with wellness positioning. Streamlined USDA organic certification accelerates product development for premium brands.
- Artificial Sweeteners:FDA GRAS determinations for novel alternatives enable sugar reduction without taste compromise. Reformulation capex intensity burdens legacy manufacturers.
- Vitamins:Fortification supports nutrient positioning for casual wellness seekers. Label claim restrictions require careful regulatory navigation.
- Minerals:Electrolyte sourcing from coconut water faces Southeast Asian supply instability. Premium positioning brands absorb margin compression from input volatility.
Natural flavors command premium positioning; artificial sweeteners enable fastest regulatory compliance adaptation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Beverage formulation talent clusters in California, Texas, and Florida anchor national production capacity. These states concentrate sports science research institutions, flavor chemistry expertise, and bottling infrastructure that supply nationwide distribution networks.
California
Silicon Valley fitness technology integration and Los Angeles entertainment industry wellness culture drive premium positioning demand. FDA nutrition labeling reform enforcement is strictest here, accelerating clean-label adoption. San Diego hosts multiple coconut water sourcing headquarters managing Southeast Asian supply relationships.
Texas
High school athletics participation rates and CrossFit gym density create concentrated consumption volume. State athletic infrastructure investment expands venue distribution opportunities. Dallas-Fort Worth bottling corridors supply central and southern regional markets.
Florida
Year-round outdoor athletics and professional sports venue density sustain heat-stress-driven electrolyte demand. Miami functional beverage incubators attract startup formulation talent. Orlando theme park captive consumption environments yield elevated margin capture.
New York
Financial services workforce wellness programs and boutique fitness studio proliferation expand addressable base beyond traditional athletes. Philadelphia sugar tax spillover effects pressure pricing architecture in adjacent metro areas. Brooklyn-based direct-to-consumer subscription platforms pioneer auto-replenishment algorithms.
Illinois
Chicago logistics hubs enable efficient Midwest distribution from coastal manufacturing centers. State-level sugar tax discussions create regulatory uncertainty for national pricing strategies. Peoria agricultural processing infrastructure supports corn-derived sweetener supply chains.
United States Sports Drink Market Competitive Landscape
The competitive structure tilts toward diversified beverage conglomerates with existing bottling infrastructure and shelf access. Three archetypes dominate: legacy hydration brands with decades of athlete endorsement relationships, premium-positioned clean-label specialists, and celebrity-backed entrants leveraging social media distribution. Dominant competitive moves include exclusive venue partnerships and direct-to-consumer platform development.
Within the diversified beverage conglomerate tier, PepsiCo, Inc. and The Coca-Cola Company exemplify scale-driven positioning through mass retail shelf dominance and sports venue exclusivity. BodyArmor occupies a premium specialist position with coconut water-based formulations. Prime Hydration represents the celebrity-backed archetype leveraging social-native marketing channels.
| Leading Market Players |
|---|
| Electrolit |
| Biolyte |
| PepsiCo, Inc. |
| Monster Beverage Corporation |
| Mas+ by Messi |
| The Coca-Cola Company |
| BodyArmor |
| Keurig Dr Pepper, Inc. |
| Prime Hydration |
| Others |
Value Network & Pricing Analysis
FDA-mandated added sugar disclosure is forcing reformulation investments that compress margins for legacy manufacturers while rewarding clean-label first movers with pricing power in California and Florida convenience channels.
Pricing Analysis
Subscription bundling versus single-serve unbundling splits the market into recurring revenue and impulse purchase architectures. Three-tier pricing structure across premium, standard, and economy levels stratifies by ingredient certification tier and channel placement. Pricing pressure stems from Philadelphia and Seattle sugar tax absorption requirements that national brands cannot fully pass through. Recreational users exhibit highest price sensitivity while aging fitness enthusiasts over 55 show lowest elasticity for protein-infused recovery positioning.
Supply Chain Analysis
Dual-sourcing mandates from major retail chains require coconut water qualification across both Southeast Asian and Central American origins to mitigate climate-driven supply disruption. Manufacturing draws from California flavor chemistry clusters, Texas bottling corridors, and Florida distribution hubs. Raw material dependencies center on electrolyte minerals, natural sweetener alternatives, and shelf-stabilizing microencapsulation inputs. Single-source vulnerability concentrates in Thai and Indonesian coconut water supply. Distribution runs through mass retail slotting agreements, direct-to-consumer subscription platforms, and captive sports venue concession networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Texas high school athletic infrastructure expansion against California's stricter FDA enforcement creates a geographic-arbitrage window for brands able to manufacture in lower-compliance-cost jurisdictions while selling into premium-positioned coastal markets.
For Market Incumbents: To counter Prime Hydration's social-native customer acquisition, PepsiCo and Coca-Cola must deepen exclusive venue partnerships with collegiate athletic conferences and accelerate in-house natural sweetener R&D to reduce GRAS determination dependency. Backward integration into coconut water sourcing through Central American agricultural investments reduces Southeast Asian supply risk exposure. For New Entrants and Emerging Players: Adults over 55 pursuing resistance training recovery represent the most penetrable buyer archetype with minimal incumbent targeting and elevated willingness-to-pay. White space concentrates in USDA-certified organic protein-infused formulations for this demographic. Go-to-market should leverage Amazon subscription auto-replenishment tied to fitness tracking application integrations. For Investors and Strategic Acquirers: Asymmetric upside sits with mid-tier clean-label specialists possessing existing low-sugar formulations and direct-to-consumer platform infrastructure. Long-term viability hinges on regulatory compliance agility rather than scale economics. Acquisition targets should demonstrate rapid GRAS navigation capabilities. The signal to watch is FDA guidance tightening on permitted exercise performance claims.| Strategic Initiative | Industry Significance |
|---|---|
| Reformulation Investment | Accelerates compliance with FDA added sugar disclosure requirements while capturing clean-label premium positioning. |
| Exclusive Venue Partnership | Secures captive consumption environments in Texas high school athletics and Florida professional sports infrastructure. |
| Subscription Platform Launch | Bypasses mass retail slotting fees through Amazon and specialized athletic nutrition auto-replenishment algorithms. |
| Organic Certification Pathway | Streamlines USDA approval for novel natural sweeteners in California's strictest enforcement environment. |
| Sports Science R&D Alliance | Validates protein-infused bioavailability claims for aging demographic resistance training recovery positioning. |
Research Methodology
Bottom-up fitness enthusiast consumption modeling reconciled against top-down bottling capacity tracking forms the analytical core. Primary interviews with beverage formulation chemists, sports venue procurement directors, retail category buyers, and direct-to-consumer platform operators combined with secondary validation from FDA GRAS filings, USDA organic certification databases, Nielsen retail audit data, and state athletic participation surveys. Triangulation across these sources anchors volume and value estimates.
Input-output matrices map electrolyte, protein, energy, and nutrient formulation segments against end-user intensity tiers and channel margin structures across the projection horizon. CAGRs derive from segment-level adoption curves and pricing trajectory modeling. Industry-specific forecast inputs include CrossFit gym density correlations, high school athletics participation rates, and sugar tax jurisdiction expansion probabilities.
Underlying measurement precision varies by segment; subscription-based online channel data carry tighter precision than recreational user impulse purchasing estimates. Forecasts reflect assumptions on FDA guidance evolution, coconut water supply stability, and state-level athletic infrastructure investment continuity. Deviation in GRAS determination timelines for novel sweeteners would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Sports Nutrition
Sports Nutrition Ingredients Market
Sports Nutrition
Europe Weight Management Supplement Market
Sports Nutrition
Pre-Workout Supplements Market
Sports Nutrition
Taurine Supplements Market
Sports Nutrition
China Sports Drink Market
Sports Nutrition
North America Sports Nutrition Market
Sports Nutrition
Weight Management Supplements Market
Sports Nutrition
Arginine Supplement Market
Sports Nutrition
Germany Sports Nutrition Market
Sports Nutrition
Active Nutrition Market
Sports Nutrition
Creatine Monohydrate Market
Sports Nutrition
Asia-Pacific Sports Drink Market
Sports Nutrition
United States Sports Nutrition Market
Sports Nutrition
Caloric Test Market
Sports Nutrition
L-Carnitine Supplements Market
Sports Nutrition
GCC Sports Nutrition Market