
 Smart Fitness Watches Market | 2026-2036
Smart Fitness Watches Market Size, Share, and Industry Trends Forecast 2026-2036
Smart Fitness Watches Market Analysis
Buyer concentration in the enterprise wellness segment is realigning procurement patterns toward bulk device deployments with centralized data analytics. Apple Inc. leverages its vertically integrated health software stack to sustain premium positioning across corporate contracts. Garmin Ltd. dominates the multisport athlete niche with specialized GPS accuracy and extended battery architectures. Samsung Electronics competes through cross-platform compatibility and broad carrier distribution channels.
Smart fitness watches combine photoplethysmography sensors, accelerometers, and GNSS receivers in wrist-worn form factors to deliver continuous physiological monitoring and activity quantification. These devices process optical heart rate data at sampling rates exceeding 100 Hz while transmitting encrypted biometric streams to paired smartphones or cloud health platforms. The smartwatch category anchors value pools through advanced health diagnostics including ECG and blood oxygen sensing, while activity trackers occupy volume leadership in price-sensitive casual user segments. GPS-enabled multisport watches command margin premiums among athletes requiring route mapping and performance analytics in extreme environments.
The FDA regulates software-as-medical-device claims through premarket notification pathways, compelling manufacturers to validate algorithm accuracy for heart rhythm and blood oxygen features. CE marking under the EU MDR and GDPR biometric data governance collectively shape European product design and data residency requirements. Stakeholders must monitor evolving regulatory distinctions between general wellness and diagnostic claims, as reclassification decisions will determine which devices require clinical validation and which remain in consumer electronics channels.
Market Dynamics
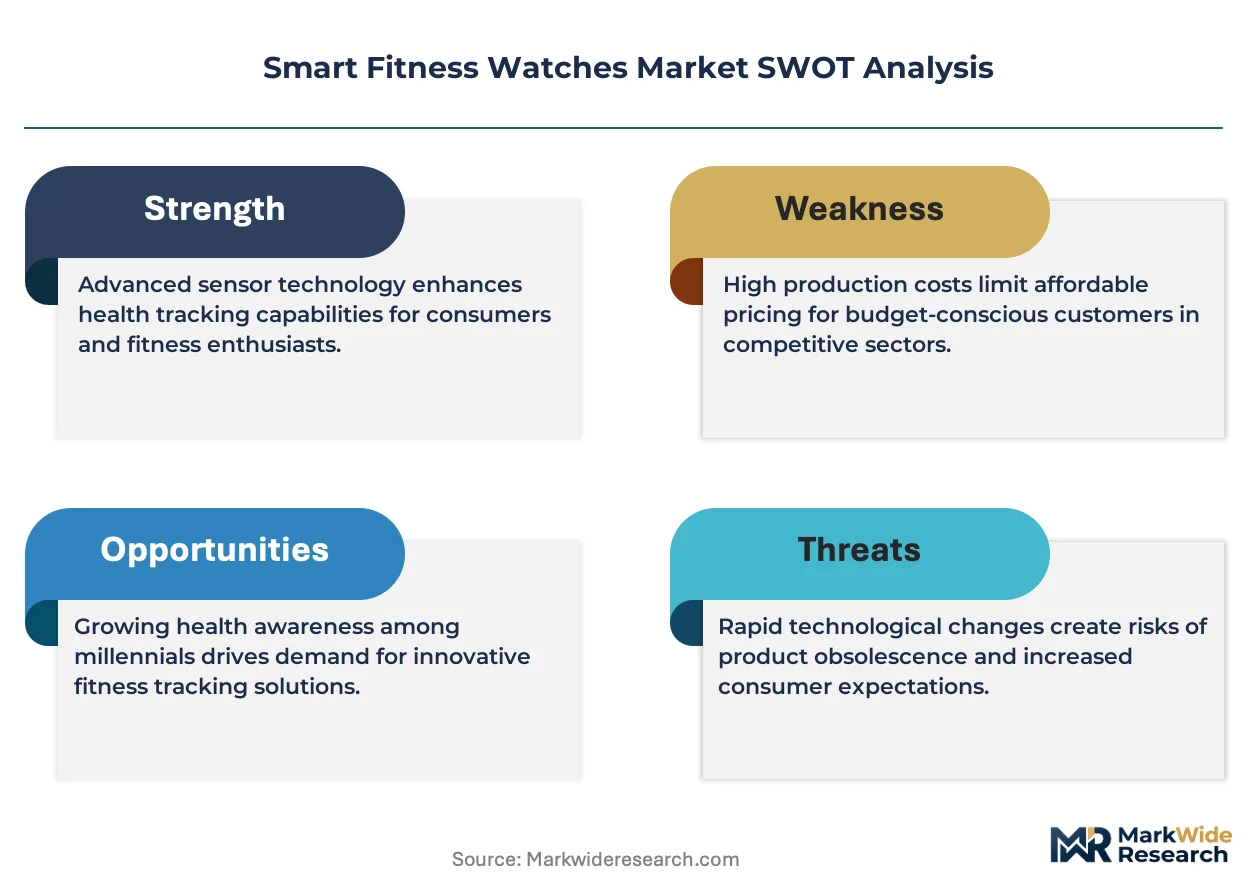
Corporate wellness programs are consolidating procurement around bulk device deployments with centralized data analytics platforms, compressing vendor margins while elevating requirements for enterprise-grade security and API interoperability.
Growth Catalysts
- FDA Software-as-Medical-Device Framework:The FDA's evolving regulatory pathway for algorithm-validated health features is expanding reimbursable use cases for clinical-grade wearables in remote patient monitoring programs.
- Photoplethysmography Sampling Advances:Optical heart rate sensors now exceed 100 Hz sampling rates, enabling atrial fibrillation detection accuracy comparable to single-lead ECGs in ambulatory settings.
- China Manufacturing Scale:Domestic Chinese brands leverage Shenzhen component ecosystems and localized health app integrations to compress production costs and accelerate feature iteration cycles.
Market Restraints
- GDPR Biometric Data Residency:EU data localization mandates force redundant cloud infrastructure investments, raising operational costs for wearable platforms serving European enterprise accounts.
- GNSS Receiver Supply Concentration:Precision GPS modules rely on concentrated semiconductor fabrication in Taiwan, exposing multisport watch manufacturers to single-source vulnerability.
- Battery Chemistry Constraints:Lithium-polymer cell energy density plateaus limit extended GPS tracking durations, forcing trade-offs between form factor and athlete-use-case functionality.
Strategic Opportunities
- India Preventive Health Mandates:Corporate health insurance regulations are incentivizing wearable adoption for premium discounts, opening volume procurement channels in underpenetrated enterprise segments.
- Continuous Glucose Monitoring Convergence:Non-invasive optical glucose sensing is approaching clinical validation thresholds, positioning smartwatches to capture metabolic monitoring share from dedicated CGM devices.
- Outcome-Based Wellness Contracts:Employers are shifting from device subsidies to performance-linked pricing tied to measurable health outcome improvements, creating recurring revenue architecture for platform providers.
Industry Challenges
- Algorithm Validation Talent Scarcity:Clinical-grade feature development requires biomedical engineering expertise in signal processing and regulatory science, creating hiring bottlenecks in competitive labor markets.
- CE Marking Timeline Compression:EU MDR recertification requirements are extending approval cycles for software updates, slowing competitive response to feature gaps.
- Legacy EHR Integration Complexity:Enterprise wellness platforms face fragmented health record system architectures requiring custom API development for each hospital network deployment.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Smart Fitness Watches Market |
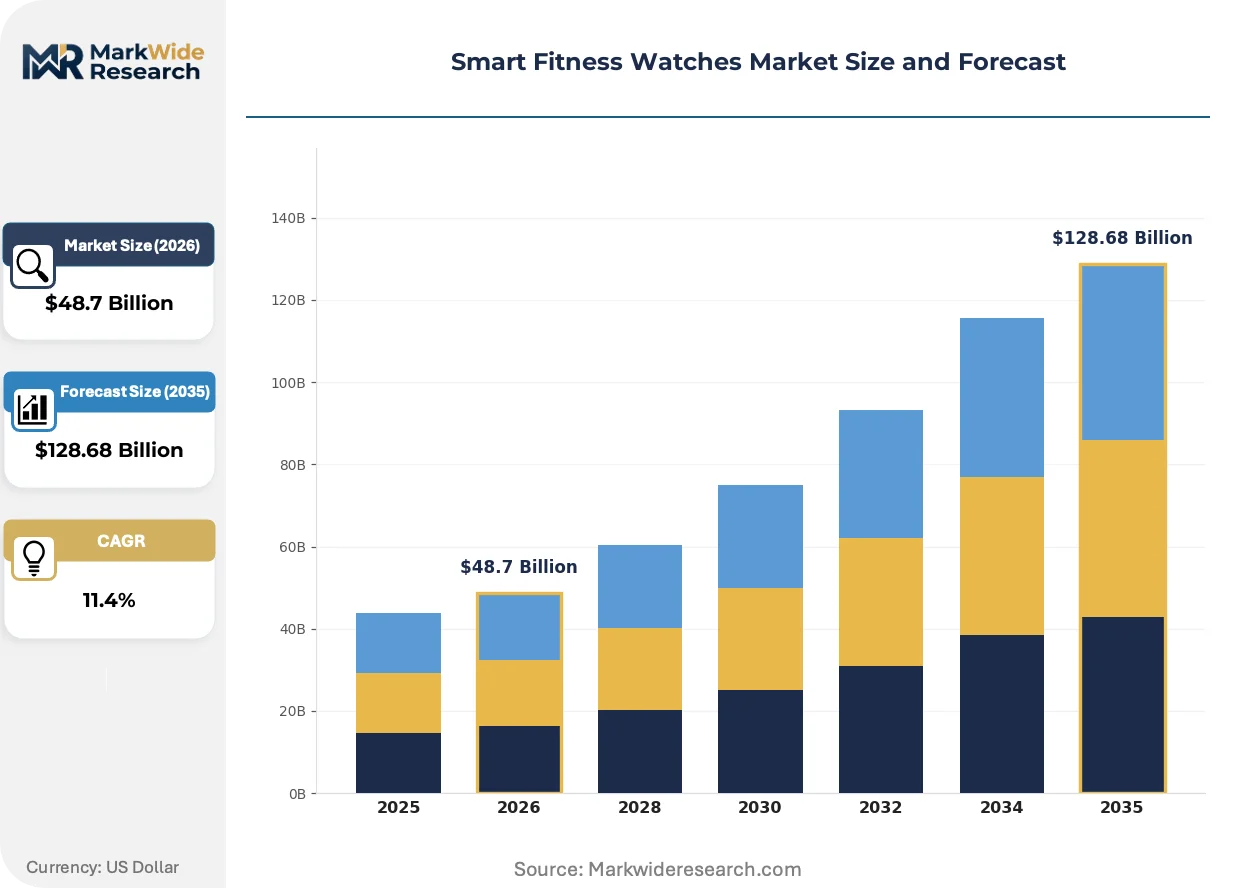
| Market Size in 2026 | $48.7 Billion |
| Market Size in 2035 | $128.68 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Heart Rate Monitors, Activity Trackers, Multisport Watches, Smartwatches Technology: GPS, Bluetooth, Wi-Fi, NFC End User: Athletes, Fitness Enthusiasts, Casual Users, Health-Conscious Individuals Feature: Sleep Tracking, Step Counting, Calorie Monitoring, Heart Rate Monitoring |
| Companies Covered | Apple Inc., Samsung Electronics, Garmin Ltd., Google (Fitbit), Huawei Technologies, Xiaomi Technology, Fossil Group, Polar Electro, Oura Health, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Smart Fitness Watches Market Emerging Trajectories
Sensor fusion architectures and regulatory reclassification are compressing the boundary between consumer electronics and clinical diagnostics, forcing manufacturers to rebuild quality systems and validation protocols.
Solid-state battery chemistry is electrifying power architecture roadmaps for wearable devices. Medical-grade smartwatch programs at Samsung and Apple are piloting silicon-anode cells that double energy density within existing form factors. This shift is compressing charging frequency requirements and enabling multi-day continuous health monitoring previously restricted to dedicated medical patches.
EU MDR Article 10 clinical evidence requirements are reshaping software update practices for health-tracking wearables. Manufacturers must now submit algorithm modifications for notified body review when claims touch cardiac rhythm or blood oxygen diagnostics. Premium-tier vendors are responding by segregating consumer wellness features from regulated diagnostic modes through distinct firmware branches.
Employer self-insurance models are rotating procurement authority from HR departments to benefits consultants with actuarial analytics capabilities. Large enterprise accounts now mandate interoperability with claims data warehouses and predictive risk scoring platforms. This concentration is visible most acutely in the United States, where Fortune 500 wellness contracts increasingly exclude vendors lacking Epic or Cerner-certified data exchange modules.
Smart Fitness Watches Market Segmentation
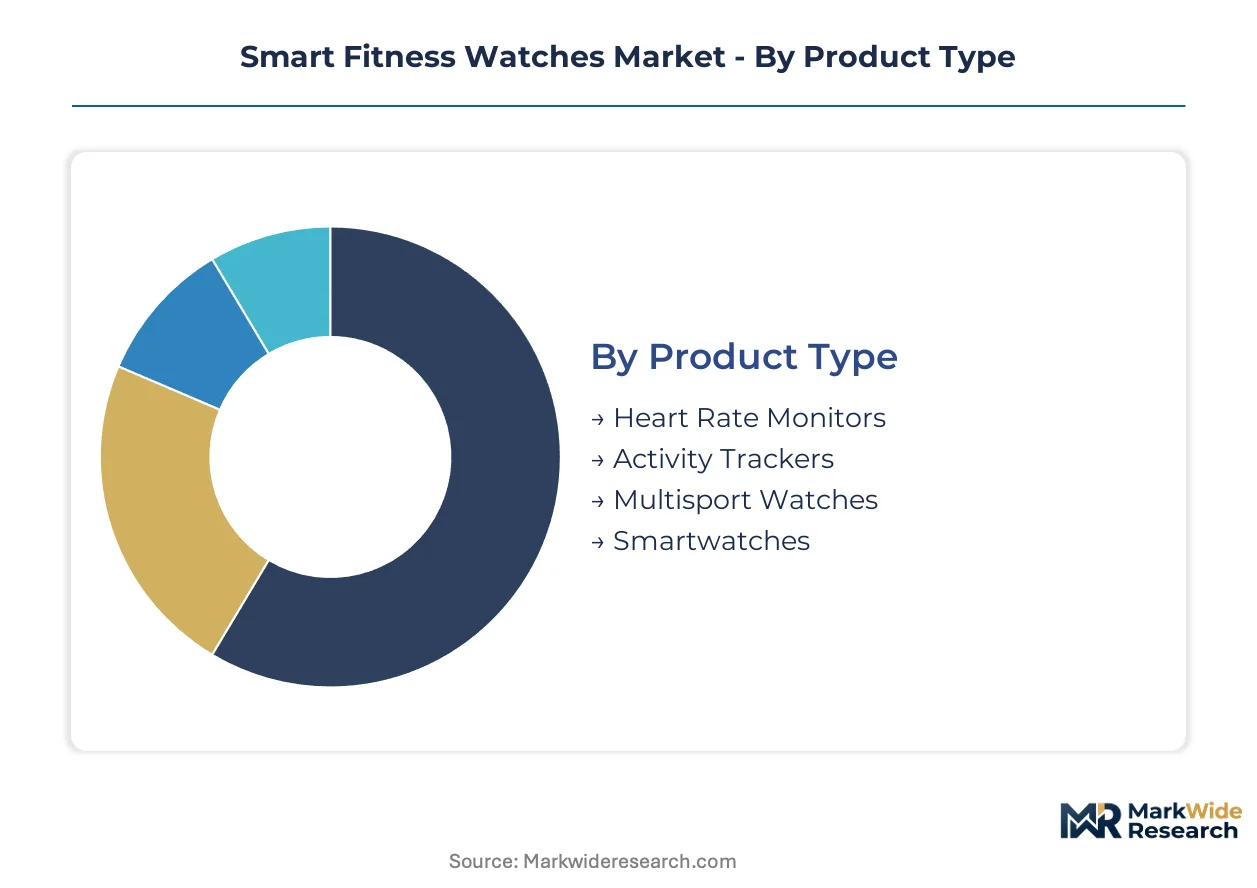
Smart fitness watches segment across functional depth, connectivity architecture, and user sophistication levels. Manufacturers configure sensor arrays, battery capacities, and software stacks differently for each tier, creating distinct margin profiles and replacement cycles.
Product Type:
Standardized hardware platforms dominate entry tiers while premium segments demand customized sensor fusion and extended battery architectures.
- Smartwatches:Full-featured wrist-worn computers integrate ECG electrodes, blood oxygen sensors, and app ecosystems with cellular connectivity. Demand concentrates in corporate wellness procurement channels where IT departments mandate enterprise-grade security certifications and centralized device management APIs.
- Multisport Watches:Specialized GNSS receivers and barometric altimeters deliver route mapping and performance analytics for triathlon and ultramarathon athletes. Garmin dominates this niche through proprietary GPS accuracy algorithms and solar charging extensions that compress battery anxiety in extreme environments.
- Activity Trackers:Stripped-down accelerometer-based devices quantify steps and basic sleep patterns at sub-premium price points.
- Heart Rate Monitors:Chest-strap or optical wrist sensors optimized for zone-based training feedback without full smartwatch functionality.
Leading the category by volume: Activity Trackers. Expanding most quickly: Smartwatches.
Technology:
Connectivity cost tiers separate premium real-time streaming from intermittent sync architectures.
- GPS:Multi-constellation GNSS receivers (GPS, GLONASS, Galileo, BeiDou) enable standalone route tracking without smartphone tethering. Athletes in remote terrain drive demand where cellular dead zones render Bluetooth-dependent devices non-functional.
- Bluetooth:Low-energy 5.3 protocols dominate smartphone pairing for notification relay and data offload. Casual user segments accept this dependency for price compression, while enterprise wellness deployments reject Bluetooth-only architectures for security and continuity risks.
- Wi-Fi:Direct cloud synchronization bypasses smartphone intermediaries for music streaming and software updates.
- NFC:Contactless payment tokenization and transit pass integration anchor convenience features in urban commuter segments.
Widest deployment: Bluetooth. Steepest capability expansion: GPS.
End User:
User sophistication determines sensor accuracy requirements and data interpretation depth.
- Athletes:Demanding users require HRV-derived recovery metrics, lactate threshold estimation, and power meter integration. Training load quantification drives replacement cycles as firmware updates extend hardware lifespans beyond typical consumer electronics obsolescence curves.
- Health-Conscious Individuals:Preventive monitoring adopters prioritize FDA-cleared ECG and blood oxygen features for early arrhythmia detection. Remote patient monitoring pilots through US health systems concentrate procurement in this segment, with reimbursement pathways expanding under CMS remote physiological monitoring codes.
- Fitness Enthusiasts:Regular gym-goers balancing performance tracking with lifestyle convenience.
- Casual Users:Step-counting and notification mirroring without training-specific analytics.
Largest installed base: Casual Users. Gaining share fastest: Health-Conscious Individuals.
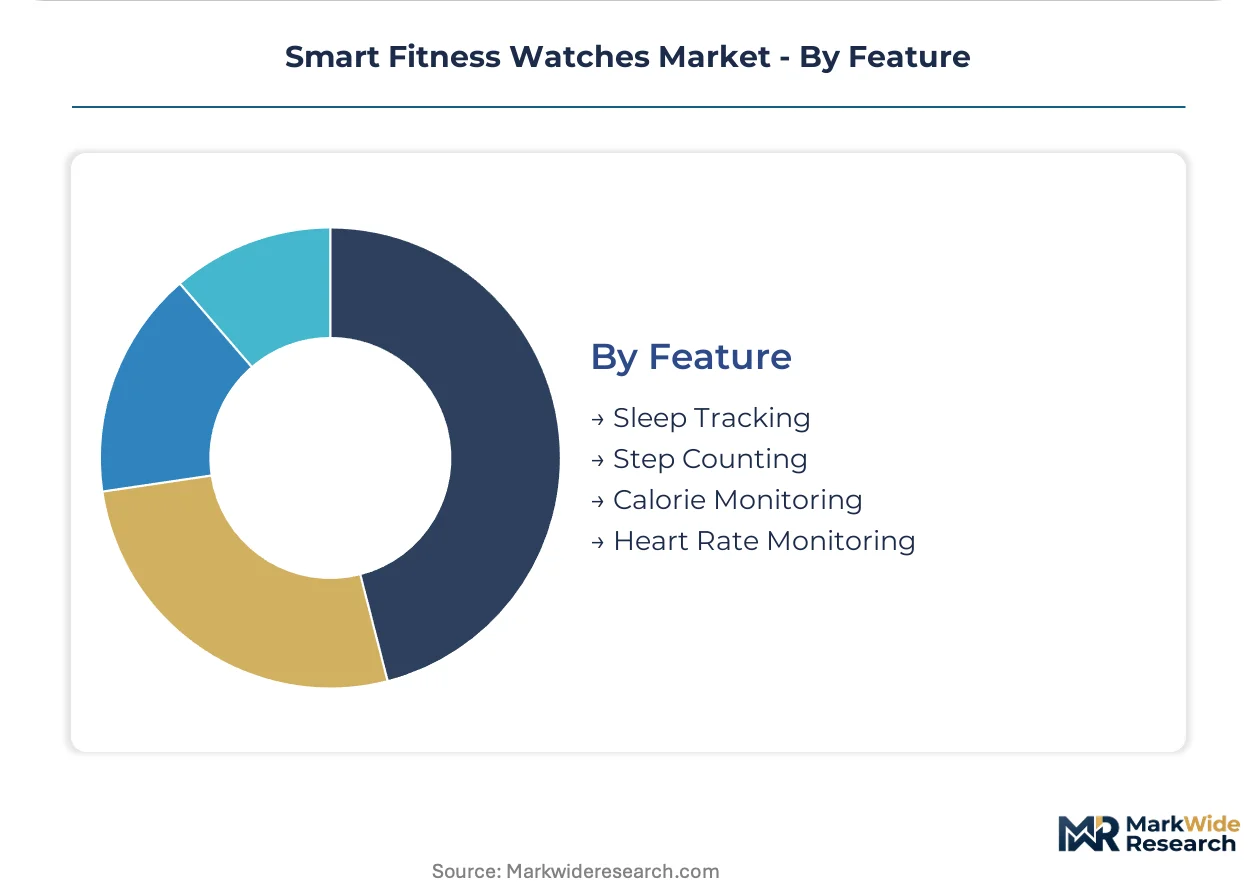
Feature:
Feature bundling strategies balance regulatory burden against differentiation potential.
- Heart Rate Monitoring:Photoplethysmography sensors sampling above 100 Hz enable atrial fibrillation detection that triggers FDA software-as-medical-device classification. Apple and Samsung segregate consumer wellness modes from regulated diagnostic branches to manage CE marking update timelines under EU MDR Article 10.
- Sleep Tracking:Multi-sensor fusion combining accelerometry, heart rate variability, and blood oxygen saturation estimates sleep stages and respiratory disturbance indices. Wellness platform vendors monetize this data through employer contracts tied to productivity and healthcare cost reduction metrics.
- Step Counting:Basic accelerometer functionality with minimal regulatory exposure.
- Calorie Monitoring:Algorithmic expenditure estimation combining heart rate, movement intensity, and user biometrics.
Highest regulatory scrutiny: Heart Rate Monitoring. Fastest platform monetization: Sleep Tracking.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Corporate wellness procurement concentrates in the United States, where Fortune 500 employers mandate centralized device management and health data analytics integration.
United States
FDA software-as-medical-device pathways for ECG and blood oxygen features expand reimbursable remote patient monitoring through CMS codes. The FDA's evolving framework distinguishes wellness claims from diagnostic classifications, compelling manufacturers to maintain dual firmware branches. San Francisco Bay Area health tech clusters anchor algorithm validation partnerships between wearable vendors and Stanford Medicine research programs.
China
Domestic brands leverage Shenzhen component ecosystems to compress production costs and accelerate feature iteration cycles. NMPA medical device registration requirements for diagnostic-grade wearables create compliance barriers for imported competitors. The Yangtze River Delta manufacturing corridor concentrates photoplethysmography sensor assembly and lithium-polymer cell integration for global supply.
Germany
EU MDR Article 10 clinical evidence requirements extend software update approval timelines for cardiac rhythm features. CE marking under GDPR biometric data residency mandates forces redundant cloud infrastructure investments for European enterprise accounts. Bavaria's precision engineering clusters supply GNSS receiver modules and barometric pressure sensors for multisport watch architectures.
India
Corporate health insurance regulations incentivize wearable adoption through premium discount mechanisms, opening volume procurement channels in underpenetrated enterprise segments. BIS certification requirements for electronic imports shape component sourcing strategies for domestic assembly operations. Karnataka's Bengaluru tech corridor hosts wearable platform development centers serving both domestic health app ecosystems and export markets.
Japan
Aging demographics drive preventive health monitoring adoption among health-conscious individuals seeking FDA-cleared arrhythmia detection. PMDA medical device approval pathways for software-as-medical-device claims require localized clinical validation studies. Tokyo-Osaka industrial corridors concentrate compact sensor fusion engineering and low-power semiconductor design for extended battery architectures.
Smart Fitness Watches Market Vendor Landscape
United States producers anchor the premium software-integrated tier; Chinese specialists hold manufacturing scale advantages in component cost compression. The vendor structure stratifies across three tiers: vertically integrated health platform operators, precision GPS multisport specialists, and Shenzhen-based volume manufacturers. Dominant competitive moves include segregating regulated diagnostic firmware from consumer wellness branches and building enterprise API interoperability for corporate wellness procurement.
Within the premium health platform tier, Apple Inc. and Samsung Electronics exemplify vertically integrated software-hardware architectures that sustain corporate contract positioning through centralized device management capabilities. Garmin Ltd. anchors the specialized multisport segment with extended battery and GNSS accuracy differentiation. Chinese volume manufacturers occupy cost-compressed tiers through Shenzhen ecosystem integration and localized health app partnerships.
| Leading Market Players |
|---|
| Apple Inc. |
| Samsung Electronics |
| Garmin Ltd. |
| Google (Fitbit) |
| Huawei Technologies |
| Xiaomi Technology |
| Fossil Group |
| Polar Electro |
| Oura Health |
| Others |
Supply Flow & Price Mechanics
Lithium carbonate spot indices cascading through Shenzhen component ecosystems compress margins for entry-tier activity trackers while elevating premium-tier pricing power for FDA-cleared diagnostic architectures. Buyers in corporate wellness channels absorb cost pass-throughs differently than price-sensitive casual consumers, fragmenting procurement negotiations across enterprise and retail channels.
Pricing Analysis
Volume leadership concentrates in sub-premium activity trackers where Shenzhen ecosystem integration enables aggressive cost compression, while margin pools anchor in GPS-enabled multisport watches and FDA-cleared smartwatches with algorithm-validated health features. Three-tier pricing structure across premium, standard, and economy levels separates enterprise-grade security certifications and API interoperability from consumer wellness modes with basic accelerometry. Pricing pressure stems from bulk procurement consolidation in Fortune 500 wellness programs compressing vendor margins. Casual users exhibit highest price sensitivity, accepting Bluetooth-dependent architectures for cost reduction, while enterprise accounts prioritize continuity and security over unit economics.
Supply Chain Analysis
Single-source vulnerability sits with Taiwan-based semiconductor fabrication for precision GNSS receiver modules, exposing multisport watch manufacturers to geographic concentration risk. Component sourcing draws from China for photoplethysmography sensor assembly and lithium-polymer cell integration, South Korea for low-power semiconductor design, and Japan for compact sensor fusion engineering. Raw material dependencies include lithium carbonate for battery chemistry, rare earth elements for magnetometer components, and specialized optical substrates for heart rate sensors. Tariff exposure on Chinese electronic imports shapes domestic assembly strategies for India and Southeast Asian markets. Distribution runs through carrier retail partnerships for consumer segments and direct enterprise sales with benefits consultants for corporate wellness procurement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Solid-state battery chemistry is displacing lithium-polymer architectures across premium wearable roadmaps, compressing charging frequency requirements and enabling multi-day continuous health monitoring previously restricted to dedicated medical patches.
For Market Incumbents: Anchor algorithm validation capabilities through partnerships with Stanford Medicine and comparable research programs to defend FDA software-as-medical-device positioning against emerging optical glucose sensing entrants. Deepen backward integration into photoplethysmography sensor design to reduce Shenzhen ecosystem dependency and accelerate CE marking timelines under EU MDR Article 10. Prioritize enterprise API interoperability investments targeting Epic and Cerner-certified data exchange modules as procurement authority shifts to benefits consultants with actuarial analytics capabilities. For New Entrants and Emerging Players: Regional health systems in India seeking CMS-equivalent remote physiological monitoring reimbursement pathways represent the most penetrable buyer archetype, given corporate health insurance regulations incentivizing wearable adoption through premium discount mechanisms. Target outcome-based wellness contracts with employer self-insurance models shifting from device subsidies to performance-linked pricing tied to measurable health outcome improvements. Pursue go-to-market partnerships with domestic health app ecosystems in China to bypass NMPA medical device registration barriers for imported competitors. For Investors and Strategic Acquirers: The window for entry favors vertically integrated health platform operators with FDA-cleared diagnostic firmware branches segregated from consumer wellness modes, given EU MDR recertification requirements extending approval cycles for algorithm modifications. Long-term viability hinges on acquisition of biomedical engineering talent pools in signal processing and regulatory science, where hiring bottlenecks constrain clinical-grade feature development. Watch for continuous glucose monitoring convergence approaching clinical validation thresholds as the inflection indicator signaling metabolic monitoring share capture from dedicated CGM devices.| Strategic Initiative | Industry Significance |
|---|---|
| FDA Software-as-Medical-Device Submission | Expands reimbursable remote patient monitoring through CMS codes for algorithm-validated ECG features. |
| EU MDR CE Marking Pathway | Segregates regulated diagnostic firmware from consumer wellness branches to manage update approval timelines. |
| Enterprise API Interoperability Investment | Secures Fortune 500 wellness contracts mandating Epic or Cerner-certified data exchange modules. |
| Solid-State Battery Supply Agreement | Enables silicon-anode cell integration doubling energy density within existing wrist-worn form factors. |
| Corporate Wellness Platform Partnership | Captures outcome-based contracts tied to measurable health improvements and predictive risk scoring. |
Methodological Framework
Document review covered FDA 510(k) premarket notification filings, EU MDR technical documentation, CMS remote physiological monitoring coding guidelines, and SEC 10-K supply chain disclosures, complemented by interviews with wearable platform engineering leads, enterprise benefits consultants, hospital biomedical engineering directors, and GPO contracts managers. Secondary validation drew from NMPA medical device registration databases, BIS certification records, and Shenzhen component ecosystem trade data. Bottom-up demand modeling triangulated against top-down market sizing across the analysis window.
Cross-referencing historical shipment trajectories against expert panel inputs on solid-state battery commercialization timelines and continuous glucose monitoring validation thresholds shaped the analytical framework. Segmentation dimensions modeled include product type tier, connectivity architecture, end-user sophistication level, and regional regulatory cluster. CAGRs were derived through iterative reconciliation of unit economics and replacement cycle assumptions. Industry-specific forecast inputs incorporated photoplethysmography sampling rate advances and GNSS receiver supply concentration vulnerability assessments.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to FDA reclassification decisions distinguishing general wellness from diagnostic claims and to solid-state battery chemistry scale-up timelines. Deviation in EU MDR notified body capacity or Taiwan semiconductor fabrication continuity would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Wearable Fitness Technology
Smart Sports Wearables Market
Wearable Fitness Technology
Global Smart Wearable Fitness and Sports Devices Market
Wearable Fitness Technology
Wearable Patch Market
Wearable Fitness Technology
Body Sensors Market
Wearable Fitness Technology
Global GPS Watch Tracker Market
Wearable Fitness Technology
Wearable Devices Market
Wearable Fitness Technology
Flexible Wearable Device Market
Wearable Fitness Technology
United States Wearable Sensors Market
Wearable Fitness Technology
Swim Watches Market
Wearable Fitness Technology
Smart Sports Bracelet Market
Wearable Fitness Technology
Wearable Band Market
Wearable Fitness Technology
Wearable Motion Sensors Market
Wearable Fitness Technology
Smart Fitness Trackers Market
Wearable Fitness Technology
Pocket Pedometers Market
Wearable Fitness Technology
Fitness Tracker Market
Wearable Fitness Technology
Wearable Devices in Sports Market