
 Japan Power EPC Market | 2026-2036
Japan Power EPC Market Size, Share, and Industry Trends Forecast 2026-2036
Japan Power EPC Market Foresight
Engineering talent scarcity in Japan is bifurcating the contractor landscape between domestic generalists and technology-specific specialists. Toshiba Energy Systems & Solutions Corporation leverages its turbine-generator heritage to dominate thermal retrofit and hydrogen co-firing integration. JFE Technos Co. specializes in steel-intensive superstructure fabrication for offshore wind jackets, anchoring its position in marine-heavy EPC scopes.
Japan Power EPC encompasses the integrated design, equipment sourcing, civil works, and commissioning of electricity generation facilities, typically spanning 500 MW to 2 GW in nameplate capacity with construction cycles of 36 to 60 months. The primary purpose is delivering turnkey generation assets that interconnect to the 50 Hz eastern or 60 Hz western grid frequencies governing Japan's bifurcated power system. Solar Power EPC occupies the largest share of contracted value due to distributed rooftop and utility-scale ground-mount pipelines accumulated under past feed-in tariff regimes, though margin compression here is severe. Offshore Wind Energy EPC represents the fastest-expanding technology segment as Japan's first commercial floating wind projects advance through METI-sponsored demonstration frameworks with specialized marine construction requirements. The Commissioning service phase captures disproportionate margin pools because grid code compliance testing and frequency response validation demand scarce local certification expertise.
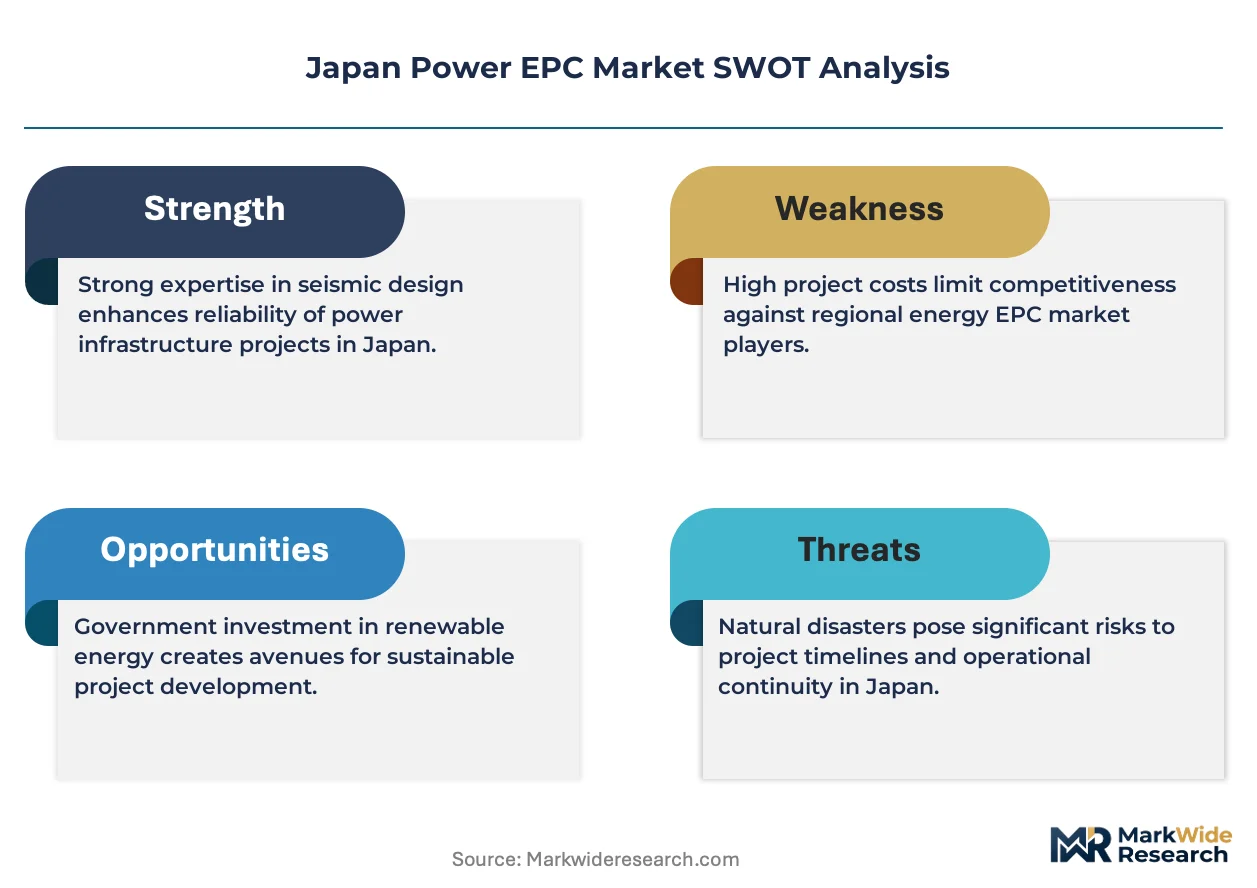
METI's GX League transition rules and the Agency for Natural Resources and Energy's revised grid interconnection standards are forcing EPC contractors to embed carbon accounting and synthetic inertia capability into plant designs from the front-end engineering phase. JIS standards for seismic resistance and the country's nuclear regulator-derived quality assurance culture create steep compliance barriers for foreign entrants lacking localized engineering subsidiaries. Stakeholders must monitor METI's forthcoming offshore wind auction design and regional utility unbundling timelines to calibrate whether to build captive marine construction capacity or pursue consortium structures with European offshore specialists.
Market Dynamics
METI's GX League transition rules are forcing contractors to embed carbon accounting and synthetic inertia capability into front-end engineering designs, redirecting procurement priorities toward grid-stabilization-ready turnkey packages.
Growth Catalysts
- Feed-in Tariff Successor Mechanism:METI's revised procurement framework redirects utility capital toward renewable baseload projects with firm power commitments, accelerating integrated EPC package demand.
- Offshore Wind Lease Rounds:Kyushu and Hokkaido marine zones overlapping transmission expansion corridors concentrate developer interest in floating foundation and subsea cable installation contracts.
- Grid Code Revisions:The Agency for Natural Resources and Energy's interconnection standards mandate frequency response validation, expanding commissioning-phase service scopes for local certification holders.
Market Restraints
- Engineering Talent Scarcity:Domestic turbine-generator specialists and marine steel fabricators face recruitment bottlenecks for seismic-resistant design expertise.
- JIS Compliance Barriers:Foreign entrants lacking localized engineering subsidiaries cannot navigate nuclear regulator-derived quality assurance protocols for pressure vessel welding certification.
- 50 Hz / 60 Hz Bifurcation:Japan's split-frequency grid forces equipment duplication and specialized commissioning protocols that inflate project mobilization costs.
Strategic Opportunities
- Hokkaido Geothermal Zones:Untapped high-temperature resource areas adjacent to existing transmission infrastructure offer brownfield expansion potential for binary cycle plant contractors.
- Hydrogen Co-firing Integration:Ammonia combustion retrofits at existing thermal sites create aftermarket EPC scopes for turbine modification and fuel handling system installation.
- Consortium Structures with European Specialists:Joint ventures combining Japanese seismic engineering with North Sea offshore construction expertise unlock floating wind demonstration frameworks.
Industry Challenges
- Seismic Certification Timelines:JIS-compliant structural validation for turbine foundations extends front-end engineering phases by eight to fourteen months.
- Marine Construction Capacity Constraints:Domestic heavy-lift vessel availability limits simultaneous project execution across multiple offshore wind sites.
- Legacy Thermal Asset Stranding:Regional utility unbundling timelines create uncertainty around retrofit versus decommissioning decisions for coal-fired units.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Japan Power EPC Market |
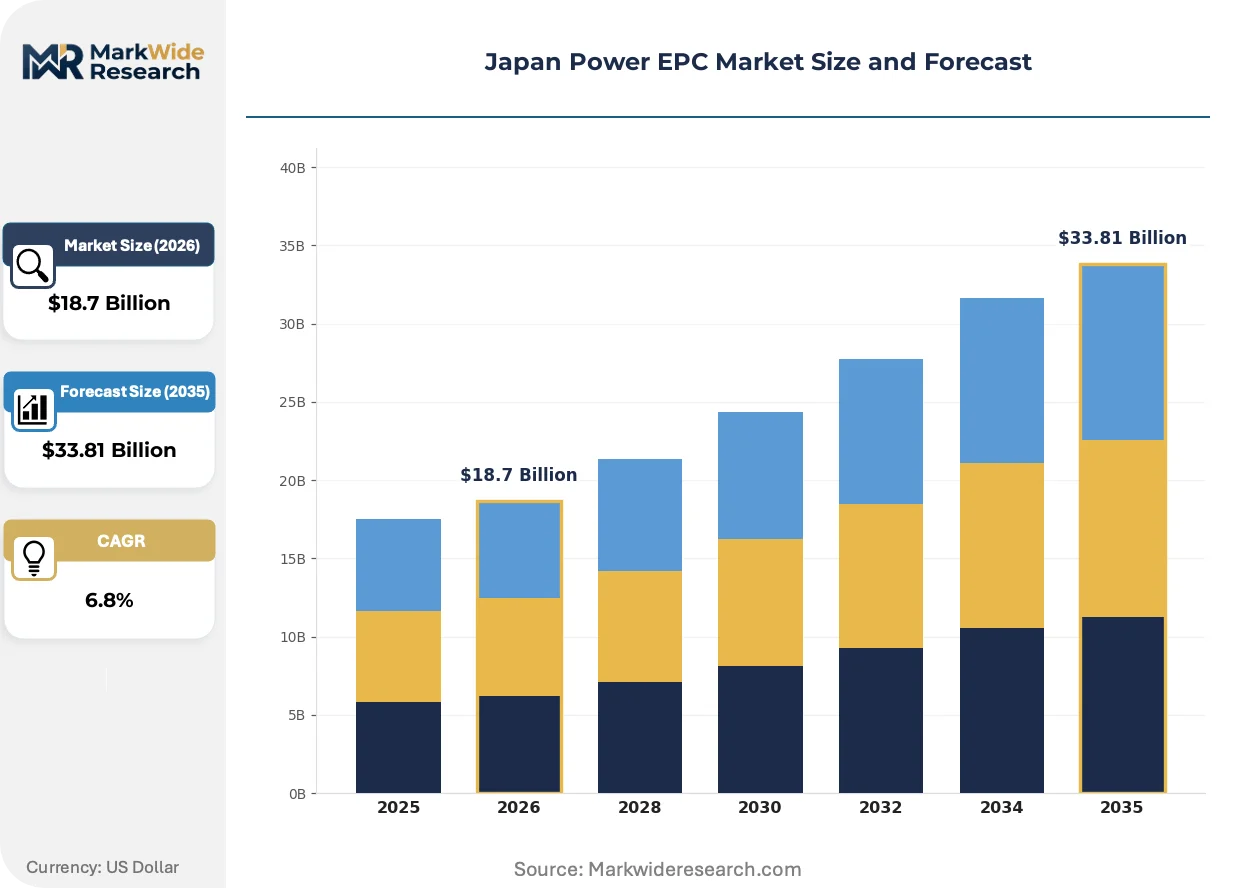
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $33.81 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Engineering, Procurement, Construction, Commissioning Technology: Wind Energy, Solar Power, Hydropower, Thermal Energy End User: Utilities, Independent Power Producers, Government, Industrial Installation: Onshore, Offshore, Grid-Connected, Off-Grid |
| Companies Covered | SHIZEN ENERGY Inc., Kansai Electric Power Co. Inc., Toshiba Energy Systems & Solutions Corporation, Pacifico Energy K.K., Marubeni Corporation, JUWI GmbH, Electric Power Development Co.,Ltd., JFE Technos Co., Sumitomo Corporation, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Japan Power EPC Market Shifts & Advancements
Floating offshore wind foundation technology is disrupting marine construction norms, while METI's carbon accounting mandates reshape contractor design obligations and procurement models favor integrated performance guarantees over discrete component sourcing.
Concrete-steel hybrid substructures for floating wind platforms are bifurcating the marine EPC contractor base. Japanese steel fabricators with jacket heritage dominate steel-intensive spar and semi-submersible designs. Concrete specialists from dam and bridge construction are entering tension-leg platform markets. The technology split is compressing margins for generalist marine contractors lacking depth in either material system.
METI's revised grid interconnection standards now mandate synthetic inertia capability verification before commercial operation date approval. Battery energy storage system integrators must coordinate with generator OEMs on frequency response testing protocols. Thermal retrofit and greenfield renewable projects in western Japan's 60 Hz zone face accelerated compliance timelines compared to eastern counterparts.
Utility procurement departments are consolidating equipment sourcing under single EPC accountability structures, displacing multi-contractor engineering-procurement splits. Regional utilities in Kyushu now require contractors to assume grid code compliance risk through commissioning-phase performance guarantees. This concentration of liability favors contractors with captive commissioning expertise and localized certification relationships.
Japan Power EPC Market Segmentation
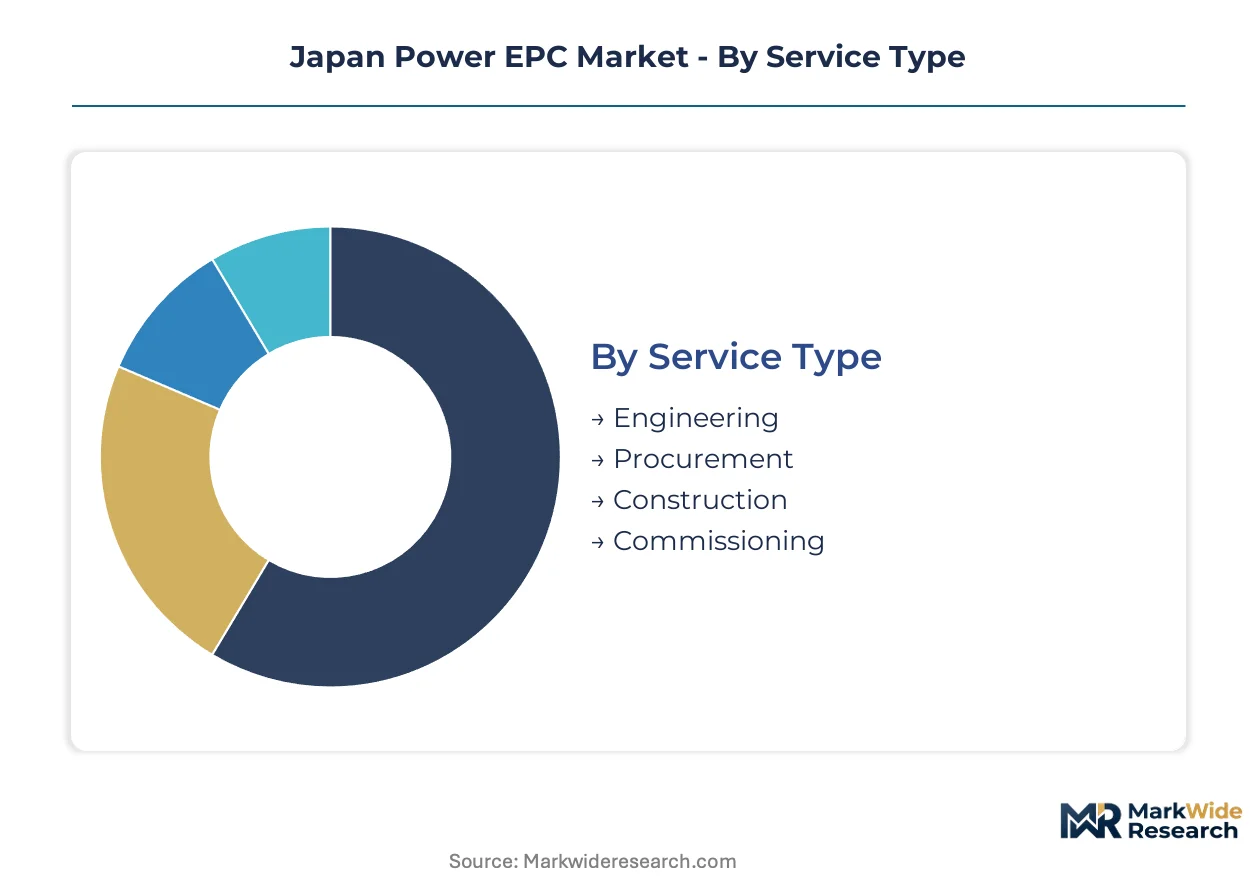
Japan Power EPC contractors must align capabilities with distinct technical requirements across service phases, generation technologies, and installation environments. Each segment imposes specialized compliance burdens ranging from JIS seismic certification to METI grid code validation.
Service Type:
Kyushu and Hokkaido project pipelines concentrate procurement for integrated packages, while discrete engineering and construction contracts persist in legacy thermal retrofits.
- Engineering:Front-end design scopes span 50 Hz and 60 Hz grid frequency specifications, with seismic-resistant foundation modeling consuming extended validation cycles. METI's synthetic inertia mandates now embed carbon accounting and frequency response capability into preliminary plant configurations.
- Procurement:Equipment sourcing consolidates under single-accountability EPC structures as regional utilities disaggregate multi-contractor splits. Long-lead turbine-generator sets and floating wind substructures dominate contracted value.
- Construction:Civil works capacity concentrates with domestic steel fabricators holding marine construction heritage for offshore wind jackets.
- Commissioning:Grid code compliance testing and frequency response validation command premium margins through scarce local certification expertise.
Engineering commands the established base. The steepest expansion runs through Commissioning.
Technology:
Cost tier stratification separates mature, margin-compressed segments from capital-intensive emerging categories requiring specialized marine or geothermal construction capabilities.
- Wind Energy:Floating offshore foundation technology disrupts marine construction norms with concrete-steel hybrid substructures. Kyushu and Hokkaido lease rounds concentrate developer interest where transmission expansion corridors overlap marine zones.
- Solar Power:Distributed rooftop and utility-scale ground-mount pipelines accumulated under past feed-in tariff regimes retain the largest contracted value share. Severe margin compression now displaces generalist contractors toward technology-specific specialists.
- Hydropower:Run-of-river and pumped-storage retrofits leverage existing civil infrastructure.
- Thermal Energy:Ammonia and hydrogen co-firing retrofits at existing sites create aftermarket scopes for turbine modification and fuel handling system installation.
Solar Power retains volume leadership. Wind Energy climbs the fastest as floating demonstration frameworks advance.
End User:
Customer type determines risk allocation structures, with utility unbundling timelines creating uncertainty around captive versus competitive procurement channels.
- Utilities:Regional power companies expanding renewable baseload procurement under METI's feed-in tariff successor mechanism. Integrated EPC packages with performance guarantees now displace discrete component sourcing.
- Independent Power Producers:Non-utility developers concentrate in offshore wind demonstration frameworks and distributed solar pipelines.
- Government:Public-sector procurement anchors geothermal resource development in Hokkaido high-temperature zones.
- Industrial:Captive power consumers pursue on-site solar and hydrogen co-firing for GX League transition compliance.
Utilities anchor procurement volume. Independent Power Producers gain share fastest through offshore wind development rights.
Installation:
Geography and grid connection status dictate equipment specifications, with bifurcated frequency standards and marine construction requirements fragmenting contractor specialization.
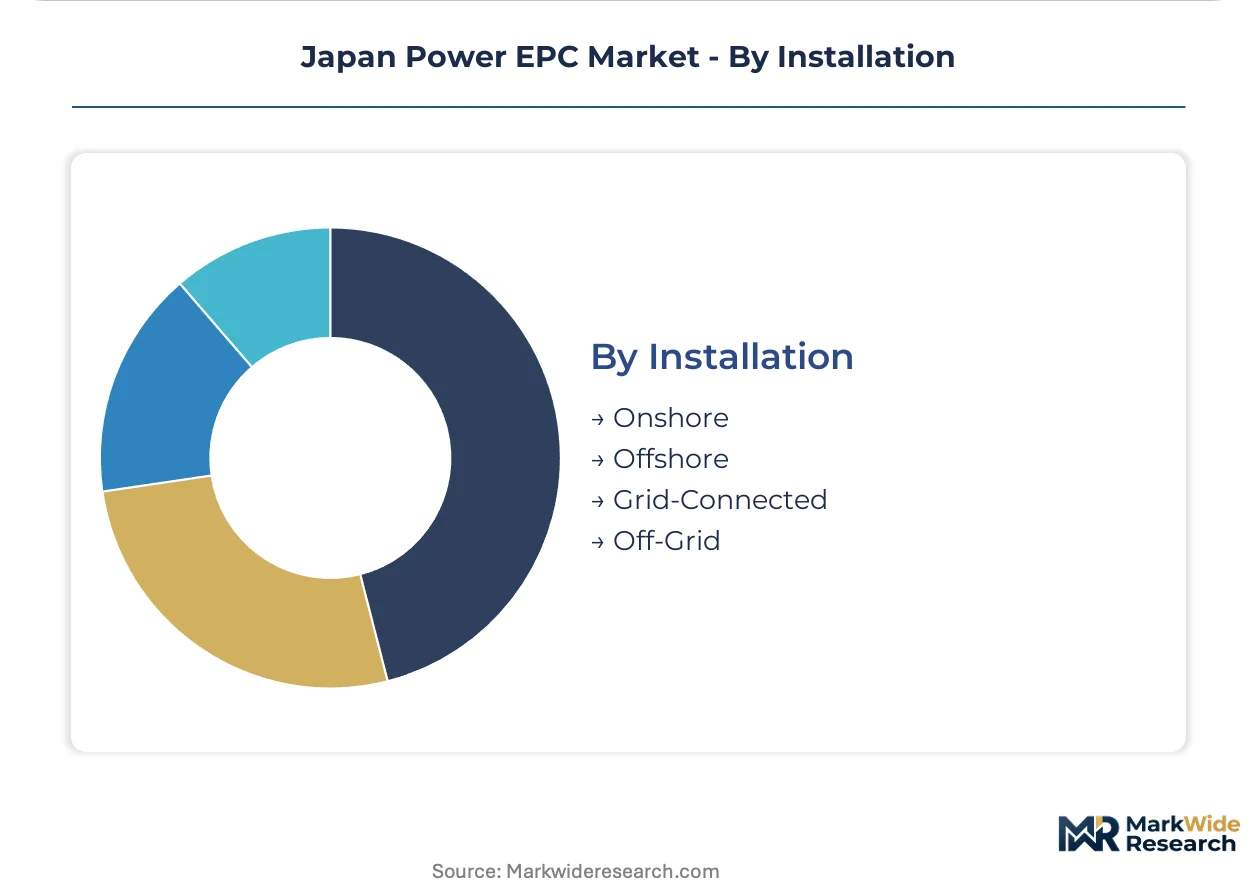
- Onshore:Ground-mount solar and geothermal binary cycle plants dominate civil works scopes. Seismic-resistant foundation design extends front-end engineering timelines.
- Offshore:Floating wind platforms require specialized marine construction capacity constrained by domestic heavy-lift vessel availability.
- Grid-Connected:Interconnection to 50 Hz eastern or 60 Hz western grids forces equipment duplication and specialized commissioning protocols.
- Off-Grid:Remote industrial and island applications concentrate in Hokkaido and southern archipelago zones.
Grid-Connected installations command the established base. Offshore scopes expand most quickly as demonstration frameworks commercialize.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Kyushu commands pricing power in floating wind marine construction while Hokkaido geothermal zones lag on contractor availability, creating a regional asymmetry that shapes procurement timelines and cost structures across Japan's bifurcated power grid.
Kanto/Tokyo
Metropolitan demand centers anchor procurement for hydrogen co-firing retrofits and grid-stabilization battery integration. METI's GX League transition rules mandate synthetic inertia verification for all new interconnection requests. Chiba and Kanagawa industrial corridors concentrate EPC contractor headquarters and certification laboratory capacity.
Kansai/Osaka
Osaka-based utilities drive ammonia combustion retrofit scopes at legacy thermal sites under the feed-in tariff successor mechanism. The 60 Hz western grid frequency forces specialized equipment sourcing distinct from eastern counterparts. Hyogo and Wakayama prefectures host steel fabricators with pressure vessel welding heritage.
Kyushu
Offshore wind lease rounds in Nagasaki and Saga prefectures concentrate floating foundation demand where transmission expansion corridors reach marine zones. Domestic heavy-lift vessel scarcity limits simultaneous project execution across multiple sites. Local contractors with marine construction heritage command premium pricing for jacket fabrication.
Hokkaido
Untapped high-temperature geothermal resources in the Toyako and Mori districts offer brownfield expansion potential for binary cycle plant contractors. The national government's resource development subsidies anchor public-sector procurement pipelines. Tomakomai and Muroran industrial zones concentrate steel-intensive fabrication capacity for remote project logistics.
Chubu/Nagoya
Nagoya's manufacturing base sustains demand for captive power hydrogen integration and on-site solar deployment. Aichi prefecture's industrial GX League compliance timelines accelerate EPC procurement for fuel handling system installation. Local engineering subsidiaries navigate JIS seismic certification protocols for turbine foundation design.
Japan Power EPC Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes, with turbine-generator specialists commanding premium margins in thermal retrofits while steel fabricators compete on marine construction scale. The contractor base splits between domestic generalists with seismic engineering heritage and technology-specific specialists with offshore wind or geothermal depth. Three archetypes dominate: integrated EPC houses with captive commissioning expertise, marine-heavy fabricators with jacket construction heritage, and hydrogen co-firing specialists with turbine modification capabilities. Competitive moves concentrate on consortium structures with European offshore partners and backward integration into long-lead equipment sourcing.
Among domestic integrated EPC providers, Toshiba Energy Systems & Solutions Corporation and JFE Technos Co. exemplify divergent specialization paths. Toshiba anchors the thermal retrofit and hydrogen co-firing integration tier through turbine-generator heritage, while JFE Technos occupies the marine-heavy steel fabrication position for offshore wind jackets. Kansai Electric Power Co. Inc. represents the utility-affiliated contractor archetype with captive grid interconnection relationships. These three entities illustrate how seismic certification capabilities and localized METI regulatory relationships determine competitive positioning in a market where foreign entrants face JIS compliance barriers.
| Leading Market Players |
|---|
| SHIZEN ENERGY Inc. |
| Kansai Electric Power Co. Inc. |
| Toshiba Energy Systems & Solutions Corporation |
| Pacifico Energy K.K. |
| Marubeni Corporation |
| JUWI GmbH |
| Electric Power Development Co.,Ltd. |
| JFE Technos Co. |
| Sumitomo Corporation |
| Others |
Supply & Pricing Matrix
Ammonia fuel substitution for coal at legacy thermal sites simultaneously relocates procurement gravity toward turbine-modification specialists and compresses margins for conventional boiler contractors. METI's GX League carbon accounting mandates force EPC providers to embed synthetic inertia capability into front-end designs, elevating commissioning-phase premiums while squeezing construction-phase returns.
Pricing Analysis
Kyushu offshore wind contracts command 15-25% premiums over Kansai thermal retrofits due to marine construction capacity scarcity and floating foundation complexity. Project-based pricing dominates, with differentiation driven by JIS seismic certification tier and captive grid-interconnection relationships. Cost compression in utility-scale solar EPC intensifies as feed-in-tariff pipeline saturation displaces generalist contractors. Regional utilities exhibit lowest price sensitivity due to regulatory compliance risk transfer requirements, while independent power producers face acute margin pressure in competitive lease rounds.
Supply Chain Analysis
Japan and South Korea anchor turbine-generator set fabrication, while European specialists dominate floating wind foundation engineering. Long-lead equipment procurement draws from domestic steel fabricators for jackets and German-Danish consortiums for tension-leg platform designs. Single-source vulnerability concentrates in heavy-lift vessel availability for marine installation windows. Distribution runs through utility-affiliated EPC houses with captive METI certification relationships, displacing multi-contractor splits.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Floating offshore wind commercialization under METI demonstration frameworks creates a high-growth disruption, with synthetic inertia mandates forcing fundamental redesign of contractor capability stacks.
For Market Incumbents: Consolidate captive commissioning expertise through certification laboratory acquisition, defending against European offshore specialists entering via joint venture structures. Deepen backward integration into long-lead turbine-generator sourcing to offset margin compression in construction-phase scopes. For New Entrants and Emerging Players: Commissioning service gaps where domestic generalists lack frequency response validation capability offer immediate white-space entry. Target Hokkaido geothermal binary cycle segments where contractor availability lags resource development subsidies. Pursue METI grid code compliance partnerships as the primary go-to-market angle. For Investors and Strategic Acquirers: Secondary-cycle assets sit with steel fabricators holding marine construction heritage but lacking floating wind technology depth. Five-to-ten year viability hinges on successful consortium structuring with North Sea specialists. Watch METI's offshore wind auction design as the signal for captive capacity buildout versus asset-light partnering strategies.| Strategic Initiative | Industry Significance |
|---|---|
| Marine Construction Capacity Buildout | Domestic heavy-lift vessel acquisition unlocks simultaneous Kyushu and Hokkaido project execution. |
| Grid Code Compliance Partnership | METI certification relationships transfer interconnection risk from utilities to EPC contractors. |
| Hydrogen Co-firing Technology Licensing | Turbine modification IP from European OEMs enables ammonia combustion retrofit scopes. |
| Backward Integration into Steel Fabrication | Captive jacket production secures margin pools in floating foundation marine EPC. |
| Joint Venture with European Offshore Specialists | North Sea construction expertise combined with JIS seismic heritage wins demonstration frameworks. |
Research Methodology
Cross-validation between utility procurement officer interviews and METI regulatory filing analysis anchors the qualitative findings. Primary fieldwork engaged EPC project directors, regional utility planning officers, IPP development leads, and marine construction subcontractors. Secondary sources encompassed Electric Power Development Co project disclosures, Agency for Natural Resources and Energy grid interconnection standards, and Japan Shipowners' Association vessel deployment records. Bottom-up project pipeline aggregation triangulates against top-down utility capital expenditure tracking.
Sensitivity analysis across synthetic inertia mandate timing and offshore wind auction velocity frames projection uncertainty. The analytical framework segments by service phase, generation technology, end-user type, and grid frequency zone throughout the forecast period. CAGRs derive from utility procurement volume trajectories under feed-in tariff successor mechanisms and marine construction capacity expansion curves. Forecast inputs incorporate METI GX League compliance timelines and regional utility unbundling progression.
Underlying assumptions cover sustained METI policy continuity and domestic engineering talent availability, with deviation risk concentrated in offshore wind lease round timing and European specialist market entry velocity. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Power Equipment
Australia Power EPC Market
Power Equipment
Air Preheater Market
Power Equipment
Equatorial Guinea Power EPC Market
Power Equipment
Global Transformerless UPS Market
Power Equipment
North America Exhaust Heat Recovery System Market
Power Equipment
North America Power Plant Boiler Market
Power Equipment
Submarine Power Cable Market
Power Equipment
France Power EPC Market
Power Equipment
Cogeneration Equipment Market
Power Equipment
Power Generation Equipment MRO Market
Power Equipment
Gas Fixed Power Capacitors Sales Market
Power Equipment
Europe Power Rental Market
Power Equipment
Global Medium Voltage AC Drives Market
Power Equipment
Industrial Power Transmission Drive Belts Market
Power Equipment
Wind Turbine Components Market
Power Equipment
Magnetic Bearing Market