
 Wind Turbine Maintenance Market | 2026-2036
Wind Turbine Maintenance Market Size, Share, and Industry Trends Forecast 2026-2036
Wind Turbine Maintenance Market Outlook
Predictive maintenance subscriptions is hardening into the dominant commercial model across the wind turbine maintenance sector. Deutsche Windtechnik AG leverages its independent service provider status to compete for multi-year contracts outside OEM captive networks. Vestas Wind Systems A/S anchors its aftermarket position through integrated digital platforms that extend turbine life cycles. Siemens Gamesa Renewable Energy specializes in offshore service vessels and technician deployment for harsh marine environments.
Wind turbine maintenance encompasses scheduled inspections, component replacement, lubrication systems management, and blade repair for horizontal-axis units typically rated above 1 MW, ensuring continuous power generation and structural integrity across 20-25 year asset lifespans. Preventive maintenance commands the largest service spend as operators prioritize gearbox and generator reliability to minimize unplanned downtime. Predictive maintenance, powered by condition monitoring and data analytics, represents the fastest-expanding segment as vibration sensors and SCADA integration enable failure forecasting weeks in advance.
Germany's Federal Maritime and Hydrographic Agency (BSH) enforces strict offshore turbine certification protocols, while the EU Green Deal's renewable targets accelerate fleet expansion and corresponding service obligations. The International Electrotechnical Commission (IEC) 61400 series defines turbine design and maintenance standards that shape warranty terms and insurer requirements across European markets. Stakeholders must weigh captive OEM service agreements against independent provider flexibility as turbine fleets age beyond original warranty periods and major component replacement cycles intensify.
Market Dynamics
The transition from corrective to predictive maintenance is compressing service contract structures across European wind fleets. Operators now demand condition-based pricing tied to turbine availability guarantees rather than fixed scheduled fees.
Growth Catalysts
- EU Green Deal renewable targets:Binding national commitments for offshore capacity expansion in Germany, Denmark, and the Netherlands generate multi-year service obligations for new turbine installations.
- SCADA-integrated vibration monitoring:Real-time sensor networks enable failure forecasting that reduces unplanned downtime and extends gearbox replacement intervals.
- Aging onshore fleets in Northern Germany:Turbines installed during the 2000-2010 expansion wave require major component overhauls and blade refurbishment.
Market Restraints
- Specialized technician scarcity:Offshore certification requirements under Germany's BSH standards limit qualified labor supply and inflate wage costs for marine-accessible sites.
- Component lead time volatility:Gearbox and main bearing procurement from concentrated European foundries creates inventory risk for independent service providers.
- IEC 61400-4 gearbox standard revisions:Updated certification protocols force premature documentation upgrades for legacy fleet maintenance records.
Strategic Opportunities
- Polish and Baltic offshore development:Estonia, Latvia, and Poland are licensing initial commercial wind zones without established OEM service infrastructure.
- Drone-based blade inspection:Automated thermography and LiDAR scanning reduce rope-access dependency and cut inspection cycle times.
- EU taxonomy-aligned green financing:Sustainability-linked loans incentivize predictive maintenance adoption through reduced carbon intensity metrics.
Industry Challenges
- Multibrand turbine fleet complexity:Independent providers must maintain proprietary tooling and software licenses across Vestas, Siemens Gamesa, and Enercon control systems.
- Offshore logistics coordination:Vessel charter availability and port access restrictions compress weather-window utilization rates.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Wind Turbine Maintenance Market |
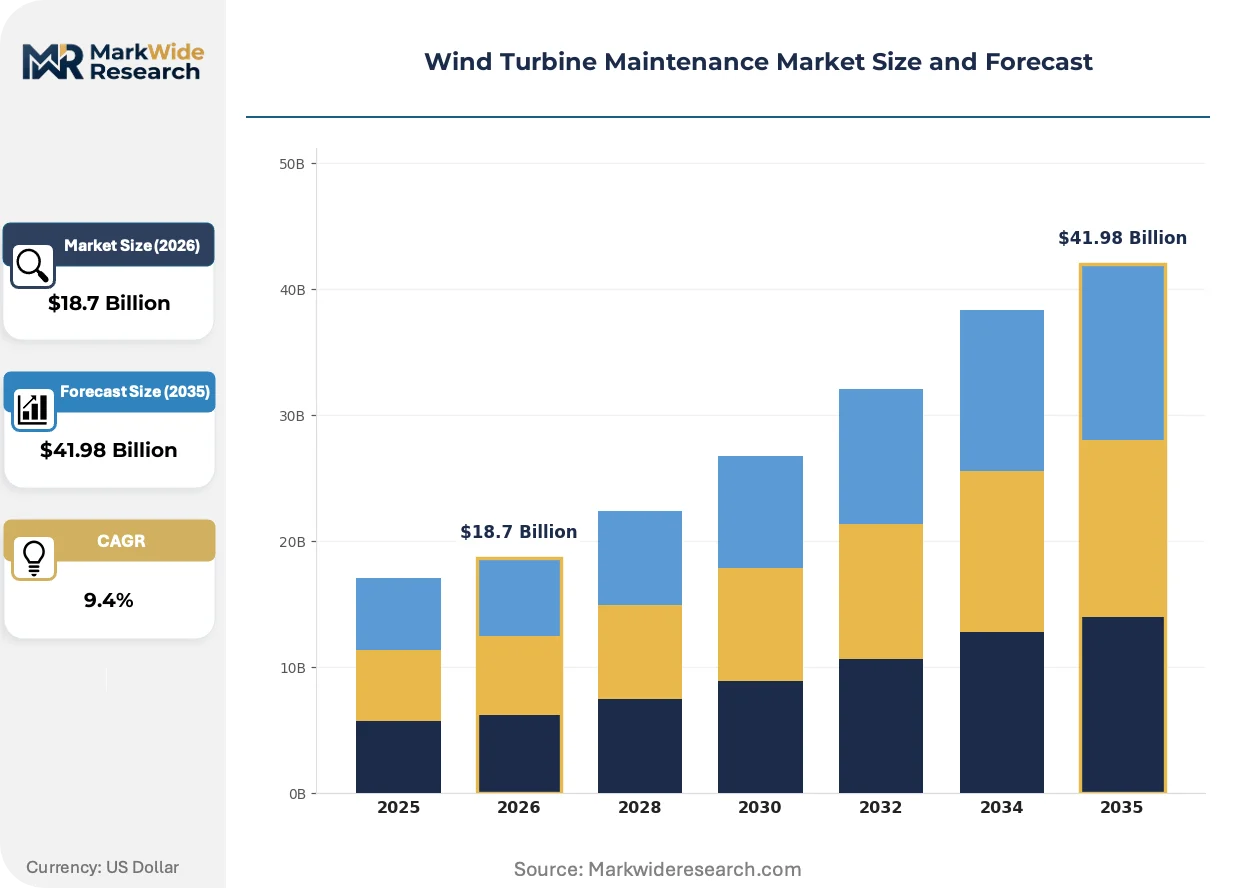
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $41.98 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Corrective Maintenance, Predictive Maintenance, Preventive Maintenance, Upgrades Application: Onshore, Offshore, Repowering, New Installation Technology: Condition Monitoring, Drones, Data Analytics, Robotics End User: Utilities, Independent Power Producers, Developers, Asset Managers |
| Companies Covered | Nordex SE, Deutsche Windtechnik AG, Vestas Wind Systems A/S, ABO Energy, Goldwind, Siemens Gamesa Renewable Energy, Suzlon Energy, REETEC GmbH, General Electric, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Wind Turbine Maintenance Market Strategic Shifts
Digital twin technology is compressing the feedback loop between field performance and engineering design. Maintenance providers now embed physics-based degradation models into operational decision systems.
Digital twin platforms aggregate SCADA streams, vibration spectra, and weather data into unified asset models. Offshore operators in the North Sea deploy these systems to optimize crane vessel scheduling around predicted component failures. The technology is rewriting how availability guarantees are priced and underwritten across long-term service agreements.
Germany's BImSchG emissions framework tightens turbine reliability standards through mandatory reporting of unplanned outages. Operators must document root-cause analyses for grid-disconnect events exceeding four hours. The regulation is forcing maintenance contractors to integrate environmental compliance modules into standard service protocols.
Asset owners are unbundling aftermarket services from original equipment warranties. Large Danish and German utilities now tender gearbox refurbishment and blade repair separately from turbine supply contracts. This pattern concentrates procurement authority with technical asset management teams rather than project development divisions.
Wind Turbine Maintenance Market Segmentation
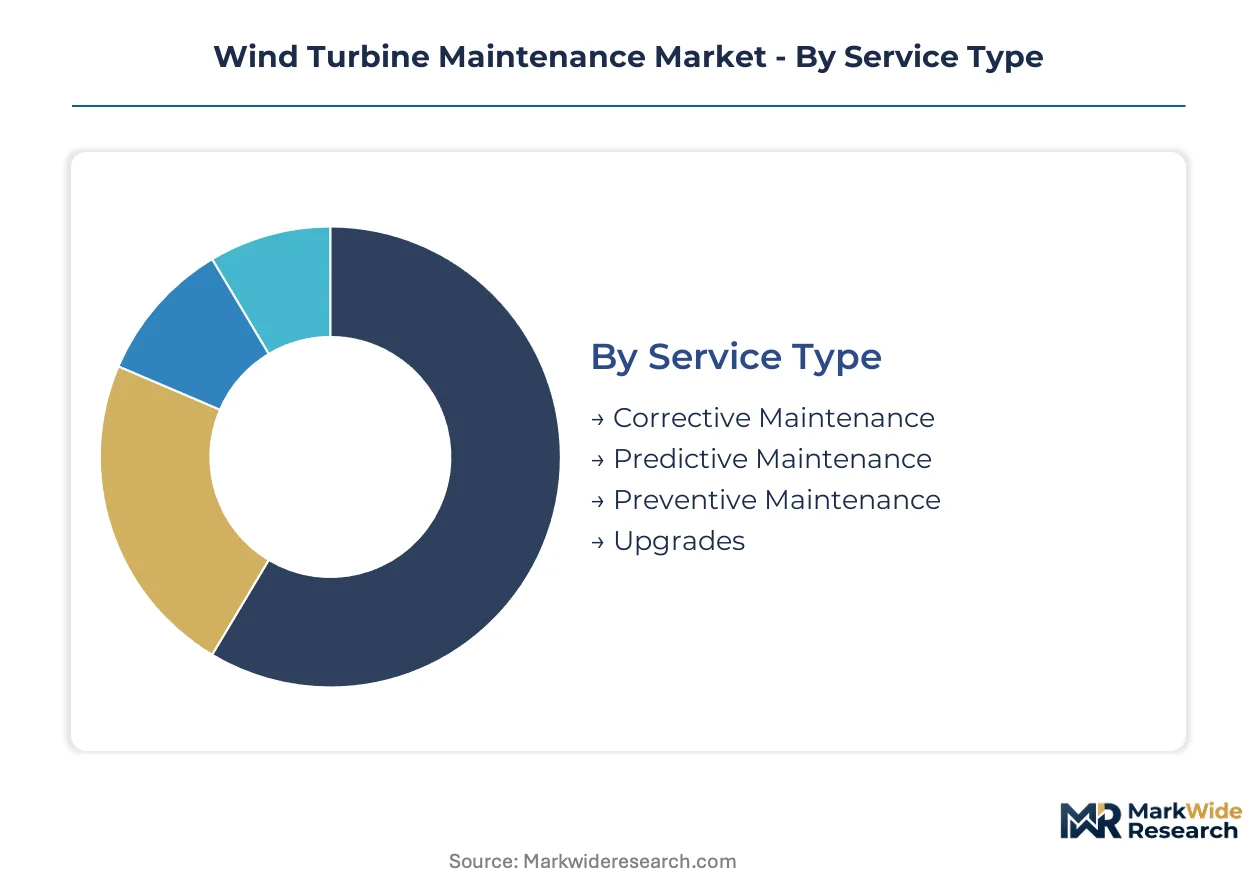
Maintenance service models diverge sharply in capital requirements and contract structures across European wind fleets. Predictive technologies command premium pricing while legacy corrective approaches face margin compression as turbine fleets age.
Service Type:
Capital intensity varies dramatically across service models, with infrastructure-heavy predictive systems requiring sensor networks and data platforms versus labor-driven corrective responses.
- Preventive Maintenance:Scheduled inspections, lubrication cycles, and component replacements executed at fixed intervals regardless of actual condition. German and Danish operators prioritize this model for aging onshore fleets where gearbox reliability dominates availability metrics.
- Predictive Maintenance:Condition-based interventions triggered by SCADA-integrated vibration monitoring and failure forecasting algorithms. North Sea offshore installations absorb the highest deployment rates as weather-window constraints amplify the value of pre-failure scheduling.
- Corrective Maintenance:Unplanned repairs following component failure or performance degradation. Emergency gearbox replacements and generator rewinds fall under this category.
- Upgrades:Control system retrofits, aerodynamic enhancements, and capacity factor improvements extending asset economic life.
Preventive maintenance absorbs the bulk of installed capacity; predictive maintenance is expanding most quickly.
Application:
Site accessibility and logistics infrastructure determine service cost structures and contract duration preferences across deployment environments.
- Onshore:Ground-accessible turbines requiring routine ground-based inspections and crane mobilization for major component exchanges. Northern Germany's aging 2000-2010 installation wave drives replacement demand.
- Offshore:Marine-accessible installations demanding specialized service vessels and helicopter logistics. Baltic Sea projects in Estonian and Polish waters lack established service infrastructure.
- Repowering:Decommissioning and replacement of legacy turbines with modern higher-capacity units. Denmark leads European repowering activity.
- New Installation:Warranty-period maintenance bundled with turbine supply contracts. EU Green Deal capacity targets sustain this segment.
Onshore deployments retain the largest service footprint; offshore applications show the steepest expansion trajectory.
Technology:
Digital tool adoption separates premium service providers from commodity maintenance contractors in competitive tendering.
- Condition Monitoring:Vibration sensors, oil particle counters, and thermal imaging systems tracking component health. Real-time data streams enable failure forecasting weeks in advance.
- Data Analytics:Machine learning models processing SCADA histories to optimize maintenance scheduling and spare parts inventory. German utilities deploy these platforms across multibrand fleets.
- Drones:Automated aerial systems conducting blade inspections via thermography and LiDAR scanning. Rope-access reduction cuts inspection cycle times significantly.
- Robotics:Climbing platforms and remotely operated vehicles executing blade leading-edge repair and offshore subsea cable inspection.
Condition monitoring claims the deepest installed base; drone systems are climbing the fastest.
End User:
Procurement authority concentration shapes contract negotiation leverage and service unbundling trends across ownership structures.
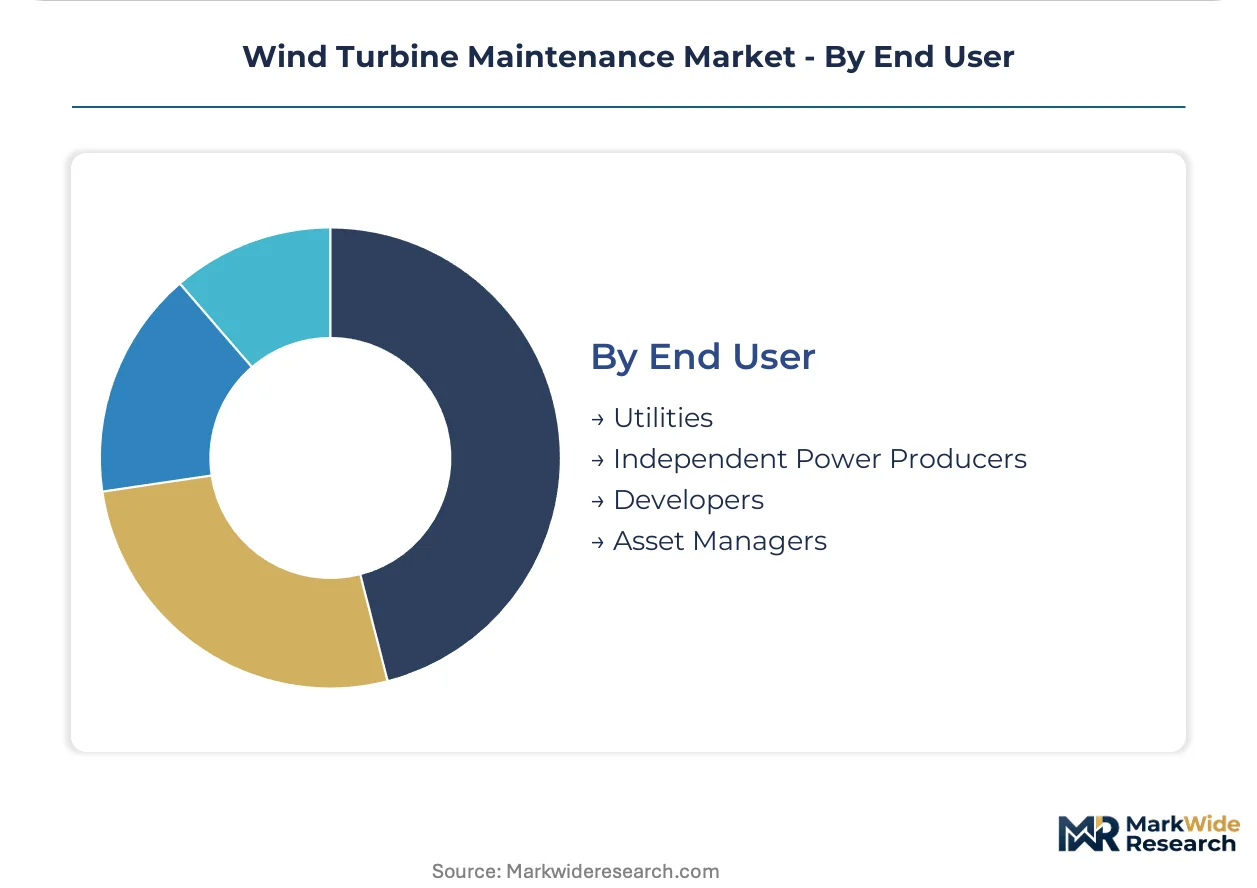
- Utilities:Vertically integrated power companies with captive technical asset management teams. RWE and Ørsted tender maintenance separately from turbine supply.
- Independent Power Producers:Non-utility generators relying on third-party service providers. Deutsche Windtechnik competes aggressively for these contracts outside OEM networks.
- Developers:Project originators transitioning assets to long-term owners post-construction. Warranty handoff negotiations dominate their maintenance focus.
- Asset Managers:Financial investors optimizing portfolio returns through predictive maintenance adoption and availability guarantee structures.
Utilities command the largest contract volumes; asset managers are gaining share fastest as infrastructure funds acquire operational wind portfolios.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Cuxhaven anchors European offshore wind maintenance activity through its specialized service port and vessel marshalling facilities. The concentration of technician training centers and component logistics hubs in this North Sea corridor shapes contract pricing across neighboring markets.
Germany
The 2000-2010 onshore installation wave drives gearbox overhaul demand across Schleswig-Holstein and Lower Saxony. Germany's Federal Maritime and Hydrographic Agency enforces strict offshore certification protocols through its BSH standards. Bremerhaven clusters specialized vessel operators and blade repair facilities serving North Sea arrays.
United Kingdom
Scotland's floating offshore demonstrations and England's Dogger Bank developments generate multi-year service obligations. The country's Health and Safety Executive mandates specific technician qualifications for marine-accessible sites. Grimsby concentrates operations-and-maintenance bases for North Sea lease rounds.
Denmark
Repowering activity dominates as 1990s vintage turbines reach end-of-design-life across Jutland and the Danish straits. The Danish Energy Agency streamlines permitting for lifetime extension projects. Esbjerg functions as the primary North Sea logistics hub with dedicated offshore vessel quays.
Netherlands
Hollandse Kust offshore zones lack established service infrastructure, creating tender opportunities for independent providers. The country's national environmental regulator enforces strict noise and emissions protocols during maintenance operations. Eemshaven develops dedicated offshore wind marshalling and component storage capacity.
Poland
Baltic Sea lease auctions attract developers without captive OEM service networks. The country's national maritime administration issues initial offshore construction permits with attached maintenance obligations. Gdańsk and Szczecin port authorities invest in heavy-lift quays and technician accommodation facilities.
Wind Turbine Maintenance Market Competitive Environment
Capital-heavy vessel operators compete with asset-light technical service firms for contract margins in European wind maintenance. The market structures around three tiers: original equipment manufacturers with captive aftermarket divisions, independent multibrand specialists, and regional contractors focused on single-country markets. Strategic differentiation centers on predictive maintenance platform deployment and offshore logistics coordination. Competitive moves concentrate on unbundling service contracts from turbine supply agreements and acquiring technician training certifications.
Within the independent service provider tier, Deutsche Windtechnik AG and REETEC GmbH exemplify the German-based multibrand specialist archetype competing outside OEM captive networks. Vestas Wind Systems A/S anchors the integrated manufacturer-service model through its aftermarket platform architecture. Siemens Gamesa Renewable Energy occupies a position spanning both turbine supply and dedicated offshore marine logistics.
| Leading Market Players |
|---|
| Nordex SE |
| Deutsche Windtechnik AG |
| Vestas Wind Systems A/S |
| ABO Energy |
| Goldwind |
| Siemens Gamesa Renewable Energy |
| Suzlon Energy |
| REETEC GmbH |
| General Electric |
| Others |
Value Chain & Pricing Dynamics
Certification-grade divergence between BSH-compliant offshore providers and onshore generalists splits both pricing power and sourcing networks across European wind maintenance. Premium predictive contracts command availability-guarantee structures that tie fees to turbine uptime metrics, while commodity corrective services compete on labor arbitrage and crane mobilization speed. This bifurcation concentrates high-margin digital platform investments among North Sea vessel operators while compressing margins for land-based blade repair contractors.
Pricing Analysis
Margin tightening in corrective maintenance reflects aging gearbox procurement bottlenecks at European foundries. Subscription-based predictive contracts dominate offshore segments, with price differentiation anchored in SCADA integration depth and vibration sensor density. Certification tier under Germany's BSH standards separates premium marine-accessible providers from standard onshore operators. Independent power producers exhibit highest price sensitivity, while utility asset managers prioritize availability guarantees over unit cost.
Supply Chain Analysis
Single-source vulnerability sits with specialized gearbox foundries concentrated in Germany, Denmark, and Spain. Critical inputs include high-grade bearing steel, rare-earth magnet components for generator rewinds, and composite resin systems for blade leading-edge repair. Tariff exposure on Chinese-sourced rare earths feeds into generator refurbishment costs. Distribution runs through Bremerhaven and Esbjerg port clusters for offshore logistics, with onshore services deploying directly from regional technician depots.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Predictive maintenance platforms are displacing scheduled inspection regimes across European wind fleets, compressing contract structures and rewriting procurement authority. This technology transition concentrates competitive advantage with providers capable of integrating SCADA analytics, physics-based degradation modeling, and offshore vessel coordination.
For Market Incumbents:Anchored market positions in OEM captive networks face unbundling pressure as utilities tender maintenance separately from turbine supply. Incumbent service divisions must deepen backward integration into condition monitoring hardware to defend margin structures against independent multibrand specialists. Certification investment under evolving IEC 61400-4 gearbox standards represents a critical lever for locking in long-term availability contracts.
For New Entrants and Emerging Players:Launch via drone-based blade inspection services targeting Polish and Baltic offshore zones lacking established OEM infrastructure. White-space concentration appears in Estonia, Latvia, and Polish waters where marine-accessible sites lack predictive maintenance deployment. Go-to-market positioning should emphasize SCADA-agnostic platform architecture enabling multibrand fleet coverage outside Vestas and Siemens Gamesa captive networks.
For Investors and Strategic Acquirers:Exit pathways concentrate in trade sales to infrastructure funds acquiring operational wind portfolios with attached service obligations. Long-term viability frames around predictive maintenance platform ownership rather than labor-intensive corrective services. Watch offshore vessel utilization rates as the inflection signal—weather-window compression amplifies the value of failure-forecasting capabilities.
| Strategic Initiative | Industry Significance |
|---|---|
| Digital Twin Platform Deployment | Physics-based degradation models from Siemens Gamesa compress feedback loops between field performance and engineering design. |
| Offshore Service Vessel Expansion | Specialized marine logistics capacity at Cuxhaven and Bremerhaven secures weather-window access for North Sea arrays. |
| Multibrand Control System Integration | SCADA-agnostic architectures from Deutsche Windtechnik enable independent providers to compete outside OEM captive networks. |
| Drone-Based Blade Inspection Scaling | Automated thermography reduces rope-access dependency and cuts inspection cycle times across aging onshore fleets. |
| BSH Certification Investment | Germany's Federal Maritime and Hydrographic Agency standards create regulatory moats for offshore service providers. |
Study Parameters
Document review covered IEC 61400 maintenance standards, EU Green Deal implementation documents, and BSH offshore certification protocols, complemented by interviews with wind farm asset managers, independent service provider technical directors, offshore vessel operators, and utility procurement leads. Secondary validation drew from customs trade data on gearbox component flows, EIA renewable capacity statistics, and project development databases tracking Baltic Sea lease auctions. Bottom-up technician deployment models and top-down contract value estimates were triangulated against disclosed service agreement structures.
Historical growth patterns in predictive maintenance adoption were cross-referenced against panel input from industry stakeholders to establish baseline assumptions across the projection horizon. Segmentation modeling incorporated service type, application environment, digital technology tier, and end-user procurement authority. CAGRs were derived from fitted curves on condition monitoring sensor deployment rates and offshore capacity expansion trajectories. Forecast inputs included SCADA integration penetration rates and BSH certification timeline assumptions.
Policy acceleration under EU renewable targets, supply disruption at European gearbox foundries, and technician training pipeline constraints are the dominant revision risks for maintenance demand projections. Forecasts reflect documented assumptions on fleet aging profiles and regulatory enforcement intensity. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Power Equipment
Global Exhaust Heat Recovery System Market
Power Equipment
Industrial Gas Turbine Ignition System Market
Power Equipment
Ecuador Power EPC Market
Power Equipment
ASEAN Power EPC Market
Power Equipment
United Kingdom Power EPC Market
Power Equipment
Gas Insulated Power Equipment Market
Power Equipment
Gas Turbine Compressor Market
Power Equipment
Brazil Power EPC Market
Power Equipment
Russian Federation Power EPC Market
Power Equipment
Thailand Power Market
Power Equipment
Global Hydraulic Power Unit Market
Power Equipment
Industrial Power Transmission Drive Belts Market
Power Equipment
Turbine Governor Market
Power Equipment
North America SCR Power Controller Market
Power Equipment
Global Power Rental Systems Market
Power Equipment
Power Equipment Testing Market