
 Brazil Power EPC Market | 2026-2036
Brazil Power EPC Market Size, Share, and Industry Trends Forecast 2026-2036
Brazil Power EPC Market Outlook
Utility procurement channels in Brazil is tilting toward auction-driven, long-term power purchase agreements that favor integrated EPC consortia. Siemens Renewable Energy SA leverages its turbine supply chain to anchor wind farm buildouts across Ceará and Rio Grande do Norte. Fluor Daniel Brasil competes on mega-project execution capability for thermal and combined-cycle installations. Techint Engenharia e Construção SA sustains its position through heavy civil infrastructure dominance in hydroelectric rehabilitation.
Brazil Power EPC encompasses the integrated design, equipment sourcing, construction management, and commissioning of electricity generation and transmission assets, typically executed under lump-sum turnkey contracts with performance guarantees tied to COD milestones. The primary purpose is delivering bankable energy infrastructure that meets ANEEL grid connection standards and long-term off-take obligations. Solar and wind segments now attract the majority of new order intake, driven by auction schedules and equipment cost curves that compress developer returns. Thermal EPC occupies a narrower but strategically vital niche, serving system reliability mandates and industrial captive demand where grid access remains constrained.
ANEEL auction rules, BNDES local content requirements, and environmental licensing protocols under IBAMA shape project timelines, equipment sourcing decisions, and foreign participation structures. Compliance complexity with CONAMA resolution 491/2018 on atmospheric emissions and evolving Green Book guidelines for hydro licensing extends pre-construction phases and elevates contingency reserves. Stakeholders must monitor regulatory uncertainty around Law 14.300/2022 implementation and its net-metering revisions, as these will determine distributed generation EPC volumes and utility-scale project queue priorities.
Market Dynamics
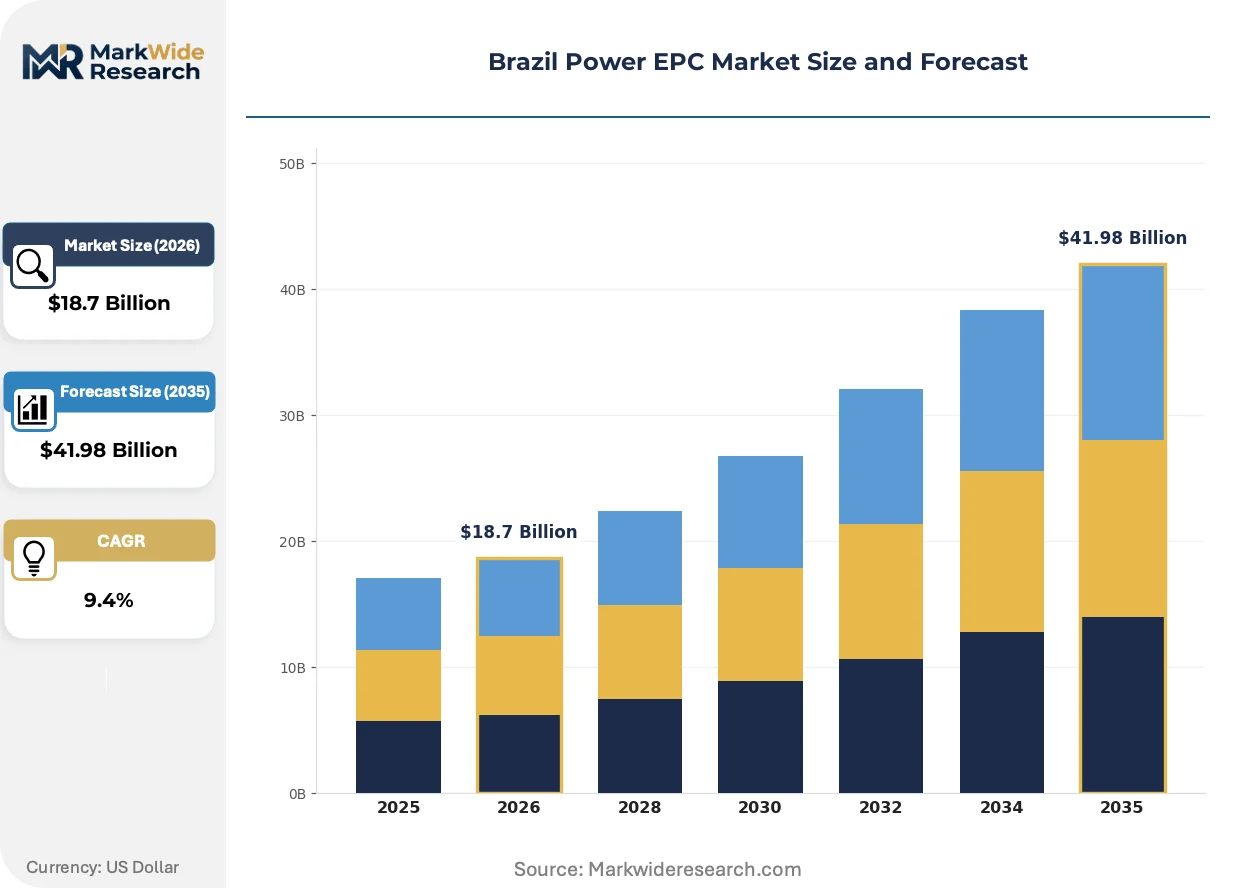
ANEEL's auction-driven procurement framework is compressing developer margins and forcing EPC contractors toward integrated turnkey delivery models with strict COD guarantees.
Growth Catalysts
- ANEEL Renewable Auctions:Scheduled capacity tenders create predictable order pipelines for wind and solar EPC consortia. Auction rules favor bidders with proven execution records.
- Northeast Resource Clustering:Wind and solar irradiance concentration in Ceará, Piauí, and Rio Grande do Norte attracts mega-project capital seeking optimal capacity factors.
- BNDES Local Content Mandates:Domestic equipment sourcing requirements under FINAME lines channel contract awards toward EPC firms with established Brazilian supply chains.
Market Restraints
- Steel and Copper Volatility:Transmission tower and cabling input costs fluctuate with global commodity benchmarks, eroding fixed-price EPC margins.
- Chinese Equipment Dominance:Solar module and wind turbine nacelle supply concentrates among East Asian manufacturers, creating import dependency and tariff exposure.
- IBAMA Licensing Delays:Environmental impact assessments for Amazon basin hydro projects extend approval timelines, freezing capital deployment.
Strategic Opportunities
- Distributed Generation Expansion:Law 14.300/2022 net-metering revisions open commercial and industrial rooftop solar EPC contracts outside auction channels.
- Green Hydrogen Integration:Electrolyzer coupling with Northeast wind farms creates hybrid EPC scopes combining generation and industrial offtake infrastructure.
- Transmission Augmentation:New line-of-business EPC opportunities emerge from ANEEL's transmission auction schedule addressing interconnection bottlenecks.
Industry Challenges
- Specialized Welder and High-Voltage Technician Scarcity:Grid-scale substation and collector system construction faces labor bottlenecks in remote Northeast sites.
- Legacy Hydro Rehabilitation Complexity:Aging Itaipu and Tucuruí infrastructure requires EPC firms to integrate new turbine runners with operational dam safety protocols.
- Supply Chain Reconfiguration Costs:BNDES local content rules force contractors to substitute imported switchgear with untested domestic suppliers, elevating commissioning risk.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Brazil Power EPC Market |
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $41.98 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Engineering, Procurement, Construction, Commissioning Technology: Solar, Wind, Hydro, Thermal End User: Utilities, Industrial, Residential, Government Project Size: Small Scale, Medium Scale, Large Scale, Mega Projects |
| Companies Covered | Siemens Renewable Energy SA, Omexom, Fluor Daniel Brasil, Duro Felguera SA, Mitsubishi Power Americas, Enel S.p.A., Canadian Solar Inc., Techint Engenharia e Construção SA, General Electric Company, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Brazil Power EPC Market Strategic Shifts
Digital twin deployment and modular construction methods are compressing project schedules while ANEEL tightens performance guarantee requirements on new auction rounds.
Bifacial solar modules with tracking systems is rendering obsolete fixed-tilt monofacial arrays in utility-scale procurement. Developers in Minas Gerais and Bahia now specify dual-axis trackers as baseline. This technology shift is compressing LCOE calculations and disqualifying EPC bidders without tracker installation experience.
CONAMA Resolution 491/2018 atmospheric emission standards now mandate continuous emissions monitoring systems on all new thermal EPC contracts. Gas turbine and combined-cycle projects must integrate CEMS hardware from FEED through commissioning. The compliance burden falls heaviest on peaker plant EPC scopes in São Paulo's industrial corridor.
Integrated O&M bundling now dominates auction-winning bids, with developers demanding 10-year service contracts wrapped into initial EPC pricing. Traditional build-only contractors lose to firms offering combined construction and long-term asset management. This pattern concentrates in wind farm awards across Rio Grande do Norte where remote site access favors captive service teams.
Brazil Power EPC Market Segmentation
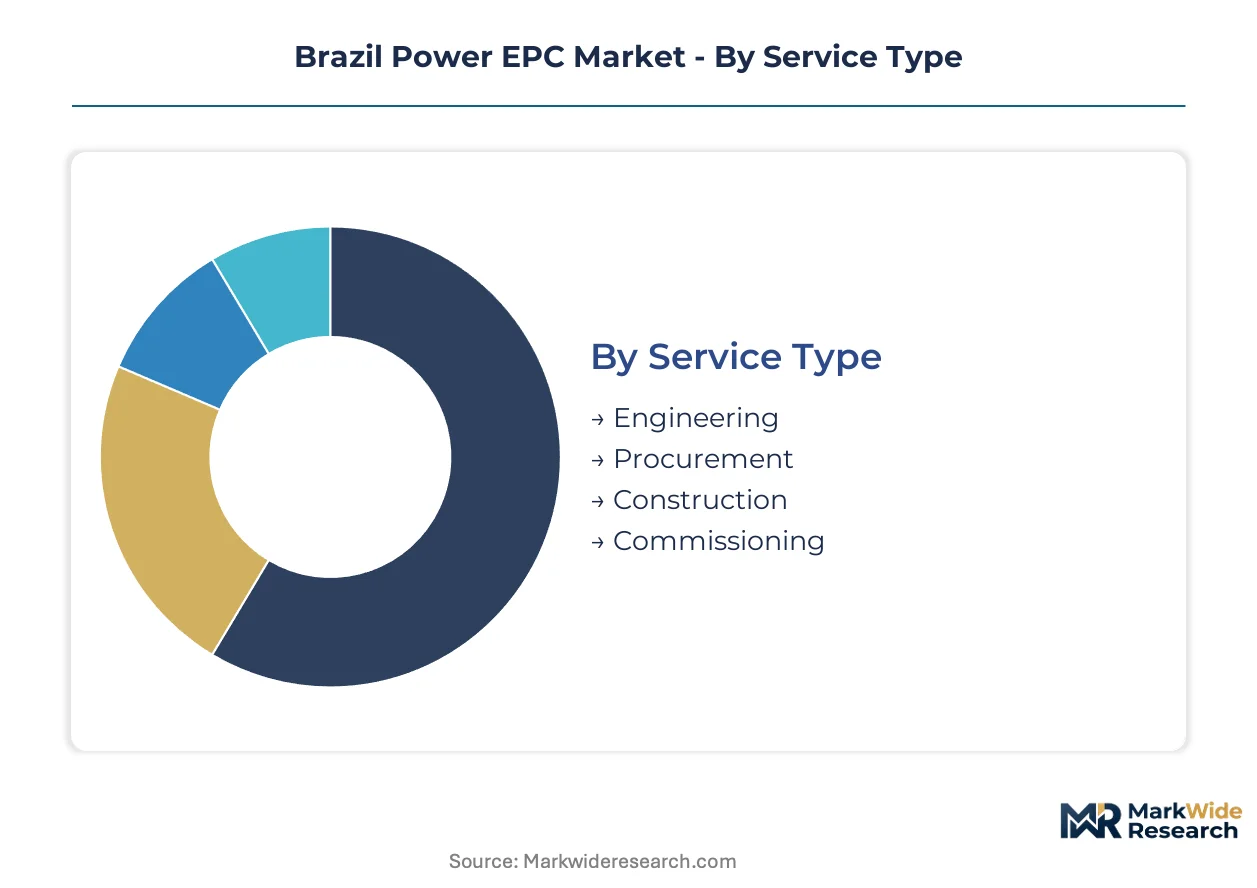
Segmentation in Brazil Power EPC reveals distinct procurement rhythms and margin structures across service types, technologies, and customer profiles. Each dimension carries implications for contract duration, local content compliance, and working capital intensity.
Service Type:
Cycle times vary dramatically across the EPC value chain, with pure engineering contracts turning over in months while full turnkey construction extends across multiple years.
- Engineering:Front-end design and detailed engineering packages for ANEEL-compliant grid studies execute on 6-12 month cycles. Demand clusters around transmission interconnection studies for Northeast wind clusters where IBAMA licensing delays compress design windows.
- Procurement:Equipment sourcing and logistics coordination spans 12-24 months for imported wind turbine nacelles and solar inverters. BNDES FINAME local content mandates force contractors to substitute domestic switchgear, extending vendor qualification timelines.
- Construction:Physical installation and civil works stretch 18-36 months for utility-scale solar farms in Bahia's high-irradiance zones. Labor scarcity for specialized welders and HV technicians at remote Northeast sites drives cost escalation.
- Commissioning:System integration testing and COD certification requires 3-9 months of parallel grid synchronization and ANEEL inspection protocols. Performance guarantee enforcement tightens with each auction round.
Construction anchors the volume base while commissioning gains share at the steepest rate as integrated O&M bundling extends contractor accountability windows.
Technology:
Cost tier differentiation separates mature hydro rehabilitation from capital-light distributed solar, with thermal occupying a reliability-premium niche.
- Solar:Utility-scale photovoltaic and distributed generation EPC now dominates new order intake. Bifacial modules with dual-axis tracking displace fixed-tilt arrays in Minas Gerais and Bahia procurement specifications.
- Wind:Onshore turbine installation and collector system construction concentrates in Ceará and Rio Grande do Norte where capacity factors exceed national averages. Siemens Renewable Energy SA anchors nacelle supply chains for these projects.
- Hydro:Greenfield dam construction has stalled under IBAMA licensing moratoria while rehabilitation of Itaipu and Tucuruí infrastructure sustains specialized civil contractors. Legacy asset complexity demands integration with operational dam safety protocols.
- Thermal:Combined-cycle and gas turbine peaker plants serve system reliability mandates in São Paulo's industrial corridor. CONAMA Resolution 491/2018 mandates continuous emissions monitoring systems from FEED through commissioning.
Solar anchors the volume base while wind gains share at the steepest expansion trajectory as auction schedules favor proven renewable resource zones.
End User:
Customer type determines contract structure, with utilities demanding long-term offtake linkage and industrial buyers prioritizing captive supply security.
- Utilities:State and private generation companies procure through ANEEL auction channels with 15-30 year PPA backing. Integrated turnkey delivery with strict COD guarantees dominates bidding requirements.
- Industrial:Mining, steel, and chemical sector captives seek behind-the-meter solutions where grid access constraints persist. Law 14.300/2022 net-metering revisions open commercial rooftop solar EPC outside auction frameworks.
- Residential:Distributed generation micro-systems under 75kW capacity fall outside traditional EPC scopes, served instead by installer networks with limited engineering sophistication.
- Government:Federal and state infrastructure programs channel through BNDES financing lines with stringent local content enforcement. Public procurement timelines extend 18-24 months beyond private sector equivalents.
Utilities anchor the volume base while industrial gains share at the steepest rate as energy cost hedging motivates captive generation investment.
Project Size:
Maturity gradients separate standardized small-scale deployment from bespoke mega-project execution with idiosyncratic risk profiles.
- Small Scale:Sub-10MW distributed solar and diesel hybrid systems execute through regional contractor networks with limited engineering integration. Standardized designs compress procurement cycles to 6-12 months.
- Medium Scale:10-100MW wind and solar farms attract national EPC consortia with established ANEEL relationships. These projects balance standardization with site-specific interconnection customization.
- Large Scale:100-500MW utility-scale developments demand integrated procurement, construction, and commissioning capabilities. Fluor Daniel Brasil and Techint Engenharia e Construção SA compete aggressively in this tier.
- Mega Projects:Above-500MW complexes including transmission integration and greenfield hydro require multi-year execution horizons and substantial contingency reserves. Only a handful of contractors maintain credible bidding capacity.
Large scale anchors the volume base while mega projects gain share at the steepest rate as capital concentrates in optimal Northeast resource clusters.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Belo Monte transmission corridor underwrites the Northeast's centrality to Brazil's power EPC market, channeling gigawatt-scale renewable generation toward southeastern load centers.
Northeast Region
Wind and solar irradiance concentration in Ceará, Piauí, and Rio Grande do Norte drives mega-project investment seeking optimal capacity factors. ANEEL's renewable energy auctions create predictable order pipelines for EPC consortia with proven execution records. Siemens Renewable Energy SA anchors turbine supply chains for wind farm buildouts across the coastal belt.
Southeast Region
Industrial captive demand from mining and steel sectors in Minas Gerais and São Paulo sustains thermal and distributed solar EPC contracts outside auction channels. CONAMA Resolution 491/2018 mandates continuous emissions monitoring systems on all new thermal installations in São Paulo's industrial corridor. The state's gas turbine peaker plants serve system reliability mandates where grid congestion persists.
South Region
Hydroelectric rehabilitation of aging infrastructure dominates EPC activity in Rio Grande do Sul and Paraná, where Itaipu and smaller dams require integration with operational safety protocols. Techint Engenharia e Construção SA sustains its position through heavy civil infrastructure dominance in these legacy asset upgrades. The region's industrial base demands reliable baseload power.
North Region
Amazon basin hydro projects face IBAMA licensing moratoria that extend approval timelines and freeze capital deployment, constraining greenfield EPC opportunities. Environmental impact assessments for new dams encounter heightened scrutiny under evolving Green Book guidelines. Transmission interconnection studies concentrate on linking isolated systems to the national grid.
Brazil Power EPC Market Competitive Environment
Platform integrators command the system tier; component specialists sit upstream. The Brazil Power EPC market structures around integrated turnkey delivery capability, with auction-winning bids favoring firms offering combined construction and long-term asset management. Three archetypes dominate: global engineering conglomerates with local subsidiaries, domestic civil infrastructure heavyweights, and renewable technology specialists leveraging equipment supply chains. Competitive moves concentrate on strategic partnerships for local content compliance and portfolio diversification into green hydrogen integration.
Among global engineering conglomerates, Fluor Daniel Brasil and General Electric Company represent the integrated execution archetype, anchoring mega-project bidding capacity for thermal and combined-cycle installations. Siemens Renewable Energy SA exemplifies the renewable technology specialist model, leveraging turbine supply chain dominance in Northeast wind clusters. These three occupy positions where auction rules favor proven track records and strict COD guarantees.
| Leading Market Players |
|---|
| Siemens Renewable Energy SA |
| Omexom |
| Fluor Daniel Brasil |
| Duro Felguera SA |
| Mitsubishi Power Americas |
| Enel S.p.A. |
| Canadian Solar Inc. |
| Techint Engenharia e Construção SA |
| General Electric Company |
| Others |
Value Chain & Pricing Dynamics
São Paulo's industrial corridor hosts the densest concentration of thermal EPC contractors, where proximity to gas turbine component suppliers compresses logistics costs and amplifies pricing leverage for peaker plant developers. This geographic clustering interacts with ANEEL auction schedules to create volume-discount tiering that rewards integrated turnkey bidders with multi-project portfolios.
Pricing Analysis
Volume-discount tiering structures dominate auction-winning bids, with three-tier pricing separating mega-project consortia from mid-scale regional players and small-scale installer networks. Price differentiation hinges on BNDES FINAME local content compliance tiers and bundled O&M contract duration, with 10-year service wrap commanding premium positioning. Cost compression in solar EPC is intensifying because bifacial tracker specifications disqualify inexperienced bidders. Industrial captive buyers in Minas Gerais exhibit highest price sensitivity, while utility offtakers prioritize COD guarantee strength over unit cost.
Supply Chain Analysis
Export-control regimes on high-voltage switchgear and gas turbine hot-section components constrain flows from Germany, Japan, and the United States into Brazilian project sites. Raw material dependencies center on Chinese solar modules, South Korean wind turbine nacelles, and domestic steel for transmission towers. Single-source vulnerability concentrates in East Asian inverter supply, where tariff exposure disrupts procurement timelines. Distribution runs through BNDES-certified logistics networks that enforce local content verification at port of entry.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Brazil Power EPC is entering a cyclical recovery phase as ANEEL's auction pipeline restocks following regulatory clarity on Law 14.300/2022 implementation. The recovery is underwritten by Northeast renewable resource clustering that attracts capital seeking optimal capacity factors.
For Market Incumbents: Pre-empt margin erosion from Chinese equipment dominance by anchoring turbine supply chain partnerships in Ceará and Rio Grande do Norte. Defensive consolidation through backward integration into domestic switchgear manufacturing addresses BNDES local content mandates while reducing commissioning risk from untested suppliers.
For New Entrants and Emerging Players: Establish a beachhead in distributed generation commercial rooftop solar outside auction channels, where Law 14.300/2022 net-metering revisions create procurement velocity unmatched by utility-scale queues. White-space targets include electrolyzer coupling for green hydrogen integration and transmission augmentation contracts addressing interconnection bottlenecks.
For Investors and Strategic Acquirers: Carve-out targets emerge from global engineering conglomerates seeking to divest non-core thermal EPC capabilities as renewable auction volumes dominate order intake. Long-term viability favors firms with integrated O&M bundling expertise and ANEEL relationship depth. The signal to watch is IBAMA licensing velocity for Amazon basin projects, where approval acceleration would unlock frozen capital deployment.
| Strategic Initiative | Industry Significance |
|---|---|
| Integrated O&M Bundling | 10-year service contracts wrapped into EPC pricing win ANEEL auction bids against build-only competitors. |
| Backward Integration into Switchgear | Domestic manufacturing satisfies BNDES FINAME local content rules and reduces commissioning risk. |
| Green Hydrogen Coupling | Electrolyzer integration with Northeast wind farms creates hybrid EPC scopes combining generation and industrial offtake. |
| Digital Twin Deployment | Virtual commissioning compresses project schedules while ANEEL tightens performance guarantee requirements. |
| Transmission Augmentation | New line-of-business opportunities emerge from ANEEL's auction schedule addressing interconnection bottlenecks. |
Study Parameters
Initial hypotheses were tested against primary input from utility planning officers, IPP project developers, EPC contractors, and grid operators and refined through secondary validation against ANEEL auction databases, BNDES FINAME disbursement records, and IBAMA environmental licensing filings. Bottom-up project pipeline tracking triangulated with top-down macroeconomic scenario modeling to anchor volume and value estimates.
Demand-supply-balance framing structured the analytical approach across the projection horizon, with segmentation modeled by fuel source, generation capacity tier, project scale, regulatory framework, and regional grid type. CAGRs were derived from installed capacity buildout trajectories and capital cost curve assumptions, incorporating auction schedule density and equipment import tariff exposure as industry-specific forecast inputs.
Stress conditions across commodity price volatility, IBAMA approval timelines, and BNDES financing availability were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions about auction rule stability and local content enforcement intensity. Material shifts in ANEEL regulatory posture or Green Book hydro licensing guidelines would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Power Equipment
Ecuador Power EPC Market
Power Equipment
Thailand Power EPC Market
Power Equipment
Power Equipment Testing Market
Power Equipment
Egypt Power EPC Market
Power Equipment
Global Transformerless UPS Market
Power Equipment
Power Plant Maintenance Market
Power Equipment
India Power EPC Market
Power Equipment
Middle East Power Filter Market
Power Equipment
Global Power System Simulator Market
Power Equipment
Power Generation Equipment MRO Market
Power Equipment
Wind Tunnel Fans Market
Power Equipment
Submarine Power Cable Market
Power Equipment
Asia-Pacific SCR Power Controller Market
Power Equipment
Portable Power Station Market
Power Equipment
Global Exhaust Heat Recovery System Market
Power Equipment
AC Power Sources Market