
 Russian Federation Power EPC Market | 2026-2036
Russian Federation Power EPC Market Size, Share, and Industry Trends Forecast 2026-2036
Russian Federation Power EPC Market Analytics
Digital twin integration in power plant design is narrowing the gap between engineering simulation and field commissioning timelines. Rosatom leverages its nuclear EPC expertise to anchor long-term reactor construction programs. Inter Rao Ues OJSC competes across conventional and renewable generation portfolios. PowerChina extends its footprint through Belt and Road-linked infrastructure financing.
Russian Federation Power EPC encompasses the full-cycle delivery of power generation and transmission infrastructure, spanning feasibility studies, equipment procurement, civil works, and commissioning with voltage ratings from 0.4 kV distribution to 750 kV backbone lines. Gas turbine technology dominates new thermal additions due to shorter construction cycles and modular scalability. The government end-user segment leads procurement volume through state-directed capacity auctions, while independent power producers specialize in co-generation and industrial captive supply.
Rostekhnadzor enforces construction safety and equipment certification standards that extend project timelines but reduce operational risk exposure. The Federal Antimonopoly Service monitors procurement transparency in state-backed tenders, shaping competitive access for foreign EPC contractors. Stakeholders must track how sanctions-adjusted equipment sourcing strategies reshape contractor-subcontractor relationships across the project lifecycle.
Market Dynamics
Federal Grid Company mandates for digital substation deployment are compressing traditional commissioning cycles across the Russian power sector. State-directed capacity auctions in Siberia and the Far East are redrawing contractor mobilization patterns.
Growth Catalysts
- Far East Generation Expansion:State-backed utilities are advancing thermal and nuclear capacity additions across the Russian Far East Federal District to serve industrial load growth.
- Rostekhnadzor Safety Certification:Equipment certification standards are lengthening project timelines but reducing long-term operational risk exposure for transmission infrastructure.
- Gas Turbine Modularization:Shorter construction cycles and scalable unit sizing are accelerating gas turbine deployments in the Volga Federal District retrofit programs.
Market Restraints
- Sanctions-Adjusted Equipment Sourcing:Import substitution requirements are extending procurement lead times for high-voltage switchgear and control systems.
- Specialized Welding Labor Concentration:Certified pipeline and pressure vessel welders cluster in the Central Federal District, creating geographic supply bottlenecks.
- Domestic Turbine Manufacturing Gap:Heavy frame gas turbine rotors and advanced blade casting capacity remains concentrated outside Russian borders.
Strategic Opportunities
- Arctic Zone Infrastructure:Northern Sea Route energy corridor development is opening EPC scope for resilient cold-climate substations and transmission lines.
- Digital Twin Integration:Engineering simulation-to-commissioning workflow compression is creating differentiation for contractors with integrated design platforms.
- Co-Generation Industrial Captive Supply:Oil and gas processing clusters in the Ural Federal District are expanding behind-the-meter power generation demand.
Industry Challenges
- Commissioning Engineer Scarcity:750 kV backbone line testing and energization specialists are in short supply relative to Federal Grid Company deployment targets.
- Legacy SCADA Integration Complexity:Digital substation deployments must interface with Soviet-era control architectures still operational across the Northwestern Federal District.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Russian Federation Power EPC Market |
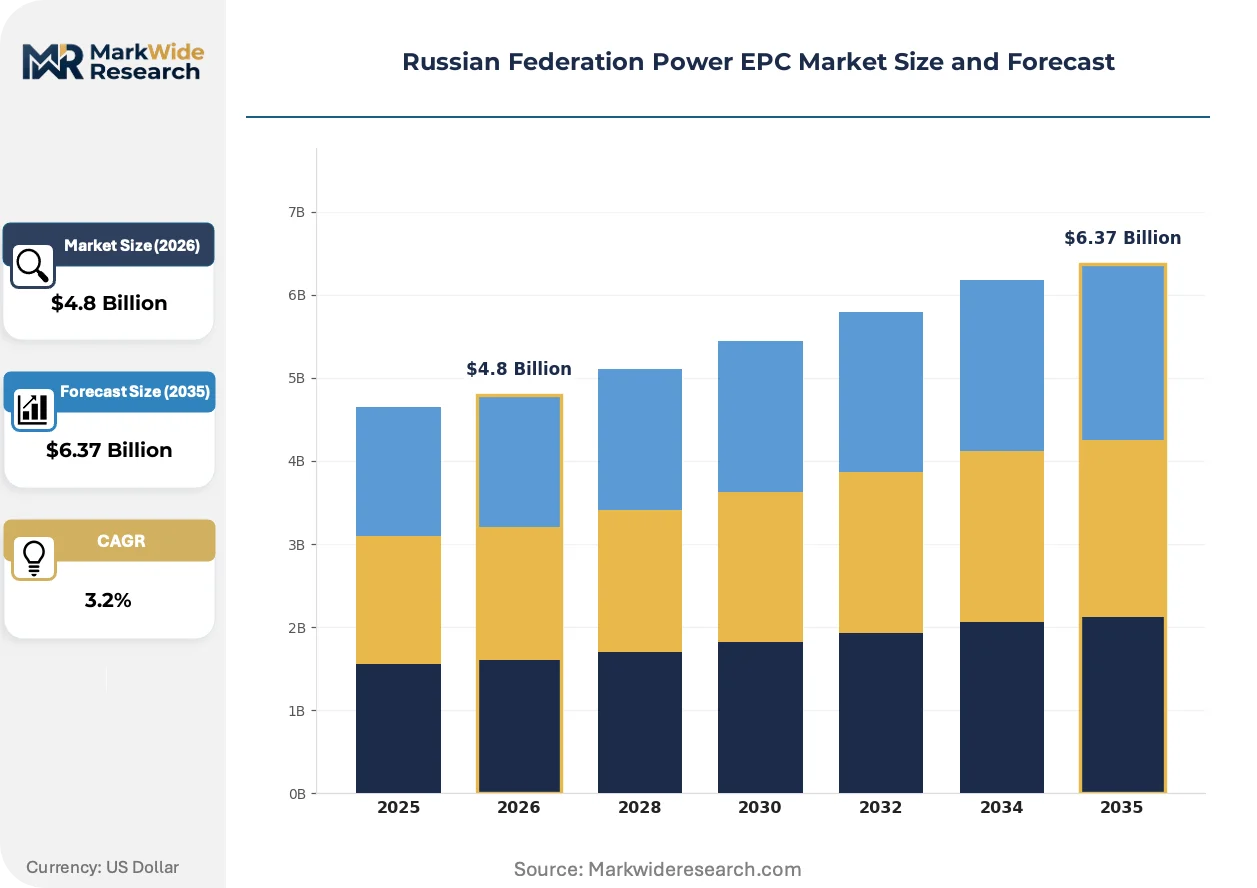
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $6.37 Billion |
| CAGR (2026 – 2036) | 3.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
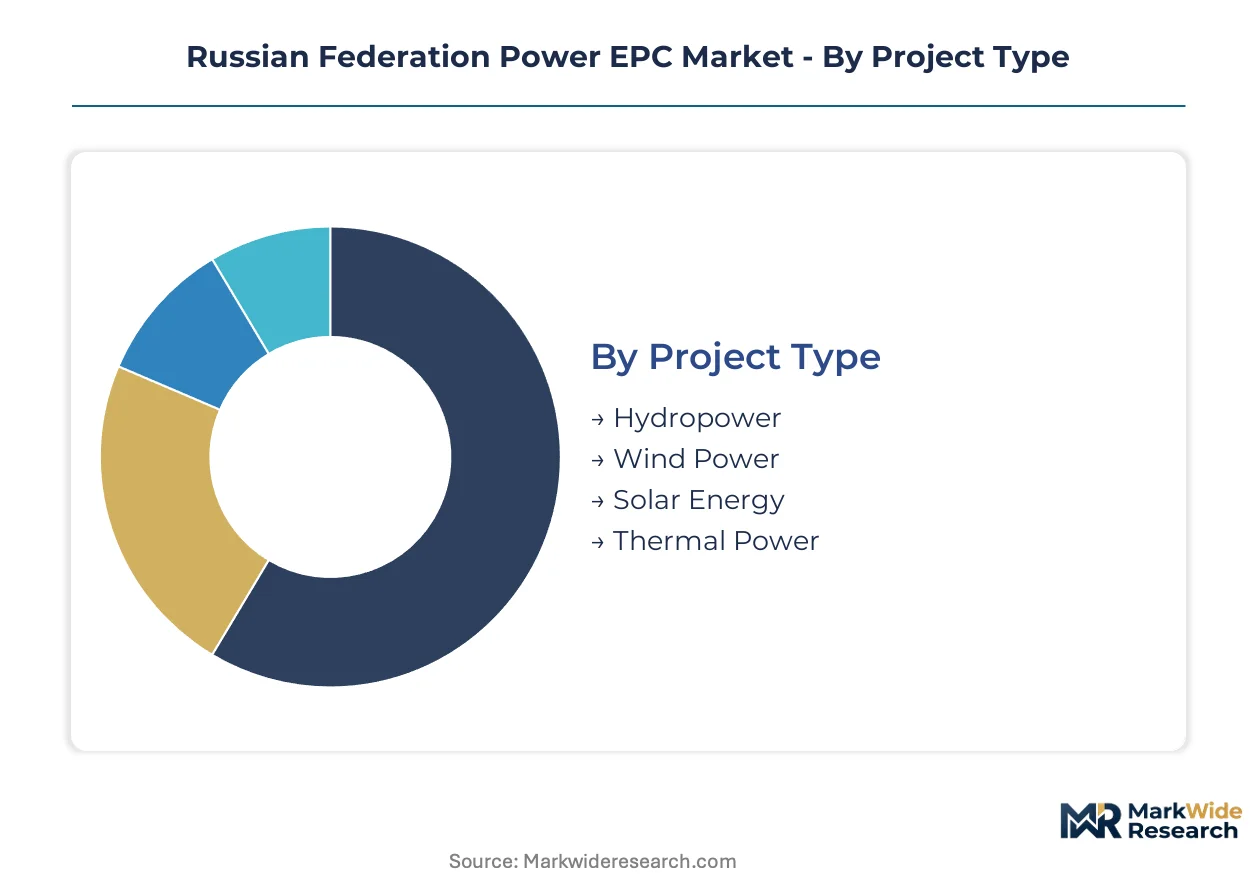
| Segmentation | Project Type: Hydropower, Wind Power, Solar Energy, Thermal Power Technology: Gas Turbine, Steam Turbine, Photovoltaic, Hydroelectric End User: Government, Independent Power Producers, Utilities, Industrial Users Service Type: Engineering, Procurement, Construction, Commissioning |
| Companies Covered | Inter Rao Ues OJSC, Rosatom, JSC Atomenergoprom, VELESSTROY, RusHydro, OJSC Power Machines, Siemens AG, PowerChina, Enka İnşaat ve Sanayi AS, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Russian Federation Power EPC Market Evolving Landscape
Digitalization of asset lifecycle management is collapsing the traditional boundary between engineering design and operational performance optimization. Russian power infrastructure is experiencing compressed innovation cycles across generation, transmission, and distribution domains.
Digital twin platforms for power plant design are digitizing the handoff between simulation environments and physical commissioning. Federal Grid Company and regional distribution network operators are mandating these tools for substation projects above 110 kV. The technology is digitizing contractor risk allocation by enabling pre-construction validation of thermal and electrical performance.
Rostekhnadzor has tightened construction safety documentation requirements for nuclear and thermal generation facilities. The regulation is extending pre-construction approval timelines by six to twelve months. EPC contractors are responding by embedding compliance specialists earlier in project development phases.
Industrial offtakers in the Ural and Volga Federal Districts are unbundling long-term service agreements from initial EPC contracts. Equipment suppliers are adapting by separating hardware procurement from multi-year maintenance provisions. This pattern is most visible among petrochemical and metallurgical end-users with captive generation requirements.
Russian Federation Power EPC Market Segmentation
Segmentation in Russian power EPC reveals how contract scope, technology choice, and procurement authority reshape contractor capabilities and margin structures. Each dimension carries distinct after-sales-service obligations that extend revenue recognition timelines and working capital requirements.
Project Type:
After-sales-service intensity varies sharply across generation technologies, with thermal and hydro assets demanding multi-decade maintenance commitments versus renewable portfolios with shorter service horizons.
- Thermal Power:Heavy-frame gas turbine and combined-cycle plants require specialized rotor maintenance and hot gas path inspections. Demand concentrates in the Volga Federal District retrofit programs, where Federal Grid Company mandates are accelerating digital control system upgrades. Long-term service agreements typically span 15-25 years and represent 40-60% of lifetime contract value.
- Hydropower:Large-scale dam and run-of-river installations involve turbine runner refurbishment cycles and concrete structure monitoring. Siberian utilities are expanding capacity along the Angara and Yenisei river basins to serve aluminum smelter load growth. Civil works intensity creates extended warranty periods for underground powerhouse complexes.
- Solar Energy:Utility-scale photovoltaic parks involve module cleaning contracts and inverter replacement schedules. Southern Federal District irradiance profiles support merchant solar development.
- Wind Power:Onshore turbine installations require gearbox overhaul programs and blade inspection protocols. Far East coastal zones offer development potential.
Thermal Power holds the largest share; momentum sits with Hydropower given Siberian capacity auction allocations.
Technology:
Technology selection determines the geographic clustering of specialized labor and the import-dependency of critical components.
- Gas Turbine:Aeroderivative and industrial heavy-frame units dominate new thermal additions for their modular scalability and rapid commissioning. The Volga Federal District retrofit market favors 60-150 MW class machines for grid stability services. Domestic blade casting capacity constraints are extending procurement lead times for hot section components.
- Steam Turbine:Subcritical and supercritical coal units remain relevant for base-load provision in Siberian heating districts. High-pressure rotor forging requirements concentrate supply among limited qualified vendors.
- Photovoltaic:Crystalline silicon module integration dominates utility-scale solar EPC. Southern Federal District projects are expanding.
- Hydroelectric:Francis and Kaplan turbine configurations serve varying head conditions across Siberian river systems. Runner cavitation repair specialists cluster in the Central Federal District.
Gas Turbine commands procurement volume; Photovoltaic is expanding most quickly as capacity auction prices compress.
End User:
Procurement authority and contract structuring diverge sharply between state-directed and market-driven offtakers.
- Government:State-directed capacity auctions through the Ministry of Energy determine project allocation and tariff mechanisms. Siberian and Far East generation expansion programs prioritize reliability over merchant price exposure. Tender documentation mandates local content thresholds and technology transfer provisions.
- Independent Power Producers:Merchant developers and industrial captive suppliers negotiate bilateral offtake agreements. Co-generation projects in the Ural Federal District petrochemical clusters are unbundling EPC from long-term service contracts.
- Utilities:Federal Grid Company and regional distribution network operators procure transmission and substation infrastructure. Digital substation mandates above 110 kV are reshaping contractor qualification requirements.
- Industrial Users:Metallurgical and mining enterprises develop behind-the-meter generation for power quality and cost hedging. Norilsk Nickel and similar operators are expanding captive thermal capacity.
Government directs the largest procurement volume; Independent Power Producers are gaining share fastest as bilateral contracting expands.
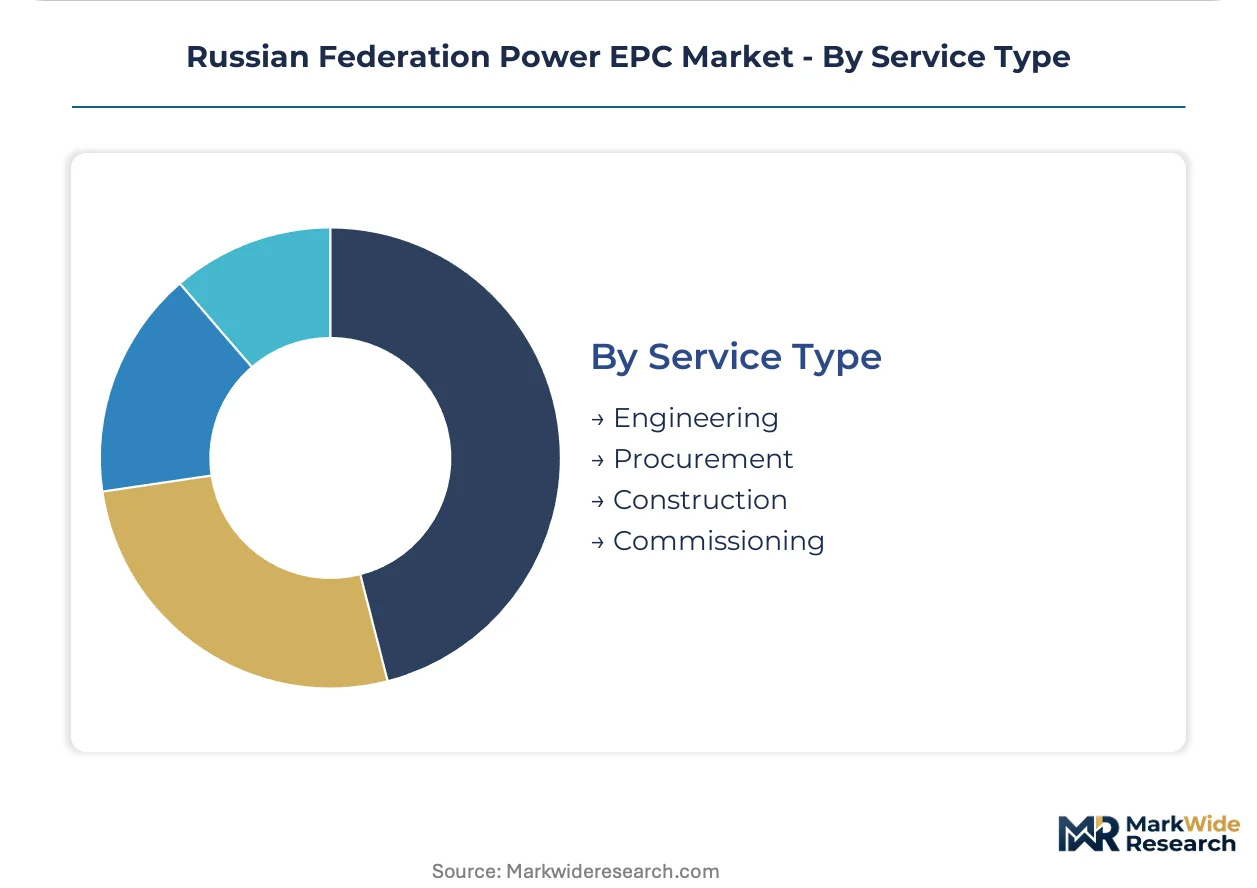
Service Type:
Contract scope unbundling is reshaping risk allocation and margin capture across the project lifecycle.
- Engineering:Front-end design and digital twin development are compressing commissioning timelines. Federal Grid Company mandates for 110 kV and above substation projects require integrated simulation platforms.
- Procurement:Equipment sourcing faces sanctions-adjusted lead time extensions for high-voltage switchgear and control systems. Import substitution requirements are reshaping supplier qualification protocols.
- Construction:Civil works and electromechanical installation dominate labor deployment. Certified pipeline and pressure vessel welders concentrate in the Central Federal District, creating mobilization bottlenecks for remote site execution.
- Commissioning:750 kV backbone line energization and protection system testing require scarce specialist labor. Federal Grid Company deployment targets exceed available qualified engineer supply.
Construction absorbs the largest cost share; Commissioning carries the steepest margin expansion trajectory as specialist scarcity intensifies.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
State-backed utilities concentrate procurement authority across Siberia and the Far East, where industrial load growth from mining and metallurgy operations drives generation capacity auctions. Federal Grid Company mandates reshape contractor mobilization patterns toward digital substation deployments.
Siberian Federal District
Aluminum smelter load growth along the Angara and Yenisei river basins propels hydropower capacity expansion. The Ministry of Energy directs capacity auction allocations prioritizing reliability over merchant price exposure. Krasnoyarsk and Irkutsk host the primary civil works contractors for underground powerhouse complexes.
Far East Federal District
Thermal and nuclear generation additions serve port infrastructure and resource extraction clusters. Rostekhnadzor enforces construction safety documentation extending pre-construction approval timelines. Vladivostok and Khabarovsk concentrate marine logistics capabilities for equipment import substitution.
Volga Federal District
Gas turbine retrofit programs dominate procurement volume for grid stability services. Federal Antimonopoly Service monitors tender transparency shaping competitive access. Samara and Kazan anchor the regional base of certified pipeline welders for pressure vessel construction.
Ural Federal District
Petrochemical and metallurgical enterprises expand behind-the-meter co-generation capacity. Industrial offtakers unbundle long-term service agreements from initial EPC contracts. Yekaterinburg and Chelyabinsk cluster oil and gas processing demand for captive power generation.
Northwestern Federal District
Digital substation deployments must interface with Soviet-era SCADA architectures still operational across legacy infrastructure. Federal Grid Company mandates above 110 kV require integrated simulation platforms. Saint Petersburg concentrates commissioning engineer training for 750 kV backbone line testing.
Russian Federation Power EPC Market Competitive Landscape
Channel-controlling players compete with product-specialist players across state-directed and merchant procurement channels. The vendor base organizes around state-backed utilities holding auction authority, industrial offtakers negotiating bilateral agreements, and international contractors accessing Belt and Road financing. Three archetypes dominate: domestic state-linked conglomerates, foreign EPC contractors with import substitution partnerships, and specialized equipment fabricators. Competitive moves concentrate on technology licensing arrangements and local content threshold compliance.
Within the state-linked tier, Rosatom anchors nuclear EPC expertise through long-term reactor construction programs. Inter Rao Ues OJSC occupies a position spanning conventional and renewable generation portfolios. PowerChina exemplifies the foreign contractor archetype leveraging infrastructure financing linked to Belt and Road initiatives. These three entities represent distinct pathways to market access: domestic regulatory alignment, diversified technology coverage, and cross-border capital deployment.
| Leading Market Players |
|---|
| Inter Rao Ues OJSC |
| Rosatom |
| JSC Atomenergoprom |
| VELESSTROY |
| RusHydro |
| OJSC Power Machines |
| Siemens AG |
| PowerChina |
| Enka İnşaat ve Sanayi AS |
| Others |
Value Network & Pricing Analysis
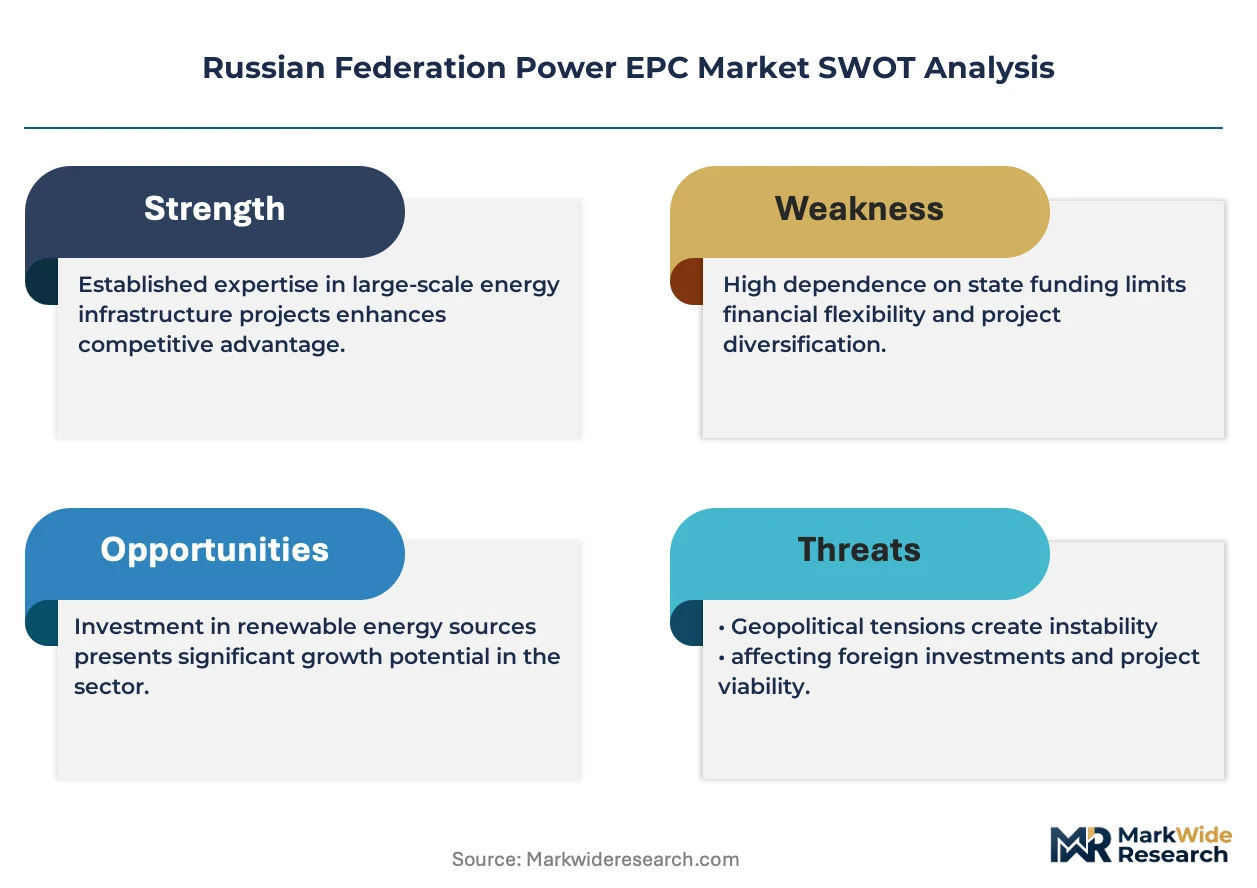
Domestic blade casting capacity constraints in the Central Federal District concentrate margin capture with foreign hot section component suppliers, while EPC contractors absorb procurement risk through indexed cost-plus structures. Sanctions-adjusted equipment sourcing has compressed contractor margins on high-voltage switchgear and digital control systems.
Pricing Analysis
Cost-plus contracts with steel and copper indexation dominate thermal and transmission EPC awards. Price differentiation separates nuclear-certified contractors from standard thermal operators based on Rostekhnadzor documentation depth and digital twin platform integration. Pricing pressure stems from import substitution requirements extending procurement lead times for 750 kV equipment. State-backed utilities exhibit lowest price sensitivity due to reliability mandates, while independent power producers in the Ural Federal District negotiate aggressively on co-generation packages.
Supply Chain Analysis
Supplier-financing through extended payment terms and supply-chain credit facilities anchors equipment procurement for Siberian hydropower and Far East thermal projects. Critical components draw from China for high-voltage switchgear, Germany for protection relays, and South Korea for gas turbine auxiliaries. Raw material dependencies center on copper busbar, transformer core steel, and pipeline-grade alloy steel. Single-source vulnerability concentrates in heavy-frame gas turbine rotor forgings. Distribution runs through Saint Petersburg and Vladivostok port clusters for import substitution logistics.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Market fragmentation creates entry niches as Federal Grid Company digital substation mandates splinter procurement authority across regional network operators. Unbundling of long-term service agreements from initial EPC contracts opens specialist commissioning and aftermarket positions.
For Market Incumbents: Insulate market position through backward integration into domestic blade casting capacity and captive welding certification programs in the Central Federal District. Secure exclusive digital twin platform licensing to lock out competitors from Federal Grid Company 110 kV and above mandates. Counter emerging Chinese EPC contractors by anchoring technology transfer provisions in state-directed capacity auctions. For New Entrants and Emerging Players: Establish a beachhead in 750 kV backbone line commissioning and protection system testing, where specialist engineer scarcity exceeds Federal Grid Company deployment targets. Target the Northwestern Federal District for digital substation integration projects requiring Soviet-era SCADA interface expertise. Lead with integrated engineering-procurement platforms that compress simulation-to-commissioning timelines. For Investors and Strategic Acquirers: Capital is best deployed toward mid-cap EPC contractors with established Rostekhnadzor certification track records and digital substation platform partnerships. Long-term viability rests on positioning for the Arctic Zone infrastructure buildout along the Northern Sea Route energy corridor. Watch import substitution progress on high-voltage switchgear as the inflection signal for domestic supply chain maturity.| Strategic Initiative | Industry Significance |
|---|---|
| Digital Twin Platform Integration | Federal Grid Company mandates above 110 kV require integrated simulation-to-commissioning workflows. |
| Arctic Zone Infrastructure Buildout | Northern Sea Route development opens EPC scope for cold-climate substations and transmission lines. |
| Import Substitution Partnership | Domestic equipment sourcing requirements reshape supplier qualification protocols for high-voltage switchgear. |
| Commissioning Specialist Acquisition | Scarcity of 750 kV backbone line testing engineers creates margin expansion in energization services. |
| Co-Generation Service Unbundling | Ural Federal District petrochemical clusters separate EPC contracts from multi-year maintenance provisions. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of EIA data, IEA power sector reports, FERC-equivalent Russian regulatory filings, and project development databases covering Siberian and Far East capacity auctions. Utility planning officers, IPP project developers, EPC contractors, grid operators, and fuel supply specialists provided operational perspectives. Bottom-up project pipeline analysis triangulates against top-down macroeconomic and regulatory scenario modeling.
Forecast inputs include generation capacity tier, fuel source, project scale, regional grid type, and regulatory framework across the projection horizon. Segmentation dimensions cover thermal, hydro, solar, and wind technologies; gas turbine, steam turbine, photovoltaic, and hydroelectric equipment types; government, independent power producer, utility, and industrial end-user categories; and engineering, procurement, construction, and commissioning service scopes. CAGRs derive from regression analysis against historical capacity auction allocations and stated Federal Grid Company deployment targets.
Stress conditions across sanctions duration, import substitution velocity, and Rostekhnadzor approval timeline extension were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions about state-backed utility procurement continuity and digital substation mandate adherence. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Power Equipment
Gas Insulated Power Equipment Market
Power Equipment
Global Auxiliary Power Unit Market
Power Equipment
United Arab Emirates Power Market
Power Equipment
Portable Power Station Market
Power Equipment
United States Turbine Control Systems Market
Power Equipment
Asia-Pacific Gas Turbine MRO Market
Power Equipment
Digital Power Conversion Market
Power Equipment
Cogeneration Equipment Market
Power Equipment
Power Infrastructure Market
Power Equipment
North America SCR Power Controller Market
Power Equipment
Global Power Supply Market
Power Equipment
Magnetic Bearing Market
Power Equipment
SCR Power Controller Market
Power Equipment
United States Power Rental Market
Power Equipment
Variable Frequency Drive (VFD) Market
Power Equipment
Global Power System Simulator Market