
 Clean Steam Separator Market | 2026-2036
Clean Steam Separator Market Size, Share, and Industry Trends Forecast 2026-2036
Clean Steam Separator Market Outlook
Pharmaceutical manufacturing is expanding its share of clean steam separator procurement as sterile processing requirements tighten across injectable and biologic drug production. Spirax Sarco leverages its global service network to anchor long-term maintenance contracts in regulated facilities. Armstrong International differentiates through steam system integration expertise that reduces total installed cost for end users. TLV International competes on precision engineering standards aligned with Japanese pharmaceutical export requirements.
A clean steam separator is a pressure vessel engineered to remove entrained moisture, non-condensable gases, and particulate contaminants from saturated steam through centrifugal or gravity-based mechanical separation, typically constructed from 316L stainless steel with surface finishes meeting Ra 0.8 μm or better for hygienic service. Its primary purpose is to deliver dry saturated steam for sterilization, humidification, and direct-contact heating applications where product contamination risks are unacceptable. Vertical separators dominate installed base in pharmaceutical cleanrooms where floor space constraints favor upward flow geometry, while modular separator configurations represent the fastest-growing product category as facilities pursue phased capacity expansion with minimal shutdown windows. Mechanical separation technology sustains the largest technology share due to proven reliability and absence of consumable membranes, though membrane separation commands premium positioning in biotechnology applications requiring absolute particle retention guarantees.
The US FDA enforces steam quality guidelines under its current Good Manufacturing Practice framework that directly specify separator performance for sterile drug manufacturing, while the European EMA aligns with EN 285 steam sterilization standards that mandate moisture content below specified thresholds. ISO 8573 compressed air and steam purity classifications provide third-party validation benchmarks that manufacturers reference for multinational facility qualification. Stakeholders must monitor evolving EMA guidance on continuous manufacturing equipment validation, as real-time steam quality monitoring could reshape separator specification requirements and aftermarket sensor attachment demand.
Market Dynamics
Clean steam separator procurement is tightening around continuous manufacturing validation requirements, as pharmaceutical facilities retrofit batch sterilization infrastructure for real-time release testing protocols demanded by advanced therapy production.
Growth Catalysts
- EMA Continuous Manufacturing Guidance:The European regulator's draft framework on real-time release testing mandates redundant steam quality assurance, driving dual-separator installations in biologics suites.
- 316L Stainless Steel Supply Concentration:German and Swedish specialty steel mills anchor global hygienic-grade material availability, securing fabrication timelines for validated equipment.
- Cell and Gene Therapy Expansion:Viral vector production facilities require absolute steam purity for closed-system bioreactor sterilization, expanding addressable demand beyond traditional small-molecule pharmaceutical plants.
Market Restraints
- Specialized Welding Labor Scarcity:ASME Section IX-certified orbital welders for 316L sanitary tubing command 40-60% wage premiums over standard pressure vessel fabrication, constraining output expansion at OEM facilities.
- Electropolishing Capacity Bottleneck:Ra 0.4 μm surface finish requirements for biotechnology applications concentrate certified finishing houses in Switzerland and southern Germany, creating geographic supply risk.
- Legacy Steam Infrastructure Incompatibility:Pre-2010 pharmaceutical plants with carbon steel distribution headers face complete system replacement costs that delay separator upgrade cycles.
Strategic Opportunities
- India Pharmaceutical Manufacturing:CDSCO's alignment with PIC/S GMP standards is accelerating sterile injectable capacity buildout in Hyderabad and Ahmedabad, creating first-mover positioning for separator vendors with local validation support.
- Modular Skid Integration:Pre-fabricated clean steam generation and separation skids are compressing facility commissioning timelines by 30-40% compared to field-erected systems, favoring suppliers with modular fabrication capabilities.
- ISO 8573-1:2010 Class 0 Steam Certification:Third-party purity validation is becoming a procurement gate in multinational pharmaceutical tenders, creating service revenue streams for testing laboratories and equipment-integrated sensor suppliers.
Industry Challenges
- Commissioning and Qualification Timeline Compression:Facility validation protocols for steam systems now require 12-18 month documentation cycles, extending working capital deployment for separator OEMs and their pharmaceutical customers.
- Legacy DCS Integration Complexity:Separator sensor outputs must interface with 1990s-era distributed control systems prevalent in established pharmaceutical plants, requiring custom signal conditioning hardware that fragments product standardization.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Clean Steam Separator Market |
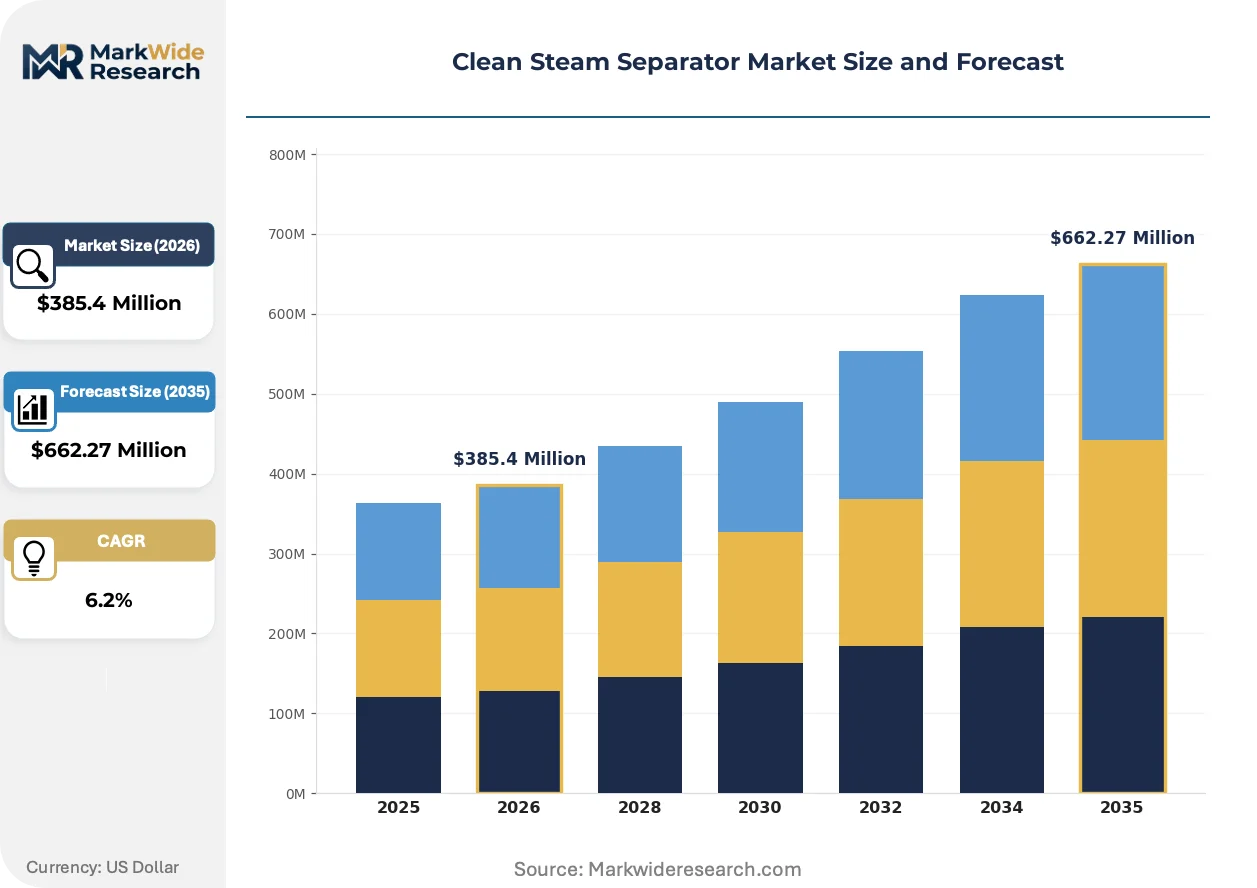
| Market Size in 2026 | $385.4 Million |
| Market Size in 2035 | $662.27 Million |
| CAGR (2026 – 2036) | 6.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Vertical Separator, Horizontal Separator, Modular Separator, Compact Separator End User: Pharmaceuticals, Food Processing, Biotechnology, Healthcare Application: Steam Sterilization, Humidification, Process Heating, Chemical Processing Technology: Membrane Separation, Flash Separation, Mechanical Separation, Others |
| Companies Covered | Spirax Sarco, Armstrong International, TLV International, GESTRA, Velan Inc., Forbes Marshall, Thermax Limited, Kadant Inc., Eaton Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Clean Steam Separator Market Strategic Shifts
Real-time steam quality monitoring is displacing periodic manual sampling in pharmaceutical facilities, compressing deviation response times from hours to minutes and reshaping separator specification requirements around integrated sensor architectures.
Condensate-powered pump technology is automating separator blowdown cycles without external utilities, eliminating compressed air consumption in cleanroom environments. Injectable drug manufacturers in Germany and Switzerland are specifying these self-actuating systems for new sterile processing lines. The technology is automating maintenance scheduling and reducing human intervention in classified spaces.
REACH Annex XVII restrictions on chromium(VI) compounds in surface treatment processes are forcing electropolishing chemistry transitions across European separator fabricators. Stainless steel finish houses in Bavaria and Baden-Württemberg are qualifying citric-acid-based passivation alternatives that maintain Ra 0.4 μm specifications. Biotechnology separator procurement in the European Union is absorbing 8-12% surface treatment cost premiums during this transition period.
Pharmaceutical engineering firms are consolidating equipment procurement under single-source validation responsibility contracts, displacing traditional multi-vendor bidding for steam system components. Large molecule drug sponsors in Massachusetts and North Carolina are awarding 10-year service agreements to integrated steam system providers. This bundling concentrates aftermarket revenue with primary equipment suppliers and raises barriers for standalone separator manufacturers lacking generation or distribution capabilities.
Clean Steam Separator Market Segmentation
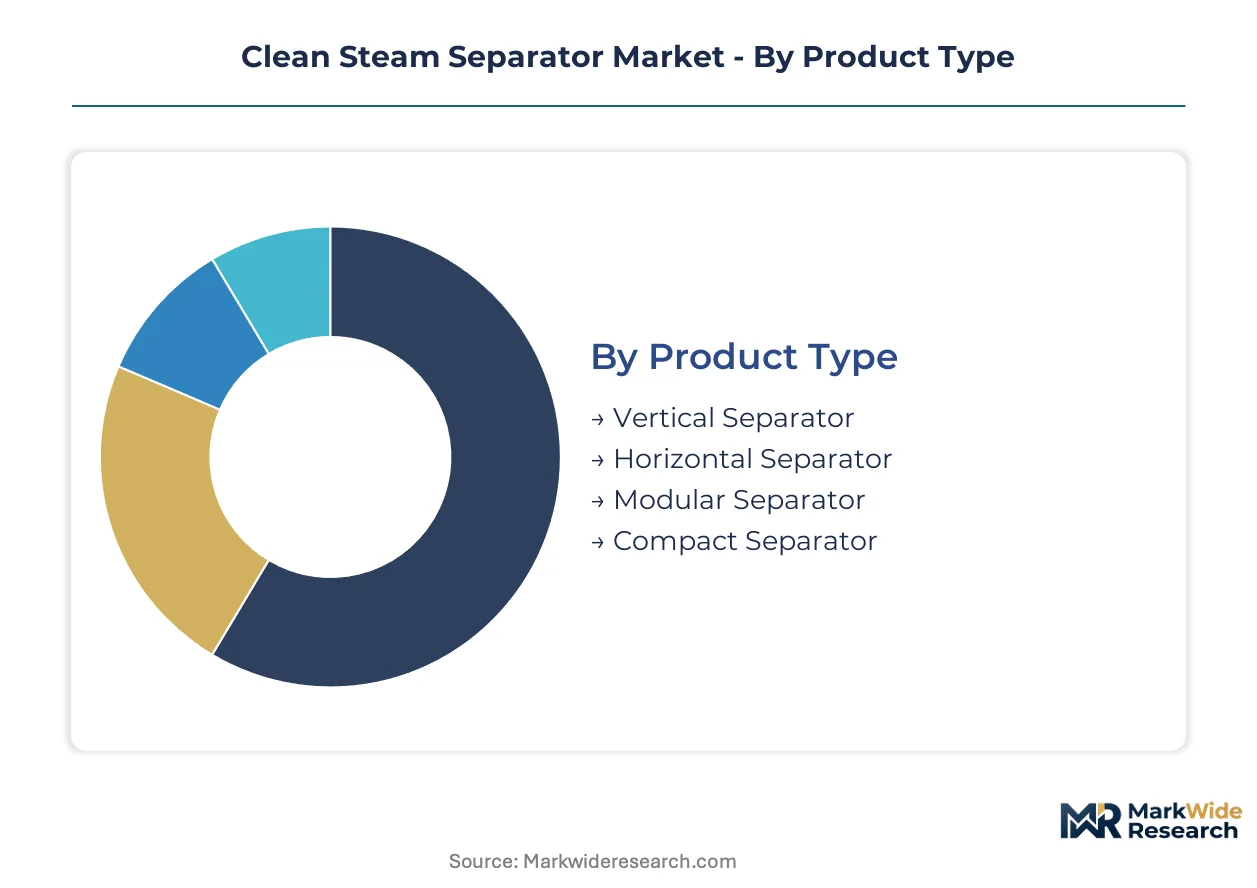
Clean steam separator procurement patterns diverge sharply across installation geometry, end-use sterility requirements, and separation technology reliability. Specification decisions cascade from facility layout constraints through regulatory compliance tiers to total cost of ownership calculations.
Product Type:
Facility footprint availability and cleanroom classification drive geometry selection more than raw performance metrics.
- Vertical Separator:Upward-flow cylindrical vessels minimize floor space consumption in classified pharmaceutical suites. Demand concentrates in Germany's Frankfurt pharmaceutical cluster where cleanroom square footage commands premium lease rates.
- Modular Separator:Pre-engineered skid-mounted units enable phased capacity expansion without production shutdowns. Biologics manufacturers in Switzerland and North Carolina specify these configurations for multi-product facility flexibility.
- Horizontal Separator:Low-profile vessels suit mechanical room installations with ceiling height constraints but adequate lateral space. Food processing plants in the US Midwest favor these for existing utility infrastructure compatibility.
- Compact Separator:Reduced-diameter units serve point-of-use installations near single bioreactor or autoclave connections. Cell therapy facilities in Massachusetts deploy these for closed-system sterility assurance.
Volume sits with vertical separators; growth tilts toward modular configurations.
End User:
Regulatory stringency tiers separate buyers by documentation burden and validation timeline tolerance.
- Pharmaceuticals:Injectable and biologic drug manufacturers face FDA and EMA steam quality mandates that specify separator performance thresholds. Facilities in Ludwigshafen and Research Triangle Park anchor procurement volume for validated 316L systems.
- Biotechnology:Viral vector and gene therapy producers require absolute particulate retention guarantees for closed-system bioreactor sterilization. CDSCO-aligned facilities in Hyderabad represent the steepest expansion trajectory as PIC/S GMP adoption accelerates.
- Healthcare:Hospital central sterile services departments balance ASME pressure vessel codes against budget constraints. Academic medical centers in the Northeast US concentrate replacement demand for aging carbon steel infrastructure.
- Food Processing:Aseptic packaging and dairy sterilization applications drive demand for hygienic-grade but non-validated separators. European dairy cooperatives specify these for UHT line steam injection systems.
Revenue concentrates in pharmaceutical applications; biotechnology is climbing the fastest.
Application:
Steam purity requirements escalate with direct product contact proximity and patient safety criticality.
- Steam Sterilization:Autoclave and SIP (sterilize-in-place) applications demand dry saturated steam with moisture content below EN 285 thresholds. Multi-national pharmaceutical tenders now require ISO 8573-1 Class 0 certification as a procurement gate.
- Process Heating:Direct-contact heating of pharmaceutical intermediates tolerates slightly elevated moisture content but mandates particulate exclusion. Continuous manufacturing retrofits in Ireland and Singapore are reshaping specification requirements around real-time quality monitoring.
- Humidification:Cleanroom environmental control systems prioritize non-condensable gas removal over extreme dryness. Biotechnology suite expansions in South Korea specify integrated separator-humidifier skids.
- Chemical Processing:Specialty chemical and API synthesis applications balance corrosion resistance against capital cost. Indian API manufacturers in Ahmedabad procure these for reactor jacket heating systems.
Installed base tilts toward sterilization; humidification is gaining share fastest.
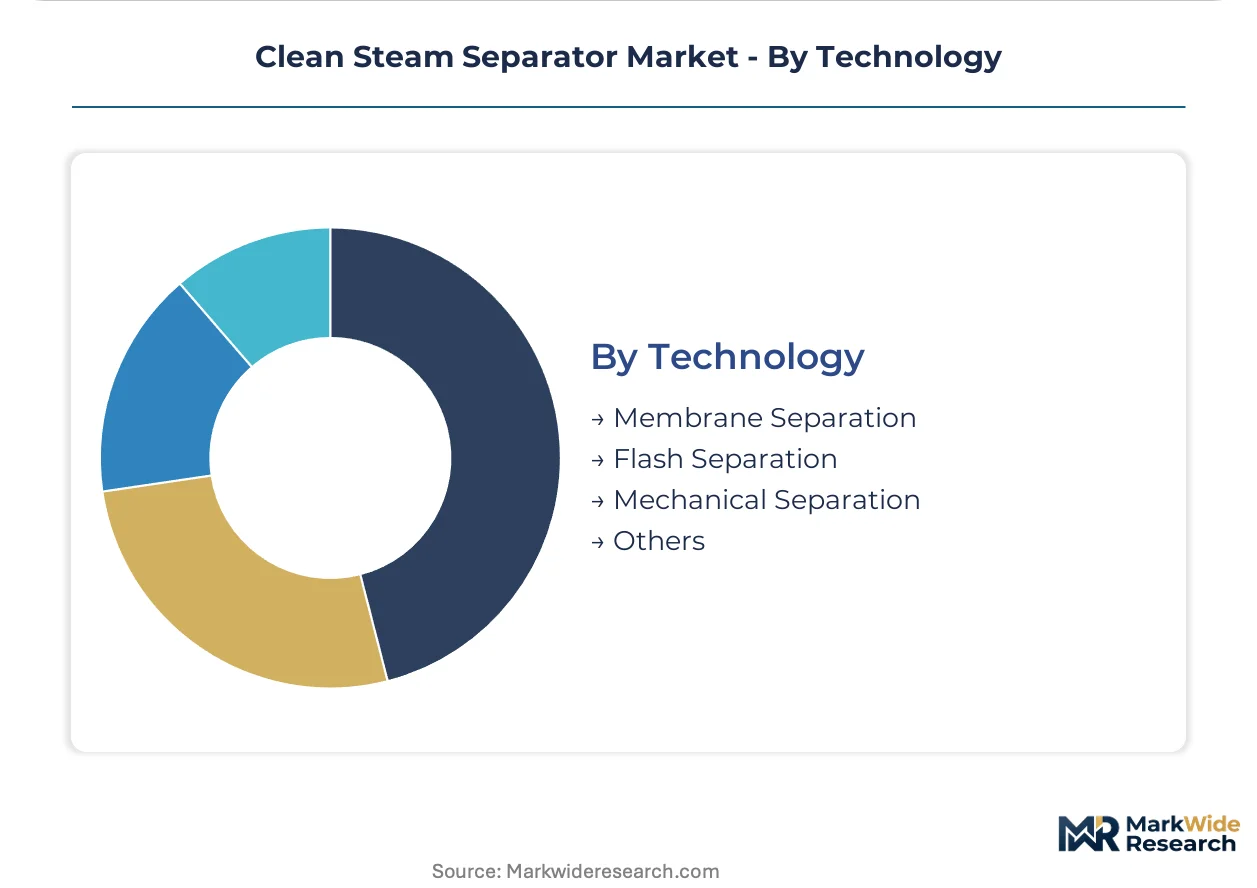
Technology:
Reliability verification timelines and consumable absence separate proven mechanical approaches from membrane precision.
- Mechanical Separation:Centrifugal and gravity-based moisture removal operates without replacement membranes or chemical regeneration. German pharmaceutical fabricators default to this technology for 20-year equipment life projections.
- Membrane Separation:Absolute particle retention guarantees serve biotechnology applications where viable organism exclusion is non-negotiable. Swiss gene therapy facilities specify these for viral vector production suite steam supply.
- Flash Separation:Pressure-drop-driven moisture removal offers intermediate purity with reduced mechanical complexity. Food aseptic processing lines in France deploy these for intermediate steam quality requirements.
- Others:Hybrid and emerging separation approaches including electrostatic precipitation occupy niche positioning. Japanese pharmaceutical exporters evaluate these for next-generation continuous manufacturing integration.
Deployment volume rests with mechanical separation; membrane systems are expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Special Economic Zones in Hyderabad and Ahmedabad concentrate Indian pharmaceutical manufacturing investment, while German industrial clusters anchor European separator fabrication capacity. Tax incentives for sterile injectable production in Gujarat and Telangana reshape procurement geography. Regulatory alignment with PIC/S GMP standards accelerates facility qualification timelines across emerging manufacturing hubs.
United States
FDA enforcement of current Good Manufacturing Practice steam quality guidelines drives separator deployment in sterile drug manufacturing. Massachusetts and North Carolina biologics clusters anchor procurement volume for validated 316L systems. Large molecule drug sponsors in these states award long-term service agreements to integrated steam system providers.
Germany
EMA continuous manufacturing guidance mandating redundant steam quality assurance propels dual-separator installations in biologics suites. REACH Annex XVII restrictions on chromium(VI) compounds force electropolishing chemistry transitions across Bavarian and Baden-Württemberg fabricators. The Frankfurt and Ludwigshafen pharmaceutical clusters concentrate demand for vertical separators where cleanroom square footage commands premium lease rates.
India
CDSCO alignment with PIC/S GMP standards accelerates sterile injectable capacity buildout in Hyderabad and Ahmedabad. The country's national pharmaceutical regulator mandates documentation protocols that extend equipment qualification timelines. Contract manufacturing organizations in these cities specify modular separator configurations for multi-product facility flexibility.
Switzerland
Swissmedic oversight of gene therapy production facilities enforces absolute steam purity requirements for closed-system bioreactor sterilization. Electropolishing capacity for Ra 0.4 μm surface finishes concentrates in certified finishing houses across the northern pharmaceutical corridor. Viral vector producers specify membrane separation systems for production suite steam supply.
Japan
PMDA export requirements for pharmaceutical steam systems align with precision engineering standards that TLV International and domestic fabricators target. METI industrial policy supports continuous manufacturing technology adoption in the Kanto and Kansai regions. Pharmaceutical engineering firms in these areas evaluate hybrid separation approaches for next-generation facility integration.
Clean Steam Separator Market Competitive Environment
Top-tier vendors anchor long-term validation contracts, while mid-scale fabricators compete on modular skid delivery speed. The vendor base stratifies across integrated steam system providers, standalone separator specialists, and regional fabrication houses. Three archetypes dominate: full-system integrators capturing bundled procurement, precision engineering specialists serving biotechnology applications, and scale-driven manufacturers addressing cost-sensitive healthcare markets. Competitive moves concentrate on modular fabrication capability expansion and aftermarket sensor integration partnerships.
Within the integrated-system tier, Spirax Sarco and Armstrong International occupy positions that exemplify service-network anchoring and steam system integration expertise respectively. TLV International represents the precision-engineering archetype aligned with Japanese pharmaceutical export requirements. These three companies illustrate how geographic origin and corporate structure shape competitive positioning: the UK-based limited company, the US-based international corporation, and the Japanese international specialist each anchor distinct value propositions without overlapping strategic territory.
| Leading Market Players |
|---|
| Spirax Sarco |
| Armstrong International |
| TLV International |
| GESTRA |
| Velan Inc. |
| Forbes Marshall |
| Thermax Limited |
| Kadant Inc. |
| Eaton Corporation |
| Others |
Value Chain & Pricing Dynamics
REACH Annex XVII restrictions on chromium(VI) compounds gate qualified electropolishing capacity and premium-tier pricing access for biotechnology-grade separators. German and Swiss finish houses absorb compliance-driven cost premiums while carbon-steel-dependent legacy facilities face displacement from validated procurement pools.
Pricing Analysis
Lead-time premiums compress standard delivery discounts for spot 316L inventory in pharmaceutical clusters. Three-tier pricing structure across validated, hygienic-grade, and industrial levels separates EMA-compliant documentation packages from basic ASME certification. Price differentiation rests on surface finish grade and integrated sensor architectures. Cost compression in standard-tier mechanical separators intensifies as Indian fabricators scale PIC/S-aligned capacity. Healthcare central sterile services departments exhibit highest price sensitivity; gene therapy viral vector producers show lowest.
Supply Chain Analysis
Warehouse-distribution networks for separator components concentrate in southern Germany and northern Switzerland for electropolished subassemblies. Raw material sourcing draws from Swedish and German specialty steel mills for 316L plate, Italian valve component suppliers, and Swiss sensor integrators. Single-source vulnerability concentrates in certified orbital welding labor pools. Distribution runs through OEM-direct channels for validated pharmaceutical systems and regional distributors for healthcare replacement demand.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a cost-of-compliance story where EMA continuous manufacturing guidance erects documentation barriers that moat compliant incumbents against unvalidated competitors.
For Market Incumbents: Acquire certified electropolishing capacity in Switzerland and southern Germany to capture surface finish bottlenecks. Anchor long-term validation contracts with Massachusetts and North Carolina biologics sponsors through integrated steam system bundling. Defensive consolidation around modular skid fabrication compresses commissioning timelines for cell therapy facility expansions. Threat substitution from membrane separation in gene therapy applications demands precision engineering investment. For New Entrants and Emerging Players: The premium-to-economy price gap in Indian pharmaceutical manufacturing invites modular separator configurations with local qualification support. White-space targets concentrate in Hyderabad and Ahmedabad sterile injectable buildout where CDSCO alignment accelerates procurement. Penetrate through pre-fabricated skid partnerships with regional engineering firms. Go-to-market leverage rests on PIC/S documentation templates that compress validation timelines. For Investors and Strategic Acquirers: Dual-separator installation mandates in EMA biologics suites are the leading indicator that redundant steam quality assurance is becoming standard specification. Long-term viability favors integrated steam system providers with captive validation service revenue. Target acquisition archetype: precision fabrication specialists with ASME U-stamp and ISO 8573 testing integration. Watch for real-time sensor attachment demand inflection in continuous manufacturing retrofits.| Strategic Initiative | Industry Significance |
|---|---|
| Modular Skid Fabrication Expansion | Compresses facility commissioning timelines by 30-40% for biologics manufacturers in Switzerland and North Carolina. |
| Electropolishing Capacity Acquisition | Captures REACH-driven supply bottleneck for Ra 0.4 μm surface finishes in Bavarian and Baden-Württemberg corridors. |
| Real-Time Sensor Integration Partnership | Positions separator architectures for EMA continuous manufacturing validation requirements in viral vector production. |
| Local Validation Support Buildout | Enables first-mover positioning in Hyderabad and Ahmedabad PIC/S-aligned sterile injectable capacity expansion. |
| Long-Term Service Agreement Structuring | Concentrates aftermarket revenue with primary equipment suppliers in Massachusetts and North Carolina biologics clusters. |
Study Parameters
Trade association data, regulatory filings, and customs records anchored secondary inputs for this analysis. Primary interviews with pharmaceutical engineering directors, cleanroom facility managers, ASME-certified fabricators, and steam system maintenance heads combined with FDA guidance documents, EMA submissions, ISO 8573 certification databases, and specialty steel import records. Bottom-up equipment procurement tracking and top-down pharmaceutical capital expenditure analysis enabled triangulation across data streams.
Data-stream reconciliation across shipment records, facility qualification timelines, and regulatory filing patterns shaped the analytical framework across the analysis window. Segmentation dimensions modeled include separator geometry, end-use sterility tier, application purity requirement, and separation technology reliability class. CAGRs derived from facility expansion pipeline tracking and validated equipment procurement cycles. Industry-specific forecast inputs incorporated electropolishing capacity utilization and orbital welding labor availability.
Inputs from EMA draft guidance releases and CDSCO regulatory alignment announcements were available through the study window; gaps in real-time continuous manufacturing adoption rates introduce uncertainty bands around sensor-integrated separator demand projections. Forecasts reflect documented assumptions regarding REACH compliance timelines and PIC/S GMP adoption velocity. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Power Equipment
Power Equipment Testing Market
Power Equipment
Equatorial Guinea Power EPC Market
Power Equipment
United States Power Rental Market
Power Equipment
Thailand Power EPC Market
Power Equipment
Power Generation Equipment MRO Market
Power Equipment
Power Recovery Winches Market
Power Equipment
Qatar Power EPC Market
Power Equipment
Ecuador Power EPC Market
Power Equipment
Natural Gas Turbine Market
Power Equipment
Brazil Power EPC Market
Power Equipment
China Power EPC Market
Power Equipment
India Power EPC Market
Power Equipment
Industrial Power Transmission Drive Belts Market
Power Equipment
Wind Tunnel Fans Market
Power Equipment
Asia-Pacific Gas Turbine MRO Market
Power Equipment
Germany Power EPC Market