
 Quenching Oil Market | 2026-2036
Quenching Oil Market Size, Share, and Industry Trends Forecast 2026-2036
Quenching Oil Market Outlook
Buyer concentration among automotive manufacturers is rebalancing as electric vehicle drivetrain producers fragment the traditional customer base alongside established internal combustion engine suppliers. ExxonMobil leverages its integrated base oil supply network to maintain cost positions in mineral oil formulations. Castrol differentiates through technical service partnerships with aerospace heat treatment facilities. FUCHS anchors European demand with localized blending capacity and OEM approvals.
Quenching oil is a heat transfer fluid engineered with controlled cooling rates, typically formulated from refined mineral bases or synthetic esters with viscosity indices between 20 and 100 cSt at 40°C, designed to achieve specific metallurgical microstructures in steel components. Mineral oil formulations still dominate volume shipments due to entrenched infrastructure and lower unit costs, though bio-based alternatives are capturing margin pools as sustainability premiums widen. Synthetic oil grades lead in aerospace surface hardening applications where repeatable distortion control justifies higher expenditure.
EPA regulations in the United States govern spent oil disposal and workplace exposure limits, while REACH in Europe restricts aromatic content and mandates biodegradability disclosures for metalworking fluids. These frameworks elevate compliance costs for mineral oil producers while creating technical barriers that favor reformulated and bio-based product lines. Stakeholders must monitor evolving state-level carbon accounting rules and OEM supplier scorecards that increasingly embed lifecycle emissions criteria into procurement decisions.
Market Dynamics
REACH biodegradability mandates and EU Green Deal carbon accounting rules are forcing mineral oil reformulation across European heat treatment operations, while precision-hardened transmission component demand from automotive manufacturers pulls premium synthetic grades into volume production.
Growth Catalysts
- Automotive transmission hardening:Precision-hardened gears and shafts for dual-clutch and electric drivetrain systems require controlled-cooling quenching oils with repeatable distortion profiles. Tier suppliers in Germany's industrial corridor anchor this demand.
- REACH aromatic restrictions:The European Chemicals Agency's limits on polycyclic aromatic hydrocarbons in metalworking fluids accelerate bio-based ester adoption among tool-making clusters seeking OEM approval compliance.
- Aerospace surface hardening:Landing gear and turbine component manufacturers specify synthetic grades for distortion-critical applications, creating margin pools that offset higher formulation costs.
Market Restraints
- Base oil supply concentration:API Group I and II mineral base stocks concentrate among integrated refiners in the US Gulf Coast and Rotterdam, exposing blenders to feedstock allocation risk during turnaround seasons.
- Biodegradability testing costs:OECD 301B and 306 biodegradability certification for bio-based formulations adds EUR 15,000-40,000 per product line, compressing margins for mid-cap regional blenders.
- Aqueous polymer substitution:Polyalkylene glycol quenchants capture low-distortion applications in automotive stampings, displacing oil in geometries where oxidation staining is unacceptable.
Strategic Opportunities
- India heat treatment expansion:The country's PLI scheme for automotive components and tooling is attracting hardening service capacity to Pune and Chennai industrial zones, creating first-mover positioning for bio-based suppliers.
- Used oil regeneration:Vacuum distillation and hydrotreating technologies enable closed-loop quenching oil recovery, aligning with OEM supplier scorecards that now embed lifecycle emissions criteria.
- ISO 9001/IATF 16949 bundling:Technical service partnerships that combine fluid supply with metallurgical process certification address skill gaps among smaller heat treatment job shops.
Industry Challenges
- Metallurgical technician scarcity:Heat treatment process engineering expertise concentrates among aging workforces in Germany and Japan, constraining quality consistency at new capacity installations.
- Reformulation timeline compression:REACH sunset dates for existing mineral oil registrations force 18-24 month product redevelopment cycles that disrupt customer qualification pipelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Quenching Oil Market |
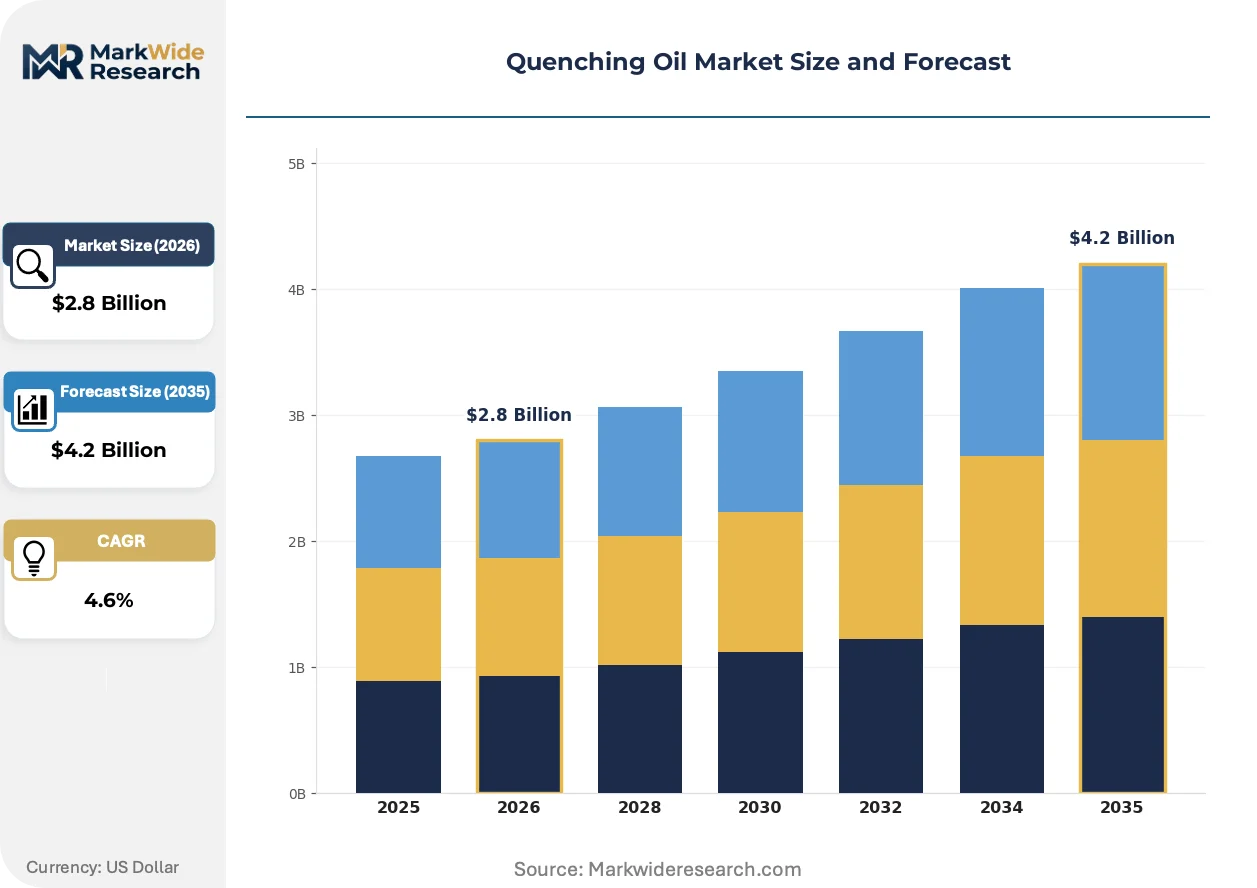
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $4.2 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Mineral Oil, Water-Soluble Oil, Synthetic Oil, Bio-Based Oil Application: Metal Hardening, Surface Hardening, Annealing, Quenching End User: Automotive Manufacturers, Aerospace Companies, Tool Making, General Engineering Distribution Channel: Direct Sales, Distributors, Online Sales, Retail Stores |
| Companies Covered | ExxonMobil, Castrol, FUCHS, Valvoline, Chevron, Idemitsu Kosan, TotalEnergies, Lukoil, Gulf Oil-Houghton, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Quenching Oil Market Strategic Shifts
Formulation chemistry is pivoting from viscosity-grade competition to controlled-cooling curve engineering, while regulatory disclosure requirements and buyer sustainability scorecards restructure how value is captured across the supply chain.
Synthetic ester formulations with tailored cooling curves are overtaking mineral oil in precision hardening applications. Aerospace landing gear manufacturers and automotive transmission suppliers specify these grades for distortion control within 50 microns. The technology is compressing price competition on viscosity index alone and forcing mineral oil blenders to add technical service capabilities.
EU Green Deal carbon border adjustments and ECHA substance of very high concern listings are tightening disclosure requirements for metalworking fluid imports. Heat treatment facilities must now document cradle-to-gate emissions for quenching oils in scope 3 supplier assessments. German automotive OEMs are the most affected, requiring reformulated products with certified renewable content shares.
Service contracts now unbundle fluid supply from metallurgical process optimization. Tier suppliers in Bavaria and Baden-Württemberg purchase quenching performance guarantees rather than volume commitments, with penalties tied to distortion rates and surface hardness variance. This model is most visible among transmission component manufacturers qualifying for electric vehicle platforms.
Quenching Oil Market Segmentation
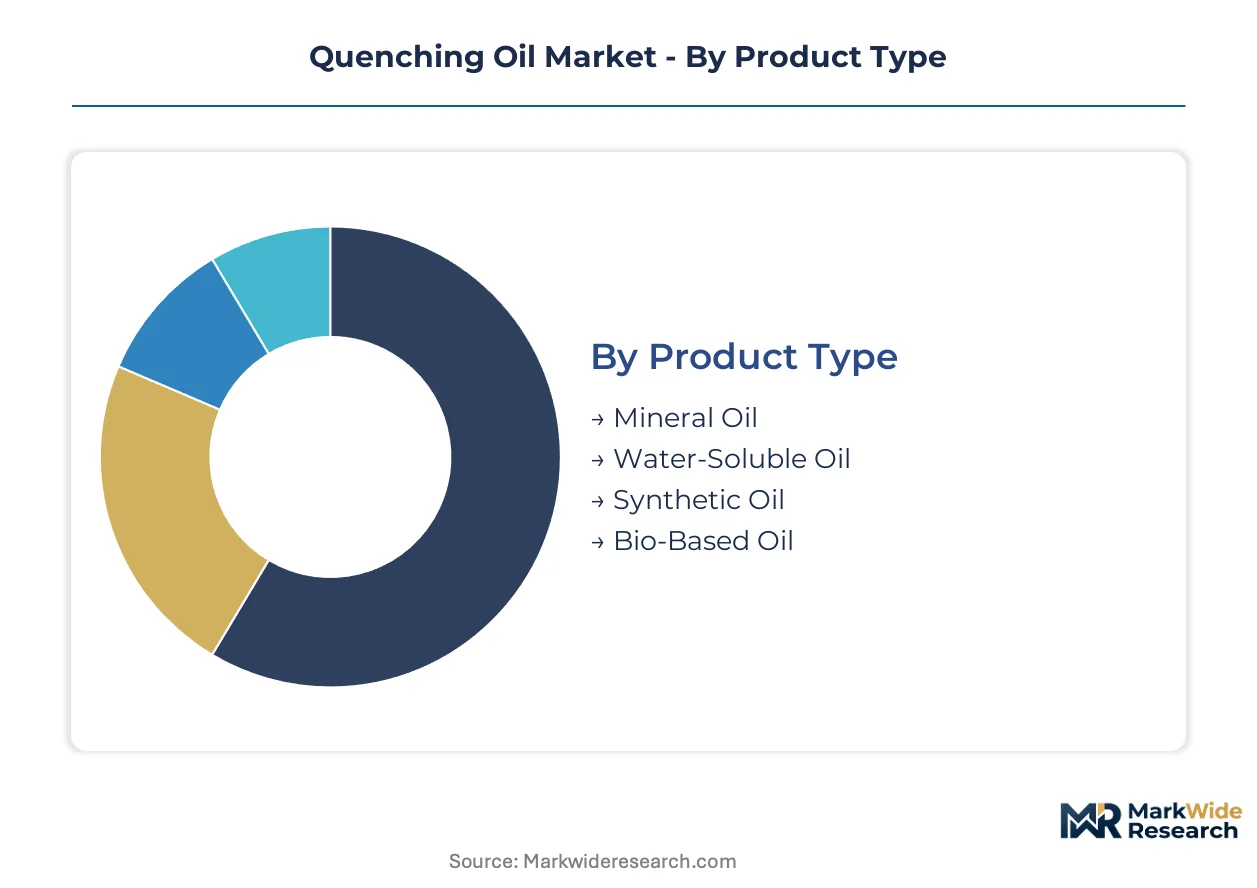
Quenching oil procurement patterns diverge sharply between precision-critical applications demanding tailored cooling curves and commodity heat treatment operations prioritizing cost containment. Segmentation reveals how formulation chemistry, metallurgical requirements, and channel economics partition buyers into distinct service tiers with diverging supplier relationships.
Product Type:
Standardization dominates high-volume mineral grades while synthetic and bio-based formulations require extensive customization for cooling curve engineering.
- Mineral Oil:Refined petroleum distillates with viscosity indices between 20 and 100 cSt at 40°C remain the default for general engineering hardening. German tool-making clusters and automotive tier suppliers in Stuttgart anchor volume demand despite REACH aromatic restrictions forcing gradual reformulation.
- Synthetic Oil:Polyalphaolefin and ester-based formulations deliver repeatable distortion control within 50 microns for aerospace landing gear and precision transmission components. Aerospace manufacturers in Toulouse and Hamburg specify these grades exclusively, creating margin pools that offset higher unit costs through reduced scrap rates.
- Water-Soluble Oil:Emulsifiable concentrates dilute to 5-15% oil content for fire safety in high-volume automotive stampings where oxidation staining must be minimized.
- Bio-Based Oil:Vegetable-derived esters with OECD 301B biodegradability certification command sustainability premiums from European OEMs embedding lifecycle emissions into supplier scorecards.
Leading the category by volume: Mineral Oil. Expanding most quickly: Bio-Based Oil.
Application:
Process temperature and cooling rate requirements stratify demand from distortion-critical surface hardening to bulk annealing operations.
- Metal Hardening:Through-hardening of gears, shafts, and bearings requires controlled martensite formation. Automotive transmission manufacturers in Bavaria specify premium grades with guaranteed cooling curve consistency for dual-clutch and electric drivetrain components.
- Surface Hardening:Induction and flame hardening of camshafts and rails demands oils with high flash points and minimal residue. Tool-making job shops in Solingen rely on technical service partnerships to optimize process parameters.
- Annealing:Slow, uniform cooling for stress relief in welded fabrications and castings prioritizes thermal stability over precision, favoring economy mineral grades.
- Quenching:General-purpose immersion hardening spans the full formulation spectrum from soluble oils for aluminum to synthetics for distortion-critical steel alloys.
Metal Hardening generates the largest revenue pool. Surface Hardening climbs the fastest as aerospace and precision automotive specifications tighten.
End User:
Buyer sophistication ranges from metallurgical engineering departments with in-house heat treatment expertise to procurement-driven general engineering shops.
- Automotive Manufacturers:Internal combustion engine suppliers and electric drivetrain producers fragment the traditional customer base. OEMs in Munich and Wolfsburg now require cradle-to-gate emissions documentation for all process fluids.
- Aerospace Companies:Landing gear and turbine component manufacturers specify synthetic grades exclusively, with Nadcap accreditation requirements filtering supplier pools to technically capable blenders.
- Tool Making:Heat treatment job shops in Germany's industrial corridor concentrate demand for premium mineral and bio-based formulations with localized technical support.
- General Engineering:Smaller fabricators and repair shops prioritize unit cost and local distributor availability over formulation sophistication.
Automotive Manufacturers command the largest procurement volumes. Aerospace Companies deliver the steepest margin expansion.
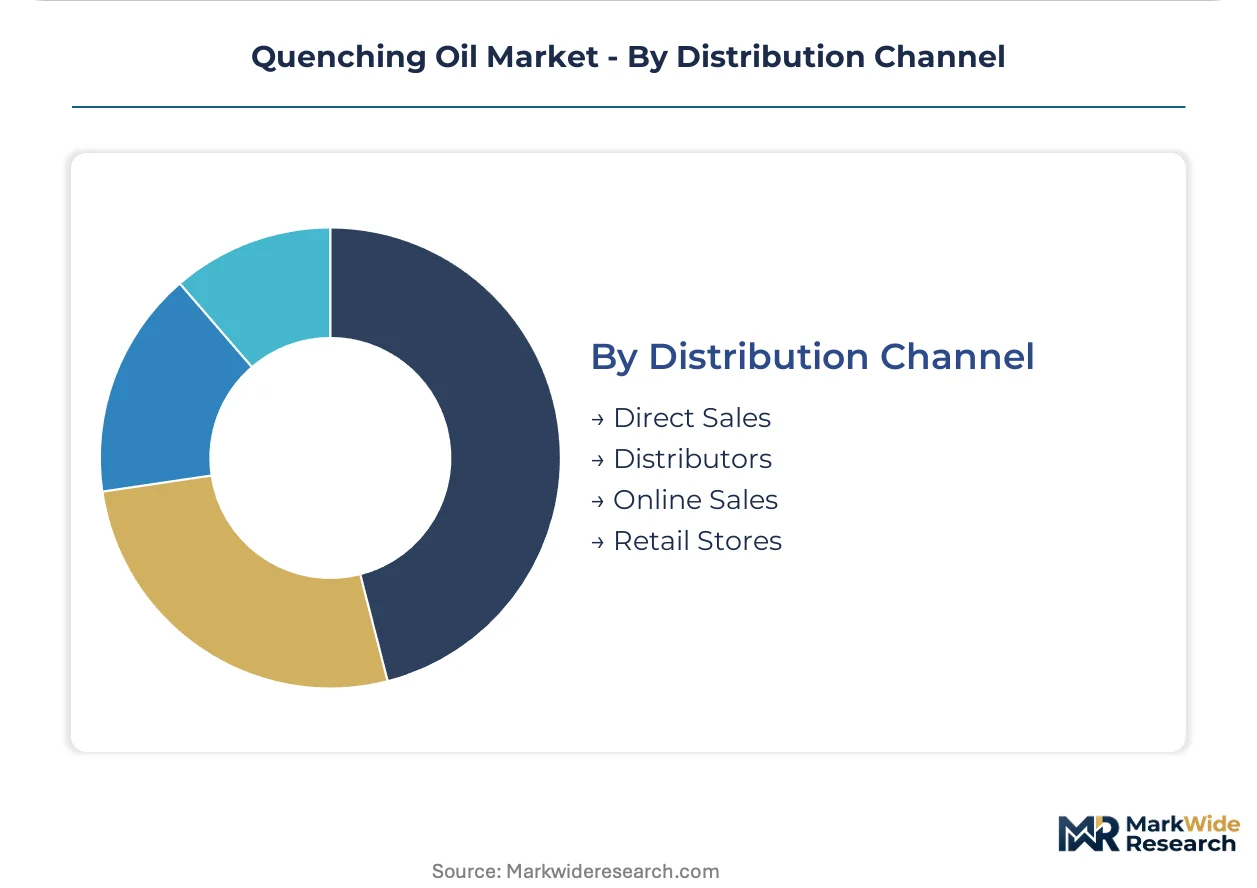
Distribution Channel:
Channel selection tracks buyer scale, technical service requirements, and geographic concentration of heat treatment capacity.
- Direct Sales:National accounts with dedicated metallurgical process engineers secure volume commitments and performance guarantees. Major automotive OEMs and aerospace primes in Germany negotiate direct relationships with formulation specialists.
- Distributors:Regional fluid distributors with blending and technical service capabilities serve mid-tier heat treatment job shops across Baden-Württemberg and North Rhine-Westphalia.
- Online Sales:Standard-grade mineral oils and soluble concentrates move through industrial e-commerce platforms for smaller general engineering accounts with predictable specifications.
- Retail Stores:Limited to emergency replenishment and maintenance-grade products for on-site repair operations.
Direct Sales captures the highest value per liter. Distributors maintain the broadest geographic coverage.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Base oil refining capacity along the US Gulf Coast and Rotterdam corridor anchors supply logistics for quenching oil blenders serving dispersed heat treatment demand.
Germany
Automotive transmission hardening for dual-clutch and electric drivetrain systems pulls premium synthetic grades into volume production. REACH aromatic restrictions and EU Green Deal carbon accounting rules force mineral oil reformulation across Baden-Württemberg and Bavaria. Stuttgart's tool-making clusters and Munich's tier suppliers concentrate demand for bio-based formulations with localized technical support.
United States
Aerospace landing gear manufacturers in Wichita and Seattle specify synthetic grades for distortion-critical surface hardening applications. EPA spent oil disposal regulations and OSHA workplace exposure limits elevate compliance costs for mineral oil producers. The US Gulf Coast's integrated refinery network exposes blenders to feedstock allocation risk during turnaround seasons.
China
Heat treatment capacity expansion for automotive components and industrial tooling drives consumption of economy mineral grades. MIIT industrial standards and dual carbon goals pressure domestic blenders toward lower-emission formulations. Yangtze River Delta manufacturing zones concentrate demand from precision machinery and automotive stampings operations.
India
The PLI scheme for automotive components and tooling attracts hardening service capacity to Pune and Chennai industrial zones. BIS standards for metalworking fluids create technical entry barriers for imported formulations. Maharashtra and Tamil Nadu's emerging heat treatment clusters favor first-mover positioning for bio-based suppliers seeking OEM supplier scorecard compliance.
Japan
Turbine component manufacturers and precision tool makers specify synthetic grades for repeatable distortion control within 50 microns. METI energy efficiency regulations and JIS standards for heat treatment fluids maintain high formulation quality thresholds. Nagoya's automotive supplier corridor and Osaka's machinery manufacturing belt anchor premium-grade consumption.
Quenching Oil Market Competitive Environment
Established producers occupy the standard tier; emerging entrants pursue bio-based certification and regional technical service partnerships. The supplier base concentrates among integrated petroleum majors with captive base oil supply and specialized lubricant blenders with metallurgical process expertise. Three archetypes dominate: Gulf Coast refiners with backward integration into Group I/II base stocks, European formulators with REACH-compliant bio-based portfolios, and regional distributors with localized blending and technical service capabilities. Competitive moves center on used oil regeneration technology licensing and ISO 9001/IATF 16949 certification bundling.
Within the integrated petroleum tier, ExxonMobil anchors North American supply through its base oil network, while TotalEnergies exemplifies European formulators navigating REACH compliance. Among specialized lubricant players, FUCHS occupies a position reflecting German industrial corridor density, and Castrol represents technical service-intensive positioning with aerospace heat treatment partnerships. These companies illustrate how supplier strategies diverge between cost-driven mineral formulations and premium synthetic grades.
| Leading Market Players |
|---|
| ExxonMobil |
| Castrol |
| FUCHS |
| Valvoline |
| Chevron |
| Idemitsu Kosan |
| TotalEnergies |
| Lukoil |
| Gulf Oil-Houghton |
| Others |
Value Chain & Pricing Dynamics
Automotive tier suppliers in Germany's industrial corridor concentrate procurement power for premium synthetic grades, forcing a contract-based pricing model with performance guarantees rather than volume commitments. REACH compliance costs and EU Green Deal carbon accounting rules embed sustainability premiums into supplier scorecards, restructuring how value is captured across formulation tiers.
Pricing Analysis
Volume shipments of mineral oil grades trade on thin margins through long-term offtake contracts with Stuttgart tool-making clusters, while synthetic and bio-based formulations command value-based pricing tied to distortion control performance. Price differentiation separates aerospace-certified synthetics from general engineering mineral grades, with certification level and after-sales metallurgical service as primary drivers. Cost compression in standard mineral tiers is intensifying because REACH aromatic restrictions force reformulation investments. General engineering job shops exhibit highest price sensitivity, while aerospace manufacturers accept premium positioning for Nadcap-accredited supply security.
Supply Chain Analysis
Base oil supply rests on integrated refiners concentrated along the US Gulf Coast and Rotterdam corridor, with API Group I and II mineral stocks feeding German blending operations. Formulation chemistry draws from petroleum distillates, vegetable-derived esters, and synthetic polyalphaolefin feedstocks. Single-source vulnerability concentrates around Rotterdam turnaround seasons, exposing Bavarian heat treatment facilities to allocation risk. Distribution runs through regional fluid distributors with localized blending and technical service capabilities serving Baden-Württemberg and North Rhine-Westphalia job shops.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
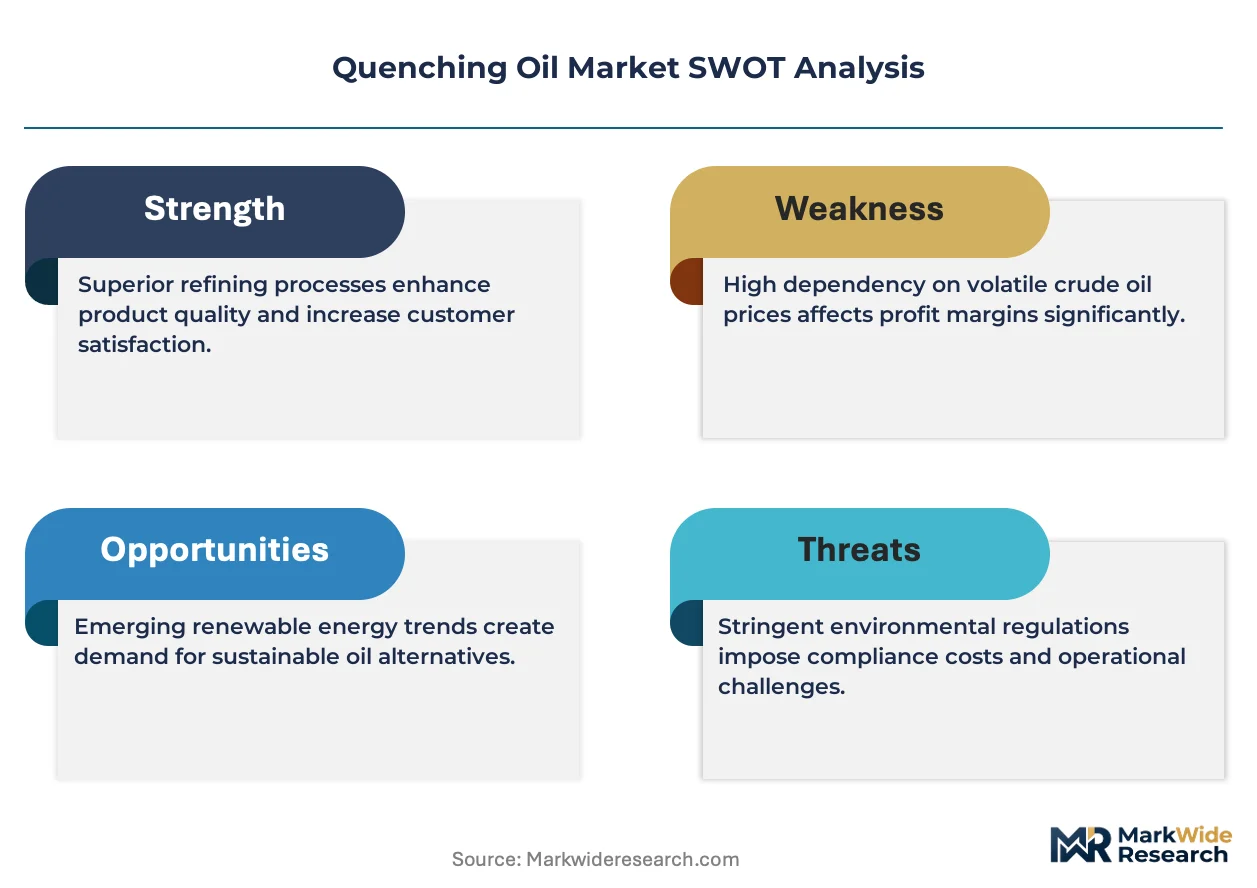
REACH biodegradability mandates and ECHA substance of very high concern listings construct a cost-of-compliance moat that favors incumbents with existing registration portfolios and technical service infrastructure, while squeezing mid-cap regional blenders unable to absorb certification costs.
For Market Incumbents: Lock in OEM supplier scorecard positioning by bundling ISO 9001/IATF 16949 metallurgical process certification with fluid supply contracts, defending against aqueous polymer substitution in automotive stampings through technical service partnerships that address skill gaps at smaller heat treatment job shops. Backward integration into used oil regeneration technology secures closed-loop recovery capabilities that align with lifecycle emissions criteria embedded in Munich and Wolfsburg procurement decisions. For New Entrants and Emerging Players: Bio-based ester formulations with OECD 301B certification offer a technology-first wedge into European OEM procurement channels, with India's PLI scheme for automotive components presenting the most penetrable geography for first-mover positioning in Pune and Chennai industrial zones. A technical service-heavy go-to-market approach that combines fluid supply with metallurgical process optimization addresses capability scarcity among emerging heat treatment capacity installations. For Investors and Strategic Acquirers: The window for entry favors specialized lubricant blenders with REACH-compliant bio-based portfolios and established aerospace heat treatment partnerships, with long-term viability hinging on regulatory compliance infrastructure rather than commodity scale. Acquisition targets should display localized blending capacity in Germany's industrial corridor alongside Nadcap accreditation for distortion-critical applications. The signal to watch is tightening EU carbon border adjustments that accelerate reformulation timelines and compress customer qualification pipelines for non-compliant suppliers.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Base Oil Supply | Captive access to API Group I and II feedstocks insulates German blenders from Rotterdam allocation disruptions. |
| REACH-Compliant Bio-Based Formulation Development | OECD 301B certification unlocks European OEM supplier scorecards embedding lifecycle emissions criteria. |
| Used Oil Regeneration Technology Licensing | Vacuum distillation capabilities align with Munich and Wolfsburg closed-loop recovery requirements. |
| ISO 9001/IATF 16949 Certification Bundling | Metallurgical process partnerships address technician scarcity at Baden-Württemberg heat treatment job shops. |
| Technical Service Partnership Expansion | Distortion rate guarantees rather than volume commitments capture Bavarian transmission component demand. |
Study Parameters
Multi-period observation of REACH registration timelines, OEM supplier scorecard evolution, and heat treatment capacity expansion anchored the trend analysis, supplemented by interviews with plant managers at German automotive tier suppliers, procurement leads at aerospace landing gear manufacturers, technical R&D directors at lubricant blenders, and distribution channel partners serving Solingen tool-making clusters. Secondary validation drew from ECHA substance registration databases, EU Green Deal policy disclosures, SEC filings of integrated petroleum majors, and customs data tracking base oil trade flows. Bottom-up heat treatment facility counts and top-down lubricant market sizing were triangulated to constrain volume estimates.
Segment-weighting across product type, application, end user, and distribution channel dimensions structured the analytical framework over the projection horizon. CAGRs were derived from regression analysis against automotive transmission production forecasts and aerospace component build rates, with synthetic grade penetration curves modeled against REACH sunset date impacts. Industry-specific inputs included hardening service capacity utilization rates in Germany's industrial corridor and OEM qualification pipeline durations for reformulated products.
Several conditions sit outside the modeled scope, including unannounced REACH substance restrictions, abrupt shifts in automotive drivetrain technology mix, and geopolitical disruptions to Rotterdam base oil logistics. Forecasts reflect documented assumptions about regulatory timeline adherence and OEM procurement inertia. A small set of named triggers warrants ongoing watch: ECHA polycyclic aromatic hydrocarbon limit revisions, EU carbon border adjustment implementation scope, and metallurgical technician training program expansion rates in emerging heat treatment clusters.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Petroleum Products
Petroleum Wax Market
Petroleum Products
Pygas (Pyrolysis Gasoline) Market
Petroleum Products
Balanos Oil Market
Petroleum Products
Naphtha Market
Petroleum Products
Paraffin Oil Market
Petroleum Products
Spiral Submerged Arc Welded (SSAW) Steel Pipe Market
Petroleum Products
West Africa Refined Petroleum Products Market
Petroleum Products
Liquefied Petroleum Gas Market
Petroleum Products
Global Petroleum Coke Market
Petroleum Products
Pyrolysis Oil Market
Petroleum Products
Nigeria Petrol Station Market
Petroleum Products
Crude Oil Market
Petroleum Products
Automotive Oil Market
Petroleum Products
Uganda Petroleum Products Market
Petroleum Products
Africa Refined Petroleum Products Market
Petroleum Products
Refined Petroleum Products Market