
 Wheel Cover Market | 2026-2036
Wheel Cover Market Size, Share, and Industry Trends Forecast 2026-2036
Wheel Cover Market Intelligence
The increasing fragmentation of buyers in the automotive aftermarket, facilitated by global e-commerce platforms, is repositioning the competitive landscape. Pilot Automotive leverages its extensive distribution network to serve both large retailers and independent repair shops. Custom Accessories specializes in licensed and themed designs, such as those from Realtree, appealing to niche consumer demographics. Plasticolor Inc. focuses on durable, molded products for a wide array of vehicle types, from passenger cars to commercial trucks.
A wheel cover is a decorative disk that attaches to a vehicle's wheel, concealing the hub and lug nuts. Primarily produced via injection molding from plastic, it shields wheel hardware from corrosion and road debris. While plastic dominates the product type segment for passenger vehicles due to its cost-effectiveness, the aftermarket dealer channel represents the largest end-user segment by volume. Sales to OEMs for base model vehicles, however, provide a stable revenue foundation.
Product standards are influenced by various national bodies. In the United States, materials must align with NHTSA safety guidelines, while Europe's REACH regulations restrict specific chemicals. China’s GB standards mandate quality and durability for all automotive components. Suppliers must continually balance the adoption of advanced materials against the cost pressures inherent in the mass-market aftermarket.
Market Dynamics
The dual pressure from automotive OEMs for lightweight components and consumer demand for aesthetic personalization defines the wheel cover market. This forces an innovation cycle balancing advanced material science against the cost pressures of mass production.
Growth Catalysts
- Advanced Injection Molding:New techniques enable complex designs and reduce cycle times, lowering costs for intricate covers appealing to the aftermarket segment.
- Automotive Production Growth:Expanding vehicle manufacturing in China and India creates sustained volume demand for OEM-fitted wheel covers on base models.
- E-commerce Channel Expansion:Online platforms allow manufacturers to directly reach consumers, fueling sales for custom designs in the fragmented aftermarket.
Market Restraints
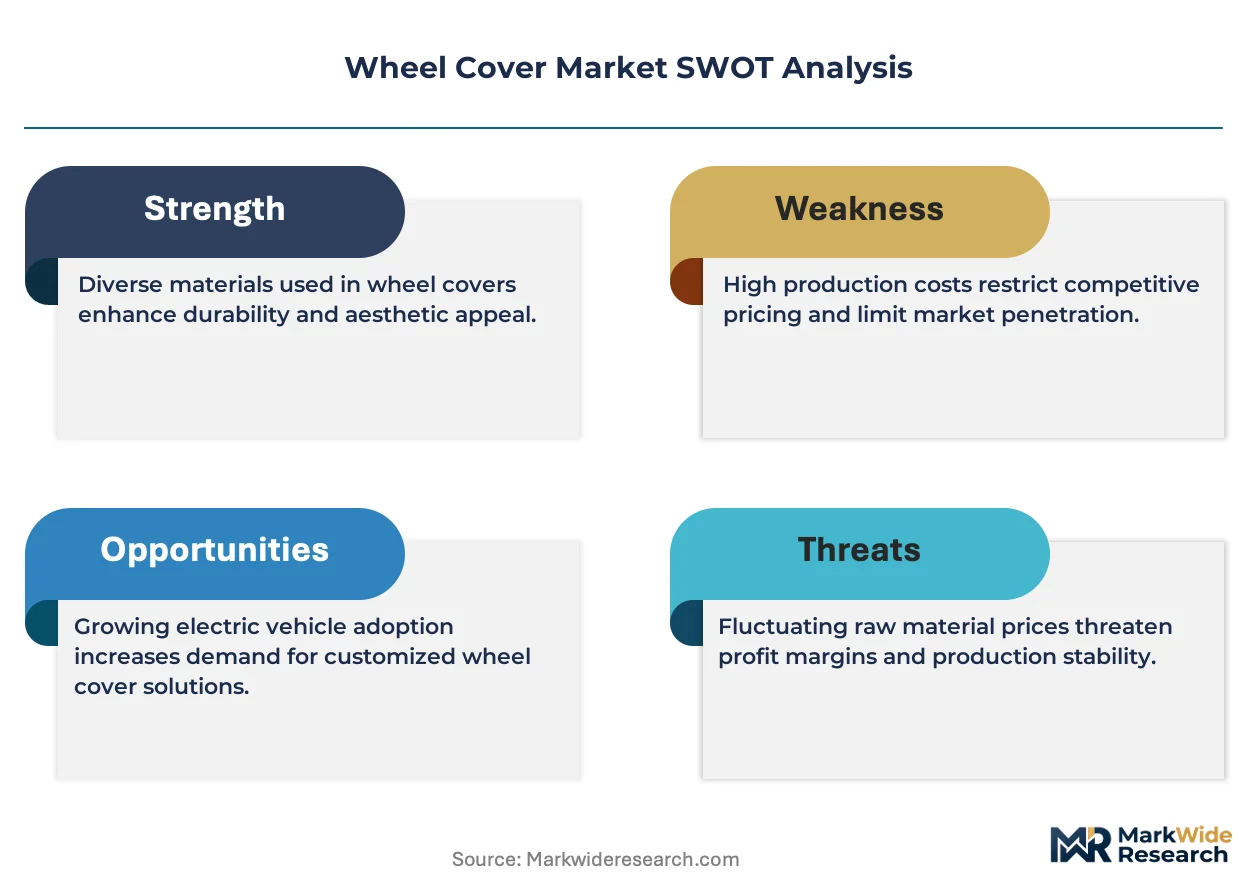
- Polymer Price Volatility:Fluctuations in polypropylene costs directly impact manufacturer margins, especially for suppliers serving the price-sensitive aftermarket.
- Alloy Wheel Proliferation:The increasing standardization of alloy wheels on mid-to-high-trim vehicles erodes the core market for wheel covers.
- Fragmented Regulatory Compliance:Adhering to disparate standards, like Europe's REACH and US NHTSA guidelines, increases testing and certification costs.
Strategic Opportunities
- Integration of Smart Features:Embedding sensors or LEDs into wheel covers creates new value for the premium aftermarket and electric vehicle segments.
- Sustainable Materials:Covers from recycled plastics appeal to consumers and OEMs targeting sustainability goals like those in the EU Green Deal.
- Commercial Vehicle Customization:Durable covers for light commercial vehicles offer a growth avenue beyond the saturated passenger car market.
Industry Challenges
- Design Piracy in Aftermarket:The ease of replicating popular designs erodes brand value and profitability for original designers.
- Fitment Standardization Gaps:Numerous wheel sizes and hub configurations complicate inventory management and increase product return rates.
- Balancing Cost and Durability:Suppliers must reduce costs for OEM contracts while meeting durability mandates like China’s GB standards, a difficult trade-off.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Wheel Cover Market |
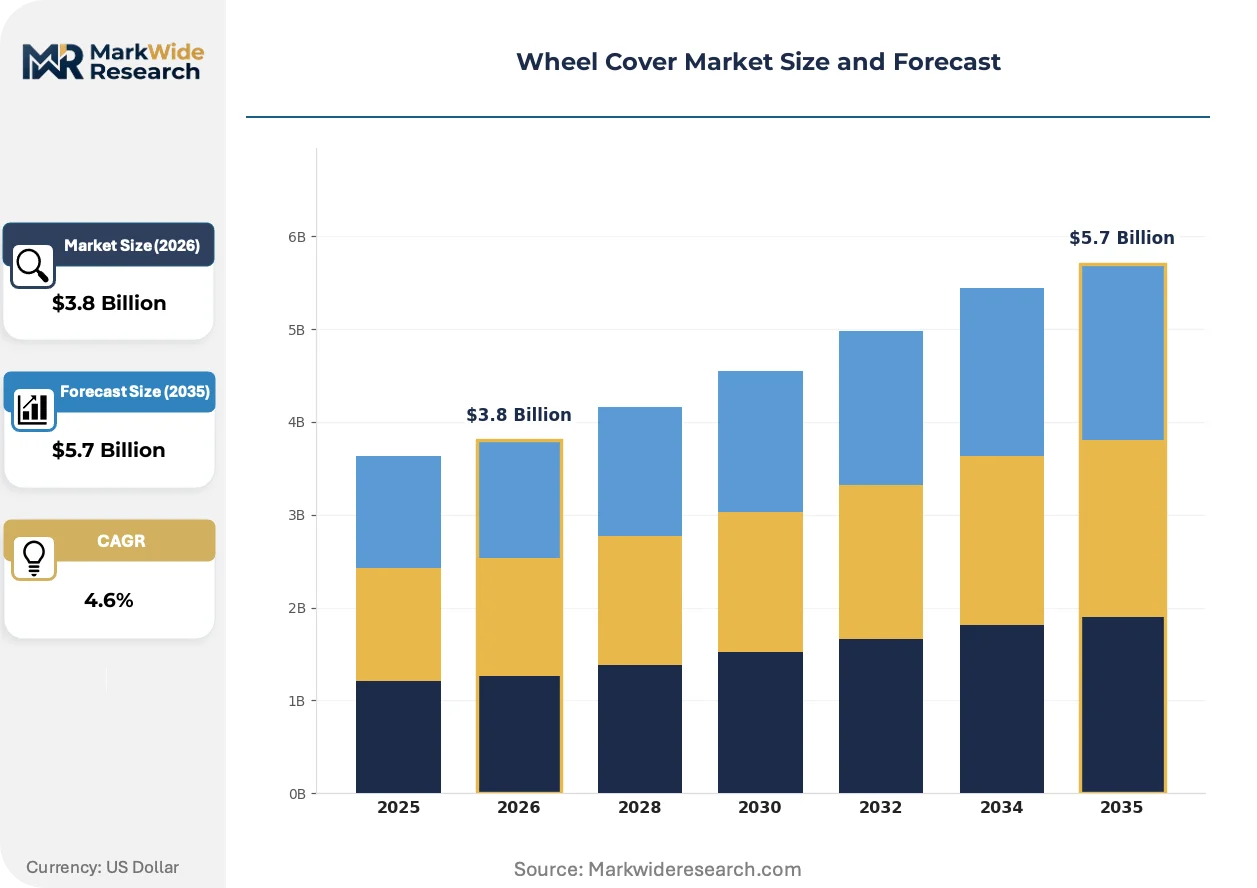
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $5.7 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Plastic, Metal, Alloy, Composite, Chrome Technology: Injection Molding, Vacuum Forming, Die Casting, Metal Stamping, Electroplating Application: Passenger Vehicles, Two-Wheelers, Commercial Trucks, Heavy Machinery, Specialty Vehicles End User: OEMs, Aftermarket Dealers, Fleet Operators, Vehicle Refurbishers |
| Companies Covered | Auto Drive Technologies, Pilot Automotive, Plasticolor Inc, Startech, Haas Outdoors, Inc - Mossy Oak, Bell Automotive Inc, Custom Accessories, Realtree, WheelSkins Inc, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Wheel Cover Market Strategic Shifts & Innovations
Material science advancements are converging with new digital retail models to redefine product value and market access. This interaction allows for greater product differentiation while simultaneously intensifying competition on a global scale.
Lightweight composite materials, including carbon fiber-reinforced plastics, offer significant weight reduction and design flexibility. Aftermarket suppliers and OEMs for electric vehicles are rapidly adopting these materials to improve vehicle range. As production scales, composite construction is overtaking conventional plastic as the standard for premium and performance-oriented wheel covers.
Europe's REACH regulation, which restricts certain chemicals in manufactured goods, is setting a de facto global standard. This forces supply chains to validate all inputs, from resins to pigments, to ensure compliance for market access. The passenger vehicle segment is most affected, with manufacturers reformulating products to avoid restricted substances.
The aftermarket is experiencing significant buyer fragmentation, driven by the accessibility of global e-commerce platforms. This trend disintermediates traditional distribution channels, allowing specialized manufacturers to connect directly with niche consumer groups. This shift is most visible in North America and Europe, where enthusiasts seek unique designs not available through conventional retailers.
Wheel Cover Market Segmentation
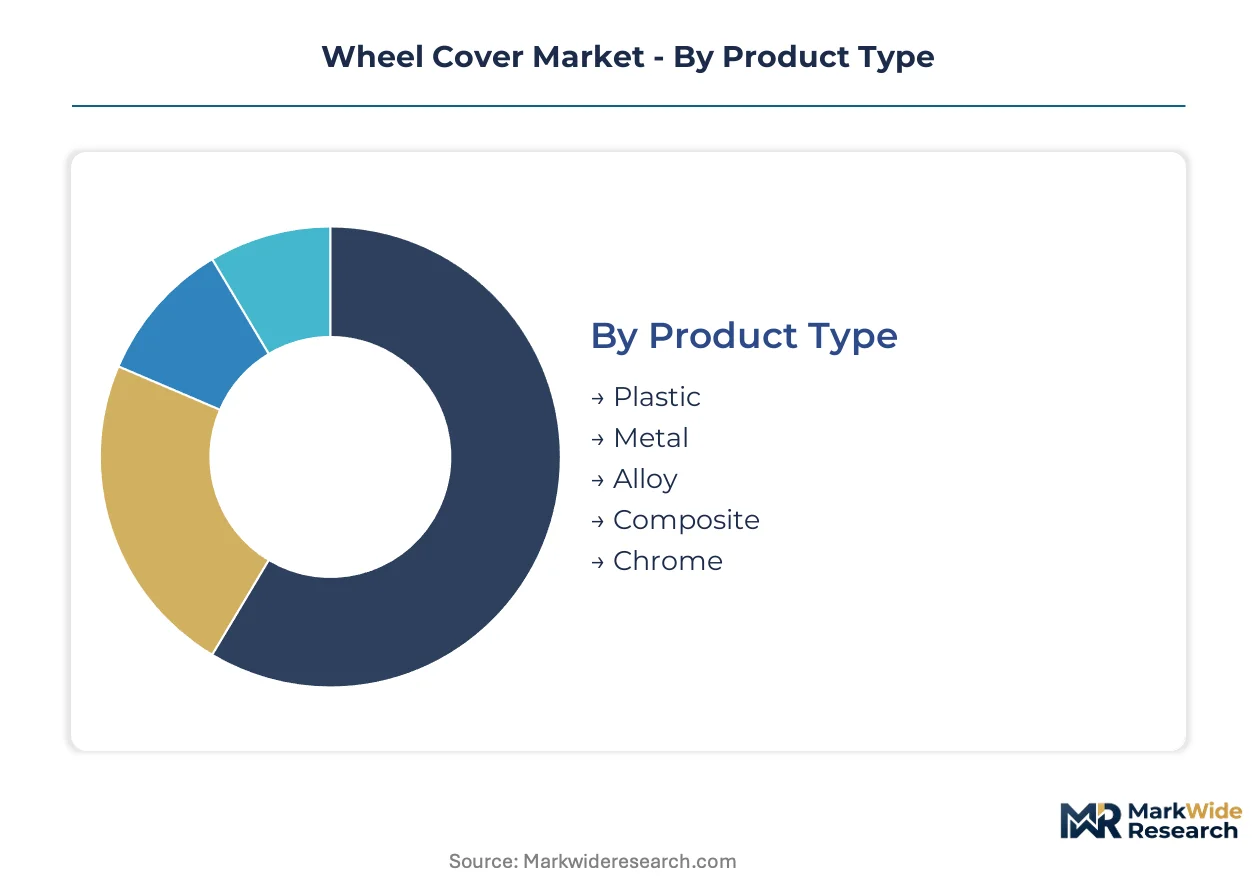
The wheel cover market's diverse product offerings and end-user requirements necessitate clear segmentation for strategic analysis. Understanding these distinct categories allows stakeholders to identify specific growth vectors and tailor product development initiatives. This detailed breakdown highlights varying material preferences and technological applications across different vehicle types.
Product Type:
Product type segmentation reveals how material choices dictate integration depth, ranging from purely aesthetic add-ons to components engineered for performance enhancements.
- Plastic:These wheel covers are predominantly manufactured through injection molding, offering cost-effectiveness and design versatility. Demand concentrates in the base model passenger vehicle segment, driven by OEM requirements for economical and easily customizable components.
- Composite:Utilizing advanced materials like carbon fiber-reinforced plastics, these covers prioritize lightweight construction and aerodynamic performance. Aftermarket suppliers and electric vehicle manufacturers in Europe are rapidly adopting composites to improve vehicle range and premium aesthetics.
- Metal:Metal wheel covers provide enhanced durability and a more robust appearance compared to plastic alternatives. They are often found on commercial vehicles.
- Alloy:Alloy wheel covers typically offer a premium aesthetic, mimicking the appearance of full alloy wheels without the higher cost. They appeal to consumers seeking an upgraded look.
- Chrome:Chrome finishes deliver a high-gloss, reflective appearance, primarily serving aesthetic customization in the aftermarket. This finish is popular in North America.
Volume placements concentrate in Plastic; the faster expansion belongs to Composite.
Technology:
Technology segmentation illustrates the diverse manufacturing processes employed, each optimized for specific material types and production scales across various applications.
- Injection Molding:This high-volume manufacturing process forms plastic wheel covers by injecting molten material into molds. The technique allows for intricate designs and cost-efficient production, predominantly serving the passenger vehicle OEM and aftermarket segments.
- Electroplating:Electroplating applies a metallic coating, such as chrome, onto plastic or metal substrates for enhanced aesthetics and corrosion resistance. This finishing process is crucial for aftermarket customization and premium product offerings, particularly in North America.
- Vacuum Forming:Vacuum forming shapes plastic sheets using heat and vacuum pressure, suitable for less complex designs and lower production volumes. This method finds use in specialized aftermarket applications.
- Die Casting:Die casting involves forcing molten metal into mold cavities under high pressure, producing durable metal wheel covers. It is common for heavy-duty commercial vehicle components.
- Metal Stamping:Metal stamping cuts and forms sheet metal into desired shapes, a cost-effective method for producing basic metal wheel covers. This technique is applied for simpler designs.
The dominant method for mass production is Injection Molding; specialized finishes often rely on Electroplating.
Application:
Application segmentation highlights how distinct vehicle categories impose unique design requirements and durability needs on wheel cover manufacturers.
- Passenger Vehicles:This segment represents the largest volume market for wheel covers, driven by aesthetic customization and OEM fitments on base models. Demand is high in China and India, where new vehicle sales continue to expand.
- Commercial Trucks:Wheel covers for commercial trucks emphasize durability, protection against road debris, and ease of maintenance. This application offers a growth avenue for robust, molded products beyond the saturated passenger car market.
- Two-Wheelers:Wheel covers for two-wheelers focus on lightweight design and aerodynamic profiles, often integrated for performance or specific aesthetic themes. This niche market is growing in Southeast Asia.
- Heavy Machinery:Wheel covers in this category provide extreme protection against harsh operating environments and physical impact. They prioritize functional integrity over aesthetics.
- Specialty Vehicles:This segment includes custom-built vehicles, emergency services, or off-road vehicles, requiring highly specialized and often custom-fabricated wheel covers. These covers address unique functional demands.
Demand stability originates from Passenger Vehicles; niche requirements define Specialty Vehicles.
End User:
End user segmentation reveals varied purchasing power and distribution channels, influencing product specifications and market access strategies for manufacturers.
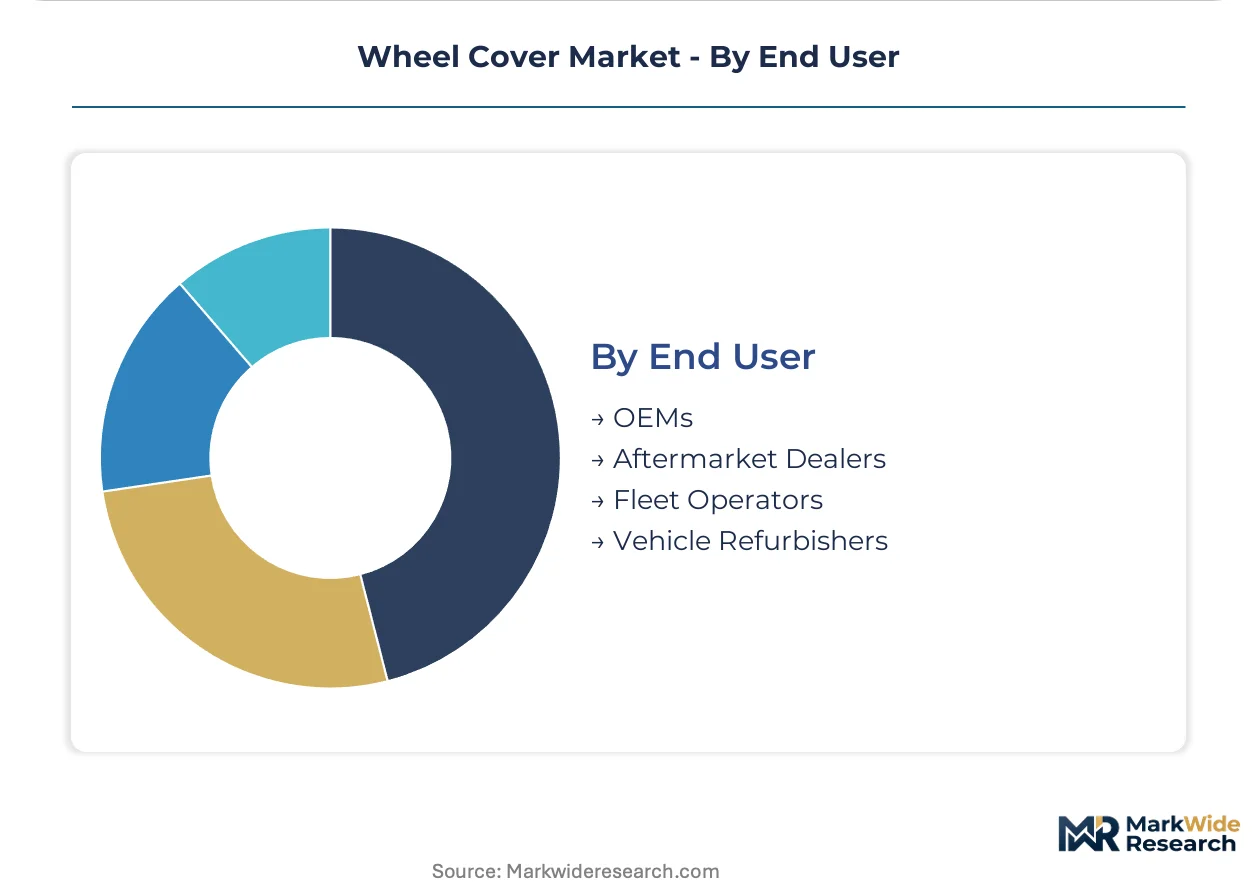
- Aftermarket Dealers:This segment represents the largest end-user channel by volume, catering to individual consumers seeking customization and replacement parts. Global e-commerce platforms facilitate direct connections between manufacturers and this fragmented buyer base in North America and Europe.
- OEMs:Original Equipment Manufacturers procure wheel covers for factory installation on new base model vehicles, providing a stable, high-volume revenue stream. These contracts demand strict adherence to quality standards like China’s GB standards.
- Fleet Operators:Fleet operators purchase durable and cost-effective wheel covers for large vehicle collections, prioritizing longevity and ease of replacement. Procurement focuses on bulk pricing and standardized designs.
- Vehicle Refurbishers:These entities acquire wheel covers for restoring used vehicles to marketable condition, often seeking cost-effective replacements or upgrades. Their demand is project-based and highly price-sensitive.
Scale procurement is characteristic of OEMs; fragmented purchasing defines Vehicle Refurbishers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Petrochemical production in China underpins a significant portion of global polymer supply for wheel covers. This region's robust manufacturing capabilities drive both OEM and aftermarket segments. Demand for wheel covers concentrates in major automotive production centers worldwide.
China
Expanding vehicle manufacturing in China creates sustained volume demand for OEM-fitted wheel covers on base models. China’s GB standards mandate quality and durability for all automotive components, influencing supplier practices. The Yangtze River Delta region, including Shanghai, sees significant investment in advanced injection molding facilities.
India
Automotive production growth in India fuels demand for cost-effective plastic wheel covers on new passenger vehicles. The Indian government's PLI scheme supports domestic manufacturing, encouraging local component sourcing. Chennai, a major automotive hub, experiences increased activity in aftermarket distribution for wheel covers.
United States
Aftermarket customization and replacement parts drive substantial wheel cover demand across the United States. Materials must align with NHTSA safety guidelines for automotive components, impacting product development. The Detroit automotive cluster continues to innovate in material science for lightweight vehicle parts.
Germany
Consumer demand for aesthetic personalization and lightweight components shapes the German wheel cover market. Europe's REACH regulations restrict specific chemicals, pushing manufacturers towards sustainable materials. The Bavaria region hosts numerous automotive suppliers focusing on premium and electric vehicle applications.
Brazil
The expanding passenger vehicle segment in Brazil generates consistent demand for both OEM and aftermarket wheel covers. Brazil's national automotive policies aim to stimulate local production and content, affecting import dynamics. São Paulo's industrial zone houses manufacturing plants catering to diverse vehicle segments.
Wheel Cover Market Key Industry Players
Established producers occupy the standard tier; emerging entrants pursue aesthetic customization and lightweight material integration for premium applications. The wheel cover market exhibits structural fragmentation, with numerous players serving distinct segments. Archetypes include large-scale OEM suppliers focused on volume, aftermarket customization specialists catering to niche tastes, and durable product manufacturers for commercial applications. Geographic expansion and continuous product innovation are dominant competitive moves shaping the market structure.
Aftermarket customization specialists like Custom Accessories, known for licensed and themed designs, exemplify players focusing on niche consumer demographics. Plasticolor Inc. occupies a position among manufacturers of durable, molded products, catering to a wide array of vehicle types from passenger cars to commercial trucks. Pilot Automotive, leveraging its extensive distribution network, represents a broader market approach, serving both large retailers and independent repair shops. These companies anchor market segments that prioritize either unique aesthetic designs, robust versatility, or wide distribution reach.
| Leading Market Players |
|---|
| Auto Drive Technologies |
| Pilot Automotive |
| Plasticolor Inc |
| Startech |
| Haas Outdoors, Inc - Mossy Oak |
| Bell Automotive Inc |
| Custom Accessories |
| Realtree |
| WheelSkins Inc |
| Others |
Cost & Logistics Intelligence
Polypropylene price volatility directly impacts wheel cover manufacturing costs, cascading through the supply chain into distinct pricing tiers for OEM and aftermarket segments. This commodity benchmark significantly influences final product pricing across diverse applications.
Pricing Analysis
Warranty and service bundling often remains unbundled for aftermarket wheel covers, while OEM contracts typically integrate quality assurance. Pricing stratifies across aesthetic, durability, and functional tiers, with customization level and adherence to standards like China’s GB standards driving differentiation. Pricing pressure intensifies in the mass-market aftermarket due to polymer price volatility and design piracy. Vehicle refurbishers represent the most price-sensitive segment, prioritizing cost-effective replacements.
Supply Chain Analysis
Reverse logistics for wheel covers primarily involve returns due to fitment standardization gaps, particularly in the aftermarket. Supply concentration centers on China for injection molding and polymer production, with India also emerging for cost-effective plastic manufacturing. Raw material dependencies include polypropylene and specialized resins for composites, creating commodity price volatility risk. Regulatory restrictions, such as Europe's REACH regulations, pose a structural risk, while distribution runs through established OEM channels and a fragmented aftermarket increasingly leveraging e-commerce platforms.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The wheel cover market operates under supply constraints, particularly due to the concentration of petrochemical production in China. This regional capacity bottleneck in polymer supply props up pricing for key raw materials like polypropylene.
For Market Incumbents: Anchor stable OEM contracts by investing in advanced injection molding facilities, particularly in growth regions like China and India. Pursue backward integration into specialized polymer or composite material production to mitigate polymer price volatility, a significant margin pressure point. Consolidate distribution channels to counter aftermarket fragmentation and design piracy threats. Develop next-generation composite materials for premium and EV segments, addressing alloy wheel proliferation.
For New Entrants and Emerging Players: Begin with niche aesthetic customization for the aftermarket, leveraging global e-commerce platforms to reach fragmented buyers in North America and Europe. Target commercial vehicle customization with durable, molded products, a less saturated segment than passenger cars. Integrate smart features like sensors or LEDs into wheel covers for premium aftermarket and electric vehicle segments. Emphasize sustainable materials from recycled plastics to align with consumer and OEM sustainability goals.
For Investors and Strategic Acquirers: Distressed-cycle entries favor vertically integrated mid-cap specialists in China and India, focusing on advanced injection molding capabilities. The long-term viability of the wheel cover market remains strong, driven by expanding vehicle production and customization trends. Target acquisition archetypes include firms specializing in lightweight composites or those with strong e-commerce distribution networks for the aftermarket. Monitor the adoption rate of sustainable materials and smart features by OEMs as a key inflection indicator.
| Strategic Initiative | Industry Significance |
|---|---|
| Capacity Expansion | Expanding advanced injection molding facilities in China supports growing OEM and aftermarket demand. |
| Product Launch | Introducing smart features like sensors and LEDs creates new value in the premium aftermarket. |
| Green Manufacturing Transition | Utilizing recycled plastics aligns with EU Green Deal goals and consumer preferences for sustainability. |
| Distribution Channel Expansion | Leveraging e-commerce platforms allows direct access to fragmented aftermarket buyers globally. |
| Platform Standardization | Reducing fitment standardization gaps streamlines inventory and decreases product return rates. |
Research Approach
Multi-period observation of automotive production growth, material science advancements, and e-commerce channel expansion anchored the trend analysis, supplemented by interviews. Primary research involved discussions with OEM procurement managers, aftermarket distributors, and material science engineers. Secondary validation drew from regulatory documents like NHTSA safety guidelines and Europe's REACH regulations. A bottom-up and top-down triangulation approach ensured data consistency.
Segment-weighting across product type, technology, application, and end user formed the core of the quantitative model, incorporating regional automotive production. The analytical framework projected market dynamics across the analysis window. Compound annual growth rates were derived from historical trends and anticipated shifts. Key forecast inputs included new vehicle sales data and material cost projections.
Underlying measurement precision varies by segment; the OEM segment carries tighter precision than the fragmented aftermarket. Forecasts reflect assumptions regarding polymer price stability and regulatory adherence. Practitioners should monitor new material breakthroughs and shifts in OEM procurement strategies for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Tires and Wheels
Kuwait Tyres Market
Tires and Wheels
Tire Cord Market
Tires and Wheels
Japan Tyre Market
Tires and Wheels
Automotive Wheel Alignment Service Market
Tires and Wheels
Tire Inflating Machine Market
Tires and Wheels
Agricultural Tires Market
Tires and Wheels
Automotive Steel Wheels Market
Tires and Wheels
Automotive Wheel Market
Tires and Wheels
Re-Tread Tires Market
Tires and Wheels
Commercial Vehicles Tires Market
Tires and Wheels
Europe Green Tire Market
Tires and Wheels
Off-The-Road (OTR) Tire Market
Tires and Wheels
Solid Tire Market
Tires and Wheels
Trailer Wheel Market
Tires and Wheels
Racing Tires Market
Tires and Wheels
North America Tire Market