
 Tire Cord Market | 2026-2036
Tire Cord Market Size, Share, and Industry Trends Forecast 2026-2036
Tire Cord Market Analysis
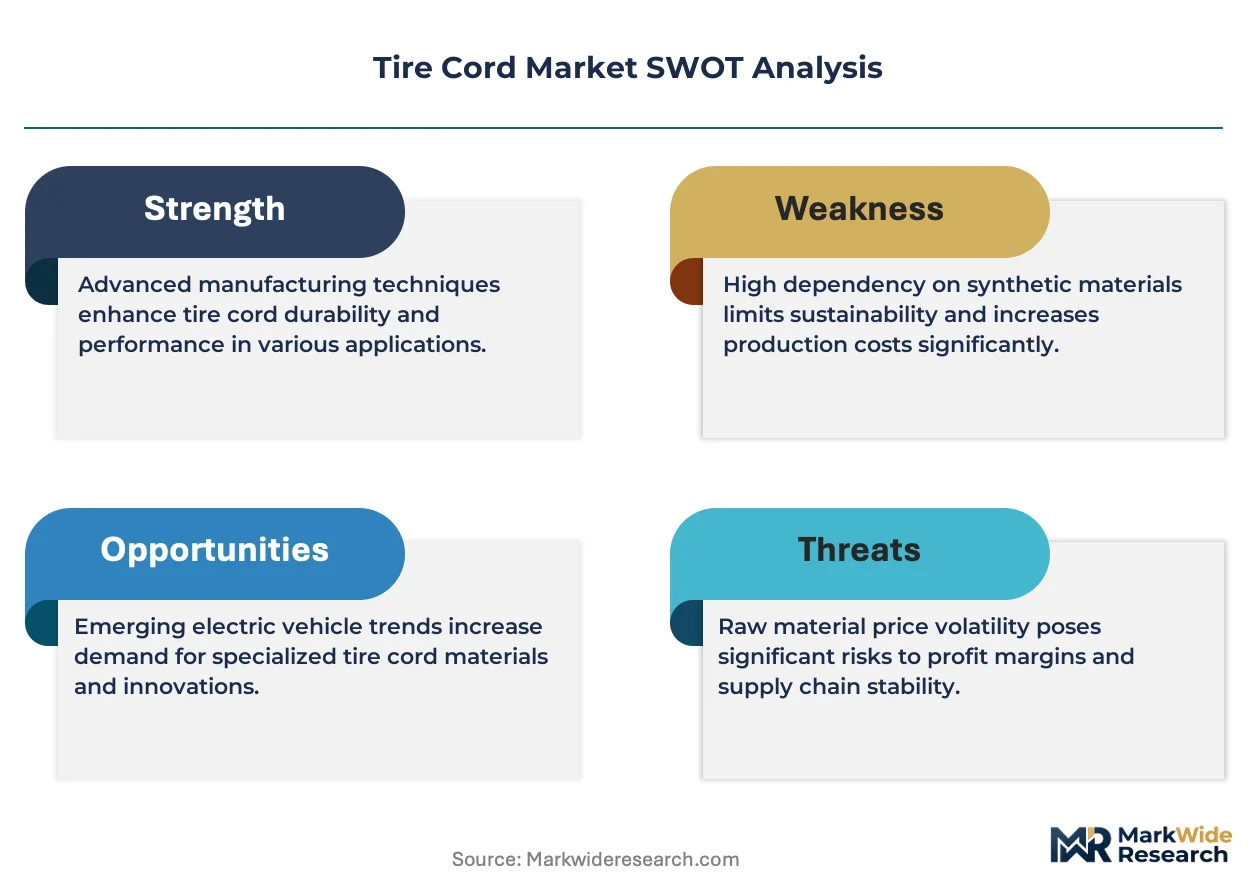
Electric vehicle OEM demand is expanding as heavier battery packs require reinforced tire structures capable of sustaining elevated load indices. Bekaert leverages its steel cord metallurgy leadership to supply European and Asian tire manufacturers with ultra-high-tensile products. Hyosung Advanced Materials anchors the nylon segment through integrated polymer-to-yarn operations in South Korea. Kolon Industries differentiates via aramid fiber development for premium performance tire applications.
Tire cord refers to the reinforcing textile or metallic filaments embedded within tire plies to provide structural integrity, dimensional stability, and load-bearing capacity, typically manufactured through twisting, weaving, or cabling processes with tensile strengths ranging from medium to extra-high grades. Its primary industrial purpose is to prevent tire deformation under inflation pressure and operational stress while maintaining adhesion to surrounding rubber compounds. Steel cord dominates commercial vehicle applications where load requirements peak, while polyester captures passenger vehicle volume due to cost efficiency and fatigue resistance. Aramid occupies the premium tier for high-performance and aerospace-adjacent tire segments where weight reduction commands priority over unit economics.
The EPA regulates particulate emissions from steel cord manufacturing facilities under Clean Air Act provisions, while REACH mandates disclosure of chemical substances in rubber-to-cord adhesion systems across European supply chains. India's BIS enforces tensile strength grading standards for domestic tire reinforcement imports, creating compliance barriers for uncertified suppliers. Stakeholders must monitor evolving carbon border adjustment mechanisms and raw material traceability requirements as sustainability criteria penetrate procurement specifications.
Market Dynamics
Electric vehicle battery weight loads are forcing tire OEMs to redesign reinforcement specifications, pulling steel cord tensile grades upward and compressing polyester adoption timelines in commercial vehicle segments.
Growth Catalysts
- EU Green Deal:Carbon border adjustment mechanisms are accelerating demand for recycled-content steel cord and bio-based polyester feedstocks across European tire supply chains.
- China's NEV penetration:Domestic electric vehicle production exceeding four million units annually is concentrating high-strength cord demand in Shanghai and Guangzhou manufacturing corridors.
- Radialization in India:Commercial vehicle fleet modernization under BIS grading mandates is displacing bias-ply construction in heavy trucking applications.
Market Restraints
- Scrap steel volatility:Electric arc furnace feedstock costs swing unpredictably, compressing margin stability for steel cord producers dependent on recycled metallurgy.
- Aramid supply concentration:Meta-aramid precursor manufacturing clusters in the United States and Japan create single-source vulnerability for premium tire reinforcement tiers.
- REACH adhesion compliance:Resorcinol-formaldehyde latex disclosure requirements are forcing reformulation of rubber-to-cord bonding systems at elevated R&D cost.
Strategic Opportunities
- Indonesia archipelago logistics:Underdeveloped radial tire penetration in inter-island trucking creates white space for polyester cord suppliers establishing local twisting operations.
- Carbon fiber hybridization:Convergence of thermoplastic resin injection with conventional cabling equipment enables weight reduction in aerospace-adjacent tire segments.
- India PLI scheme:Production-linked incentives for advanced textile manufacturing are drawing Korean and European cord producers into Tamil Nadu and Gujarat industrial zones.
Industry Challenges
- Metallurgical talent scarcity:Phased retirement of wire-drawing specialists in Belgium and Japan is outrunning apprenticeship pipeline development.
- Multi-standard certification lag:Simultaneous BIS, GB, and ECE R30 testing protocols extend product qualification timelines by eight to fourteen months.
- Legacy adhesion system integration:Cobalt salt bonding chemistry remains embedded in radial truck tire production lines, resisting aqueous-silane replacement without capital-intensive extruder modification.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Tire Cord Market |
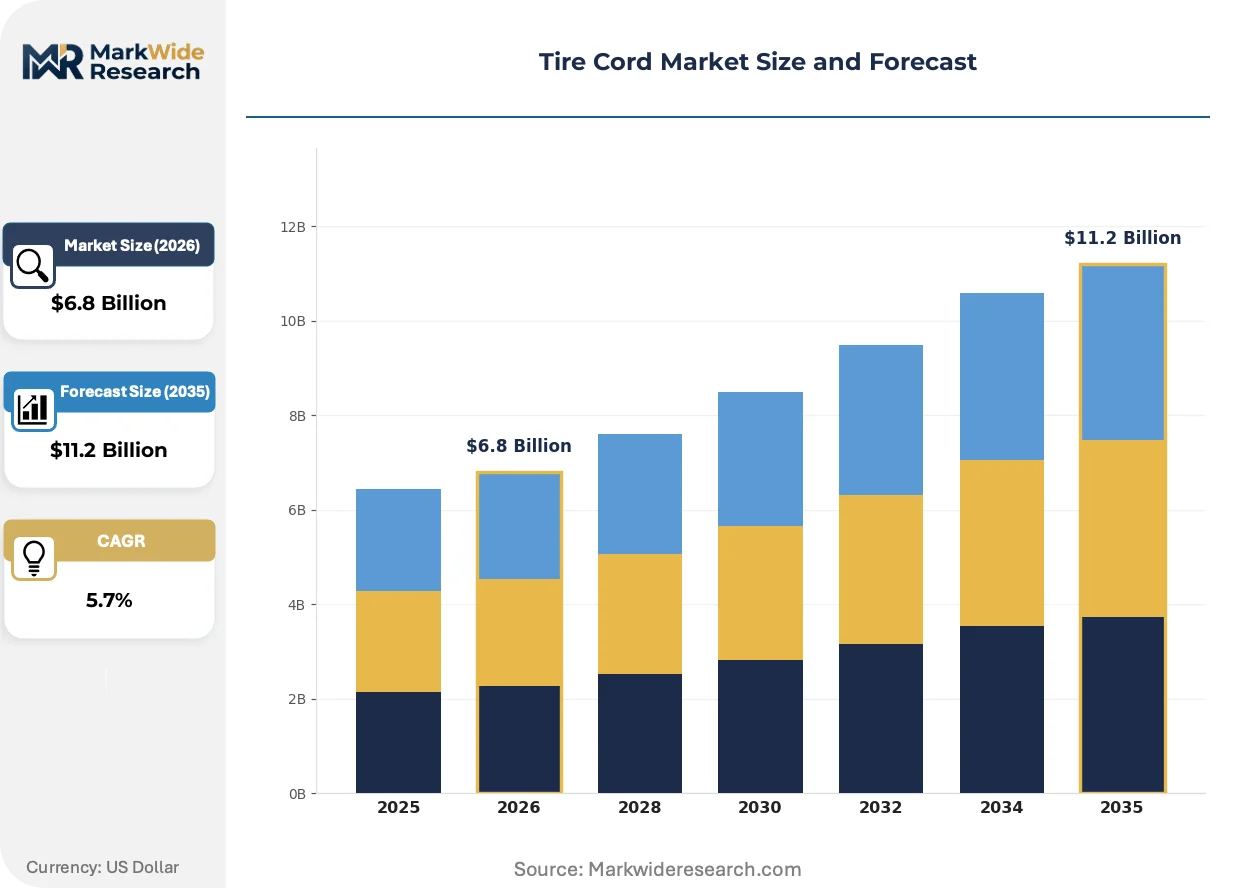
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $11.2 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Material Type: Steel, Nylon, Polyester, Aramid Application: Passenger Vehicles, Commercial Vehicles, Two-Wheelers, Off-Road Vehicles Tensile Strength: High, Medium, Low, Extra High End User: OEMs, Aftermarket Suppliers, Tire Manufacturers, Exporters |
| Companies Covered | Sumitomo Electric Industries, Kolon Industries, Hyosung Advanced Materials, Tokusen Kogyo, SRF Limited, Bekaert, Teijin, Indorama Ventures, Kordsa Global, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Tire Cord Market Emerging Trajectories
Material science advances and regulatory chemistry mandates are converging to restructure how tire reinforcement interfaces with rubber matrices and how suppliers validate environmental claims.
Ultra-high-tensile steel cord metallurgy is unifying previously separate strength and fatigue-resistance specifications into single-wire offerings. Tier-one tire OEMs in Germany and Japan are specifying 4,000 MPa grades for electric vehicle original fitment. This unification is compressing the number of qualified steel cord suppliers capable of meeting simultaneous load index and endurance requirements.
REACH substance restriction proposals targeting polycyclic aromatic hydrocarbons in rubber processing aids are forcing compound reformulation across European tire manufacturing. ECHA consultation timelines suggest enforcement beginning in 2026 for cord-rubber adhesion promoters. Premium passenger tire segments are responding fastest, with several manufacturers accelerating silicone-based bonding chemistry validation.
Direct procurement contracts between tire OEMs and cord producers are displacing traditional merchant market structures in high-volume segments. Long-term offtake agreements now specify recycled content percentages and carbon intensity disclosures alongside mechanical specifications. This pattern is most visible in South Korean and German supply corridors, where Hyundai, Kumho, Continental, and Michelin have established dedicated supply lines bypassing distributor intermediaries.
Tire Cord Market Segmentation
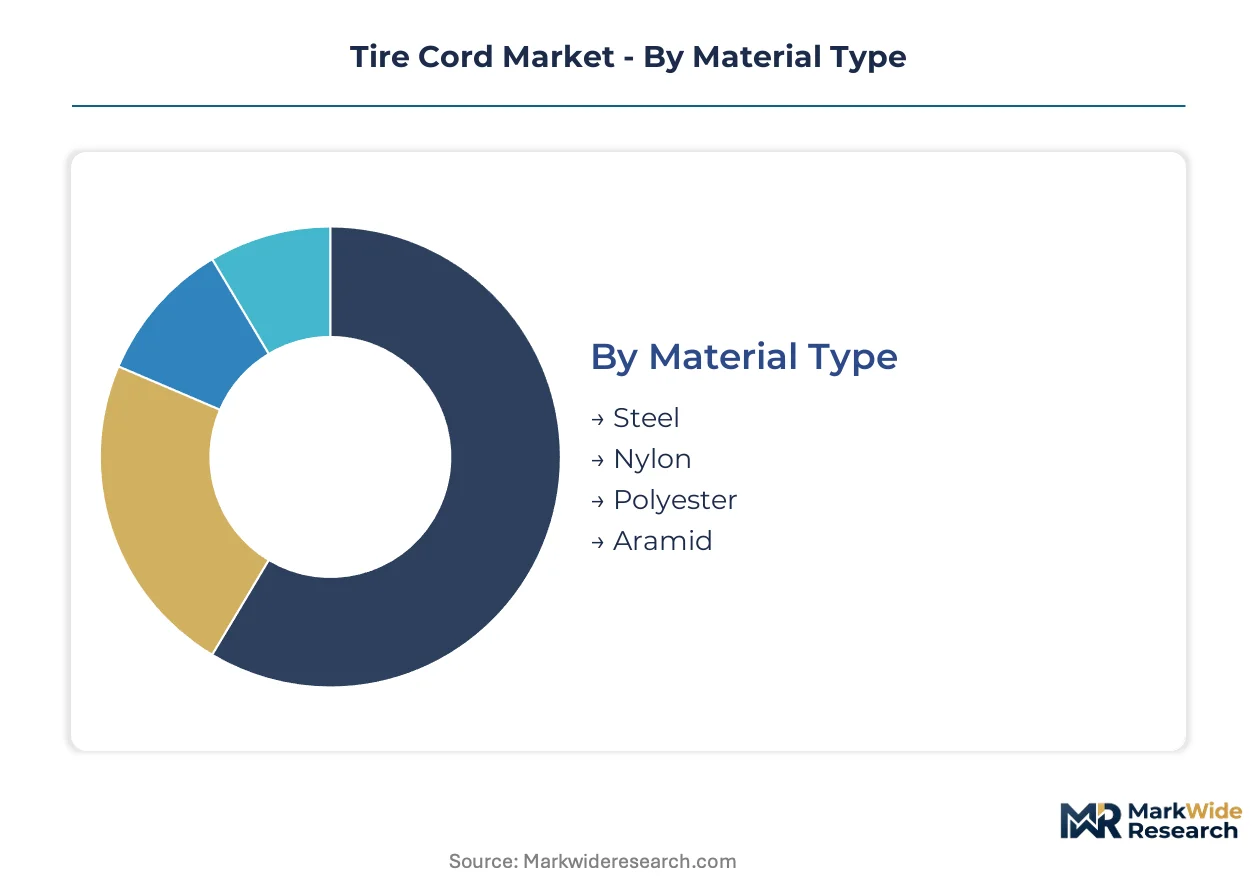
Tire cord segmentation reflects divergent metallurgical capabilities, polymer chemistry specializations, and end-use load specifications. Supply-side concentration varies sharply across material categories, with steel cord producers consolidating around ultra-high-tensile grades while polyester and nylon segments fragment across Asian textile manufacturers.
Material Type:
Steel cord supply concentrates among Belgian, Japanese, and Chinese metallurgical specialists with integrated wire-drawing and heat-treatment capabilities. Polyester and nylon cord production disperses across South Korean, Indian, and Taiwanese polymer-to-yarn operators with lower capital barriers to entry.
- Steel:Ultra-high-tensile grades from 3,500 to 4,000 MPa dominate electric vehicle original fitment requirements. Demand concentrates in Shanghai and Guangzhou manufacturing corridors serving domestic NEV production exceeding four million units annually, with Bekaert and domestic Chinese suppliers capturing volume through direct OEM contracts.
- Polyester:Cost-efficient fatigue resistance makes this the default reinforcement for standard passenger tires. Hyosung Advanced Materials anchors supply through integrated polymer-to-yarn operations in South Korea, though Indian and Vietnamese producers are expanding twisting capacity under PLI scheme incentives.
- Nylon:Superior heat resistance suits this material to truck tire carcass plies and aircraft tire applications. Kolon Industries and Hyosung control filament spinning technology, with supply tightening around meta-aramid precursor availability.
- Aramid:Premium weight reduction for aerospace-adjacent and ultra-high-performance tires. Meta-aramid precursor manufacturing clusters in the United States and Japan create single-source vulnerability for this tier.
Steel absorbs the bulk of installed capacity; aramid is expanding most quickly.
Application:
Passenger vehicle volume dictates polyester cord economics, while commercial vehicle load indices pull steel cord specifications upward. Two-wheeler and off-road segments operate on distinct certification and distribution pathways.
- Passenger Vehicles:Radial construction dominance and cost-sensitive OEM procurement sustain polyester's share. European REACH compliance is forcing silicone-based bonding chemistry validation fastest in this tier.
- Commercial Vehicles:Heavy trucking radialization under India's BIS grading mandates is displacing bias-ply construction. Steel cord specifications here unify strength and fatigue-resistance requirements into single-wire offerings.
- Two-Wheelers:Bias-ply construction persists in emerging markets. Indonesia's inter-island logistics create white space for polyester cord suppliers establishing local twisting operations.
- Off-Road Vehicles:Mining and agricultural equipment demand puncture-resistant carcass designs. Aramid hybridization gains traction where weight reduction offsets premium unit economics.
Commercial vehicles command the highest reinforcement value per tire; two-wheelers are climbing the fastest as Asian motorcycle production scales.
Tensile Strength:
Grade stratification determines supplier qualification barriers and pricing power. Extra-high and high grades consolidate around metallurgical specialists, while medium and low grades fragment across commodity producers.
- Extra High:4,000 MPa specifications for electric vehicle load indices. Tier-one tire OEMs in Germany and Japan specify these grades, compressing qualified supplier counts.
- High:Standard heavy truck and premium passenger tire reinforcement. This grade captures the intersection of volume and performance where margin stability is strongest.
- Medium:General passenger tire and light commercial applications. Chinese producers dominate through cost-optimized wire-drawing operations.
- Low:Economy tire segments and industrial rubber goods. Scrap steel volatility compresses margin stability for producers dependent on recycled metallurgy.
High tensile grades absorb the bulk of qualified supplier attention; extra high specifications are gaining share fastest as EV penetration deepens.
End User:
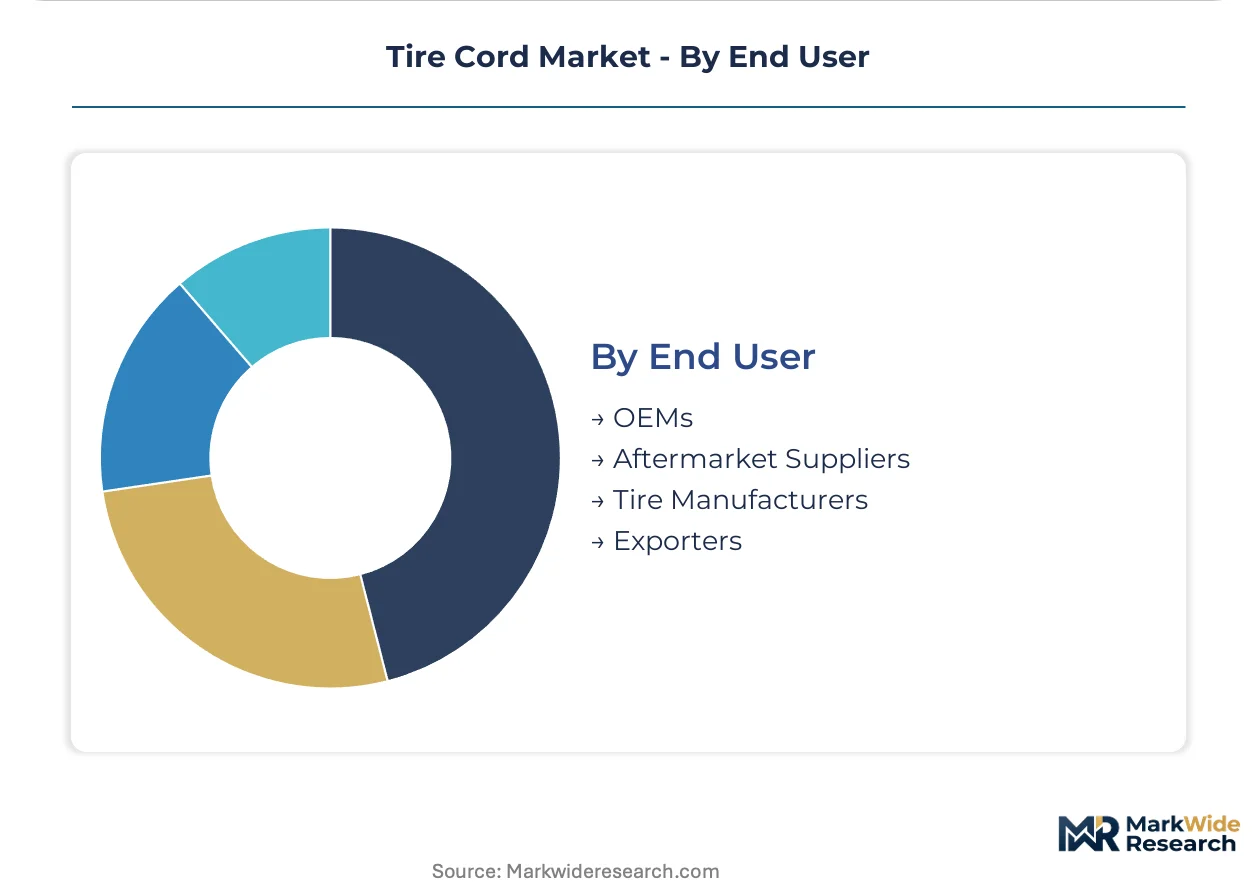
Direct procurement contracts between tire OEMs and cord producers are displacing traditional merchant market structures. Aftermarket and exporter channels retain distributor intermediaries with lower transparency requirements.
- OEMs:Long-term offtake agreements now specify recycled content percentages and carbon intensity disclosures alongside mechanical specifications. Hyundai, Kumho, Continental, and Michelin have established dedicated supply lines in South Korean and German corridors.
- Tire Manufacturers:Mid-tier producers without captive cord operations rely on merchant markets with shorter contract terms. Multi-standard certification lag extends product qualification timelines by eight to fourteen months for this segment.
- Aftermarket Suppliers:Replacement tire producers prioritize cost efficiency over performance specification. REACH adhesion compliance costs fall heaviest on smaller compounders lacking R&D scale.
- Exporters:Cross-border trade in unbranded cord serves regional tire producers in Africa, Latin America, and Southeast Asia. India's DGFT export incentives support this channel.
OEMs absorb the bulk of premium grade volume; tire manufacturers are expanding procurement autonomy fastest through backward integration efforts.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Special economic zones in Shanghai, Chennai, and Antwerp concentrate tire cord production capacity through tax abatements and duty-free import regimes for metallurgical and polymer feedstocks. These zones anchor supply chains serving adjacent automotive manufacturing corridors.
China
Domestic NEV production exceeding four million units annually pulls ultra-high-tensile steel cord demand into Shanghai and Guangzhou manufacturing corridors. MIIT enforces GB standards for tire reinforcement tensile grading, creating compliance barriers for uncertified imports. Qingdao and Shenyang host integrated wire-drawing facilities supplying domestic tire OEMs with 4,000 MPa grades.
India
Commercial vehicle radialization under BIS grading mandates displaces bias-ply construction in heavy trucking applications. The PLI scheme for advanced textile manufacturing draws Korean and European cord producers into Tamil Nadu and Gujarat industrial zones. Chennai and Ahmedabad cluster twisting operations serving domestic tire manufacturers expanding radial capacity.
Germany
REACH mandates disclosure of chemical substances in rubber-to-cord adhesion systems across European supply chains. ECHA consultation timelines target enforcement beginning in 2026 for cord-rubber bonding promoters. Continental and Michelin operations in Hanover and Frankfurt anchor direct procurement contracts specifying recycled content percentages.
South Korea
Hyundai and Kumho Tire operations concentrate high-strength cord demand in Seoul Capital Area manufacturing corridors. MFDS regulates chemical exposure in polymer spinning facilities, complementing environmental standards enforced by regional industrial complexes. Busan-Ulsan hosts integrated polymer-to-yarn operations supplying domestic and export tire markets.
United States
EPA regulates particulate emissions from steel cord manufacturing facilities under Clean Air Act provisions. Meta-aramid precursor manufacturing clusters create single-source vulnerability for premium tire reinforcement tiers. Ohio and South Carolina host wire-drawing operations serving domestic commercial vehicle tire producers.
Tire Cord Market Vendor Landscape
Branded specialists and contract manufacturers split share differently across segments, with metallurgical specialists consolidating around ultra-high-tensile grades while polymer producers fragment across commodity tiers. Belgian and Japanese wire-drawing operations concentrate supply for electric vehicle original fitment, whereas South Korean and Indian polymer-to-yarn operators compete on cost efficiency. Three archetypes dominate: integrated metallurgical specialists with captive heat-treatment capabilities, polymer-to-yarn operators with backward integration into petrochemical feedstocks, and aramid-focused premium material developers. Capacity expansion and direct OEM contracting represent the dominant competitive moves, displacing traditional merchant market structures.
Among Belgian and Japanese metallurgical specialists, Bekaert and Tokusen Kogyo occupy positions exemplifying ultra-high-tensile steel cord leadership through integrated wire-drawing and heat-treatment capabilities. Hyosung Advanced Materials anchors the polymer-to-yarn operator archetype with integrated operations spanning petrochemical feedstock through finished cord. Kolon Industries sits within the premium material developer tier, representing aramid-focused positioning for aerospace-adjacent and ultra-high-performance tire segments.
| Leading Market Players |
|---|
| Sumitomo Electric Industries |
| Kolon Industries |
| Hyosung Advanced Materials |
| Tokusen Kogyo |
| SRF Limited |
| Bekaert |
| Teijin |
| Indorama Ventures |
| Kordsa Global |
| Others |
Supply Flow & Price Mechanics
EU Green Deal carbon border adjustment mechanisms gate qualified supply and premium-tier pricing access for tire cord producers, as OEM procurement contracts now mandate recycled content percentages alongside mechanical specifications. This regulatory filter compresses margin stability for uncertified suppliers while rewarding metallurgical specialists with integrated heat-treatment capabilities.
Pricing Analysis
Short lead-time premiums distinguish contract pricing from spot inventory discounts across European and Asian supply corridors. Three-tier pricing structure across premium, standard, and economy levels stratifies by tensile grade certification and volume commitment scale. Cost compression in low-tensile grades is intensifying because scrap steel volatility feeds electric arc furnace feedstock unpredictability. Aftermarket suppliers exhibit highest price sensitivity, while OEM direct procurement shows lowest elasticity due to performance specification rigidity.
Supply Chain Analysis
Direct-to-OEM channels handle hyperscale buyer demand from Continental, Michelin, Hyundai, and Kumho, displacing traditional merchant market structures in high-volume segments. Supply concentrates in Belgium, Japan, and China for steel cord metallurgy, while South Korea, India, and Taiwan anchor polymer-to-yarn operations. Raw material dependencies center on scrap steel feedstock, meta-aramid precursor availability, and petrochemical-derived polyester chips. Single-source vulnerability in United States and Japanese meta-aramid precursor manufacturing creates structural risk for premium tire reinforcement tiers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
REACH substance restriction proposals and carbon border adjustment mechanisms are consolidating tire cord supply around metallurgical specialists with integrated compliance capabilities, forcing smaller compounders and merchant market intermediaries toward exit or acquisition.
For Market Incumbents: Deepen backward integration into scrap steel sorting and heat-treatment capabilities to defend margin position against feedstock volatility. Secure long-term offtake agreements with NEV OEMs specifying 4,000 MPa ultra-high-tensile grades before qualification timelines extend further under multi-standard certification requirements. For New Entrants and Emerging Players: Digital procurement platforms serving mid-tier tire manufacturers without captive cord operations offer a lower-barrier entry route than direct OEM qualification. Indonesia's underdeveloped radial tire penetration in inter-island trucking represents the most penetrable white space, with local twisting operations enabling cost-competitive polyester cord supply. For Investors and Strategic Acquirers: Korean and European cord producers establishing Tamil Nadu and Gujarat operations under India's PLI scheme is the leading indicator that production-linked incentive arbitrage will reshape regional supply concentration. Target metallurgical specialists with captive wire-drawing and heat-treatment capabilities, monitoring BIS certification approval velocity as the inflection signal for market access viability.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Scrap Steel Processing | Captive feedstock supply buffers Bekaert and Tokusen Kogyo against electric arc furnace cost volatility. |
| Long-term Supply Agreement with NEV OEMs | Hyundai and Kumho Tire direct contracts specify recycled content percentages alongside 4,000 MPa tensile grades. |
| Green Manufacturing Transition | Silicone-based bonding chemistry validation accelerates as ECHA targets 2026 enforcement for cord-rubber adhesion promoters. |
| Geographic Manufacturing Footprint Expansion | Tamil Nadu and Gujarat industrial zones attract Korean and European producers under India's PLI scheme incentives. |
| Joint Venture for Local Twisting Operations | Indonesia archipelago logistics create partnership opportunities for polyester cord suppliers establishing regional capacity. |
Methodological Framework
Trade databases, SEC filings from listed tire and materials producers, and MIIT/GB standard documentation formed the secondary backbone, cross-referenced with primary interviews involving tire OEM procurement directors, steel cord plant managers, polymer spinning technical leads, and REACH compliance officers at European compounders. Bottom-up and top-down triangulation validated volume estimates across material type and application segments.
Bottom-up modeling aggregated individual country production capacity, utilization rates, and OEM fitment ratios across the projection horizon. Segmentation dimensions included material type, tensile strength grade, vehicle application, and end-user procurement channel. CAGRs derived from fitted growth curves incorporating NEV penetration trajectories, radialization rates in commercial vehicle fleets, and regulatory compliance cost pass-through assumptions.
The model holds under stable scrap steel feedstock availability and continued NEV production scaling; deviation in aramid precursor supply disruptions or BIS certification timeline extensions would shift supplier qualification dynamics. Periodic stress-testing of base assumptions against ECHA enforcement timelines and PLI scheme uptake rates is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Tires and Wheels
Asia-Pacific Alloy Wheels Market
Tires and Wheels
Tire & Wheel Cleaners Market
Tires and Wheels
North America OTR Tire Market
Tires and Wheels
Alloy Wheels Market
Tires and Wheels
Japan Tyre Market
Tires and Wheels
Bias Tire Market
Tires and Wheels
Tire Changers Market
Tires and Wheels
Tire Carousel Market
Tires and Wheels
Asia-Pacific Aircraft Tires Market
Tires and Wheels
Civil Aircraft Tire Market
Tires and Wheels
Specialty Tire Market
Tires and Wheels
E-Bike Tire Market
Tires and Wheels
GCC Tire Market
Tires and Wheels
Automotive Carbon Wheels Market
Tires and Wheels
Carbon Wheels Market
Tires and Wheels
Industrial Tire Market