
 Automotive Metal Wheel Market | 2026-2036
Automotive Metal Wheel Market Size, Share, and Industry Trends Forecast 2026-2036
Automotive Metal Wheel Market Insights
Fleet operators are redrawing procurement priorities across the Automotive Metal Wheel landscape. Maxion Wheels leverages vertical integration across steel and aluminum supply chains to serve commercial vehicle contracts. CITIC Dicastal anchors high-volume die-casting capacity for Chinese OEM platforms. Borbet differentiates through forged aluminum specialization in European performance segments.
Automotive metal wheels are structural rotating components, typically fabricated from aluminum alloys, steel, or magnesium, engineered to withstand cyclic loading, corrosion exposure, and thermal stress while supporting vehicle mass and transmitting steering and braking forces. Primary manufacturing routes include low-pressure die casting for alloy wheels, stamped and welded steel construction for commercial applications, and closed-die forging for motorsport and premium variants. Alloy wheels lead product type value contribution due to weight-driven fuel efficiency mandates, while forged wheels capture disproportionate margin pools despite smaller volume. Steel wheels retain dominance in truck and fleet segments where cost and reparability outweigh mass reduction priorities.
FAA, NHTSA, and EPA standards govern wheel fatigue performance, impact resistance, and embedded emissions in the US market, with NHTSA FMVSS No. 110 and No. 120 setting minimum dimensional and strength thresholds for passenger and commercial vehicles. Europe's REACH and ECHA substance restrictions constrain coating chemistries and aluminum alloy compositions, compelling reformulation of surface treatments across the supply base. Stakeholders must monitor evolving battery-electric vehicle platform specifications, as axle load redistribution and regenerative braking torque profiles are rewriting wheel design load cases ahead of regulatory harmonization.
Market Dynamics
Electric vehicle platform architectures are redistributing axle loads and regenerative braking torque profiles, forcing wheel suppliers to recast fatigue load cases and thermal management specifications ahead of formal regulatory harmonization.
Growth Catalysts
- EU REACH substance restrictions:Compliance deadlines are accelerating reformulation of coating chemistries and aluminum alloy compositions, creating upgrade cycles across European supplier bases.
- Lightweight alloy die-casting:High-pressure casting advances are enabling thinner wall sections without sacrificing impact resistance, aligning with OEM mass reduction mandates.
- China premium SUV production:Domestic automakers are scaling dedicated platforms with larger wheel diameters, concentrating procurement volume for 19-inch and above configurations.
Market Restraints
- Magnesium input cost volatility:Primary magnesium smelting capacity concentrates in specific supplier geographies, exposing forged wheel margins to energy-price-driven feedstock swings.
- Steel wheel reparability threshold:Commercial fleet operators prioritize field-serviceable stamped constructions over alloy alternatives, limiting premium substitution in heavy-duty segments.
- NHTSA FMVSS No. 120 testing burden:Commercial vehicle wheel certification requires destructive impact and fatigue protocols that extend validation timelines for new designs.
Strategic Opportunities
- India PLI scheme for auto components:Production-linked incentives for advanced manufacturing are attracting greenfield forging and casting investments to serve export and domestic OEM programs.
- Closed-loop aluminum recycling:In-house remelt capabilities are converging with renewable energy procurement to position suppliers for EU Green Deal embedded carbon requirements.
- Direct-to-fleet digital channels:Telematics-enabled wheel condition monitoring is enabling subscription-based replacement programs bypassing traditional distributor networks.
Industry Challenges
- Multi-physics simulation talent scarcity:Coupled thermal-mechanical fatigue modeling for EV-specific load cases requires specialized CAE expertise concentrated among Tier-1 engineering centers.
- Surface treatment certification delays:ECHA SVHC candidate list expansions are triggering reformulation cycles for chromate-free conversion coatings ahead of validated alternatives.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Automotive Metal Wheel Market |
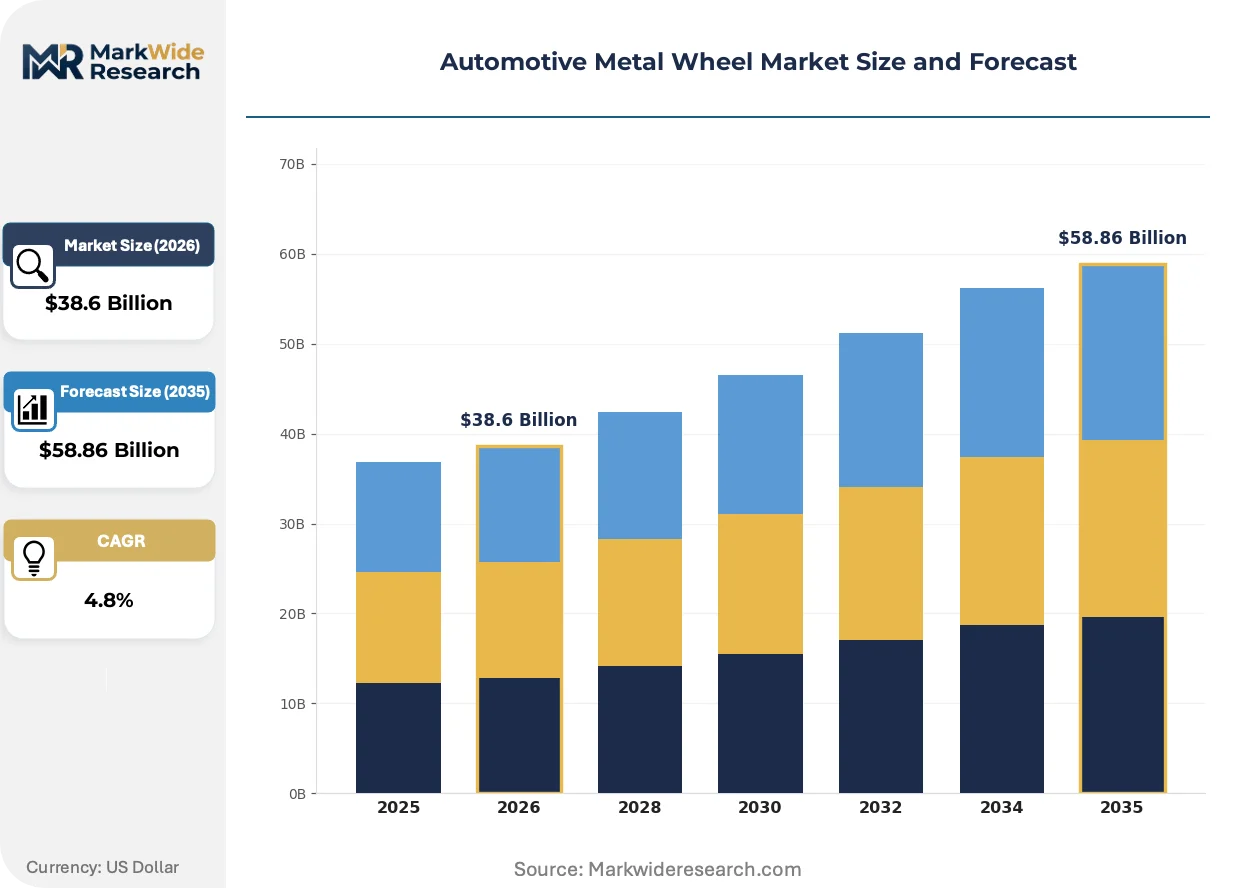
| Market Size in 2026 | $38.6 Billion |
| Market Size in 2035 | $58.86 Billion |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Alloy Wheels, Steel Wheels, Cast Wheels, Forged Wheels Vehicle Type: Sedan, SUV, Truck, Motorcycle Manufacturing Process: Die Casting, Stamping, Machining, Welding End User: OEMs, Aftermarket Retailers, Distributors, Fleet Operators |
| Companies Covered | Maxion Wheels, CITIC Dicastal, Borbet, Superior Industries, Topy, Accuride, Enkei Corporation, Ronal Group, Steel Strips Wheels, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Automotive Metal Wheel Market Trends and Innovations
Manufacturing process intensification and regulatory chemistry constraints are converging to compress traditional design-to-production cycles while elevating performance verification standards.
Forged aluminum flow-forming hybrid processes are displacing conventional low-pressure die casting in premium passenger applications. European performance OEMs are adopting these hybrid constructions for 20-inch and above fitments where unsprung mass reduction justifies unit cost premiums. The technology is displacing single-process forging in mid-premium segments by narrowing the cost gap while retaining strength-to-weight advantages.
Europe's ECHA SVHC authorization procedures are constraining hexavalent chromium surface treatments across wheel supply chains. Manufacturers are qualifying trivalent conversion coatings and plasma electrolytic oxidation alternatives to maintain corrosion performance under extended warranty terms. Aftermarket refinishing operations face the steepest compliance recertification burden as REACH enforcement tightens across member state customs checkpoints.
Consolidated fleet procurement is compressing supplier qualification cycles and unbundling wheel-tire assemblies as separate contract lines. Large commercial lessors are negotiating direct supply agreements with foundries for standardized steel wheel specifications, bypassing traditional tiered distribution. This pattern is most pronounced in North American long-haul trucking where asset utilization metrics dominate total cost of ownership calculations.
Automotive Metal Wheel Market Segmentation
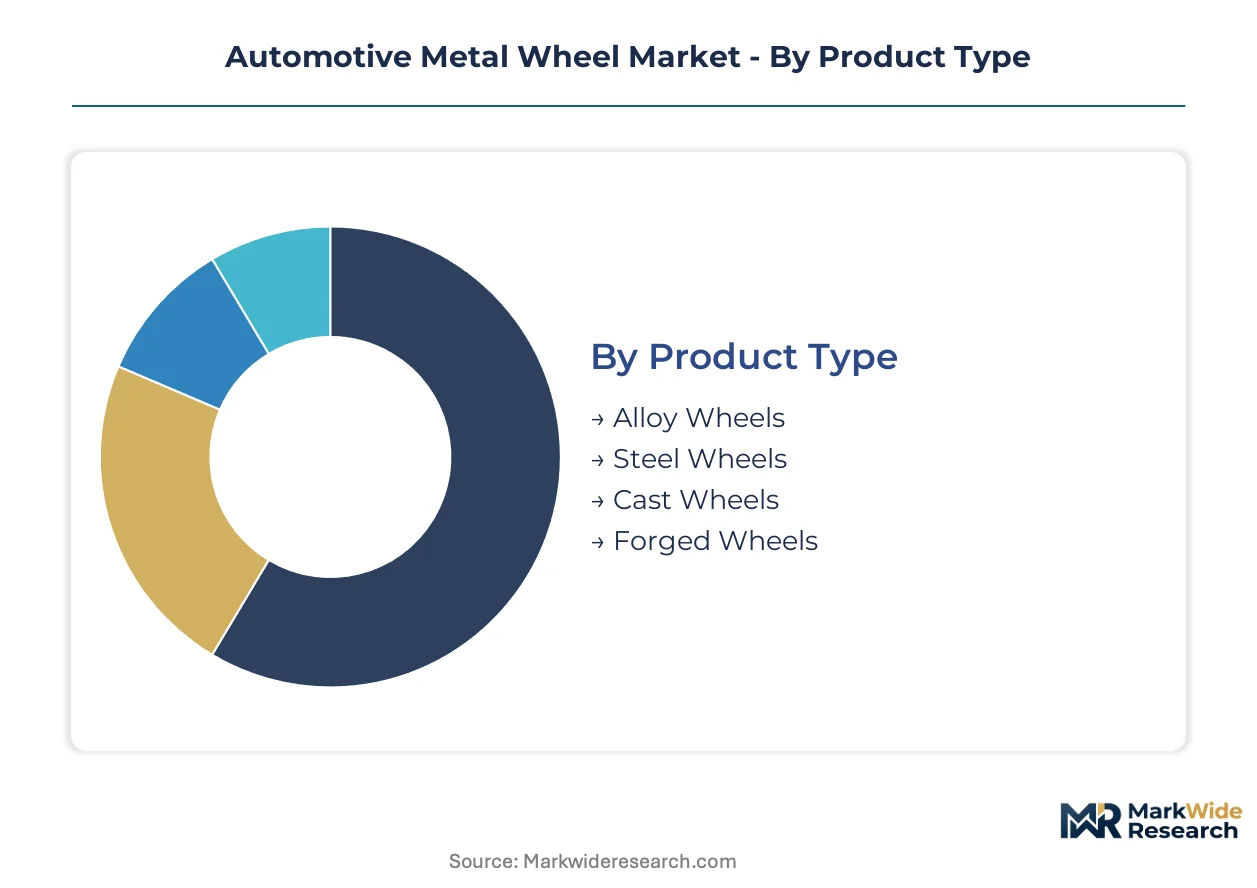
Wheel procurement patterns diverge sharply across vehicle platforms and supply channels. Segmentation reveals how alloy specifications, manufacturing routes, and customer types allocate margin pools unevenly across the value chain.
Product Type:
Margin concentration tracks with material performance premiums and production complexity barriers.
- Alloy Wheels:Aluminum-silicon-magnesium castings dominate passenger car fitments where unsprung mass reduction delivers measurable fuel economy gains. Demand clusters in Chinese premium SUV platforms and European electric vehicle programs where 19-inch and larger diameters are becoming baseline specifications.
- Forged Wheels:Closed-die aluminum forgings with flow-formed rims command the highest unit economics in motorsport and luxury segments. European performance OEMs specify these for thermal management under regenerative braking loads that exceed cast alloy fatigue limits.
- Steel Wheels:Stamped and welded two-piece constructions retain total cost of ownership advantages in commercial trucking where field reparability outweighs mass reduction priorities.
- Cast Wheels:Low-pressure die-cast aluminum variants serve mass-market applications where impact resistance requirements moderate against cost constraints.
The dominant share belongs to Alloy Wheels, while Forged Wheels is closing the gap fastest on margin contribution per unit.
Vehicle Type:
Platform architecture differences are redistributing wheel load cases and diameter specifications across customer segments.
- SUV:Higher center of gravity and all-terrain duty cycles demand reinforced bead seats and larger brake clearance envelopes. Chinese domestic automakers are scaling dedicated premium SUV platforms with wheel diameters starting at 19 inches.
- Truck:Axle load ratings and dual-wheel configurations in heavy-duty segments preserve steel wheel dominance despite alloy penetration in light-duty pickups. Fleet operators negotiate direct foundry contracts for standardized specifications.
- Sedan:Passenger car programs are converging on 17-18 inch alloy wheels as regulatory fuel economy mandates harden. Sedan wheel design emphasizes aerodynamic cladding integration for drag coefficient targets.
- Motorcycle:Cast and forged aluminum wheels dominate two-wheeler applications where gyroscopic effects of unsprung mass directly impact handling response.
SUV commands the largest procurement volume, though Truck maintains the steadiest replacement demand through commercial fleet channels.
Manufacturing Process:
Process selection determines capital intensity, cycle time, and the feasible alloy systems for each product tier.
- Die Casting:High-pressure aluminum die casting enables thin-wall sections with complex spoke geometries for styling differentiation. CITIC Dicastal anchors capacity serving high-volume Chinese OEM programs with automated cell configurations.
- Stamping:Progressive die forming of steel blanks remains the cost floor for commercial vehicle wheels where production scale justifies dedicated press lines.
- Machining:CNC finishing operations precision-machine forged blanks to final dimensions, capturing value in premium segments where dimensional tolerances affect vehicle dynamics.
- Welding:Automated arc and laser welding of stamped steel rims to disc centers produces serviceable commercial wheels with reparable damage modes.
Die Casting holds the production volume lead, with Machining expanding most quickly in premium electric vehicle programs.
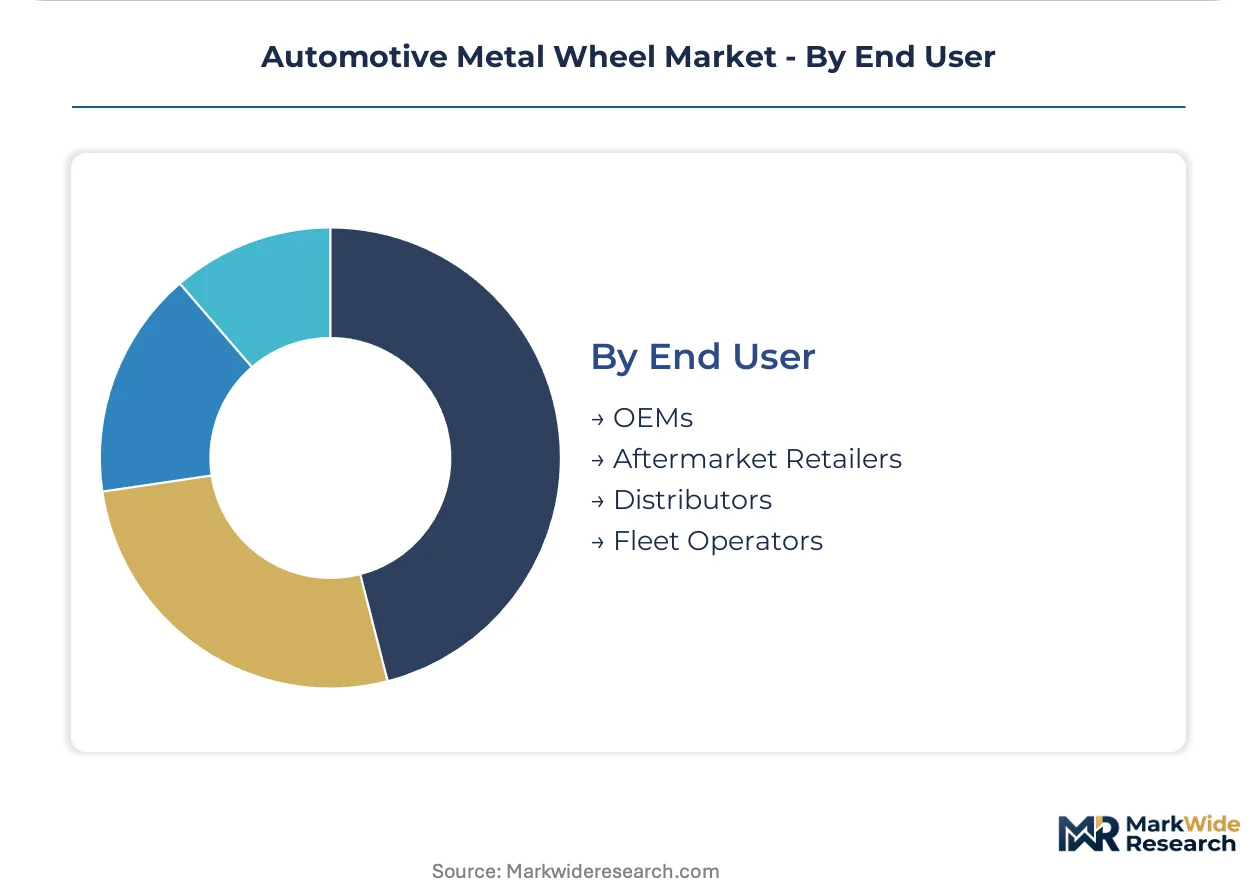
End User:
Channel structure fragments procurement behavior across specification control, price sensitivity, and replacement timing predictability.
- OEMs:Original equipment manufacturers specify wheels at platform development gates with multi-year contract horizons. EV platform teams are rewriting fatigue load cases ahead of regulatory harmonization for regenerative braking torque profiles.
- Fleet Operators:Commercial lessors unbundle wheel-tire assemblies and negotiate direct foundry agreements for standardized steel specifications, bypassing traditional distribution tiers.
- Aftermarket Retailers:Independent channels serve styling upgrade demand and collision replacement with catalog breadth across multiple fitment databases.
- Distributors:Traditional tiered distribution retains role in fragmented geographic markets where consolidated fleet penetration remains limited.
OEMs anchor the value chain on contract value, while Fleet Operators are gaining procurement sophistication fastest through telematics-enabled condition monitoring.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Fleet operators and premium SUV OEMs concentrate procurement in manufacturing clusters where die-casting capacity, forging expertise, and regulatory compliance infrastructure overlap. Buyer archetypes fragment across cost-driven commercial lessors, mass-market EV platforms, and performance-oriented European marques.
China
Domestic automakers scaling 19-inch and larger wheel programs for premium SUV platforms drive die-casting volume concentration. MIIT fuel economy mandates and dual carbon goals pressure suppliers toward closed-loop aluminum recycling. CITIC Dicastal anchors high-volume capacity in Zhejiang province serving Geely, BYD, and NIO platform teams.
Germany
Performance OEMs specify forged aluminum flow-forming hybrids for thermal management under regenerative braking loads. REACH substance restrictions and ECHA SVHC candidate list expansions compel coating chemistry reformulation. Borbet maintains forging specialization in Medebach while supplying Porsche, BMW M, and Mercedes-AMG programs.
United States
Commercial fleet operators negotiate direct foundry contracts for standardized steel wheel specifications in long-haul trucking. NHTSA FMVSS No. 110 and No. 120 set fatigue and impact thresholds extending validation timelines. Maxion Wheels leverages vertical integration across steel and aluminum supply chains from its Michigan and Mexico operations.
India
PLI scheme production-linked incentives attract greenfield forging and casting investments for export and domestic OEM programs. BIS certification requirements and axle load regulations for commercial vehicles preserve steel wheel dominance in trucking. Steel Strips Wheels expands capacity in Punjab to serve Maruti Suzuki and Tata Motors platforms.
Japan
JIS standards and METI technology roadmaps guide lightweight alloy development for hybrid and battery-electric platforms. Enkei Corporation maintains motorsport-derived forging expertise supplying Toyota, Honda, and Nissan performance variants. Closed-die forging capacity concentrates in Shizuoka prefecture where thermal-mechanical fatigue modeling capabilities support EV-specific load cases.
Automotive Metal Wheel Market Competitive Landscape
Player mix skews toward vertically integrated steel specialists and aluminum die-casting scale operators with regional density advantages. Market structure concentrates procurement leverage among three to five foundry groups capable of serving multi-year OEM platform contracts. Strategic archetypes include high-volume die-casting specialists, forged aluminum premium-tier suppliers, and stamped steel commercial fleet providers. Competitive moves center on backward integration into aluminum remelt capabilities and direct-to-fleet digital channel development bypassing traditional distribution tiers.
Among forged aluminum specialists, Borbet and Ronal Group occupy positions in European performance segments where thermal management specifications exceed cast alloy fatigue limits. CITIC Dicastal represents the scale-driven archetype anchoring high-volume die-casting capacity for Chinese OEM platform teams. Maxion Wheels exemplifies vertical integration across steel and aluminum supply chains serving commercial vehicle contracts in North America and Europe.
| Leading Market Players |
|---|
| Maxion Wheels |
| CITIC Dicastal |
| Borbet |
| Superior Industries |
| Topy |
| Accuride |
| Enkei Corporation |
| Ronal Group |
| Steel Strips Wheels |
| Others |
Pricing and Supply Chain Analysis
Ninety-day die-casting tool lead times from Chinese foundries concentrate procurement leverage among OEMs with multi-year platform visibility, compressing margin buffers for suppliers without captive aluminum remelt capacity or direct fleet channel access. This inventory-to-pricing linkage tightens whenever REACH substance restrictions trigger coating reformulation cycles that extend qualification timelines.
Pricing Analysis
Current-generation flow-formed forged wheels command unit economics three to four tiers above prior-generation low-pressure die castings, while next-generation magnesium-intensive designs remain pre-commercial due to feedstock volatility. Three-tier pricing structure across premium, standard, and economy levels stratifies by fatigue certification grade and thermal management performance. Cost compression in standard-tier alloy wheels is intensifying because Chinese OEMs are consolidating procurement around 19-inch and above specifications. Fleet operators exhibit highest price sensitivity through direct foundry negotiations, while European performance marques maintain lowest sensitivity where unsprung mass reduction justifies unit premiums.
Supply Chain Analysis
Inventory cycles of 45-60 days for primary aluminum ingot and 90-120 days for specialized forging dies expose suppliers to commodity price swings and capacity allocation decisions. Manufacturing concentrates in China, Germany, and the United States, with secondary clustering in Japan for motorsport-grade forging expertise. The supply chain draws from primary aluminum smelters, magnesium alloy producers, and chromate-free coating chemical suppliers. Single-source vulnerability concentrates in high-pressure die-casting equipment where European and Japanese machine builders dominate. Distribution runs through OEM platform engineering gates for original fitment, with aftermarket channels fragmenting across independent retailers and telematics-enabled fleet procurement systems.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a defensive-moat story where regulatory entrenchment—specifically NHTSA FMVSS and REACH certification timelines—creates switching costs that extend incumbent tenure beyond typical automotive component cycles.
For Market Incumbents: Consolidate backward integration into aluminum remelt capabilities to capture EU Green Deal embedded carbon compliance premiums before independent recyclers scale. Add closed-die forging capacity in India under PLI scheme incentives to serve export OEM programs. Magnesium input cost volatility represents the priority threat requiring long-term offtake agreements with primary smelters. For New Entrants and Emerging Players: NHTSA FMVSS No. 120 fast-track certification for commercial steel wheels offers entry path through standardized fleet specifications bypassing OEM platform gate complexity. Target North American long-haul trucking where direct foundry contracting is displacing traditional distribution tiers. Aftermarket refinishing operations present most penetrable segment given REACH enforcement gaps at member state customs checkpoints. For Investors and Strategic Acquirers: Long-term, this sits as a consolidation play because procurement leverage is concentrating among three to five foundry groups capable of serving multi-year EV platform contracts. Acquisition targets should exhibit in-house thermal-mechanical fatigue modeling capabilities for regenerative braking load cases. The signal to watch is battery-electric vehicle platform specification releases that rewrite axle load distributions and wheel diameter baselines.| Strategic Initiative | Industry Significance |
|---|---|
| Closed-Loop Aluminum Recycling Investment | Captive remelt capabilities align with EU Green Deal embedded carbon thresholds for European OEM supply. |
| Direct-to-Fleet Digital Channel Development | Telematics-enabled condition monitoring bypasses traditional distributor tiers in North American trucking. |
| Flow-Forming Forging Hybrid Capacity Expansion | European performance OEMs specify these constructions for 20-inch and above thermal management requirements. |
| India PLI Scheme Manufacturing Footprint | Greenfield forging investments serve Maruti Suzuki and Tata Motors export and domestic platform programs. |
| Chromate-Free Coating Qualification | ECHA SVHC compliance maintains corrosion performance under extended warranty terms across European supply chains. |
Research Methodology
A standing panel of OEM platform engineers, Tier 1 supplier procurement directors, aftermarket distributor operations heads, and commercial fleet asset managers provided ongoing calibration against secondary validation from vehicle production databases, IHS Markit registration data, SEC 10-K filings, and customs/trade flow records. Bottom-up segment sizing triangulated against top-down macroeconomic elasticity checks ensured dimensional consistency across product type, vehicle class, manufacturing process, and end-user channel analyses.
Consistency checks against external benchmarks validated volume and value outputs across the projection horizon, with analytical framework modeling vehicle class, propulsion architecture, content per vehicle, OEM tier, and regional production cluster dimensions. CAGRs derived from regression-based trend extrapolation incorporated EV platform specification shifts, REACH compliance deadline impacts, and fleet procurement digitization trajectories as industry-specific forecast inputs.
The analysis sits within stated boundaries; outcomes outside sustained battery-electric vehicle adoption rates, stable magnesium feedstock pricing, or harmonized regulatory load case standards would require recalibration. Forecasts reflect documented assumptions regarding OEM platform launch timing and fleet replacement cycle behavior. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Parts
Automotive Belts and Hoses Market
Automotive Parts
Tappet Market
Automotive Parts
South Africa Commercial Vehicles Lubricants Market
Automotive Parts
X-Arm Type Window Regulator Market
Automotive Parts
Automotive Cylinder Head Gasket Market
Automotive Parts
Global Auto Parts and Accessories Market
Automotive Parts
Vehicle Jump Starter Market
Automotive Parts
Automotive Spring Market
Automotive Parts
Automotive Electric Vacuum Pump Market
Automotive Parts
Suspension Spring Market
Automotive Parts
Automotive Differential Housing Market
Automotive Parts
North America Automotive Foams Market
Automotive Parts
India Automotive Parts Aluminum Die Casting Market
Automotive Parts
Automotive Spacer Ring Market
Automotive Parts
Motorcycle Catalyst Market
Automotive Parts
Automotive Mechanical Control Cable Market