
 Tire Inflating Machine Market | 2026-2036
Tire Inflating Machine Market Size, Share, and Industry Trends Forecast 2026-2036
Tire Inflating Machine Market Outlook
Fleet maintenance operators are unwinding long-standing reliance on manual inflation protocols as commercial vehicle uptime metrics tighten. Michelin leverages captive tire service networks to anchor aftermarket equipment placement across European logistics hubs. Atlas Copco competes through pneumatic technology leadership in high-volume truck service bays. Robert Bosch GmbH extends automotive diagnostic integration into digital inflation systems for passenger vehicle workshops.
A tire inflating machine is a pressure-generating device that delivers compressed air or nitrogen to vehicle tires, typically operating between 0-150 PSI with flow rates calibrated to tire volume and construction type. Its primary commercial purpose is maintaining optimal tire pressure for fuel efficiency, tread longevity, and vehicle safety across automotive, logistics, and industrial mobility applications. Portable units lead the product type category due to roadside assistance and mobile fleet servicing requirements, while digital technology is displacing analog gauges in professional settings where precision liability matters. Electric systems dominate residential and light commercial installations, but pneumatic technology controls margin pools in heavy-duty fleet maintenance where durability under continuous cycling determines total cost of ownership.
NHTSA enforces tire pressure monitoring system compatibility standards that shape inflating machine specifications for US automotive service providers. The EU Green Deal's transport decarbonization framework pushes fleet operators toward precision inflation equipment that reduces rolling resistance and fuel consumption. ISO certification requirements for workshop equipment create compliance barriers for unqualified manufacturers entering European and North American distribution channels. Stakeholders must monitor how battery-electric vehicle weight distributions alter tire pressure protocols and equipment calibration standards.
Market Dynamics
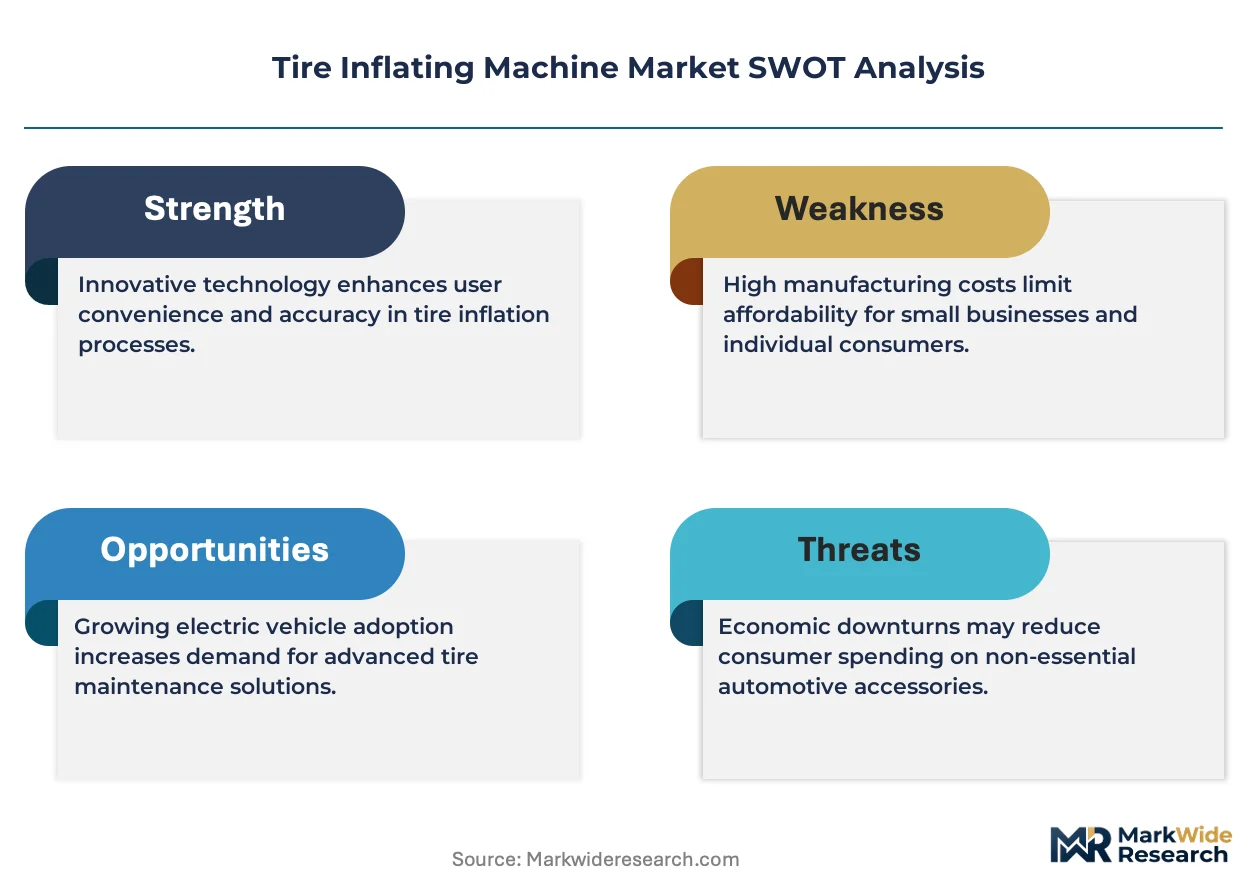
Fleet operators are compressing tire maintenance cycles as automated yard systems replace manual protocols, while NHTSA and EU Green Deal mandates force equipment upgrades across service networks. This structural pressure is redrawing competitive boundaries between pneumatic durability leaders and digital precision entrants.
Growth Catalysts
- EU Green Deal transport decarbonization:Fleet operators face binding fuel efficiency targets that require precision inflation equipment to minimize rolling resistance. German logistics hubs are retrofitting service yards with automated systems to meet compliance deadlines.
- Roadside assistance mobilization:Portable electric inflators are penetrating mobile fleet servicing contracts where uptime guarantees dominate procurement criteria. Light commercial vehicle operators are standardizing 12V DC units for field deployment.
- NHTSA TPMS mandate enforcement:US automotive service providers must maintain compatible calibration equipment, creating replacement demand as analog gauge systems age out of certification.
Market Restraints
- Aluminum alloy input volatility:Pneumatic system housings and compressor castings face commodity price swings that compress margin pools for mid-tier manufacturers without captive metal sourcing.
- ISO certification barriers:European and North American distribution channels require workshop equipment standards that disqualify unqualified Asian manufacturers from premium segment participation.
- Compressed air substitution:Nitrogen inflation systems are capturing high-value fleet maintenance contracts where oxidation prevention and pressure stability justify premium pricing over atmospheric air solutions.
Strategic Opportunities
- India commercial vehicle fleet expansion:Domestic logistics growth and PLI scheme manufacturing incentives are creating demand for durable pneumatic systems in truck service bays lacking automated infrastructure.
- Battery-electric vehicle weight protocols:Heavier EV powertrains are altering tire pressure specifications, opening calibration service opportunities for equipment manufacturers who adapt sensor integration and software updates.
- Direct-to-fleet distribution:Bypassing traditional automotive service channels, manufacturers are selling automated inflation systems through procurement contracts with national logistics operators seeking centralized maintenance control.
Industry Challenges
- Pneumatic technician scarcity:Heavy-duty fleet maintenance requires specialized compressed air system diagnostics that vocational training programs have deprioritized in favor of electric vehicle curricula.
- Legacy analog integration:Digital inflation systems must interface with existing shop air infrastructure designed for mechanical gauges, creating commissioning delays and compatibility disputes.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Tire Inflating Machine Market |
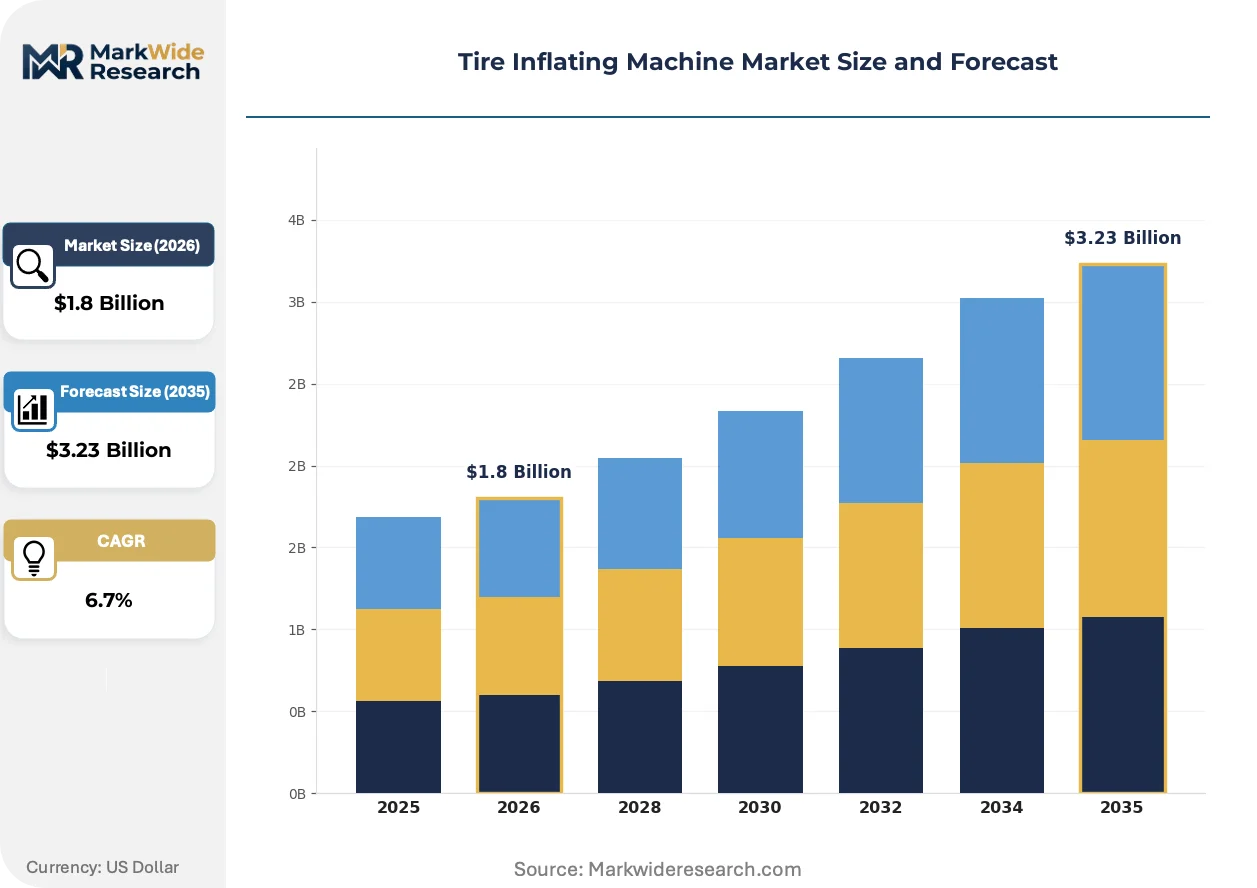
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Portable, Stationary, Digital, Analog End User: Automotive Shops, Service Stations, Fleet Maintenance, Residential Users Technology: Electric, Pneumatic, Mechanical, Hybrid Installation: Wall-Mounted, Free Standing, Integrated, Mobile |
| Companies Covered | Michelin, VIAIR, Slime, BONAIRE Industries, Hendrickson USA, Robert Bosch GmbH, Stanley Black & Decker, Atlas Copco, Gardner Denver Holdings, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Tire Inflating Machine Market Strategic Shifts
Digital pressure sensing technology is fragmenting the equipment landscape as precision liability concerns displace tolerance for analog measurement error. Three developments are compressing competitive timelines across product categories.
MEMS-based pressure transducers are decomposing the traditional mechanical gauge supply chain by embedding semiconductor sensors directly into inflator wands and hose assemblies. Commercial vehicle service chains in Germany are adopting these systems for warranty documentation purposes. The technology is decomposing price premiums previously commanded by calibrated dial instruments, forcing analog specialists into aftermarket replacement parts.
REACH chemical compliance is extending to pneumatic lubricants and seal materials used in compressor systems, forcing reformulation of maintenance consumables. Equipment manufacturers serving EU markets must certify component materials against substance restriction lists. Workshop operators in France and the Netherlands are prioritizing compliant systems to avoid liability exposure during environmental inspections.
Fleet procurement departments are consolidating tire service contracts under total-cost-of-ownership frameworks that bundle inflation equipment with predictive maintenance software. National logistics operators are displacing decentralized shop-level purchasing decisions with centralized vendor selection. This concentration is most visible in US long-haul trucking networks where fuel economy guarantees now determine equipment specification authority.
Tire Inflating Machine Market Segmentation
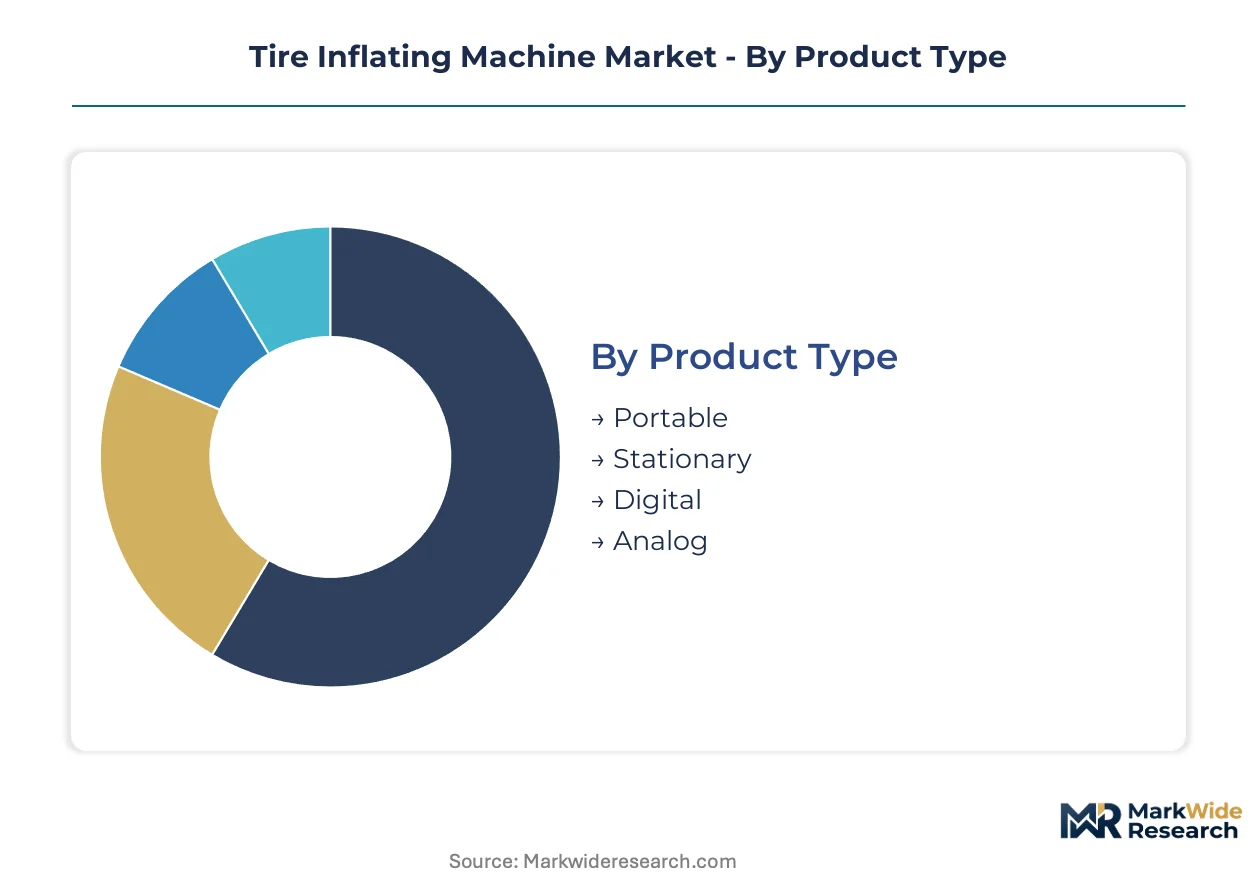
Tire inflating machine procurement decisions split sharply between mobility requirements and fixed infrastructure investments. Fleet operators prioritize uptime compatibility while automotive service chains balance precision liability against capital deployment cycles.
Product Type:
Portable units face substitution pressure from integrated vehicle compressor systems in light-duty applications, while stationary equipment defends position through calibration certification requirements.
- Portable:Battery-powered and 12V DC units dominate roadside assistance contracts and mobile fleet servicing where vehicle uptime guarantees dictate equipment selection. Demand concentrates in German logistics hubs retrofitting service vans with automated inflation capability to meet EU Green Deal fuel efficiency deadlines.
- Stationary:Fixed compressor installations serve high-volume truck service bays with continuous cycling durability requirements. US long-haul trucking networks specify these systems for centralized yard maintenance facilities under NHTSA TPMS compliance frameworks.
- Digital:MEMS-based pressure transducers embed semiconductor sensors directly into inflator wands for warranty documentation precision.
- Analog:Mechanical gauge systems persist in price-sensitive replacement markets and legacy workshop infrastructure.
Stationary retains volume leadership; Digital holds the steepest expansion curve.
End User:
Cost tier stratification separates capital-intensive fleet operations from discretionary residential purchases, with service stations occupying a contested middle ground.
- Fleet Maintenance:National logistics operators consolidate tire service contracts under total-cost-of-ownership frameworks that bundle inflation equipment with predictive maintenance software. Procurement authority has shifted from decentralized shop-level decisions to centralized vendor selection in US long-haul networks.
- Automotive Shops:Passenger vehicle workshops integrate digital inflation systems with diagnostic platforms to meet precision liability standards. German automotive service chains lead retrofitting activity with equipment placement through captive tire service networks.
- Service Stations:High-traffic retail fuel locations deploy coin-operated and automated units for consumer self-service.
- Residential Users:Light commercial vehicle operators standardize 12V DC portable units for field deployment and emergency preparedness.
Fleet Maintenance commands margin concentration; Automotive Shops face the most rapid technology displacement.
Technology:
Application severity determines technology selection, with heavy-duty cycling requirements favoring pneumatic durability over electric convenience.
- Pneumatic:Compressed air systems control margin pools in heavy-duty fleet maintenance where durability under continuous cycling determines total cost of ownership. Aluminum alloy housing castings face commodity price volatility that compresses margins for mid-tier manufacturers without captive metal sourcing.
- Electric:Motor-driven compressors dominate residential and light commercial installations for plug-and-play simplicity. Portable electric inflators penetrate mobile fleet servicing contracts where field deployment speed outweighs cycling endurance.
- Mechanical:Foot-pump and hand-operated systems persist in emergency backup applications and regulatory compliance kits.
- Hybrid:Dual-power systems combine battery portability with AC grid capability for flexible workshop deployment.
Pneumatic retains durability premiums; Electric captures volume scaling.
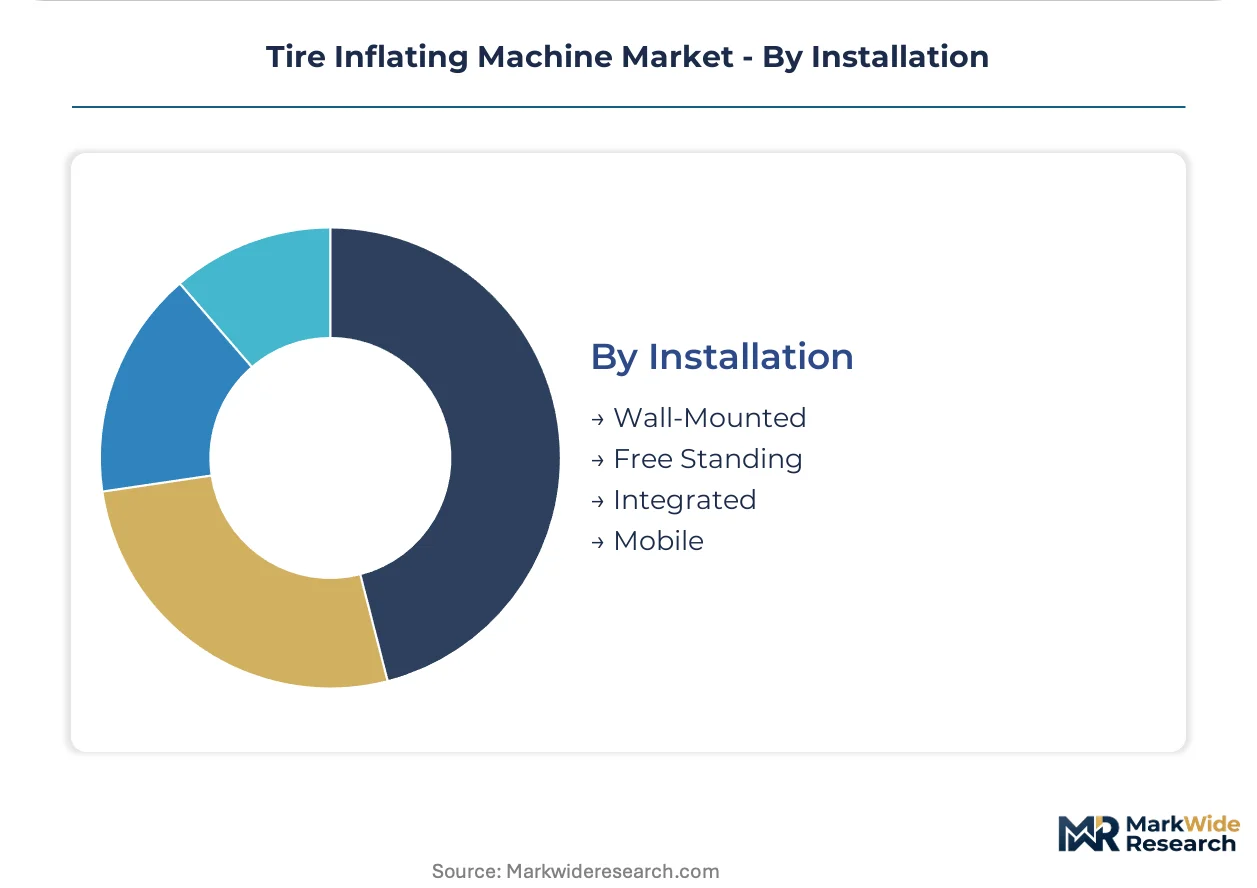
Installation:
Volume concentration in established service infrastructure favors wall-mounted and free-standing formats, while mobility requirements fragment the remaining demand.
- Wall-Mounted:Fixed installations maximize floor space efficiency in congested European workshop environments. French and Netherlands operators prioritize REACH-compliant systems to avoid liability exposure during environmental inspections.
- Free Standing:Modular compressor units allow reconfiguration of service bay layouts without structural modification. These systems dominate retrofitting activity in Indian commercial vehicle service bays lacking automated infrastructure.
- Integrated:Built-in inflation modules merge with vehicle lift and diagnostic platforms for streamlined workflow.
- Mobile:Cart-mounted and vehicle-integrated systems serve field deployment and temporary service locations.
Free Standing retains retrofit flexibility; Wall-Mounted gains share in space-constrained urban markets.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German manufacturers export precision inflation systems to US fleet operators, establishing a transatlantic trade corridor that channels European pneumatic technology into North American logistics infrastructure.
United States
Long-haul trucking networks compress tire maintenance cycles as automated yard systems replace manual protocols. NHTSA TPMS mandate enforcement requires compatible calibration equipment, creating replacement demand across service providers. Dallas-Fort Worth logistics hubs concentrate procurement authority under centralized fleet management contracts.
Germany
Automotive service chains retrofit workshops with digital inflation equipment to meet EU Green Deal transport decarbonization targets. REACH chemical compliance extends to pneumatic lubricants and seal materials, forcing reformulation of maintenance consumables. Stuttgart industrial corridor anchors captive tire service network expansion.
China
Domestic logistics growth accelerates demand for durable pneumatic systems in truck service bays lacking automated infrastructure. MIIT equipment certification standards create compliance barriers for unqualified manufacturers entering premium distribution channels. Yangtze River Delta manufacturing clusters scale compressor housing production for regional supply.
India
Commercial vehicle fleet expansion drives demand for heavy-duty cycling equipment under PLI scheme manufacturing incentives. BIS workshop equipment standards disqualify uncertified imports from formal service channel participation. Maharashtra logistics corridors retrofit service facilities with free-standing modular compressor units.
Japan
Passenger vehicle workshops integrate digital inflation systems with diagnostic platforms to meet precision liability standards. METI industrial equipment efficiency guidelines shape procurement specifications for service bay automation. Kanto region automotive clusters adopt MEMS-based pressure transducers for warranty documentation.
Tire Inflating Machine Market Competitive Environment
Listed leaders compete with private specialists across pneumatic technology and digital precision segments. Market structure fragments between consolidated tire service networks and dispersed equipment fabricators serving regional aftermarket channels. Three archetypes dominate: integrated tire manufacturers leveraging captive service placement, pneumatic technology specialists controlling heavy-duty durability premiums, and diversified industrial conglomerates extending diagnostic platforms into inflation equipment. Competitive moves concentrate on strategic partnerships with fleet operators and backward integration into compressor component supply.
Among European industrial conglomerates, Robert Bosch GmbH and Atlas Copco occupy positions at opposite ends of the technology spectrum. Bosch exemplifies diagnostic-integrated digital systems for passenger vehicle workshops, while Atlas Copco represents pneumatic durability leadership in high-volume commercial applications. Michelin, the integrated tire manufacturer, anchors aftermarket equipment placement through captive service networks. Stanley Black & Decker, the diversified tool and equipment provider, sits within the portable electric segment serving mobile fleet servicing contracts.
| Leading Market Players |
|---|
| Michelin |
| VIAIR |
| Slime |
| BONAIRE Industries |
| Hendrickson USA |
| Robert Bosch GmbH |
| Stanley Black & Decker |
| Atlas Copco |
| Gardner Denver Holdings |
| Others |
Value Chain & Pricing Dynamics
ISO certification requirements for workshop equipment gate both supply qualification and price differentiation simultaneously, forcing unqualified manufacturers toward economy tiers while certified incumbents capture premium positioning through NHTSA TPMS and EU Green Deal compliance bundling.
Pricing Analysis
Digital-to-analog-to-hybrid technology generations create a pricing gap where MEMS-based systems command premium placement against mechanical gauge replacements. Three-tier pricing structure across precision-certified, standard-compliant, and economy tiers separates fleet maintenance contracts from residential purchases. Cost compression in pneumatic housing castings intensifies because aluminum alloy input volatility squeezes mid-tier manufacturers without captive metal sourcing. Fleet operators show least price sensitivity where total-cost-of-ownership frameworks bundle inflation equipment with predictive maintenance software, while residential users drive volume at economy tiers.
Supply Chain Analysis
Yangtze River Delta manufacturing clusters anchor compressor housing production, creating a chokepoint where Chinese scale advantages concentrate casting and machining capacity. Component supply draws from Germany for precision pneumatic systems, China for aluminum alloy castings, and India for PLI-incentivized assembly operations. Raw material dependencies span aluminum alloys for housings, semiconductor sensors for MEMS transducers, and specialized lubricants for REACH-compliant seal materials. Single-source vulnerability runs through Yangtze Delta casting capacity for pneumatic system enclosures. Distribution runs through captive tire service networks for fleet placement, automotive service chains for workshop retrofitting, and direct procurement contracts for national logistics operators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Integrated vehicle compressor systems threaten portable unit incumbents as OEMs embed inflation capability directly into light-duty platforms, forcing equipment specialists to defend placement through fleet aftermarket contracts and heavy-duty durability premiums.
For Market Incumbents: Shield installed base relationships by embedding software update capability for battery-electric vehicle pressure protocols before diagnostic-integrated competitors capture calibration service revenue. Backward integration into aluminum alloy casting capacity defends margin position against commodity volatility that mid-tier pneumatic manufacturers cannot absorb. Prioritize NHTSA TPMS certification maintenance as analog systems age out of compliance to lock replacement demand.
For New Entrants and Emerging Players: Differentiate on nitrogen inflation system specialization where oxidation prevention justifies premium pricing over atmospheric air solutions in high-value fleet contracts. Target Indian commercial vehicle service bays lacking automated infrastructure through free-standing modular compressor formats that retrofit existing facilities without structural modification. Pursue direct-to-fleet distribution bypassing traditional automotive service channels where procurement authority has centralized under national logistics operators.
For Investors and Strategic Acquirers: EU Green Deal transport decarbonization deadlines reshape the acquisition landscape by compressing valuation windows for precision inflation equipment specialists ahead of compliance-driven fleet retrofitting waves. Long-term viability hinges on software-enabled calibration service revenue rather than hardware placement alone. Prioritize targets with MEMS sensor integration capability and predictive maintenance platform development. Watch battery-electric vehicle weight distribution standards as the signal indicating which equipment manufacturers have adapted sensor protocols for emerging powertrain specifications.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Aluminum Casting | Captive alloy sourcing insulates pneumatic manufacturers from commodity volatility compressing mid-tier margins. |
| Nitrogen Inflation System Specialization | Oxidation prevention capability captures premium fleet contracts where pressure stability reduces rolling resistance. |
| MEMS Sensor Platform Development | Semiconductor-embedded wands displace calibrated dial instruments for warranty documentation precision. |
| Direct Fleet Procurement Contracts | Bypassing automotive service channels concentrates vendor selection under centralized logistics operator authority. |
| REACH-Compliant Lubricant Reformulation | Certified seal materials and consumables unlock French and Netherlands workshop operator procurement. |
Study Parameters
Initial hypotheses were tested against primary input from fleet maintenance directors, automotive service chain procurement managers, pneumatic equipment technicians, and aftermarket distribution channel heads and refined through secondary validation against NHTSA regulatory filings, EU Green Deal transport decarbonization documentation, ISO equipment certification registries, and customs trade data for aluminum alloy compressor component flows. Bottom-up triangulation across product category demand curves and top-down reconciliation against regional fleet operator expenditure patterns anchored volume estimates.
Variance decomposition across the projection horizon isolates technology substitution effects, regulatory compliance deadlines, and raw material cost trajectories as independent drivers. Segmentation dimensions modeled include product mobility format, end-user cost tier, pneumatic versus electric technology, and installation configuration. CAGRs were derived from fitted growth curves against historical equipment replacement cycles and forward compliance mandate schedules. Industry-specific forecast inputs incorporate battery-electric vehicle weight distribution protocol evolution and nitrogen inflation system penetration rates in premium fleet contracts.
Material uncertainties — aluminum alloy price volatility, REACH chemical restriction expansion, and vocational training program prioritization shifts — sit outside the modeled envelope. Forecasts reflect assumptions about regulatory enforcement continuity and fleet operator procurement centralization trends. Practitioners should keep alternative scenarios live as battery-electric vehicle tire pressure calibration standards and integrated vehicle compressor system adoption curves evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Tires and Wheels
Specialty Tire Market
Tires and Wheels
Cargo Bike Tire Market
Tires and Wheels
Global Off-Highway Tire Market
Tires and Wheels
Green Tires Market
Tires and Wheels
Tire Carousel Market
Tires and Wheels
Europe 2-Wheeler Replacement Tire Market
Tires and Wheels
Asia-Pacific Automotive Tire Pressure Management System Market
Tires and Wheels
Alloy Wheels Market
Tires and Wheels
Low Rolling Resistance Tire Market
Tires and Wheels
Two Wheeler Tire Market
Tires and Wheels
Performance Tires Market
Tires and Wheels
Elastic Polyurethane Wheels Market
Tires and Wheels
Global Ultra High Performance Tire Market
Tires and Wheels
Run Flat Tire Inserts Market
Tires and Wheels
Self-Sealing Tire Market
Tires and Wheels
Carbon Wheels Market