
 North America Tire Market | 2026-2036
North America Tire Market Size, Share, and Industry Trends Forecast 2026-2036
North America Tire Market Intelligence
Advanced silica compounds and sustainable rubber sourcing are reshaping how tire manufacturers formulate tread and sidewall compositions for the North American climate. Michelin leverages its R&D footprint in Greenville, South Carolina to test bio-sourced materials across temperature extremes. Goodyear anchors its position through proprietary soybean-oil tread technology and extensive retail-service integration. Bridgestone competes via its Nashville-based commercial tire solutions center, which controls fleet-service contracts across the southeastern United States.
A tire is an engineered composite structure comprising rubber compounds, steel belts, textile plies, and chemical additives, manufactured through calendering, extrusion, and vulcanization to achieve specified load ratings, speed indices, and rolling-resistance coefficients. Its primary purpose is to transmit vehicle forces to road surfaces while managing wear, heat dissipation, and ride comfort across diverse operating conditions. The passenger car segment dominates volume but faces margin compression from commoditization, while the commercial vehicle application generates superior profitability through fleet-service contracts and retread programs. Radial technology leads in both OEM fitment and replacement demand, whereas the online retail channel is gaining share as direct-to-consumer fitment tools reduce dealer dependency.
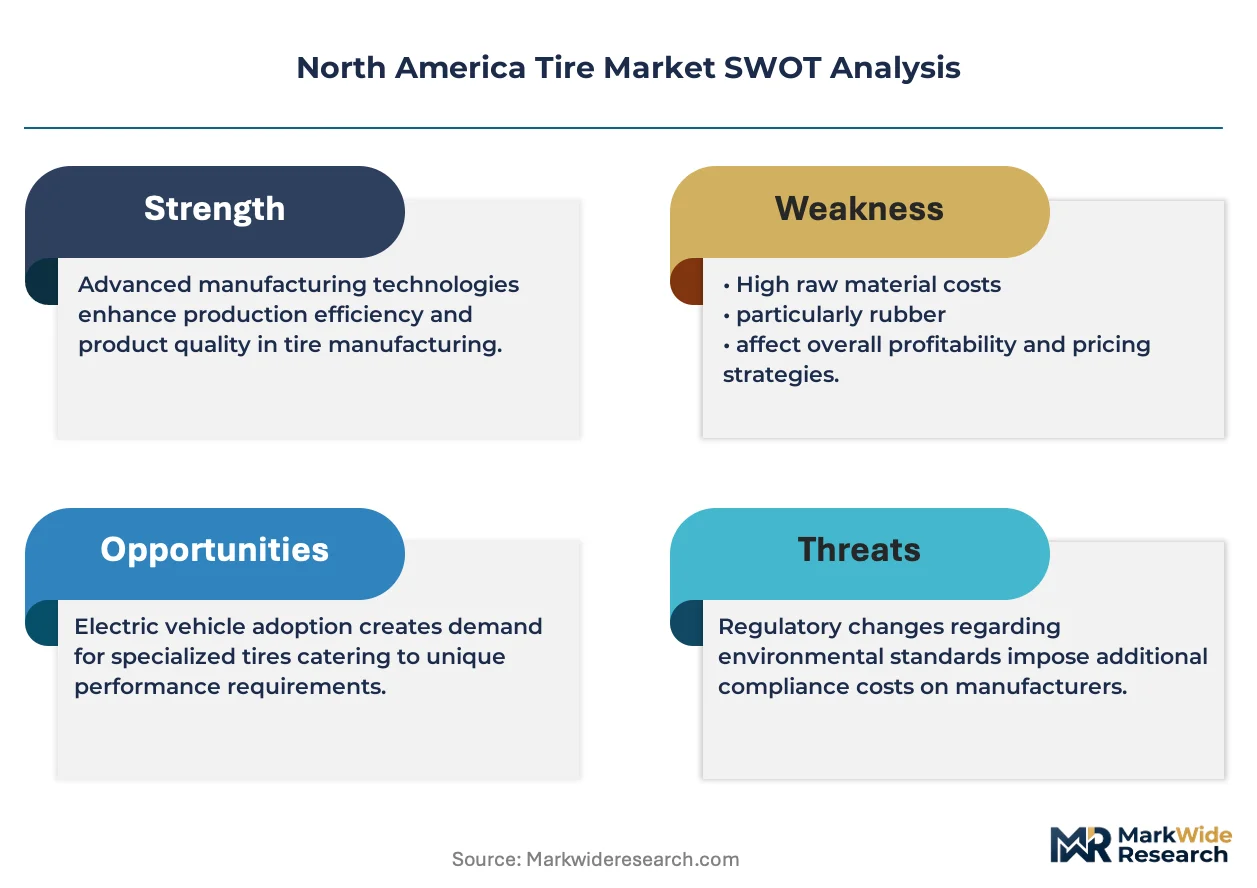
The U.S. National Highway Traffic Safety Administration enforces the Uniform Tire Quality Grading standards for treadwear, traction, and temperature resistance, while Transport Canada mandates bilingual labeling and winter-performance certification under its tire regulations. These frameworks elevate compliance costs for imported products and create preference for North American-certified manufacturing. Stakeholders must monitor how proposed revisions to Corporate Average Fuel Economy standards recalibrate rolling-resistance targets and retooling requirements across the supply base.
Market Dynamics
Fleet electrification timelines and Corporate Average Fuel Economy rolling-resistance mandates are compressing tire development cycles, forcing manufacturers to retool compounds and tread geometries faster than traditional vulcanization schedules permit.
Growth Catalysts
- Fleet electrification mandates:The U.S. EPA's heavy-duty vehicle emission standards are accelerating demand for low-rolling-resistance tires optimized for electric drivetrain torque profiles.
- Last-mile logistics expansion:E-commerce fulfillment networks across the U.S. Great Lakes corridor are driving replacement cycles for commercial van and light truck radials.
- Retread program economics:Commercial fleet operators are extending casing life through proprietary retreading systems, reducing per-mile tire costs by 30-50% versus new tire procurement.
Market Restraints
- Natural rubber price volatility:Southeast Asian supply disruptions and currency fluctuations are compressing gross margins on commodity-grade passenger tires.
- Steel cord supply concentration:Domestic wire rod production capacity constraints in the Ohio River Valley are lengthening lead times for radial belt packages.
- Winter certification friction:Transport Canada's mandatory mountain snowflake testing adds 8-12 weeks to product approval timelines for cross-border tire lines.
Strategic Opportunities
- Direct-to-consumer fitment platforms:Mobile mounting services and AI-based size-matching tools are bypassing traditional dealer networks in suburban U.S. markets.
- Sustainable material mandates:The U.S. Department of Agriculture's BioPreferred program creates procurement preference for tires incorporating bio-sourced oils and recycled carbon black.
- Autonomous vehicle integration:Tire pressure monitoring systems with edge-computing capabilities are becoming specification requirements for robotaxi fleet operators.
Industry Challenges
- Compound formulation talent scarcity:Polymer chemistry expertise for silica-silane coupling systems is concentrated among retiring specialists at legacy Akron-area R&D centers.
- Smart tire IP complexity:Sensor-embedded tread designs are triggering patent disputes between tier-one suppliers and semiconductor component manufacturers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Tire Market |
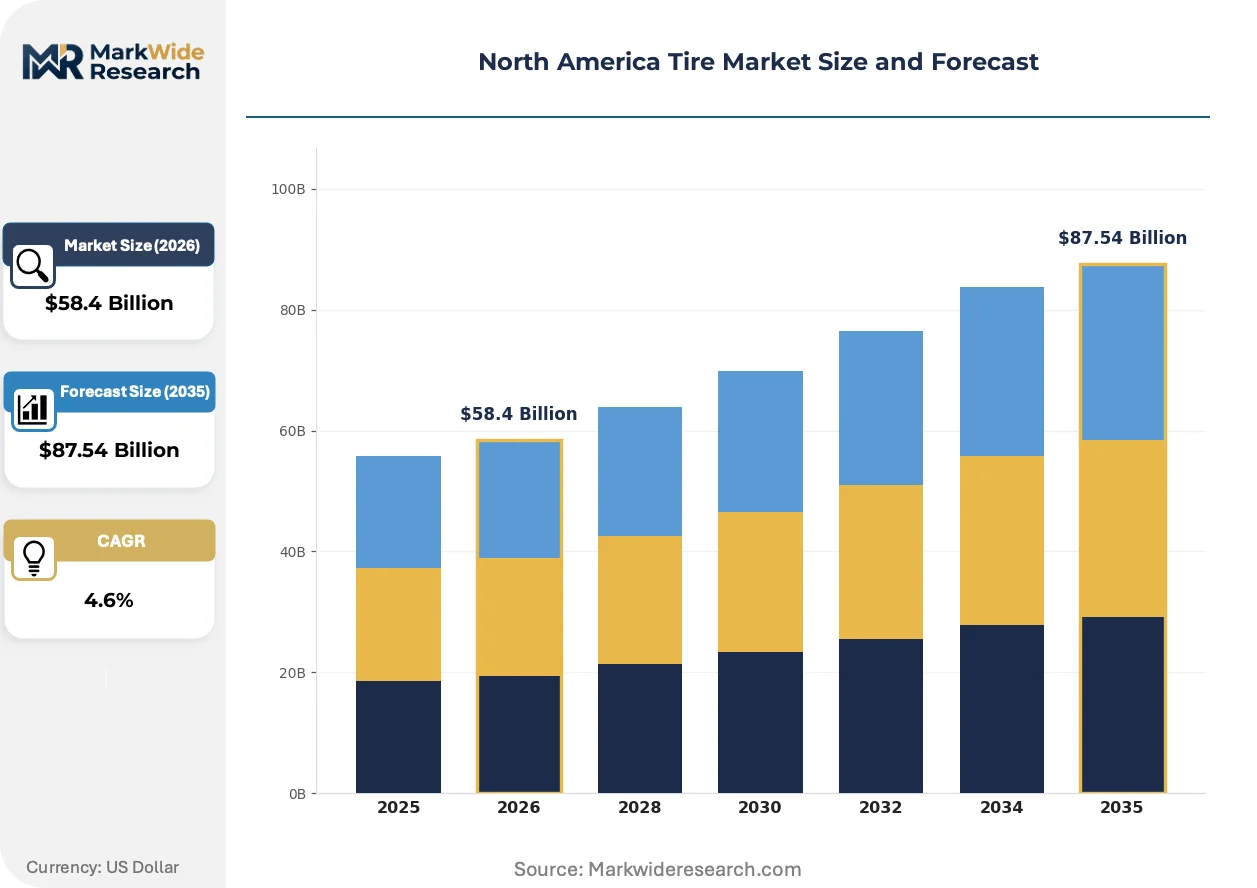
| Market Size in 2026 | $58.4 Billion |
| Market Size in 2035 | $87.54 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Passenger Car, Light Truck, Heavy Truck, Two-Wheeler Application: OEM, Replacement, Motorsports, Commercial Vehicles Technology: Radial, Bias, All-Season, Performance Distribution Channel: Online Retail, Discount Stores, Tire Dealers, Wholesale |
| Companies Covered | Continental, Sumitomo Rubber Industries, Michelin, Yokohama Rubber, Hankook, Bridgestone, Pirelli, Cooper Tire, Goodyear, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Tire Market Strategic Shifts & Innovations
Digital tire monitoring and predictive maintenance platforms are converging with sustainable material science to redefine how fleet operators manage lifecycle costs and regulatory compliance across North American road networks.
Sensor-integrated intelligent tires are virtualizing the traditional inspection and replacement workflow. Commercial fleet managers at long-haul operators are deploying continuous pressure, temperature, and tread-depth telemetry. This capability is virtualizing scheduled manual inspections into algorithm-driven, condition-based interventions that compress downtime and extend casing utilization rates.
The U.S. National Highway Traffic Safety Administration's proposed updates to Uniform Tire Quality Grading standards are elevating wet-traction performance thresholds. Manufacturers serving the replacement market must reformulate tread compounds and resubmit test data. The all-season passenger segment faces the steepest retooling burden as existing SKUs risk downgraded ratings under stricter hydroplaning resistance protocols.
Subscription-based tire-as-a-service models are displacing upfront purchase patterns among municipal and corporate fleet operators. Third-party fleet management providers are bundling installation, rotation, and replacement into per-mile contracts. This shift is most pronounced in California and Texas, where large commercial vehicle pools prioritize operational expenditure predictability over capital deployment.
North America Tire Market Segmentation
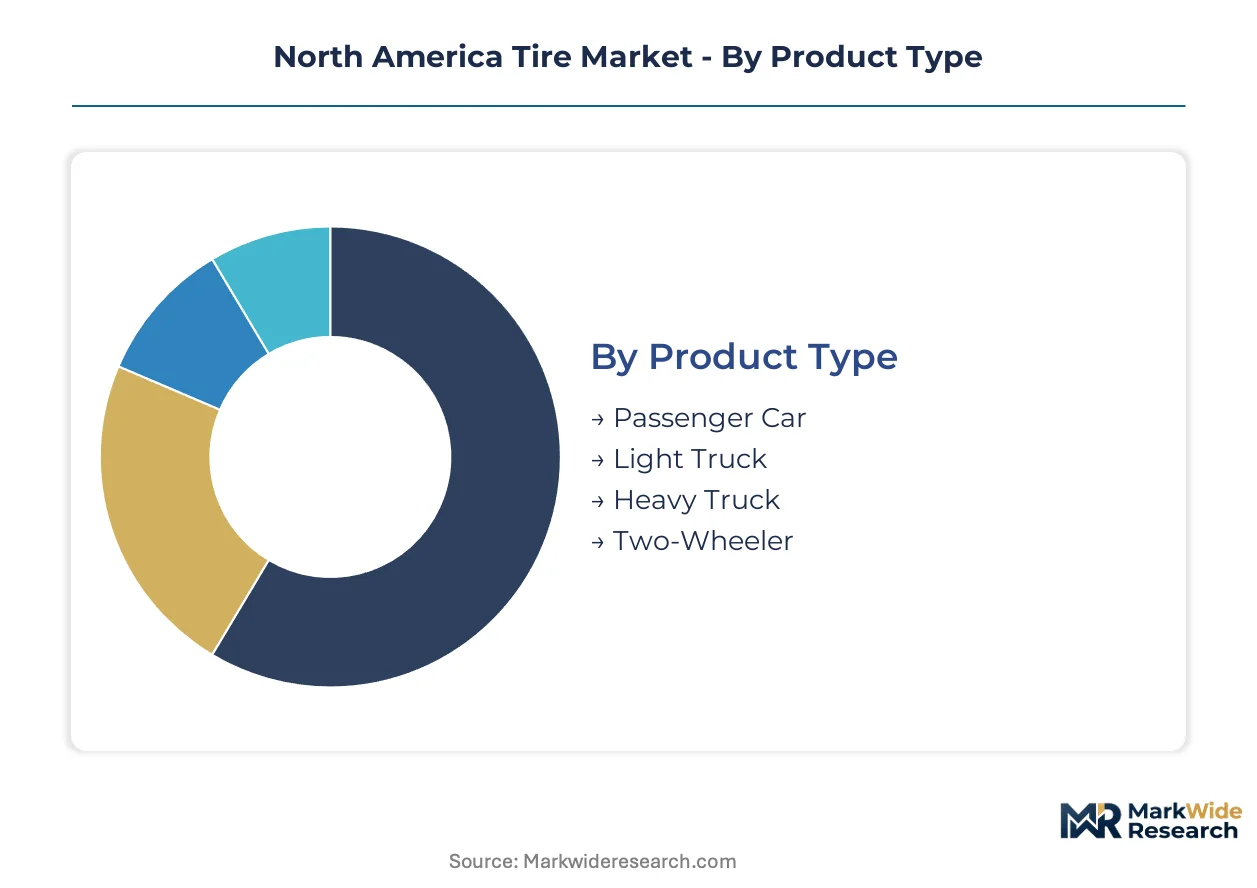
Tire replacement cycles vary dramatically across vehicle classes and duty profiles, creating divergent margin structures and inventory velocity requirements for manufacturers and distributors. Understanding these turnover dynamics enables precise capacity allocation and channel strategy calibration.
Product Type:
Replacement intervals compress from passenger vehicles through heavy commercial equipment, with fleet utilization intensity and load severity driving fundamentally different procurement rhythms.
- Passenger Car:All-season radial constructions dominate volume with standardized 16-18 inch fitments for compact and mid-size sedans. Fleet operators in the U.S. Great Lakes corridor prioritize 50,000-mile treadwear warranties for high-mileage commuter pools.
- Heavy Truck:Multi-position steer, drive, and trailer configurations with reinforced belt packages withstand 80,000-pound gross vehicle weights. Long-haul operators across Interstate 80 corridors demand 18-month casing warranties to support multiple retread cycles.
- Light Truck:P-metric and LT-rated sidewalls serve contractor and recreational towing applications with enhanced load range specifications.
- Two-Wheeler:Motorcycle and scooter fitments concentrate in urban California and Florida markets with sport-touring and cruiser compound variants.
Passenger car tires anchor the volume base while heavy truck tires gain share at the steepest rate through fleet electrification and expanded logistics coverage.
Application:
Procurement authority separates into capital-intensive upfront specification versus operational replacement budgeting, with distinct margin and contract structures.
- Replacement:Aftermarket demand flows through independent service centers and retail chains with price-transparent comparison shopping. The U.S. Department of Transportation's tread-depth enforcement drives predictable seasonal surges in northern states.
- OEM:Original equipment fitment requires multi-year platform commitments with vehicle manufacturers, embedding rolling-resistance targets into compound development roadmaps years ahead of production.
- Commercial Vehicles:Fleet-service contracts bundle installation, rotation, and casing management into per-mile operational expenditures.
- Motorsports:Slick and wet-weather racing compounds serve sanctioned series with rapid heat-cycle degradation and no retread potential.
Replacement tires command the revenue base while commercial vehicle contracts expand most quickly through subscription-based tire-as-a-service models.
Technology:
Manufacturing complexity and material science intensity stratify across construction methods, with silica-silane coupling systems commanding premium positioning.
- Radial:Steel-belted radial architecture with polyester or nylon body plies delivers superior fuel efficiency and tread life. The U.S. EPA's heavy-duty vehicle emission standards accelerate low-rolling-resistance radial adoption for electric drivetrain compatibility.
- All-Season:Tread compounds balanced across temperature ranges with siping patterns for wet traction and light snow. Transport Canada's mandatory mountain snowflake testing elevates formulation requirements for cross-border product lines.
- Performance:Summer-focused compounds with asymmetric tread designs and speed ratings exceeding 149 mph for enthusiast segments.
- Bias:Cross-ply construction persists in specialty agricultural and industrial applications with lower speed requirements.
Radial technology anchors the volume base while all-season configurations climb the fastest through regulatory traction mandates and climate variability.
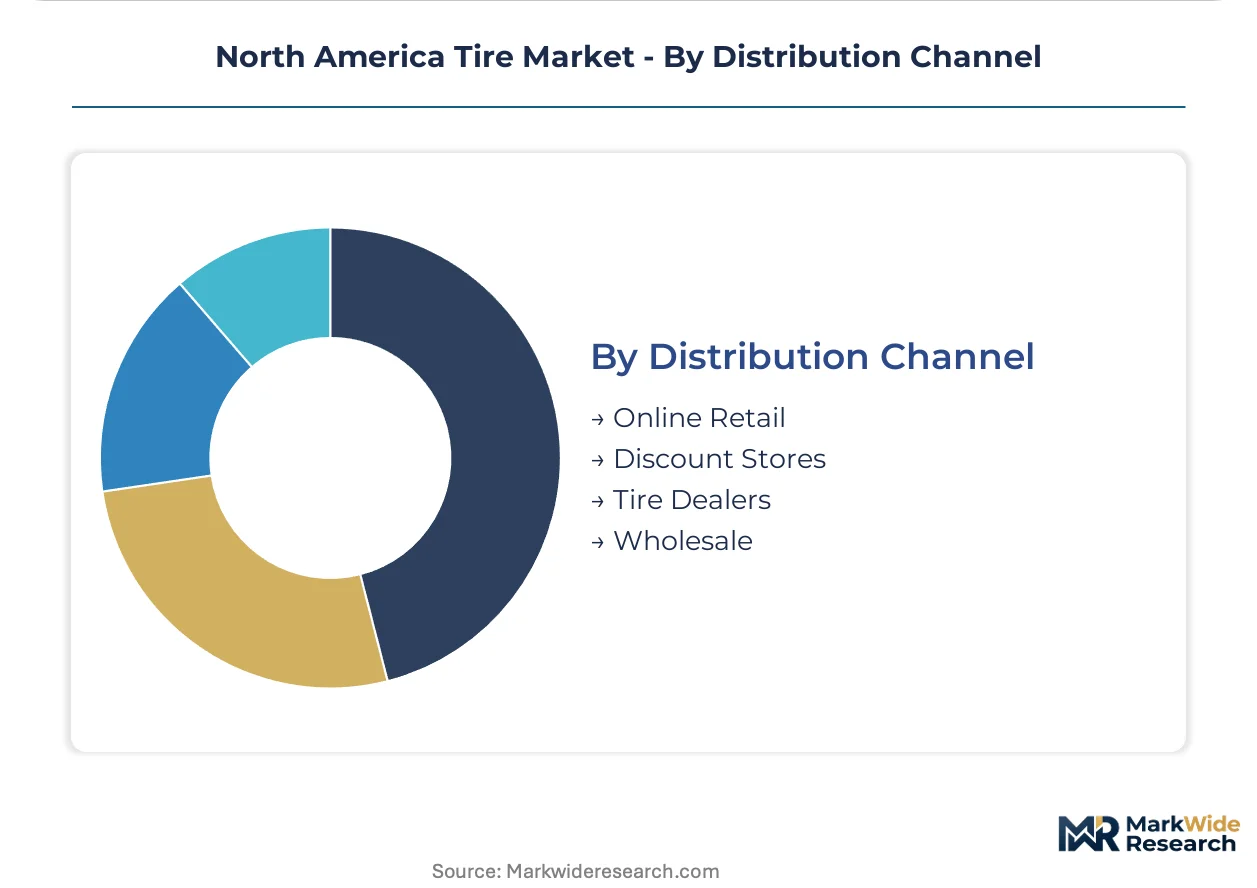
Distribution Channel:
Channel economics diverge between inventory-heavy physical networks and asset-light digital platforms with mobile fulfillment capabilities.
- Tire Dealers:Independent and branded service centers with mounting, balancing, and alignment equipment capture premium installation margins. Michigan and Ohio dealer networks leverage proximity to manufacturing facilities for rapid replenishment.
- Online Retail:Direct-to-consumer platforms with AI-based fitment tools and mobile van mounting services bypass traditional retail overhead. California and Texas suburban markets show the steepest digital adoption curves.
- Wholesale:Distributor networks serving independent repair shops and fleet maintenance facilities with bulk pricing and private-label options.
- Discount Stores:Mass merchandisers with limited service capabilities compete on price for self-installing consumers.
Tire dealers anchor the volume base while online retail gains share fastest through fitment technology and convenience-oriented suburban demographics.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Canadian tire exports flow southward into U.S. Great Lakes distribution hubs, while Mexican manufacturing corridors supply radial assemblies for cross-border fleet operators. This trilateral trade pattern concentrates procurement authority in U.S. commercial vehicle pools.
United States
Michigan and Ohio host concentrated tire production and testing infrastructure serving domestic OEM contracts and aftermarket channels. The NHTSA enforces Uniform Tire Quality Grading standards for treadwear, traction, and temperature resistance that elevate compliance costs for imported products. Fleet operators across the Great Lakes corridor are expanding orders for all-season radial tires as delivery networks broaden coverage.
Canada
Cross-border logistics networks drive replacement demand for commercial van and light truck fitments in Ontario and Quebec. Transport Canada mandates bilingual labeling and winter-performance certification under its tire regulations, adding approval timelines for mountain snowflake testing. Quebec's winter tire mandate sustains seasonal demand spikes for cold-weather compounds.
Mexico
Manufacturing investments in Nuevo León and the Bajío Region support radial assembly for U.S. fleet-service contracts. Mexico's proximity to Texas and California distribution hubs reduces freight costs for high-volume commercial tire shipments. The country's automotive supplier base is deepening integration with North American OEM just-in-sequence production schedules.
North America Tire Market Key Industry Players
On the supply side, the industry is consolidating around integrated manufacturers with captive R&D and retread service networks. Tier-one suppliers with proprietary compound science and fleet-management platforms command premium positioning in commercial vehicle contracts. Three archetypes dominate: integrated multinationals with full-cycle manufacturing, regional specialists with retread-focused service models, and technology licensors supplying compound patents. Competitive dynamics center on backward integration into sustainable rubber sourcing and geographic expansion of mobile mounting services.
Within the integrated multinational tier, Continental, Michelin, and Bridgestone occupy positions defined by R&D scale and fleet-service infrastructure. These manufacturers exemplify the archetype of suppliers controlling vulcanization technology, distribution logistics, and casing management programs under unified operational umbrellas. Their market presence anchors pricing benchmarks across both OEM specification channels and replacement aftermarket segments.
| Leading Market Players |
|---|
| Continental |
| Sumitomo Rubber Industries |
| Michelin |
| Yokohama Rubber |
| Hankook |
| Bridgestone |
| Pirelli |
| Cooper Tire |
| Goodyear |
| Others |
Cost & Logistics Intelligence
Underutilized radial belt capacity in the Ohio River Valley is pressuring manufacturers to accept thinner margins on commodity passenger tires while redirecting compound R&D investment toward premium fleet-service contracts. This utilization asymmetry between high-volume low-margin and low-volume high-margin segments shapes procurement negotiations and supplier consolidation timelines across the North American replacement channel.
Pricing Analysis
Next-generation silica-silane coupling compounds command 15-25% premiums over conventional carbon-black formulations, while legacy bias-ply constructions face accelerated price erosion in agricultural specialty niches. Three-tier pricing structure across premium, standard, and economy levels stratifies by rolling-resistance certification grade and retread casing warranty duration. Cost compression in the economy passenger segment intensifies because Southeast Asian import competition and currency headwinds squeeze landed costs. Fleet operators with centralized procurement functions exhibit lowest price sensitivity, whereas independent owner-operators in the replacement channel comparison-shop aggressively across digital platforms.
Supply Chain Analysis
Contract manufacturing concentration among Michelin's Greenville facility, Bridgestone's Nashville solutions center, and Continental's Fort Mill campus controls premium radial capacity for U.S. OEM just-in-sequence programs. Raw material flows draw from Thai and Indonesian natural rubber plantations, Ohio River Valley steel cord mills, and Louisiana carbon black facilities. Single-source vulnerability in winter-compound specialty polymers creates approval timeline risk for cross-border product lines. Distribution runs through Michigan and Ohio wholesale hubs serving Great Lakes corridor dealers, with direct-to-consumer platforms bypassing traditional inventory-heavy networks in California and Texas suburban markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fleet electrification mandates and last-mile logistics expansion represent early-cycle tailwinds still below saturation thresholds across commercial vehicle segments. Penetration of tire-as-a-service subscription models remains under 20% outside California and Texas, leaving substantial runway for contract conversion.
For Market Incumbents: Insulate proprietary retread casing management programs from digital-native entrants by embedding sensor-integrated pressure monitoring into fleet-service contracts. Backward integration into sustainable rubber sourcing through USDA BioPreferred program qualification creates procurement preference stickiness. Capacity addition in Nuevo León supports just-in-sequence OEM commitments while hedging Ohio River Valley steel cord lead time volatility. For New Entrants and Emerging Players: Direct-to-consumer fitment platforms with AI-based size-matching tools and mobile van mounting services in suburban Texas and California represent the most penetrable entry point for bypassing dealer network incumbency. Municipal fleet tire-as-a-service contracts in mid-sized Great Lakes corridor cities offer consolidated procurement authority with lower incumbent switching costs. White-label compound sourcing from established manufacturers enables rapid SKU launch without captive vulcanization investment. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among fleet-management providers bundling installation, rotation, and casing replacement into per-mile operational expenditures. Over the coming decade, vertically integrated manufacturers with captive R&D and retread infrastructure demonstrate superior margin durability versus commodity assemblers. Acquisition target archetypes include regional specialists with established mountain snowflake certification and proprietary soybean-oil tread formulations. The signal to watch is Transport Canada regulatory harmonization proposals that would elevate wet-traction testing costs for non-compliant imports.| Strategic Initiative | Industry Significance |
|---|---|
| Retread Infrastructure Expansion | Captive casing management programs lock in 30-50% per-mile cost advantages for fleet operators. |
| Bio-Sourced Compound Development | USDA BioPreferred qualification creates procurement preference among federal and municipal fleet buyers. |
| Direct-to-Consumer Platform Launch | AI fitment tools with mobile mounting bypass dealer overhead in California and Texas suburban markets. |
| Smart Tire Sensor Integration | Edge-computing pressure monitoring becomes specification requirement for autonomous vehicle fleet operators. |
| Cross-Border Certification Harmonization | Unified NHTSA-Transport Canada testing protocols reduce 8-12 week approval timelines for tire lines. |
Research Approach
A standing panel of fleet procurement directors, tire compound R&D leads, OEM platform engineers, and aftermarket distributor operations managers provided ongoing calibration across primary interview cycles. Secondary validation drew from NHTSA Uniform Tire Quality Grading submissions, Transport Canada winter certification databases, USDA BioPreferred procurement records, and vehicle production data from IHS Markit. Bottom-up segment sizing triangulated against top-down macroeconomic demand indicators to constrain forecast variance.
Scenario-bracketing around fleet electrification penetration rates, natural rubber price volatility bands, and retread program adoption curves bounded high-low trajectory envelopes across the analysis window. Segmentation dimensions modeled encompassed product type, application, technology generation, and distribution channel with regional production cluster overlays. CAGRs were derived from logistic diffusion curves fitted to historical replacement cycle data and projected vehicle miles traveled elasticity. Industry-specific inputs included rolling-resistance coefficient trajectories under EPA heavy-duty emission standards and casing utilization rates from commercial fleet telematics.
Stress conditions across Thai natural rubber supply disruptions, Ohio River Valley steel cord capacity constraints, and NHTSA wet-traction grading revisions were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding fleet electrification timelines and logistics network expansion. Quarterly review of Transport Canada regulatory harmonization proposals and EPA emission standard revision comment periods is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Tires and Wheels
Asia-Pacific Aircraft Tires Market
Tires and Wheels
Automotive Tire Analytics Market
Tires and Wheels
Global Commercial Vehicle Run Flat Tire Inserts Market
Tires and Wheels
Global Electric Vehicle Tire Market
Tires and Wheels
Run Flat Tire Inserts Market
Tires and Wheels
Tire Carousel Market
Tires and Wheels
Smart Tire Market
Tires and Wheels
Automotive Green Tires Market
Tires and Wheels
Europe Two-Wheeler Tire Market
Tires and Wheels
Tire Retreading Market
Tires and Wheels
Russia OTR Tire Market
Tires and Wheels
Kuwait Tyres Market
Tires and Wheels
Automotive Winter Tire Market
Tires and Wheels
GCC Tire Market
Tires and Wheels
Low Rolling Resistance Tire Market
Tires and Wheels
Elastic Polyurethane Wheels Market