
 Agricultural Tires Market | 2026-2036
Agricultural Tires Market Size, Share, and Industry Trends Forecast 2026-2036
Agricultural Tires Market Intelligence
Multi-source procurement for natural rubber and synthetic compounds is shifting toward vertically integrated supply chains among top manufacturers. Bridgestone Corporation leverages captive rubber plantations across Southeast Asia to buffer raw material volatility. Michelin Group anchors its competitive position through sustained R&D spending on airless tire architectures for heavy field equipment. Continental AG dominates the European replacement channel through direct distributor partnerships and digital fleet monitoring services.
Agricultural tires are engineered structures combining natural rubber, synthetic polymers, and steel cord reinforcement, manufactured through calendering, extrusion, and vulcanization processes to deliver load-bearing capacity, soil compaction control, and traction across uneven terrain. Radial tires command the premium tier due to superior fuel efficiency and longer field life, while bias tires retain cost-sensitive share in emerging markets with shorter replacement cycles. Tractor applications generate the largest volume pool, though harvester configurations carry higher per-unit margins due to specialized lug tread patterns and reinforced sidewall specifications.
The EPA governs volatile organic compound emissions from tire curing operations in the United States, while REACH restricts specific chemical additives in European-manufactured compounds, and India's BIS mandates minimum load-rating certifications for imported agricultural tires. These frameworks elevate compliance costs for cross-border suppliers while creating preferential access for domestic producers meeting localized testing protocols. Stakeholders must weigh regional certification requirements against centralized manufacturing scale when configuring regional distribution footprints.
Market Dynamics
Farm mechanization in Brazil and the Midwestern United States is compressing replacement cycles for radial tires, while Europe's F-Gas Regulation forces curing-process retooling across manufacturing footprints.
Growth Catalysts
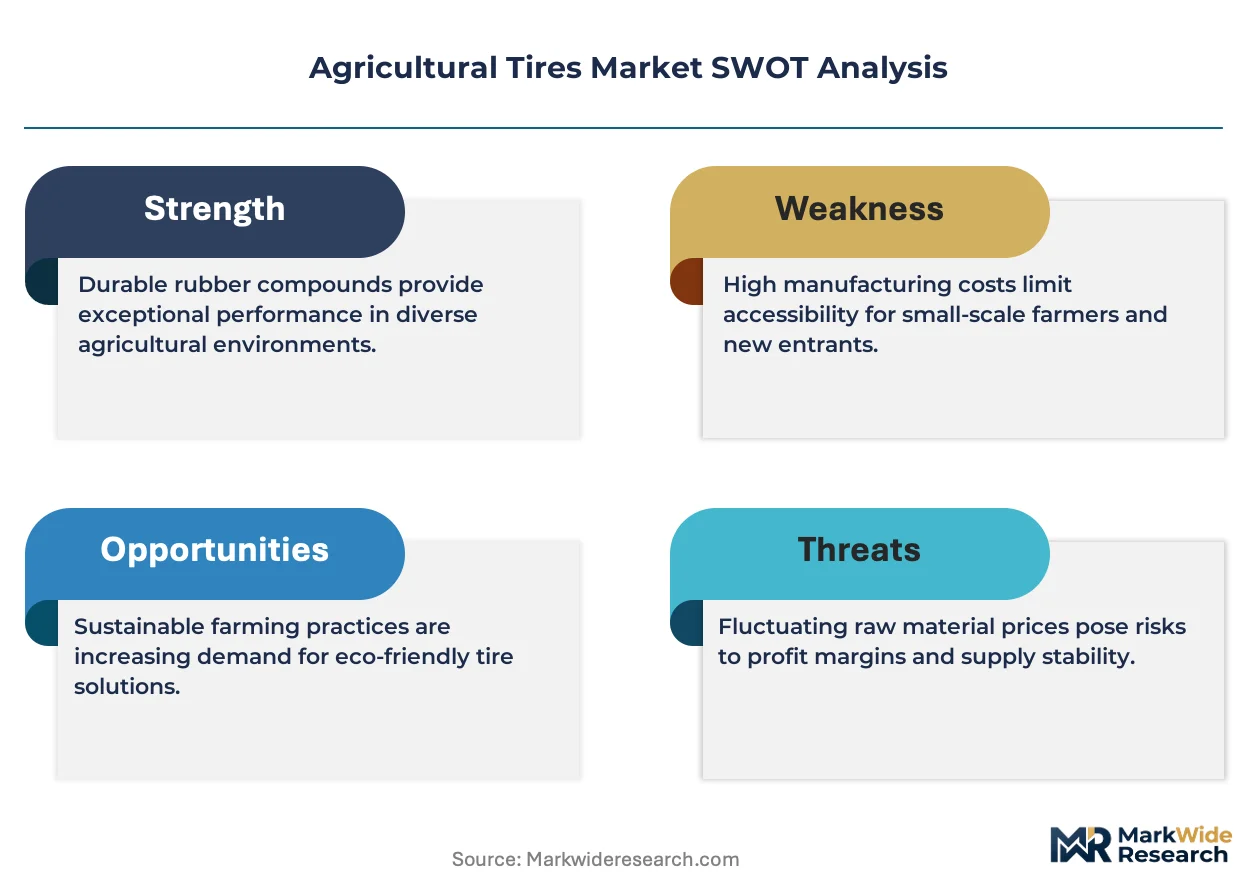
- REACH chemical restrictions:European compound reformulation is accelerating low-emission curing adoption, opening premium positioning for compliant manufacturers.
- Row-crop farming concentration:Midwestern United States producers sustain heavy radial consumption through extended field hours and larger equipment fleets.
- Steel cord reinforcement:Advanced metallurgy in radial architectures extends field life and reduces soil compaction penalties for large-scale operators.
Market Restraints
- Natural rubber price volatility:Southeast Asian supply disruptions transmit directly to compound costs, squeezing margin predictability for non-integrated producers.
- BIS load-rating mandates:India's certification requirements create procedural friction for cross-border suppliers without localized testing infrastructure.
- Bias tire substitution:Cost-sensitive emerging markets retain shorter-cycle bias configurations, limiting radial penetration in price-driven segments.
Strategic Opportunities
- Brazilian farm expansion:Large-scale agricultural producers in Mato Grosso and Goiás are extending mechanization depth, creating replacement demand for high-load radial configurations.
- Digital fleet monitoring:Sensor-enabled tire performance tracking opens subscription revenue streams alongside hardware sales.
- Airless tire architectures:R&D convergence of polymer science and structural engineering promises elimination of pressure-maintenance downtime for harvester applications.
Industry Challenges
- Vulcanization technician scarcity:Specialized curing-process expertise is concentrating among legacy manufacturing workforces, constraining capacity expansion timelines.
- EPA compliance capex:Volatile organic compound abatement systems require substantial facility investment for US-based production.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Agricultural Tires Market |
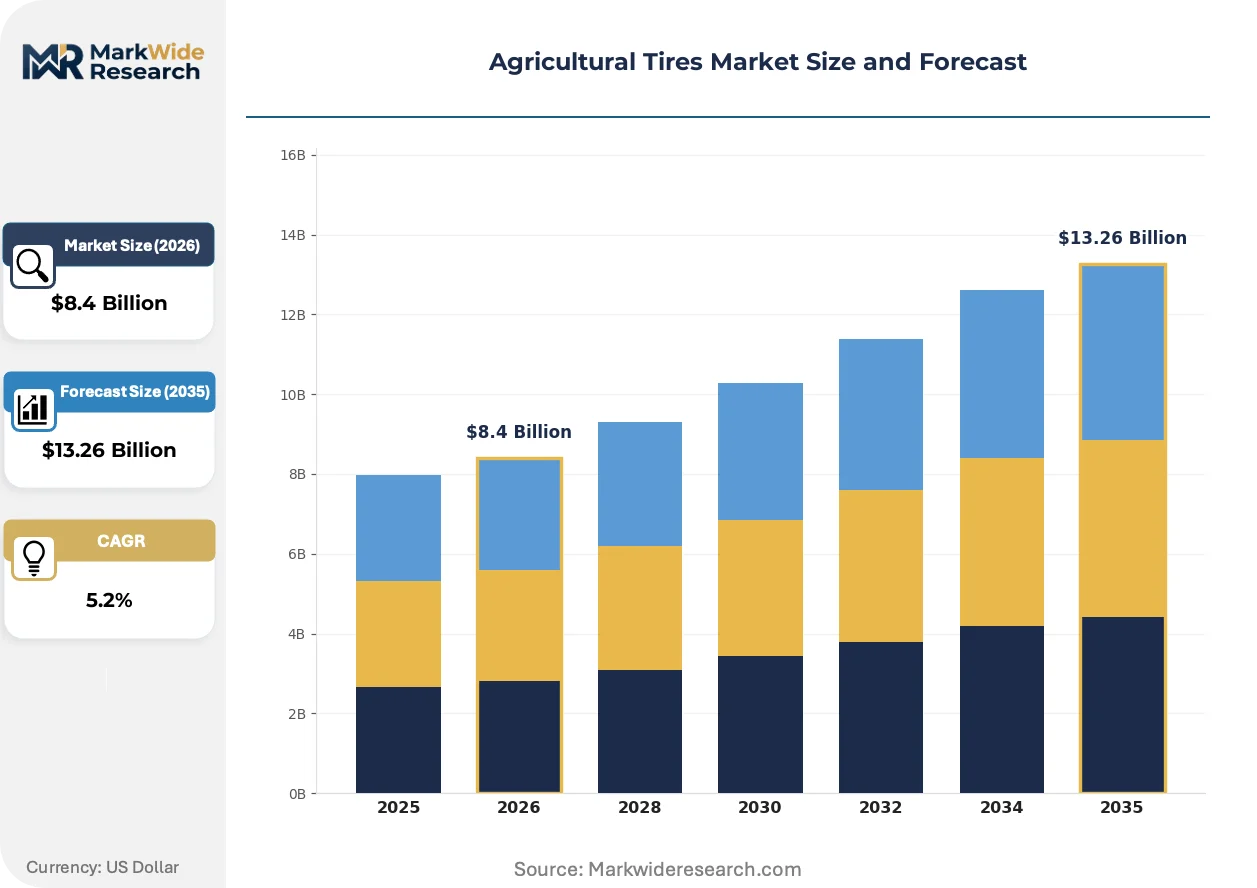
| Market Size in 2026 | $8.4 Billion |
| Market Size in 2035 | $13.26 Billion |
| CAGR (2026 – 2036) | 5.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Radial Tires, Bias Tires, Implement Tires, Multi-Purpose Tires Application: Tractors, Harvesters, Sprayers, Soil Preparation Tread Pattern: Rib, Lug, Bar, Chevron End User: Agricultural Producers, Contractors, Equipment Rental Companies, Dealers |
| Companies Covered | Bridgestone Corporation, Michelin Group, Continental AG, Titan International, Trelleborg AB, Balkrishna Industries Limited (BKT), Apollo Tyres Ltd, Hankook Tire & Technology, Alliance Tire Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Agricultural Tires Market Strategic Shifts & Innovations
Material science breakthroughs and regulatory chemistry mandates are restructuring how agricultural tires are formulated, cured, and sold across divergent regional compliance regimes.
Airless tire architectures are rewriting performance expectations for heavy field equipment. Polymer-composite lattice structures replace pressurized air chambers, eliminating puncture risk and pressure monitoring overhead. Large-scale grain operations in North America are piloting these configurations for harvester fleets, compressing total cost-of-ownership calculations for seasonal peak-demand equipment.
Europe's F-Gas Regulation is forcing wholesale reformulation of tire curing chemistry. Hydrofluorocarbon-based processes face phase-down timelines, compelling manufacturers to deploy alternative blowing agents and heating systems. Premium radial production lines in Germany and France are absorbing the steepest retooling costs, creating temporary capacity constraints that favor compliant early movers.
Service bundling is displacing transactional tire sales in concentrated agricultural regions. Fleet operators in Iowa and Illinois are negotiating performance-based contracts that wrap replacement, monitoring, and field-service response into per-acre pricing. This procurement evolution favors suppliers with distributed service infrastructure and real-time logistics capabilities over pure manufacturing scale.
Agricultural Tires Market Segmentation
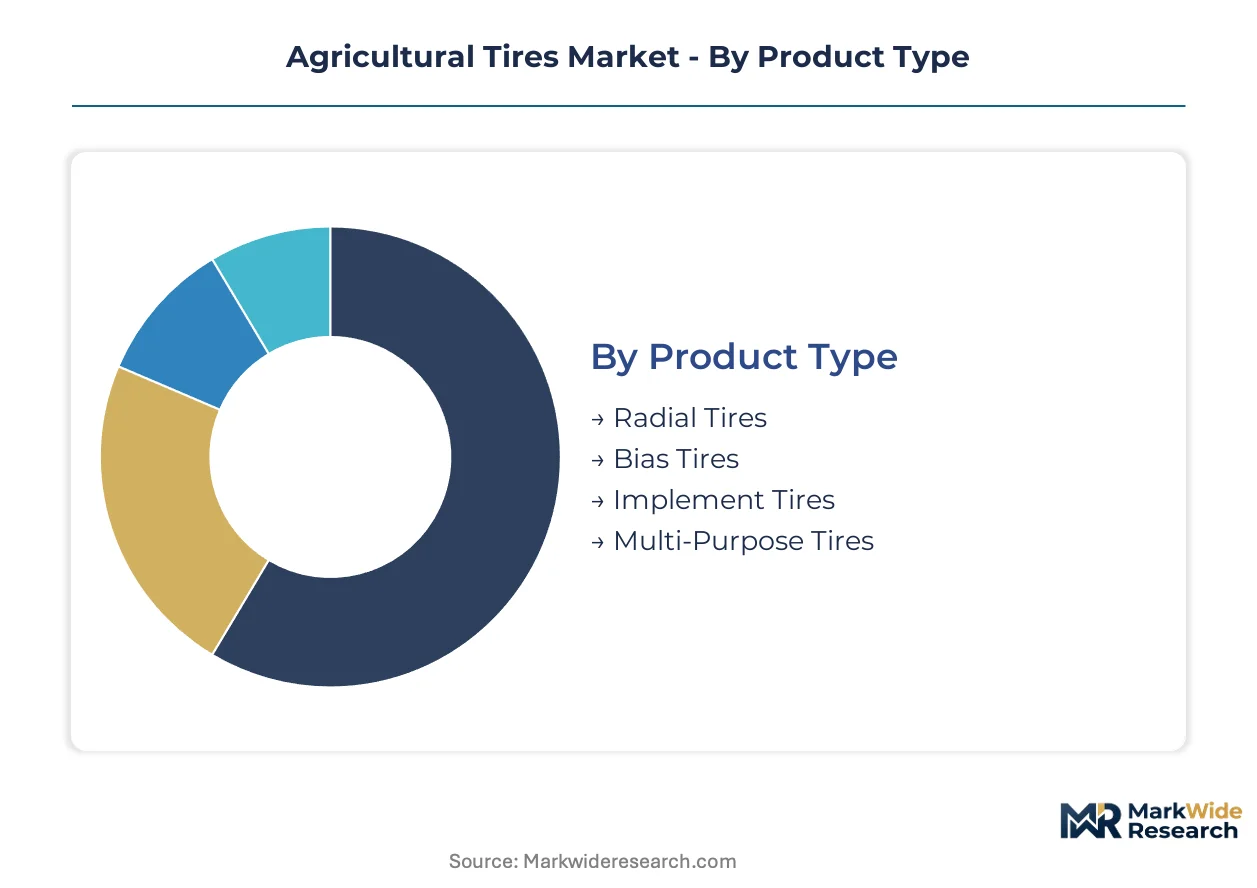
Agricultural tire procurement splits sharply across equipment duty cycles, soil conditions, and ownership models. Understanding these fault lines exposes where margin pools concentrate and which technical specifications command pricing power.
Product Type:
Cost tier separates buyers seeking field longevity from those prioritizing upfront capital preservation.
- Radial Tires:Steel-belted construction with flexible sidewalls reduces soil compaction and improves fuel efficiency across extended field hours. Demand concentrates in the Midwestern United States, where large-scale corn and soybean operations run equipment 14-16 hours daily during planting and harvest windows.
- Bias Tires:Cross-ply nylon or polyester cord construction delivers lower unit costs but shorter service intervals and higher per-hour operating expenses. Brazilian Mato Grosso cotton producers and Southeast Asian rice cooperatives favor these configurations where replacement infrastructure remains sparse and capital constraints dominate procurement decisions.
- Implement Tires:Non-powered axle designs for tillage and seeding equipment prioritize flotation over traction.
- Multi-Purpose Tires:Hybrid tread geometries serve mixed-use tractors shifting between fieldwork and transport duties.
Volume sits with Bias Tires; growth tilts toward Radial Tires.
Application:
Equipment duty intensity and seasonal utilization rates determine replacement frequency and specification grade.
- Tractors:Primary power units across all farm scales generate the largest absolute tire volume, with front axle sizes typically 30-40% smaller than drive axle configurations. Row-crop operations in Iowa and Illinois sustain heavy radial consumption through 8,000-12,000 annual engine hours.
- Harvesters:Combine and forage harvester tires carry the highest per-unit margins due to massive load ratings, specialized lug patterns for grain cart traction, and reinforced sidewalls resisting stubble puncture. North American grain cooperatives are piloting airless architectures for these seasonal peak-demand assets.
- Sprayers:High-clearance designs with narrow profiles minimize crop damage during mid-season chemical application.
- Soil Preparation:Tillage and seeding implements use flotation tires to distribute weight across seedbeds.
Tractors dominate unit shipments; harvesters capture the steepest expansion trajectory in value terms.
Tread Pattern:
Surface contact geometry directly links to traction requirements across soil moisture conditions and operational speeds.
- Rib:Continuous circumferential grooves deliver low rolling resistance and minimal soil disturbance for transport and front-axle steering applications. European arable farming regions favor these patterns for roading efficiency between dispersed land parcels.
- Lug:Aggressive angled blocks penetrate loose and wet soils for maximum drive axle traction during primary tillage and harvest operations. Brazilian soybean producers in Goiás specify deep-lug radials for clay-heavy cerrado soils.
- Bar:Transverse parallel ribs suit slow-speed implement flotation.
- Chevron:V-shaped patterns balance self-cleaning with directional stability on slopes.
Lug patterns command the premium tier; rib configurations scale most efficiently in manufacturing.
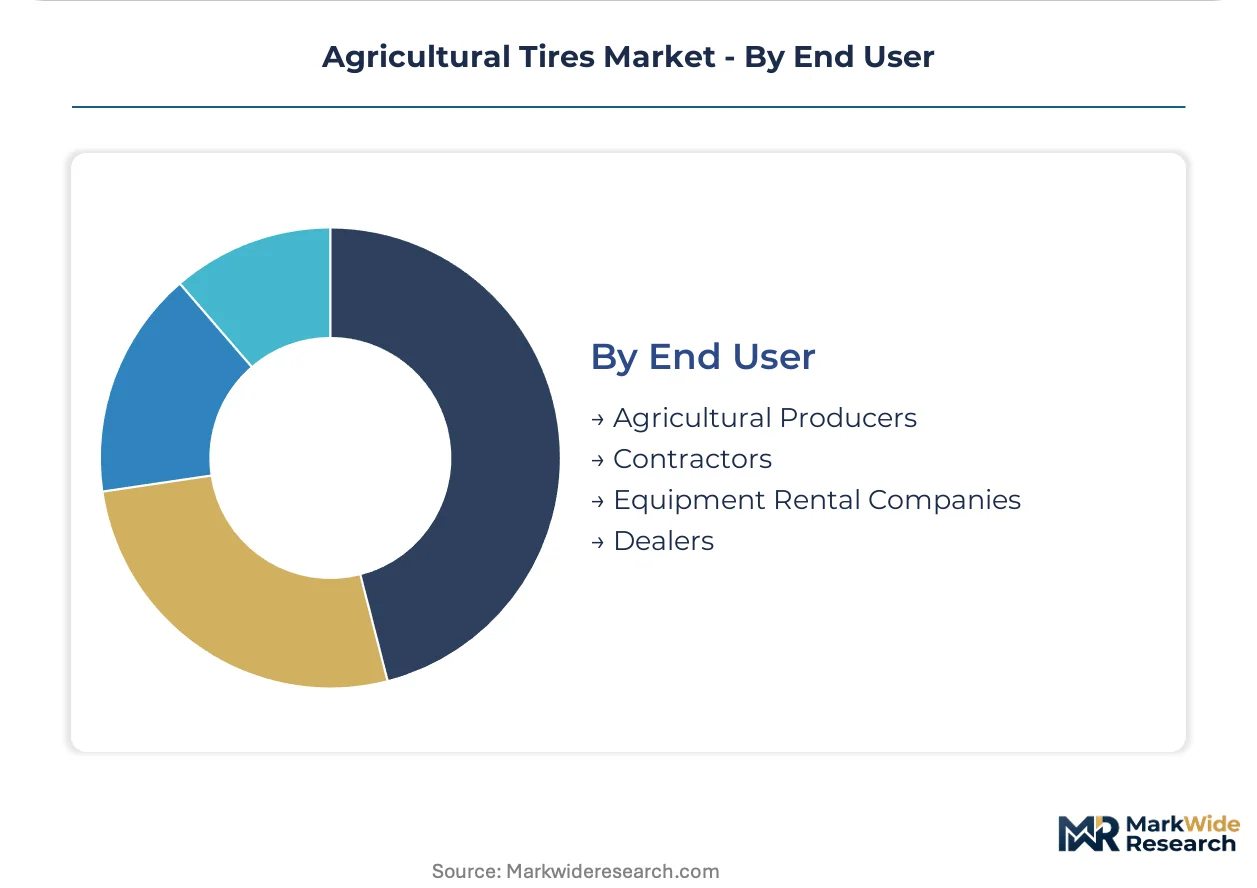
End User:
Ownership duration and fleet sophistication shape procurement sophistication and service bundling appetite.
- Agricultural Producers:Owner-operators with 500-5,000 acre holdings make replacement decisions based on tread wear indicators and seasonal timing, with larger operations adopting digital fleet monitoring for predictive replacement scheduling.
- Contractors:Custom harvesters and tillage service providers prioritize rapid turnaround and 24-hour field service response over unit price, creating demand for supplier networks with distributed logistics infrastructure.
- Equipment Rental Companies:Fleet turnover cycles favor bias tires for acquisition cost control.
- Dealers:OEM-affiliated distribution channels bundle tires with new equipment sales and warranty packages.
Agricultural Producers anchor volume; Contractors are expanding most quickly in service-contract value.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Natural rubber plantations across Southeast Asia supply the feedstock that anchors agricultural tire manufacturing networks in Thailand, Indonesia, and Malaysia, with finished goods flowing toward mechanized farming regions in Brazil, the United States, and Germany.
United States
Row-crop farming across Iowa and Illinois sustains heavy radial consumption through 14-16 hour daily equipment runs during planting and harvest windows. EPA volatile organic compound regulations govern curing emissions from domestic production facilities. The Midwestern Corn Belt concentrates replacement demand, where digital fleet monitoring is compressing procurement cycles for large-scale operators.
Brazil
Soybean and cotton expansion in Mato Grosso and Goiás is extending mechanization depth among large-scale agricultural producers. ANVISA oversees chemical additive standards in imported tire compounds. São Paulo state hosts distribution infrastructure serving the cerrado farming frontier, where clay-heavy soils specify deep-lug radial configurations.
Germany
Premium radial production lines absorb steep retooling costs from Europe's F-Gas Regulation phase-down of hydrofluorocarbon curing processes. REACH chemical restrictions accelerate low-emission compound reformulation. The Baden-Württemberg industrial corridor concentrates manufacturing capacity, where compliant early movers capture temporary supply constraints.
India
BIS load-rating mandates create procedural friction for cross-border suppliers without localized testing infrastructure. Bias tires retain cost-sensitive share among rice cooperatives and cotton producers with shorter replacement cycles. Gujarat and Maharashtra host domestic manufacturing clusters serving both internal demand and export markets across South Asia.
China
Domestic farm mechanization programs expand tractor fleet penetration in the Northeast grain belt and North China Plain. GB standards and MIIT regulations govern tire safety certifications and manufacturing emissions. Shandong Province anchors production capacity, with Qingdao-based facilities supplying both domestic replacement channels and export markets.
Agricultural Tires Market Key Industry Players
Backward integration into captive rubber supply dominates the current landscape among top-tier manufacturers seeking margin protection against Southeast Asian feedstock volatility. The vendor base organizes around three strategic archetypes: vertically integrated plantation owners, R&D-intensive architecture specialists, and distributor-network operators. M&A activity and capacity expansion in low-emission curing infrastructure represent the dominant competitive moves as regulatory deadlines approach.
Within the integrated supply tier, Bridgestone Corporation exemplifies plantation-backed feedstock security, while Michelin Group occupies a position as an R&D anchor for airless tire architectures. Continental AG represents the distributor-network archetype through European replacement channel dominance. These three entities illustrate how geographic origin and structural positioning map to divergent strategic vectors in a market splitting between premium radial expansion and cost-sensitive bias retention.
| Leading Market Players |
|---|
| Bridgestone Corporation |
| Michelin Group |
| Continental AG |
| Titan International |
| Trelleborg AB |
| Balkrishna Industries Limited (BKT) |
| Apollo Tyres Ltd |
| Hankook Tire & Technology |
| Alliance Tire Group |
| Others |
Cost & Logistics Intelligence
Natural rubber feedstock from Southeast Asian plantations flows through compound blending facilities before tiering into radial premium configurations and bias economy alternatives downstream. This input cost pathway concentrates pricing power among manufacturers with captive plantation supply, while spot-market buyers absorb volatility at the compound stage.
Pricing Analysis
Warranty and field-service bundling separates premium radial suppliers from unbundled transactional sellers in concentrated agricultural regions. Three-tier pricing structure across premium, standard, and economy levels tracks certification grade and steel-cord metallurgy quality. Cost compression in the bias tier is intensifying because Brazilian cotton producers prioritize acquisition economy over field longevity. Contractors and rental fleets exhibit the sharpest price sensitivity; large-scale Midwestern row-crop operators show the least.
Supply Chain Analysis
Single-source vulnerability sits with Southeast Asian natural rubber plantations concentrated in Thailand, Indonesia, and Malaysia. Compound manufacturing draws from synthetic polymer feedstocks and steel cord reinforcement anchored in Chinese and Indian metallurgy facilities. Tariff exposure on cross-border finished goods creates procedural friction for non-compliant suppliers. Distribution runs through OEM-affiliated dealer networks and independent replacement channels serving concentrated farming regions.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Backward integration into captive rubber supply and downstream service infrastructure has become the defining competitive race, with plantation ownership and digital fleet monitoring representing the critical levers separating margin-protected leaders from spot-market exposed followers.
For Market Incumbents: To counter feedstock volatility from Southeast Asian supply disruptions, accelerate captive plantation expansion across Indonesia and Malaysia while embedding sensor-enabled tire performance tracking into subscription service contracts. Prioritize low-emission curing certification investments to capture temporary capacity constraints from European F-Gas Regulation compliance deadlines. For New Entrants and Emerging Players: The price-point gap between premium radial and economy bias configurations in India's rice cooperatives and Southeast Asian smallholder markets offers the most penetrable entry trajectory. Target BIS-certified bias tire production for South Asian replacement channels, leveraging localized testing infrastructure partnerships to bypass procedural friction for cross-border suppliers. For Investors and Strategic Acquirers: Distressed-cycle entries favor mid-tier manufacturers with established distributor relationships in Brazil's Mato Grosso and Goiás farming frontiers. Long-term viability hinges on airless tire architecture R&D convergence and low-emission curing capacity buildout. Watch for European F-Gas Regulation compliance deadline acceleration as the primary inflection signal for consolidation timing.| Strategic Initiative | Industry Significance |
|---|---|
| Captive Rubber Plantation Acquisition | Buffers compound cost volatility from Southeast Asian supply disruptions for integrated manufacturers. |
| Low-Emission Curing Capacity Expansion | Captures temporary supply constraints from European F-Gas Regulation phase-down timelines. |
| Digital Fleet Monitoring Platform Launch | Opens subscription revenue streams alongside hardware sales for Iowa and Illinois operators. |
| Airless Tire Architecture R&D Investment | Eliminates pressure-maintenance downtime for North American grain harvester fleets. |
| BIS Certification Infrastructure Partnership | Reduces procedural friction for cross-border suppliers targeting Indian replacement channels. |
Research Approach
Trade databases, customs filings, and tire manufacturer SEC disclosures formed the secondary backbone, cross-referenced with primary interviews involving procurement directors at Midwestern grain cooperatives, Brazilian cotton plantation managers, European tire plant engineers, and Southeast Asian rubber plantation operators. Bottom-up volume modeling across equipment type, tire construction, and regional farming intensity combined with top-down macroeconomic validation to establish market sizing.
Bottom-up segment modeling tracked radial versus bias penetration rates, harvester versus tractor replacement cycles, and lug versus rib pattern adoption across soil condition clusters. CAGRs were derived from equipment fleet expansion trajectories and mechanization depth indicators throughout the forecast period. Industry-specific inputs included EPA emission compliance cost curves, REACH chemical restriction timelines, and ANVISA additive standard evolution.
Underlying measurement precision varies by segment; radial tire value pools carry tighter precision than bias tire volume estimates due to concentrated OEM channel transparency. Forecasts reflect assumptions on farm mechanization cadence, regulatory deadline adherence, and natural rubber price band stability. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Tires and Wheels
Construction Machinery Tires Market
Tires and Wheels
Tire & Wheel Cleaners Market
Tires and Wheels
Automotive Wheel Rims Market
Tires and Wheels
Steel Tire Cord Market
Tires and Wheels
Civil Aircraft Tire Market
Tires and Wheels
Bias Tire Market
Tires and Wheels
North America 2-Wheeler Tire Market
Tires and Wheels
Global Tire Curing Press Market
Tires and Wheels
Global Electric Vehicle Tire Market
Tires and Wheels
Asia Pacific Two Wheeler Tire Market
Tires and Wheels
Automotive Retread Tires Market
Tires and Wheels
Truck and Bus Radial (TBR) Tire Market
Tires and Wheels
Automotive Automatic Tire Inflation System (ATIS) Market
Tires and Wheels
Global Advanced Tires Market
Tires and Wheels
Tire Repair Patch Market
Tires and Wheels
Ground Support Equipment Tires Market