
 Re-Tread Tires Market | 2026-2036
Re-Tread Tires Market Size, Share, and Industry Trends Forecast 2026-2036
Re-Tread Tires Market Analysis
Fleet operators are reorganizing procurement priorities around total cost of ownership, shifting volume away from price-sensitive independent owner-operators toward large logistics providers with structured retread programs. Bridgestone Corporation leverages its Bandag franchise network to control service touchpoints across North American trucking corridors. Michelin sustains technology leadership through its Remix process, which competes on casing durability thresholds that extend second-life mileage. Continental AG anchors European fleet supply through integrated tire management contracts that bundle new tire sales with captive retread services.
Re-tread tires are remanufactured products created by bonding new tread rubber to inspected tire casings, typically requiring casing integrity verification through shearography or holographic inspection to ensure structural soundness before renewal. The primary commercial purpose is to deliver 30-50% cost savings versus new tires while preserving approximately 70% of the original casing material value. Commercial vehicles dominate application demand due to predictable highway duty cycles that preserve casing quality for multiple retread lives, while hot process retreading leads volume in heavy-duty segments where adhesion strength requirements are most demanding. Cold process and pre-cured methods are gaining share in regional fleet operations where faster turnaround times and lower energy inputs align with sustainability targets.
EPA emission regulations and NHTSA fuel economy standards shape United States demand by incentivizing tire lifecycle extension as a component of fleet decarbonization strategies, while REACH and EU Green Deal frameworks in Europe impose material traceability requirements on retread compound formulations. The EU F-Gas Regulation indirectly influences retread competitiveness by raising new tire production energy costs relative to remanufacturing. Stakeholders must monitor evolving Extended Producer Responsibility proposals across multiple jurisdictions that could reallocate end-of-life tire costs between original manufacturers and retread service providers.
Market Dynamics
Fleet procurement centralization around total cost of ownership metrics is compressing margins for independent retreaders while rewarding integrated tire management providers with multi-year service contracts.
Growth Catalysts
- EPA emission standards:Lifecycle cost requirements for commercial vehicle tires in the United States incentivize casing reuse over new tire procurement.
- Shearography inspection:Non-destructive testing protocols reduce casing rejection rates and extend retreadable inventory for heavy-duty fleet operators.
- Hot process retreading:Superior adhesion strength in high-load applications sustains demand across North American long-haul corridors.
Market Restraints
- Natural rubber price volatility:Input cost swings compress retread margin buffers against fixed-price fleet contracts.
- Casing supply concentration:Premium tire manufacturers control high-quality casing flows through captive collection networks.
- Speed rating limitations:Retread products face technical caps that exclude high-performance passenger vehicle segments.
Strategic Opportunities
- Regional fleet operations:Cold process and pre-cured methods penetrate municipal and short-haul segments where turnaround speed outweighs adhesion demands.
- EU Green Deal frameworks:Material traceability mandates favor retread compound formulations with documented recycled content.
- Tire-as-a-service models:Per-mile pricing contracts bundle retread services with predictive casing management.
Industry Challenges
- Shearography technician certification:Qualified casing inspection specialists remain scarce relative to fleet operator quality requirements.
- Extended Producer Responsibility proposals:Evolving end-of-life tire cost allocation rules create compliance uncertainty across multiple jurisdictions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Re-Tread Tires Market |
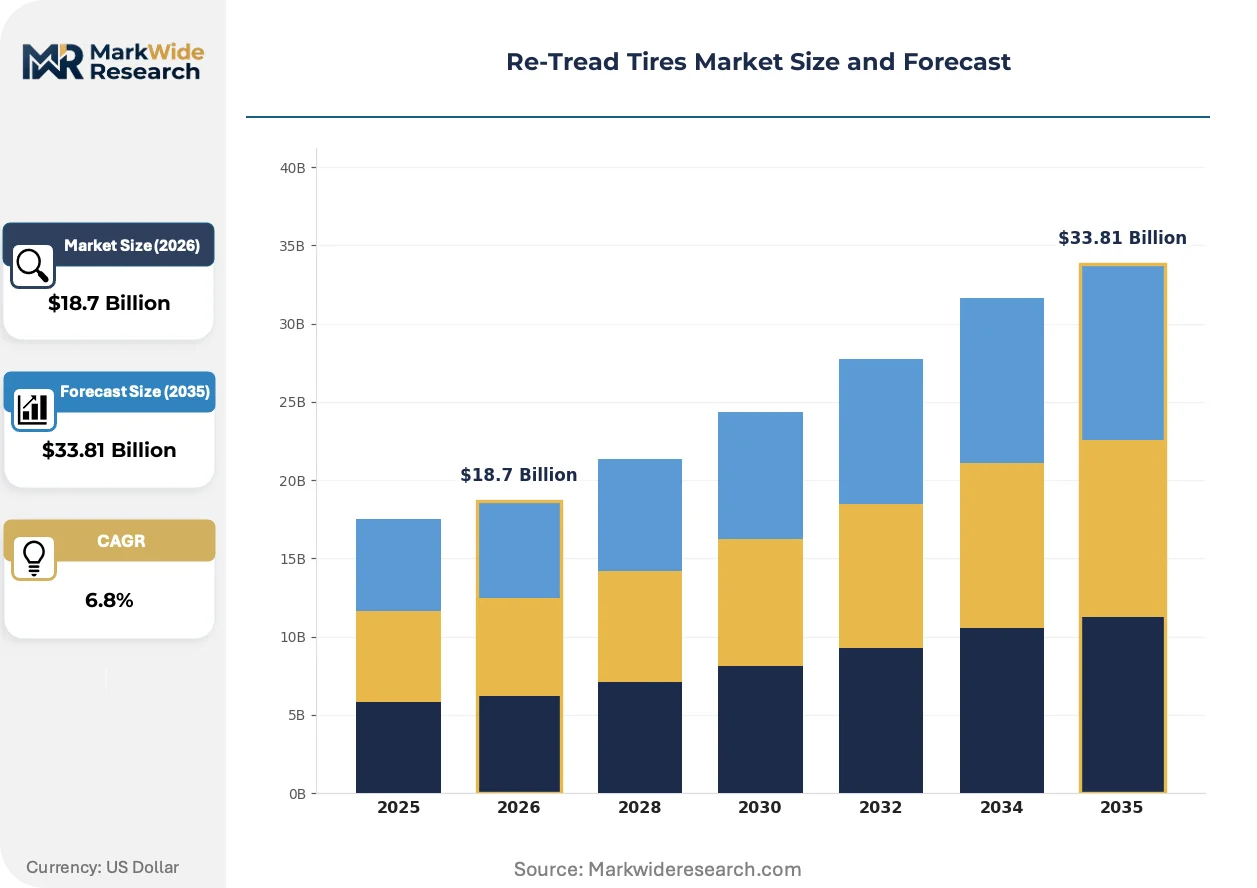
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $33.81 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Application: Commercial Vehicles, Passenger Vehicles, Aviation, Off-Road Material: Natural Rubber, Synthetic Rubber, Steel, Polyester End User: Fleet Operators, Transportation Companies, Logistics Providers, Municipalities Process Type: Hot Process, Cold Process, Pre-Cured, Mold Cure |
| Companies Covered | Bridgestone Corporation, Michelin, Goodyear Tire & Rubber Company, Continental AG, Marangoni S.p.A., Yokohama Rubber Company, Hankook Tire, Vipal Rubber, Pirelli, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Re-Tread Tires Market Emerging Trajectories
Digital casing tracking and automated inspection systems are compressing quality variance between retread tiers while enabling predictive lifecycle management.
Shearography-based holographic inspection is supplanting manual visual casing assessment in premium fleet programs. Large logistics providers with structured retread mandates are adopting automated defect detection at 3-4x manual throughput rates. This technology is supplanting subjective grading standards that previously allowed marginal casings into second-life production.
REACH material traceability requirements in Europe mandate documented origin data for retread compound formulations. Compound suppliers must certify recycled content percentages and chemical substance registrations. Heavy-duty fleet contracts in Germany and France now specify REACH-compliant retread sourcing as a procurement gate.
Buyer consolidation among logistics providers is fragmenting the independent owner-operator channel that historically drove spot-market retread volume. Structured multi-year tire management agreements with integrated service networks are capturing procurement authority previously held by small fleet managers. This concentration is most visible across United States interstate corridors where top-50 logistics providers control an expanding share of heavy-duty tire placements.
Re-Tread Tires Market Segmentation
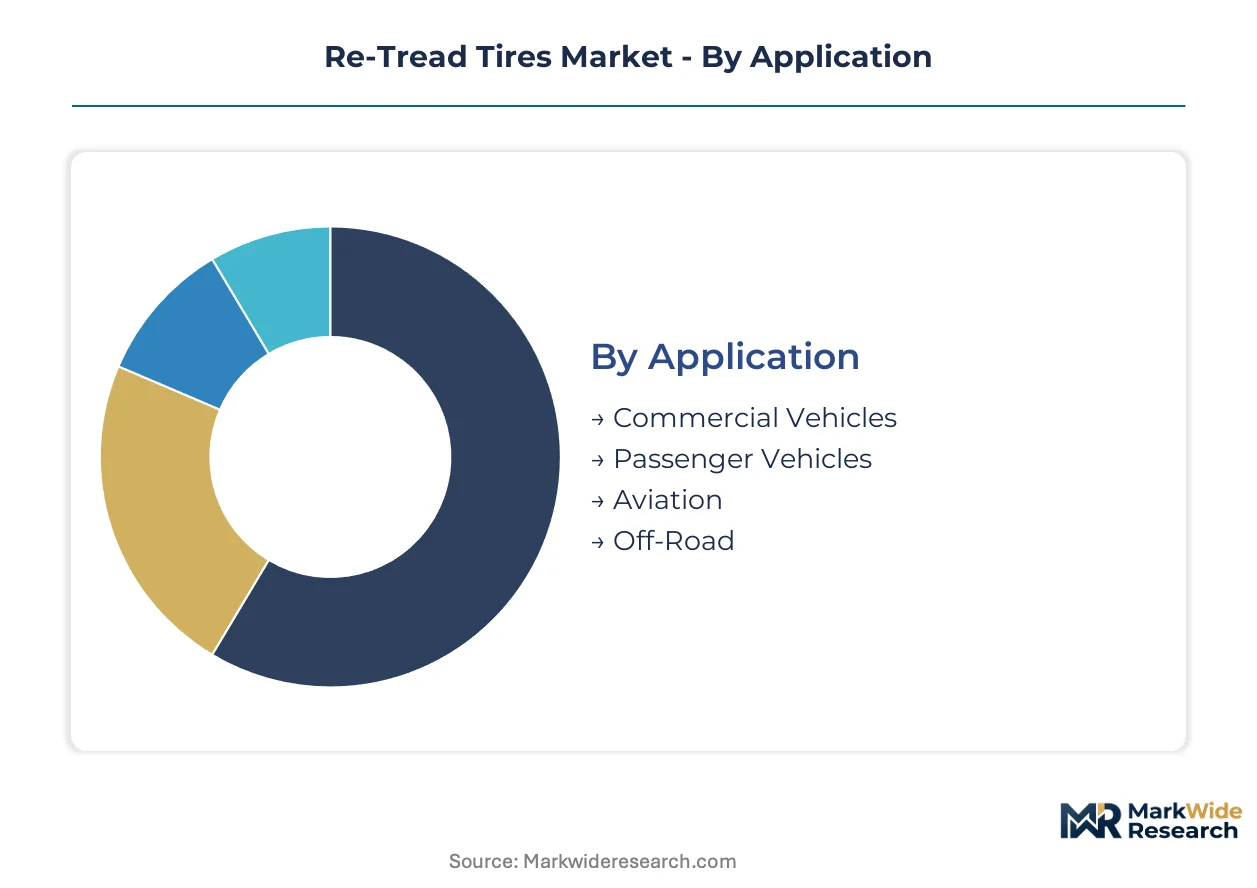
Segmentation in re-tread tires reflects divergent regulatory pressures across vehicle classes and end-use profiles. EPA emission standards and EU Green Deal frameworks create tiered compliance burdens that reshape material selection and process adoption by application.
Application:
EPA emission standards and EU Green Deal frameworks impose distinct lifecycle cost requirements across vehicle categories, reshaping retread penetration rates.
- Commercial Vehicles:Heavy-duty trucks and buses dominate retread consumption due to predictable highway duty cycles that preserve casing integrity for multiple renewal cycles. Fleet operators across United States interstate corridors structure procurement around total cost of ownership metrics that favor casing reuse over new tire procurement.
- Passenger Vehicles:Speed rating limitations and consumer perception barriers restrict retread adoption in light-duty applications. Technical caps exclude high-performance segments where new tire safety certifications dominate purchasing decisions.
- Aviation:FAA certification requirements mandate specialized inspection protocols for aircraft tire retreading. Narrow casing supply and stringent quality thresholds limit this segment to a handful of approved service providers.
- Off-Road:Mining and construction equipment generate demand for extra-durable tread compounds. Severe duty cycles reduce casing reusability compared to highway applications.
Established volume favors Commercial Vehicles; emerging adoption favors Off-Road where durability specifications are tightening.
Material:
Cost tier differentiation separates premium compound formulations from commodity-grade alternatives, with REACH traceability mandates reshaping supplier qualification.
- Natural Rubber:Price volatility compresses margin buffers for retreaders locked into fixed-price fleet contracts. Brazilian and Southeast Asian supply fluctuations directly impact compound cost structures.
- Synthetic Rubber:Styrene-butadiene and polybutadiene variants deliver consistent performance in high-load applications. REACH documentation requirements favor suppliers with certified petrochemical feedstock chains.
- Steel:Bead wire and belt plies provide structural reinforcement for heavy-duty retreads. Scrap steel recovery rates influence end-of-life tire economics.
- Polyester:Body ply materials reduce weight in regional fleet applications. Lower heat resistance limits use in sustained high-speed operation.
Procurement gravity centers on Natural Rubber for cost-sensitive contracts; specification-grade demand migrates toward Synthetic Rubber for traceability compliance.
End User:
Customer type concentration determines service model economics, with integrated tire management providers capturing procurement authority from fragmented independent operators.
- Fleet Operators:Structured retread programs with multi-year service contracts dominate heavy-duty volume. Shearography inspection mandates and predictive casing management differentiate premium procurement tiers.
- Transportation Companies:Municipal bus and coach operators balance turnaround speed against adhesion performance. Cold process methods gain share where depot-based maintenance limits hot cure equipment investment.
- Logistics Providers:Top-50 United States logistics providers control expanding shares of interstate tire placements. Centralized procurement compresses spot-market volume historically served by independent retreaders.
- Municipalities:Waste collection and public works vehicles generate steady regional demand. Sustainability targets accelerate pre-cured method adoption for lower energy inputs.
Contract value concentrates with Logistics Providers; service expansion opportunities favor Municipalities with tightening carbon reduction mandates.
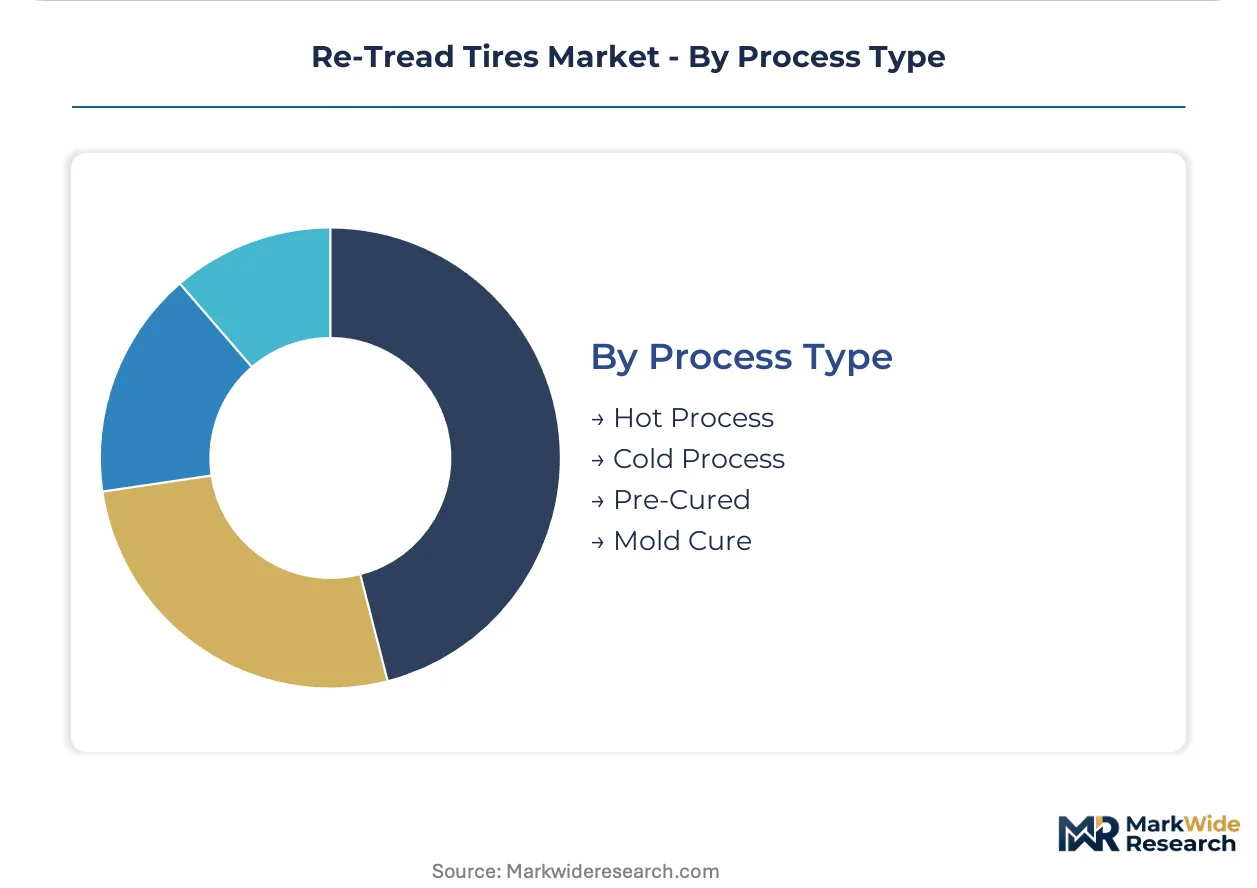
Process Type:
Technology maturity curves separate established hot cure dominance from emerging cold process and pre-cured penetration in niche segments.
- Hot Process:Direct extrusion and vulcanization deliver superior adhesion strength for high-load highway applications. Bandag franchise networks and integrated manufacturer service chains control equipment deployment across North American trucking corridors.
- Cold Process:Buffed casings receive pre-cured tread strips without full mold cure, reducing energy inputs and turnaround times. Regional fleet operators in Germany and France specify cold process for municipal and short-haul duty cycles.
- Pre-Cured:Factory-vulcanized tread rings bond to prepared casings under pressure. EU Green Deal energy cost frameworks improve competitiveness against hot cure in carbon-accounted procurement.
- Mold Cure:Custom tread designs vulcanized in segment molds serve specialized off-road and aviation requirements. Low volume and high tooling costs limit adoption outside premium niches.
Technology leadership resides with Hot Process; steepest expansion trajectory belongs to Pre-Cured methods under tightening energy efficiency regulations.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Mexican retreaders supply casing processing services to United States fleet operators along cross-border trucking corridors, with Nuevo León facilities handling volume from Texas-based logistics providers.
United States
EPA emission standards and NHTSA fuel economy mandates drive fleet procurement toward casing reuse programs. The IRA's commercial vehicle decarbonization incentives indirectly support retread lifecycle extension. Interstate trucking corridors through Illinois, Ohio, and Pennsylvania concentrate Bandag franchise operations serving long-haul logistics providers.
Germany
KBA vehicle inspection protocols and EU Green Deal carbon accounting favor cold process retreading in municipal bus fleets. REACH material traceability requirements reshape compound supplier qualification. Industrial retread capacity clusters in North Rhine-Westphalia serve Rhine-Ruhr logistics networks.
China
MIIT tire remanufacturing standards and dual carbon goals accelerate domestic retread adoption in commercial vehicle fleets. SAMR quality certification requirements differentiate premium service tiers. Shandong Province tire manufacturing bases extend into captive retread operations for export casing supply.
Brazil
ANVISA industrial safety frameworks and national biofuel blending mandates shape heavy-duty fleet tire economics. BIS-equivalent tire quality standards govern commercial vehicle retread eligibility. São Paulo state agricultural and mining equipment operators generate off-road retread demand.
India
BIS tire remanufacturing standards and PLI scheme automotive incentives indirectly support commercial vehicle retread penetration. State transport corporation procurement rules specify casing quality thresholds. Gujarat industrial corridors host retread service networks supplying Mumbai-Nashik logistics lanes.
Re-Tread Tires Market Vendor Landscape
Player mix skews toward integrated tire manufacturers with captive retread networks. Consolidation pressure concentrates procurement authority among large logistics providers with multi-year service contracts. Three archetypes dominate: manufacturer-integrated service chains, independent regional processors, and tire-as-a-service platform operators. M&A activity targets regional retreaders for network density, while technology licensing agreements spread automated inspection systems.
Within the manufacturer-integrated tier, Bridgestone Corporation and Michelin exemplify archetypes leveraging franchise networks and proprietary processes respectively. Continental AG occupies a position anchoring European fleet supply through bundled tire management contracts. These three represent the dominant competitive positioning vectors: network control, technology differentiation, and service integration.
| Leading Market Players |
|---|
| Bridgestone Corporation |
| Michelin |
| Goodyear Tire & Rubber Company |
| Continental AG |
| Marangoni S.p.A. |
| Yokohama Rubber Company |
| Hankook Tire |
| Vipal Rubber |
| Pirelli |
| Others |
Supply Flow & Price Mechanics
REACH material traceability mandates in Europe simultaneously gate supplier qualification and stratify price tiers by documented recycled content percentages, forcing compound vendors to absorb certification costs or cede share to integrated manufacturers with captive documentation systems. Fleet procurement centralization amplifies this bifurcation as large logistics providers demand REACH-compliant sourcing while independent operators trade down to undocumented alternatives.
Pricing Analysis
Hot process versus cold process versus pre-cured method pricing gaps reflect adhesion performance thresholds and energy input differentials that separate highway fleet contracts from municipal procurement tiers. Three-tier pricing structure across premium shearography-certified, standard visual-inspection, and economy non-fleet retreads captures quality-grade differentiation, with EPA emission compliance costs compressing margins in the standard tier. Pricing pressure stems from natural rubber volatility and fixed-price multi-year contracts locking retreaders below replacement cost during supply shocks. Independent owner-operators exhibit highest price sensitivity; top-50 logistics providers with total-cost-of-ownership mandates accept premium tier pricing for predictive casing management.
Supply Chain Analysis
Just-in-time casing collection from fleet depots dominates premium tier operations, while strategic stockpiling of inspected inventory buffers regional processors against supply interruptions from premium tire manufacturers. Casing supply concentrates in United States interstate corridors, Germany's Rhine-Ruhr logistics networks, and Shandong Province manufacturing bases. Raw material dependencies span Brazilian and Southeast Asian natural rubber, petrochemical feedstocks for synthetic rubber, and scrap steel recovery for bead wire reinforcement. Single-source vulnerability from premium tire manufacturers controlling high-quality casing flows through captive collection networks threatens independent retreader viability. Distribution runs through Bandag franchise networks, integrated manufacturer service chains, and tire-as-a-service platform operators serving large fleet accounts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating among top-50 logistics providers with multi-year tire management contracts, fragmenting procurement authority previously held by independent fleet managers and compressing spot-market volume for unaffiliated retreaders.
For Market Incumbents: Fortify network density along United States interstate corridors through regional retreader acquisitions that expand service radius for captive casing collection. Deepen backward integration into shearography equipment and technician certification programs to lock out competitors from premium fleet contracts threatened by qualified inspection specialist scarcity. For New Entrants and Emerging Players: Anchor in municipal and short-haul fleet segments where cold process and pre-cured methods penetrate against hot cure dominance due to faster turnaround requirements and lower capital barriers. Germany and France municipal bus operators present most penetrable geography under EU Green Deal energy accounting frameworks; tire-as-a-service per-mile pricing contracts offer viable go-to-market angle against entrenched equipment ownership models. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting downward across pre-cured and cold process equipment tiers, enabling asset-light platform operators to challenge integrated manufacturers. Long-term viability favors tire-as-a-service platform operators with predictive casing management software and multi-year fleet contracts over capital-heavy hot cure processors. Target acquisition archetype: regional retreaders with established municipal relationships and underutilized cold process capacity. Signal to watch: Extended Producer Responsibility proposal adoption rates across United States state legislatures and EU member states.| Strategic Initiative | Industry Significance |
|---|---|
| Shearography Equipment Deployment | Automated inspection at 3-4x manual throughput rates differentiates premium fleet service tiers. |
| REACH-Compliant Compound Sourcing | Documented recycled content percentages gate supplier qualification for EU logistics contracts. |
| Tire-as-a-Service Platform Launch | Per-mile pricing bundles retread services with predictive casing management for large fleet accounts. |
| Regional Retreader Acquisition | Network density expansion captures procurement authority from fragmented independent operators. |
| Cold Process Capacity Addition | Lower energy inputs align with EU Green Deal carbon accounting for municipal fleet segments. |
Methodological Framework
A standing panel of fleet procurement directors, retread plant operations managers, tire compound technical directors, and logistics provider sustainability officers provided ongoing calibration across primary interview cycles. Secondary validation drew from EPA emission standard filings, NHTSA fuel economy rulemakings, REACH substance registrations, EU Green Deal implementation documents, and MIIT tire remanufacturing standards. Bottom-up casing flow modeling triangulated against top-down fleet tire placement estimates.
Consistency checks against external benchmarks validated volume and value outputs across the projection horizon. Segmentation dimensions modeled include vehicle application class, retread process technology, compound material grade, end-user customer type, and regional regulatory cluster. CAGRs were derived from fitted growth curves incorporating fleet size expansion, retread penetration rate assumptions, and process technology substitution elasticities. Industry-specific inputs encompassed shearography adoption trajectories and Extended Producer Responsibility policy evolution.
Decision-makers should treat outputs as directional under base assumptions of sustained EPA emission standard enforcement and stable natural rubber supply chains; material deviation would warrant model refresh. Practitioners should keep alternative scenarios live as EU Green Deal carbon accounting rules and United States state-level Extended Producer Responsibility proposals evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Tires and Wheels
Bike Wheels Market
Tires and Wheels
Construction Machinery Tires Market
Tires and Wheels
Kuwait Tyres Market
Tires and Wheels
Global Automotive Tires Market
Tires and Wheels
Industrial Tire Market
Tires and Wheels
Bicycle Rim Brake Market
Tires and Wheels
North America 2-Wheeler Tire Market
Tires and Wheels
Tire Building Machinery Market
Tires and Wheels
Automotive Intelligent Tires Market
Tires and Wheels
Low Rolling Resistance Tire Market
Tires and Wheels
North Commercial Vehicle Tire Pressure Monitoring Systems Market
Tires and Wheels
Tire Repair Patch Market
Tires and Wheels
Continuous Track Wheels Market
Tires and Wheels
Intelligent Tire Market
Tires and Wheels
Automotive Green Tires Market
Tires and Wheels
Solid Tire Market