
 North America Used Car Market | 2026-2036
North America Used Car Market Size, Share, and Industry Trends Forecast 2026-2036
North America Used Car Market Analytics
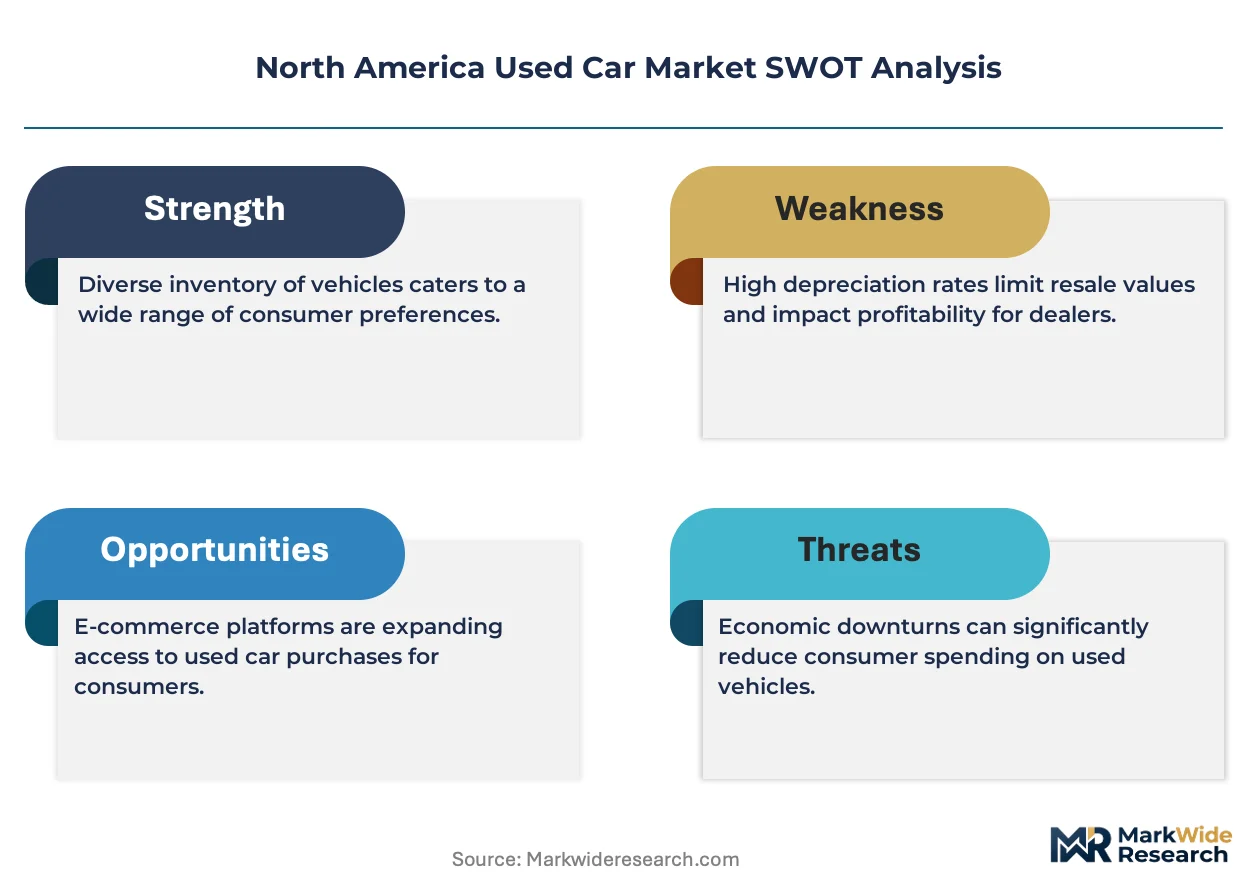
Fragmentation among digital-native buyers is recalibrating how inventory moves through wholesale channels. CarMax, Inc. leverages its appraisal algorithm and national reconditioning footprint to control liquidity across price tiers. Carvana Co. competes through proprietary vending logistics and online title-transfer infrastructure. AutoNation, Inc. sustains margin capture by anchoring certified pre-owned flow through fixed operations in metropolitan Sun Belt markets.
A used car is a previously registered motor vehicle resold through secondary channels, typically assessed by odometer reading, structural integrity, powertrain condition, and ownership history prior to reconditioning for retail or wholesale disposition. Certified pre-owned programs dominate margin pools by attaching factory-backed warranties and inspection protocols that command price premiums over fair-condition inventory. Electric and hybrid units within the fuel type segment represent the fastest-growing trade category as battery health diagnostics mature and original powertrain warranties transfer. Dealerships and online platforms now split transaction flow, with auctions receding as direct-to-consumer tooling captures younger demographics.
The EPA tailpipe standards and NHTSA safety recall databases shape vehicle eligibility for resale, while state-level lemon laws and title-branding regulations in California, Texas, and Florida create patchwork compliance costs for cross-border remarketers. The FTC's Used Car Rule mandates Buyer's Guide disclosures that standardize warranty transparency but vary in enforcement intensity across provincial Canadian markets and U.S. state attorney general offices. Stakeholders must monitor how connected-vehicle data access policies and right-to-repair legislation reshape valuation models and consumer trust mechanisms.
Market Dynamics
Fleet turnover acceleration among ride-hailing operators and gig-economy drivers is compressing vehicle holding periods and flooding wholesale channels with late-model inventory. This structural oversupply is forcing remarketers to reprice certified pre-owned units faster than historical depreciation curves.
Growth Catalysts
- EPA Tailpipe Standards:Commercial buyers in Texas and California face compliance deadlines that favor newer used vehicles with cleaner powertrains. Fleet managers accelerate replacement cycles to avoid penalty exposure.
- Battery Health Diagnostics:Standardized testing protocols for electric and hybrid powertrains now transfer original manufacturer warranties. Secondary buyers gain confidence in electrified used inventory.
- Sun Belt Population Inflows:Florida and Texas sustain elevated transaction volumes as relocating households establish vehicle ownership. Demographic shifts concentrate demand in low-tax, warm-climate states.
Market Restraints
- Interest Rate Sensitivity:Subprime auto loan spreads widen as the Federal Reserve maintains elevated policy rates. Credit-constrained buyers exit the market or downsize vehicle class.
- Title Branding Fragmentation:California's salvage disclosure requirements differ materially from Texas and Florida standards. Cross-border remarketers absorb compliance overhead that erodes margin.
- Semiconductor Supply Normalization:New vehicle production recovery reduces the price gap between used and new inventory. Substitution pressure intensifies in the 2-4 year age cohort.
Strategic Opportunities
- Direct-to-Consumer Platforms:Online title-transfer infrastructure and proprietary logistics networks bypass traditional auction intermediaries. Younger demographics complete end-to-end transactions without dealership contact.
- Right-to-Repair Legislation:Proposed federal and state mandates would unlock connected-vehicle data for independent service providers. Third-party reconditioners gain diagnostic parity with franchised dealers.
- Metropolitan Fixed Operations:Certified pre-owned programs anchored through service bays in Sun Belt cities capture lifetime maintenance revenue. Factory-backed warranties lock in recurring customer relationships.
Industry Challenges
- Connected-Vehicle Data Access:OEMs restrict telematics feeds that power algorithmic pricing and predictive maintenance offers. Independent platforms face information asymmetry against manufacturer-captive remarketers.
- Reconditioning Labor Shortage:Certified technician pipelines fail to match throughput targets at national reconditioning centers. Wage inflation in automotive service compresses unit economics.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Used Car Market |
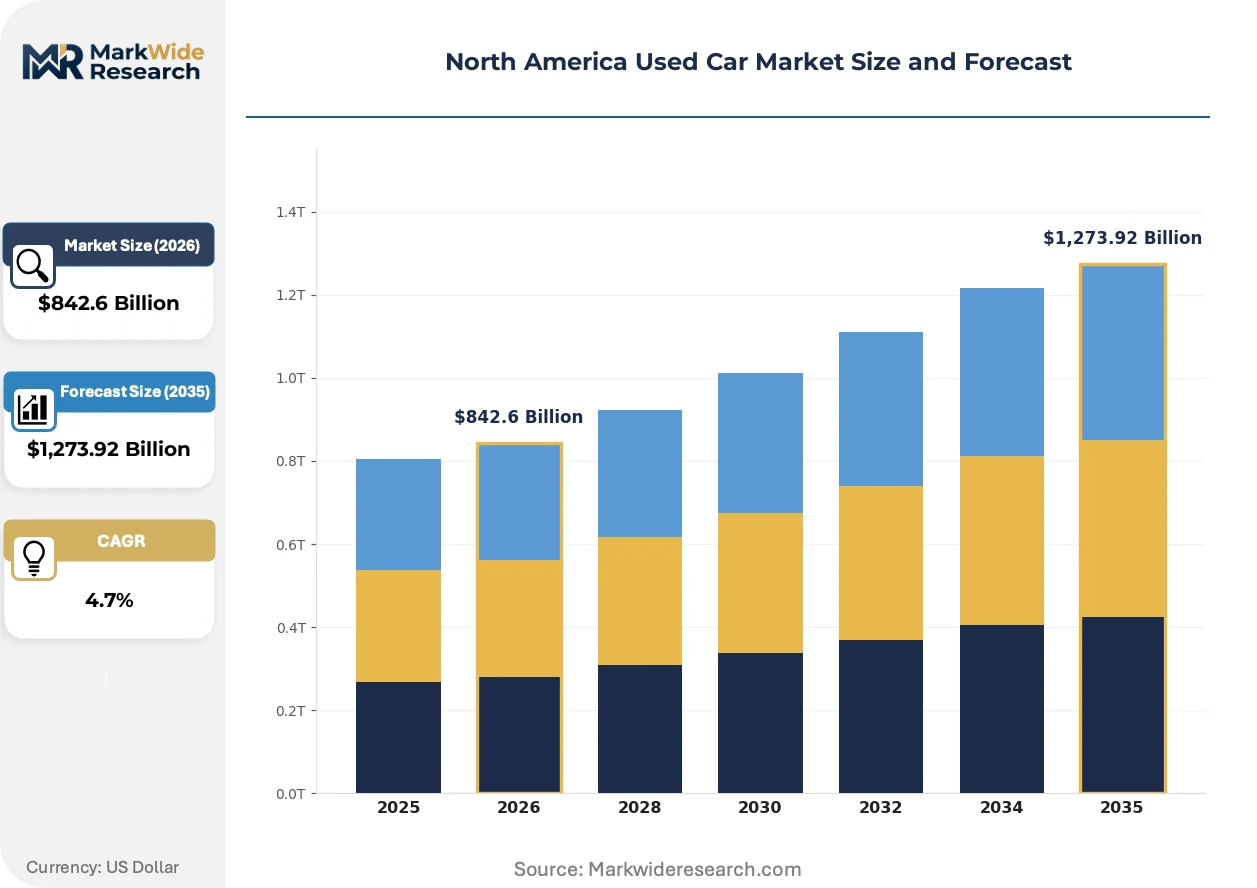
| Market Size in 2026 | $842.6 Billion |
| Market Size in 2035 | $1,273.92 Billion |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Vehicle Type: SUV, Sedan, Coupe, Pickup Condition: Certified Pre-Owned, Good, Fair, Poor Fuel Type: Gasoline, Diesel, Electric, Hybrid Sales Channel: Dealerships, Private Sellers, Online Platforms, Auctions |
| Companies Covered | CarMax, Inc., AutoNation, Inc., Carvana Co., Group 1 Automotive, Inc., Lithia Motors, Inc., Hendrick Automotive Group, Asbury Automotive Group, Cox Automotive, Penske Automotive Group, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Used Car Market Evolving Landscape
Digital-native inventory discovery and transaction completion are displacing physical auction attendance and dealership lot visits. Three convergent developments are restructuring how vehicles move through secondary channels.
AI-powered appraisal algorithms ingest real-time wholesale transactions, regional demand signals, and reconditioning cost estimates to generate instant purchase offers. CarMax and digital competitors deploy these systems at scale, compressing the bid-ask spread that independent dealers historically captured. Machine learning is expanding into price prediction for individual VINs based on option packages and ownership history.
The FTC's Used Car Rule mandates standardized Buyer's Guide disclosures that expose warranty coverage gaps and prior damage history. Enforcement intensity varies across state attorney general offices, creating compliance arbitrage for multi-state operators. California and Texas markets show the strictest interpretation, forcing inventory segmentation by disclosure risk tier.
Subscription and short-term ownership models are fragmenting traditional 72-month financing commitments. Fleet operators and urban consumers in Florida and California pilot vehicle-as-a-service programs that return units to remarketing channels within 18 months. This behavioral shift concentrates supply in the near-new segment where depreciation curves remain steep.
North America Used Car Market Segmentation
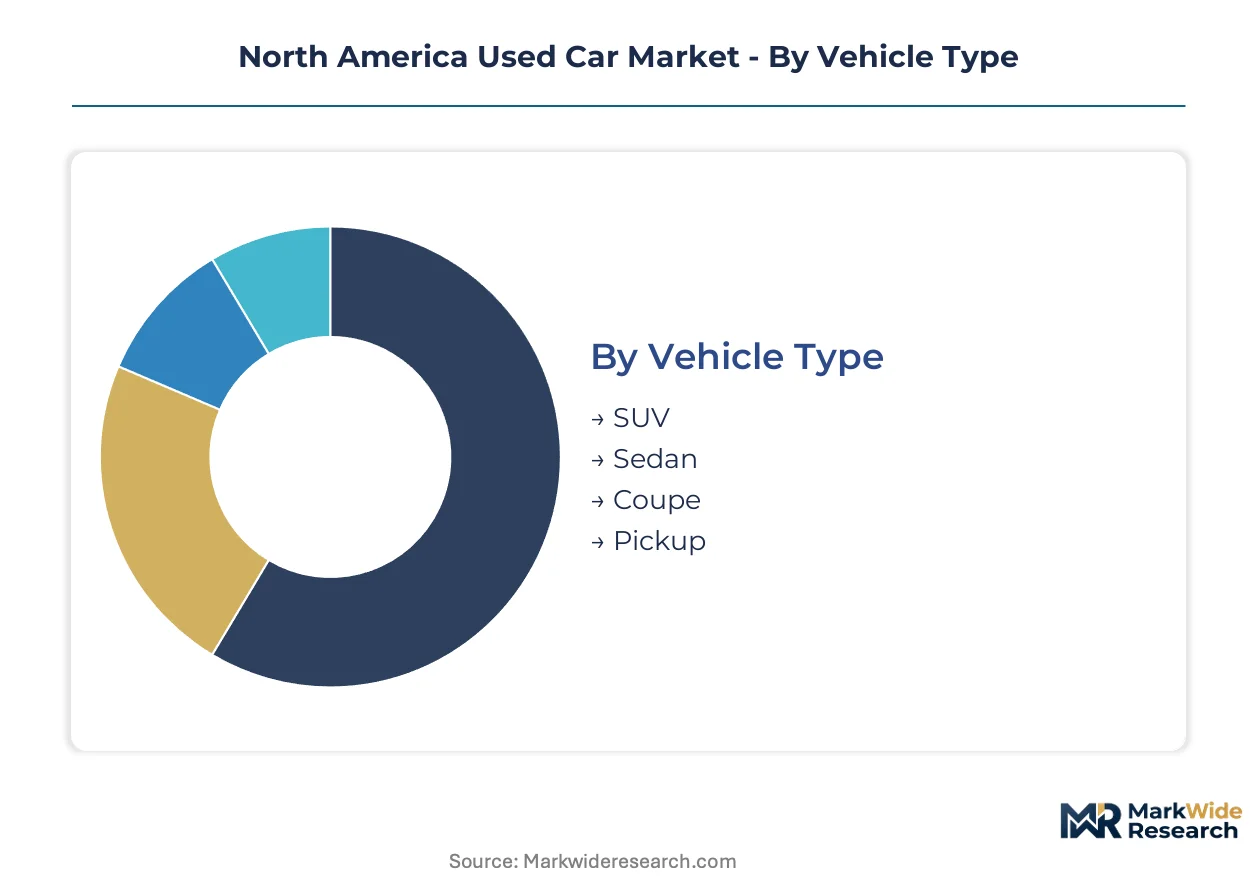
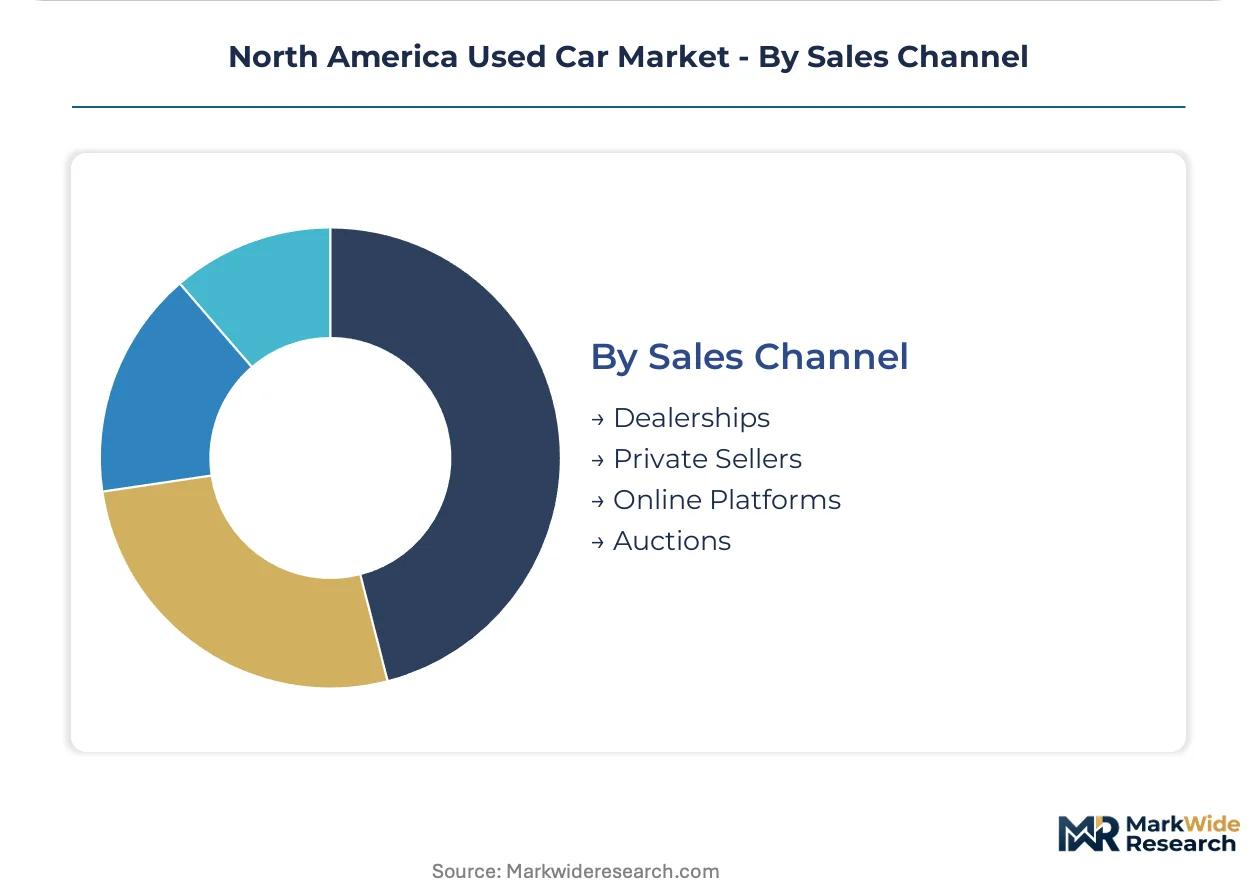
Segmentation in the North American used car market determines pricing power, reconditioning investment, and channel selection. Vehicle type and condition grade anchor valuation models, while fuel type and sales channel shape buyer demographics and margin capture.
Vehicle Type:
Customization spans body configurations from utility-focused haulers to passenger-centric designs, with standardization strongest in mass-market sedans.
- SUV:Three-row and compact crossovers dominate Texas and Florida transactions. Sun Belt families prioritize cargo capacity and ground clearance for suburban mobility.
- Sedan:Four-door passenger cars with standardized trunk configurations. Fleet operators in California accelerate sedan turnover to meet EPA tailpipe compliance deadlines.
- Coupe:Two-door performance variants with limited rear seating. Enthusiast buyers in metropolitan markets seek low-mileage examples for recreational use.
- Pickup:Full-size and mid-size trucks with open-bed utility. Contractors in Texas sustain elevated demand for work-grade configurations.
Leading the category by volume: SUV. Growing fastest: Pickup.
Condition:
Cost tier stratification separates warranty-backed inventory from as-is wholesale units, with reconditioning intensity determining retail readiness.
- Certified Pre-Owned:Factory-backed inspection protocols with extended powertrain coverage. Dealerships in Florida command price premiums through fixed operations anchoring.
- Good:Clean title history with documented maintenance and minimal cosmetic defects. Private sellers in Texas leverage this grade for peer-to-peer transactions.
- Fair:Mechanical soundness with visible wear requiring partial reconditioning. Auction channels absorb this tier for wholesale redistribution.
- Poor:Significant structural or powertrain defects sold for parts or salvage. California's strict disclosure requirements limit cross-border remarketing.
Highest margin capture: Certified Pre-Owned. Steepest volume: Good.
Fuel Type:
Technology maturity separates established internal combustion from electrified powertrains with transferable warranty coverage.
- Gasoline:Conventional port and direct-injection engines with established service infrastructure. This segment maintains dominant transaction share across all sales channels.
- Diesel:Compression-ignition engines with torque-focused applications. Commercial buyers in Texas favor heavy-duty pickups for towing capacity.
- Electric:Battery-electric powertrains with range and health diagnostics now standardized. Secondary buyers gain confidence as original manufacturer warranties transfer.
- Hybrid:Dual-powertrain systems combining gasoline and electric propulsion. California fleet managers prioritize these units for HOV lane access and emission compliance.
Volume leader: Gasoline. Gaining share fastest: Electric.
Sales Channel:
Customer type fragmentation splits between convenience-seeking digital natives and relationship-driven traditional buyers.
- Dealerships:Brick-and-mortar operations with reconditioning bays and financing partnerships. AutoNation and CarMax anchor certified pre-owned flow in Sun Belt metros.
- Private Sellers:Individual owners transacting through classified platforms or word-of-mouth. Price discovery relies on buyer inspection without standardized disclosures.
- Online Platforms:End-to-end digital infrastructure with proprietary logistics and title transfer. Carvana's vending model captures younger demographics without dealership contact.
- Auctions:Wholesale-only venues for dealer-to-dealer inventory movement. Physical auction attendance recedes as direct-to-consumer tooling expands.
Transaction volume concentrates: Dealerships. Channel expanding most quickly: Online Platforms.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Transaction volumes concentrate in Texas and Florida, where population inflows and fleet turnover cycles sustain elevated secondary vehicle demand. Sun Belt metros anchor certified pre-owned flow through dealership fixed operations. Cross-border remarketers navigate divergent state disclosure requirements that fragment compliance costs.
United States
Texas and Florida dominate transaction volumes as relocating households establish vehicle ownership and gig-economy drivers accelerate fleet replacement. The EPA's evolving tailpipe emission standards push commercial buyers toward newer used vehicles with cleaner powertrains. Dallas-Fort Worth and Miami-Fort Lauderdale corridors concentrate reconditioning infrastructure and digital platform logistics.
California
Stringent salvage disclosure requirements and emission compliance deadlines reshape vehicle eligibility for resale. The California Air Resources Board enforces zero-emission vehicle mandates that accelerate hybrid and electric unit turnover. Los Angeles and San Francisco Bay Area metros anchor certified pre-owned programs with factory-backed warranty transfer protocols.
Canada
Provincial variation in safety certification and title branding creates patchwork compliance for cross-border remarketers. Health Canada and Transport Canada administer recall databases that shape vehicle eligibility. The Greater Toronto Area and Vancouver corridors concentrate digital platform penetration and dealership consolidation.
Mexico
Informal secondary channels absorb significant import volume from US wholesale auctions. The Secretariat of Economy oversees automotive sector regulations with limited standardization of used vehicle disclosures. Mexico City and Monterrey metros anchor formal dealership networks expanding certified pre-owned coverage.
North America Used Car Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue direct-to-consumer digital infrastructure. The market structures around national reconditioning footprints, proprietary logistics networks, and fixed operations anchoring. Three archetypes dominate: algorithm-driven appraisal platforms, vending logistics specialists, and metropolitan service-bay operators. Competitive moves concentrate on geographic expansion into Sun Belt corridors and technology licensing for battery health diagnostics.
Within the national reconditioning tier, CarMax, Inc. and AutoNation, Inc. exemplify scale-driven footprint control across price tiers. Carvana Co. occupies a position representing digital-native vending logistics and online title-transfer infrastructure. These three anchors illustrate how proprietary algorithms, fixed operations density, and end-to-end digital tooling fragment competitive positioning across wholesale and retail channels.
| Leading Market Players |
|---|
| CarMax, Inc. |
| AutoNation, Inc. |
| Carvana Co. |
| Group 1 Automotive, Inc. |
| Lithia Motors, Inc. |
| Hendrick Automotive Group |
| Asbury Automotive Group |
| Cox Automotive |
| Penske Automotive Group |
| Others |
Value Network & Pricing Analysis
Certified technician concentrations in Texas and Florida create labor-cost differentials that widen spreads between certified pre-owned premiums and fair-condition wholesale baselines. Reconditioning wage inflation in Sun Belt metros compresses margin capture at national centers while independent shops in lower-cost secondary markets maintain pricing flexibility.
Pricing Analysis
Volume concentrates in good-condition peer-to-peer transactions while margin pools accrue to certified pre-owned programs with factory-backed warranties. Price differentiation rests on inspection protocol rigor and transferable powertrain coverage duration. Cost compression in the fair-condition tier is intensifying because wholesale auction oversupply from fleet turnover accelerates depreciation. Subprime auto loan spread widening makes credit-constrained buyers most price-sensitive, while commercial fleet managers show least sensitivity due to EPA compliance deadline pressures.
Supply Chain Analysis
Regional distribution centers in Dallas-Fort Worth and Miami-Fort Lauderdale anchor hub-and-spoke patterns that feed reconditioning throughput to Sun Belt retail corridors. Inventory sourcing draws from California, Texas, and Florida wholesale auctions where ride-hailing fleet turnover concentrates late-model supply. Single-source vulnerability sits with OEM telematics data access restrictions that limit independent valuation parity. Distribution runs through direct-to-consumer platforms bypassing traditional auction intermediaries.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Used car market consolidation accelerates as interest rate sensitivity forces subprime-dependent independents toward exit or acquisition. Platform scale and reconditioning density separate viable national operators from regional survivors.
For Market Incumbents: Anticipate margin compression from digital-native entrants by deepening proprietary appraisal algorithm investment and locking exclusive battery health diagnostic licensing. Defensive consolidation moves include acquiring regional reconditioning centers in Texas and Florida to control throughput capacity, and securing OEM data-sharing agreements to neutralize telematics asymmetry against manufacturer-captive remarketers.
For New Entrants and Emerging Players: Begin with metropolitan fixed operations in Sun Belt corridors where certified pre-owned anchoring captures lifetime maintenance revenue. White-space targets include hybrid and electric unit specialization with transferable warranty protocols, and right-to-repair diagnostic tooling for independent service parity. Go-to-market angle centers on subscription ownership models returning near-new inventory to remarketing channels within compressed holding periods.
For Investors and Strategic Acquirers: Re-rating potential sits with algorithm-driven appraisal platforms given AI-powered VIN-specific pricing expansion across the analysis window. Long-term viability favors operators combining national reconditioning footprints with direct-to-consumer logistics infrastructure. Acquisition target archetype: regional dealership groups with dense service bay networks in Texas and Florida metros. Signal to watch: EPA tailpipe standard enforcement intensity accelerating commercial buyer migration toward newer used powertrains.
| Strategic Initiative | Industry Significance |
|---|---|
| Proprietary Appraisal Algorithm Deployment | CarMax and Carvana compress bid-ask spreads that independent dealers historically captured through machine learning. |
| Metropolitan Fixed Operations Expansion | AutoNation anchors certified pre-owned flow through service bay density in Sun Belt markets with population inflows. |
| Battery Health Diagnostic Licensing | Standardized testing protocols for electrified powertrains transfer original manufacturer warranties to secondary buyers. |
| Direct-to-Consumer Platform Buildout | Online title-transfer infrastructure bypasses traditional auction intermediaries for younger demographic capture. |
| Right-to-Repair Diagnostic Tooling | Federal and state mandates would unlock connected-vehicle data for independent reconditioner parity with franchised dealers. |
Research Methodology
Independent corroboration across dealership operations executives, fleet procurement managers, and digital platform engineers underwrites the qualitative findings. Primary interviews with reconditioning center directors, auction channel specialists, and regulatory compliance officers combined with secondary validation from NHTSA recall databases, EPA emission standard filings, and state attorney general enforcement records. Bottom-up transaction volume modeling and top-down macroeconomic triangulation anchored market sizing.
Comparable-period anchoring linked historical wholesale transaction patterns to forward projection assumptions across the modeling period. Segmentation dimensions modeled include vehicle type, condition grade, fuel type, and sales channel with regional production cluster overlays. CAGRs derived from weighted average of demand elasticity coefficients and supply-side capacity constraints. Forecast inputs incorporated battery health diagnostic adoption curves and right-to-repair legislative probability assessments.
Underlying measurement precision varies by segment; certified pre-owned and online platform channels carry tighter precision than informal private seller transactions. Forecasts reflect documented assumptions regarding interest rate trajectory and EPA enforcement intensity. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Used Vehicles
Middle East and Africa Used Car Market
Used Vehicles
Used E-Scooter Market
Used Vehicles
Indonesia Used Car Market
Used Vehicles
Online Car Buying Market
Used Vehicles
New Zealand Used Car Market
Used Vehicles
United Kingdom Used Car Market
Used Vehicles
UAE Certified Pre-Owned Car Market
Used Vehicles
India Used Car Market
Used Vehicles
Russia Used Car Market
Used Vehicles
Kuwait Used Car Market
Used Vehicles
Kenya Used Car Market
Used Vehicles
Spain Used Car Market
Used Vehicles
UAE Used Cars Industry Market
Used Vehicles
Philippines Used Car Market
Used Vehicles
Netherlands Used Car Market
Used Vehicles
Canada Used Car Market