
 UK Automotive Glass Fiber Composites Market | 2026-2036
UK Automotive Glass Fiber Composites Market Size, Share, and Industry Trends Forecast 2026-2036
UK Automotive Glass Fiber Composites Market Analytics
Asset-light leasing models for composite manufacturing equipment is fragmenting competitive entry barriers across the UK supply base. Owens Corning leverages its upstream fiber production capabilities to secure raw material access for British tier suppliers. SAERTEX specializes in multiaxial fabric architectures that dominate wind and automotive crossover applications. Toray Industries extends its carbon fiber expertise into glass hybrid solutions for premium vehicle platforms.
UK automotive glass fiber composites combine silica-based glass filaments with thermoset or thermoplastic matrices to produce lightweight, high-strength parts typically achieving 40-60% weight reduction versus stamped steel equivalents. Sheet Molding Compound occupies the mature volume tier serving bumper beams and underbody shields where cost-per-part economics dominate procurement decisions. Continuous Fiber Composite leads structural applications for electric vehicle battery enclosures where stiffness-to-weight ratios determine platform qualification. Interior Components represents the fastest-growing application segment as OEMs eliminate metal substrates to reduce cabin noise and thermal mass.
The UK's Vehicle Certification Agency enforces UN ECE type-approval standards that mandate crashworthiness validation for composite structural members, while the Health and Safety Executive regulates styrene emissions from open-mold processes. The Department for Transport's decarbonisation roadmap tightens fleet-average CO2 thresholds that push OEMs toward material substitution strategies. Stakeholders must monitor how the proposed UK Carbon Border Adjustment Mechanism reshapes import competitiveness for European compound suppliers versus domestic molders.
Market Dynamics
The UK government's Net Zero Strategy is compressing fleet-average CO2 thresholds, forcing OEMs to substitute stamped steel with glass fiber composites in structural applications. This regulatory pressure is restructuring material procurement priorities across the Midlands manufacturing corridor.
Growth Catalysts
- UN ECE type-approval standards:The Vehicle Certification Agency mandates crashworthiness validation for composite structural members, creating certified demand pull for qualified UK molders.
- Electric vehicle battery enclosures:Continuous Fiber Composite achieves stiffness-to-weight ratios that qualify platforms for premium EV architectures, accelerating specification rates.
- Midlands manufacturing corridor:Concentrated OEM assembly around Birmingham and Coventry reduces logistics costs for just-in-time composite component delivery.
Market Restraints
- Styrene emission compliance:The Health and Safety Executive regulates open-mold processes, adding capital expenditure for emission capture systems at smaller molders.
- Raw material concentration:Glass fiber roving supply concentrates among three European producers, exposing UK compounders to input cost volatility and allocation risk.
- Steel substitution economics:Sheet Molding Compound faces price resistance in bumper beam applications where high-volume steel stamping retains cost-per-part advantages.
Strategic Opportunities
- Scotland and Northern England:Underpenetrated automotive supply bases offer greenfield molding capacity with access to offshore wind-trained composite workforces.
- UK Carbon Border Adjustment Mechanism:Proposed import levies on European compounds would improve domestic molder competitiveness versus continental suppliers.
- Thermoplastic-thermoset hybrid processing:Converging resin systems enable recyclable structural components that align with extended producer responsibility mandates.
Industry Challenges
- Composite design engineering talent:UK universities produce insufficient specialists in fiber orientation simulation and failure mode analysis for automotive load cases.
- Crash certification timelines:UN ECE structural validation requires 18-24 month qualification cycles that compress product development windows for new EV platforms.
- Legacy paint shop integration:Composite substrates demand modified e-coat and bake processes that disrupt established OEM finishing line configurations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | UK Automotive Glass Fiber Composites Market |
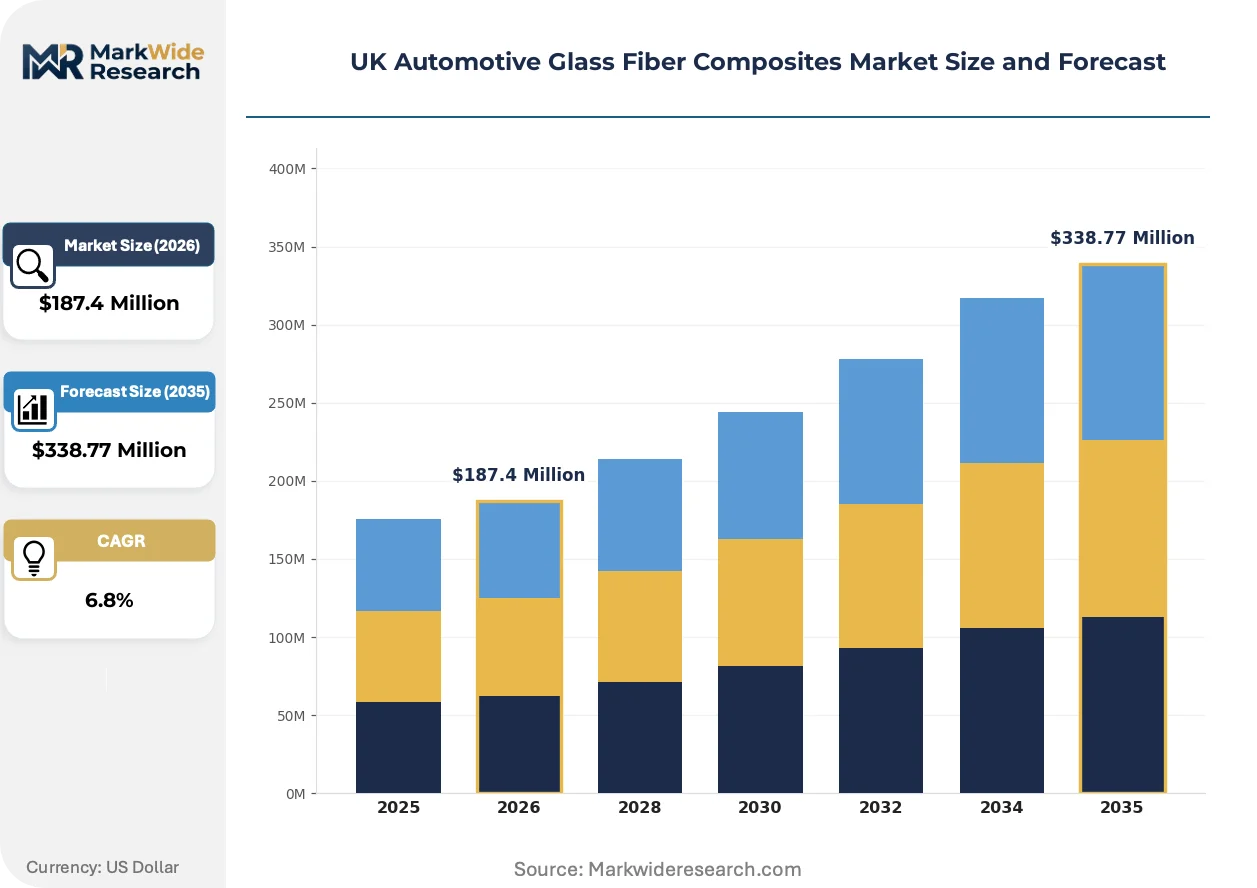
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $338.77 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Sheet Molding Compound, Bulk Molding Compound, Continuous Fiber Composite, Discontinuous Fiber Composite End User: Passenger Vehicles, Commercial Vehicles, Electric Vehicles, Hybrid Vehicles Application: Interior Components, Exterior Components, Structural Parts, Safety Features Manufacturing Stage: Raw Material Processing, Molding, Finishing, Quality Control |
| Companies Covered | Solvay Group, Owens Corning, 3B Fiberglass, SAERTEX, Veplas Group, Saint-Gobain, Toray Industries, SGL Carbon, Teijin Limited, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
UK Automotive Glass Fiber Composites Market Evolving Landscape
Digital manufacturing tools are compressing composite development cycles while regulatory tightening and procurement centralization reshape competitive access to UK automotive platforms.
Digital twin simulation is virtualizing the traditional prototype-test-iterate cycle for glass fiber component development. Tier suppliers serving JLR and BMW Group adopt real-time fiber draping simulation to reduce tooling iterations by half. This compression of qualification timelines is virtualizing competitive advantage toward engineering-intensive molders with captive simulation capabilities.
The Department for Transport's decarbonisation roadmap tightens fleet-average CO2 thresholds annually through 2035. OEMs respond by eliminating metal substrates from interior components to reduce thermal mass and HVAC load. Interior trim suppliers accelerate thermoplastic composite adoption to meet these accumulating mass-reduction mandates.
Buyer consolidation among UK-based OEM procurement functions is displacing fragmented tier-two sourcing. Nissan Sunderland and Stellantis Ellesmere Port now mandate direct molder relationships for structural composite programs, bypassing traditional compound distributors. This channel compression concentrates volume with molders possessing in-house compounding and Class A surface finishing capabilities.
UK Automotive Glass Fiber Composites Market Segmentation
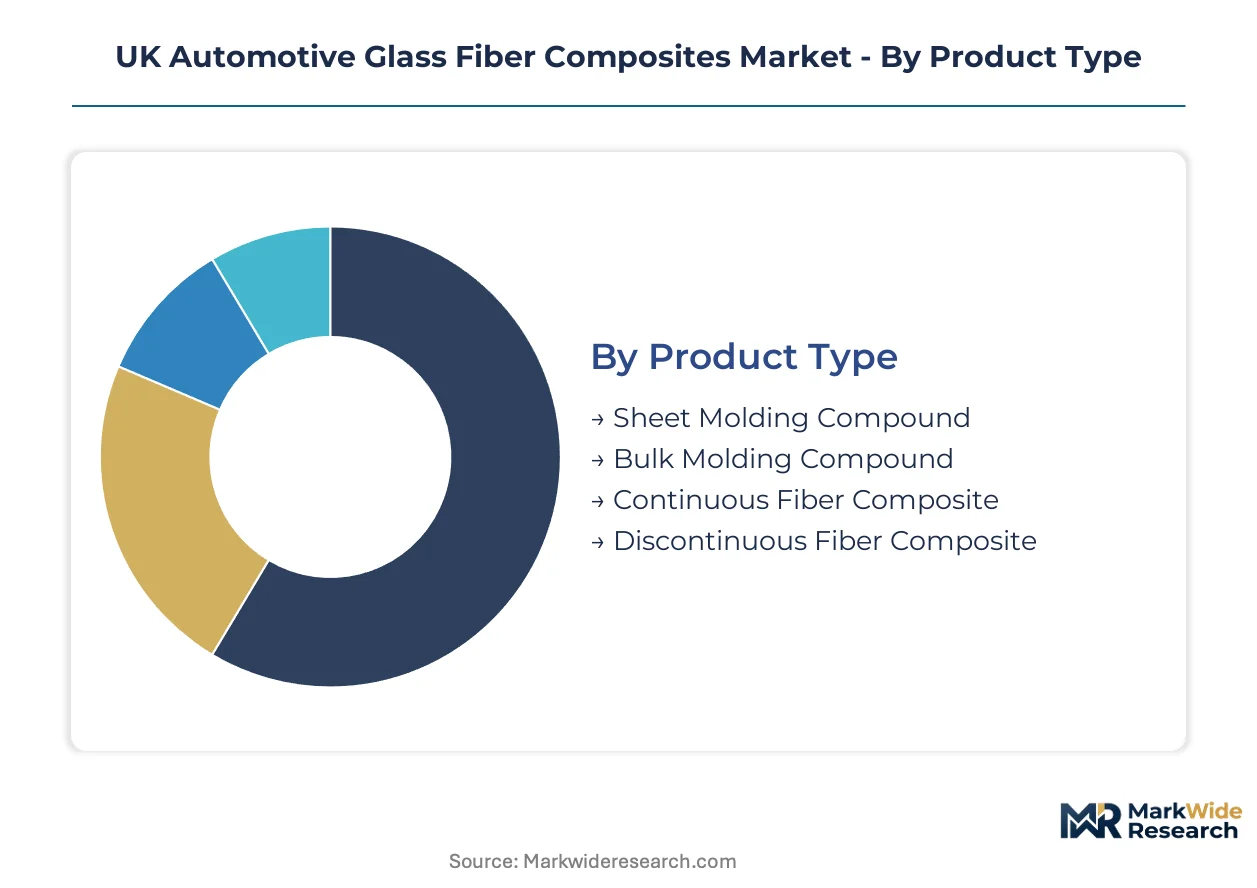
UK automotive glass fiber composites segment across material form, vehicle architecture, functional placement, and production stage. Procurement patterns diverge sharply between legacy internal combustion platforms and emerging electric vehicle architectures.
Product Type:
Material selection tracks the stiffness-to-cost trade-off spectrum across vehicle structural requirements.
- Sheet Molding Compound:Chopped glass fibers dispersed in thermoset polyester resin enable high-volume compression molding for non-structural panels. Procurement concentrates in bumper beam and underbody shield programs serving Stellantis Ellesmere Port where cost-per-part economics dominate supplier qualification.
- Continuous Fiber Composite:Unidirectional or woven glass roving architectures achieve specific stiffness values exceeding 40 GPa, qualifying for electric vehicle battery enclosures. Demand is accelerating around JLR's Coventry engineering center as platform architectures migrate to dedicated EV skateboards requiring torsional rigidity.
- Bulk Molding Compound:Higher fiber loading than SMC enables intricate geometries for electrical housings and connector modules. Midlands tier suppliers favor BMC for relay boxes and fuse holders where dimensional stability under thermal cycling matters.
- Discontinuous Fiber Composite:Random fiber orientation delivers isotropic properties suitable for non-critical brackets and clips. Scottish compounders exploit discontinuous fiber for secondary structural elements in commercial vehicle cab assemblies.
Established volume favors Sheet Molding Compound; emerging adoption favors Continuous Fiber Composite.
End User:
Vehicle electrification status restructures composite specification intensity and performance thresholds.
- Electric Vehicles:Battery enclosure and thermal management components demand fire-retardant glass phenolic systems. UK EV assembly at Sunderland and Oxford drives specification of compression-molded battery trays where flame resistance and electromagnetic shielding converge.
- Passenger Vehicles:Interior trim and closure panels represent mature composite penetration. Birmingham-area molders supply door modules and seat structures for volume OEMs where mass reduction targets remain secondary to cost containment.
- Commercial Vehicles:Cab structures and aerodynamic fairings exploit glass fiber corrosion resistance. Northern England logistics hubs source composite deflectors and sleeper cab panels where steel fatigue and road salt degradation accelerate material substitution.
- Hybrid Vehicles:Dual powertrain packaging constraints create niche demand for underhood thermal shields. Midlands engineering centers specify hybrid-specific heat management composites isolating battery packs from exhaust-adjacent tunnel structures.
Procurement scale concentrates in Passenger Vehicles; specification intensity climbs fastest in Electric Vehicles.
Application:
Functional placement determines surface finish requirements and structural validation burden.
- Interior Components:Thermoplastic glass mat substrates replace stamped steel in instrument panels and door trims. OEMs eliminate metal substrates to reduce cabin noise and thermal mass, accelerating specification rates across premium and mass-market segments.
- Structural Parts:Load-bearing members including cross-members and subframes require UN ECE crash certification. The Vehicle Certification Agency mandates 18-24 month qualification cycles that compress development windows for new EV platform launches.
- Exterior Components:Class A surface finishing capability separates qualified suppliers from commodity molders. Fenders and hoods demand in-mold coating or paint-ready surfaces that integrate with established OEM electrocoat lines.
- Safety Features:Bumper beams and crash absorbers exploit controlled crush characteristics of glass fiber composites. SMC dominates energy absorption applications where specific energy absorption values exceed 40 kJ/kg.
Interior Components gain share fastest from metal substitution; Structural Parts carry the heaviest certification overhead.
Manufacturing Stage:
Process control points determine quality consistency and regulatory compliance exposure.
- Molding:Compression and injection molding operations concentrate value-add and capital intensity. Midlands molders differentiate through fiber orientation control and automated preform placement reducing cycle variation.
- Raw Material Processing:Glass fiber roving chopping and resin compounding establish material specifications. Three European roving suppliers dominate input supply, exposing UK compounders to allocation risk during demand surges.
- Finishing:Edge trimming, drilling, and surface preparation enable assembly integration. The Health and Safety Executive regulates dust and styrene exposure, mandating local exhaust ventilation and automated trimming cells.
- Quality Control:Non-destructive testing and dimensional validation gate shipment to OEM assembly lines. Ultrasonic inspection and computed tomography verify fiber distribution and void content for structural programs.
Molding captures margin concentration; Quality Control absorbs regulatory compliance burden.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Import dependency on European glass fiber roving concentrates supply risk at UK ports, while domestic molding capacity expansion across the Midlands and Northern England is narrowing the trade deficit in finished composite components. The Department for Transport's decarbonisation mandates are accelerating regional production localization to secure just-in-time supply chains for EV assembly.
Midlands
Birmingham and Coventry anchor the UK's automotive glass fiber composite demand, with JLR's engineering center and Stellantis Ellesmere Port driving specification of battery enclosure structures. The West Midlands Combined Authority coordinates advanced materials innovation funding that supports local molder scale-up. Tier suppliers concentrate around the M6 corridor to minimize logistics costs for daily component delivery to OEM assembly lines.
North England
Nissan Sunderland's EV36Zero project is pulling glass fiber composite procurement toward the Northeast, with battery tray and structural component demand scaling through 2025. The North East Combined Authority administers automotive transformation funds that subsidize molding equipment investment. Local suppliers are establishing finishing capabilities to bypass Midlands-based intermediaries for Class A surface components.
Scotland
Offshore wind composite manufacturing expertise in Glasgow and Aberdeen is transferring into automotive applications, particularly for large structural moldings where vacuum infusion skills transfer directly. Scottish Enterprise targets automotive diversification grants at wind energy suppliers facing order cyclicality. The Central Belt offers greenfield sites with lower property costs than English manufacturing zones.
Wales
Stellantis Ellesmere Port's conversion to electric van production is stimulating Welsh border region composite investment, with molders locating near the Dee estuary for port access to European raw materials. The Welsh Government's automotive sector recovery program funds skills retraining from steel processing into polymer composite fabrication. Wrexham and Deeside industrial parks host emerging tier-two suppliers qualifying for OEM direct relationships.
Southeast England
London orbital logistics hubs handle imported Sheet Molding Compound distribution to Midlands molders, with Dartford and Thurrock warehousing concentrations serving just-in-sequence delivery contracts. The Thames Freeport designation reduces customs friction for European compound imports pending UK Carbon Border Adjustment Mechanism implementation. Proximity to Vehicle Certification Agency headquarters in Bristol accelerates crash certification documentation for structural programs.
UK Automotive Glass Fiber Composites Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream in a structure where raw material producers and fabricators occupy distinct competitive layers. Three European glass fiber roving suppliers dominate input supply, concentrating pricing power at the compound production stage. Strategic archetypes separate captive compounders serving single OEMs from independent molders qualifying across multiple platforms. Competitive moves center on backward integration into fiber processing and geographic expansion toward Scottish wind-to-automotive workforce pools.
Among Belgian-headquartered chemical conglomerates, Solvay Group exemplifies the platform-integrator archetype with composite material systems spanning automotive and aerospace qualification. Owens Corning and 3B Fiberglass occupy upstream positions as fiber producers supplying UK compounders with standardized roving specifications. SAERTEX represents the fabric architecture specialist tier, with multiaxial reinforcement know-how transferable between wind energy and automotive structural applications. These three anchors illustrate how competitive positioning stratifies across raw material production, intermediate fabric processing, and finished component molding stages.
| Leading Market Players |
|---|
| Solvay Group |
| Owens Corning |
| 3B Fiberglass |
| SAERTEX |
| Veplas Group |
| Saint-Gobain |
| Toray Industries |
| SGL Carbon |
| Teijin Limited |
| Others |
Value Network & Pricing Analysis
The M6 corridor freight network ties Midlands molders to European glass fiber roving suppliers, with logistics cost volatility feeding directly into compound pricing tiers and buyer procurement leverage across volume tiers.
Pricing Analysis
Industrial OEM buyers anchor contract-based long-term offtake structures that stratify across certification grade and volume scale. Three-tier pricing separates UN ECE crash-certified structural molders from standard interior component suppliers and commodity Sheet Molding Compound vendors. Price erosion runs through SMC bumper beam programs where steel stamping retains cost-per-part advantages; battery enclosure specialists face least price sensitivity due to platform qualification lock-in.
Supply Chain Analysis
Belgian, German, and French compounders hold dominant European glass fiber roving capacity feeding UK molders. Raw material dependencies center on silica-based roving, thermoset polyester resin, and fire-retardant phenolic additives. Single-source vulnerability concentrates in three European fiber producers exposing UK compounders to allocation risk during EV demand surges. Distribution runs through Thames Freeport warehousing clusters serving just-in-sequence delivery to Midlands assembly lines.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
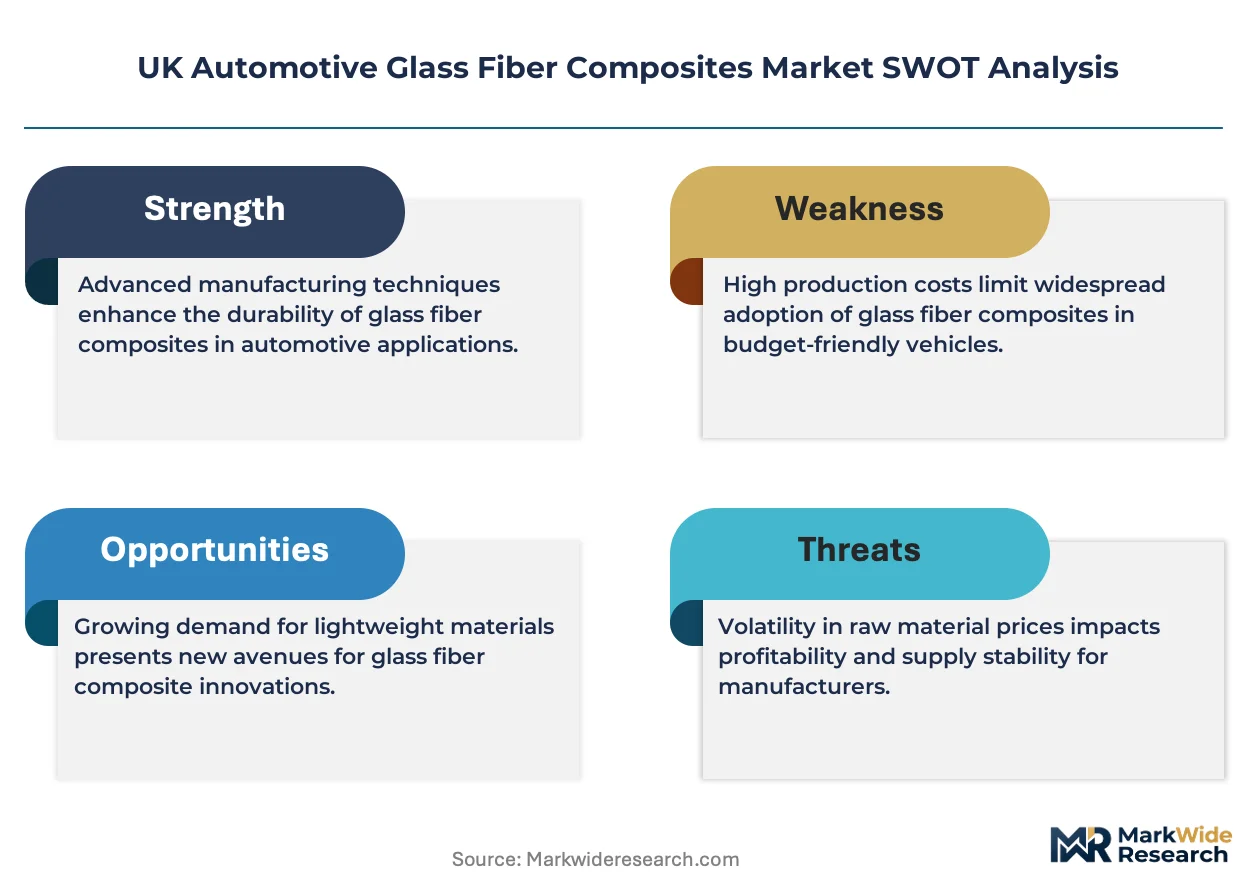
Carbon fiber substitution threatens glass fiber composites in premium EV battery enclosures, forcing incumbents to defend structural cost-performance positioning against hybrid material encroachment.
For Market Incumbents: Harden backward integration into fiber processing to secure roving allocation during demand surges. Expand Midlands molding capacity adjacent to JLR and Stellantis assembly corridors. Lock in UN ECE certification pipelines to extend platform qualification moats against emerging thermoplastic composite entrants. For New Entrants and Emerging Players: Build out Scotland greenfield sites leveraging offshore wind-trained workforces for large structural vacuum infusion. Target underpenetrated Northern England commercial vehicle cab assemblies where corrosion resistance drives material substitution. Lead with thermoplastic-thermoset hybrid offerings aligned with extended producer responsibility mandates. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors molders with captive simulation capabilities and direct OEM procurement relationships. Long-term viability hinges on EV platform content-per-vehicle expansion rather than legacy ICE penetration. Watch battery enclosure specification rates at JLR Coventry as inflection signal for structural composite demand acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Fiber Processing | Owens Corning and 3B Fiberglass roving allocation security buffers UK compounders against European supply shocks. |
| UN ECE Crash Certification Investment | Vehicle Certification Agency validation pipelines compress competitive entry timelines for structural EV battery tray programs. |
| Thermoplastic-Thermoset Hybrid Scale-Up | Recyclable structural components align with Department for Transport decarbonisation mandates and producer responsibility frameworks. |
| Scotland Greenfield Molding Expansion | Glasgow and Aberdeen wind energy workforces transfer vacuum infusion skills into automotive structural applications. |
| Direct OEM Procurement Relationship | Nissan Sunderland and Stellantis Ellesmere Port channel compression displaces tier-two compound distributors. |
Research Methodology
Cross-validation between OEM platform engineering disclosures and tier supplier production data anchors the qualitative findings. Primary interviews with Tier 1 procurement leads, composite molder operations directors, Vehicle Certification Agency technical assessors, and resin compounder R&D heads combined with secondary validation from Department for Transport policy filings, UN ECE regulatory databases, and Midlands automotive cluster trade records. Bottom-up volume modeling triangulates against top-down OEM production forecasts.
Calibration against historical substitution elasticities and EV platform launch cadences shapes the analytical framework across the analysis window. Segmentation dimensions span material form, vehicle propulsion architecture, functional application, and regional production cluster. CAGRs derive from fitted adoption curves for continuous fiber composite penetration in battery enclosures and SMC displacement rates in closure panels. Industry-specific inputs include glass fiber content-per-vehicle trajectories and UN ECE certification cycle durations.
Stress conditions across European roving supply allocation, UK Carbon Border Adjustment Mechanism implementation timing, and carbon fiber hybrid substitution rates were modeled; outcomes outside those bands fall beyond the analytical envelope. Quarterly review of JLR and Stellantis platform engineering specifications is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Vehicle Components
Fuel Sensor Market
Vehicle Components
Electric Wheelchair Market
Vehicle Components
China Forklift Battery Market
Vehicle Components
Japan Automotive Pneumatic Actuators Market
Vehicle Components
Steering Tie Rod Market
Vehicle Components
Thrust Bearings Market
Vehicle Components
Rail Wheel and Axle Market
Vehicle Components
Electric Vehicles Component Market
Vehicle Components
Vehicle Trailer Hitch Market
Vehicle Components
Mining Vehicle AC Kits Market
Vehicle Components
Automotive Powertrain Sensors Market
Vehicle Components
Global Automotive Rain, Light, Humidity Sensor Market
Vehicle Components
Gas-Powered Chainsaw Market
Vehicle Components
Automotive Battery Terminals Market
Vehicle Components
Russia Automotive Composites Market
Vehicle Components
Suction Road Sweeper Market