
 Off-The-Road (OTR) Tire Market | 2026-2036
Off-The-Road (OTR) Tire Market Size, Share, and Industry Trends Forecast 2026-2036
Off-The-Road (OTR) Tire Market Outlook
Multi-source procurement for raw carbon black and natural rubber is shifting toward captive supply arrangements among tier-one manufacturers. Bridgestone Corporation leverages backward integration into synthetic rubber facilities across Southeast Asia to insulate margin pools from commodity swings. Michelin anchors its competitive stance through sustained R&D intensity in radial-cord metallurgy for ultra-class mining applications. Titan International specializes in narrow-niche agricultural flotation tires, occupying a defensible position in North American row-crop equipment.
Off-the-road tires are engineered pneumatic or solid structures built with reinforced carcass plies, specialized tread compounds, and bead bundles designed to withstand extreme load indices, puncture hazards, and uneven terrain across mining, construction, and agricultural duty cycles. Radial constructions now dominate premium fleet specifications due to superior heat dissipation and footprint uniformity under sustained loads. Bias configurations retain structural relevance in emerging-market construction fleets where acquisition cost sensitivity outweighs total-cost-of-ownership metrics. Mining applications command the deepest margin pools, with tire management contracts increasingly bundled with telematics-enabled wear monitoring.
EPA emissions thresholds for non-road equipment are tightening compliance burdens on OE tire fitments, while REACH restrictions on aromatic oils in tread compounds are forcing reformulation across European supply chains. Brazil's ANVISA and the country's national environmental regulator are jointly scrutinizing tire durability standards for Amazon basin agricultural mechanization. Stakeholders must monitor how carbon-border adjustment mechanisms and regional content requirements reshape sourcing economics for natural rubber and steel cord.
Market Dynamics
Radial-cord metallurgy is displacing bias-ply dominance in ultra-class mining fleets as heat dissipation under sustained loads becomes the decisive specification criterion for procurement teams.
Growth Catalysts
- EU F-Gas Regulation:Synthetic rubber producers are accelerating reformulation investments to meet fluorinated gas phase-down schedules, tightening supply discipline among compliant manufacturers.
- Soybean mechanization:Brazil's agricultural heartland is expanding flotation tire specifications as row-crop equipment scales toward 24-hour harvest windows.
- Telematics integration:Mining tire management contracts now bundle wear-monitoring sensors with replacement scheduling, embedding suppliers deeper into fleet operations.
Market Restraints
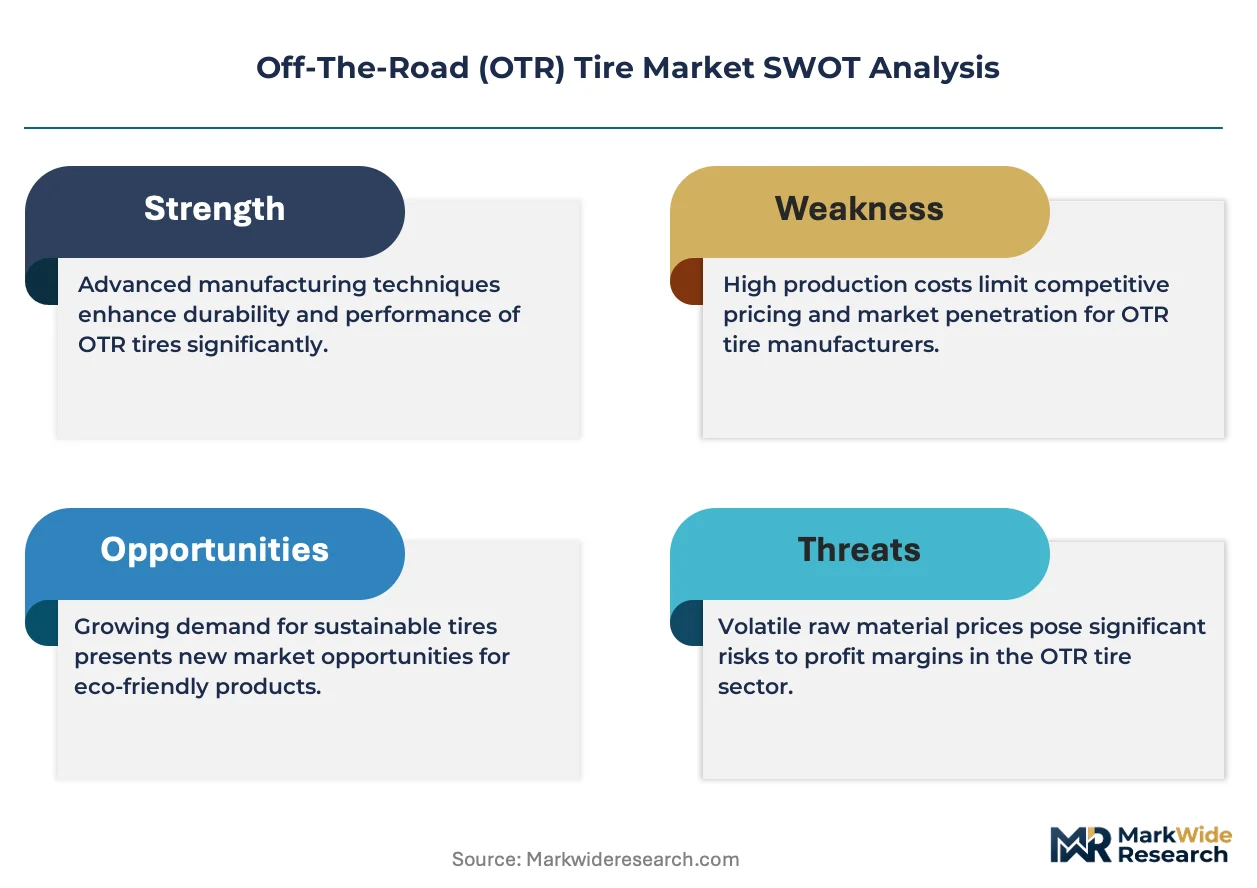
- Natural rubber concentration:Southeast Asian latex supply channels face climate volatility and labor migration constraints that destabilize input cost forecasting.
- REACH aromatic oil restrictions:European tread compound reformulation is extending R&D cycles and raising certification burdens for export-oriented manufacturers.
- Steel cord supply:Arc furnace capacity limitations in specific producing regions are elongating lead times for radial tire reinforcement materials.
Strategic Opportunities
- Amazon basin mechanization:ANVISA durability scrutiny is creating first-mover advantage for suppliers meeting Brazil's emerging tire lifespan standards.
- Solid tire conversion:Construction waste handling and port terminal equipment are pivoting toward puncture-proof solid constructions in high-debris environments.
- Carbon border adjustments:EU CBAM implementation is incentivizing regional carbon black production investments to preserve margin structures on European-bound shipments.
Industry Challenges
- Radial metallurgy expertise:Mining-grade cord-wire fatigue analysis requires specialized engineering talent that concentrates among a narrow supplier base.
- Legacy fleet retrofit:Bias-ply wheel rim incompatibility with radial specifications is compressing replacement decisions into expensive full-wheel assemblies.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Off-The-Road (OTR) Tire Market |
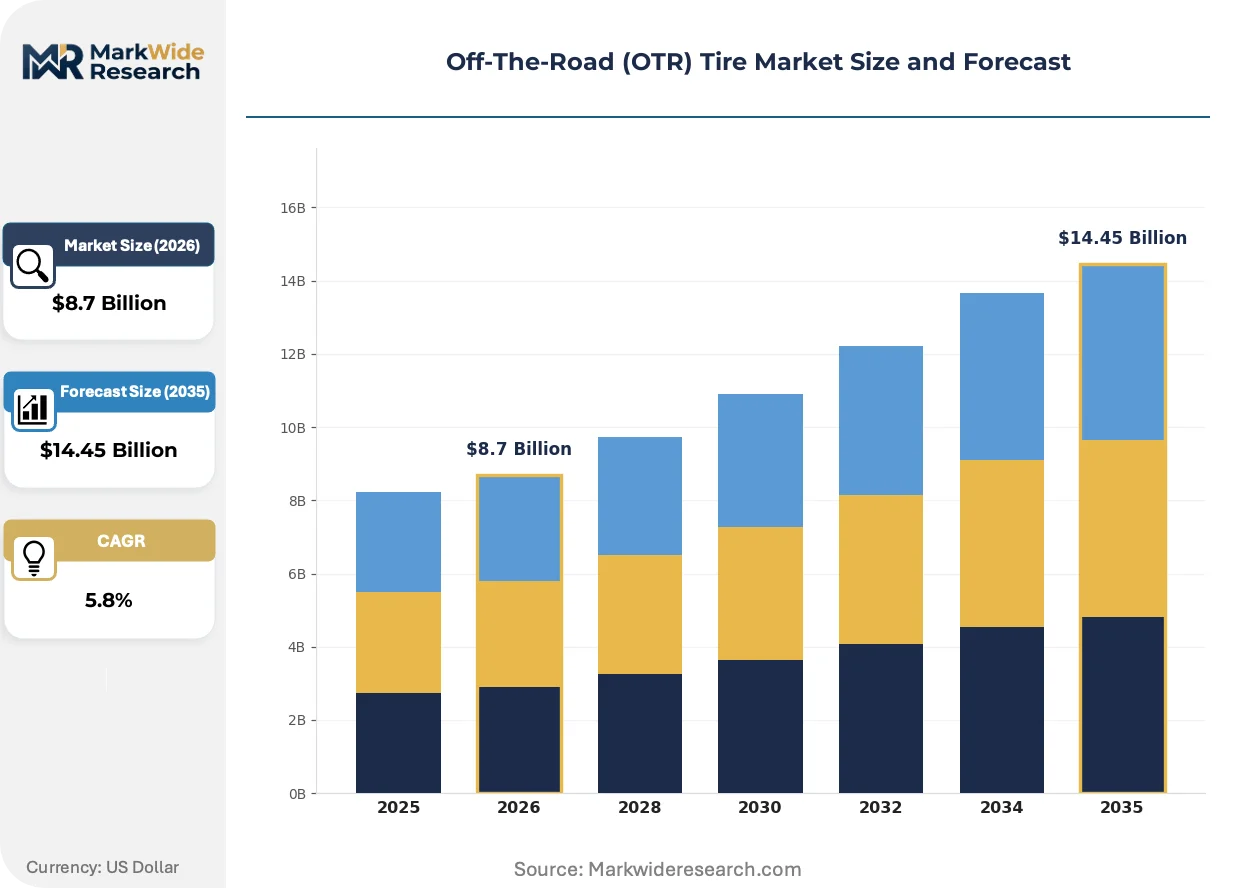
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $14.45 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Radial, Bias, Solid, Retreaded Application: Construction, Mining, Agriculture, Industrial End User: Fleet Operators, Equipment Rental, Mining Companies, Agricultural Firms Distribution Channel: Direct Sales, Online Retail, Dealers, Distributors |
| Companies Covered | Bridgestone Corporation, Continental AG, Michelin, The Goodyear Tire & Rubber Company, Yokohama Rubber Company, Pirelli, Nokian Tyres, Titan International, Hankook Tire & Technology, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Off-The-Road (OTR) Tire Market Strategic Shifts
Active sensor layers embedded within tire carcasses are transforming static rubber products into data-generating assets, compressing the traditional boundary between equipment OEMs and aftermarket service providers.
Intelligent tire systems integrating pressure, temperature, and strain gauges directly into sidewall plies are rewriting how mining operators schedule maintenance intervals. Ultra-class haul truck fleets in Australia and Chile are specifying these sensor-embedded radials as standard equipment. The technology is compressing unplanned downtime costs while shifting supplier relationships toward continuous monitoring subscriptions.
REACH restrictions on polycyclic aromatic hydrocarbons in tread oils are forcing compound reformulation across European supply chains. Tire manufacturers are substituting bio-based process oils and retesting wear characteristics under accelerated laboratory protocols. Agricultural tire exports to EU markets face the steepest compliance ramps, with Brazilian producers investing in European-certified blending facilities.
Fleet procurement teams are unbundling tire supply from integrated maintenance contracts, creating direct purchasing relationships with manufacturers. Mining operators in Australia are leading this disintermediation, negotiating volume commitments that bypass traditional distributor markups. The pattern is compressing channel margins while rewarding suppliers with captive service networks and rapid response capabilities.
Off-The-Road (OTR) Tire Market Segmentation
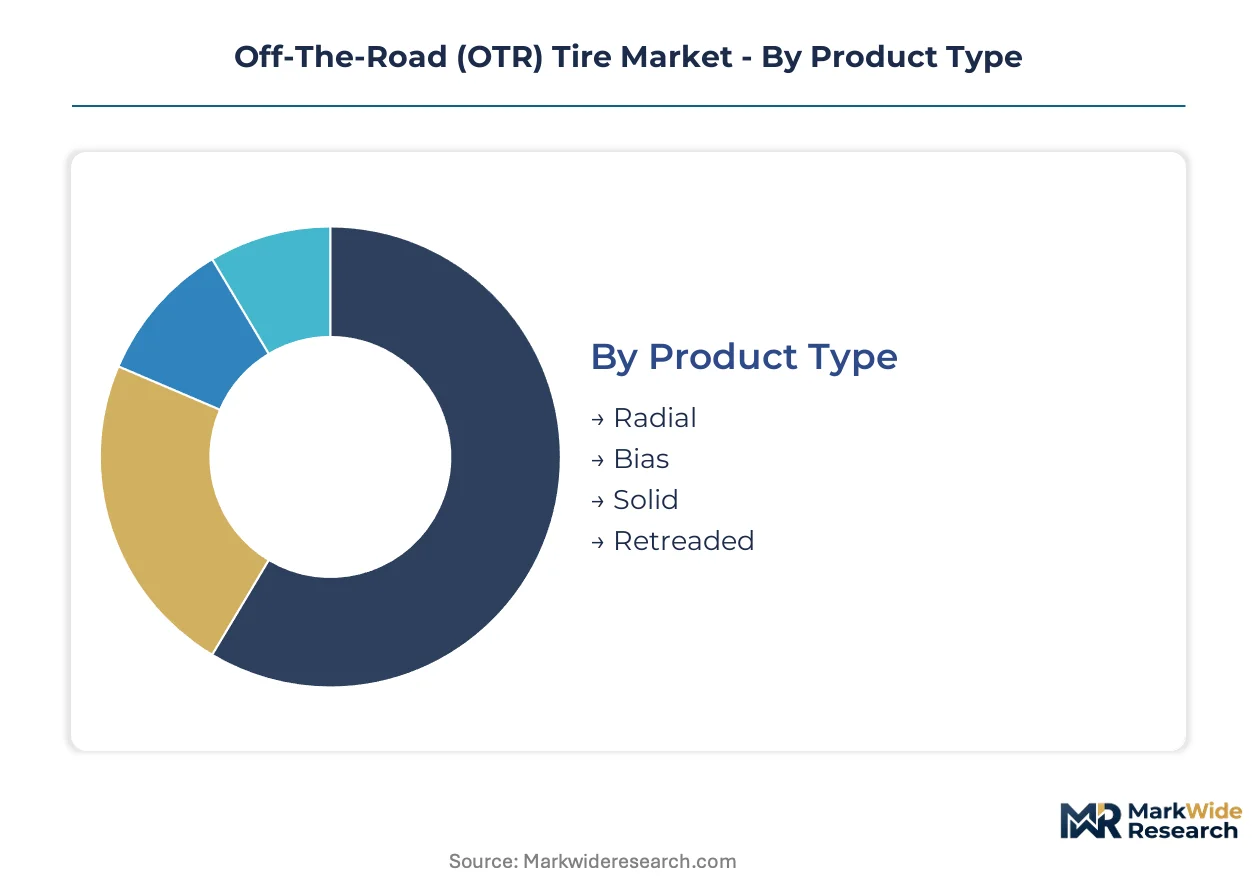
OTR tire procurement patterns diverge sharply across duty cycles and ownership models. Fleet specifications for ultra-class mining trucks bear little resemblance to rental yard acquisition criteria for construction equipment. Understanding these segment boundaries clarifies where margin pools concentrate and which technical specifications command premium positioning.
Product Type:
Cost tier separates buyers in this category, with total-cost-of-ownership calculations diverging radically between premium radial adopters and price-sensitive bias-ply purchasers.
- Radial:Steel-cord carcass construction delivers superior heat dissipation and footprint uniformity under sustained loads. Australian and Chilean mining fleets specify these as standard for ultra-class haul trucks, with procurement teams prioritizing tire management contracts bundled with telematics-enabled wear monitoring.
- Bias:Cross-ply nylon or polyester cord arrangements retain structural relevance where acquisition cost sensitivity outweighs lifecycle economics. Emerging-market construction fleets in Brazil and India continue specifying these configurations for medium-duty earthmoving equipment.
- Solid:Puncture-proof rubber compounds molded onto metal bases eliminate inflation failure modes entirely. Port terminal equipment and construction waste handling operations specify these for high-debris environments.
- Retreaded:Casing recovery processes extend service life through renewed tread application. Cost-conscious fleet operators in agricultural and industrial segments utilize these for secondary-duty equipment.
Volume sits with Bias configurations; growth tilts toward Radial specifications.
Application:
Margin concentration varies by application, with mining duty cycles generating the deepest profit pools through technical complexity and service bundling.
- Mining:Ultra-class haul truck specifications demand specialized radial-cord metallurgy and heat-resistant tread compounds. Australian operators lead adoption of sensor-embedded tires with integrated pressure and temperature monitoring.
- Agriculture:Flotation tire designs distribute machinery weight across broad footprints to minimize soil compaction. Brazil's soybean mechanization drives specification expansion for 24-hour harvest window equipment.
- Construction:Bias-ply dominance persists in emerging markets where equipment utilization rates justify lower upfront investment. EPA emissions thresholds for non-road equipment tighten compliance burdens on OE fitments.
- Industrial:Forklift and port handling equipment specifications split between pneumatic and solid constructions based on debris exposure and load cycling intensity.
Mining commands the steepest pricing; Agriculture expands most quickly.
End User:
Procurement sophistication separates this category, with direct manufacturer relationships replacing distributor channels among large-scale operators.
- Mining Companies:Integrated tire management contracts bundle supply with predictive maintenance and rapid response service networks. Australian operators are disintermediating traditional distributors through volume commitments.
- Fleet Operators:Standardized specifications across equipment classes enable consolidated purchasing power and inventory reduction.
- Equipment Rental:Acquisition cost minimization prioritizes retreaded and bias-ply options for short-duty-cycle deployment.
- Agricultural Firms:Seasonal demand concentration creates procurement timing challenges, with Brazilian producers investing in European-certified blending facilities to meet REACH-compliant export requirements.
Volume sits with Fleet Operators; growth tilts toward Mining Companies.
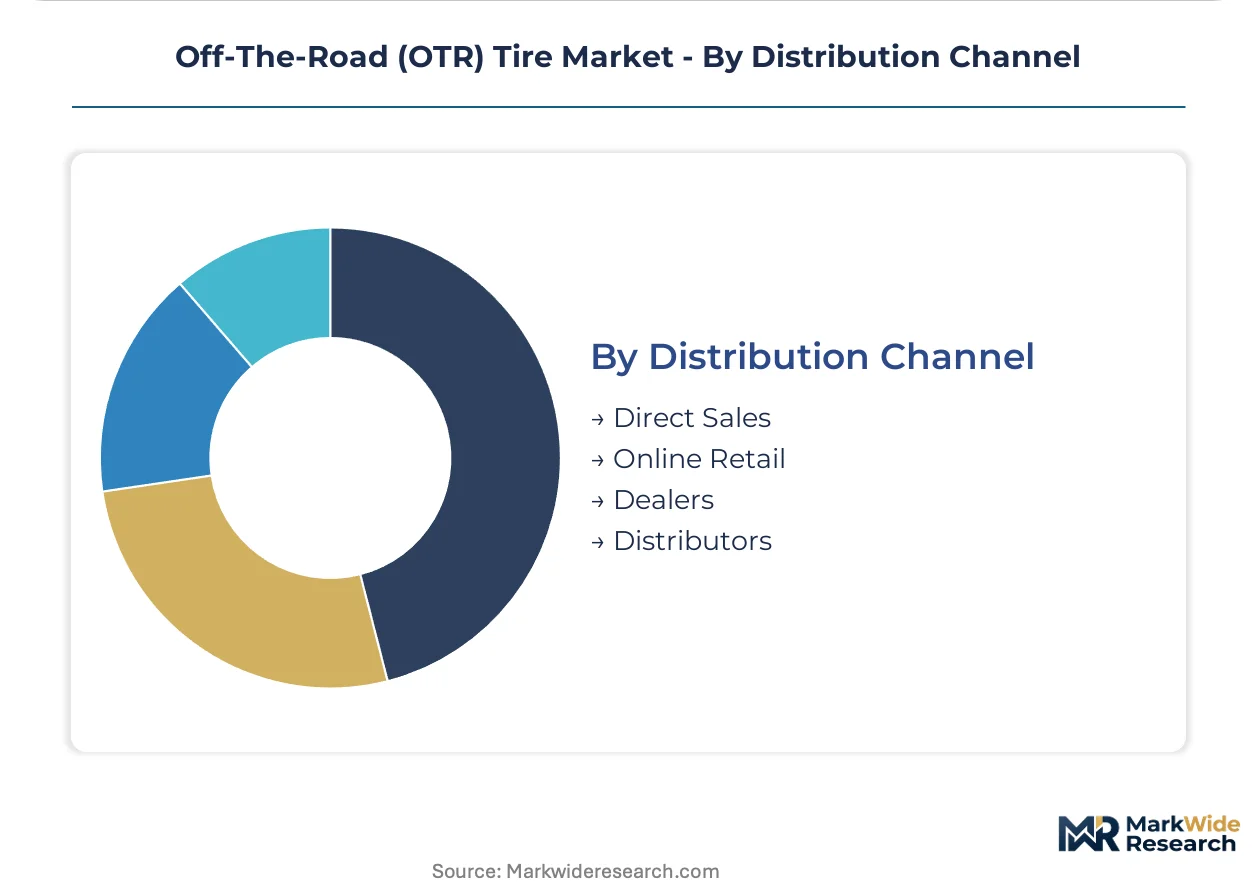
Distribution Channel:
Channel economics are restructuring as direct procurement compresses traditional markups and embedded service capabilities become the decisive competitive factor.
- Direct Sales:Manufacturer-to-operator relationships eliminate distributor margins and enable customized tire management subscriptions. Australian mining fleets lead this disintermediation pattern.
- Dealers:Local service networks and rapid response capabilities defend position against direct channel encroachment in remote mining territories.
- Distributors:Inventory pooling and credit extension remain relevant for mid-scale construction and agricultural buyers lacking direct procurement scale.
- Online Retail:Specification standardization in industrial and replacement segments enables digital transaction models with limited technical consultation requirements.
Volume sits with Dealers; growth tilts toward Direct Sales.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Natural rubber plantations across Southeast Asia anchor supply-side geography for OTR tire manufacturing, while demand concentrates in mining belts and agricultural mechanization zones across five distinct national markets.
Australia
Ultra-class haul truck fleets in the Pilbara iron ore region specify radial-cord metallurgy for heat dissipation under sustained loads. TGA durability standards govern tire certification for heavy mining equipment. Perth-based procurement teams negotiate direct manufacturer relationships that bypass traditional distributor channels.
Brazil
Soybean mechanization across Mato Grosso and Goiás drives flotation tire specifications for 24-hour harvest windows. ANVISA and IBAMA jointly scrutinize tire lifespan standards for Amazon basin agricultural equipment. São Paulo-state manufacturers invest in European-certified blending facilities to meet REACH-compliant export requirements.
Chile
Copper mining operations in the Atacama Desert extend fleet replacement cycles for ultra-class haul trucks. The national mining regulator enforces equipment safety protocols affecting tire procurement specifications. Antofagasta and Calama mining clusters specify sensor-embedded radials with integrated telematics monitoring.
Germany
Construction equipment OEMs in Baden-Württemberg and Bavaria face REACH restrictions on aromatic oils in tread compound formulations. KBA type-approval requirements extend certification cycles for export-oriented manufacturers. Stuttgart and Munich industrial corridors concentrate R&D facilities for radial-cord metallurgy advancement.
United States
EPA emissions thresholds for non-road equipment tighten compliance burdens on OE tire fitments across construction and mining fleets. The agency's Tier 4 Final standards influence equipment specifications downstream to tire procurement. Texas and Arizona oil sands operations specify heat-resistant compounds for high-temperature duty cycles.
Off-The-Road (OTR) Tire Market Competitive Environment
Global majors compete with regional champions across technical specification depth and service network density. The vendor base stratifies into three tiers: integrated rubber-chemical producers, specialized mining-grade metallurgists, and agricultural flotation specialists. Consolidation pressures concentrate among mid-scale manufacturers lacking captive raw material supply. Dominant competitive moves include backward integration into synthetic rubber facilities and telematics-enabled service bundling.
Within the integrated producer tier, Bridgestone Corporation and Continental AG exemplify archetypes combining chemical feedstock control with radial-cord engineering depth. Michelin occupies a position emphasizing sustained R&D intensity for ultra-class mining applications. Among agricultural specialists, Titan International represents the narrow-niche flotation segment serving North American row-crop equipment.
| Leading Market Players |
|---|
| Bridgestone Corporation |
| Continental AG |
| Michelin |
| The Goodyear Tire & Rubber Company |
| Yokohama Rubber Company |
| Pirelli |
| Nokian Tyres |
| Titan International |
| Hankook Tire & Technology |
| Others |
Value Chain & Pricing Dynamics
Australian mining procurement teams negotiating direct manufacturer relationships command substantial volume leverage, compressing distributor markups and shifting pricing power toward suppliers with embedded service capabilities and rapid response networks.
Pricing Analysis
Warranty and tire management contract bundling separates premium radial specifications from unbundled bias-ply transactions in emerging markets. Three-tier pricing structure across premium, standard, and economy levels reflects radial-cord metallurgy grade, telematics integration depth, and geographic service density. Cost compression in bias-ply tiers is intensifying because Brazilian and Indian construction fleets prioritize acquisition cost over lifecycle economics. Equipment rental yards exhibit highest price sensitivity; ultra-class mining operators demonstrate lowest sensitivity due to unplanned downtime cost exposure.
Supply Chain Analysis
Dual-sourcing mandates from tier-one manufacturers now require qualified suppliers across Thailand, Indonesia, and Vietnam for natural rubber feedstock. Raw material dependencies center on Southeast Asian latex plantations, Chinese steel cord production, and Gulf Coast petrochemical derivatives for synthetic rubber. Single-source vulnerability concentrates in radial metallurgy engineering talent pools. Distribution runs through manufacturer-direct channels for mining fleets and dealer networks for agricultural and construction segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market operates under supply-constrained conditions where arc furnace capacity limitations for steel cord reinforcement prop pricing firmness across radial specifications.
For Market Incumbents: Deepen backward integration into synthetic rubber facilities across Southeast Asia to insulate margin pools from EU F-Gas Regulation compliance costs and commodity volatility. Anchor competitive position through sustained R&D intensity in sensor-embedded radial systems for Australian and Chilean mining fleets. Fortify against distributor disintermediation by embedding telematics-enabled wear monitoring into tire management subscriptions. For New Entrants and Emerging Players: Launch via direct sales relationships with mid-scale Brazilian agricultural firms seeking REACH-compliant flotation tire exports to European markets. Target solid tire conversion opportunities in port terminal equipment and construction waste handling where puncture-proof specifications displace pneumatic alternatives. Penetrate through ANVISA-certified durability standards for Amazon basin mechanization. For Investors and Strategic Acquirers: Distressed-cycle entries favor agricultural flotation specialists with European-certified blending facilities in São Paulo state. Long-term viability hinges on captive natural rubber supply arrangements and radial metallurgy engineering depth. Watch steel cord lead time elongation as the inflection signal for pricing power shifts toward integrated manufacturers.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Synthetic Rubber | Captive supply from Southeast Asian petrochemical corridors insulates margin pools from EU F-Gas compliance costs. |
| Telematics-Enabled Service Bundling | Sensor-embedded radials with continuous monitoring subscriptions embed suppliers deeper into Australian mining fleet operations. |
| REACH-Compliant Blending Facility Investment | São Paulo-state certification enables Brazilian agricultural tire exports to European markets facing aromatic oil restrictions. |
| Radial-Cord Metallurgy R&D Expansion | Stuttgart and Munich industrial corridors concentrate specialized engineering talent for ultra-class mining heat dissipation specifications. |
| Solid Tire Manufacturing Scale-Up | Puncture-proof constructions capture port terminal and construction waste handling demand in high-debris environments. |
Study Parameters
Document review covered trade customs data, SEC filings from tire manufacturers, ECHA REACH registration databases, and mining fleet procurement disclosures, complemented by interviews with procurement directors at Australian iron ore operators, maintenance heads at Chilean copper mines, and agricultural equipment dealers across Brazil's Mato Grosso region. Secondary validation drew from ANVISA certification records, TGA durability standards documentation, and EU F-Gas Regulation compliance filings. Bottom-up segment sizing triangulated against top-down macroeconomic indicators across the analysis window.
Cross-referencing historical replacement cycle patterns with expert panel input on telematics adoption curves shaped the analytical framework across product type, application, and distribution channel dimensions. CAGRs were derived from regression analysis of fleet expansion rates and equipment utilization intensity. Forecast inputs incorporated EPA Tier 4 Final compliance timelines for non-road equipment and soybean mechanization trajectories in Brazil's agricultural heartland.
Natural rubber price volatility, steel cord supply disruptions, and regulatory phase-in schedule delays are the dominant revision risks to modeled outcomes. Deviation in Southeast Asian latex plantation output would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Tires and Wheels
Green Tires Market
Tires and Wheels
Forestry Equipment Tire Market
Tires and Wheels
Global Electric Vehicle Tire Market
Tires and Wheels
Automotive Wheel Cap Market
Tires and Wheels
Bicycle Rim Market
Tires and Wheels
Asia Pacific Two Wheeler Tire Market
Tires and Wheels
Truck and Bus Tires Market
Tires and Wheels
Bias Tire Market
Tires and Wheels
Global Off-Highway Tire Market
Tires and Wheels
Continuous Track Wheels Market
Tires and Wheels
North Commercial Vehicle Tire Pressure Monitoring Systems Market
Tires and Wheels
Automotive Steel Wheels Market
Tires and Wheels
Construction Machinery Tires Market
Tires and Wheels
Rail Road Wheels Market
Tires and Wheels
Automotive Racing Slicks Tire Market
Tires and Wheels
Russia OTR Tire Market