
 Solid Tire Market | 2026-2036
Solid Tire Market Size, Share, and Industry Trends Forecast 2026-2036
Solid Tire Market Analysis
China's Pearl River Delta manufacturing belt is narrowing the cost-performance gap between Asian and Western solid tire producers. Continental AG leverages captive rubber compounding facilities across its European footprint to sustain margin stability. CAMSO dominates the off-highway segment through specialized tread compounds engineered for extreme surface abrasion. Bridgestone extends its position in material handling through direct OEM supply agreements with forklift manufacturers.
A solid tire is a non-pneumatic wheel assembly constructed from layered rubber compounds, steel bead wires, and reinforced cushioning segments that eliminate air inflation entirely. These structures typically incorporate multi-layer elastomer formulations with Shore A hardness ratings between 60 and 75, manufactured through compression molding or continuous extrusion processes to deliver puncture-proof operation in debris-rich environments. Industrial tires and construction tires anchor current revenue pools, with polyurethane material formulations representing the fastest-expanding segment due to load-bearing efficiency in warehouse handling applications. Mining applications command premium positioning through specialized heat-resistant compounds, while agricultural tires occupy a mature replacement-driven niche with limited OEM penetration.
OSHA workplace safety mandates and EPA emissions standards for material handling equipment shape product certification requirements in the United States, while REACH and RoHS frameworks in Europe restrict hazardous substance content in rubber formulations. China's GB standards and MIIT industrial equipment regulations govern domestic manufacturing quality benchmarks and import compliance protocols. Stakeholders must monitor regulatory divergence between jurisdictions to align product development pipelines with diverging chemical composition and performance testing requirements.
Market Dynamics
Material handling fleets in warehousing and distribution centers are converting to solid tire configurations for uptime reliability, compressing replacement cycles and reshaping manufacturer order patterns. The EU F-Gas Regulation and REACH compliance frameworks are pushing manufacturers toward low-emission curing processes and reduced aromatic oil formulations.
Growth Catalysts
- E-commerce fulfillment infrastructure:China's industrial logistics corridor drives replacement cycles as automated warehouses expand throughput capacity.
- REACH chemical restrictions:European rubber formulation mandates accelerate adoption of low-aromatic oil compounds across export-oriented producers.
- Polyurethane load-bearing efficiency:Warehouse handling applications favor polyurethane material formulations for weight distribution and durability.
Market Restraints
- Natural rubber price volatility:Input cost fluctuations in latex and synthetic rubber feedstocks compress margin predictability for compounders.
- Asian supply concentration:China's Pearl River Delta manufacturing belt concentrates production capacity, creating geographic risk exposure.
- Heat dissipation limits:Solid tire thermal management constraints restrict speed ratings in continuous high-load mining applications.
Strategic Opportunities
- Indian material handling expansion:Underpenetrated warehouse automation creates replacement demand as domestic e-commerce fulfillment scales.
- EU Green Deal procurement mandates:Public sector tire purchasing criteria favor low-emission curing process certifications.
- Sensor-embedded tire convergence:Integration of pressure-monitoring and wear-detection electronics enables predictive maintenance service models.
Industry Challenges
- Compound formulation expertise gap:Shortage of rubber chemists skilled in multi-layer elastomer formulations with Shore A hardness calibration delays product development timelines.
- Dual certification complexity:Parallel OSHA workplace safety and EPA emissions compliance for material handling equipment extends product launch schedules.
- Legacy fleet retrofit friction:Wheel assembly standardization gaps between pneumatic and solid configurations complicate conversion programs for existing forklift deployments.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Solid Tire Market |
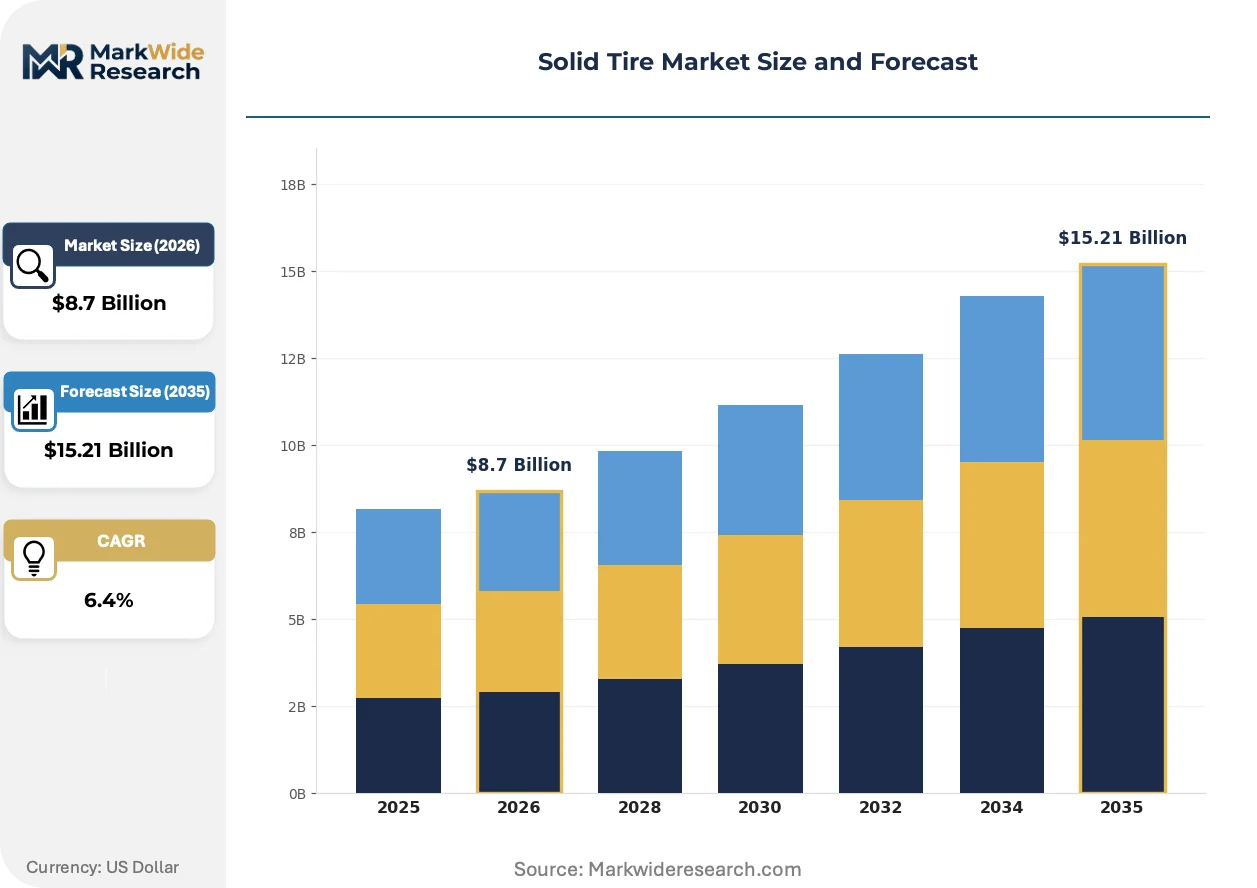
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $15.21 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Industrial Tires, Construction Tires, Agricultural Tires, Motorcycle Tires Material: Rubber, Polyurethane, Foam, Composite End User: Construction Companies, Logistics Providers, Agricultural Operations, OEMs Application: Warehouse Handling, Road Construction, Landscaping, Mining |
| Companies Covered | CAMSO, Continental AG, Bridgestone, Global Rubber Industries, NEXEN TIRE, Setco Solid Tire & Rim Assembly, TY Cushion Tire, Trelleborg AB, Superior Tire & Rubber Corp., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Solid Tire Market Emerging Trajectories
Compression molding automation and continuous extrusion process refinements are collapsing production cycle times while improving hardness consistency across batch runs. Digital thread integration from compound mixing to curing monitoring enables real-time quality deviation detection.
Continuous extrusion with in-line Shore hardness monitoring is collapsing the defect rate variance between batch-molded and continuously produced solid tires. Tier-1 forklift OEMs are adopting these lines for just-in-sequence supply contracts. The technology is collapsing quality assurance labor costs and compressing warranty claim exposure for material handling tire suppliers.
REACH authorization requirements for extender oils containing polycyclic aromatics are forcing reformulation of traditional carbon black masterbatches. German and French compounders have shifted to hydrogenated nitrile rubber alternatives. Mining tire producers face the steepest compliance cost escalation due to heat-resistant compound complexity.
Fleet operators are consolidating supplier relationships around integrated tire-and-service contracts that bundle installation, removal, and recycling. Independent distributors are losing share to direct manufacturer programs in North American warehousing. The shift is most pronounced in automated fulfillment centers where uptime penalties exceed tire procurement costs.
Solid Tire Market Segmentation
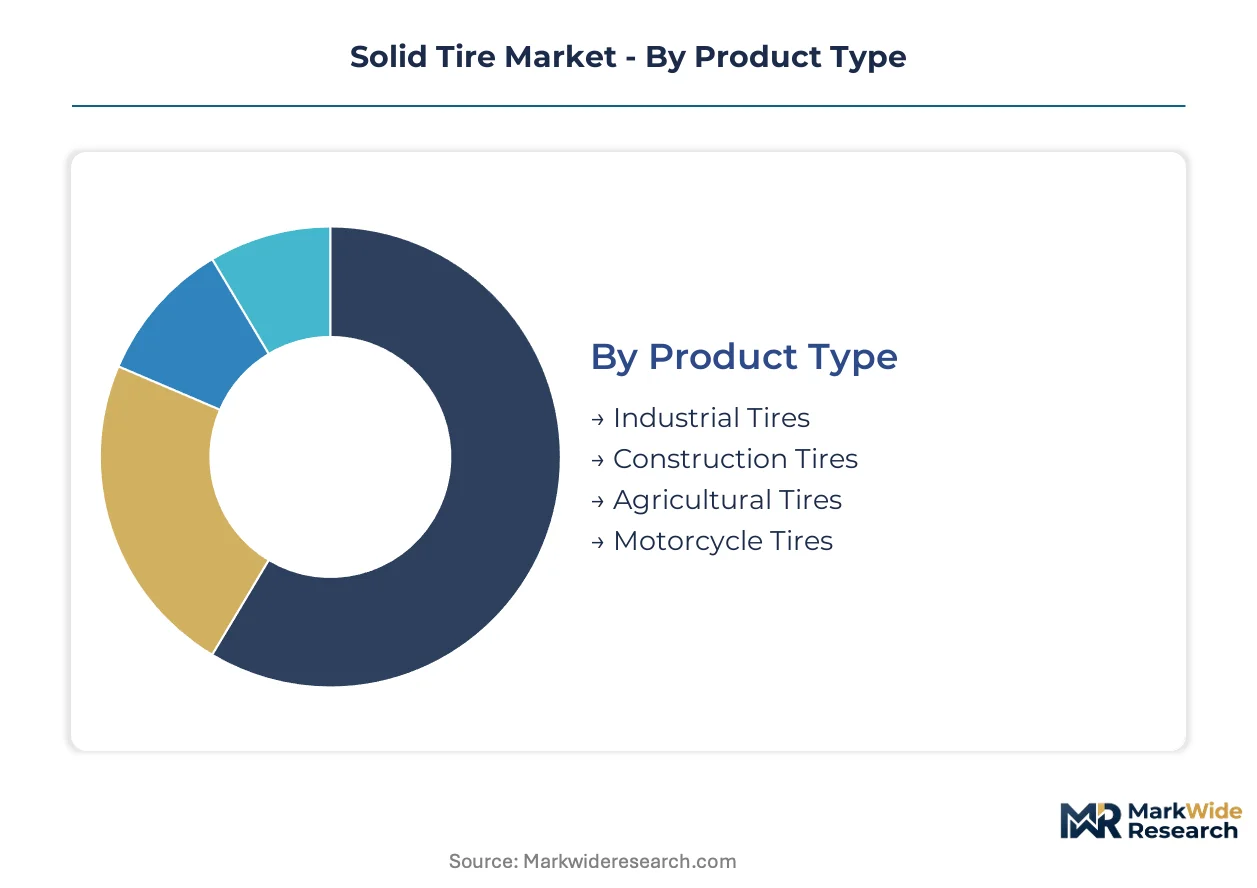
Solid tire procurement patterns diverge sharply across operational environments, with material formulation choices and load-bearing specifications driving distinct supplier relationships. Segmentation clarity enables manufacturers to align compounding investments with specific duty-cycle demands rather than pursuing undifferentiated volume strategies.
Product Type:
Application severity determines product architecture, with duty-cycle intensity dictating compound layering and tread depth specifications.
- Industrial Tires:Multi-layer elastomer constructions with Shore A hardness between 60 and 75 dominate forklift and material handling fleets. China's e-commerce fulfillment corridor compresses replacement cycles as automated warehouses prioritize uptime reliability over per-unit tire cost.
- Construction Tires:Reinforced sidewall designs withstand debris penetration and uneven surface abrasion on job sites. Road infrastructure investment cycles in Germany and France drive OEM attachment rates for compact equipment fleets.
- Agricultural Tires:Lower-durometer compounds reduce soil compaction for field operations. Replacement demand concentrates in Midwest US grain operations with limited OEM penetration.
- Motorcycle Tires:Lightweight solid configurations address urban delivery fleet needs where puncture resistance outweighs ride comfort priorities. Southeast Asian last-mile logistics networks favor these for scooter-based courier services.
Industrial tires hold installed capacity. Construction tires are rotating up the share rankings.
Material:
Cost-performance tradeoffs between raw material inputs reshape competitive positioning across end-use verticals.
- Rubber:Natural and synthetic latex formulations deliver heat resistance for continuous high-load mining applications. REACH aromatic oil restrictions force European compounders toward hydrogenated nitrile alternatives, escalating formulation costs.
- Polyurethane:Castable polymers achieve precise load distribution with weight advantages over rubber equivalents. Warehouse handling applications in China's Pearl River Delta manufacturing belt favor polyurethane for automated guided vehicle fleets.
- Foam:Microcellular structures provide cushioning without inflation vulnerability. Landscaping equipment OEMs specify foam fills for ride-on mowers operating on debris-strewn terrain.
- Composite:Hybrid constructions layer dissimilar materials for specialized performance envelopes. Mining tire producers deploy composites where thermal management constraints restrict pure rubber speed ratings.
Rubber maintains volume leadership. Polyurethane is climbing the fastest on load-bearing efficiency gains.
End User:
Procurement sophistication varies dramatically across customer types, with fleet scale determining service bundling preferences.
- Construction Companies:Project-based purchasing favors regional distributors with rapid field service capabilities. Equipment rental fleets in Texas and Florida consolidate supplier relationships around installation and removal contracts.
- Logistics Providers:Automated fulfillment centers demand predictive maintenance integration and uptime guarantees. Direct manufacturer programs displace independent distributors in North American warehousing.
- Agricultural Operations:Seasonal replacement patterns align with planting and harvest windows. Cooperative buying groups in Iowa and Illinois negotiate volume discounts for fleet standardization.
- OEMs:Forklift manufacturers specify tires at equipment configuration stage, locking in multi-year supply agreements. Just-in-sequence delivery requirements favor suppliers with continuous extrusion capabilities.
Logistics providers drive specification innovation. OEMs are rotating up the share rankings on captive supply agreements.
Application:
Operating environment severity dictates compound formulation priorities and warranty exposure profiles.
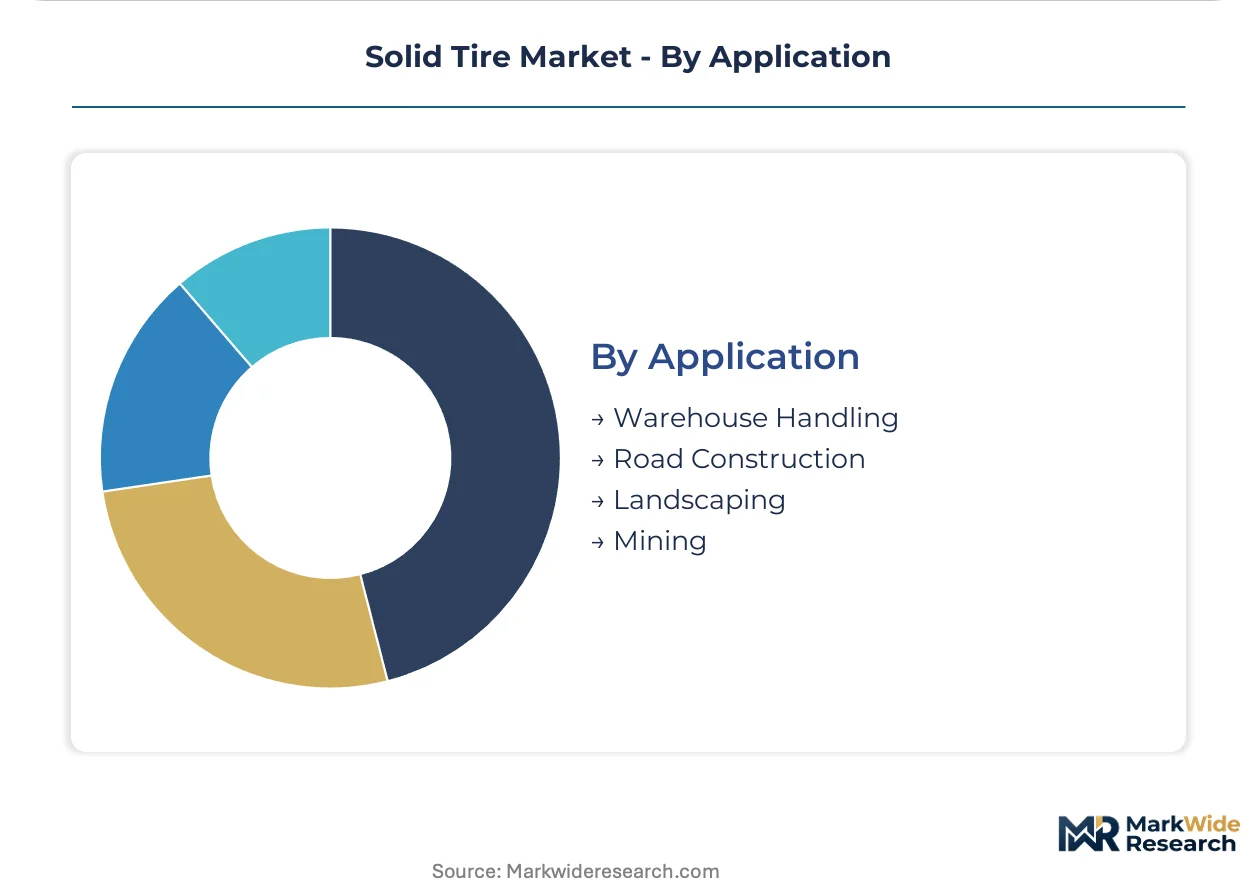
- Warehouse Handling:Smooth tread patterns minimize floor marking while polyurethane cores reduce rolling resistance. Distribution centers in the Netherlands and Belgium specify these for high-bay storage retrieval systems.
- Road Construction:Deep lug designs provide traction on loose aggregate and graded surfaces. German roadbuilding contractors face EU Green Deal procurement mandates favoring low-emission curing process certifications.
- Landscaping:Compact dimensions suit walk-behind and ride-on equipment with limited wheel well clearance. Municipal maintenance fleets in California specify these for drought-resistant turf management.
- Mining:Heat-resistant compounds withstand continuous operation on abrasive haul roads. Australian iron ore operations command premium positioning through specialized tread formulations engineered for extreme surface abrasion.
Warehouse handling holds installed capacity. Mining is rotating up the share rankings on thermal management advances.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
MIIT governs China's GB standards for industrial equipment quality, anchoring the dominant geography where e-commerce fulfillment infrastructure drives solid tire replacement cycles. Germany's REACH framework and the EU F-Gas Regulation reshape compounding requirements across European supply chains. India's warehouse automation expansion creates underpenetrated demand corridors.
China
Automated warehouse throughput expansion in the Pearl River Delta compresses replacement cycles for material handling fleets. MIIT industrial equipment regulations enforce GB standards on domestic manufacturers and import compliance protocols. Shenzhen and Guangzhou distribution centers specify polyurethane-core solid tires for high-bay storage retrieval systems.
Germany
Road infrastructure investment cycles drive OEM attachment rates for compact construction equipment fleets. REACH authorization requirements for polycyclic aromatic extender oils force hydrogenated nitrile rubber reformulation. The Ruhr industrial corridor concentrates rubber compounding facilities serving low-emission curing process mandates.
United States
OSHA workplace safety mandates and EPA emissions standards shape product certification for material handling equipment procurement. Texas and Florida equipment rental fleets consolidate supplier relationships around installation and removal service contracts. Midwest grain operations drive seasonal agricultural tire replacement through cooperative buying groups.
India
Domestic e-commerce fulfillment scale creates replacement demand in underpenetrated warehouse automation corridors. BIS quality benchmarks govern domestic manufacturing standards for industrial tire imports. Maharashtra and Gujarat logistics hubs favor solid tire configurations for uptime reliability in emerging automated distribution networks.
Australia
Iron ore mining operations command premium positioning through heat-resistant compound specifications for extreme surface abrasion. The country's national mining safety regulator enforces thermal management standards for continuous haul road operation. Western Australia's Pilbara region anchors demand for specialized tread formulations engineered for abrasive conditions.
Solid Tire Market Vendor Landscape
Integrated rubber compounders and specialized off-highway tire fabricators split the market into distinct capability tiers. Continental AG leverages captive rubber compounding facilities across its European footprint to sustain margin stability. CAMSO dominates the off-highway segment through specialized tread compounds. Bridgestone extends its position through direct OEM supply agreements. Competitive moves concentrate on backward integration into rubber compounding and continuous extrusion capacity expansion for just-in-sequence delivery contracts.
Among the named players, Continental AG exemplifies the integrated compounder archetype with European manufacturing presence. CAMSO and Bridgestone occupy positions on the specialized performance tier, with the latter anchoring material handling supply relationships. Global Rubber Industries and NEXEN TIRE represent the scale-oriented fabrication segment. Trelleborg AB sits within the premium industrial tire tier, while Setco Solid Tire & Rim Assembly and TY Cushion Tire exemplify regional specialists focused on assembly and cushion technologies respectively.
| Leading Market Players |
|---|
| CAMSO |
| Continental AG |
| Bridgestone |
| Global Rubber Industries |
| NEXEN TIRE |
| Setco Solid Tire & Rim Assembly |
| TY Cushion Tire |
| Trelleborg AB |
| Superior Tire & Rubber Corp. |
| Others |
Supply Flow & Price Mechanics
China's Pearl River Delta rubber compounding concentration feeds margin pools toward forklift OEMs and automated warehouse operators downstream. REACH aromatic oil restrictions and natural rubber price volatility compress compounder margins while pushing pricing power toward integrated manufacturers with captive formulation capabilities.
Pricing Analysis
Asian-produced solid tires trade at a 15-25% discount to European equivalents, though the gap narrows on polyurethane formulations where load-bearing efficiency commands premiums. Three-tier pricing structure across premium heat-resistant mining compounds, standard industrial elastomers, and economy-grade construction tiers dominates the market. Pricing pressure stems from compressed replacement cycles in Chinese e-commerce fulfillment centers where uptime guarantees outweigh per-unit costs. Logistics providers and automated warehouse operators show lowest price sensitivity, while independent equipment rental fleets in Texas and Florida negotiate aggressively on installation-bundled contracts.
Supply Chain Analysis
Contract manufacturing concentrates among Continental AG's captive European compounding network, CAMSO's specialized Quebec facilities, and Bridgestone's integrated Asian plants. Raw material sourcing draws from Thai and Indonesian natural rubber plantations, German hydrogenated nitrile rubber refiners, and Chinese carbon black masterbatch producers. Single-source vulnerability around REACH-compliant extender oils creates regulatory chokepoint risk. Distribution runs through direct manufacturer programs displacing independent distributors in North American warehousing, with just-in-sequence delivery contracts favoring continuous extrusion-capable suppliers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Solid tire demand is accelerating on warehouse automation disruption and EU Green Deal procurement mandates that favor low-emission curing certifications. The market structure rewards backward integration and predictive maintenance service bundling.
For Market Incumbents: Insulate margin stability through captive rubber compounding investments in Germany and Poland to offset REACH formulation cost escalation. Secure multi-year just-in-sequence supply agreements with Tier-1 forklift OEMs before continuous extrusion capacity shortages harden. The threat of sensor-embedded tire convergence from electronics suppliers demands preemptive predictive maintenance platform development. For New Entrants and Emerging Players: Build out polyurethane-core specialization for automated guided vehicle fleets in India's underpenetrated Maharashtra and Gujarat logistics corridors. Target mid-size construction equipment rental fleets in Florida and Texas with rapid field service capabilities that incumbent direct programs underserve. A go-to-market angle bundling installation, removal, and recycling under fixed per-hour uptime contracts bypasses capital-intensive compounding investments. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across sensor-embedded tire development and continuous extrusion automation, favoring scaled compounders over assembly-only specialists. Long-term viability across the analysis window rests on REACH compliance infrastructure and OEM captive supply relationships. Acquisition targets should demonstrate hydrogenated nitrile rubber formulation expertise and Qingdao or Guangdong manufacturing presence. The signal to watch is forklift OEM procurement committee shifts toward predictive maintenance integration requirements.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Rubber Compounding | Captive formulation capabilities insulate Continental AG from REACH aromatic oil cost volatility. |
| Continuous Extrusion Capacity Expansion | CAMSO's automated lines compress quality assurance labor costs for just-in-sequence contracts. |
| Sensor-Embedded Tire Development | Bridgestone's pressure-monitoring integration enables predictive maintenance service revenue streams. |
| Low-Emission Curing Certification | German compounders' EU Green Deal compliance unlocks public sector procurement mandates. |
| Direct Manufacturer Program Consolidation | Trelleborg AB's integrated tire-and-service contracts displace independent distributors in North American warehousing. |
Methodological Framework
Cross-validation between primary interviews with rubber compounders, forklift OEM procurement teams, and warehouse maintenance directors anchors the qualitative findings. Secondary validation draws from MIIT industrial equipment regulations, ECHA REACH authorization databases, customs trade data on natural rubber imports, and SEC filings of listed tire manufacturers. Bottom-up demand modeling across polyurethane, rubber, and composite material segments triangulates against top-down industrial equipment production forecasts.
Calibration against historical replacement cycle data and e-commerce fulfillment infrastructure investment trajectories shapes the analytical framework. Segmentation dimensions include product architecture, material formulation, end-user procurement sophistication, and application severity across the projection horizon. CAGRs derive from elasticity-adjusted demand curves incorporating fleet automation penetration rates and regulatory compliance cost pass-through assumptions. Forecast inputs include Chinese warehouse automation deployment schedules and EU F-Gas Regulation enforcement intensity.
Stress conditions across natural rubber price volatility bands, REACH authorization timeline delays, and warehouse automation capital expenditure cycles were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions on compound formulation substitution rates and OEM supply agreement renewal probabilities. Quarterly review of forklift OEM procurement committee composition and Chinese MIIT industrial equipment regulation updates is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Tires and Wheels
Connected Tire Market
Tires and Wheels
Global OTR Tires Market
Tires and Wheels
Asia Pacific Two Wheeler Tire Market
Tires and Wheels
Trailer Wheel Market
Tires and Wheels
Global Tire Curing Press Machine Market
Tires and Wheels
Automotive Wheel Alignment System Market
Tires and Wheels
Intelligent Tire Market
Tires and Wheels
Global Tire Curing Press Market
Tires and Wheels
Southeast Asian Tire Market
Tires and Wheels
Saudi Arabia Tire Market
Tires and Wheels
Automotive Retread Tires Market
Tires and Wheels
Rolling Stock Wheel Market
Tires and Wheels
Performance Tires Market
Tires and Wheels
Tire Inflating Machine Market
Tires and Wheels
Automotive Tire Analytics Market
Tires and Wheels
Civil Aircraft Tire Market