
 Automotive Steel Wheels Market | 2026-2036
Automotive Steel Wheels Market Size, Share, and Industry Trends Forecast 2026-2036
Automotive Steel Wheels Market Analysis
EPA fuel-economy benchmarks is shifting the cost-of-entry calculus for steel wheel manufacturers serving North American light-truck programs. MAXION Wheels leverages its vertically integrated foundry network across Mexico and the US to sustain cost advantages in heavy-duty segments. Accuride Corporation anchors its position through captive production of wheel-end components in Arkansas and Ohio. thyssenkrupp AG competes on high-strength steel grades that reduce unsprung mass without sacrificing load ratings.
Automotive steel wheels are circular structural components fabricated from hot-rolled steel coils, typically formed through roll-forming or stamping processes and welded at the rim joint, designed to mount tires and support vehicle axle loads. Standard wheels occupy the highest volume share in commercial vehicle fitments where cost sensitivity dominates procurement decisions, while performance wheels command premium positioning in motorsport and off-road applications requiring enhanced bead retention. OEMs represent the most concentrated demand channel, with fleet operators and vehicle assemblers negotiating multi-year supply agreements that lock in specifications and pricing tiers.
The US NHTSA enforces FMVSS No. 120 for tire and rim matching on commercial vehicles, while the EPA's greenhouse gas standards for heavy-duty trucks indirectly shape wheel weight targets through fuel-efficiency mandates. India's BIS certification requirements for automotive wheels create compliance barriers for imports, favoring domestic producers such as Wheels India Limited and Steel Strips Wheels Limited. Stakeholders must monitor evolving alloy-steel formulations and regional carbon-border adjustments that could restructure sourcing economics between integrated mills and independent wheel fabricators.
Market Dynamics
The US NHTSA rollover resistance standards are compressing design cycles as manufacturers recalibrate rim profiles and bead seat geometries to meet stricter strength-to-weight thresholds without sacrificing load ratings.
Growth Catalysts
- EPA fuel-economy benchmarks:Heavy-duty truck OEMs in North America are downsizing wheel mass to comply with greenhouse gas standards, pulling demand for high-strength steel grades.
- Brazil commercial fleet durability requirements:Fleet operators are expanding steel wheel procurement as axle load limits rise and road conditions deteriorate in agricultural corridors.
- Roll-forming process automation:Indian fabricators around Ludhiana are deploying robotic rim welding to cut cycle times and reduce porosity defects in high-volume output.
Market Restraints
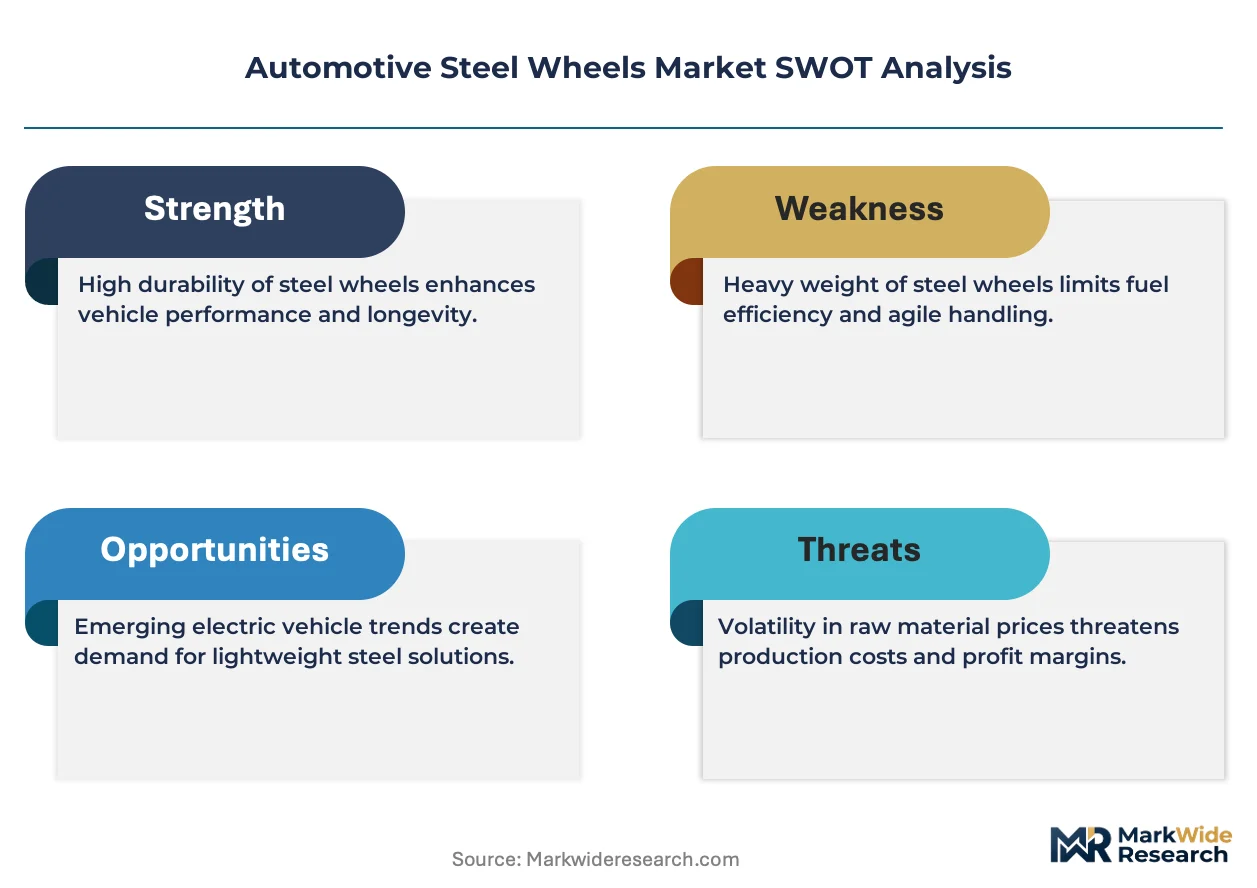
- Hot-rolled steel coil price volatility:Integrated mills in China and India are passing through carbon-border adjustment costs, squeezing margin buffers for independent wheel fabricators.
- Aluminum wheel substitution in light-truck segments:OEMs are specifying cast aluminum for premium trim levels where unsprung mass reduction justifies the cost premium.
- BIS certification timelines:India's mandatory wheel testing protocols create 4-6 month import barriers that favor domestic producers over foreign suppliers.
Strategic Opportunities
- Carbon-border adjustment arbitrage:Mexican producers with captive steel supply can re-export to the US under USMCA rules while avoiding EU carbon tariffs on direct Asian imports.
- Off-road motorsport bead-lock demand:Performance wheel specifications for desert racing and rock-crawling applications command 3-4x standard wheel pricing with limited competition.
- Retreading-compatible rim designs:Commercial fleet operators in India and Brazil are specifying reinforced drop-center profiles that extend rim life across multiple tire cycles.
Industry Challenges
- High-strength steel welding qualification:Fabricators must retrain manual welders on pulsed MIG parameters for advanced grades like DP980 and CP800.
- FMVSS No. 120 testing backlog:Third-party laboratories in the US are reporting 8-12 week queues for commercial vehicle rim certification, delaying program launches.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Automotive Steel Wheels Market |
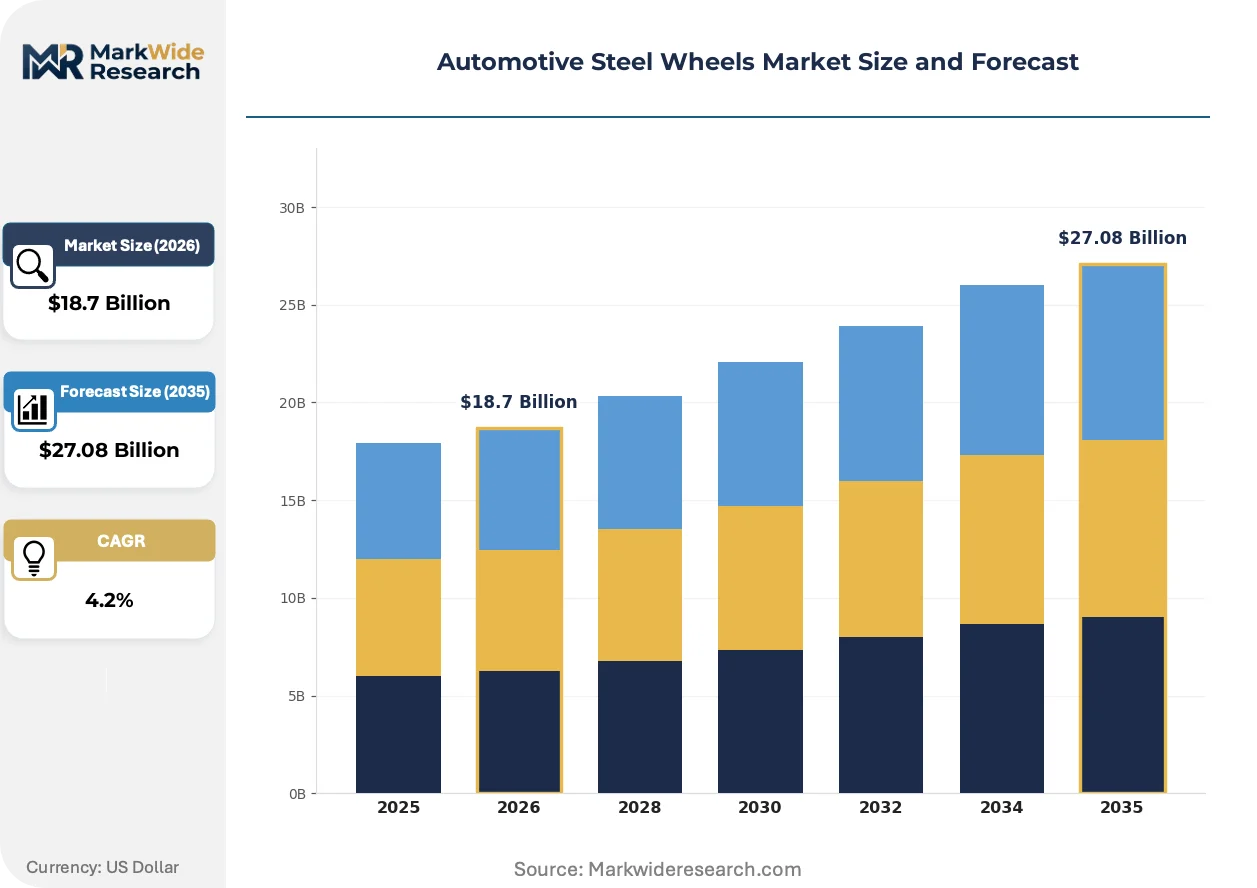
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $27.08 Billion |
| CAGR (2026 – 2036) | 4.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Standard Wheels, Alloy Wheels, Custom Wheels, Performance Wheels End User: OEMs, Aftermarket Providers, Tier-1 Suppliers, Dealerships Installation: Direct Fit, Universal Fit, Lightweight Installation, Heavy-Duty Installation Distribution Channel: Online Retail, Physical Stores, Wholesalers, Auctions |
| Companies Covered | Central Motor Wheel of America, Inc., MAXION Wheels, Accuride Corporation, Wheels India Limited, thyssenkrupp AG, Steel Strips Wheels Limited, Topy Industries Limited, Automotive Wheels Ltd., The Carlstar Group LLC, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Automotive Steel Wheels Market Emerging Trajectories
Material substitution pressures and regulatory mass targets are forcing simultaneous investment in metallurgy, forming processes, and design simulation tools across the supplier base.
Advanced high-strength steel (AHSS) grades with tensile strengths exceeding 980 MPa are consolidating their position in heavy-duty commercial wheel applications. Fleet operators running 80,000-pound gross combination weights are specifying these alloys to reduce rotating mass while maintaining load ratings. The technology is consolidating procurement decisions around mills with certified AHSS production lines, marginalizing smaller fabricators dependent on commodity grades.
The US EPA greenhouse gas standards for heavy-duty trucks are tightening wheel weight targets indirectly through fuel-efficiency mandates. OEMs must now document mass reduction contributions from every axle component in certification filings. Long-haul tractor programs are responding by deleting multi-piece rims in favor of lighter single-piece designs, even at higher piece cost.
Fleet maintenance departments are unbundling wheel-end service from tire contracts and bringing rim inspection in-house. Large operators with 500-plus unit counts are deploying portable rim gauging equipment to catch out-of-round conditions before mounting. This pattern is most visible in Brazil's sugar-ethanol haulage sector where seasonal intensity compresses maintenance windows.
Automotive Steel Wheels Market Segmentation
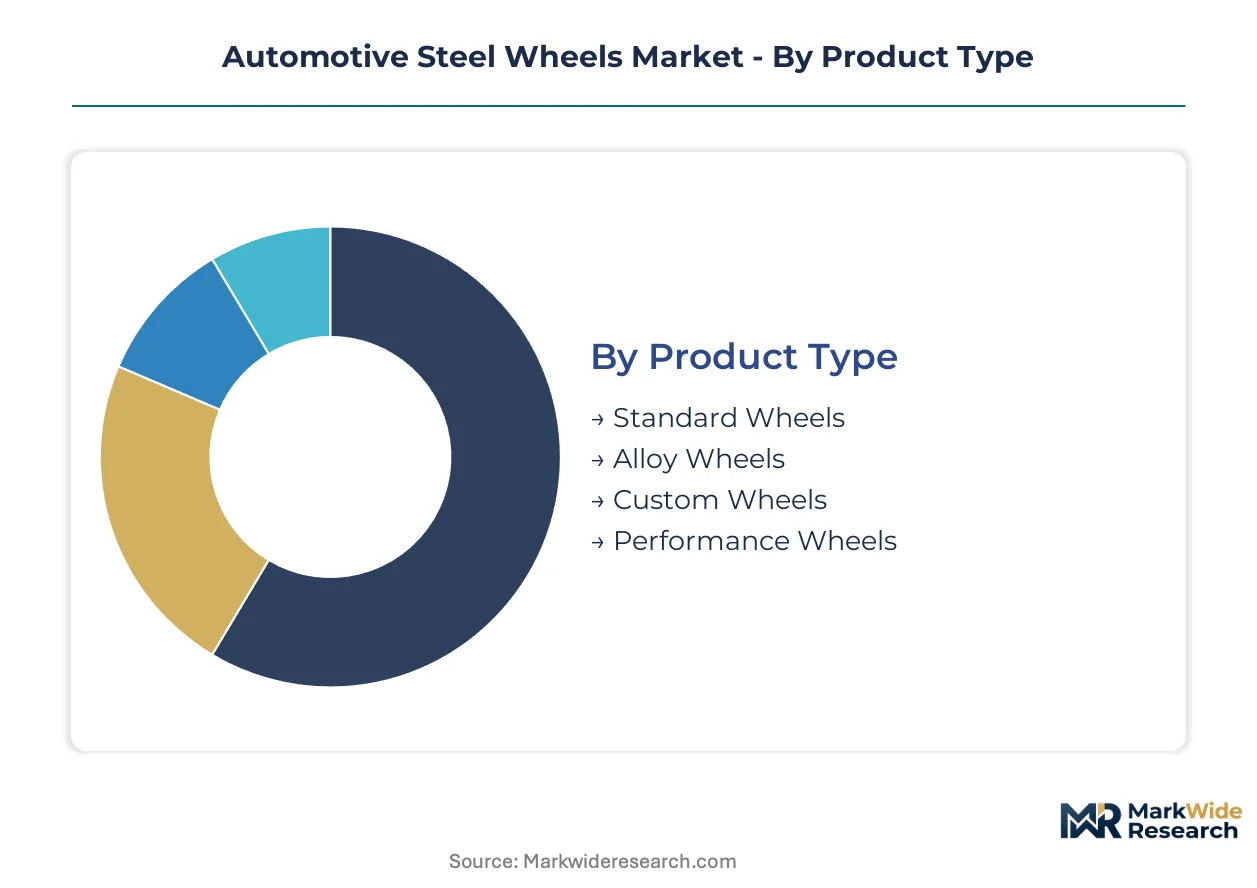
Steel wheel procurement patterns diverge sharply across product tiers and customer channels. Capital allocation, certification requirements, and margin structures vary by segment in ways that reshape supplier competitive position.
Product Type:
Roll-forming equipment and rim welding automation demand the heaviest upfront capital outlays in high-volume segments.
- Standard Wheels:Fabricated from hot-rolled steel coils through stamping and roll-forming processes, these wheels carry load ratings up to 3,750 pounds for commercial vehicle fitments. Fleet operators in Brazil's agricultural corridors are expanding procurement as axle load limits rise and road surfaces deteriorate, pulling volume toward reinforced drop-center profiles.
- Performance Wheels:Motorsport and off-road specifications require enhanced bead retention and bead-lock functionality for extreme terrain applications. Desert racing and rock-crawling segments command premium positioning with limited supplier competition, though volumes remain fractional against commercial fitments.
- Alloy Wheels:Hybrid steel-alloy constructions target weight reduction in light-truck segments where EPA fuel-economy benchmarks tighten.
- Custom Wheels:Low-volume specialty fabrications serve restoration and show-vehicle markets with extended lead times.
Most installed capacity flows through Standard Wheels. Expansion is steepest in Performance Wheels.
End User:
Contract structures and specification control determine which customer types capture the deepest supplier relationships.
- OEMs:Vehicle assemblers negotiate multi-year supply agreements that lock in load ratings, rim geometries, and pricing tiers across program lifecycles. The US NHTSA rollover resistance standards are compressing design cycles as manufacturers recalibrate strength-to-weight thresholds.
- Aftermarket Providers:Independent distributors and service chains source replacement wheels for fleet maintenance departments bringing rim inspection in-house. Brazil's sugar-ethanol haulage sector shows concentrated demand where seasonal intensity compresses maintenance windows.
- Tier-1 Suppliers:Wheel-end component integrators bundle rims with brake drums and hub assemblies for axle OEMs.
- Dealerships:Retail channels capture individual owner replacement demand with higher per-unit margins but fragmented volume.
Specification authority concentrates with OEMs. Margin capture is strongest among Aftermarket Providers.
Installation:
Fitment complexity drives labor allocation and tooling requirements at the point of assembly or service.
- Direct Fit:Vehicle-specific rim profiles match OEM bead seat geometries and offset specifications without modification. Indian commercial vehicle assemblers around Ludhiana and Jamshedpur specify direct-fit wheels to minimize mounting variance on high-volume production lines.
- Heavy-Duty Installation:Multi-piece rim assemblies for 80,000-pound gross combination weights require specialized mounting equipment and trained technicians. Fleet operators are deleting multi-piece designs in favor of lighter single-piece alternatives despite higher piece cost.
- Universal Fit:Adjustable offset designs serve cross-platform applications with inventory efficiency trade-offs.
- Lightweight Installation:Reduced-mass wheels target fuel-economy certification contributions in long-haul tractor programs.
Production volume flows through Direct Fit. Technical differentiation is greatest in Heavy-Duty Installation.
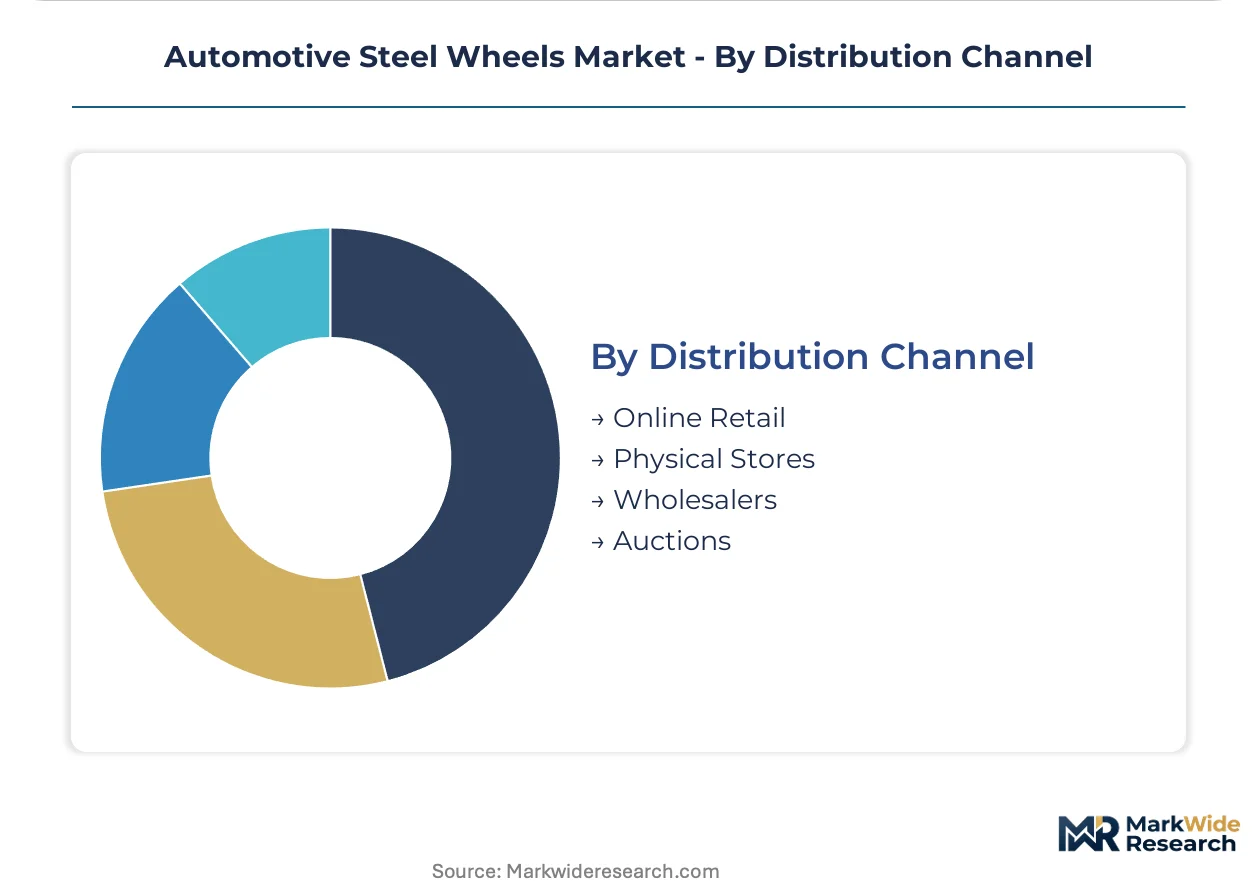
Distribution Channel:
Channel economics reflect working capital intensity and customer proximity requirements.
- Wholesalers:Regional distributors consolidate inventory across multiple wheel SKUs for fleet and independent garage customers. India's BIS certification timelines create 4-6 month import barriers that favor domestic wholesalers with certified stock positions.
- Physical Stores:Tire and wheel retailers provide mounting, balancing, and alignment services bundled with rim sales. Urban clusters in Brazil and India concentrate store footprints where commercial fleet density justifies local inventory.
- Online Retail:Digital channels capture price-sensitive replacement demand with extended delivery horizons.
- Auctions:Secondary markets liquidate surplus and salvage inventory for cost-conscious operators.
Inventory velocity runs highest through Wholesalers. Customer acquisition costs are compressing fastest in Online Retail.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Skilled welders and metallurgists concentrate in India's northern manufacturing belt, Mexico's integrated mill corridors, and Germany's automotive engineering clusters, anchoring regional production capabilities.
United States
Long-haul fleet operators are deleting multi-piece rim designs in favor of lighter single-piece alternatives to meet fuel-economy targets. The NHTSA enforces FMVSS No. 120 for tire and rim matching on commercial vehicles. Third-party laboratories in Michigan and Ohio report testing backlogs of 8-12 weeks for rim certification.
Mexico
Heavy-duty truck OEMs are sourcing single-piece steel wheels to comply with EPA greenhouse gas standards for heavy-duty trucks. USMCA rules enable re-export advantages while avoiding carbon tariffs on direct Asian imports. Foundry networks across Nuevo León and the Bajío Region sustain cost advantages through captive steel supply.
India
Commercial vehicle assemblers are expanding procurement of reinforced drop-center profiles as axle load limits rise. The BIS mandates certification timelines creating 4-6 month import barriers favoring domestic producers. Fabricators around Ludhiana and Jamshedpur deploy robotic rim welding to cut cycle times.
Brazil
Sugar-ethanol haulage fleets are bringing rim inspection in-house with portable gauging equipment to compress seasonal maintenance windows. ANVISA coordinates with transport regulators on commercial vehicle safety standards. Urban clusters in São Paulo concentrate tire and wheel retail footprints where commercial fleet density justifies local inventory.
Germany
Heavy-duty tractor programs specify advanced high-strength steel grades exceeding 980 MPa tensile strength to reduce rotating mass. The EU Green Deal and associated carbon-border adjustments restructure sourcing economics for wheel fabricators. Engineering clusters in Baden-Württemberg and North Rhine-Westphalia consolidate procurement around mills with certified AHSS production lines.
Automotive Steel Wheels Market Vendor Landscape
The competitive structure tilts toward vertically integrated mill operators with captive steel supply. Consolidation pressures favor fabricators with in-house production of high-strength grades and certified welding protocols. Three archetypes dominate: integrated steel-wheel producers with foundry networks, independent fabricators dependent on commodity coil supply, and hybrid alloy-steel specialists targeting light-truck mass reduction. Capacity expansion and backward integration into hot-rolled coil sourcing represent the dominant competitive moves.
Among integrated producers, MAXION Wheels and thyssenkrupp AG exemplify the foundry-network archetype, while Accuride Corporation occupies a position representing captive wheel-end component integration. Wheels India Limited and Steel Strips Wheels Limited anchor the domestic-fabricator tier within India's protected certification environment. These named entities collectively illustrate how geographic regulatory barriers and steel supply configuration determine sustainable competitive position.
| Leading Market Players |
|---|
| Central Motor Wheel of America, Inc. |
| MAXION Wheels |
| Accuride Corporation |
| Wheels India Limited |
| thyssenkrupp AG |
| Steel Strips Wheels Limited |
| Topy Industries Limited |
| Automotive Wheels Ltd. |
| The Carlstar Group LLC |
| Others |
Supply Flow & Price Mechanics
Skilled welders and robotic technicians cluster in India's Ludhiana-Jamshedpur corridor, Mexico's Bajío foundry belt, and Germany's automotive engineering clusters, creating labor-cost differentials that widen pricing spreads between premium certified and commodity-grade wheel tiers.
Pricing Analysis
Bundled wheel-end service contracts are fragmenting as fleet operators unbundle rim inspection from tire maintenance agreements. Three-tier pricing structure across premium AHSS-certified, standard load-rated, and economy commodity grades separates OEM multi-year agreements from aftermarket spot purchases. Pricing pressure stems from hot-rolled steel coil volatility as Chinese and Indian mills pass carbon-border adjustment costs downstream. Fleet operators in Brazil's agricultural corridors exhibit highest price sensitivity, while motorsport performance wheel buyers show least elasticity.
Supply Chain Analysis
Single-source vulnerability sits with integrated steel mills in China, India, and Germany that control certified AHSS production lines for 980 MPa-plus grades. Wheel fabricators draw from hot-rolled steel coil, robotic welding equipment, and third-party testing laboratory capacity. Tariff exposure through carbon-border adjustments threatens margin buffers for independent fabricators lacking captive steel supply. Distribution runs through regional wholesalers consolidating inventory across fleet and independent garage channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The automotive steel wheels market functions as a stable compounder anchored by regulatory mass-reduction mandates that perpetually refresh replacement demand across commercial vehicle fleets.
For Market Incumbents: Anchor market position through backward integration into certified AHSS steel supply and captive wheel-end component production. Defend against aluminum substitution in light-truck segments by accelerating single-piece design adoption for EPA compliance documentation. Prioritize certification investment in India's BIS-mandated testing protocols to exploit import barriers favoring domestic producers. For New Entrants and Emerging Players: Aftermarket distributors represent the most accessible channel partners for penetrating Brazil's sugar-ethanol haulage sector where seasonal maintenance intensity compresses service windows. Target off-road motorsport bead-lock specifications commanding premium multiples with limited incumbent competition. Pursue white-label manufacturing arrangements with fleet operators bringing rim inspection in-house. For Investors and Strategic Acquirers: Valuations sit cheapest among independent fabricators dependent on commodity coil supply and lacking certified welding protocols. Long-term viability favors vertically integrated producers with captive steel mills and multi-regional foundry networks. Monitor EPA greenhouse gas standard tightening as inflection signal for accelerated single-piece wheel adoption.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into AHSS Steel Supply | Captive access to 980 MPa grades insulates margin from carbon-border volatility. |
| Robotic Rim Welding Deployment | Automation in India's Ludhiana cluster cuts cycle times and porosity defect rates. |
| Single-Piece Design Standardization | Lightweight alternatives replace multi-piece rims for EPA fuel-economy certification. |
| BIS Certification Investment | Domestic Indian producers exploit 4-6 month import barriers against foreign competition. |
| Performance Wheel Specialty Expansion | Bead-lock specifications for desert racing command 3-4x standard wheel pricing. |
Methodological Framework
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with OEM platform engineers, Tier 1 supplier procurement leads, aftermarket distributors, fleet maintenance directors, and robotic welding equipment specialists with secondary validation against vehicle production databases, IHS Markit registration data, SEC filings from integrated steel producers, and EPA greenhouse gas certification records. Bottom-up segment sizing and top-down macro anchoring were cross-checked for consistency.
Segment-weighting approaches modeled product type, end user channel, installation complexity, and regional production cluster dimensions across the analysis window. CAGRs were derived from elasticity-adjusted volume projections and value-per-unit trajectories. Forecast inputs incorporated NHTSA rollover resistance standard evolution, BIS certification timeline changes, and commercial vehicle axle load limit adjustments.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to carbon-border adjustment implementation, aluminum wheel substitution acceleration, and AHSS welding qualification bottlenecks. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Tires and Wheels
Wheel and Tire Service Equipment Market
Tires and Wheels
Trailer Wheel Market
Tires and Wheels
Global Tire Curing Press Market
Tires and Wheels
Bicycle Rim Brake Market
Tires and Wheels
Europe Two-Wheeler Tire Market
Tires and Wheels
Global High Performance Tires Market
Tires and Wheels
Global Off-Highway Tire Market
Tires and Wheels
Automotive Alloy Wheels Market
Tires and Wheels
Self-Healing Tire Market
Tires and Wheels
Automotive 3D Printed Tires Market
Tires and Wheels
Automotive Tire Chains Market
Tires and Wheels
Asia Pacific 2-Wheeler Tire Market
Tires and Wheels
Bias Tire Market
Tires and Wheels
Truck and Bus Radial (TBR) Tire Market
Tires and Wheels
Automotive Tire Analytics Market
Tires and Wheels
Solid Tire Market