
 Europe Green Tire Market | 2026-2036
Europe Green Tire Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Green Tire Market Analysis
A widening capital-intensity divergence between integrated compound producers and assembly-only tire makers is reorganizing competitive hierarchy in the Europe Green Tire Market. Michelin leverages captive rubber plantations and in-house silica development to sustain margin control across premium radial lines. Continental AG anchors its position through deep backward integration into synthetic polymer research facilities in Hanover and Korbach. Nokian Tyres specializes in Arctic-grade bio-based compounds, dominating Nordic replacement cycles where cold-climate performance commands price premiums.
Europe green tires incorporate silica-reinforced tread compounds, low-rolling-resistance carcass designs, and bio-sourced fillers that reduce fuel consumption by minimizing hysteresis loss during deformation. Their primary commercial purpose centers on helping vehicle fleets and passenger car owners meet EU CO2 emission reduction mandates while maintaining safety ratings under wet braking protocols. Radial tires occupy the dominant volume position due to structural compatibility with silica-dispersion manufacturing, while bio-based compounds represent the fastest-expanding material category as compounders reformulate away from petroleum-derived synthetic rubber. Passenger vehicles channel the majority of value demand, though heavy-duty trucks are emerging as a concentrated margin pool where fleet operators amortize fuel savings across high-mileage duty cycles.
The EU Green Deal, REACH chemical registration requirements, and F-Gas Regulation collectively mandate rolling-resistance labeling and restrict hazardous aromatic oils in tire manufacturing. ECHA substance evaluations now drive reformulation timelines, forcing compounders to pre-certify alternative plasticizers before market entry. Stakeholders must monitor pending CSRD disclosure rules that will require Scope 3 emission reporting across tire supply chains, fundamentally altering supplier qualification criteria and capital allocation toward traceable bio-feedstock sourcing.
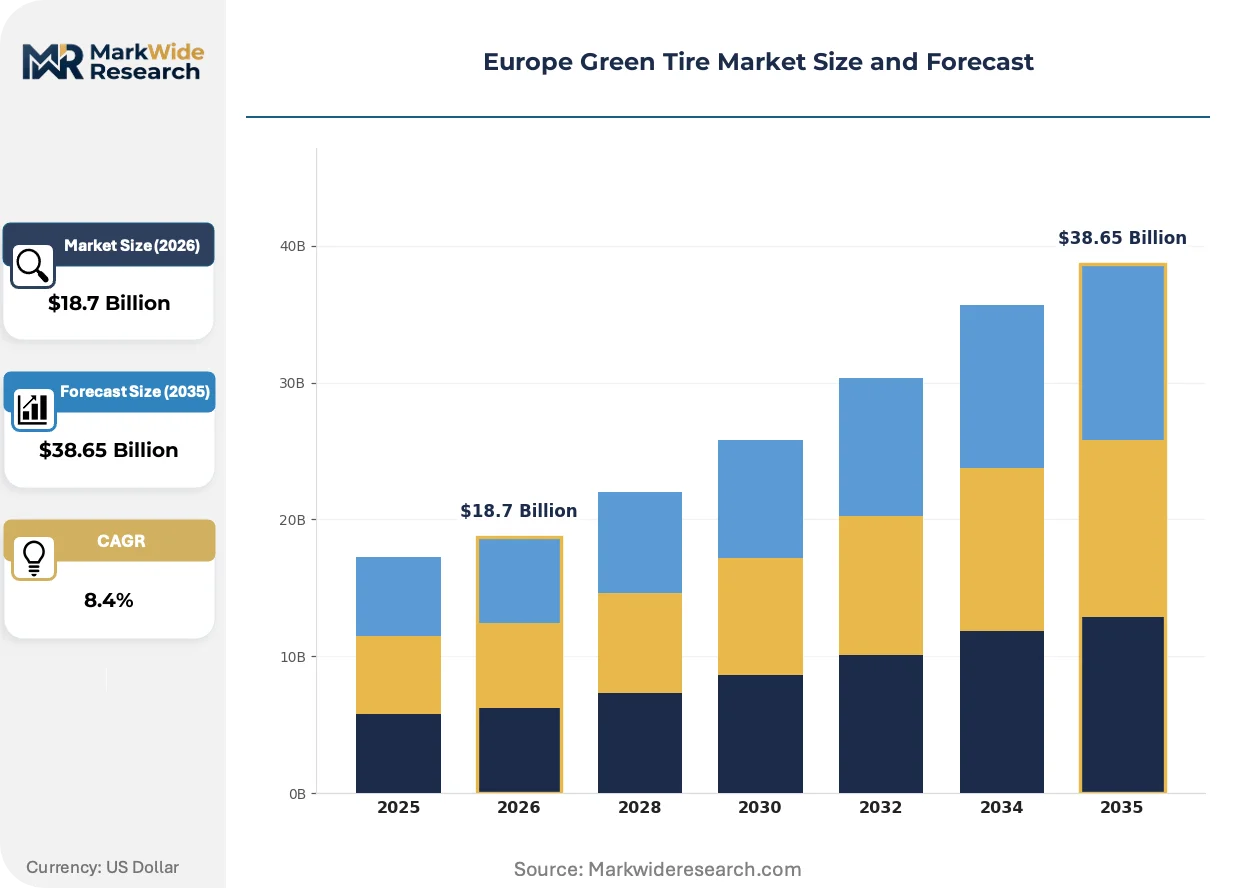
Market Dynamics
EU CO2 fleet emission mandates are compressing tire procurement timelines, forcing automakers to specify silica-reinforced compounds before vehicle platform freezes while compounders scramble to certify bio-based fillers under REACH's evolving substance evaluations.
Growth Catalysts
- EU Green Deal enforcement:Rolling-resistance labeling mandates now bind tire importers to minimum efficiency grades, redirecting fleet procurement toward A-rated products across Germany, France, and the Netherlands.
- Passenger vehicle electrification:EV manufacturers specify low-hysteresis compounds to extend battery range, pulling green tire specifications into platform design phases earlier than combustion-era cycles.
- Stuttgart-Munich-Wolfsburg corridor concentration:OEM engineering centers cluster within 300 kilometers, enabling same-day compound testing iterations that accelerate validation timelines for new silica dispersions.
Market Restraints
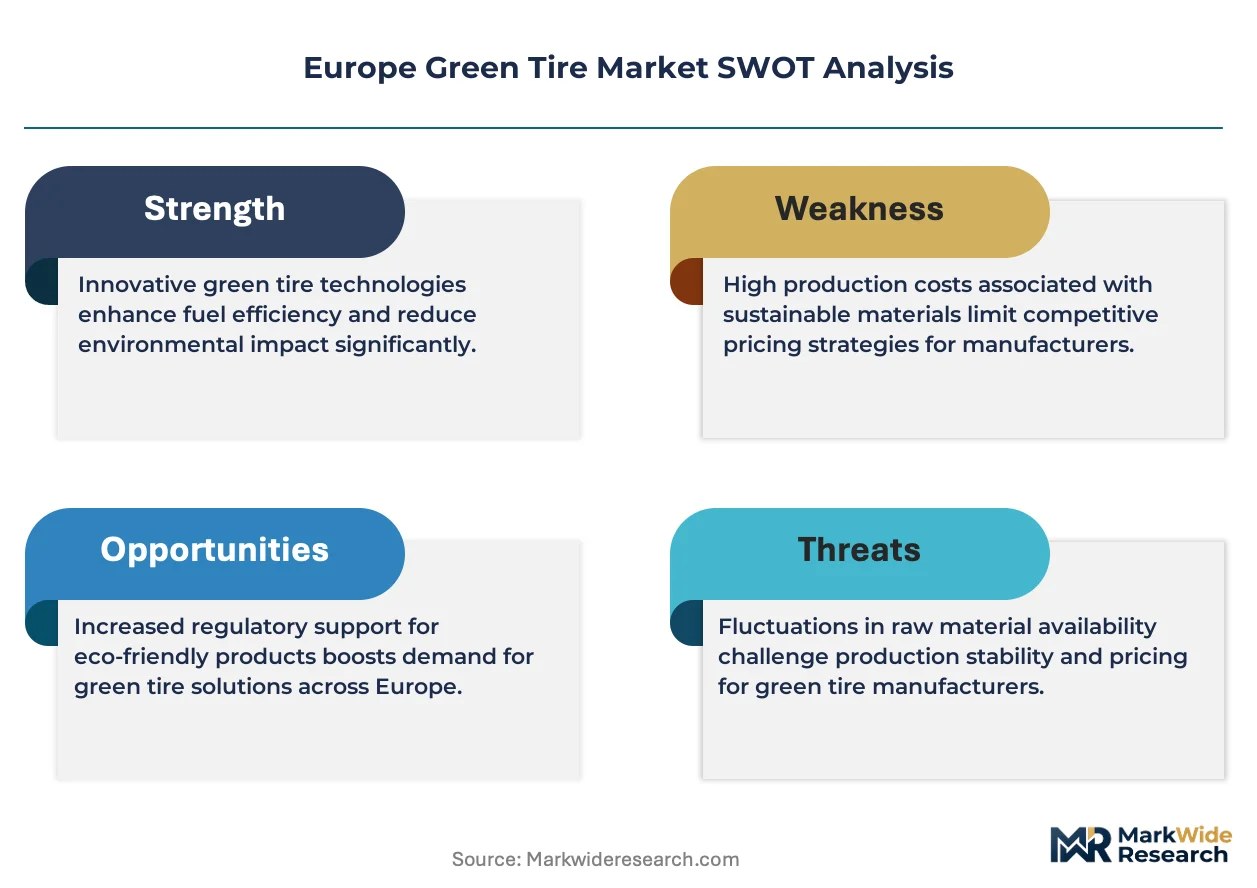
- Petroleum-derived synthetic rubber price volatility:Butadiene and styrene-butadiene rubber feedstock costs swing with crude oil indices, compressing compounder margins when bio-based alternatives remain at pilot-scale premiums.
- High-purity precipitated silica supply concentration:Four European chemical groups control furnace-grade silica output, creating bottleneck risk for tire makers lacking backward integration into silicate processing.
- Wet-grip performance trade-offs:Low-rolling-resistance tread formulations historically sacrificed braking coefficients on rain-slick surfaces, forcing compounders to maintain dual-compound inventories until new dispersion technologies mature.
Strategic Opportunities
- Poland and Czech Republic aftermarket penetration:Replacement cycles in Central European markets lag Western adoption curves by 3-4 years, creating first-mover advantage for distributors building green tire awareness among price-sensitive fleet operators.
- Heavy-duty truck mileage-based contracting:Logistics operators in the Rhine-Alpine corridor are piloting tire-as-a-service models where suppliers capture fuel savings via per-kilometer fees rather than upfront product sales.
- CSRD Scope 3 disclosure preparation:Pending corporate sustainability reporting requirements will force fleet buyers to document tire-related emissions, creating qualified demand for traceable bio-rubber supply chains with mass-balance certification.
Industry Challenges
- Compound formulation talent scarcity:The intersection of polymer chemistry and tire engineering expertise concentrates among retiring specialists at Continental AG and Michelin, constraining knowledge transfer to mid-tier competitors.
- ECHA pre-certification timelines:Alternative plasticizers and bio-sourced oils now require 18-24 month substance evaluation periods, delaying product launches regardless of technical readiness.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Green Tire Market |
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $38.65 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Radial Tires, Bias Tires, Tubeless Tires, Run-flat Tires Material: Natural Rubber, Synthetic Rubber, Recycled Materials, Bio-based Compounds End User: Passenger Vehicles, Commercial Vehicles, Two-wheelers, Heavy-duty Trucks Distribution Channel: Retail Stores, Online Platforms, Wholesale Distributors, Direct Sales |
| Companies Covered | Pirelli & C. S.p.A., Nokian Tyres, Michelin, Sumitomo Corporation, Hankook Tire, Continental AG, Goodyear Tire & Rubber Company, Maxxis International, Bridgestone Corporation, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Green Tire Market Emerging Trajectories
Silica-silane coupling chemistry is rewriting tread compound performance boundaries while regulatory disclosure requirements pull traceability technology into supply chain infrastructure faster than compounders anticipated.
Advanced precipitated silica with surface-functionalized silane groups is decomposing the traditional wet-grip versus rolling-resistance trade-off that constrained green tire design for two decades. German premium OEMs now specify these compounds for 2027 platform releases, accepting 15% higher unit costs to avoid dual-sourcing separate summer and efficiency tire lines. The technology is decomposing tier-2 compounders' historical reliance on licensed formulations from integrated producers.
REACH Annex XVII restrictions on polycyclic aromatic hydrocarbons in extender oils are forcing compounders to reformulate around distillate aromatic extracts and treated distillate aromatic extracts by 2026. Tire makers with captive testing facilities in Hanover and Clermont-Ferrand are compressing validation cycles, while smaller competitors face 12-month backlog at independent laboratories. Nordic replacement markets show earliest compliance completion due to Nokian Tyres' decade-long bio-oil research programs.
Fleet procurement departments now specify total cost of ownership models incorporating fuel consumption, tire life, and disposal fees rather than unit price alone. This behavior is concentrating contract awards among suppliers offering predictive wear monitoring via embedded RFID tags, displacing traditional distributor relationships in the Benelux heavy-duty segment. German long-haul operators lead this shift, with French refrigerated transport fleets following 18 months behind.
Europe Green Tire Market Segmentation
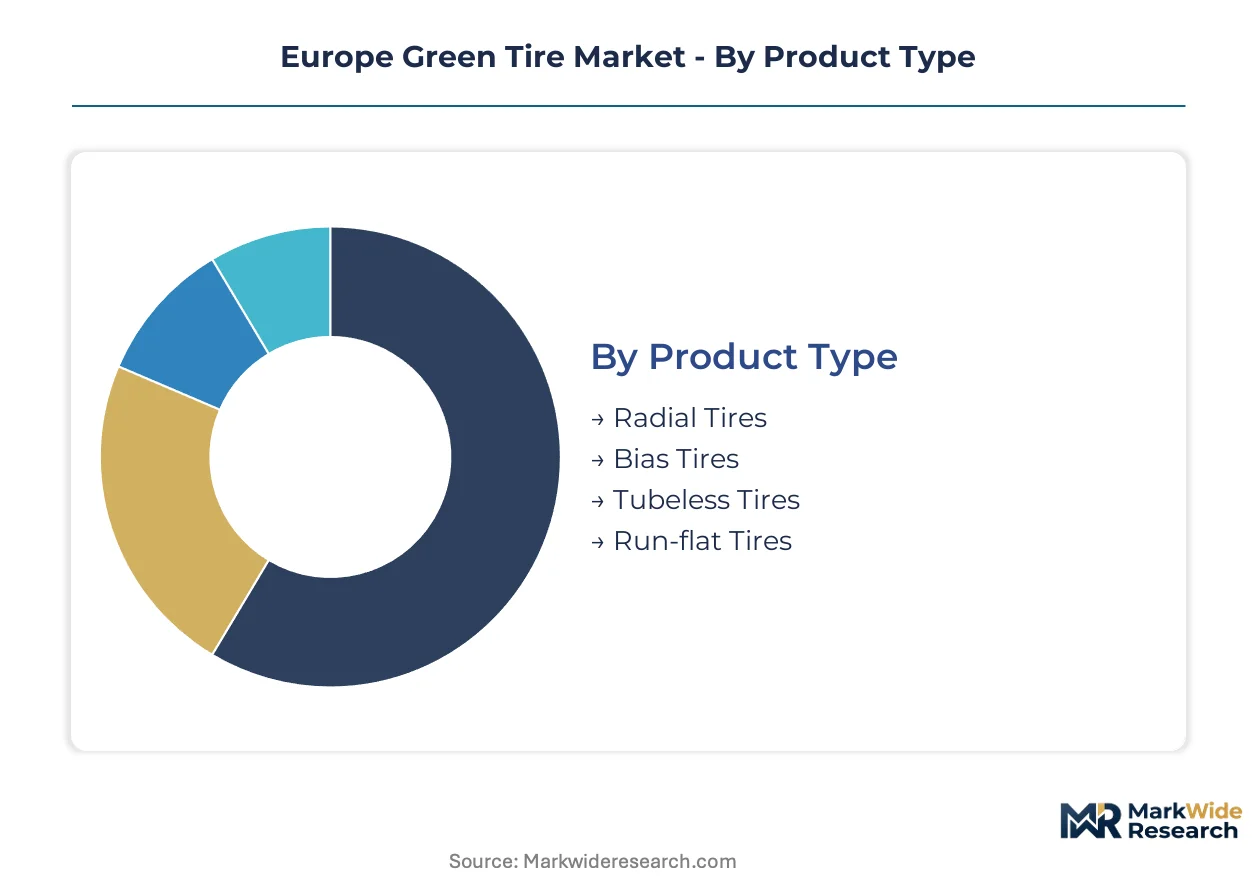
Green tire segmentation in Europe tracks divergent supply chain requirements across compound chemistry, vehicle platform specifications, and procurement channel economics. Each dimension carries distinct regulatory exposure and margin architecture that reshapes competitive positioning.
Product Type:
Radial tire demand concentrates in Germany's OEM corridor where same-day compound validation cycles compress platform development timelines. Bias and specialty constructions serve replacement markets with longer inventory cycles.
- Radial Tires:Silica-reinforced tread compounds and low-hysteresis carcass designs dominate volume. Stuttgart and Wolfsburg engineering centers specify these for EU CO2 fleet compliance, pulling demand into platform freeze phases earlier than legacy tire categories.
- Bias Tires:Cross-ply construction persists in agricultural and industrial niches where load-bearing capacity outweighs rolling-resistance optimization. Eastern European fleet operators maintain replacement demand where price sensitivity exceeds efficiency mandates.
- Tubeless Tires:Eliminate inner tubes through airtight bead-seat sealing, reducing unsprung weight for passenger EV platforms.
- Run-flat Tires:Reinforced sidewalls enable extended mobility after pressure loss, commanding premium positioning in premium German OEM fitments.
Radial tires command the established base. The steepest expansion runs through run-flat configurations as EV weight distributions strain conventional spare tire packaging.
Material:
Compound sourcing strategies split between petroleum-dependent synthetic rubber and bio-based alternatives facing REACH pre-certification timelines. Feedstock traceability is becoming a procurement qualifier under pending CSRD disclosure rules.
- Synthetic Rubber:Styrene-butadiene and polybutadiene derivatives provide consistent polymer architecture for silica dispersion. Butadiene price volatility tied to crude indices compresses compounder margins when bio-based alternatives remain at pilot-scale premiums.
- Bio-based Compounds:Guayule and dandelion-derived latex plus rice husk silica reduce Scope 3 emissions. Nordic replacement markets show earliest adoption due to Nokian Tyres' decade-long bio-oil research programs and cold-climate performance validation.
- Natural Rubber:Hevea brasiliensis latex supplies structural elasticity for heavy-load applications.
- Recycled Materials:Devulcanized crumb rubber and recovered carbon black close material loops under EU circular economy directives.
Synthetic rubber retains the volume anchor. Bio-based compounds are climbing the fastest as E substance evaluations force reformulation away from petroleum feedstocks.
End User:
Vehicle platform electrification is rewriting tire specification timelines, with EV manufacturers integrating low-hysteresis compounds into battery range calculations during early design phases.
- Passenger Vehicles:Channel the majority of value demand through OEM fitments and premium replacement cycles. French and Dutch fleet procurement now mandates A-rated rolling-resistance labels, redirecting volume toward silica-reinforced constructions.
- Heavy-duty Trucks:Concentrate margin potential where Rhine-Alpine logistics operators amortize fuel savings across high-mileage duty cycles. Tire-as-a-service pilots capture efficiency gains through per-kilometer contracting rather than upfront product sales.
- Commercial Vehicles:Light trucks and vans balance payload capacity with urban emission restrictions.
- Two-wheelers:Motorcycles and scooters face distinct wet-grip certification protocols under ECE R75.
Passenger vehicles anchor current revenue. Heavy-duty applications are expanding most quickly as fleet TCO models incorporate predictive wear monitoring and embedded RFID traceability.
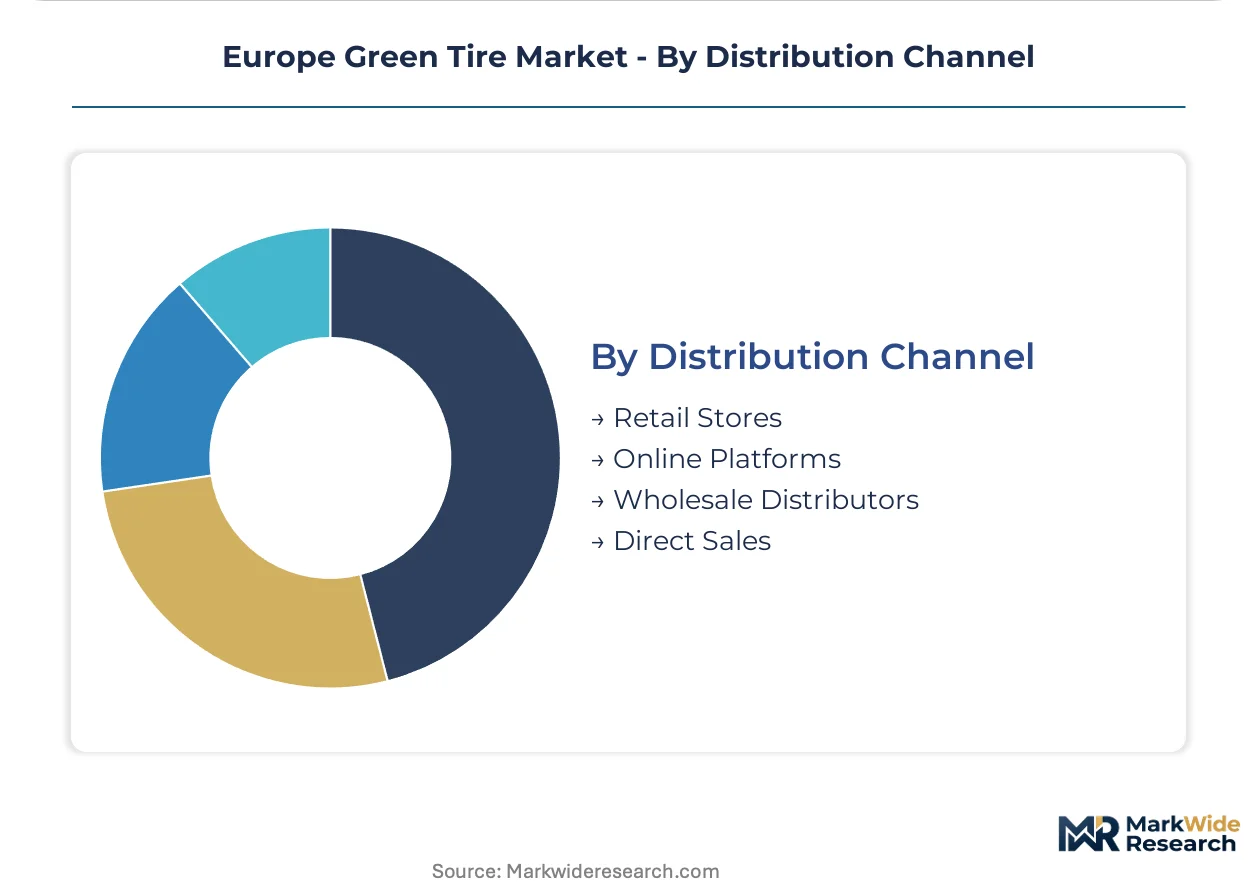
Distribution Channel:
Channel economics reflect divergent service intensity requirements, from technical specification support for OEM procurement to price transparency for replacement consumers.
- Direct Sales:OEM supply agreements with Stuttgart-Munich-Wolfsburg engineering centers require co-located testing facilities and same-day compound iteration capabilities. These relationships lock in multi-year platform supply with penalty clauses for rolling-resistance deviation.
- Online Platforms:Price transparency and EU tire label comparison tools are displacing traditional distributor relationships in Benelux passenger replacement markets. German consumers lead channel shift adoption.
- Retail Stores:Fitting services and seasonal changeover labor retain relevance for Nordic markets with mandatory winter tire regulations.
- Wholesale Distributors:Inventory pooling serves fragmented Central European garage networks with 3-4 year adoption lag behind Western efficiency curves.
Direct sales command the established base. Online platforms are gaining share fastest as fleet procurement departments migrate toward digital specification and total cost of ownership comparison tools.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power concentrates in Germany's automotive corridor while Polish and Czech fleet operators lag Western adoption curves by three to four years, compressing margin capture for distributors serving Central European replacement cycles.
Germany
OEM engineering centers in Stuttgart, Munich, and Wolfsburg drive silica-reinforced compound specifications into platform freeze phases. The EU Green Deal's rolling-resistance labeling mandates bind domestic tire importers to minimum A-rated efficiency grades. Continental AG's synthetic polymer research facilities in Hanover and Korbach anchor backward integration into low-hysteresis carcass development.
France
Paris-based fleet procurement departments now mandate total cost of ownership models incorporating fuel consumption and disposal fees rather than unit price alone. REACH Annex XVII restrictions on polycyclic aromatic hydrocarbons force compounders to reformulate around treated distillate aromatic extracts by 2026. Clermont-Ferrand hosts captive testing facilities compressing validation cycles for bio-sourced oil alternatives.
Netherlands
Rhine-Alpine logistics operators pilot tire-as-a-service models where suppliers capture fuel savings via per-kilometer fees. The Dutch national fleet emission reduction program accelerates A-rated rolling-resistance procurement timelines. Rotterdam's port-centric heavy-duty truck concentration creates concentrated margin pools for predictive wear monitoring with embedded RFID traceability.
Poland
Replacement cycles in Warsaw and Krakow garage networks lag German efficiency adoption by three to four years, creating first-mover advantage for green tire awareness campaigns. EU F-Gas Regulation compliance deadlines approach without domestic silica processing capacity. Poznan-based wholesale distributors inventory pool for fragmented Central European service networks.
Sweden
Nordic winter tire mandates sustain demand for cold-climate performance validation. Stockholm and Gothenburg fleet operators show earliest bio-based compound adoption due to decade-long bio-oil research programs. The Swedish Transport Agency's tire labeling enforcement redirects volume toward silica-reinforced constructions meeting wet-grip protocols.
Europe Green Tire Market Vendor Landscape
Technology leadership and cost leadership are held by different player archetypes, creating tiered competitive dynamics across the Europe Green Tire Market. Integrated compound producers with captive rubber sourcing and in-house silica development sustain margin control against assembly-only tire makers exposed to petroleum-derived synthetic rubber price volatility. Three strategic archetypes dominate: backward-integrated multinationals with polymer research facilities, regional specialists in Arctic-grade bio-based formulations, and scale-driven Asian manufacturers leveraging volume efficiencies. Dominant competitive moves include capacity expansion into precipitated silica processing and strategic partnerships securing mass-balance certified bio-feedstock traceability ahead of CSRD Scope 3 disclosure requirements.
Within the integrated multinational tier, Michelin and Continental AG exemplify archetypes combining captive supply chains with OEM co-location strategies. Nokian Tyres occupies a specialist position representing Nordic-focused bio-compound expertise. These three entities anchor the competitive structure without exhausting its diversity, as Hankook Tire and Bridgestone Corporation represent scale-driven alternatives competing on manufacturing efficiency rather than backward integration depth.
| Leading Market Players |
|---|
| Pirelli & C. S.p.A. |
| Nokian Tyres |
| Michelin |
| Sumitomo Corporation |
| Hankook Tire |
| Continental AG |
| Goodyear Tire & Rubber Company |
| Maxxis International |
| Bridgestone Corporation |
| Others |
Supply Flow & Price Mechanics
Silica-reinforced tread compounds displacing conventional carbon-black formulations are redrawing raw material sourcing maps from petroleum refineries toward chemical processing hubs in Germany and the Netherlands, compressing compounder margins during the transition while rewarding tire makers with captive silicate production.
Pricing Analysis
The customization-premium spread between OEM-configured silica compounds and standard replacement formulations spans three performance tiers: A-rated rolling-resistance lines for EU fleet compliance, mid-grade all-season constructions, and economy bias-ply alternatives for price-sensitive Central European garages. Price differentiation hinges on wet-grip certification grades under ECE R117 and volume scale commitments from Stuttgart-Munich-Wolfsburg engineering centers. Pricing pressure stems from butadiene cost volatility tied to crude indices, eroding margins for non-integrated compounders. Fleet procurement departments show lowest price sensitivity due to total cost of ownership modeling, while independent Polish distributors face acute margin compression.
Supply Chain Analysis
Inventory lead times for high-purity precipitated silica extend 8-12 weeks, forcing tire makers without backward integration to carry buffer stocks against German chemical group allocation constraints. Supply concentrates in Germany, France, and Belgium where four European chemical groups control furnace-grade silicate output. Raw material dependencies include styrene-butadiene rubber, surface-functionalized silane coupling agents, and guayule-derived bio-latex. Single-source vulnerability around precipitated silica creates bottleneck exposure for assembly-only manufacturers. Distribution runs through direct OEM supply agreements with engineering co-location requirements, wholesale pooling for fragmented garage networks, and emerging online platforms with EU tire label comparison tools.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a defensive-moat arena where regulatory entrenchment through REACH pre-certification timelines and ECHA substance evaluation backlogs protects incumbent compounders from fast-follower competition.
For Market Incumbents: Consolidate control over precipitated silica processing capacity and captive bio-feedstock traceability systems ahead of CSRD Scope 3 disclosure mandates. Secure multi-year platform supply agreements with penalty clauses for rolling-resistance deviation to lock out emerging Asian scale manufacturers. Deepen backward integration into synthetic polymer research to defend margin position against petroleum feedstock volatility. For New Entrants and Emerging Players: Anchor in Poland and Czech Republic aftermarket channels where green tire awareness lags Western adoption curves by 3-4 years, creating first-mover positioning before efficiency mandates tighten. Target heavy-duty truck tire-as-a-service pilots in the Rhine-Alpine corridor where per-kilometer contracting models favor agile suppliers over legacy distributors. Pursue mass-balance certification partnerships with Nordic bio-rubber researchers as the qualifying credential for fleet procurement. For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors compounders with integrated silica development and captive testing facilities over assembly-only tire brands. Long-term viability across the projection horizon rests on regulatory compliance infrastructure rather than manufacturing scale alone. Monitor ECHA substance evaluation completion rates as the inflection signal for bio-based compound market readiness.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Silica Processing | Captive precipitated silica production insulates Continental AG and Michelin from chemical group allocation bottlenecks. |
| Bio-Feedstock Mass-Balance Certification | Traceable guayule and dandelion latex sourcing qualifies suppliers for CSRD Scope 3 fleet procurement mandates. |
| OEM Engineering Co-Location | Same-day compound testing in Stuttgart-Munich-Wolfsburg corridor accelerates platform validation timelines. |
| Heavy-Duty Tire-as-a-Service Pilots | Per-kilometer contracting with Rhine-Alpine logistics operators captures fuel savings via outcome-based pricing. |
| REACH Alternative Plasticizer Pre-Certification | 18-24 month ECHA evaluation timelines for bio-sourced oils create regulatory moats against fast followers. |
Methodological Framework
The analysis maps silica-reinforced radial compounds, bio-based filler formulations, and heavy-duty truck constructions, each validated through compound development directors, OEM platform engineers, and fleet procurement managers at Rhine-Alpine logistics operators. Primary fieldwork combined with secondary validation from ECHA substance evaluation databases, EU tire labeling compliance records, customs trade flows for synthetic rubber feedstocks, and SEC filings from integrated chemical groups. Bottom-up segment sizing triangulated against top-down market envelope checks ensures consistency across material, end-use, and channel dimensions.
Consistency checks against external benchmarks validated volume and value outputs across the projection horizon. The analytical framework modeled vehicle platform electrification timelines, REACH Annex XVII reformulation deadlines, and fleet emission reduction trajectories as segmentation drivers. CAGRs derived from installed base turnover analysis, OEM platform freeze schedules, and replacement cycle elasticity to fuel price movements. Industry-specific forecast inputs include silica-dispersion manufacturing capacity utilization and bio-based compound pilot-scale cost curves.
Material uncertainties — ECHA evaluation timeline extensions, crude oil price volatility affecting synthetic rubber costs, and EV platform specification shifts — sit outside the modeled envelope. Forecasts reflect assumptions around regulatory enforcement consistency and fleet procurement behavior adoption. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Tires and Wheels
Global Commercial Vehicle Run Flat Tire Inserts Market
Tires and Wheels
Europe Tire Market
Tires and Wheels
Global Electric Vehicle Tire Market
Tires and Wheels
Automotive Wheel Rims Market
Tires and Wheels
Europe Aircraft Tires Market
Tires and Wheels
Global Tire Curing Press Machine Market
Tires and Wheels
Ground Support Equipment Tires Market
Tires and Wheels
Automotive Automatic Tire Inflation System (ATIS) Market
Tires and Wheels
North America Tire Market
Tires and Wheels
United States Tire Market
Tires and Wheels
Asia-Pacific Automotive Tire Pressure Management System Market
Tires and Wheels
Europe Agricultural Tires Market
Tires and Wheels
Heavy Duty Tire Market
Tires and Wheels
Automotive Smart Tire Market
Tires and Wheels
North America OTR Tire Market
Tires and Wheels
Passenger Tire Market