
 Japan Tyre Market | 2026-2036
Japan Tyre Market Size, Share, and Industry Trends Forecast 2026-2036
Japan Tyre Market Intelligence
Multi-source procurement among Japanese fleet operators is hardening as logistics companies diversify supplier relationships to mitigate disruption risks. Bridgestone Corporation anchors domestic production through its extensive manufacturing footprint across Kyushu and Kanto. Yokohama Rubber Company Limited differentiates through motorsports-derived compound technology transferred to premium passenger lines. Sumitomo Rubber Industries Limited leverages its Dunlop brand heritage to sustain aftermarket loyalty among independent repair chains.
Tyres are composite structures of rubber compounds, textile reinforcement, and steel bead wires engineered to transmit vehicle loads while maintaining traction across temperature and surface variations. Radial construction dominates Japanese OEM fitment due to superior heat dissipation and tread life under sustained highway speeds. Passenger car tyres command the largest volume share, though heavy-duty truck tyres generate disproportionate margin pools from fleet replacement cycles. Run-flat technology occupies a growing niche among premium vehicle manufacturers seeking to eliminate spare tire weight and packaging constraints.
METI enforces fuel efficiency labeling under the Energy Conservation Act, compelling manufacturers to disclose rolling resistance grades at point of sale. JIS standards govern dimensional tolerances and load ratings, while the Ministry of Land, Infrastructure, Transport and Tourism administers type approval for imported tyres through designated technical services. Stakeholders must monitor how Japan's alignment with UN Regulation 117 on tyre noise and wet grip reshapes product development priorities and import eligibility criteria.
Market Dynamics
Japan's tyre market is being restructured by METI's fuel efficiency labeling mandates, which force compound reformulation across domestic manufacturing while fleet operators delay replacement cycles to manage capital outlays.
Growth Catalysts
- Commercial Fleet Aging:Extended asset lifecycles among logistics operators in the Kanto corridor generate sustained replacement demand as capital constraints postpone new vehicle acquisitions.
- METI Energy Conservation Act:Mandatory rolling resistance disclosure at point of sale compels manufacturers to develop low-resistance compounds, creating product differentiation opportunities.
- Radial Construction Dominance:Superior heat dissipation characteristics under sustained highway speeds cement radial tyres as the default specification for Japanese OEM fitment.
Market Restraints
- Natural Rubber Price Volatility:Import dependence on Southeast Asian latex supplies exposes domestic compounders to commodity swings that compress margin predictability.
- Kanto Production Concentration:Manufacturing gravity clustering around Tokyo-Yokohama logistics networks creates single-point vulnerability to seismic disruption.
- UN Regulation 117 Alignment:Wet grip and noise testing protocols impose recertification burdens that extend product development timelines for import-dependent distributors.
Strategic Opportunities
- Run-Flat Technology Expansion:Premium vehicle manufacturers seeking spare tyre elimination present a niche for self-supporting sidewall constructions with higher unit economics.
- Kyushu Manufacturing Base:Underutilized production capacity in southern Japan offers geographic diversification from Kanto corridor concentration risks.
- Independent Repair Chain Loyalty:Heritage brand positioning among aftermarket specialists creates defensible channel relationships against direct-to-fleet disintermediation.
Industry Challenges
- Compound Chemistry Talent Scarcity:Formulation expertise in silica-reinforced low-rolling-resistance blends remains concentrated among retiring specialist cohorts.
- Type Approval Bottlenecks:Ministry of Land, Infrastructure, Transport and Tourism certification queues for imported tyres delay market entry for non-domestic suppliers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Japan Tyre Market |
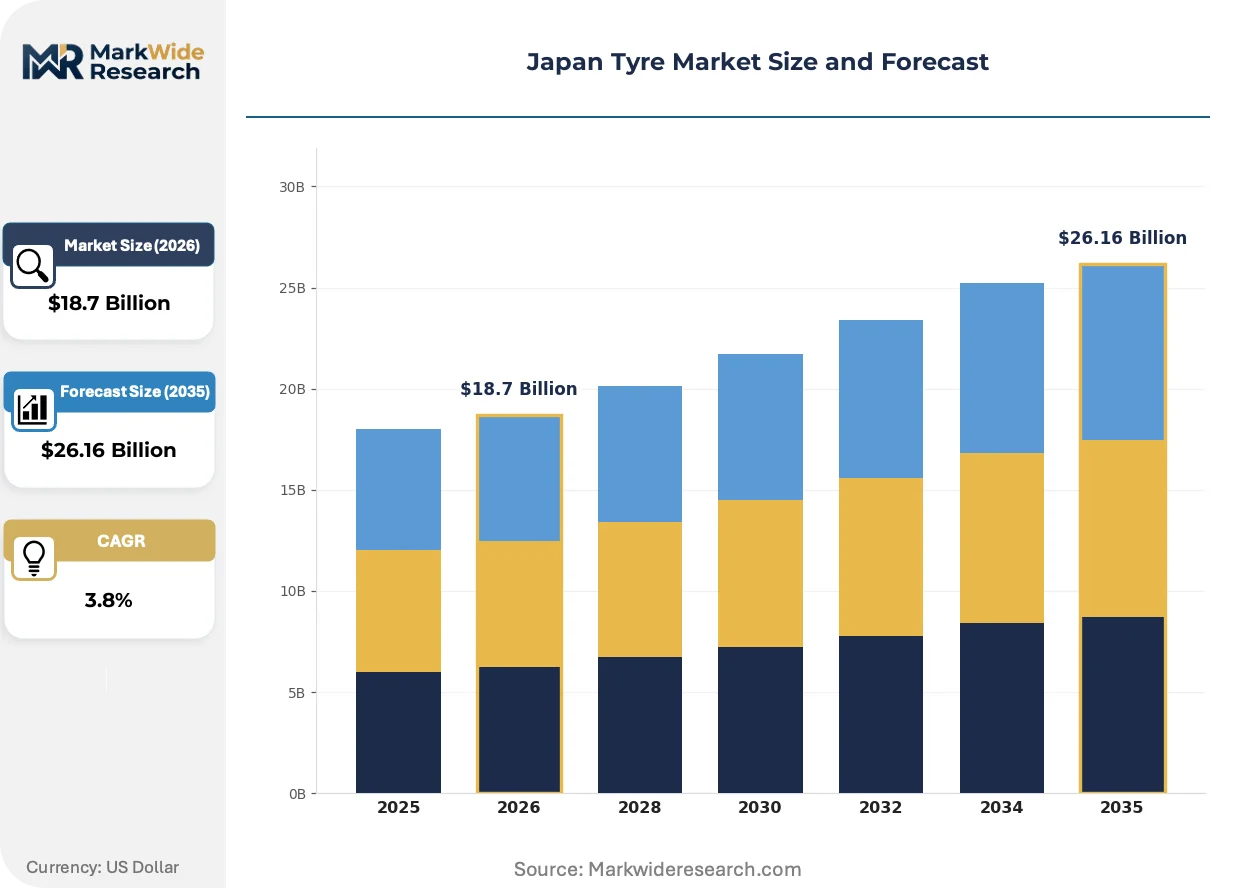
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $26.16 Billion |
| CAGR (2026 – 2036) | 3.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Radial, Bias, Run-flat, All-season Vehicle Type: Passenger Cars, Commercial Vehicles, Two-wheelers, Heavy-duty Trucks Sales Channel: Online, Retail, Wholesale, Service Stations Application: On-road, Off-road, Racing, Utility |
| Companies Covered | Toyo Tires & Rubber Company Limited, Japan Michelin Tire Co Ltd., Bridgestone Corporation, Japan Pirelli Inc., Japan Goodyear Inc., Yokohama Rubber Company Limited, Kumho Tire Japan Inc., Hankook Tire Japan, Sumitomo Rubber Industries Limited, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Japan Tyre Market Strategic Shifts & Innovations
Material science advances and regulatory disclosure requirements are converging to redefine product specifications and procurement criteria across Japanese tyre distribution channels.
Silica-reinforced tread compounds is rewriting performance benchmarks for wet grip and rolling resistance simultaneously. Fleet operators in expressway logistics are specifying these formulations for highway-dominant routes. The technology is compressing the performance gap between premium and standard tier offerings.
METI's alignment with UN Regulation 117 noise and wet grip standards is reshaping import eligibility criteria. Domestic distributors must now recalibrate sourcing strategies to accommodate extended homologation timelines. Heavy-duty truck tyre categories face the steepest compliance adjustment burdens.
Multi-source procurement patterns among logistics operators are fragmenting historical single-supplier relationships. Large fleet managers in the Tokyo metropolitan zone are qualifying secondary vendors to mitigate disruption exposure. This behavior is most pronounced among temperature-controlled freight specialists with zero-tolerance downtime policies.
Japan Tyre Market Segmentation
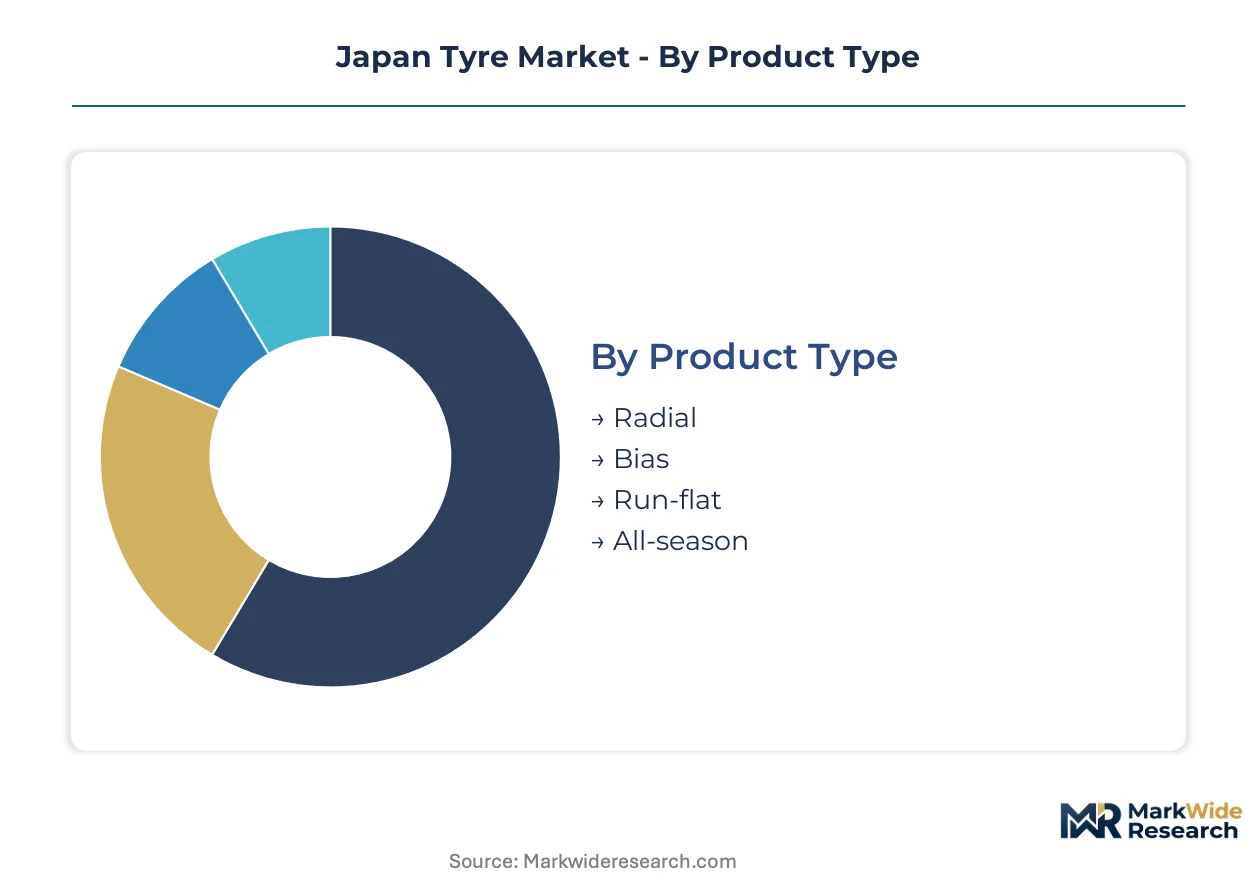
Tyre procurement patterns in Japan diverge sharply across vehicle categories and distribution channels, with METI fuel efficiency labels and JIS certification requirements creating distinct compliance burdens for each segment. Fleet operators and retail buyers apply fundamentally different selection criteria, fragmenting manufacturer go-to-market strategies.
Product Type:
METI's Energy Conservation Act imposes differential rolling resistance disclosure requirements across construction technologies, with radial and run-flat variants facing the strictest labeling scrutiny for OEM fitment.
- Radial:Steel-belted construction with perpendicular cord plies delivers superior heat dissipation under sustained highway speeds. Demand concentrates among expressway logistics fleets in the Kanto corridor, where METI fuel efficiency mandates favor low rolling-resistance radial specifications for commercial replacement cycles.
- Run-flat:Self-supporting sidewall compounds reinforced with heat-resistant inserts enable continued operation at zero inflation pressure. Premium vehicle manufacturers in Tokyo and Yokohama specify these for weight reduction and packaging efficiency, despite higher unit costs and limited repairability.
- Bias:Diagonal ply construction with overlapping cord layers suits lower-speed applications where cost sensitivity outweighs highway performance requirements.
- All-season:Tread compounds balanced across temperature ranges address consumer preference for single-set solutions in mild-climate prefectures.
Leading the category by volume: Radial. Expanding most quickly: Run-flat.
Vehicle Type:
Replacement cycle timing and procurement authority differ fundamentally between owner-operated passenger vehicles and fleet-managed commercial assets, with the latter concentrating decision-making among fewer professional buyers.
- Passenger Cars:Original equipment specifications from domestic OEMs dominate fitment patterns, with replacement demand fragmented across independent retail channels. Volume concentrates in Tokyo, Osaka, and Nagoya metropolitan zones where vehicle density supports service infrastructure.
- Heavy-duty Trucks:Steel-carcass construction with deep-tread compounds withstands axle loads exceeding 10 tonnes on expressway corridors. Fleet operators in the Kanto logistics belt drive replacement demand through centralized procurement contracts, with downtime tolerance near zero for temperature-controlled freight specialists.
- Commercial Vehicles:Light and medium-duty configurations serve urban delivery networks with frequent stop-start duty cycles.
- Two-wheelers:Smaller-diameter bias construction dominates motorcycle fitment, with aftermarket distribution through specialized retailers.
Highest margin concentration: Heavy-duty Trucks. Steepest expansion trajectory: Commercial Vehicles.
Sales Channel:
Channel selection determines pricing transparency and installation service bundling, with fleet operators increasingly bypassing retail intermediaries for direct manufacturer relationships.
- Service Stations:Integrated tire replacement alongside scheduled maintenance captures time-constrained consumers seeking single-visit solutions. Demand concentrates along expressway service areas and urban arterial routes where convenience premiums offset higher unit pricing.
- Wholesale:Volume contracting to fleet operators and independent repair chains enables manufacturers to secure committed offtake with reduced marketing expenditure. Relationships anchor around technical support and inventory consignment rather than brand advertising.
- Retail:Dealer networks with alignment and balancing equipment serve owner-operators prioritizing immediate installation availability.
- Online:Direct-to-consumer platforms gain traction among specification-savvy buyers comparing rolling resistance grades independently.
Dominant by transaction volume: Service Stations. Gaining share fastest: Wholesale.
Application:
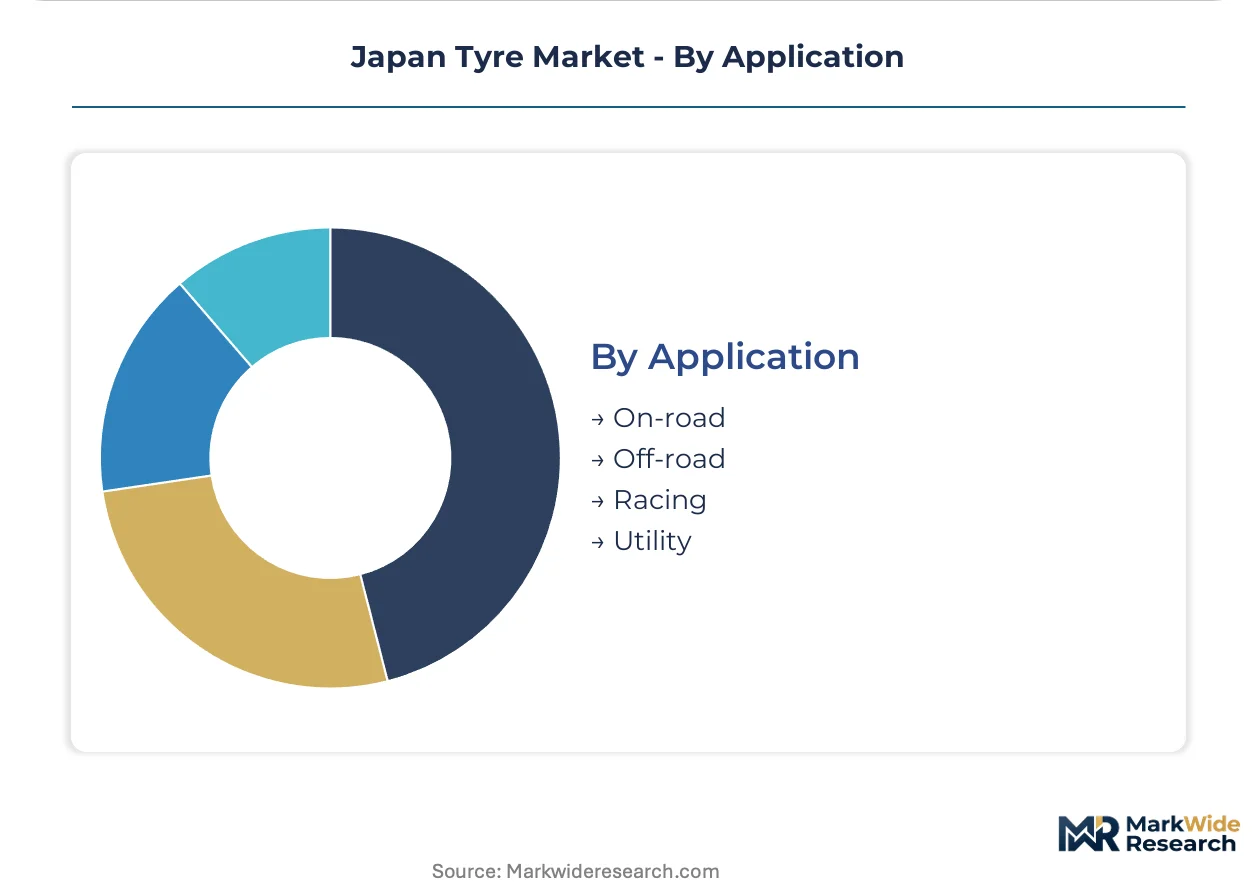
Surface conditions and duty cycle intensity dictate compound hardness and tread pattern selection, with regulatory approval pathways varying between highway-certified and specialized off-road constructions.
- On-road:Highway-optimized tread patterns with continuous center ribs minimize rolling resistance for fuel efficiency compliance. Fleet procurement in the Kanto corridor specifies these for intercity logistics routes where pavement quality supports long tread life.
- Off-road:Aggressive lug patterns with self-cleaning tread blocks maintain traction in unpaved construction and agricultural settings. Demand clusters in Hokkaido and Kyushu where forestry and farming operations require cut-resistant sidewall compounds.
- Racing:Track-specific slicks and intermediate compounds face limited homologation for street use, constraining addressable market.
- Utility:Multi-surface constructions balance on-road efficiency with occasional unpaved capability for light commercial versatility.
Highest unit volume: On-road. Climbing the fastest: Off-road.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Natural rubber import dependence on Southeast Asian suppliers shapes Japan's tyre manufacturing geography, with domestic production clustering around port access and logistics infrastructure rather than raw material sources.
Kanto/Tokyo
Expressway logistics fleets and premium vehicle OEMs drive concentrated demand across Tokyo and Yokohama. METI's fuel efficiency labeling mandates compel compound reformulation for low rolling-resistance specifications. The corridor hosts the densest concentration of tyre retail and service infrastructure nationwide.
Kansai/Osaka
Commercial vehicle operators in the Osaka metropolitan zone sustain replacement cycles through centralized procurement contracts. JIS standards enforcement maintains strict dimensional tolerance requirements for aftermarket distribution. Manufacturing facilities in the region serve both domestic and export markets through Kobe port access.
Chubu/Nagoya
Automotive OEM supply relationships anchor tyre fitment demand among Nagoya-based vehicle manufacturers. The region's industrial machinery sector generates specialized off-road tyre requirements for construction equipment. Technical services administering Ministry of Land, Infrastructure, Transport and Tourism type approvals concentrate administrative functions here.
Kyushu
Underutilized production capacity offers geographic diversification from Kanto corridor concentration risks. Natural rubber processing and compound manufacturing facilities leverage port proximity to Southeast Asian supply routes. Regional logistics networks serve agricultural and forestry equipment operators with bias-construction tyres.
Hokkaido
Forestry operations and cold-climate driving conditions sustain demand for aggressive tread patterns and cut-resistant sidewall compounds. Fleet operators in resource extraction industries prioritize durability over fuel efficiency metrics. Limited service infrastructure concentrates procurement through wholesale channels rather than retail networks.
Japan Tyre Market Key Industry Players
Capacity expansion dominates the current landscape as manufacturers reconfigure compound facilities to meet METI's rolling resistance disclosure requirements. The market structure consolidates around three domestic conglomerates with integrated manufacturing footprints, while import-dependent distributors occupy specialized niche positions. Strategic archetypes include vertically integrated compound-to-retail operators, technology licensors leveraging motorsports heritage, and regional wholesalers managing homologation complexity. Portfolio diversification and backward integration into silica-reinforced compound production represent the two dominant competitive moves.
Within the integrated manufacturing tier, Bridgestone Corporation, Yokohama Rubber Company Limited, and Sumitomo Rubber Industries Limited occupy positions defined by production scale and brand heritage rather than discrete strategic actions. Bridgestone anchors domestic capacity through its Kyushu and Kanto manufacturing presence. Yokohama exemplifies the technology-transfer archetype with motorsports-derived compound positioning. Sumitomo represents aftermarket channel loyalty strategies through heritage brand maintenance. These three entities collectively shape procurement standards for fleet operators and OEM fitment specifications.
| Leading Market Players |
|---|
| Toyo Tires & Rubber Company Limited |
| Japan Michelin Tire Co Ltd. |
| Bridgestone Corporation |
| Japan Pirelli Inc. |
| Japan Goodyear Inc. |
| Yokohama Rubber Company Limited |
| Kumho Tire Japan Inc. |
| Hankook Tire Japan |
| Sumitomo Rubber Industries Limited |
| Others |
Cost & Logistics Intelligence
Fleet operator consolidation in the Kanto corridor is compressing procurement timelines and forcing compounders to absorb certification costs, which in turn squeezes margin structures across standard-tier offerings. METI's rolling resistance disclosure mandates add compliance overhead that manufacturers must either pass through or offset via formulation efficiency gains.
Pricing Analysis
Warranty bundling separates premium from standard positioning, with run-flat and radial constructions carrying extended mileage guarantees that justify higher unit economics. Three-tier pricing structure across premium, standard, and economy levels tracks JIS certification grades and METI fuel efficiency labels. Cost compression in the economy tier is intensifying because import-dependent distributors face extended homologation timelines. Fleet operators demonstrate lowest price sensitivity due to zero-tolerance downtime policies, while independent retail channels show highest elasticity.
Supply Chain Analysis
Retread and refurbishment flows remain underdeveloped in Japan compared to European markets, creating stranded value in heavy-duty truck casings that could extend asset lifecycles. Natural rubber sourcing draws from Thailand, Indonesia, and Malaysia, with port concentration in Kyushu and Kanto. Synthetic polymer and silica filler inputs rest on petrochemical supply chains anchored in South Korea and China. Single-source vulnerability to seismic disruption in the Tokyo-Yokohama manufacturing belt threatens continuity. Distribution runs through wholesale contracting to fleet operators and service station networks for retail fragmentation.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Japan's tyre market is consolidating around compound technology capabilities and METI compliance infrastructure, with smaller import distributors facing elimination as homologation burdens mount.
For Market Incumbents: Lock in fleet procurement relationships through inventory consignment and technical service bundling that raises switching costs. Secure backward integration into silica-reinforced compound production to control formulation IP as specialist talent retires. METI's alignment with UN Regulation 117 creates compliance leverage against import-dependent competitors lacking certification infrastructure. For New Entrants and Emerging Players: Begin with underutilized Kyushu production capacity to bypass Kanto seismic concentration risks and establish geographic differentiation. Target Hokkaido forestry and agricultural equipment segments where bias-construction demand remains fragmented and brand loyalty is weaker. Pursue direct wholesale contracting to independent repair chains rather than retail channel buildout. For Investors and Strategic Acquirers: Re-rating potential sits with regional wholesalers possessing Ministry of Land, Infrastructure, Transport and Tourism type approval expertise given METI regulatory alignment extending homologation timelines. Long-term viability favors targets with captive compound formulation capabilities and established fleet relationships. Monitor Ministry certification queue lengths as early signal of import distributor distress.| Strategic Initiative | Industry Significance |
|---|---|
| Silica-Reinforced Compound Investment | Captures METI fuel efficiency tier positioning while wet grip performance gaps compress. |
| Kyushu Manufacturing Footprint Expansion | Diversifies seismic risk from Kanto concentration while leveraging Southeast Asian rubber port access. |
| Run-Flat Technology Line Extension | Addresses premium OEM weight reduction mandates with higher unit economics than standard radial. |
| Fleet Direct Contracting | Bypasses retail margin extraction while embedding through inventory consignment and technical support. |
| Retread Infrastructure Partnership | Unlocks stranded value in heavy-duty casings where Japanese refurbishment penetration lags European benchmarks. |
Research Approach
Trade association data, regulatory filings, and customs records anchored secondary inputs, supplemented by primary interviews with fleet procurement managers, compound R&D directors, independent repair chain operators, and METI standards administrators. Japan Automobile Tyre Manufacturers Association shipment statistics, Ministry of Land, Infrastructure, Transport and Tourism type approval databases, and customs import declarations provided volume and trade flow validation. Bottom-up segment sizing triangulated against top-down macroeconomic elasticity estimates.
Granularity-level modeling applied vehicle type, product construction technology, and sales channel dimensions at the prefecture level across the projection horizon. CAGRs derived from replacement cycle analysis tied to commercial fleet aging data and passenger vehicle ownership patterns. Forecast inputs incorporated METI regulatory phase-in schedules and natural rubber price elasticity assumptions from Southeast Asian supply markets.
Underlying measurement precision varies by segment; heavy-duty truck replacement cycles carry tighter precision than passenger retail fragmentation. Forecasts reflect assumptions around fleet capital expenditure recovery timelines and homologation processing speeds. Practitioners should monitor Ministry certification queue lengths and natural rubber futures volatility for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Tires and Wheels
Automotive All-Season Tire Market
Tires and Wheels
Tire Protection Chains Market
Tires and Wheels
Brazil Automotive Tire Market
Tires and Wheels
Automotive Intelligent Tires Market
Tires and Wheels
Automotive Wheel Cap Market
Tires and Wheels
Tire Building Machinery Market
Tires and Wheels
Rechargeable Tires Market
Tires and Wheels
Automotive Tire Analytics Market
Tires and Wheels
Tire Repair Patch Market
Tires and Wheels
Automotive Wheel Coating Market
Tires and Wheels
Global Pneumatic Tires Market
Tires and Wheels
North America OTR Tire Market
Tires and Wheels
North America Alloy Wheels Market
Tires and Wheels
Europe Green Tire Market
Tires and Wheels
Automotive Airless Tire Market
Tires and Wheels
Automotive Summer Tire Market