
 Commercial Vehicles Tires Market | 2026-2036
Commercial Vehicles Tires Market Size, Share, and Industry Trends Forecast 2026-2036
Commercial Vehicles Tires Market Outlook
Silica-reinforced tread compounds is repositioning commercial tire economics by cutting rolling resistance without sacrificing wear life. Michelin Group leverages captive rubber plantations and advanced mixing technology to stabilize compound costs across production cycles. Bridgestone Corporation anchors its position through integrated tire-and-sensor systems for fleet telematics. Goodyear Tire & Rubber Company competes on retreading infrastructure density, extending casing utilization for cost-sensitive operators.
Commercial vehicle tires are engineered elastomeric structures—typically incorporating steel belts, polyester or nylon carcass plies, and carbon-black or silica-loaded tread compounds—manufactured through calendering, extrusion, and vulcanization to deliver load-bearing capacity, traction, and heat dissipation under sustained highway or off-road duty. Radial tires dominate installed base value due to superior fuel economy and casing durability for multiple retread cycles, while tubeless configurations gain share in heavy-duty applications where puncture resistance and thermal management outweigh bias-ply simplicity. Fleet operators represent the most concentrated demand pool, with procurement consolidating around total-cost-of-ownership metrics rather than upfront unit price.
EPA greenhouse-gas standards and NHTSA fuel-economy regulations for medium and heavy-duty vehicles mandate measurable reductions in tire rolling resistance, directly shaping OEM fitment specifications and replacement-market product mix. ISO 28580 testing protocols for rolling-resistance measurement create cross-border compliance baselines that manufacturers must satisfy for North American and European market access. Stakeholders must monitor how California Air Resources Board phase-in timelines and pending federal trailer standards recalibrate fleet replacement schedules and premium-tier demand.
Market Dynamics
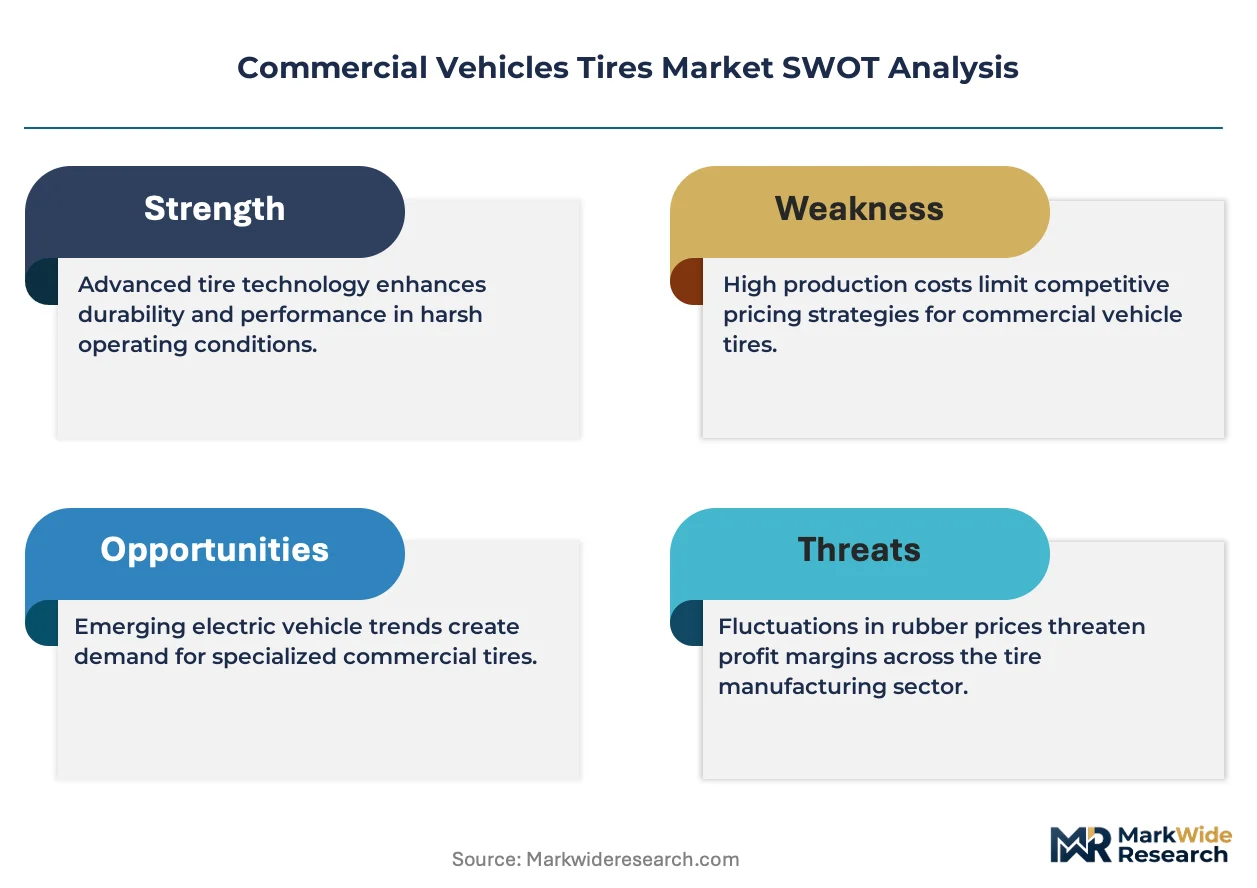
Fleet telematics integration is compressing tire replacement cycles as real-time wear monitoring enables predictive maintenance scheduling, while EPA Phase 3 greenhouse-gas standards force rolling-resistance reductions across medium and heavy-duty vehicle classes.
Growth Catalysts
- EPA Phase 3 Standards:Federal mandates for 2027 model-year trucks tighten rolling-resistance coefficients, compelling fleet-wide upgrades to low-resistance tire configurations.
- Silica Compound Advancement:Reinforced tread formulations cut fuel consumption without degrading casing durability, extending retread viability for cost-sensitive operators.
- Long-Haul Freight Densification:Interstate corridor volumes sustain replacement demand as logistics networks consolidate around hub-and-spoke distribution models.
Market Restraints
- Natural Rubber Volatility:Southeast Asian plantation output fluctuations expose compounders to input cost swings that compress margin predictability.
- Steel Belt Concentration:ArcelorMittal and Nippon Steel dominate high-tensile cord supply, creating single-source vulnerability for radial tire carcass production.
- Retread Quality Perception:Fleet skepticism toward remanufactured casing performance limits penetration in premium long-haul segments despite total-cost advantages.
Strategic Opportunities
- Autonomous Truck Integration:Self-driving freight corridors demand tires with embedded RFID sensors for continuous pressure and temperature telemetry.
- California CARB Acceleration:State-level mandates ahead of federal timelines create premium-tier demand pull for zero-emission vehicle tire specifications.
- Last-Mile Electrification:Urban delivery van electrification requires load-rated tires optimized for instant torque transmission and regenerative braking wear patterns.
Industry Challenges
- Compounder Talent Scarcity:Specialized elastomer formulation expertise is concentrating at legacy manufacturers, constraining new entrant R&D velocity.
- Vulcanization Equipment Lead Times:Press and mold capacity expansion requires 18-24 month procurement cycles, limiting supply response to demand surges.
- ISO 28580 Certification Complexity:Cross-border rolling-resistance testing protocol harmonization delays product launches in multi-jurisdictional fleet contracts.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Commercial Vehicles Tires Market |
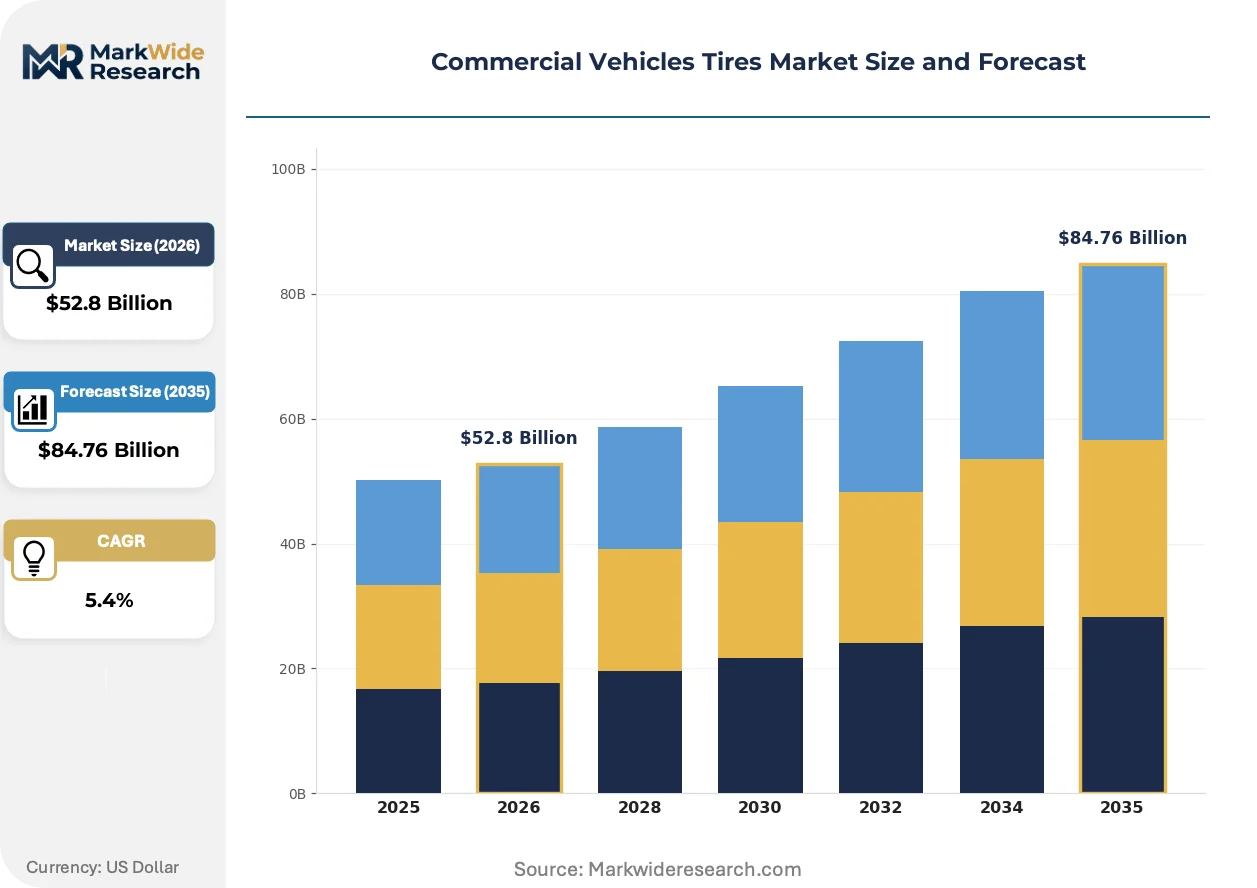
| Market Size in 2026 | $52.8 Billion |
| Market Size in 2035 | $84.76 Billion |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Radial Tires, Bias Tires, Tubeless Tires, Tube Tires End User: Fleet Operators, Logistics Companies, Construction Firms, Public Transportation Application: Medium-Duty Vehicles, Heavy-Duty Vehicles, Light-Duty Vehicles, Specialty Vehicles Distribution Channel: Online Retailers, Dealerships, Wholesalers, Service Centers |
| Companies Covered | Bridgestone Corporation, Michelin Group, Goodyear Tire & Rubber Company, Continental AG, Hankook Tire & Technology, Yokohama Rubber, Pirelli, Sumitomo Rubber Industries, Apollo Tyres, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Commercial Vehicles Tires Market Strategic Shifts
Tire intelligence systems are migrating from aftermarket accessories to factory-embedded architecture, while regulatory pressure and fleet data maturity converge to reshape product development priorities.
Sensor-integrated tire architecture is automating condition monitoring through pressure, temperature, and tread-depth telemetry transmitted to fleet management platforms. Large-scale freight operators are mandating smart-tire fitments on new tractor purchases to eliminate manual inspection labor. This automation is compressing maintenance intervals and shifting supplier relationships toward data-service subscription models.
EPA greenhouse-gas standards for medium and heavy-duty vehicles now incorporate tire rolling resistance as a certified compliance pathway alongside engine and aerodynamic improvements. Manufacturers must validate products through standardized test protocols to maintain OEM fitment eligibility. Heavy-duty line-haul segments face the steepest compliance ramps, accelerating R&D allocation toward silica-dominant tread compounds.
Fleet procurement consolidation around total-cost-of-ownership metrics is displacing unit-price contracting in long-haul replacement markets. Third-party fleet management companies now specify tire programs across thousands of vehicles, centralizing supplier selection authority. This concentration is most visible in dedicated contract carriage operations serving retail distribution networks.
Commercial Vehicles Tires Market Segmentation
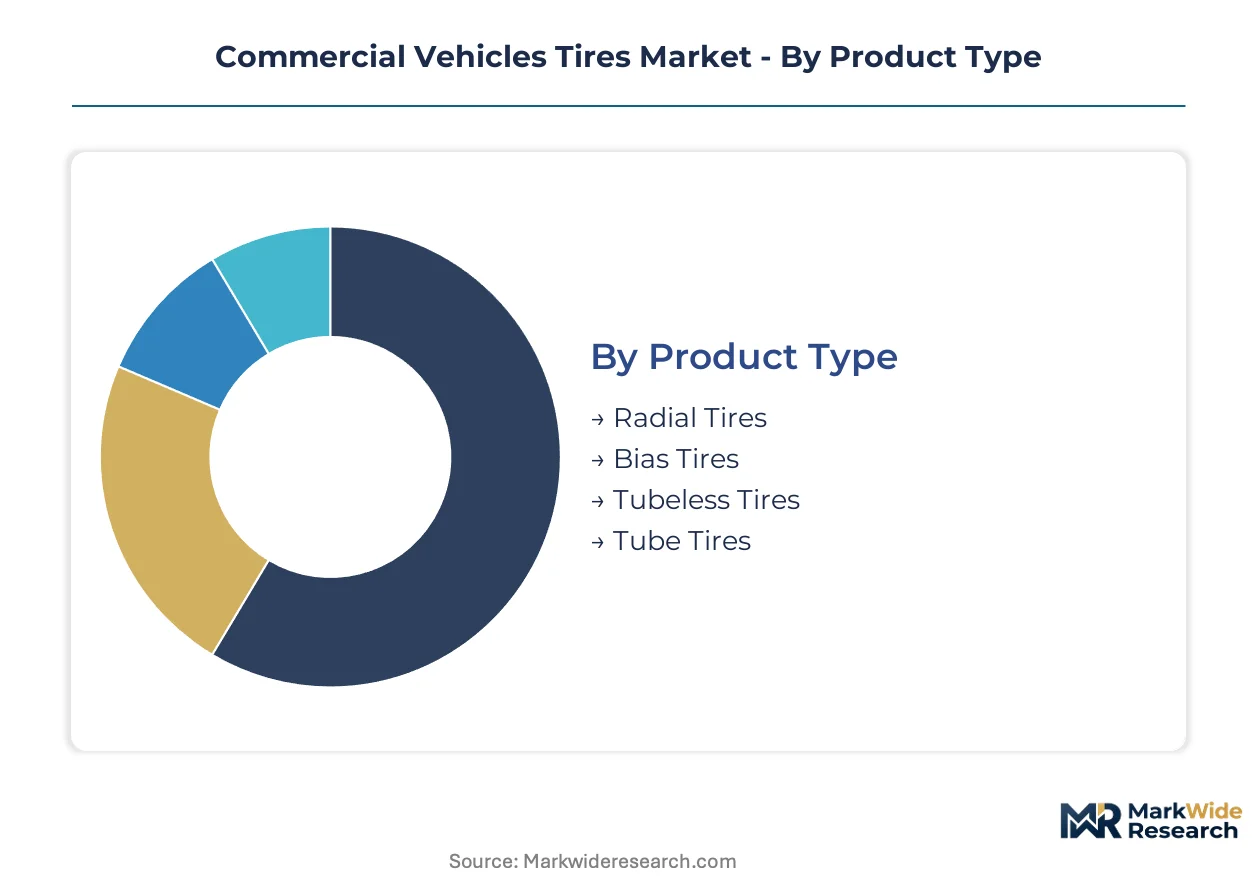
Commercial vehicle tire procurement stratifies across performance tiers, operational duty cycles, and channel economics. Fleet managers segment specifications by total-cost-of-ownership metrics rather than unit price alone, reshaping how manufacturers configure product portfolios and pricing architectures.
Product Type:
Volume concentration favors radial architectures for long-haul fuel efficiency, while premium positioning attaches to specialized constructions for extreme duty cycles.
- Radial Tires:Steel-belted radial carcasses with polyester or nylon plies deliver 15-20% fuel economy gains over bias constructions through reduced rolling resistance. Demand concentrates in United States interstate freight corridors where EPA Phase 3 compliance mandates and retread economics dominate procurement criteria.
- Bias Tires:Cross-ply nylon construction provides sidewall puncture resistance and load distribution stability for off-road and mixed-terrain applications. Construction firms and mining operators in Australia and South Africa specify bias configurations where cut resistance outweighs highway efficiency requirements.
- Tubeless Tires:Eliminate inner tubes through airtight bead-seal design, reducing weight and thermal failure risk in heavy-duty braking cycles. Adoption accelerates in European Union markets where ECE R30 certification and run-flat safety protocols drive OEM fitment.
- Tube Tires:Retain inner-tube architecture for split-rim compatibility and extreme load-rated applications in emerging-market commercial fleets. Remain specified for certain retread-restrictive vocational segments in India and Brazil.
Today's leader: Radial Tires. Tomorrow's challenger: Tubeless Tires.
End User:
Customer concentration patterns reflect operational scale economies and centralized procurement authority across freight, construction, and mobility networks.
- Fleet Operators:Large-scale dedicated contract carriage fleets with 500+ vehicle assets negotiate enterprise tire programs based on cost-per-mile analytics. United States-based retail distribution networks and refrigerated transport operators drive premium-tier silica-compound adoption through centralized specification authority.
- Logistics Companies:Third-party freight brokers and warehouse operators balance asset-light models with leased vehicle tire accountability. German and Dutch logistics clusters prioritize ISO 28580-certified rolling-resistance grades to satisfy CSRD-linked carbon reporting requirements.
- Construction Firms:Project-based equipment utilization demands puncture-resistant tread patterns and reinforced sidewalls for aggregate hauling and earthmoving. Australian and Canadian mining contractors specify severe-service compounds for 24-hour continuous duty cycles.
- Public Transportation:Municipal bus authorities and intercity coach operators prioritize wet-grip safety ratings and noise-reduction compliance over fuel efficiency. European urban transit agencies in France and Italy mandate ECE R117 labeling adherence for passenger-carrying commercial vehicles.
Procurement authority is concentrating fastest among Fleet Operators, while Construction Firms retain the most fragmented specification patterns.
Application:
Duty-cycle severity determines casing durability requirements and retread viability, creating distinct margin structures across vehicle weight classes.
- Medium-Duty Vehicles:Class 4-6 delivery trucks and urban freight vans require load-range E-F tires optimized for stop-start wear patterns and regenerative braking thermal loads. Last-mile electrification in United States metropolitan corridors drives demand for instant-torque-rated constructions.
- Heavy-Duty Vehicles:Class 7-8 tractor-trailers sustain the highest annual mileage and retread cycle frequency, making casing durability the dominant procurement factor. Long-haul operators across the Interstate highway system specify premium tread compounds to maximize second and third retread yields.
- Light-Duty Vehicles:Class 1-3 commercial pickups and van upfits demand passenger-car-derived architectures with elevated load ratings. Small-business fleet operators in India and Mexico prioritize acquisition cost over lifecycle economics in this segment.
- Specialty Vehicles:Refuse trucks, concrete mixers, and fire apparatus require application-specific tread designs for high-torque, low-speed, or debris-intensive environments. Vocational specifications in Japan and South Korea emphasize JIS-compliant durability testing for municipal procurement eligibility.
Heavy-Duty Vehicles command the deepest supplier relationships, while Specialty Vehicles present the steepest specification complexity.
Distribution Channel:
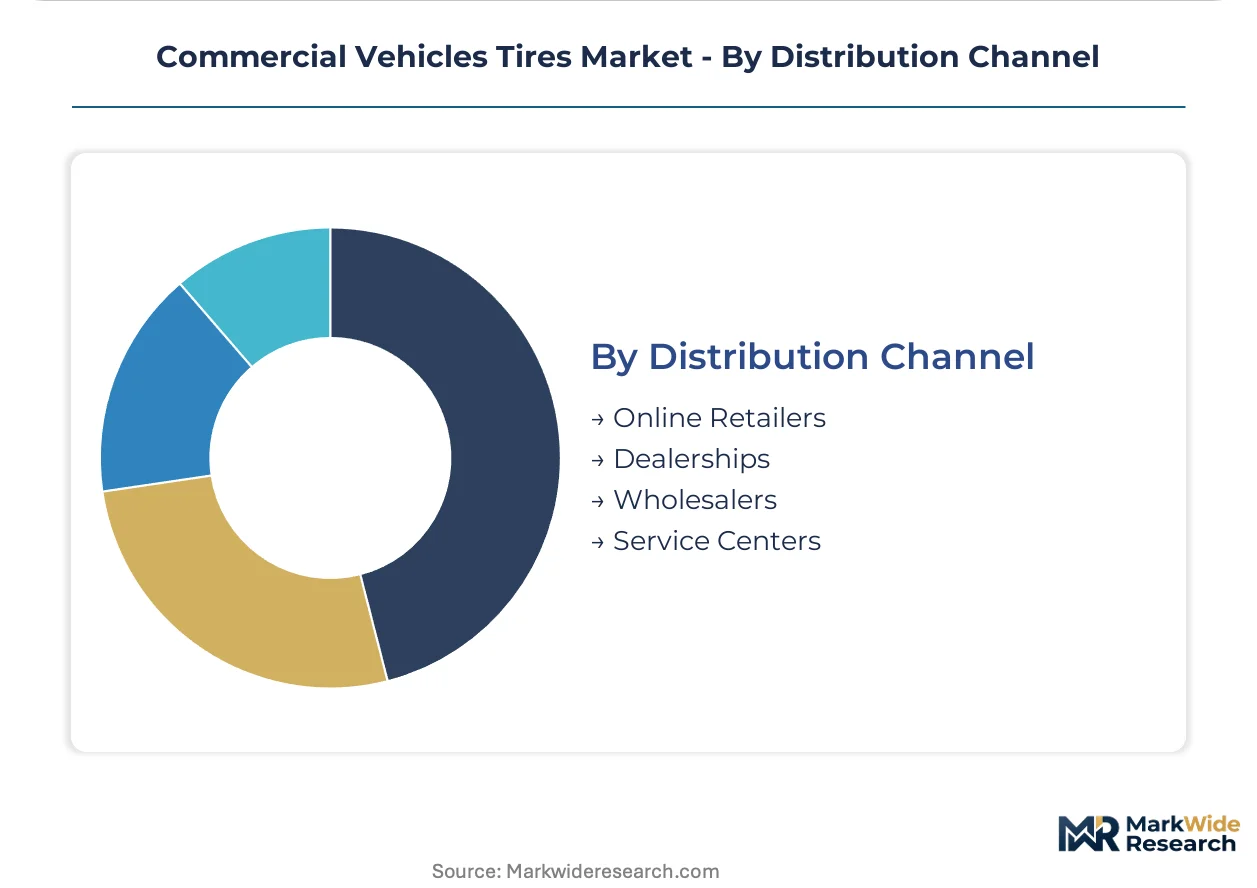
Channel economics reflect inventory carrying costs, technical service requirements, and fleet procurement centralization trends.
- Online Retailers:Digital platforms aggregate price-transparent sourcing for small fleet and owner-operator segments, though tire mounting and balancing require physical fulfillment partnerships. Growth concentrates in United States independent contractor markets where Amazon Business and specialized B2B tire portals displace traditional jobber relationships.
- Dealerships:OEM-aligned commercial truck dealers bundle tire programs with vehicle acquisition financing and warranty coverage. Paccar, Daimler Truck, and Volvo Group dealer networks in North America and Europe capture premium-tier fitment and replacement loyalty through integrated service contracts.
- Wholesalers:Regional tire distributors maintain inventory depth and credit terms for independent repair facilities and small fleet accounts. Consolidation among United States-based TireHub and NTW operations is compressing margins for secondary-tier manufacturers.
- Service Centers:National quick-service chains and mobile tire installation fleets provide roadside replacement and predictive maintenance integration. Bridgestone's Speedco and Goodyear's Fleet HQ networks in the United States embed telematics-enabled tire monitoring into subscription-based maintenance programs.
Service Centers are capturing the most fleet-telemetics-adjacent revenue, while Online Retailers face the steepest last-mile fulfillment constraints.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The United States interstate freight corridor anchors commercial tire demand through sustained long-haul replacement cycles and federal infrastructure spending. Fleet telematics adoption and EPA Phase 3 compliance deadlines are compressing procurement timelines across major freight markets.
United States
Class 8 tractor-trailer fleets along the I-10 and I-80 corridors drive premium radial tire consumption through centralized procurement programs. NHTSA fuel-economy regulations mandate rolling-resistance reductions for 2027 model-year trucks. The Dallas-Fort Worth logistics cluster sustains dense retreading infrastructure to maximize casing utilization.
Germany
Ruhr Valley freight operators and Rhine-Alpine corridor haulers prioritize ISO 28580-certified compounds for CSRD-linked carbon reporting compliance. ECE R117 labeling requirements govern bus and coach tire specifications for intercity passenger transport. Stuttgart-based commercial vehicle OEMs coordinate tire fitment standards with supplier development programs.
China
Yangtze River Delta logistics hubs and Pearl River Delta manufacturing clusters generate heavy-duty tire demand from container drayage and express freight networks. MIIT fuel-consumption limits for commercial vehicles tighten rolling-resistance thresholds for domestic truck production. Shandong Province tire manufacturing zones supply both domestic fleet replacement and export markets.
India
Maharashtra and Gujarat industrial corridors sustain medium-duty tire demand from last-mile distribution networks serving e-commerce fulfillment. BIS certification requirements for commercial vehicle tires establish minimum performance standards for domestic sales. Tamil Nadu automotive manufacturing clusters integrate tire specifications into commercial vehicle export programs.
Brazil
São Paulo state agribusiness and mining sectors specify severe-service bias and radial constructions for off-highway equipment utilization. ANVISA-equivalent transport safety regulations govern commercial vehicle tire specifications for interstate cargo operations. Minas Gerais mining contractors drive demand for cut-resistant tread compounds in 24-hour extraction cycles.
Commercial Vehicles Tires Market Competitive Environment
Global majors compete with regional champions across compound technology and fleet service infrastructure. The market structure consolidates around integrated tire-and-telemetry systems while fragmenting across price-tiered replacement segments. Three archetypes dominate: full-line multinationals with captive rubber supply, technology-focused sensor integrators, and retreading-specialized service networks. Capacity expansion and strategic partnerships represent the primary competitive moves as manufacturers secure vulcanization press availability and fleet data platform access.
Among the established multinational tier, Bridgestone Corporation, Michelin Group, and Goodyear Tire & Rubber Company anchor competitive positioning through differentiated capability emphasis. Bridgestone exemplifies the integrated tire-and-sensor archetype through fleet telematics platform development. Michelin represents compound technology leadership with captive plantation supply chain control. Goodyear occupies the service-network position through dense retreading infrastructure and mobile maintenance deployment. Each anchors a distinct vector of competitive differentiation without overlapping strategic emphasis.
| Leading Market Players |
|---|
| Bridgestone Corporation |
| Michelin Group |
| Goodyear Tire & Rubber Company |
| Continental AG |
| Hankook Tire & Technology |
| Yokohama Rubber |
| Pirelli |
| Sumitomo Rubber Industries |
| Apollo Tyres |
| Others |
Value Chain & Pricing Dynamics
Silica-reinforced compound migration is compressing manufacturing cost curves while concentrating formulation expertise at legacy manufacturers with captive rubber supply. This dual effect simultaneously elevates R&D entry barriers and reshapes procurement economics across fleet operator segments.
Pricing Analysis
Natural rubber and carbon black cost pass-through dominates pricing volatility, with compounders indexing contracts to Singapore Exchange futures to stabilize margin predictability. Three-tier pricing structure across premium, standard, and economy levels separates EPA-certified low-rolling-resistance grades from basic replacement tiers and retread-restrictive vocational specifications. Price differentiation hinges on ISO 28580 certification attainment and fleet telematics bundling. Margins are tightening in economy tiers due to Southeast Asian import competition, while premium segments show lowest price sensitivity among telematics-integrated fleet operators.
Supply Chain Analysis
Direct-to-OEM channels handle hyperscale fleet procurement through integrated tire-and-service contracts, while independent wholesalers serve fragmented owner-operator demand. Manufacturing concentrates in Thailand, Indonesia, and China for natural rubber proximity and vulcanization scale. Steel cord draws from ArcelorMittal and Nippon Steel mills, creating single-source vulnerability for radial carcass production. Tariff exposure on Southeast Asian tire imports into the United States represents the dominant supply chain risk. Distribution runs through regional wholesalers, OEM-aligned dealerships, and emerging B2B digital platforms.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The commercial vehicle tire market reads as a late-cycle quality story as EPA Phase 3 compliance deadlines pull fleet procurement toward certified low-rolling-resistance specifications. Premium-tier compound technology is displacing unit-price contracting across consolidated fleet accounts.
For Market Incumbents: Lock in compound formulation advantages through backward integration into rubber plantation assets and advanced mixing technology. Secure vulcanization press capacity with 18-24 month lead times to constrain competitor supply response. Prioritize fleet telematics platform integration to defend against sensor-integrated tire challengers. For New Entrants and Emerging Players: Capture last-mile electrification demand in United States metropolitan corridors where instant-torque-rated tire specifications lack established supply relationships. Target medium-duty delivery van segments where regenerative braking wear patterns create specification white space. Pursue direct digital distribution partnerships with Amazon Business and specialized B2B tire portals to bypass entrenched wholesaler relationships. For Investors and Strategic Acquirers: Roll-up economics work for regional retreading service networks because fleet telematics adoption compresses maintenance intervals and centralizes supplier relationships around data-enabled providers. Five-to-ten year viability favors platforms with embedded sensor architecture and subscription-based maintenance programs. Watch California CARB acceleration timelines as inflection indicators for premium-tier demand pull ahead of federal mandates.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Rubber Supply | Michelin's captive plantation model stabilizes compound costs against Singapore Exchange volatility. |
| Fleet Telematics Platform Development | Bridgestone's sensor-integrated architecture automates predictive maintenance for large-scale operators. |
| Retreading Infrastructure Expansion | Goodyear's Speedco network maximizes casing utilization through mobile installation capabilities. |
| ISO 28580 Certification Investment | Cross-border rolling-resistance protocol harmonization secures OEM fitment eligibility across EPA and ECE jurisdictions. |
| Digital B2B Channel Partnership | Online platform aggregation displaces traditional jobber relationships in owner-operator segments. |
Study Parameters
Bottom-up fleet operator demand modeling reconciled against top-down tire production tracking forms the analytical core of this study. Primary interviews with fleet procurement directors, commercial vehicle OEM platform engineers, tire compound R&D leads, and aftermarket service network managers combined with secondary validation from EPA regulatory filings, NHTSA fuel-economy rulemakings, customs trade data, and SEC 10-K disclosures from listed manufacturers. Triangulation between demand-side fleet telematics adoption curves and supply-side vulcanization capacity expansion schedules ensures cross-verified output integrity.
Input-output matrix framing connects vehicle-mileage projections, retread cycle frequency assumptions, and replacement-rate elasticities across the analysis window. Segmentation dimensions modeled include product architecture, vehicle weight class, operational duty cycle, distribution channel, and regional regulatory cluster. CAGRs derive from elasticity-adjusted replacement demand curves and OEM fitment specification trajectories. Industry-specific forecast inputs incorporate EPA Phase 3 compliance ramp schedules and silica compound penetration rates.
Natural rubber price volatility, steel cord supply disruption, and fleet telematics adoption deceleration are the dominant revision risks to baseline projections. Forecasts reflect assumptions regarding regulatory timeline adherence, compound technology maturation, and channel consolidation velocity. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Tires and Wheels
Europe Agricultural Tires Market
Tires and Wheels
Automotive Wheel Coating Market
Tires and Wheels
Steel Tire Cord Market
Tires and Wheels
All Weather Tire Market
Tires and Wheels
South Korea Automotive Carbon Wheels Market
Tires and Wheels
Bus Radial Tire Market
Tires and Wheels
Tire Inflating Machine Market
Tires and Wheels
Automotive Carbon Wheels Market
Tires and Wheels
Rail Road Wheels Market
Tires and Wheels
Europe Aircraft Tires Market
Tires and Wheels
Tire Cord Market
Tires and Wheels
Global Winter Tires Market
Tires and Wheels
Wheel Cover Market
Tires and Wheels
Wheel Spacers and Adapters Market
Tires and Wheels
Civil Aircraft Tire Market
Tires and Wheels
Global Automotive Tires Market