
 Kuwait Tyres Market | 2026-2036
Kuwait Tyres Market Size, Share, and Industry Trends Forecast 2026-2036
Kuwait Tyres Market Outlook
Silica compounds are rebalancing tread formulations across premium tyre lines as manufacturers reduce rolling resistance without sacrificing wet grip. Bridgestone Corporation leverages its proprietary NanoPro-Tech compound platform to sustain performance differentiation in the passenger car segment. Hankook Tire & Technology Co., Ltd. anchors its regional position through dedicated SUV and light truck fitments tailored to Gulf climate conditions.
Kuwait tyres are composite structures of natural and synthetic rubber reinforced with steel belts, textile plies, and chemical additives, manufactured through calendering, extrusion, and vulcanization processes to provide load-bearing, shock-absorbing contact between vehicles and road surfaces. Radial construction dominates original equipment fitments due to superior fuel efficiency and tread life, while the run-flat technology segment is gaining traction among luxury vehicle owners seeking mobility assurance. The commercial vehicle category commands concentrated margin pools because fleet operators prioritize total cost of ownership over upfront purchase price.
Kuwait's Public Authority for Industry administers Gulf Standardization Organization conformity assessment protocols, while the Ministry of Commerce and Industry monitors import licensing and anti-dumping enforcement. These frameworks compel distributors to maintain certified stock and documentation trails, filtering out uncertified suppliers. Stakeholders must track enforcement intensity at Kuwait's Shuwaikh and Shuaiba port entry points.
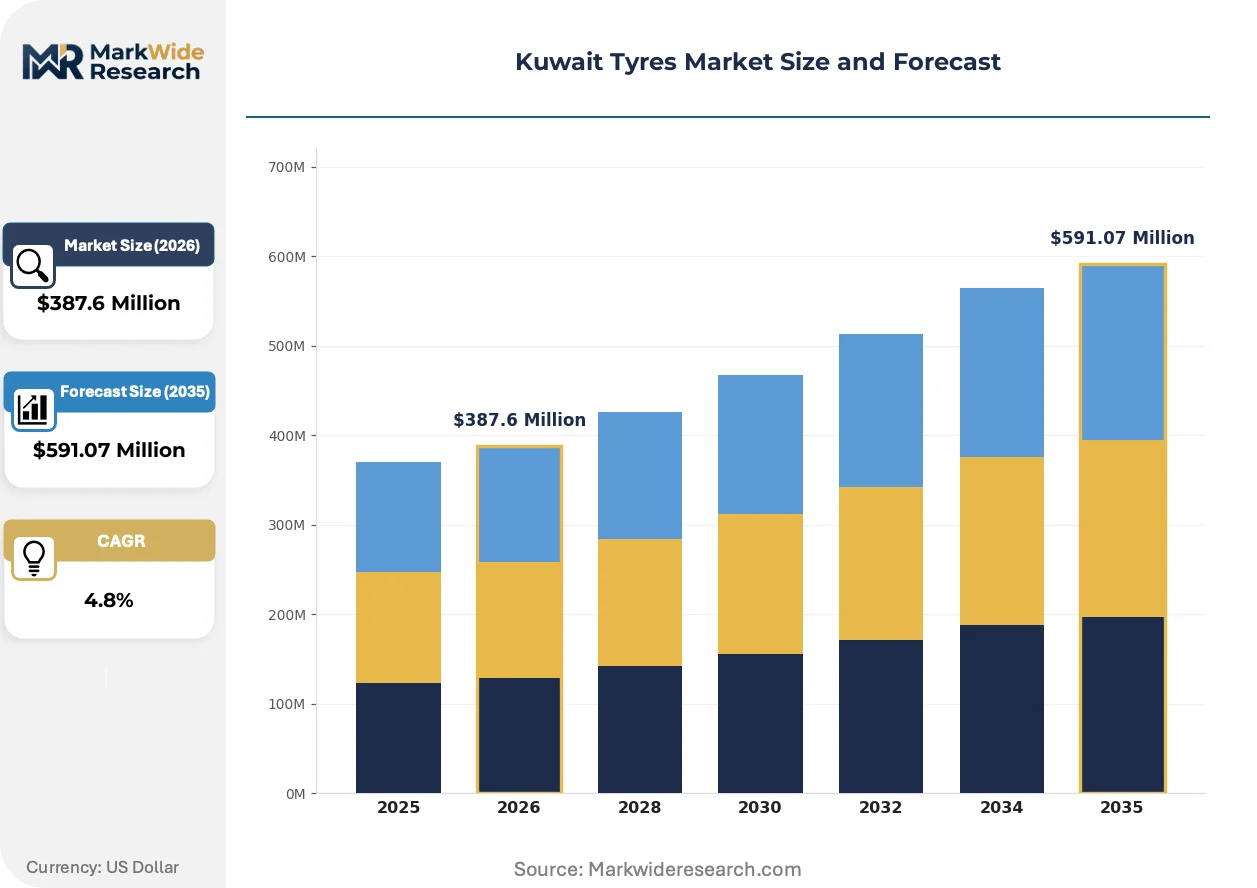
Market Dynamics
Fleet operators in Kuwait's logistics corridor are consolidating procurement volumes, reshaping distributor relationships and compressing replacement cycles for commercial-grade radial tyres.
Growth Catalysts
- GSO Certification Mandates:Kuwait's Public Authority for Industry enforces Gulf Standardization Organization conformity protocols, filtering uncertified suppliers and elevating compliant distributors.
- Silica Compound Adoption:Tread formulations incorporating silica compounds reduce rolling resistance while preserving wet grip, pulling premium segment demand.
- Logistics Fleet Expansion:Transport operators across Kuwait City industrial zones are expanding vehicle counts, concentrating replacement tyre procurement into fewer, larger contracts.
Market Restraints
- Synthetic Rubber Price Volatility:Petrochemical feedstock fluctuations compress margin pools for distributors holding inventory across extended replacement cycles.
- Port Concentration Risk:Shuwaikh and Shuaiba entry points handle the majority of certified tyre imports, creating single-point vulnerability for supply continuity.
- Run-Flat Technical Limitations:Reinforced sidewall constructions impose ride-quality trade-offs that constrain adoption beyond luxury passenger segments.
Strategic Opportunities
- Jahra Governorate Penetration:Agricultural and construction vehicle fleets in western Kuwait remain underserved by premium radial distributors.
- Digital Fleet Management Integration:Tyre pressure monitoring systems linked to telematics platforms enable predictive replacement scheduling for commercial operators.
- Retreading Regulatory Tailwinds:Gulf Standardization Organization protocols for remanufactured tyres create certified pathways for cost-conscious fleet procurement.
Industry Challenges
- Vulcanization Technician Scarcity:Specialized repair and retreading skills are concentrated among aging workforce cohorts, constraining service network expansion.
- GSO Certification Timeline Compression:Documentation and testing requirements for new product lines extend stock-to-shelf intervals, tying up working capital.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Kuwait Tyres Market |
| Market Size in 2026 | $387.6 Million |
| Market Size in 2035 | $591.07 Million |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Passenger Car, SUV, Light Truck, Commercial Vehicle Feature: All-Season, Performance, Off-Road, Eco-Friendly Technology: Radial, Bias, Run-Flat, Tubeless Sales Channel: Online Retail, Dealerships, Wholesale, Distributors |
| Companies Covered | Continental AG, Hankook Tire & Technology Co., Ltd., Bridgestone Corporation, Sumitomo Rubber Industries, Ltd., Yokohama Rubber Co., Ltd., Michelin Group, Pirelli & C. S.p.A., Toyo Tire Corporation, Goodyear Tire & Rubber Company, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Kuwait Tyres Market Strategic Shifts
Material science advances and compliance automation are redefining product differentiation and procurement workflows across Kuwait's tyre distribution channels.
Silica-silane coupling systems are overtaking conventional carbon-black tread compounds in premium passenger fitments. Luxury vehicle owners in Kuwait City metropolitan showrooms specify these formulations for reduced fuel consumption. The shift is compressing demand for legacy compound categories at the upper price tier.
Gulf Standardization Organization conformity assessment protocols now require digital traceability from manufacturing batch through port clearance. Kuwait's Public Authority for Industry has mandated documentation systems that track tyre origin, testing date, and certification validity. Commercial distributors are responding by integrating inventory management platforms that flag expiry dates and automate reorder triggers.
Fleet operators are unbundling tyre procurement from vehicle acquisition contracts, creating standalone replacement agreements with specialized distributors. Transport companies in Kuwait's logistics corridor now negotiate multi-year supply frameworks separate from original equipment purchases. This pattern concentrates volume with distributors holding certified stock and service capabilities across the Jahra-Ahmadi industrial axis.
Kuwait Tyres Market Segmentation
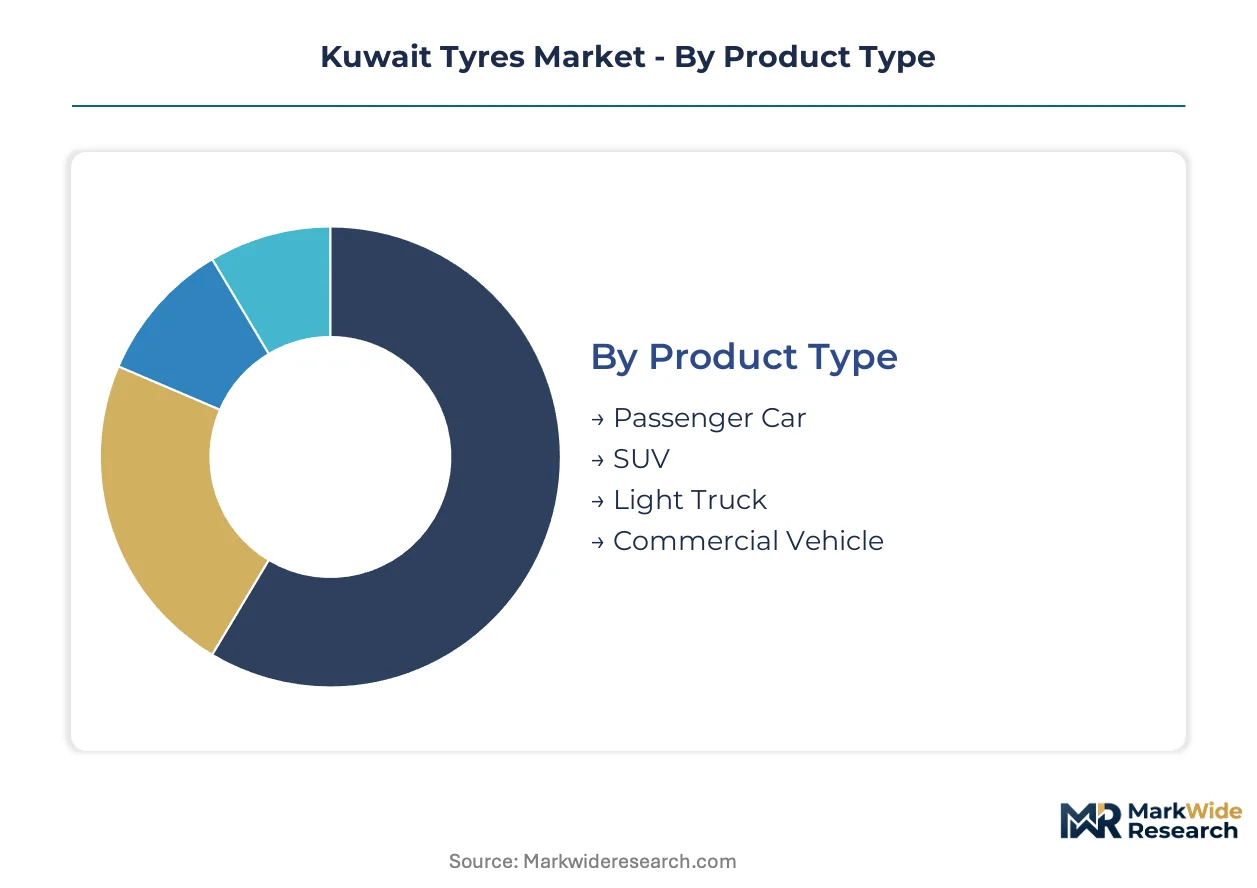
Tyre procurement patterns in Kuwait diver sharply across vehicle categories and operational intensity. Fleet operators prioritize total cost of ownership calculations, while individual buyers respond to climate-specific performance claims and GSO certification visibility.
Product Type:
Purchase volume correlates directly with fleet size and vehicle utilization rates across Kuwait's logistics corridor.
- Passenger Car:Radial constructions with silica-enhanced tread compounds dominate original equipment fitments. Kuwait City showroom traffic concentrates replacement demand among luxury sedan owners seeking wet-grip assurance during winter months.
- SUV:Reinforced sidewall specifications address high-load conditions common on Jahra Governorate agricultural routes. Hankook Tire anchors regional positioning through dedicated SUV fitments engineered for Gulf temperature extremes.
- Light Truck:Commercial operators in the Ahmadi industrial zone specify these for mixed-load duties spanning construction materials and perishable goods.
- Commercial Vehicle:Fleet procurement consolidation favors radial designs with extended tread-life warranties; total cost of ownership calculations override upfront price sensitivity.
Volume sits with Commercial Vehicle; growth tilts toward SUV.
Feature:
Climate exposure and road surface variety determine feature selection across Kuwait's driving environments.
- All-Season:Tread formulations balance wet and dry performance for urban commuters navigating Kuwait City's mixed highway and arterial networks.
- Performance:Low-profile constructions with enhanced cornering stiffness attract luxury vehicle owners; silica-silane coupling systems reduce rolling resistance without sacrificing grip.
- Off-Road:Deep-lug patterns serve construction and agricultural fleets operating on unpaved surfaces west of Jahra.
- Eco-Friendly:Low-rolling-resistance compounds align with fleet sustainability reporting requirements; adoption concentrates among logistics operators with documented carbon targets.
All-Season commands current volume; Eco-Friendly specifications are expanding most quickly.
Technology:
Structural design choices reflect the trade-off between repairability, weight, and mobility assurance under Kuwait's regulatory framework.
- Radial:Steel-belted constructions with perpendicular ply orientation deliver superior fuel efficiency and tread life. Original equipment fitments across Kuwait City dealerships favor this architecture.
- Bias:Cross-ply designs retain niche demand for heavy-load agricultural applications where sidewall puncture resistance outweighs rolling resistance penalties.
- Run-Flat:Reinforced sidewall constructions enable continued mobility after pressure loss; adoption concentrates among luxury passenger segments despite ride-quality trade-offs.
- Tubeless:Self-sealing liner technologies reduce roadside failure frequency; fleet operators across the Shuwaikh logistics corridor specify these for downtime minimization.
Radial technology holds installed base dominance; Run-Flat specifications gain share fastest among premium buyers.
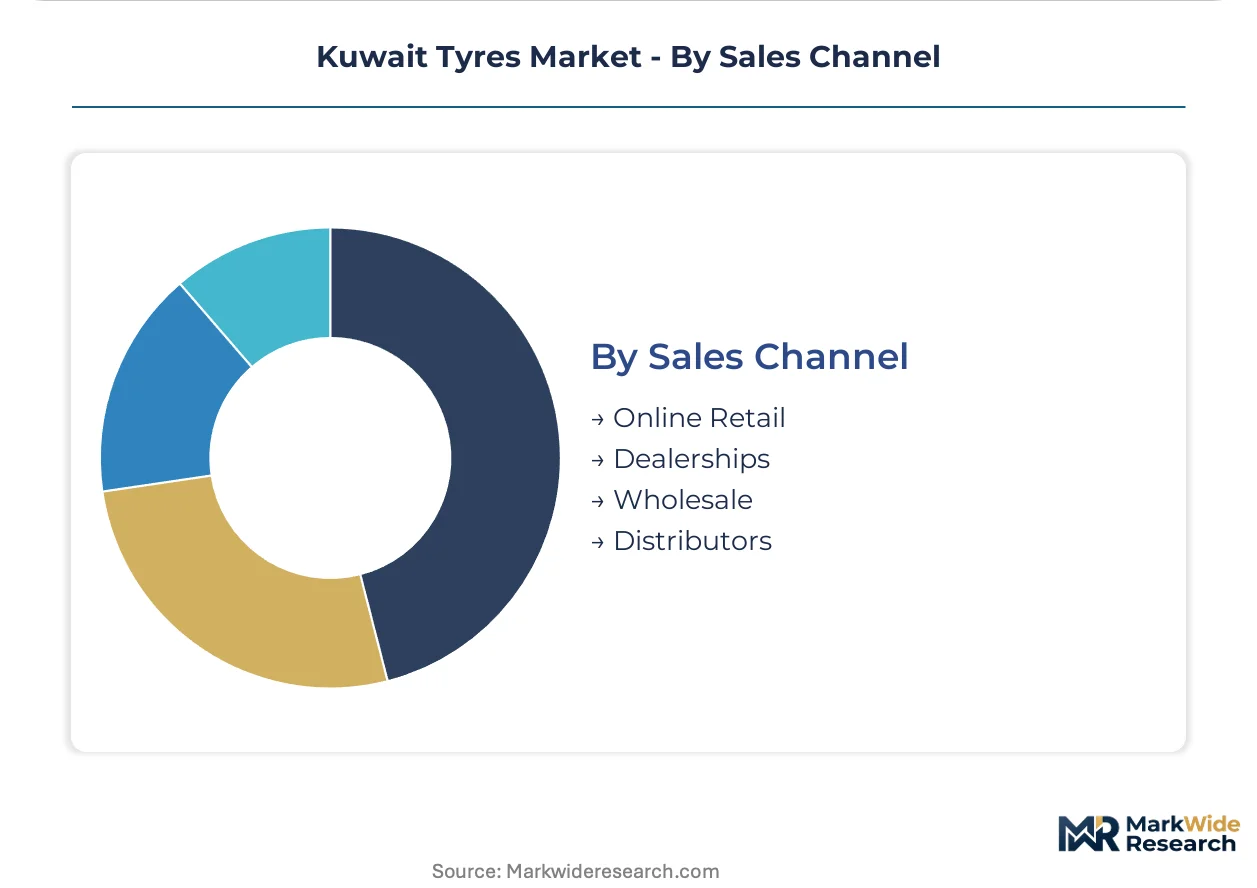
Sales Channel:
Procurement pathway selection tracks buyer scale, technical support requirements, and GSO certification verification needs.
- Online Retail:Digital platforms serve price-sensitive individual buyers with standardized fitments; certification documentation visibility remains a conversion friction point.
- Dealerships:Authorized channels bundle original equipment replacement with warranty continuity; Kuwait City metropolitan showrooms concentrate this traffic.
- Wholesale:Volume aggregators supply independent fitters across secondary governorates; inventory depth determines competitive position.
- Distributors:Certified stockholders with GSO documentation capabilities capture consolidated fleet contracts along the Jahra-Ahmadi industrial axis.
Distributors command commercial volume; Online Retail shows steepest expansion trajectory among individual replacement buyers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Replacement tyre procurement concentrates heavily in Kuwait City and its surrounding industrial corridors, with logistics fleet operators driving volume consolidation across the metropolitan area.
Kuwait City Metropolitan Corridor
Luxury vehicle owners and commercial fleet operators dominate replacement demand in Kuwait City's showroom districts. The Public Authority for Industry enforces Gulf Standardization Organization certification at Shuwaikh port entry points. Jahra-Ahmadi industrial zones host concentrated distributor networks serving logistics and construction vehicle fleets.
Jahra Governorate
Agricultural and construction vehicle fleets generate underserved demand for heavy-duty radial and off-road specifications. The Public Authority for Industry monitors GSO compliance for retreaded tyres entering western Kuwait supply chains. Unpaved routes west of Jahra sustain bias-ply demand where sidewall puncture resistance outweighs fuel efficiency priorities.
Al-Ahmadi Industrial Zone
Petrochemical and logistics operators specify commercial-grade radials with extended tread-life warranties. Ministry of Commerce and Industry import licensing requirements filter distributor eligibility at Shuaiba port. Fleet procurement consolidation favors certified stockholders with multi-year supply frameworks and service capabilities.
Hawalli Governorate
Residential vehicle owners prioritize all-season and performance fitments for urban commuting patterns. The Public Authority for Industry mandates digital traceability documentation through retail channels. Showroom traffic concentrates replacement demand among sedan owners seeking wet-grip assurance during winter months.
Al-Farwaniya Governorate
Mixed commercial-residential demand supports independent fitters and wholesale volume aggregators. GSO certification visibility remains a conversion friction point for price-sensitive buyers accessing digital retail platforms. Secondary distributor networks serve vehicle owners across the governorate's arterial highway connections.
Kuwait Tyres Market Competitive Environment
Portfolio diversification dominates the current landscape as manufacturers calibrate tread formulations and construction types to Gulf climate conditions. The vendor base organizes around three strategic archetypes: integrated compound innovators, regional climate specialists, and scale-driven volume suppliers. Technology licensing and certified distribution partnerships constitute the primary competitive moves, with distributors vying for consolidated fleet contracts along industrial corridors.
Among compound technology specialists, Bridgestone Corporation and Continental AG exemplify the premium-tier vector where proprietary silica-silane systems reduce rolling resistance. Hankook Tire & Technology Co., Ltd. occupies a position as a regional climate specialist, anchoring positioning through SUV and light truck fitments engineered for temperature extremes. These three entities represent distinct strategic postures within a market where GSO certification capabilities and service network density determine competitive outcomes.
| Leading Market Players |
|---|
| Continental AG |
| Hankook Tire & Technology Co., Ltd. |
| Bridgestone Corporation |
| Sumitomo Rubber Industries, Ltd. |
| Yokohama Rubber Co., Ltd. |
| Michelin Group |
| Pirelli & C. S.p.A. |
| Toyo Tire Corporation |
| Goodyear Tire & Rubber Company |
| Others |
Value Chain & Pricing Dynamics
Backward integration into synthetic rubber feedstocks anchors pricing power for manufacturers serving Kuwait's certified tyre market, while distributors without captive compound supply face compressed margins during petrochemical volatility cycles. This structural asymmetry concentrates margin retention with integrated producers and forces independent distributors toward volume-based procurement consolidation.
Pricing Analysis
Volume concentrates in commercial vehicle radials where fleet operators negotiate multi-year contracts with thin margins; premium passenger segments retain wider spreads through silica-compound differentiation and GSO certification premiums. Price differentiation hinges on Gulf Standardization Organization compliance tier and after-sales service bundling, with certified stockholders commanding measurable premiums over uncertified competitors. Pricing pressure stems from synthetic rubber cost volatility tied to naphtha feedstock fluctuations, compressing distributor margins during inventory holding periods. Fleet procurement managers exhibit lowest price sensitivity due to total cost of ownership calculations, while individual retail buyers through digital channels show highest elasticity.
Supply Chain Analysis
Natural rubber supply rests on Thai and Indonesian plantation output, while synthetic rubber polymerization feeds from South Korean and Japanese petrochemical complexes. Steel cord reinforcement draws from Chinese metallurgical producers, and silica filler sources from European specialty chemical manufacturers. Single-source vulnerability concentrates at Kuwait's Shuwaikh and Shuaiba port entry points, where GSO certification processing creates clearance bottlenecks. Distribution runs through certified stockholders with bonded warehouse capabilities, serving fleet operators along the Jahra-Ahmadi industrial corridor.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Kuwait's tyre market reads as supply-constrained through GSO certification bottlenecks at port entry points, where documentation timelines prop pricing for compliant distributors holding certified inventory.
For Market Incumbents: Lock in fleet procurement consolidation by expanding bonded warehouse capacity at Shuwaikh port and embedding tyre pressure monitoring telemetry into multi-year service contracts. Synthetic rubber price volatility threatens margin stability; backward integration into compound formulation or long-term offtake agreements with Thai natural rubber suppliers reduces feedstock exposure. For New Entrants and Emerging Players: GSO certification protocols for retreaded tyres in Kuwait open a window for specialized remanufacturing operations targeting cost-conscious construction fleets in Jahra Governorate. White-space sits in digital fleet management platforms linking telematics to predictive replacement scheduling; penetrate through partnerships with logistics operators seeking downtime minimization rather than tyre-only supply. For Investors and Strategic Acquirers: Exit pathways concentrate in trade sales to regional distributors seeking certified stockholder status and service network density. Five-to-ten-year viability favors acquirers of distributors with GSO documentation capabilities and established fleet relationships along the Kuwait City industrial corridor. Monitor enforcement intensity at Shuwaikh port as inflection signal for compliant inventory valuation premiums.| Strategic Initiative | Industry Significance |
|---|---|
| GSO Certification Investment | Digital traceability systems satisfy Kuwait's Public Authority for Industry mandates and accelerate port clearance timelines. |
| Silica Compound R&D Partnership | Collaboration with Japanese specialty chemical producers secures low-rolling-resistance formulations for premium passenger fitments. |
| Fleet Telematics Integration | Tyre pressure monitoring platforms enable predictive replacement contracts with logistics operators across the Ahmadi industrial zone. |
| Retreading Facility Certification | GSO-compliant remanufacturing capacity captures cost-sensitive demand from agricultural and construction vehicle fleets. |
| Port-Adjacent Warehouse Expansion | Bonded storage at Shuwaikh reduces stock-to-shelf intervals and supports consolidated procurement volumes from fleet operators. |
Study Parameters
Multi-period observation of import volumes, GSO certification issuance rates, and fleet procurement contract structures anchored the trend analysis, supplemented by interviews with commercial vehicle fleet managers, tyre distributor operations heads, Public Authority for Industry compliance officers, and logistics procurement directors. Secondary validation drew from Kuwait's Ministry of Commerce and Industry trade statistics, Gulf Standardization Organization technical bulletins, customs entry records at Shuwaikh and Shuaiba ports, and petrochemical feedstock pricing indices. Bottom-up segment sizing triangulated against top-down market value estimates derived from distributor revenue disclosures.
Segment-weighting across vehicle category, technology type, and sales channel dimensions informed the analytical framework, with passenger car, SUV, light truck, and commercial vehicle splits calibrated against fleet size data and replacement cycle frequencies. CAGRs were derived from regression analysis of historical procurement patterns projected across the analysis window, incorporating silica compound adoption curves, retreading penetration assumptions, and digital fleet management integration rates as industry-specific inputs.
The model assumes a particular technology adoption path; alternative pathways for run-flat and self-sealing liner technologies would alter the outlook if ride-quality trade-offs resolve faster than baseline assumptions. Forecasts reflect documented assumptions regarding GSO enforcement intensity, synthetic rubber price stability, and fleet operator consolidation behavior. A small set of triggers—port clearance automation investments, retreading regulatory amendments, and telematics platform standardization—warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Tires and Wheels
Tire Carousel Market
Tires and Wheels
Southeast Asian Tire Market
Tires and Wheels
Smart Tire Market
Tires and Wheels
Europe Agricultural Tires Market
Tires and Wheels
Two Wheeler Tire Market
Tires and Wheels
E-Bike Tire Market
Tires and Wheels
Re-Tread Tires Market
Tires and Wheels
Tire Protection Chains Market
Tires and Wheels
Automotive Carbon Wheels Market
Tires and Wheels
Automotive Winter Tire Market
Tires and Wheels
Rolling Stock Wheel Market
Tires and Wheels
North Commercial Vehicle Tire Pressure Monitoring Systems Market
Tires and Wheels
Racing Tires Market
Tires and Wheels
Bike Wheels Market
Tires and Wheels
Alloy Wheels Market
Tires and Wheels
Ground Support Equipment Tires Market