
 Wheat & Rice Flour Substitute-Resistant Starch Market | 2026-2036
Wheat & Rice Flour Substitute-Resistant Starch Market Size, Share, and Industry Trends Forecast 2026-2036
Wheat & Rice Flour Substitute-Resistant Starch Market Analytics
The capital-intensity divergence between integrated wet-millers and specialty ingredient houses is reorganizing competitive dynamics in resistant starch supply. Tate & Lyle leverages its British manufacturing footprint to sustain consistent supply to European bakery chains. Ingredion anchors its position through deep corn wet-milling integration across Midwestern US facilities. Cargill, Incorporated competes by controlling origination-to-ingredient pipelines that buffer raw material volatility.
Wheat and rice flour substitute-resistant starch comprises retrograded or chemically modified amylose-rich fractions that resist enzymatic digestion in the small intestine, typically delivering 60-85% total dietary fiber content on a dry basis. Manufacturers produce these starches through heat-moisture treatment, enzymatic debranching, or acid hydrolysis to achieve specific resistant starch type classifications for clean-label applications. Modified starches currently dominate value capture due to their tailored functionality in high-moisture systems like sauces and dairy products, while native starches attract premium positioning in organic baked goods where processors limit additive declarations. Specialty starches represent the fastest-growing category as formulators seek dual-function ingredients that simultaneously replace wheat flour and deliver fermentable fiber for gut health positioning.
FDA dietary fiber guidance, EU EFSA health claim frameworks, and USDA organic certification requirements collectively determine which resistant starch variants achieve qualified health claims and clean-label status in their respective jurisdictions. The FDA's isolated or synthetic fiber assessment process directly filters which resistant starch structures manufacturers can deploy in US-positioned products bearing fiber content claims. Stakeholders must monitor evolving regulator positions on novel resistant starch types and corresponding substantiation requirements before committing capacity expansion decisions.
Market Dynamics
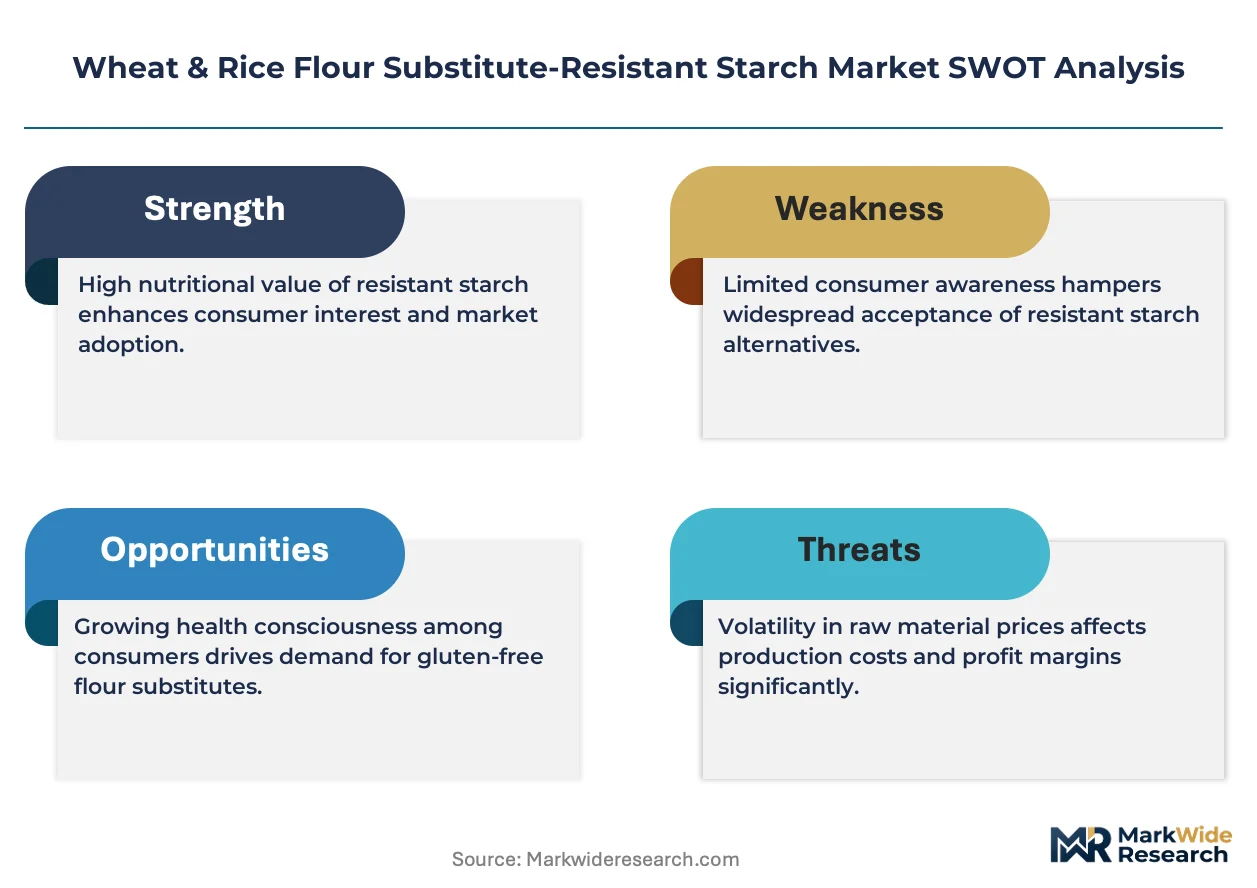
The FDA's 2023 isolated fiber guidance is restructuring which resistant starch variants qualify for dietary fiber claims, forcing manufacturers to revalidate ingredient portfolios and redirect R&D spending toward enzymatically debranched starches that meet the new substantiation threshold.
Growth Catalysts
- Clean-label bakery demand:Gluten-free bread and pastry manufacturers are accelerating resistant starch incorporation to achieve dual fiber-replacement functionality without additive declarations.
- Type 3 resistant starch retrogradation:Heat-moisture treatment technologies now enable native starch modification without chemical intervention, satisfying organic certification pathways.
- US gut health positioning:Fermentable fiber claims in digestive wellness products are pulling modified resistant starch volumes into functional food formulations.
Market Restraints
- Input cost volatility:Corn and wheat starch feedstock prices fluctuate with Midwestern US agricultural commodity cycles, compressing margin predictability for non-integrated processors.
- Supply concentration risk:Wet-milling capacity clusters in the US Corn Belt and European port corridors, creating geographic vulnerability to weather and logistics disruptions.
- FDA fiber qualification friction:The isolated or synthetic fiber assessment process delays new resistant starch type approvals, extending time-to-market for novel structures.
Strategic Opportunities
- India bakery modernization:Traditional wheat-heavy flatbread producers are exploring resistant starch partial substitution to address rising diabetes prevalence and FSSAI fiber fortification guidance.
- EU EFSA health claim convergence:The 13.5 health claim framework for bowel function creates a regulatory tailwind for resistant starch types with validated fermentability data.
- Pasta and noodle reformulation:Extruded durum wheat products represent an emerging application where resistant starch maintains texture while reducing glycemic load.
Industry Challenges
- Enzymology talent scarcity:Formulation chemists with amylose retrogradation expertise are concentrated at legacy wet-millers, limiting specialty ingredient house expansion.
- Organic certification timelines:USDA National Organic Program compliance for enzymatic processes extends 18-24 months, delaying clean-label product launches.
- Legacy equipment retrofit costs:Conventional starch processing lines require heat-moisture reactor installation to produce Type 3 resistant starch, demanding significant capital redeployment.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Wheat & Rice Flour Substitute-Resistant Starch Market |
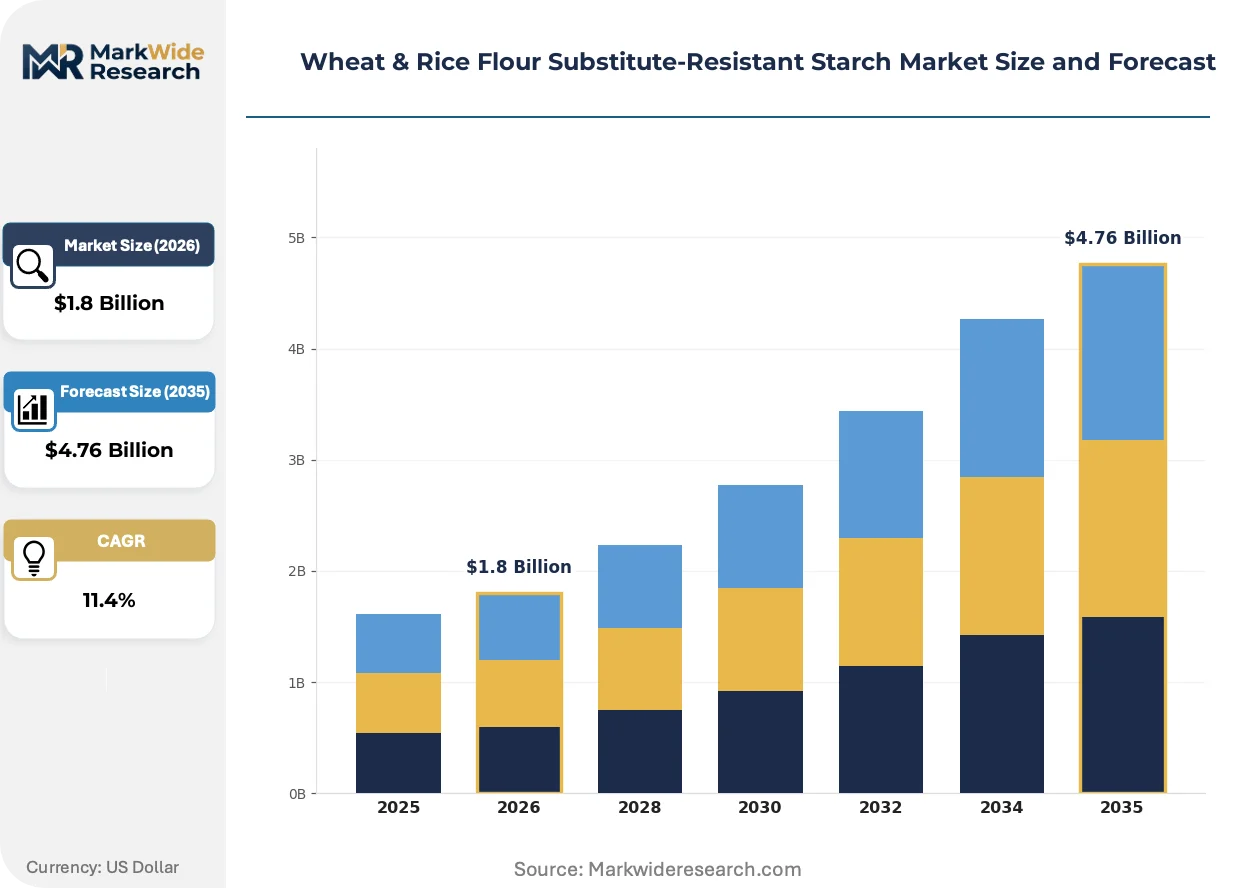
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $4.76 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Modified Starches, Native Starches, Organic Starches, Specialty Starches End Use: Baked Goods, Sauces, Dairy Products, Beverages Form: Powder, Granules, Flakes, Pearls Distribution Channel: Supermarkets, Online Retail, Specialty Stores, Direct Sales |
| Companies Covered | Tate & Lyle, Ingredion, ADM, Cargill, Incorporated, Roquette Frères, Emsland Group, MSP Starch Products, PURIS, MGP Ingredients, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Wheat & Rice Flour Substitute-Resistant Starch Market Evolving Landscape
Enzymatic debranching technologies are overtaking chemical modification as the preferred production pathway, while regulatory fiber definitions and procurement sophistication reshape competitive positioning across ingredient supply chains.
Enzyme-catalyzed amylose reassociation is displacing acid-thinned and cross-linked starches in premium bakery applications. Clean-label bread manufacturers in the US and EU are adopting these native-derived resistant starches at accelerating rates. This enzymatic shift is compressing demand for chemically modified alternatives and rewarding suppliers with in-house enzyme production capabilities.
EFSA's evolving stance on novel fiber substantiation is tightening health claim eligibility for resistant starch types lacking human intervention data. European bakery chains are now demanding comprehensive fermentability studies before ingredient qualification. This regulatory pressure is favoring established resistant starch categories with existing dossiers while delaying market entry for experimental structures.
Direct procurement relationships between bakery chains and specialty starch houses are eroding traditional distributor intermediaries. Large North American gluten-free manufacturers are negotiating volume commitments with Ingredion and Tate & Lyle for customized resistant starch blends. This channel consolidation is most visible in the US, where clean-label mandates have concentrated buying power among national bakery brands.
Wheat & Rice Flour Substitute-Resistant Starch Market Segmentation
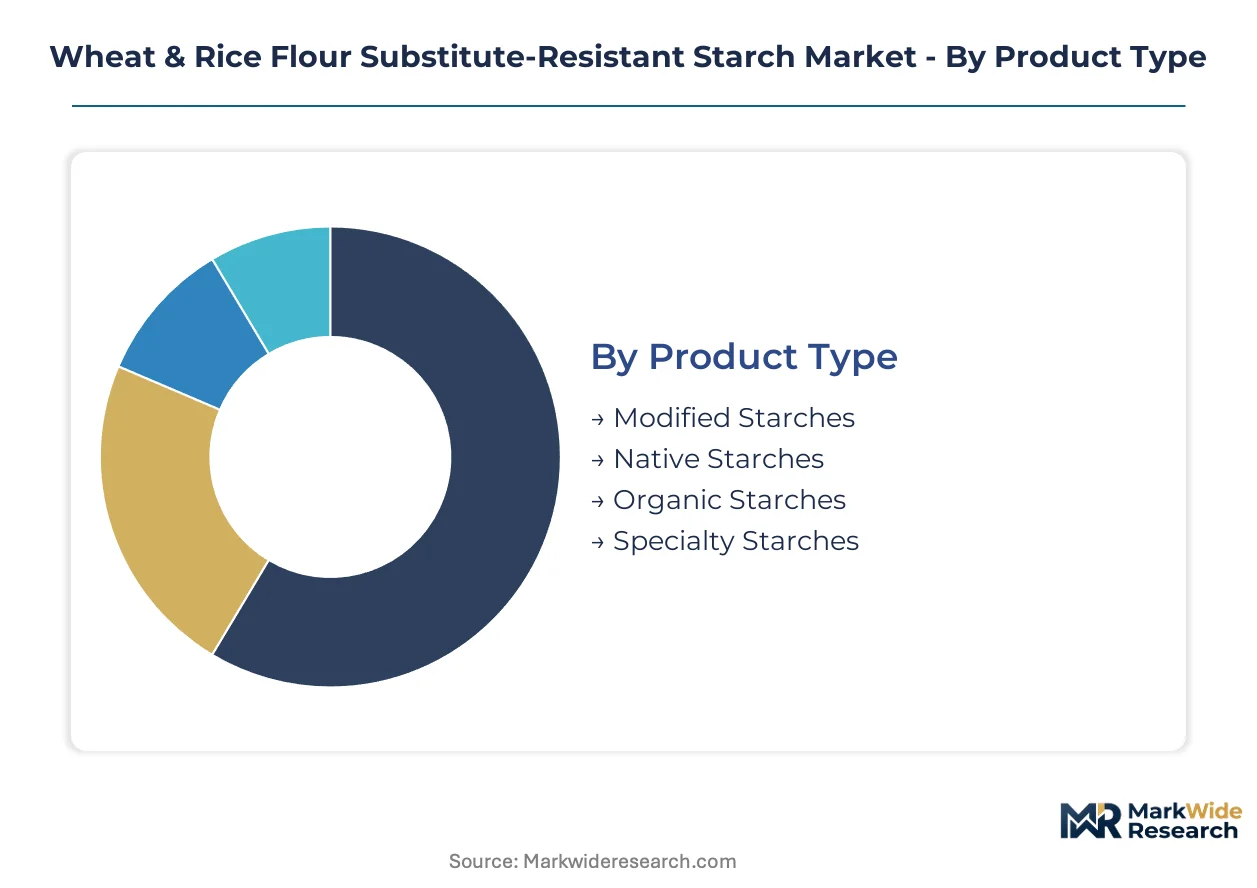
Resistant starch procurement patterns diverge sharply across product grades and application requirements. Formulators select starch types based on fiber claim eligibility, organic certification status, and functional performance in specific food matrices.
Product Type:
Domestic US production dominates modified and native starch supply, while organic and specialty grades draw significant import volumes from European enzymatic processors.
- Modified Starches:Chemically cross-linked or acid-thinned amylose structures deliver tailored viscosity stability in high-moisture systems. US sauce and dairy manufacturers anchor demand here, though FDA fiber qualification friction constrains new product pipeline speed.
- Specialty Starches:Dual-function ingredients engineered for simultaneous flour replacement and fermentable fiber delivery command premium positioning. Clean-label bakery chains in Germany and the Netherlands are pulling these volumes for gut-health-positioned product lines.
- Native Starches:Heat-moisture treated starches without chemical intervention serve organic certification pathways.
- Organic Starches:USDA National Organic Program-compliant variants attract premium baked goods applications.
Modified starches hold the largest share; momentum sits with specialty starches.
End Use:
Application-driven procurement separates commodity-scale buyers from premium formulators seeking health claim substantiation.
- Baked Goods:Gluten-free bread and pastry manufacturers deploy resistant starch for dual fiber-replacement functionality without additive declarations. US national bakery brands negotiate direct volume commitments with integrated wet-millers.
- Sauces:High-moisture emulsion systems demand modified starch viscosity control.
- Dairy Products:Fermentable fiber positioning in yogurt and kefir applications pulls resistant starch volumes.
- Beverages:Low-pH drink systems require acid-stable resistant starch variants.
Baked goods command the dominant volume position; beverage applications are climbing the fastest.
Form:
Physical format selection tracks equipment compatibility and dissolution kinetics in target food matrices.
- Powder:Fine-milled starches integrate rapidly into dry bakery premixes and beverage bases.
- Granules:Controlled particle size enables uniform hydration in extruded pasta and noodle systems.
- Flakes:Intermediate surface-area formats suit specialty coating applications.
- Pearls:Pre-gelatinized spherical structures dissolve without heating for instant applications.
Powder formats retain the largest installed base; pearl forms are gaining share fastest in instant beverage segments.
Distribution Channel:
Channel selection reflects order scale, technical service requirements, and geographic proximity to processing facilities.
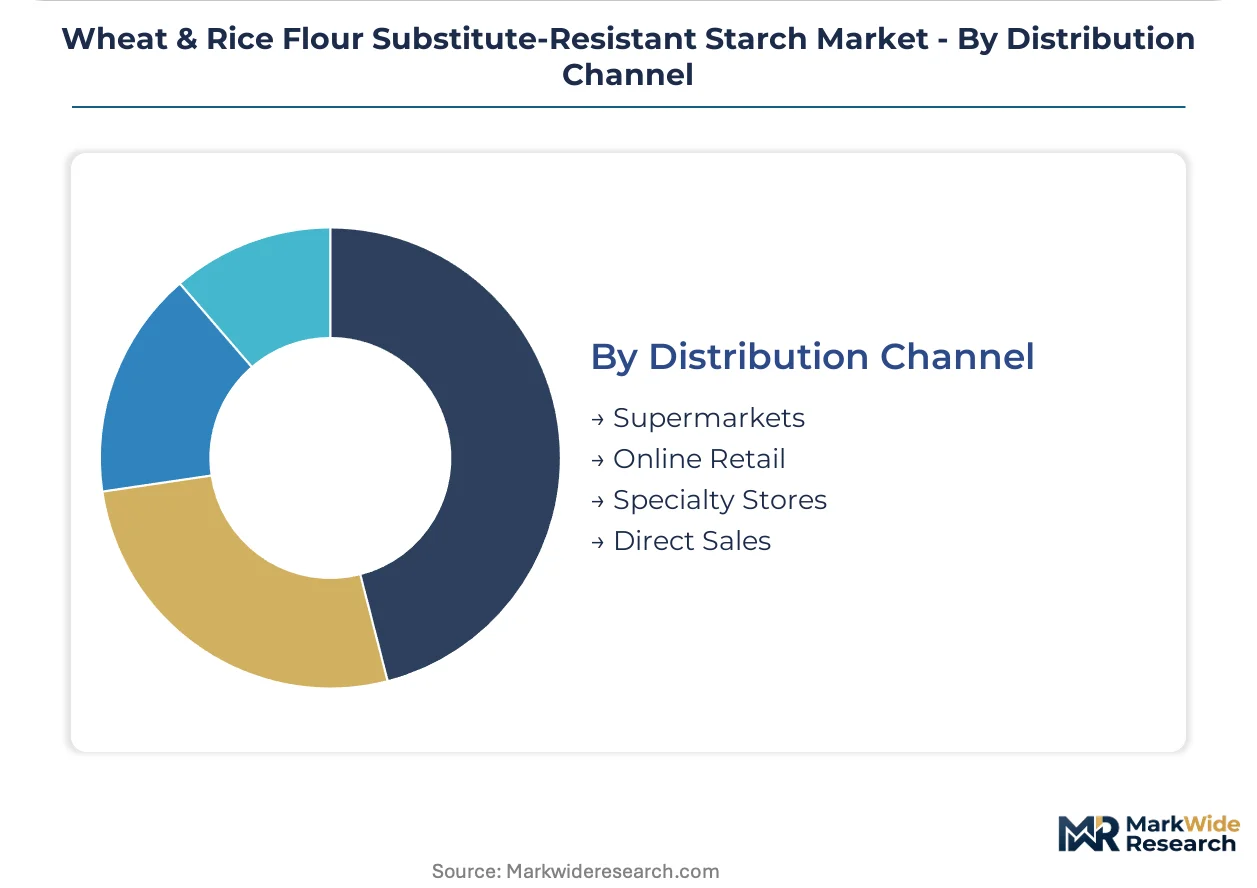
- Direct Sales:Large North American gluten-free manufacturers negotiate customized resistant starch blends directly with Ingredion and Tate & Lyle, bypassing traditional distributor intermediaries. Volume commitments and technical co-development agreements characterize these relationships.
- Specialty Stores:Regional organic and clean-label ingredient suppliers serve mid-tier bakery and sauce producers.
- Supermarkets:Mass-market retail channels move standardized starch grades for home baking applications.
- Online Retail:E-commerce platforms aggregate small-lot procurement for artisanal and startup food processors.
Direct sales capture the largest revenue share; online retail is expanding most quickly among emerging food entrepreneurs.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Consumption patterns diverge sharply across geographies. US buyers prioritize FDA-qualified fiber claims for clean-label positioning, while European procurement emphasizes EFSA-validated gut health substantiation. Asian markets, led by India and China, are accelerating adoption for diabetes management applications.
United States
Gluten-free bakery chains and national bread brands anchor demand for dual-function resistant starches. The FDA's isolated fiber assessment process filters which variants qualify for dietary fiber declarations on nutrition labels. Midwestern corn wet-milling clusters in Illinois and Iowa sustain integrated supply chains for modified starch production.
Germany
Clean-label bakery manufacturers in the Netherlands and Germany pull specialty starches for organic product lines. EFSA's 13.5 health claim framework for bowel function creates regulatory tailwinds for fermentable fiber positioning. The Emsland region anchors enzymatic processing capabilities serving pan-European distribution.
India
Traditional flatbread producers explore partial wheat flour substitution to address rising diabetes prevalence and FSSAI fiber fortification guidance. The Food Safety and Standards Authority of India has issued draft regulations encouraging resistant starch incorporation in staple foods. Maharashtra and Gujarat host emerging ingredient processing partnerships between local millers and international starch houses.
China
Functional food manufacturers deploy resistant starch in low-glycemic noodle and steamed bread applications for prediabetic consumer segments. The National Health Commission has expanded permitted dietary fiber definitions to include specific resistant starch types. Yangtze River Delta food technology hubs in Shanghai and Jiangsu province concentrate formulation R&D for regional bakery chains.
Brazil
São Paulo-based food processors experiment with cassava-derived resistant starches for tropical climate stability in baked goods. ANVISA's evolving nutrition labeling regulations are shaping fiber claim eligibility for imported starch variants. The Southeast region's ingredient distribution corridors connect local manufacturers with US and European supplier networks.
Wheat & Rice Flour Substitute-Resistant Starch Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier in the resistant starch supply structure. Wet-milling conglomerates with captive corn origination control volume supply to major food manufacturers. Specialty ingredient houses compete on enzymatic modification capabilities and clean-label certification pathways. Strategic moves concentrate on backward integration into enzyme production and geographic expansion through regional toll-processing partnerships.
Among integrated wet-millers, Ingredion and Tate & Lyle exemplify the scale-driven archetype with Midwestern US manufacturing footprints and direct bakery chain relationships. Cargill, Incorporated represents the origination-integrated model, controlling supply pipelines from agricultural procurement through finished ingredient. These three entities anchor the premium tier where volume commitments and technical co-development agreements characterize procurement relationships with national gluten-free brands.
| Leading Market Players |
|---|
| Tate & Lyle |
| Ingredion |
| ADM |
| Cargill, Incorporated |
| Roquette Frères |
| Emsland Group |
| MSP Starch Products |
| PURIS |
| MGP Ingredients |
| Others |
Value Network & Pricing Analysis
Sixty-to-ninety-day raw material inventory cycles at Midwestern wet-millers translate directly into pricing power asymmetry between integrated processors and non-integrated specialty houses. This lead-time concentration amplifies margin compression for buyers lacking origination control when corn starch feedstock volatility spikes.
Pricing Analysis
Long-term offtake contracts dominate procurement relationships between national gluten-free bakery chains and integrated wet-millers, locking in volume commitments that insulate buyers from spot market swings. Three-tier pricing structure across premium specialty starches, standard modified grades, and economy native starches reflects certification status and enzymatic processing depth. Cost compression in standard modified grades is intensifying because FDA fiber qualification friction delays new product pipelines and extends R&D payback periods. Small regional sauce manufacturers exhibit the highest price sensitivity, while national clean-label bakery brands prioritize supply security over unit cost.
Supply Chain Analysis
Container availability constraints on Asia-North America trade lanes elevate inbound logistics costs for European enzymatic processors serving US organic starch demand. Supply concentrates in the United States Corn Belt, the Emsland region of Germany, and emerging processing partnerships in Maharashtra and Gujarat, India. The network draws from corn and wheat starch feedstocks, specialty enzyme inputs, and organic certification-compliant process chemicals. Single-source vulnerability around heat-moisture reactor equipment creates bottleneck risk for Type 3 resistant starch expansion. Distribution runs through direct technical sales relationships with national bakery chains, supplemented by regional specialty ingredient distributors for mid-tier processors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating among national gluten-free bakery chains that negotiate direct volume commitments, fragmenting the intermediary distributor tier and reshaping supplier relationship economics.
For Market Incumbents: Shield margin position by deepening backward integration into captive enzyme production capabilities that accelerate FDA fiber qualification timelines. Accelerate capacity addition in the Emsland region to capture EU EFSA health claim tailwinds for bowel function positioning. The priority lever sits with controlling heat-moisture reactor installation pipelines that constrain Type 3 resistant starch supply expansion. For New Entrants and Emerging Players: Technical service gaps in enzymatic debranching expertise present entry points for regional toll-processing partnerships with Indian flatbread modernizers. Target Maharashtra and Gujarat bakery clusters where FSSAI fiber fortification guidance creates pull without entrenched incumbent relationships. Lead with customized fermentability study packages that accelerate EFSA dossier preparation for European clean-label manufacturers. For Investors and Strategic Acquirers: Carve-out targets emerge from diversified agribusiness conglomerates with under-optimized specialty starch divisions lacking enzymatic modification capabilities. Five-to-ten-year viability hinges on regulatory fiber definition stability rather than commodity starch economics. Monitor FDA isolated fiber assessment pipeline velocity as the critical inflection signal for portfolio reallocation timing.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Enzyme Production | Captive enzymatic capabilities compress FDA qualification timelines for fiber claim eligibility. |
| Regional Toll-Processing Partnership | Maharashtra and Gujarat facilities access Indian flatbread modernization demand with limited capital deployment. |
| Long-term Supply Agreement | Direct volume commitments with national gluten-free bakery chains displace distributor intermediaries. |
| Green Manufacturing Transition | Heat-moisture treatment technologies satisfy USDA National Organic Program certification pathways. |
| Joint Venture | Emsland-European bakery chain collaborations accelerate EFSA 13.5 health claim dossier development. |
Research Methodology
Operator-level perspectives from starch plant managers, bakery chain procurement directors, enzymatic process R&D leads, and FSSAI regulatory affairs specialists anchored the qualitative base. These primary inputs combined with secondary validation from FDA guidance documents, EFSA health claim registers, USDA National Organic Program standards, and corn wet-milling trade association capacity reports. Bottom-up facility capacity modeling and top-down end-use demand estimation provided triangulation checks across the analysis window.
Sensitivity analysis around FDA fiber qualification approval velocity and corn starch feedstock price bands tested forecast robustness. The analytical framework segmented volume and value across product type, end-use application, physical form, and distribution channel dimensions, with additional granularity on organic certification status. CAGRs derived from installed capacity expansion announcements and buyer procurement intention surveys. Enzymatic debranching technology adoption curves and EFSA health claim substantiation timelines served as industry-specific demand drivers.
Material uncertainties — regulatory reclassification of resistant starch types, Midwestern agricultural commodity price shocks, and enzymology talent scarcity constraints — sit outside the modeled envelope. Forecasts reflect documented assumptions about fiber claim eligibility pathways and clean-label bakery chain expansion trajectories. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Additives and Ingredients
Food Grade Ammonium Bicarbonate Market
Food Additives and Ingredients
Calcium Inosinate Market
Food Additives and Ingredients
Africa Food Acidulants Market
Food Additives and Ingredients
Food Phosphate Market
Food Additives and Ingredients
Alcohol Additives Market
Food Additives and Ingredients
Global Food Release Agents Market
Food Additives and Ingredients
Global Edible Films and Coatings for Fruits and Vegetables Market
Food Additives and Ingredients
Film Forming Starches Market
Food Additives and Ingredients
Soft Drink Ingredients Market
Food Additives and Ingredients
Lactoperoxidase Market
Food Additives and Ingredients
Carrageenan Gum Market
Food Additives and Ingredients
Food Binders Market
Food Additives and Ingredients
Egypt Feed Additives Market
Food Additives and Ingredients
Protein Films Market
Food Additives and Ingredients
Mexico Food Preservatives Market
Food Additives and Ingredients
Citrus Fruit Coatings Market