
 Food Grade Ammonium Bicarbonate Market | 2026-2036
Food Grade Ammonium Bicarbonate Market Size, Share, and Industry Trends Forecast 2026-2036
Food Grade Ammonium Bicarbonate Market Foresight
Sodium bicarbonate is shifting toward restricted-use status in premium baked goods as ammonium bicarbonate captures share in flatbread and cracker applications where residual alkalinity must stay minimal. BASF leverages its integrated ammonia supply chain to maintain cost discipline across European food-grade output. ADDCON sustains specialized distribution networks for bakery ingredient houses in Central and Eastern Europe. Fengxi Fertilizer anchors volume production from Shaanxi province, competing primarily on bulk pricing for domestic Chinese cracker manufacturers.
Food grade ammonium bicarbonate is a white crystalline salt with the chemical formula NH₄HCO₃, manufactured through the reaction of ammonia with carbon dioxide under controlled temperature and pressure, then purified to meet food safety specifications for residual sulfides and heavy metals below regulatory thresholds. It functions as a chemical leavening agent that decomposes entirely into ammonia, carbon dioxide, and water during baking, leaving no residual sodium salts in the finished product. The food grade powder segment dominates current volume due to its dispersion efficiency in dry dough mixes, while food grade granules represent the fastest-growing format as automated dosing equipment spreads through industrial bakeries. Snack food production commands the deepest margin pool, particularly in laminated and rotary-molded cracker categories where precise gas release timing determines product texture.
The FDA's Food Chemicals Codex and EFSA's purity specifications under EU food additive regulations jointly define the analytical thresholds that determine market access for imported ammonium bicarbonate. China's SAMR enforces GB standards for food-grade ammonia derivatives, creating a dual-compliance burden for exporters serving both Western and Chinese bakery chains. India's FSSAI has begun aligning its food additive purity benchmarks with Codex Alimentarius, opening incremental volume opportunities as domestic biscuit and rusk production scales. Stakeholders must monitor divergence between regional heavy-metal limits and certification reciprocity agreements to avoid stranded inventory in cross-border ingredient trade.
Market Dynamics
The clean-label ingredient mandate across European and North American bakery chains is compressing sodium bicarbonate's addressable market while elevating ammonium bicarbonate's formulation priority in flatbread and cracker production.
Growth Catalysts
- EU F-Gas Regulation:Tightening restrictions on fluorinated greenhouse gases redirect food processing R&D budgets toward ammonia-based leavening systems with lower environmental footprints.
- Industrial bakery automation:Automated dosing equipment spreading through Southeast Asian cracker plants favors granule-format ammonium bicarbonate for precise gas-release timing control.
- China's snack food industrialization:Domestic chemical producers scaling food-grade purification capacity serve both export demand and rapidly expanding cracker manufacturing clusters in Shandong and Guangdong provinces.
Market Restraints
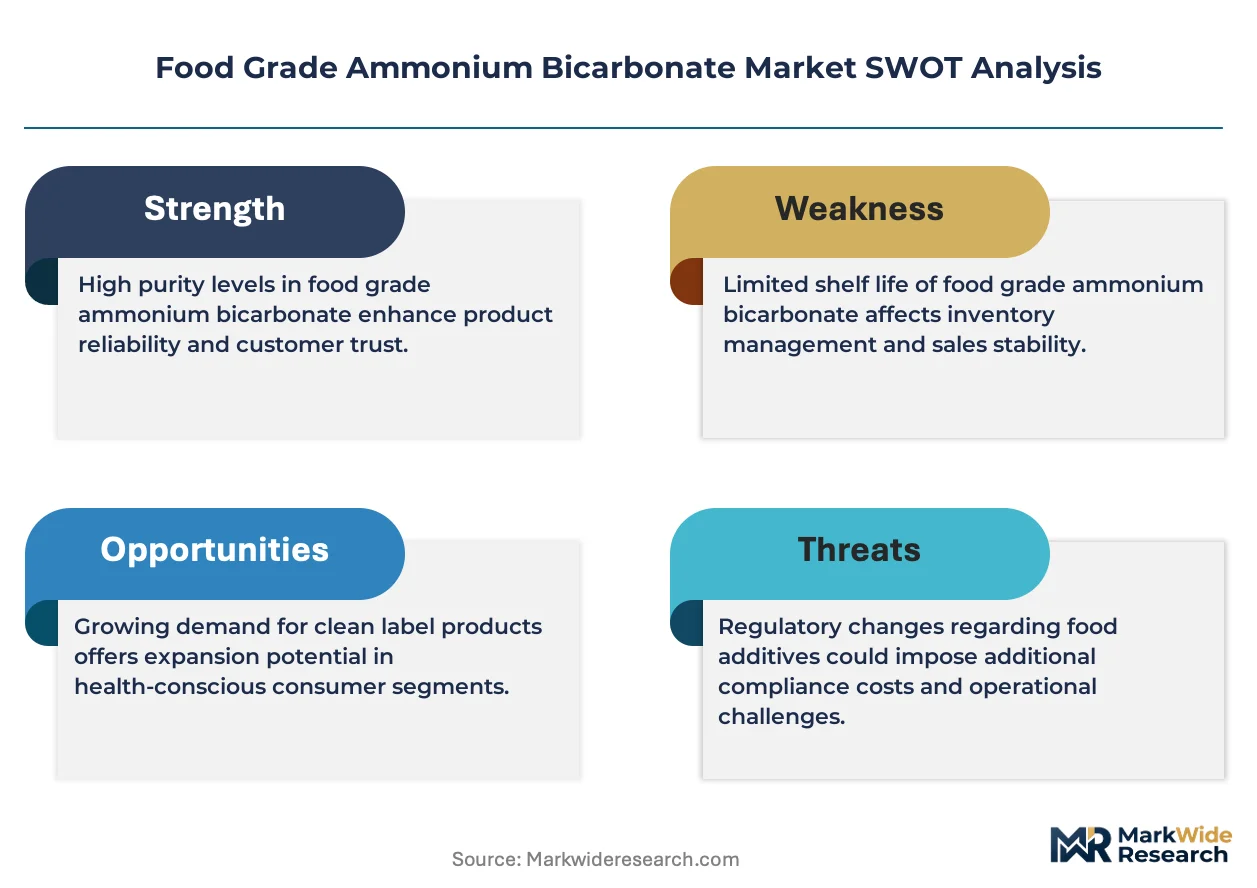
- Ammonia feedstock volatility:Natural gas price swings directly compress margins for synthetic ammonia producers supplying food-grade bicarbonate synthesis.
- Heavy-metal compliance burden:Divergent residual sulfide thresholds between FDA Food Chemicals Codex and China's GB standards create stranded inventory risk for cross-border ingredient traders.
- Sodium bicarbonate substitution defense:Established baking soda suppliers leverage existing distribution contracts and baker familiarity to retain share in non-clean-label product lines.
Strategic Opportunities
- India's biscuit sector scaling:FSSAI alignment with Codex Aluminarius purity benchmarks opens volume growth as domestic rusk and cracker production modernizes.
- Granule format penetration:Automated dosing equipment retrofits in European industrial bakeries create pull for low-dust handling properties unavailable in powder grades.
- Carbon footprint labeling:EU Green Deal corporate sustainability reporting requirements favor leavening agents with transparent ammonia supply chain carbon accounting.
Industry Challenges
- Food-grade certification timelines:Dual-compliance testing for simultaneous FDA and SAMR approval extends product launch cycles by eight to fourteen months.
- Specialized handling infrastructure:Ammonia release during storage requires ventilated warehousing and dedicated transport fleets unfamiliar to conventional baking ingredient distributors.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Food Grade Ammonium Bicarbonate Market |
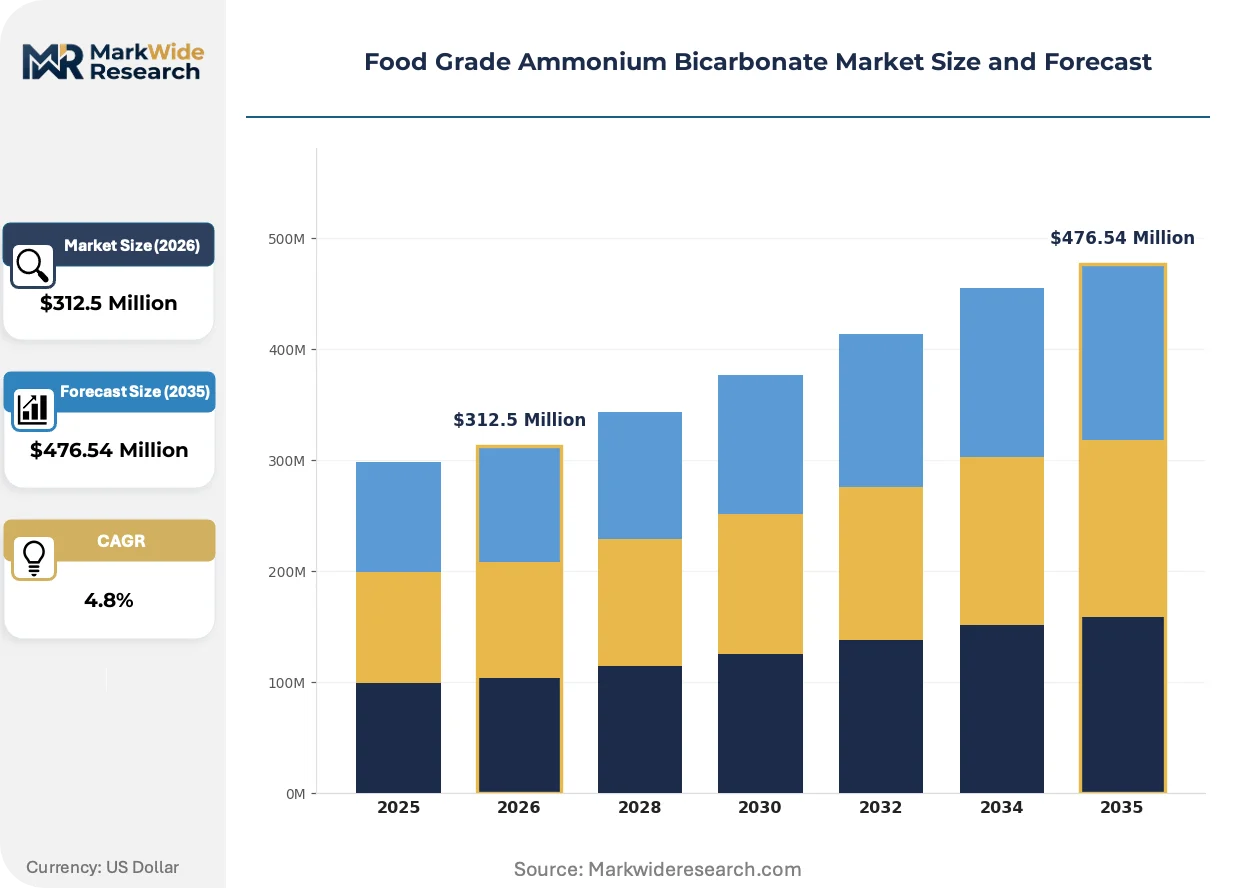
| Market Size in 2026 | $312.5 Million |
| Market Size in 2035 | $476.54 Million |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Food Grade Powder, Food Grade Granules, Industrial Grade Powder, Pharmaceutical Grade Powder, Technical Grade Application: Baking Industry, Snack Food Production, Pharmaceutical Industry, Agriculture, Fire Extinguishing Agents End User: Food Processing Units, Pharmaceutical Manufacturers, Agricultural Suppliers, Chemical Distributors, Bakeries Packaging Type: Paper Bags, Plastic Bags, Drum Containers, Bulk Packaging, Foil Packs |
| Companies Covered | BASF, ADDCON, MCF, Fengxi Fertilizer, Boyu Chemical, Anhui Haoyuan Chemical Group, Shandong Lianmeng Chemical, Shijiazhuang Huiquan Chemical Group, Solvay, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Food Grade Ammonium Bicarbonate Market Shifts & Advancements
Process intensification in leavening agent manufacturing and evolving procurement patterns among multinational bakery chains are compressing traditional supply relationships while elevating technical service capabilities.
Encapsulated ammonium bicarbonate variants with controlled-release coatings are rewriting gas evolution kinetics in laminated cracker production. Industrial bakeries in the Netherlands and Belgium are adopting these modified grades for rotary-molded applications requiring extended dough sheet stability before oven spring. The technology is compressing scrap rates in high-speed lines where premature leavening previously generated texture defects.
REACH authorization requirements for ammonia derivatives are forcing European producers to document full substance volume tracking through the supply chain. Industrial chemical manufacturers must now register food-grade ammonium bicarbonate under extended safety data sheet protocols. German and French bakery ingredient houses are consolidating supplier relationships to reduce compliance administration burden.
Direct procurement contracts between cracker manufacturers and ammonia producers are displacing traditional distributor intermediaries in Southeast Asia. Thai and Indonesian snack food conglomerates now negotiate annual volume commitments with Shaanxi-based chemical plants for landed-cost predictability. This channel compression is most visible in rotary-molded cracker categories where ingredient cost precision determines margin defense.
Food Grade Ammonium Bicarbonate Market Segmentation
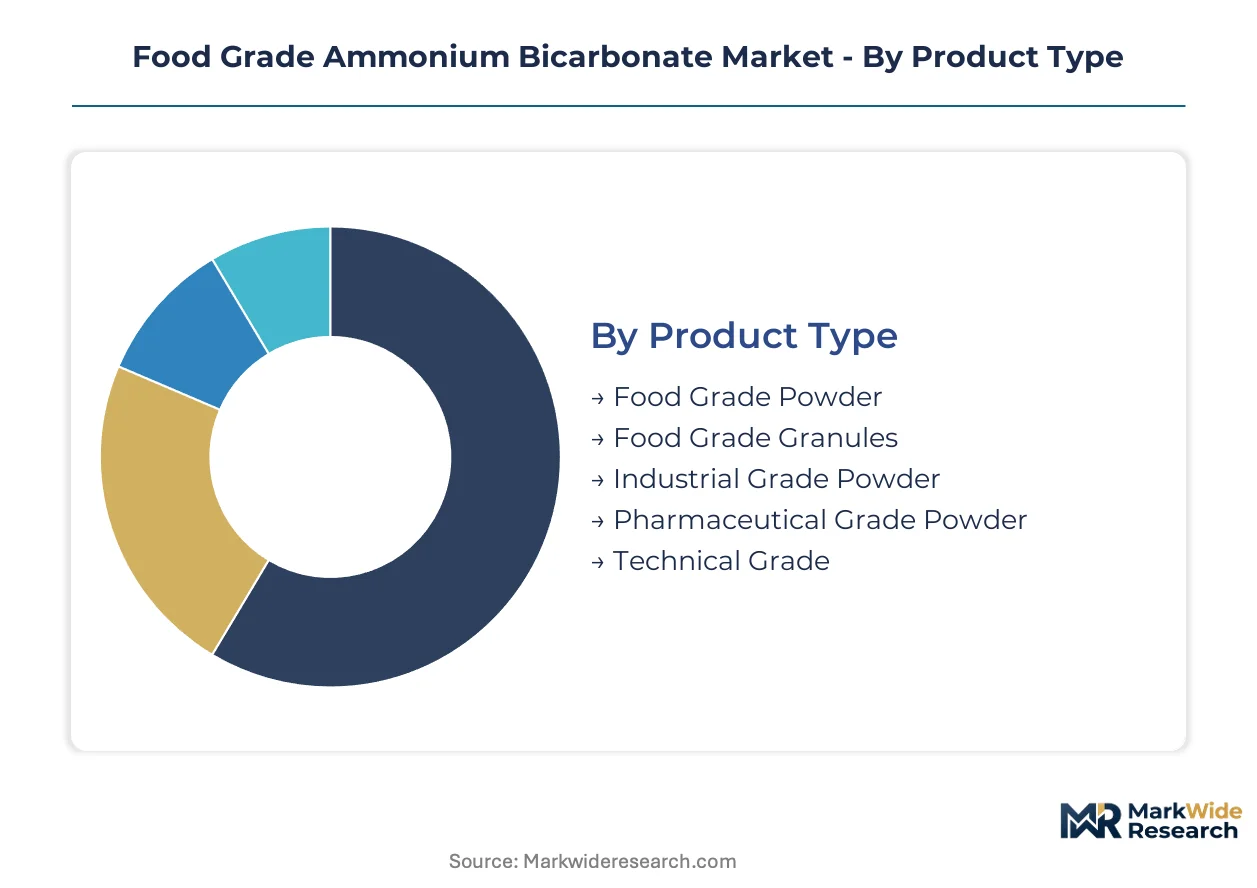
Segmentation in the food grade ammonium bicarbonate market determines compliance pathways, handling infrastructure investments, and procurement contract structures. Each dimension carries distinct certification requirements that shape supplier selection and pricing negotiations.
Product Type:
FDA Food Chemicals Codex and EFSA purity specifications apply differentially across grades, with food-grade variants demanding sulfide and heavy-metal testing that industrial and technical grades bypass entirely.
- Food Grade Powder:Fine crystalline particles optimized for dispersion in dry dough mixes. Industrial bakeries in China and Germany specify this grade for rotary-molded crackers where uniform gas distribution determines texture consistency. Powder format commands the deepest volume concentration due to legacy equipment compatibility.
- Food Grade Granules:Dense, free-flowing particles engineered for automated dosing systems. Southeast Asian cracker plants retrofitting pneumatic conveyance favor this format for dust suppression and precise feed-rate control. Granules are climbing the fastest as industrial automation spreads through snack food manufacturing clusters.
- Industrial Grade Powder:Unpurified synthesis output retaining higher residual sulfide content for non-food chemical applications.
- Pharmaceutical Grade Powder:Ultra-purified variant meeting USP monograph standards for excipient use in tablet formulations.
- Technical Grade:Intermediate purity specification serving fire suppression and industrial gas generation applications.
Leading the category by volume: Food Grade Powder. Expanding most quickly: Food Grade Granules.
Application:
Margin concentration varies sharply across applications, with snack food production capturing premium pricing for precise gas-release specifications that agricultural and fire suppression segments do not require.
- Baking Industry:Flatbread and cracker manufacturers specify ammonium bicarbonate for clean-label positioning against sodium bicarbonate. Dutch and Belgian industrial bakeries drive formulation R&D for encapsulated variants with extended dough stability.
- Snack Food Production:Laminated and rotary-molded cracker categories command the steepest margin pool. Thai and Indonesian conglomerates negotiate direct procurement contracts with Shaanxi chemical plants for landed-cost precision in high-volume lines.
- Pharmaceutical Industry:Tablet effervescence and pH buffering applications requiring USP-grade certification.
- Agriculture:Soil amendment and fertilizer component uses tolerating lower purity thresholds.
- Fire Extinguishing Agents:Dry chemical suppression systems utilizing ammonia gas generation properties.
Deepest margin capture: Snack Food Production. Fastest application expansion: Baking Industry.
End User:
Procurement sophistication diverges between multinational food processors with dedicated regulatory affairs teams and regional distributors managing mixed chemical portfolios.
- Food Processing Units:Industrial-scale cracker and biscuit manufacturers with in-house quality laboratories. These buyers enforce dual FDA and SAMR compliance documentation, extending supplier qualification timelines.
- Pharmaceutical Manufacturers:Excipient purchasers demanding USP certification and batch-level CoA traceability.
- Agricultural Suppliers:Volume buyers prioritizing bulk pricing over purity documentation.
- Chemical Distributors:Intermediary channel facing compression as direct procurement spreads through Southeast Asia.
- Bakeries:Artisan and mid-scale operations with limited technical service requirements.
Highest compliance burden: Food Processing Units. Channel share under pressure: Chemical Distributors.
Packaging Type:
Handling infrastructure investments and ammonia venting requirements segment packaging selection more than unit economics.
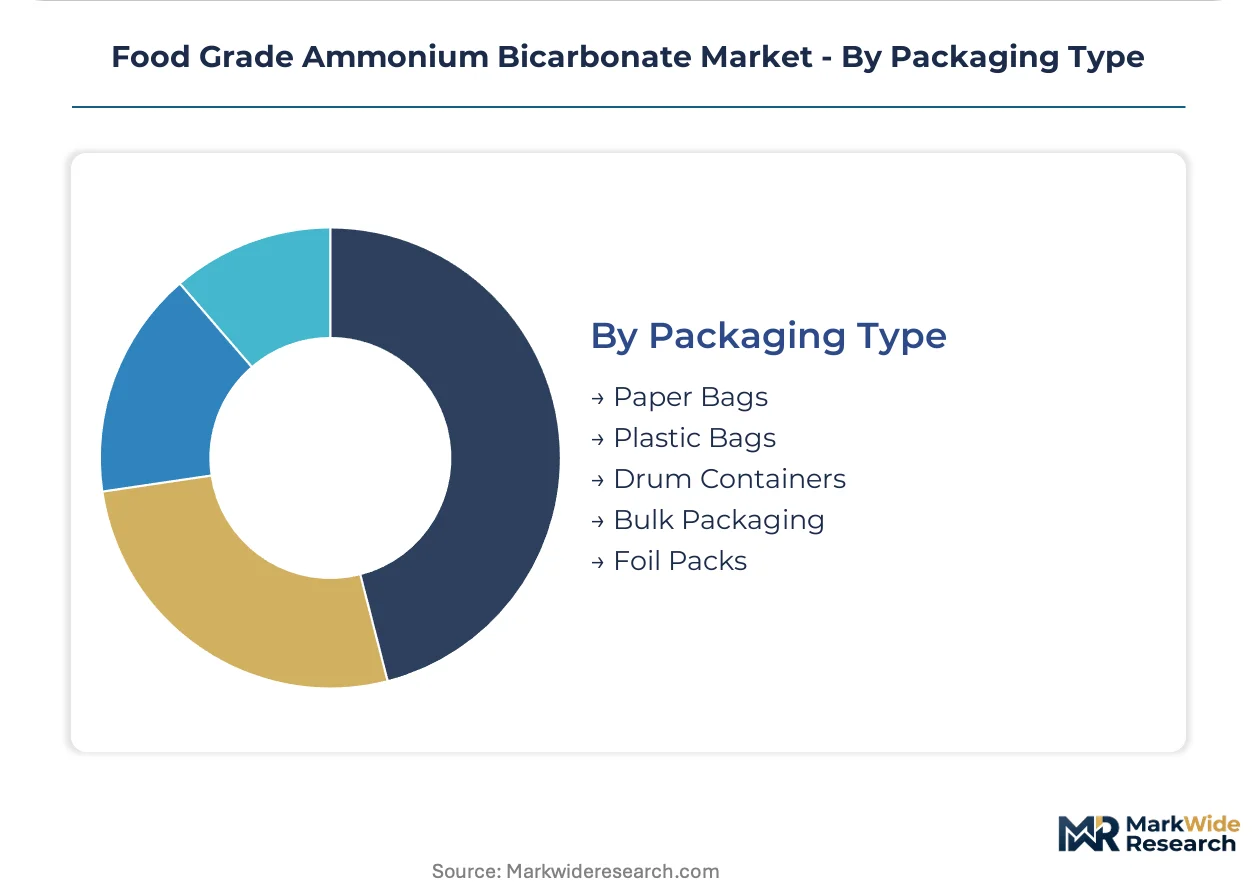
- Paper Bags:Standard multi-wall kraft construction for domestic Chinese distribution. Low unit cost dominates procurement for high-volume cracker manufacturers with rapid inventory turnover.
- Plastic Bags:Moisture-barrier polyethylene liners for humid climates. Indonesian and Thai snack plants specify this format for warehouse stability in tropical conditions.
- Drum Containers:Steel or fiber drums for pharmaceutical and export shipments requiring palletized handling.
- Bulk Packaging:Tanker and silo delivery for integrated chemical processors with captive ammonia supply chains.
- Foil Packs:High-barrier laminates for moisture-sensitive pharmaceutical and specialty food applications.
Dominant format by tonnage: Paper Bags. Premium positioning: Foil Packs.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China concentrates the deepest procurement pull as domestic snack food industrialization accelerates, while European clean-label mandates redirect formulation budgets toward ammonia-based leavening systems. Southeast Asian cracker manufacturers are retrofitting automated dosing equipment that favors granule-format specifications.
China
Shandong and Guangdong provinces host expanding cracker manufacturing clusters that source ammonium bicarbonate from Shaanxi-based chemical plants scaling food-grade purification capacity. SAMR enforces GB standards for residual sulfides and heavy metals that create dual-compliance burdens for exporters. Domestic producers now serve both export demand and rapidly industrializing domestic snack food sectors with bulk pricing discipline.
Germany
Dutch and Belgian industrial bakeries drive encapsulated variant adoption for rotary-molded applications requiring extended dough sheet stability. REACH authorization requirements for ammonia derivatives force producers to document full substance volume tracking through supply chains. BASF leverages its integrated ammonia supply chain to maintain cost discipline across European food-grade output.
Thailand
Snack food conglomerates negotiate direct procurement contracts with Chinese chemical plants for landed-cost predictability in high-volume laminated cracker lines. Humid tropical conditions drive specification of moisture-barrier polyethylene packaging for warehouse stability. Bangkok-based manufacturing clusters are displacing traditional distributor intermediaries through annual volume commitments.
United States
Flatbread and cracker manufacturers specify ammonium bicarbonate for clean-label positioning against sodium bicarbonate in premium baked goods. FDA Food Chemicals Codex purity thresholds determine market access for imported material. Industrial bakeries in the Midwest and Southeast retrofit pneumatic conveyance systems that favor low-dust granule handling.
India
FSSAI alignment with Codex Alimentarius purity benchmarks opens incremental volume opportunities as domestic biscuit and rusk production scales. Maharashtra and Gujarat house expanding manufacturing clusters modernizing with automated dosing equipment. Procurement sophistication remains split between multinational processors with dedicated regulatory affairs teams and regional distributors managing mixed chemical portfolios.
Food Grade Ammonium Bicarbonate Market Competitive Landscape
Capacity expansion dominates the current landscape as Chinese producers scale food-grade purification infrastructure to serve export and domestic snack food demand simultaneously. The vendor base separates into three tiers: integrated chemical majors with captive ammonia supply, regional specialists serving bakery ingredient houses through dedicated distribution networks, and bulk commodity producers competing primarily on tonnage pricing. Strategic archetypes include backward-integrated ammonia producers, formulation technology licensors, and automated dosing equipment partners. Geographic expansion and portfolio diversification represent the dominant competitive moves as European clean-label mandates and Southeast Asian industrialization create parallel growth vectors.
Among European integrated chemical majors, BASF and Solvay occupy positions exemplifying supply chain control through captive ammonia production. ADDCON represents the specialist archetype sustaining dedicated distribution networks for bakery ingredient houses in Central and Eastern Europe. Within Chinese bulk production, Fengxi Fertilizer anchors volume supply from Shaanxi province while Anhui Haoyuan Chemical Group and Shandong Lianmeng Chemical exemplify regional competitors scaling food-grade capacity to serve domestic cracker manufacturers.
| Leading Market Players |
|---|
| BASF |
| ADDCON |
| MCF |
| Fengxi Fertilizer |
| Boyu Chemical |
| Anhui Haoyuan Chemical Group |
| Shandong Lianmeng Chemical |
| Shijiazhuang Huiquan Chemical Group |
| Solvay |
| Others |
Supply & Pricing Matrix
Henry Hub natural gas futures cascade directly into synthetic ammonia production costs, compressing margins for food-grade bicarbonate manufacturers and forcing tiered pricing stratification across European, Chinese, and Southeast Asian supply bases. This feedstock volatility feeds into contract structures that separate integrated producers with captive ammonia supply from merchant buyers exposed to spot market swings.
Pricing Analysis
Volume concentration in powder grades trades at thin margins against premium capture in encapsulated granule formats for automated dosing lines. Three-tier pricing structure across pharmaceutical-grade, food-grade powder, and food-grade granule levels separates buyers by certification burden and handling infrastructure investment. Pricing pressure stems from Shaanxi-based bulk producers competing on landed cost for Southeast Asian cracker manufacturers. Regional distributors managing mixed chemical portfolios exhibit the highest price sensitivity, while multinational food processors with dedicated regulatory affairs teams prioritize supply security over unit cost.
Supply Chain Analysis
Dual FDA and SAMR certification requirements gate market access, extending supplier qualification timelines and concentrating viable supply among integrated chemical majors with dedicated compliance infrastructure. Manufacturing capacity clusters in China, Germany, and the Netherlands serve distinct regional demand pools with limited cross-shipping flexibility. Ammonia feedstock, carbon dioxide supply contracts, and specialized ventilated warehousing constitute critical input dependencies. Tariff exposure on Chinese chemical exports to North American bakery chains represents the dominant structural risk. Distribution runs through direct procurement contracts displacing traditional intermediary channels across Thai and Indonesian manufacturing clusters.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
REACH authorization requirements for ammonia derivatives erect a cost-of-compliance moat that favors incumbent producers with established substance volume tracking systems, locking out undercapitalized entrants lacking dedicated regulatory affairs infrastructure.
For Market Incumbents: Anchor market position through backward integration into captive ammonia supply chains, eliminating feedstock volatility exposure that compresses merchant producer margins. Extend certification investment into dual FDA-SAMR compliance documentation to capture stranded inventory risk from single-standard competitors. Defend against direct procurement channel compression by embedding technical service teams within Southeast Asian cracker manufacturing clusters.
For New Entrants and Emerging Players: Enter via India's biscuit and rusk modernization wave, where FSSAI alignment with Codex Alimentarius benchmarks creates incremental volume opportunities without entrenched supplier relationships. Target Maharashtra and Gujarat manufacturing clusters with automated dosing equipment retrofits favoring granule-format specifications. Pursue equipment-attach go-to-market partnerships with pneumatic conveyance system vendors to bypass established distribution networks.
For Investors and Strategic Acquirers: Distressed-cycle entries favor mid-cap European bakery ingredient houses facing REACH compliance administration burden consolidation pressure. Long-term viability hinges on exposure to clean-label mandate acceleration in premium baked goods rather than commodity sodium bicarbonate defense. Monitor EU Green Deal corporate sustainability reporting requirements as inflection signal favoring transparent ammonia supply chain carbon accounting.
| Strategic Initiative | Industry Significance |
|---|---|
| Capacity Expansion | Shaanxi-based producers scaling food-grade purification infrastructure capture domestic Chinese snack food industrialization demand. |
| Backward Integration | BASF's captive ammonia supply chain insulates European food-grade output from Henry Hub volatility compressing merchant margins. |
| Long-term Supply Agreement | Thai conglomerates negotiating annual volume commitments with Chinese chemical plants displace distributor intermediaries for landed-cost precision. |
| Joint Venture | Dutch and Belgian industrial bakeries partnering with encapsulation technology licensors rewrite gas evolution kinetics in rotary-molded applications. |
| Green Manufacturing Transition | EU Green Deal sustainability reporting requirements favor leavening agents with documented ammonia supply chain carbon accounting transparency. |
Research Methodology
Multi-period observation of ammonia feedstock pricing, food-grade certification timelines, and automated dosing equipment deployment rates anchored the trend analysis, supplemented by interviews with plant managers at Shandong and Guangdong cracker manufacturing clusters, procurement leads at European bakery ingredient houses, technical R&D directors at encapsulation technology developers, and distribution channel partners in Central and Eastern Europe. Secondary validation drew from customs and trade data, ECHA REACH registration databases, SEC filings of integrated chemical majors, and SAMR GB standard update bulletins. Bottom-up volume estimates from end-use application consumption rates triangulated against top-down capacity assessments from regional chemical production statistics.
Input-output matrix modeling connected ammonia synthesis capacity, food-grade purification yield rates, and downstream application demand across grade tier, end-use industry, packaging format, and regional production hub dimensions. CAGRs were derived from segment-level growth rate reconciliation against aggregate market expansion over the projection horizon. Forecast inputs incorporated natural gas price trajectory assumptions, clean-label mandate penetration curves in European and North American bakery chains, and Southeast Asian industrial automation retrofit timelines.
Forecast precision tightens around the base case; tail outcomes carry wider variance under abrupt natural gas price spikes, divergence between FDA and SAMR heavy-metal threshold adjustments, or accelerated sodium bicarbonate substitution defense by established baking soda suppliers. A model refresh is warranted upon material change in EU F-Gas Regulation enforcement intensity or China's dual carbon goals implementation affecting ammonia production economics.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Additives and Ingredients
Microencapsulated Phytosterols Market
Food Additives and Ingredients
Africa Food Stabilizers Market
Food Additives and Ingredients
Lake Food Colors Market
Food Additives and Ingredients
Global Crystalline Maltitol Market
Food Additives and Ingredients
Fat-Replacing Starch Market
Food Additives and Ingredients
Food Binders Market
Food Additives and Ingredients
Vietnam Food Additives Market
Food Additives and Ingredients
Beverage Clouding Agent Market
Food Additives and Ingredients
Flavor Encapsulation Market
Food Additives and Ingredients
India Food Enzymes Market
Food Additives and Ingredients
Japan Food Preservatives Market
Food Additives and Ingredients
France Food Enzymes Market
Food Additives and Ingredients
United States Feed Additives Market
Food Additives and Ingredients
United States Food Acidulants Market
Food Additives and Ingredients
France Anti Caking Market
Food Additives and Ingredients
Spain Food Additives Market