
 Calcium Inosinate Market | 2026-2036
Calcium Inosinate Market Size, Share, and Industry Trends Forecast 2026-2036
Calcium Inosinate Market Outlook
Monosodium glutamate is pivoting toward partial replacement by calcium inosinate in premium seasoning formulations, altering cost structures for flavor houses. Ajinomoto Co., Inc. leverages decades of nucleotide fermentation expertise to sustain leadership in high-purity grades. CJ CheilJedang Corporation anchors its position through integrated lysine-inosinate production complexes in South Korea. Fufeng Group Limited dominates bulk powder output, competing on manufacturing scale across Shandong province facilities.
Calcium inosinate is the calcium salt of inosinic acid, a nucleotide produced via microbial fermentation of carbohydrate substrates, typically specified at 97-102% purity on an anhydrous basis and employed primarily as a flavor potentiator that synergizes with glutamates to amplify umami perception. The food additive segment occupies the largest volume share, with powder formulations leading due to blending compatibility in savory bases and snack seasonings. Dietary supplement applications represent the fastest-expanding category, as nutraceutical manufacturers incorporate nucleotides into immune-support and gut-health formulations. Direct sales channels control the premium pharmaceutical-grade tier, while online stores extend reach to mid-size nutraceutical buyers seeking smaller lot sizes.
FDA GRAS status and EFSA food additive evaluations shape product specifications for US and European market access, with China's National Health Commission setting domestic purity and microbial limits that influence export-grade production. The EU F-Gas Regulation and REACH compliance requirements constrain solvent-based purification methods, pushing manufacturers toward aqueous fermentation recovery systems. Stakeholders must monitor regulatory divergence between major jurisdictions when siting purification capacity and certifying product grades for cross-border trade.
Market Dynamics
Fermentation-based nucleotide production is consolidating around integrated carbohydrate-to-purification complexes, with China's Shandong province facilities capturing bulk output capacity and forcing standalone processors toward specialty grades or exit.
Growth Catalysts
- Clean-label mandates:EU EFSA and US FDA frameworks are tightening additive disclosure requirements, pushing savory seasoning formulators toward calcium inosinate as a recognizable nucleotide alternative to synthetic enhancers.
- China:Domestic flavor enhancer production anchors regional supply chains, with National Health Commission purity standards enabling export-grade certification that unlocks cross-border trade for Shandong-based manufacturers.
- Immune-support formulations:Nutraceutical manufacturers are incorporating nucleotides into gut-health supplements, creating incremental demand outside traditional food additive applications.
Market Restraints
- Input cost volatility:Corn starch and molasses feedstock prices fluctuate with agricultural commodity cycles, compressing margin predictability for fermentation operators.
- Supply concentration risk:Bulk powder output clusters in Shandong province facilities, creating geographic vulnerability to regional energy rationing or environmental enforcement actions.
- REACH compliance friction:EU solvent-based purification methods face constraints under F-Gas Regulation and ECHA registration requirements, elevating capital costs for European market access.
Strategic Opportunities
- Pharmaceutical-grade tier:Direct sales channels for high-purity calcium inosinate remain underdeveloped outside Ajinomoto's established network, creating white space for certified entrants.
- Dietary supplement convergence:Nucleotide blends targeting immune modulation are expanding into pediatric and geriatric nutrition, segments with limited incumbent penetration.
- Aqueous recovery systems:EU regulatory tailwinds favoring aqueous fermentation recovery over solvent methods reward early adopters with streamlined EFSA approval pathways.
Industry Challenges
- Fermentation specialist scarcity:Nucleotide-grade microbial strain development and bioprocess optimization require rare cross-training in enzymology and industrial microbiology.
- Dual certification timelines:Simultaneous FDA GRAS self-affirmation and EFSA food additive evaluation create 18-24 month market entry delays for new suppliers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Calcium Inosinate Market |
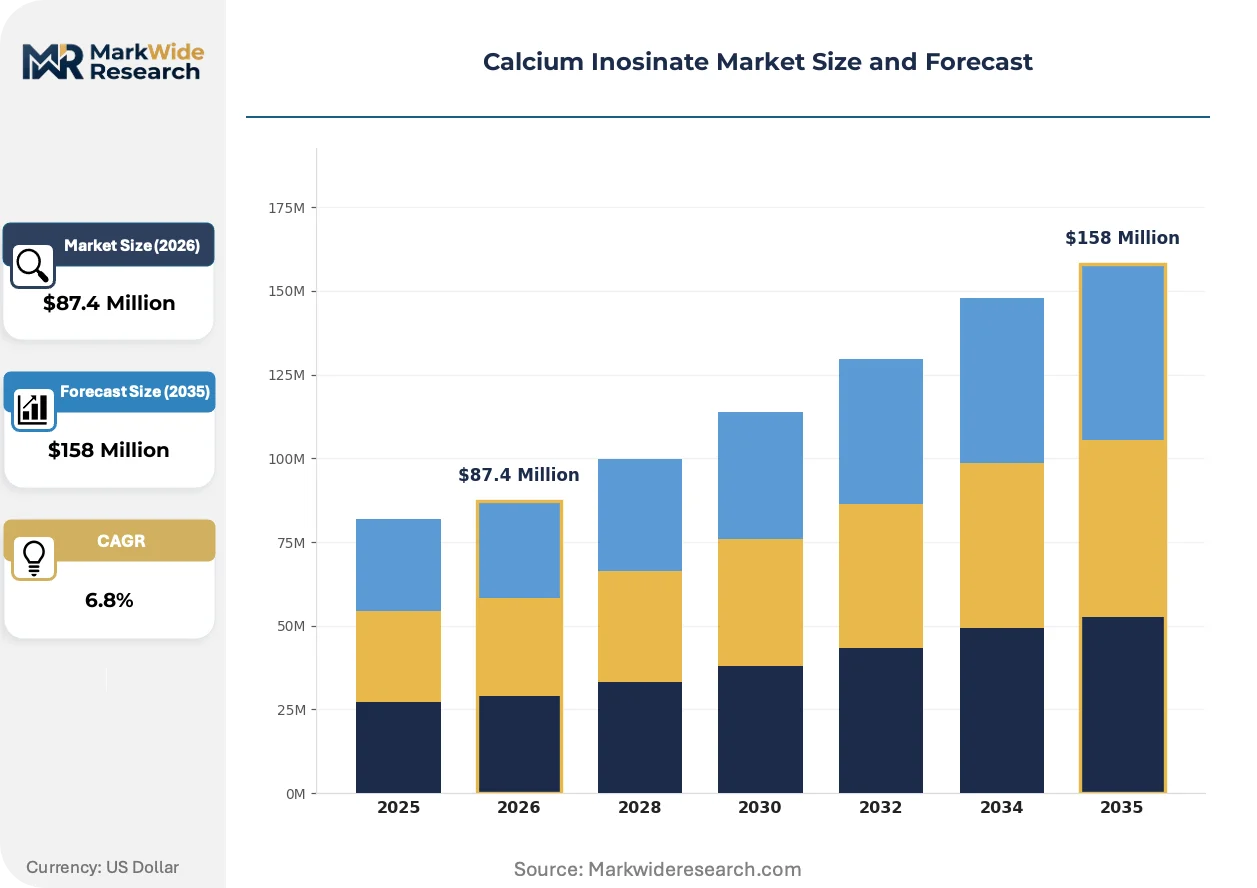
| Market Size in 2026 | $87.4 Million |
| Market Size in 2035 | $158 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Powder, Granules, Tablets, Capsules Application: Food Additive, Dietary Supplement, Flavor Enhancer, Animal Feed End User: Food & Beverage Industry, Pharmaceutical Companies, Nutraceutical Manufacturers, Agriculture Sector Distribution Channel: Online Stores, Supermarkets, Specialty Retailers, Direct Sales |
| Companies Covered | Ajinomoto Co., Inc., CJ CheilJedang Corporation, Fufeng Group Limited, Meihua Holdings Group Co., Ltd., Gulshan Polyols Ltd., Triveni Interchem Pvt. Ltd., Qingdao Develop Chemistry Co. Ltd., Daesang Corporation, Star Lake Bioscience, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Calcium Inosinate Market Strategic Shifts
Microbial strain engineering and downstream processing advances are compressing production economics while regulatory divergence between major jurisdictions is fragmenting certification strategies.
Continuous fermentation systems with real-time metabolite monitoring are expanding into calcium inosinate manufacturing, enabling titers above traditional batch methods. Mid-size flavor houses in Southeast Asia are adopting these systems to bypass Shandong supply dependence. The technology is expanding into pharmaceutical-grade production, where batch consistency requirements previously blocked continuous methods.
EU F-Gas Regulation phase-down schedules are forcing solvent recovery retrofits at continental purification facilities. ECHA REACH registration updates for nucleotide salts are elevating analytical documentation burdens. Food additive segment manufacturers are responding by relocating aqueous recovery capacity to jurisdictions with streamlined chemical registration frameworks.
Online stores are displacing traditional distributor networks for nutraceutical-grade calcium inosinate procurement. Mid-size buyers seeking sub-ton lot sizes now source directly through specialized chemical marketplaces, bypassing regional distributors that imposed minimum order thresholds. This channel shift is most visible in North American immune-support supplement manufacturing, where formulation agility outweighs volume pricing.
Calcium Inosinate Market Segmentation
Calcium inosinate buyers diverge sharply by purity requirements and lot-size flexibility, with food additive purchasers prioritizing bulk powder consistency while nutraceutical formulators demand certified pharmaceutical grades in smaller quantities. Segmentation reveals how regulatory certification tiers and channel accessibility fragment addressable markets across application verticals.
Product Type:
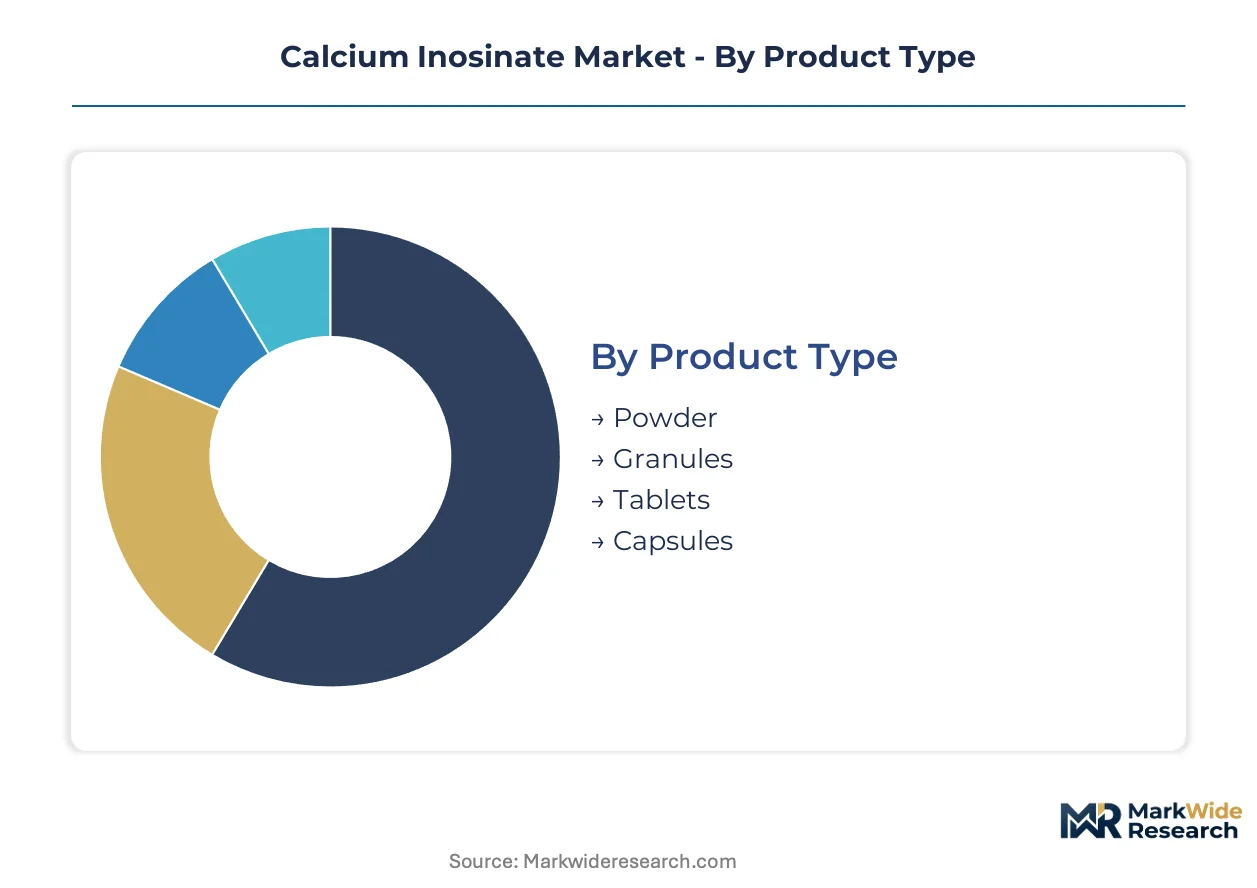
Powder formulations attract high-volume food manufacturers seeking blending uniformity, while tablets and capsules command premium positioning in direct-to-consumer nutraceutical channels.
- Powder:Fine-mesh calcium inosinate powder specified at 97-102% purity on an anhydrous basis serves as the standard input for savory seasoning blends and processed food bases. Demand concentrates among Shandong-based fermentation facilities supplying bulk flavor houses, with EFSA food additive evaluations and FDA GRAS status determining export-grade eligibility for cross-border trade.
- Granules:Agglomerated particle structures improve flowability in high-speed packaging lines for snack seasonings and soup base manufacturing. European savory formulators favor granules for reduced dust generation during automated blending operations, though aqueous recovery system investments elevate unit economics versus powder alternatives.
- Tablets:Compressed nucleotide delivery formats target immune-support supplement positioning in North American nutraceutical retail. Amazon and specialized chemical marketplaces displace traditional distributor minimums for sub-ton procurement.
- Capsules:Encapsulated calcium inosinate serves pediatric and geriatric nutrition segments requiring precise dosing control. Direct sales channels capture premium-tier pharmaceutical-grade certification requirements.
Powder leads volumes today; capsules are gaining share fastest.
Application:
End-use differentiation tracks regulatory exposure, with food additive volumes scaling through clean-label reformulations while dietary supplements exploit nucleotide health positioning outside strict additive frameworks.
- Food Additive:Calcium inosinate functions as a flavor potentiator synergizing with glutamates to amplify umami perception in processed foods and savory seasonings. EU EFSA tightening of additive disclosure requirements accelerates partial replacement of monosodium glutamate in premium seasoning formulations, with Ajinomoto leveraging decades of fermentation expertise to sustain high-purity grade leadership.
- Dietary Supplement:Nucleotide incorporation into immune-support and gut-health formulations represents the steepest expansion trajectory outside traditional food applications. Nutraceutical manufacturers source through online stores for formulation agility, bypassing regional distributor thresholds.
- Flavor Enhancer:Standalone umami amplification applications in restaurant and institutional foodservice channels. China's National Health Commission purity standards enable domestic production for captive consumption.
- Animal Feed:Palatability enhancement for aquaculture and livestock nutrition formulations. Agricultural commodity cycle exposure compresses margin predictability for fermentation operators supplying this tier.
Food additive dominates current offtake; dietary supplement climbs the fastest.
End User:
Customer procurement sophistication spans commodity tender-based purchasing at agricultural processors versus certified quality agreements with pharmaceutical manufacturers requiring dual FDA-EFSA documentation.
- Food & Beverage Industry:Savory seasoning formulators and processed food manufacturers constitute the anchor demand base, with clean-label mandates under EU EFSA and US FDA frameworks driving nucleotide substitution strategies.
- Pharmaceutical Companies:High-purity grade requirements for parenteral and specialized therapeutic applications. Dual certification timelines of 18-24 months for FDA GRAS self-affirmation and EFSA evaluation create supply scarcity premiums.
- Nutraceutical Manufacturers:Immune-modulation and gut-health positioning drives pediatric and geriatric segment penetration with limited incumbent saturation.
- Agriculture Sector:Feed palatability applications in aquaculture and intensive livestock operations. Corn starch and molasses feedstock price volatility transmits directly to procurement costs.
Food and beverage industry leads volumes today; nutraceutical manufacturers are gaining share fastest.
Distribution Channel:
Channel selection reflects lot-size requirements and certification documentation intensity, with bulk powder flowing through direct sales while fragmented nutraceutical buyers aggregate through digital marketplaces.
- Online Stores:Specialized chemical marketplaces and Amazon displace traditional distributor networks for mid-size nutraceutical buyers seeking sub-ton lot sizes. North American immune-support supplement manufacturing exhibits the most visible channel shift.
- Supermarkets:Limited retail shelf presence for finished supplement products containing calcium inosinate as a labeled ingredient. Consumer recognition of nucleotide ingredients remains nascent outside Japan.
- Specialty Retailers:Professional-grade ingredient suppliers serving regional flavor houses and independent supplement formulators. REACH compliance documentation burdens elevate analytical requirements for European market access.
- Direct Sales:Pharmaceutical-grade tier control through certified quality agreements with Ajinomoto's established network. White space exists for certified entrants targeting high-purity segments outside incumbent coverage.
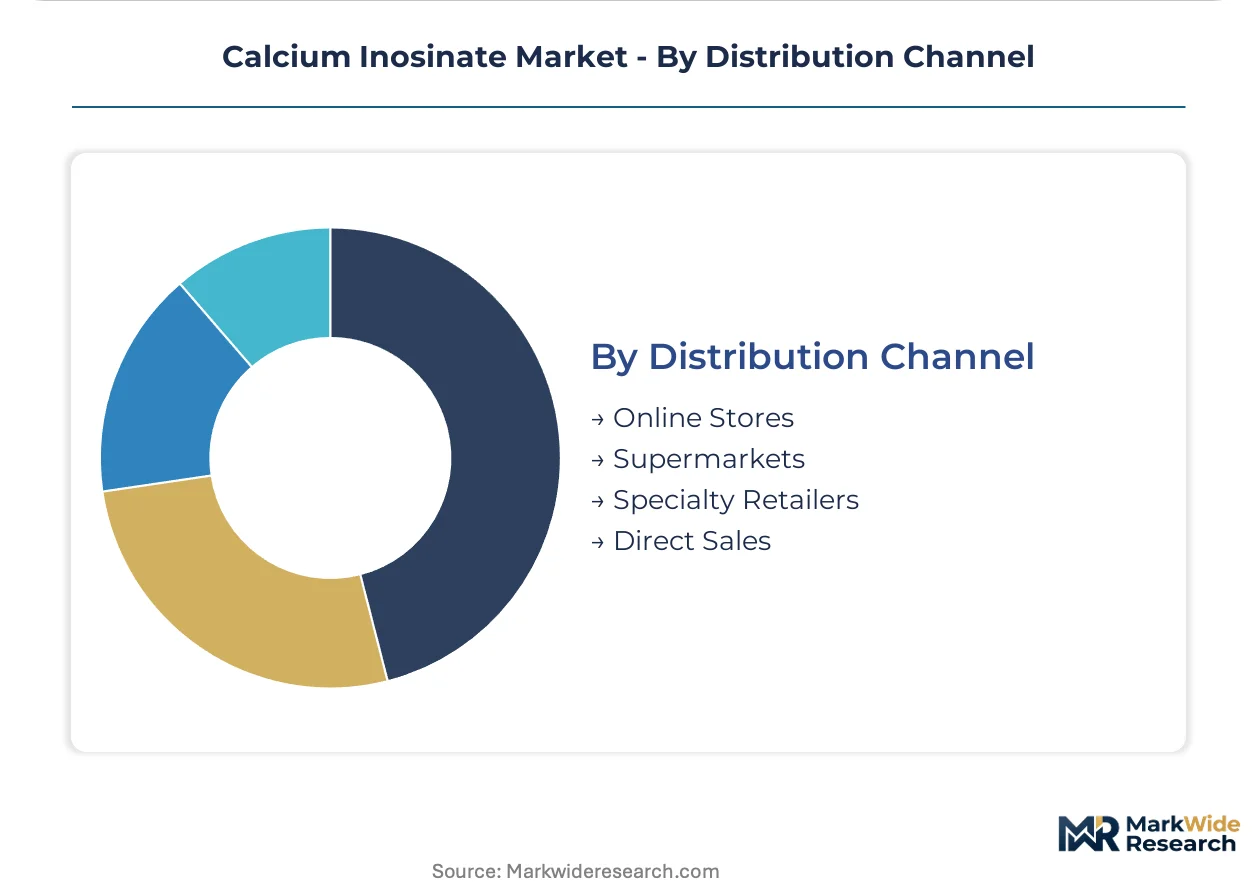
Direct sales leads volumes today; online stores are gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Shandong province facilities anchor global bulk powder capacity, while fermentation-based nucleotide production clusters in East Asian coastal zones and European purification sites adapt to solvent-phase regulatory constraints.
China
Domestic flavor enhancer production drives volume demand as savory seasoning manufacturers respond to National Health Commission purity standards. The country's export-grade certification framework enables cross-border trade for Shandong-based fermentation complexes. Qingdao and Weifang industrial zones concentrate aqueous recovery system investments that bypass REACH solvent constraints.
United States
North American immune-support supplement manufacturing exhibits visible channel migration toward online procurement platforms. FDA GRAS self-affirmation timelines shape market entry economics for new nucleotide suppliers. Midwest nutraceutical formulators in Illinois and Wisconsin source sub-ton quantities through specialized chemical marketplaces.
Japan
Decades of microbial fermentation expertise sustain high-purity grade leadership in premium seasoning applications. METI industrial standards and PMDA pharmaceutical-grade specifications create dual certification pathways for nucleotide salts. Kanto region facilities around Tokyo maintain integrated carbohydrate-to-purification complexes.
Germany
EU F-Gas Regulation phase-down schedules force solvent recovery retrofits at continental purification sites. ECHA REACH registration updates elevate analytical documentation burdens for nucleotide salt imports. North Rhine-Westphalia chemical processing clusters relocate aqueous capacity to jurisdictions with streamlined registration frameworks.
South Korea
Integrated lysine-inosinate production complexes anchor regional supply chain control. MFDS pharmaceutical-grade specifications and food additive evaluations create certification alignment with EU and US frameworks. Busan-Ulsan industrial zones concentrate fermentation capacity serving both domestic seasoning and export pharmaceutical markets.
Calcium Inosinate Market Competitive Environment
Global majors compete with regional champions across fermentation scale and certification tier depth. The vendor base organizes around three strategic archetypes: integrated amino acid-nucleotide conglomerates, standalone fermentation specialists, and purified-grade traders serving nutraceutical channels. Competitive moves concentrate on backward integration into carbohydrate feedstock sourcing and aqueous recovery technology licensing to circumvent EU solvent regulations.
Among Japanese and Korean industrial conglomerates, Ajinomoto Co., Inc. and CJ CheilJedang Corporation exemplify integrated production archetypes with decades of nucleotide fermentation lineage. Chinese bulk manufacturers occupy the scale-driven tier, with Fufeng Group Limited representing fermentation capacity concentration in Shandong province. These three anchors sit within distinct competitive vectors: premium-grade certification, integrated lysine-nucleotide complexes, and bulk powder manufacturing scale.
| Leading Market Players |
|---|
| Ajinomoto Co., Inc. |
| CJ CheilJedang Corporation |
| Fufeng Group Limited |
| Meihua Holdings Group Co., Ltd. |
| Gulshan Polyols Ltd. |
| Triveni Interchem Pvt. Ltd. |
| Qingdao Develop Chemistry Co. Ltd. |
| Daesang Corporation |
| Star Lake Bioscience |
| Others |
Value Chain & Pricing Dynamics
EU F-Gas Regulation phase-down schedules gate qualified supply for European market access and premium-tier pricing eligibility, forcing manufacturers toward aqueous recovery investments that stratify cost structures across certification grades. Shandong-based bulk producers compete on manufacturing scale while Japanese and Korean incumbents capture pharmaceutical-grade premiums through dual FDA-EFSA documentation.
Pricing Analysis
Corn starch and molasses feedstock volatility transmits directly through fermentation economics, compressing margin predictability for bulk powder operators. Three-tier pricing structure separates pharmaceutical-grade certified product from food additive standard grades and economy-tier feed applications. Cost compression in the bulk tier is intensifying because Shandong capacity additions outpace seasoning demand growth. Agricultural processors exhibit highest price sensitivity, while pharmaceutical manufacturers absorb premiums for dual-certified documentation.
Supply Chain Analysis
Direct-to-flavor-house channels handle high-volume food additive demand, while specialized chemical marketplaces serve fragmented nutraceutical buyers. Supply concentrates in China, Japan, and South Korea, with Shandong province anchoring global bulk powder capacity. Fermentation draws from corn starch, molasses, and proprietary microbial strain inputs. Single-source vulnerability runs through Shandong's geographic clustering, exposing buyers to regional energy rationing or environmental enforcement disruptions.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Clean-label reformulation mandates across EU and US regulatory frameworks position calcium inosinate as a stable compounder, with nucleotide substitution in premium seasonings driving steady volume expansion.
For Market Incumbents: Lock in carbohydrate feedstock sourcing through backward integration into corn starch supply or long-term molasses offtake agreements with agricultural processors. Expand aqueous recovery capacity in Qingdao and Weifang industrial zones to preempt EU F-Gas compliance costs. Certification investment in simultaneous FDA GRAS and EFSA additive pathways defends against emerging Chinese exporters gaining dual documentation capabilities. For New Entrants and Emerging Players: Begin with pharmaceutical-grade white space outside Ajinomoto's established direct sales network, where 18-24 month dual certification timelines create supply scarcity premiums. Target North American nutraceutical manufacturers sourcing through Amazon and specialized chemical marketplaces for sub-ton immune-support formulation demand. A go-to-market angle emphasizing pediatric and geriatric nucleotide positioning bypasses incumbent saturation in standard food additive tiers. For Investors and Strategic Acquirers: Roll-up economics work for regional fermentation specialists with captive strain libraries because aqueous recovery technology licensing creates defendable process moats. Five-to-ten year viability hinges on clean-label mandate durability across EU EFSA and US FDA frameworks. Acquisition targets should demonstrate integrated carbohydrate-to-purification complexes or proprietary microbial engineering capabilities. The signal to watch is EFSA food additive evaluation backlog duration, which indicates pricing power inflection for certified suppliers.| Strategic Initiative | Industry Significance |
|---|---|
| Aqueous Recovery System Investment | EU F-Gas Regulation compliance streamlines EFSA approval pathways for Shandong manufacturers. |
| Dual Certification Pathway | Simultaneous FDA GRAS and EFSA evaluation unlocks pharmaceutical-grade pricing premiums. |
| Feedstock Backward Integration | Corn starch and molasses sourcing control buffers agricultural commodity cycle exposure. |
| Continuous Fermentation Scale-Up | Real-time metabolite monitoring enables titers above traditional batch methods for mid-size flavor houses. |
| Online Marketplace Channel Expansion | Specialized chemical marketplaces displace distributor minimums for North American nutraceutical procurement. |
Study Parameters
Direct dialogue with fermentation plant managers, savory seasoning formulators, nutraceutical procurement leads, and regulatory affairs specialists at nucleotide manufacturers grounded qualitative insights. Secondary validation drew from FDA GRAS notifications, EFSA food additive evaluations, customs and trade data for nucleotide salt flows, and SEC filings of publicly traded amino acid producers. Bottom-up capacity assessments across Shandong province facilities triangulated with top-down demand modeling from clean-label reformulation trends.
Segment-level projections across powder, granule, tablet, and capsule formulations combined with application splits between food additive, dietary supplement, and pharmaceutical-grade tiers. CAGRs were derived from elasticity-adjusted volume trajectories tied to EFSA evaluation timelines and US FDA self-affirmation patterns. Forecast inputs included microbial strain productivity advances, aqueous recovery adoption rates, and online channel penetration in North American immune-support manufacturing.
Several conditions sit outside the modeled scope, including abrupt EU F-Gas Regulation enforcement actions, Shandong environmental policy shifts, and breakthrough synthetic biology routes to nucleotide production. Forecasts reflect assumptions around regulatory divergence persistence and fermentation scale economies. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Additives and Ingredients
Europe Food Micronized Salt Market
Food Additives and Ingredients
Russia Food Preservatives Market
Food Additives and Ingredients
Food Grade Phosphates Market
Food Additives and Ingredients
Ammonium Chloride Food Grade Market
Food Additives and Ingredients
Clean Label Ingredients Market
Food Additives and Ingredients
Food Grade Dipotassium Phosphate Market
Food Additives and Ingredients
Flour Treatment Agent Market
Food Additives and Ingredients
Microencapsulation Market
Food Additives and Ingredients
Brazil Food Acidulants Market
Food Additives and Ingredients
North America Clean Label Ingredient Market
Food Additives and Ingredients
Cream Emulsifier Market
Food Additives and Ingredients
Mexico Food Additives Market
Food Additives and Ingredients
Carrageenan Market
Food Additives and Ingredients
Food Antimicrobial Additives Market
Food Additives and Ingredients
Oxidized Starch Market
Food Additives and Ingredients
Argentina Food Additives Market