
 Global Edible Films and Coatings for Fruits and Vegetables Market | 2026-2036
Global Edible Films and Coatings for Fruits and Vegetables Market Size, Share, and Industry Trends Forecast 2026-2036
Global Edible Films and Coatings for Fruits and Vegetables Market Foresight
Direct-to-retail supply contracts between coating suppliers and supermarket chains is reconfiguring procurement patterns across the produce sector. Apeel Sciences leverages its plant-derived lipid barrier platform to dominate shelf-life extension programs for avocado and citrus exporters. Tate & Lyle anchors polysaccharide formulation supply through its established hydrocolloid distribution networks. Sumitomo Chemical competes in Asian commercial shipping channels with composite film systems engineered for tropical fruit humidity control.
Edible films and coatings for fruits and vegetables constitute thin, consumable layers applied to fresh produce surfaces, typically formulated from polysaccharides, proteins, lipids, or composite blends at thicknesses between 0.01 and 0.5 millimeters to reduce moisture loss and gas exchange. These barriers serve the commercial purpose of extending postharvest viability without synthetic chemical residues that trigger regulatory rejection at import inspection points. Polysaccharide-based formulations currently occupy the largest formulation share due to favorable cost structures and established GRAS status, while composite films represent the fastest-growing category as processors seek multifunctional barriers combining moisture resistance with antimicrobial activity. Protein-based coatings sustain premium positioning among organic retail chains that restrict petroleum-derived inputs, though lipid-based alternatives dominate wax-replacement applications for citrus and apple surface finishing.
The FDA governs coating components under food additive regulations, while the EU Green Deal and REACH framework restrict synthetic preservative migration into edible tissue, compelling reformulation toward plant-derived inputs. EFSA evaluations of novel protein coatings determine market access timelines for European-bound exports from Latin American agricultural cooperatives. Stakeholders must monitor evolving residue threshold harmonization between FDA and EMA standards to avoid shipment detention at transatlantic ports.
Market Dynamics
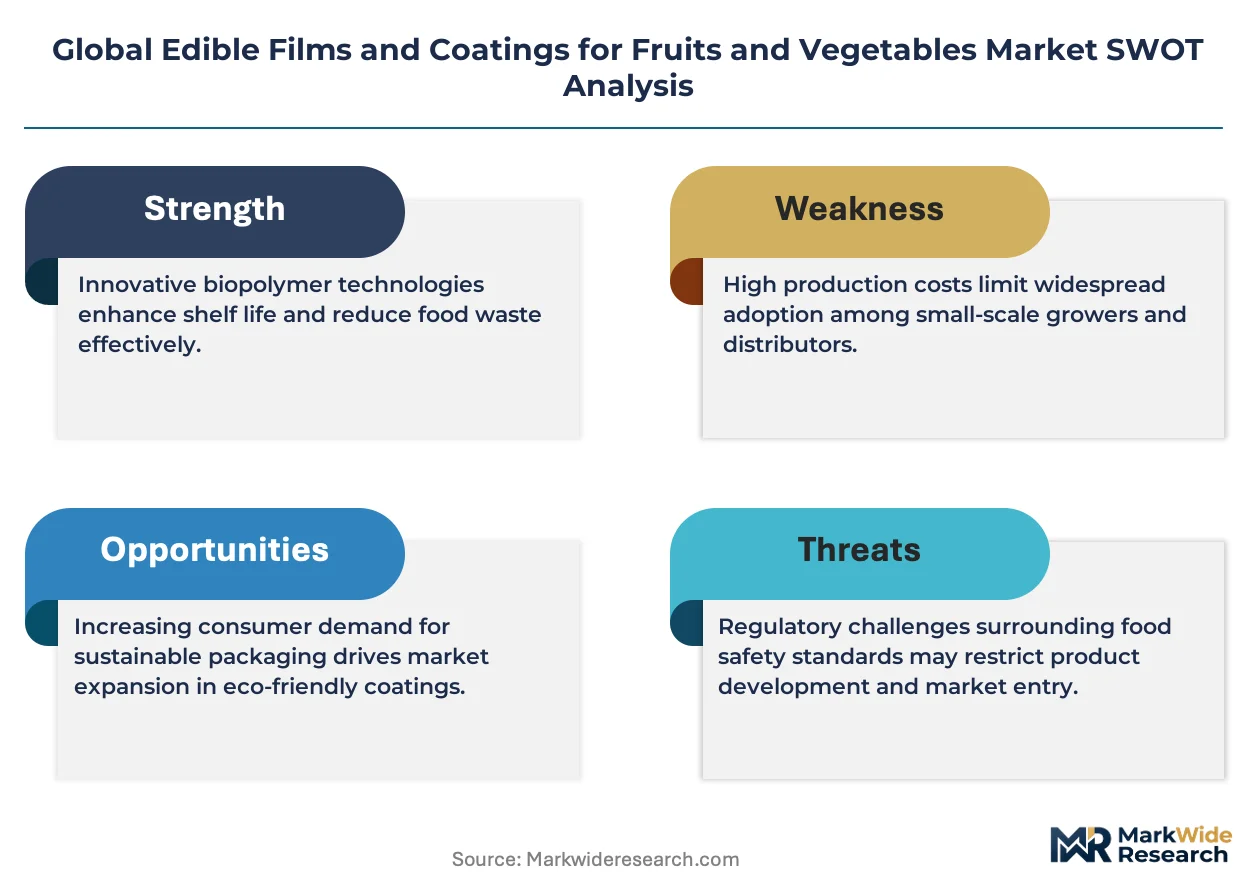
Fresh-cut produce processors face mounting pressure to eliminate synthetic wax residues as the EU Green Deal and F-Gas Regulation tighten import thresholds, forcing rapid reformulation toward plant-derived barrier technologies.
Growth Catalysts
- EU Green Deal residue mandates:The framework's tightening chemical thresholds on imported produce compel Latin American agricultural cooperatives to adopt edible coatings for European market access.
- Brazilian export transit requirements:Extended shipping durations to European retail chains drive demand for humidity-controlling film systems in São Paulo and Minas Gerais agricultural clusters.
- Polysaccharide GRAS status:Established FDA safety classifications accelerate regulatory approval timelines for hydrocolloid-based formulations entering US supermarket supply chains.
Market Restraints
- Protein input cost volatility:Fluctuating whey and collagen prices squeeze margins for organic-certified coating suppliers targeting premium retail channels.
- Antimicrobial additive supply concentration:Chitosan sourcing depends heavily on Southeast Asian crustacean processing clusters, exposing formulators to weather and trade disruptions.
- REACH compliance friction:ECHA substance evaluation timelines delay novel lipid barrier introductions by 18-24 months for European-bound exports.
Strategic Opportunities
- Indian fresh-cut segment expansion:FSSAI clean-label mandates create entry points for polysaccharide coatings in Mumbai and Bangalore organized retail.
- Antimicrobial-protein convergence:Combining chitosan with pea protein isolates enables dual-function barriers for tropical fruit exporters.
- Direct-to-retail procurement channels:Supermarket chain coating specifications bypass traditional distributor markups in German and Dutch retail networks.
Industry Challenges
- Formulation chemist talent scarcity:Shortages of specialists trained in both food science and polymer chemistry constrain R&D throughput for composite film development.
- EFSA novel food approval timelines:Protein coating dossier evaluations create 24-36 month market access gaps for Latin American cooperatives.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Edible Films and Coatings for Fruits and Vegetables Market |
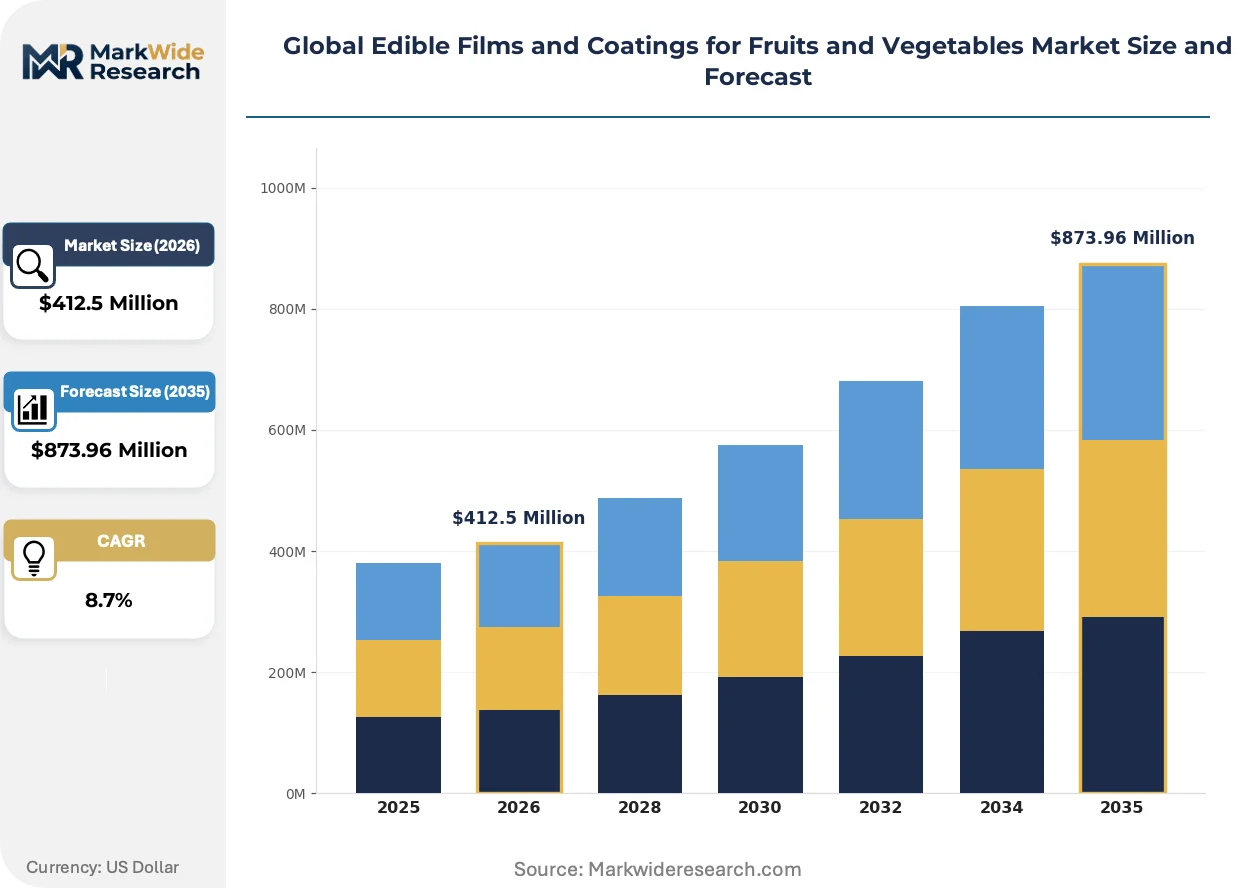
| Market Size in 2026 | $412.5 Million |
| Market Size in 2035 | $873.96 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Polysaccharide-Based, Protein-Based, Lipid-Based, Composite Films Application: Fresh-Cut Protection, Shelf-Life Extension, Quality Preservation, Pest Control End User: Food Processors, Commercial Shippers, Retail Chains, Agricultural Cooperatives Packaging Type: Films, Spray Coatings, Dips, Wax Coatings, Edible Wraps |
| Companies Covered | Apeel Sciences, Hazel Technologies, RPM International, Tate & Lyle, Sufresca, Sumitomo Chemical, Flo Chemical Corporation, Pace International, Kerry Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Edible Films and Coatings for Fruits and Vegetables Market Shifts & Advancements
Active barrier technologies and procurement restructuring are compressing traditional supply relationships while regulatory harmonization pressures force simultaneous multi-jurisdiction compliance strategies.
Composite lipid-polysaccharide films incorporating plant-derived antimicrobial agents are rendering obsolete single-function synthetic wax coatings in citrus and avocado export operations. Major Brazilian and Peruvian packing houses now specify these multifunctional barriers for European-bound shipments. The technology is rendering obsolete legacy petroleum-derived surface finishes that fail EU residue testing protocols.
REACH substance restriction amendments and the EU F-Gas Regulation are accelerating elimination of fluorinated coating components from fruit surface treatments. ECHA evaluation schedules now determine reformulation investment cycles for coating manufacturers serving transatlantic trade lanes. Latin American agricultural cooperatives front-load EFSA dossier preparation to preempt detention risks at Rotterdam and Hamburg inspection points.
Supermarket chains now issue direct coating specifications that displace distributor-mediated procurement in produce supply chains. German REWE Group and Dutch Albert Heijn binding technical requirements override traditional supplier relationships for shelf-life extension programs. This pattern concentrates most visibly in Northern European retail networks where centralized produce sourcing dominates category management.
Global Edible Films and Coatings for Fruits and Vegetables Market Segmentation
Formulation chemistry, application method, and procurement channel each dictate distinct margin structures and regulatory compliance burdens across the edible coatings sector. Segmentation reveals where technology investments concentrate versus where commoditization pressures dominate.
Product Type:
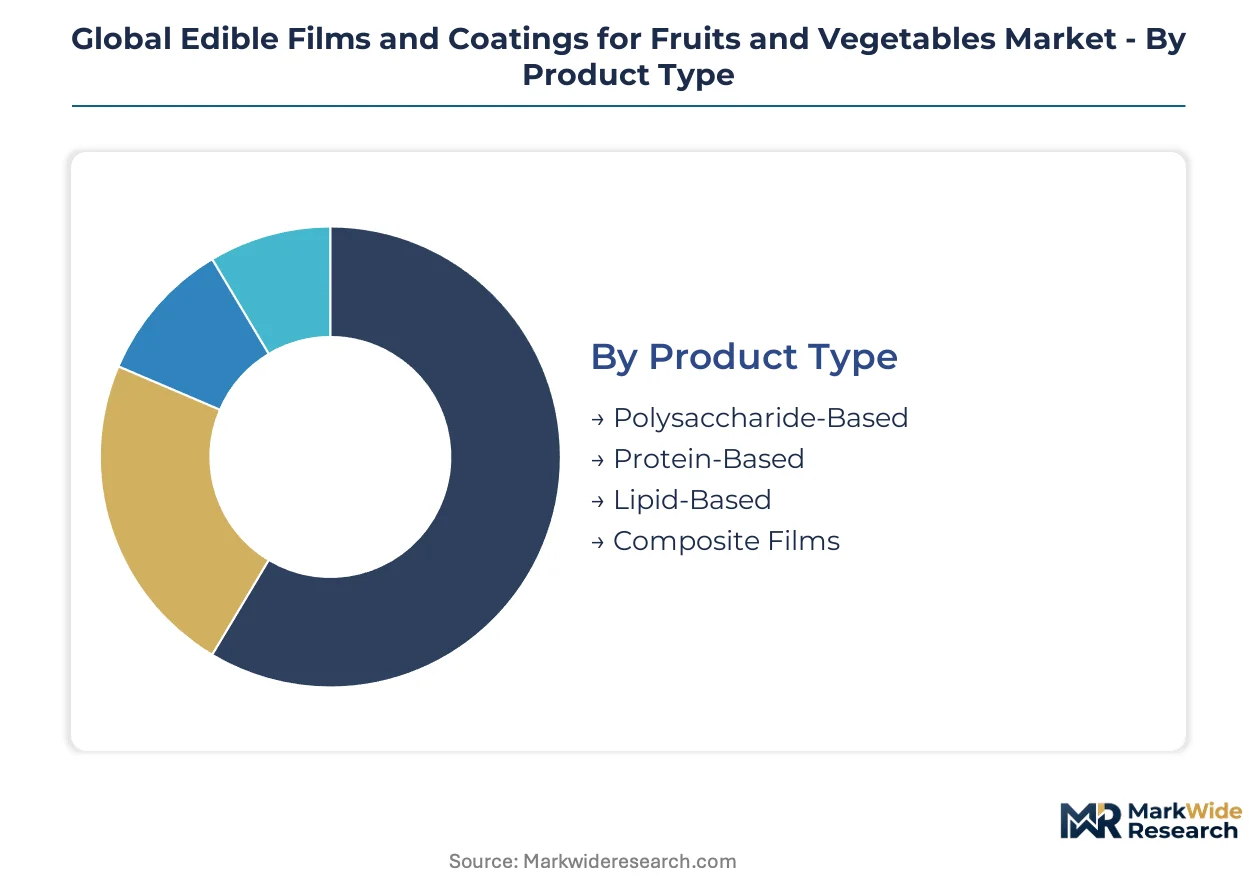
Polysaccharide formulations anchor commodity volume, while composite systems command premium positioning through multifunctional performance.
- Polysaccharide-Based:Hydrocolloid matrices from starch, cellulose, and alginate dominate cost-sensitive applications. FDA GRAS status accelerates US supermarket adoption, though margin compression intensifies as Brazilian agricultural cooperatives standardize on basic formulations.
- Composite Films:Layered lipid-polysaccharide architectures integrate moisture barriers with antimicrobial activity. European-bound citrus and avocado exporters in São Paulo and Peru specify these systems to satisfy EU Green Deal residue thresholds.
- Protein-Based:Whey and collagen isolates serve organic retail chains restricting petroleum-derived inputs.
- Lipid-Based:Plant-derived wax replacements dominate surface finishing for apples and citrus.
Established volume favors polysaccharide formulations; emerging adoption favors composite films.
Application:
Functional requirements range from passive moisture retention to active antimicrobial intervention across postharvest handling stages.
- Shelf-Life Extension:Barrier systems targeting ethylene permeability reduction and respiration control. Latin American exporters to European retail chains deploy these coatings to survive 21-28 day maritime transits through humidity-calibrated formulations.
- Fresh-Cut Protection:Surface treatments for sliced produce preventing enzymatic browning and microbial colonization. Indian organized retail in Mumbai and Bangalore drives specification tightening under FSSAI clean-label mandates.
- Quality Preservation:Color retention and texture maintenance for premium cultivars.
- Pest Control:Botanical-infused barriers replacing synthetic fumigants in organic supply chains.
Shelf-life extension commands the largest application spend; fresh-cut protection is climbing the fastest as processing infrastructure expands in emerging markets.
End User:
Procurement authority concentrates differently across fragmented agricultural supply chains versus consolidated retail networks.
- Agricultural Cooperatives:Latin American grower associations in Minas Gerais and Peru's Ica Valley specify coatings for export certification compliance. EFSA dossier preparation absorbs significant administrative bandwidth for European market access.
- Retail Chains:German REWE Group and Dutch Albert Heijn issue binding technical specifications that displace distributor relationships. Direct-to-retail contracting compresses traditional supply margins while locking in volume commitments.
- Commercial Shippers:Maritime logistics operators prioritize humidity stability for tropical fruit consignments.
- Food Processors:Fresh-cut facilities integrate coating application into HACCP workflows.
Retail chain procurement is gaining share fastest; agricultural cooperatives retain the deepest volume base.
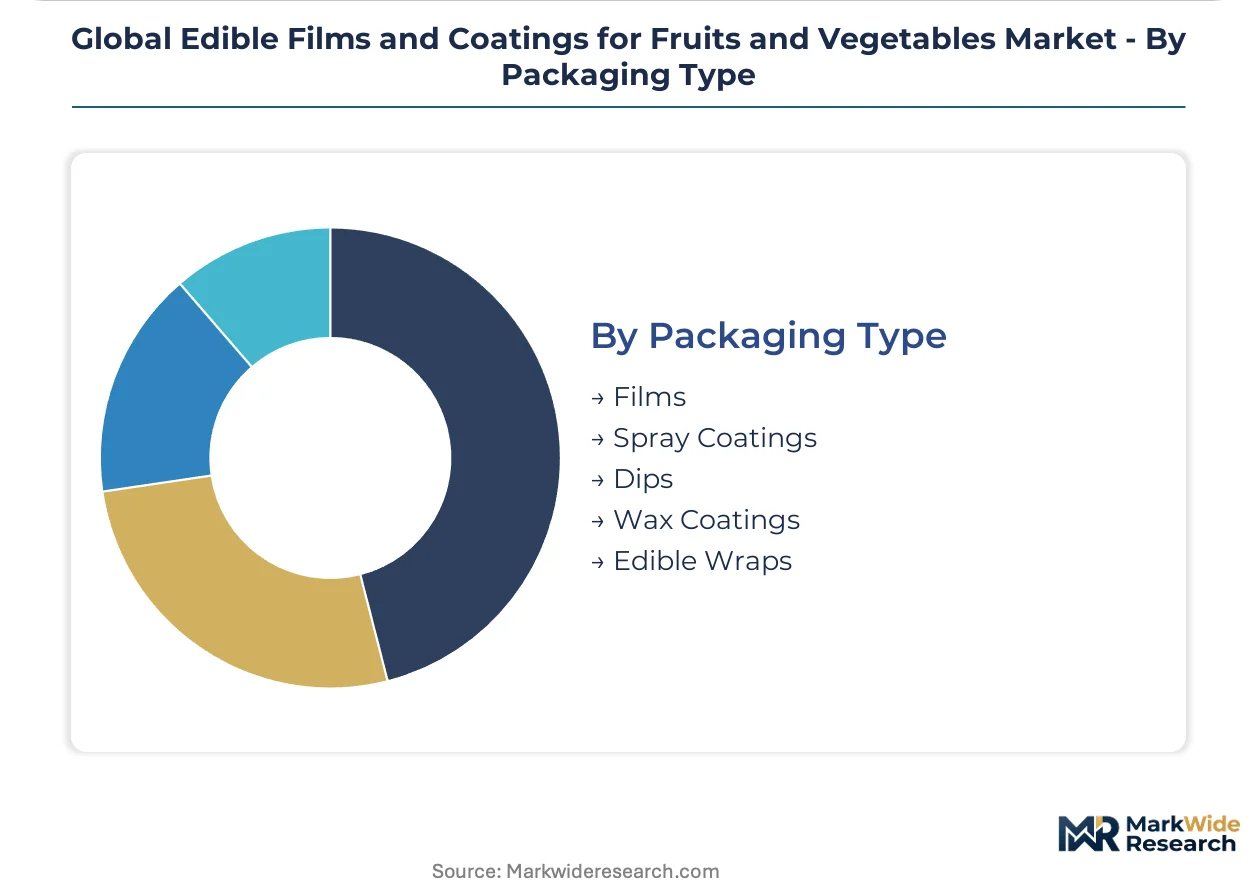
Packaging Type:
Application technology determines coating uniformity, throughput economics, and compatibility with existing packing house infrastructure.
- Spray Coatings:Atomized application systems integrate into high-speed packing lines for citrus and stone fruit. Brazilian São Paulo packing houses favor this method for wax replacement programs targeting European export markets.
- Films:Pre-formed sheets for individual fruit wrapping in premium retail presentation. Japanese supermarket chains specify these for gift-grade melon and strawberry categories.
- Dips:Immersion tanks for complete surface coverage on irregular geometries.
- Wax Coatings:Legacy petroleum-derived systems facing REACH restriction pressure.
- Edible Wraps:Sheet formats for fresh-cut salad and herb bundling.
Spray coatings dominate throughput economics; films command the steepest expansion trajectory in premium Asian retail channels.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Port of Rotterdam's cold-chain infrastructure underwrites European import handling for coated produce shipments from Latin America and Southeast Asia. This logistics backbone determines coating specification requirements for exporters targeting Dutch, German, and Belgian retail distribution networks.
Brazil
Agricultural cooperatives in São Paulo and Minas Gerais states face 21-28 day maritime transits to Northern European retail chains. ANVISA alignment with EFSA evaluation protocols accelerates coating approval timelines for export-bound shipments. Packing houses in the São Paulo citrus belt now specify composite lipid-polysaccharide barriers to satisfy EU Green Deal residue thresholds.
Germany
REWE Group and Aldi Süd issue binding technical specifications that displace traditional distributor relationships in produce procurement. The country's national food safety regulator enforces REACH-compliant coating standards through import inspection protocols at Hamburg and Bremerhaven ports. Bavarian fresh-cut processors integrate coating application into HACCP workflows for supermarket private-label programs.
United States
California's Central Valley avocado and citrus exporters deploy plant-derived barriers to replace petroleum-based waxes under FDA food additive regulations. The Los Angeles-Long Beach port complex handles coated produce volumes destined for national retail distribution networks. Florida grapefruit packing houses favor spray application systems for high-throughput wax replacement programs.
India
FSSAI clean-label mandates create specification tightening for polysaccharide coatings in Mumbai and Bangalore organized retail channels. The Jawaharlal Nehru Port Trust infrastructure supports coated produce exports to Middle Eastern markets. Agricultural clusters in Maharashtra and Gujarat states adopt humidity-controlling films for extended domestic supply chains.
Japan
METI standards for food-contact materials drive premium-tier coating adoption for gift-grade melon and strawberry presentation formats. The Port of Yokohama's cold-chain facilities handle coated tropical fruit imports from Southeast Asian suppliers. Tokyo metropolitan retail chains specify pre-formed edible films for individual fruit wrapping in high-value categories.
Global Edible Films and Coatings for Fruits and Vegetables Market Competitive Landscape
On the supply side, the industry is consolidating around technology platforms rather than commodity chemical production. Specialist coating formulators compete with diversified hydrocolloid suppliers for procurement contracts with agricultural cooperatives and retail chains. Three archetypes dominate: plant-derived barrier technology platforms, established food ingredient distributors with coating portfolios, and chemical conglomerates with film system engineering capabilities. Competitive moves concentrate on direct-to-retail procurement channel establishment and EFSA dossier preparation partnerships with Latin American exporters.
Within the technology platform tier, Apeel Sciences and Hazel Technologies exemplify the plant-derived lipid barrier approach for shelf-life extension programs. Tate & Lyle occupies a position among established food ingredient suppliers leveraging hydrocolloid distribution networks. Sumitomo Chemical represents the diversified chemical conglomerate archetype competing in Asian commercial shipping channels. These three anchors illustrate the strategic segmentation between innovation-driven specialists, incumbent ingredient distributors, and scale-oriented chemical manufacturers.
| Leading Market Players |
|---|
| Apeel Sciences |
| Hazel Technologies |
| RPM International |
| Tate & Lyle |
| Sufresca |
| Sumitomo Chemical |
| Flo Chemical Corporation |
| Pace International |
| Kerry Group |
| Others |
Supply & Pricing Matrix
São Paulo state's citrus packing belt concentrates composite film formulation capacity, and its volume throughput dynamics translate directly into pricing leverage for European-bound exporters facing EU Green Deal residue compliance costs.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels dominates procurement contracts. Price differentiation centers on EFSA certification status and volume scale, with organic-certified protein coatings commanding substantial premiums over commodity polysaccharide grades. Pricing pressure stems from Brazilian agricultural cooperative consolidation, which squeezes margins on basic hydrocolloid formulations. Fresh-cut processors in Indian organized retail channels exhibit the highest price sensitivity, while German REWE Group and Dutch Albert Heijn tolerate premium tiers for direct specification compliance.
Supply Chain Analysis
Toll manufacturing capacity for edible film coating application concentrates among specialized food-grade contract processors in Brazil, India, and the United States. Raw material sourcing draws from Southeast Asian chitosan clusters, Midwestern US whey processing facilities, and European alginate harvesting operations. Single-source vulnerability in crustacean-derived antimicrobial inputs exposes formulators to weather disruption and trade policy shifts. Distribution runs through agricultural cooperative aggregation points into direct retail chain procurement channels, bypassing traditional ingredient distributor markups.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Specialist formulation chemists trained in both food science and polymer chemistry remain scarce, constraining R&D throughput for composite film development and creating bottlenecks for coating manufacturers seeking multifunctional barrier innovation.
For Market Incumbents: Entrench regulatory dossier capabilities through EFSA pre-submission partnerships with Latin American agricultural cooperatives, eliminating 18-24 month approval delays that threaten European market access. Deepen backward integration into chitosan sourcing through captive crustacean processing agreements, mitigating Southeast Asian supply concentration risk. Prioritize direct-to-retail contracting with Northern European supermarket chains to lock out distributor-dependent competitors. For New Entrants and Emerging Players: Indian fresh-cut processing infrastructure in Mumbai and Bangalore presents underpenetrated white-space opportunity under tightening FSSAI clean-label mandates. Brazilian Minas Gerais agricultural clusters offer second entry point for humidity-controlling composite systems targeting extended export transit. Lead with antimicrobial-protein convergence formulations as differentiated technical positioning against commodity polysaccharide incumbents. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors plant-derived barrier technology platforms with established EFSA dossier track records over commodity hydrocolloid distributors facing margin compression. Long-term viability across the projection horizon rests on regulatory compliance automation capabilities and direct retail channel lock-in. Monitor ECHA substance evaluation timeline accelerations as inflection signal for reformulation investment cycles.| Strategic Initiative | Industry Significance |
|---|---|
| EFSA Dossier Partnership | Pre-emptive regulatory alignment eliminates detention risks at Rotterdam and Hamburg inspection points. |
| Direct-to-Retail Contracting | Bypassing distributor markups captures margin compression from supermarket chain specification authority. |
| Antimicrobial-Protein Convergence | Dual-function barriers command premium positioning in tropical fruit export segments. |
| Backward Integration into Chitosan | Captive crustacean processing mitigates Southeast Asian supply concentration vulnerability. |
| Fresh-Cut Segment Expansion | FSSAI clean-label mandates in Indian organized retail create specification-driven entry points. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted across primary interview programs with coating formulation chemists, agricultural cooperative procurement managers, supermarket chain technical specification officers, and food safety regulatory consultants. Secondary validation drew from FDA food additive filings, EFSA novel food evaluations, ANVISA export certification records, and customs trade data for coated produce shipments. Bottom-up volume modeling from individual packing house capacity was triangulated against top-down market sizing from hydrocolloid and lipid ingredient consumption patterns.
Calibration against historical adoption curves for wax replacement programs anchored the analytical framework across the analysis window. Segmentation dimensions modeled included formulation chemistry tier, application method, procurement channel authority, and regional regulatory cluster. CAGRs were derived from compound growth trajectory analysis incorporating technology substitution rates for synthetic wax displacement and fresh-cut processing infrastructure expansion. Forecast inputs included EU Green Deal threshold tightening schedules and Brazilian export transit duration requirements.
Practitioners should monitor ECHA substance evaluation timeline shifts and FSSAI clean-label mandate enforcement intensity for early signals of reformulation investment cycles. Forecasts reflect assumptions regarding regulatory harmonization progress between FDA and EMA standards. Quarterly review of coating specification adoption rates at German and Dutch retail chains is advised to detect inflection in direct-to-retail procurement penetration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Additives and Ingredients
Salatrim Market
Food Additives and Ingredients
Sustained Release Excipients Market
Food Additives and Ingredients
Edible and Soluble Films Market
Food Additives and Ingredients
Cook-Up Starch Market
Food Additives and Ingredients
Spain Food Colorants Market
Food Additives and Ingredients
Brazil Food Acidulants Market
Food Additives and Ingredients
Food Grade Magnesium Derivatives Market
Food Additives and Ingredients
Food Grade Glue Market
Food Additives and Ingredients
Middle East and Africa Clean Label Ingredients Market
Food Additives and Ingredients
Bulking Agents Market
Food Additives and Ingredients
Canada Food Enzymes Market
Food Additives and Ingredients
Africa Food Preservatives Market
Food Additives and Ingredients
Calcium Inosinate Market
Food Additives and Ingredients
Polyglycerol Esters of Fatty Acids Market
Food Additives and Ingredients
Africa Microbial Food Culture Market
Food Additives and Ingredients
North America Fermented Ingredient Market