
 Film Forming Starches Market | 2026-2036
Film Forming Starches Market Size, Share, and Industry Trends Forecast 2026-2036
Film Forming Starches Market Foresight
ISO 9001 quality management certification is bifurcating the competitive landscape into qualified suppliers and marginal participants. Cargill, Incorporated leverages its global grain procurement network to sustain cost-advantaged feedstock access. Ingredion Incorporated anchors North American supply through integrated corn wet-milling infrastructure. Roquette Frères competes from European pea starch origins, differentiating on non-GMO positioning and clean-label alignment.
Film forming starches comprise polysaccharide extracts from corn, potato, tapioca, or pea sources, typically exhibiting amylose content between 20-70% depending on botanical origin; manufacturers deploy enzymatic or chemical modification to tune solubility, viscosity, and mechanical strength for barrier coatings or controlled-release matrices. Modified starches command the dominant value share due to functional customization for pharmaceutical and personal care film applications, while pregelatinized variants represent the fastest-expanding category as cold-water solubility eliminates heat-processing steps for energy-sensitive formulators. Native starches retain volume leadership in paper coatings where cost minimization outweighs performance premiums.
FDA excipient guidelines and EMA quality standards govern pharmaceutical-grade starch qualification, with REACH registration requirements in Europe restricting certain chemical modification pathways and propelling enzymatic alternatives. India's CDSCO mandates BIS-compliant excipient testing for imported and domestic film-forming materials, creating compliance thresholds that favor established multinationals with dedicated regulatory affairs capacity. Stakeholders must monitor evolving pharmacopeial monograph revisions and regional substitution incentives for petroleum-derived film formers to anticipate raw-material qualification cycles and capacity allocation decisions.
Market Dynamics
Pharmaceutical excipient qualification timelines are compressing competitive response windows as CDSCO, FDA, and EMA simultaneously tighten purity documentation requirements for film-forming starch suppliers.
Growth Catalysts
- Controlled-Release Formulation Demand:Tablet manufacturers in India and the United States are substituting synthetic polymers with modified starches to achieve tunable dissolution profiles. CDSCO's streamlined excipient approval pathways accelerate domestic qualification cycles.
- REACH Substitution Mandates:ECHA's restrictions on petroleum-derived film formers are forcing European pharmaceutical coaters toward enzymatically modified starches. This regulatory pressure creates immediate pull-through for pea and potato starch alternatives.
- Clean-Label Personal Care:Cosmetic formulators in France and Germany are rejecting synthetic film formers in favor of non-GMO tapioca starches. Consumer ingredient transparency demands are translating into specification changes at contract manufacturers.
Market Restraints
- Amylose Supply Concentration:High-amylose corn genetics remain controlled by a narrow germplasm base concentrated in the United States Midwest. This botanical concentration creates single-source vulnerability for barrier-coating applications.
- Enzymatic Modification Cost Structure:Specialist enzyme inputs for targeted starch hydrolysis carry 40-60% premia over chemical alternatives. European REACH compliance is forcing this costlier pathway without offsetting price recovery mechanisms.
- Cellulose Ether Substitution Threat:Hydroxypropyl methylcellulose (HPMC) continues to defend position in high-performance pharmaceutical coatings. HPMC's established pharmacopeial monographs and broader supplier base resist displacement in premium controlled-release segments.
Strategic Opportunities
- Brazilian Pharmaceutical Localization:ANVISA's import substitution incentives for excipient manufacturing create first-mover advantages for starch processors establishing Brazilian wet-milling capacity. Domestic production avoids currency volatility and import documentation delays.
- Edible Packaging Convergence:Food-grade film starches are converging with active packaging technologies incorporating antimicrobial or oxygen-scavenging functions. Japanese food processors are piloting these dual-function coatings for shelf-life extension.
- CDSCO Domestic Sourcing Mandates:India's phased procurement preferences for BIS-certified local excipients are creating captive demand for indigenous potato and tapioca starch processors. Multinationals are responding through joint ventures with Indian agricultural processors.
Industry Challenges
- Pharmacopeial Harmonization Delays:Divergent USP, EP, and IP monograph specifications for modified starch viscosity and microbial limits force manufacturers to maintain separate production campaigns. This standardization fragmentation inflates inventory carrying costs.
- Specialized Regulatory Affairs Talent Scarcity:The intersection of food chemistry, pharmaceutical GMP, and regional excipient registration requirements creates narrow qualification profiles. CDSCO and EMA submission experience commands 35-50% compensation premia over general regulatory roles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Film Forming Starches Market |
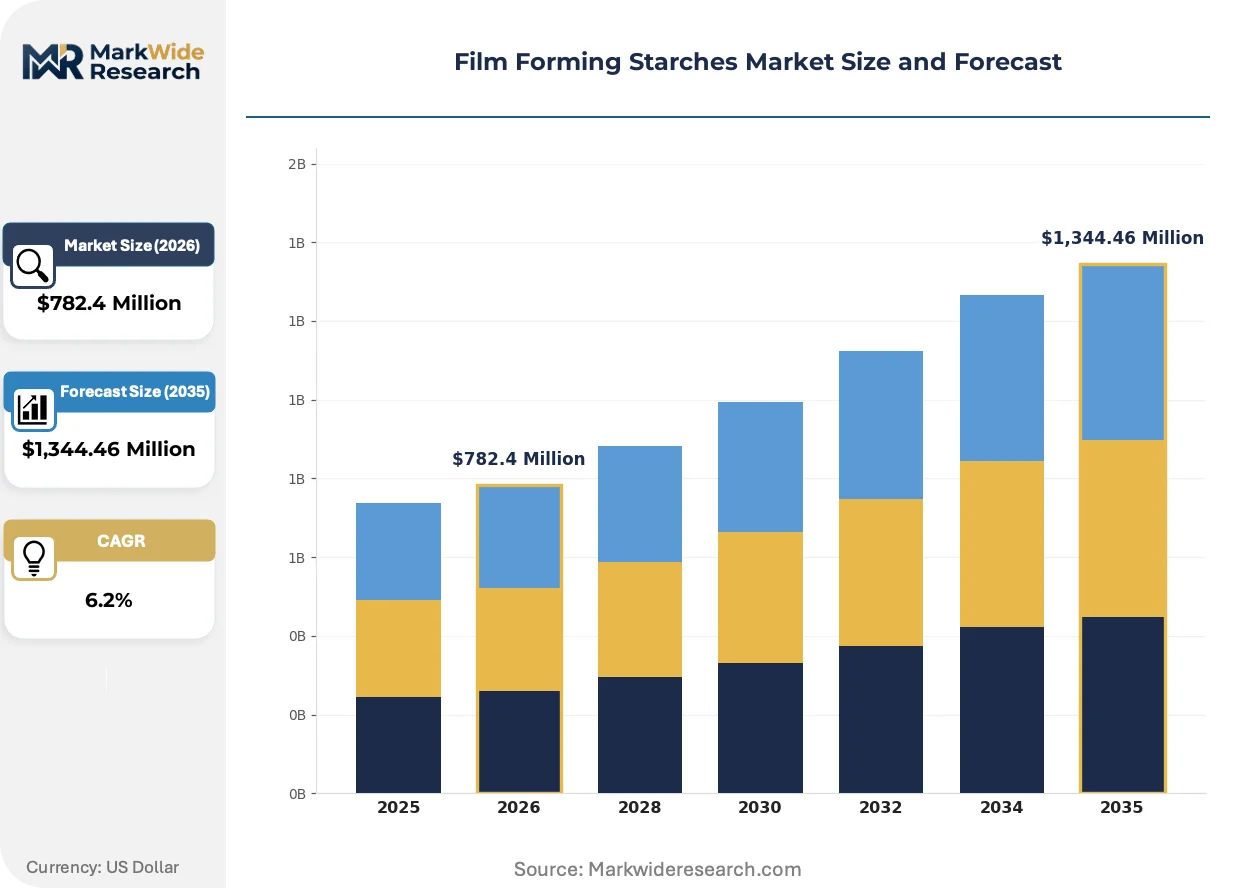
| Market Size in 2026 | $782.4 Million |
| Market Size in 2035 | $1,344.46 Million |
| CAGR (2026 – 2036) | 6.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Native Starches, Modified Starches, Pregelatinized Starches, Cross-Linked Starches Application: Food & Beverage, Pharmaceuticals, Personal Care, Paper Coatings End User: Food Manufacturers, Cosmetic Companies, Pharmaceutical Firms, Textile Industries Distribution Channel: Wholesale, Retail, Online, Direct Sales |
| Companies Covered | Cargill, Incorporated, Ingredion Incorporated, Archer Daniels Midland Company, Tate & Lyle PLC, AGRANA Beteiligungs-AG, Roquette Frères, AVEBE, Grain Processing Corporation, Emsland Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Film Forming Starches Market Shifts & Advancements
Enzymatic modification platforms are supplanting chemical derivatization as the dominant starch engineering paradigm, driven by regulatory toxicity concerns and clean-label positioning requirements across pharmaceutical and personal care end-uses.
Dual-enzyme systems combining amylase and branching enzyme activities are decomposing the traditional trade-off between cold-water solubility and film mechanical strength. Pharmaceutical coaters in Germany and Switzerland are adopting these systems at pilot scale within 18-month qualification windows. The technology is decomposing established premium tiers that previously separated pregelatinized starches from chemically modified alternatives.
EMA's revised excipient guideline on nitrosamine risk assessment is forcing starch suppliers to document absence of specific process contaminants. European contract manufacturers are now requiring batch-level nitrosamine testing certificates from film-forming starch vendors. Modified starch categories produced via acid-thinning pathways face disproportionate documentation burdens compared to enzymatically processed alternatives.
Formulator purchasing patterns are consolidating around qualified supplier lists with dedicated regulatory affairs support. Mid-sized pharmaceutical companies in India are bypassing distributors to contract directly with starch processors offering CDSCO submission assistance. This channel compression is most visible in Mumbai and Hyderabad, where domestic coaters prioritize single-source accountability over multi-supplier price arbitrage.
Film Forming Starches Market Segmentation
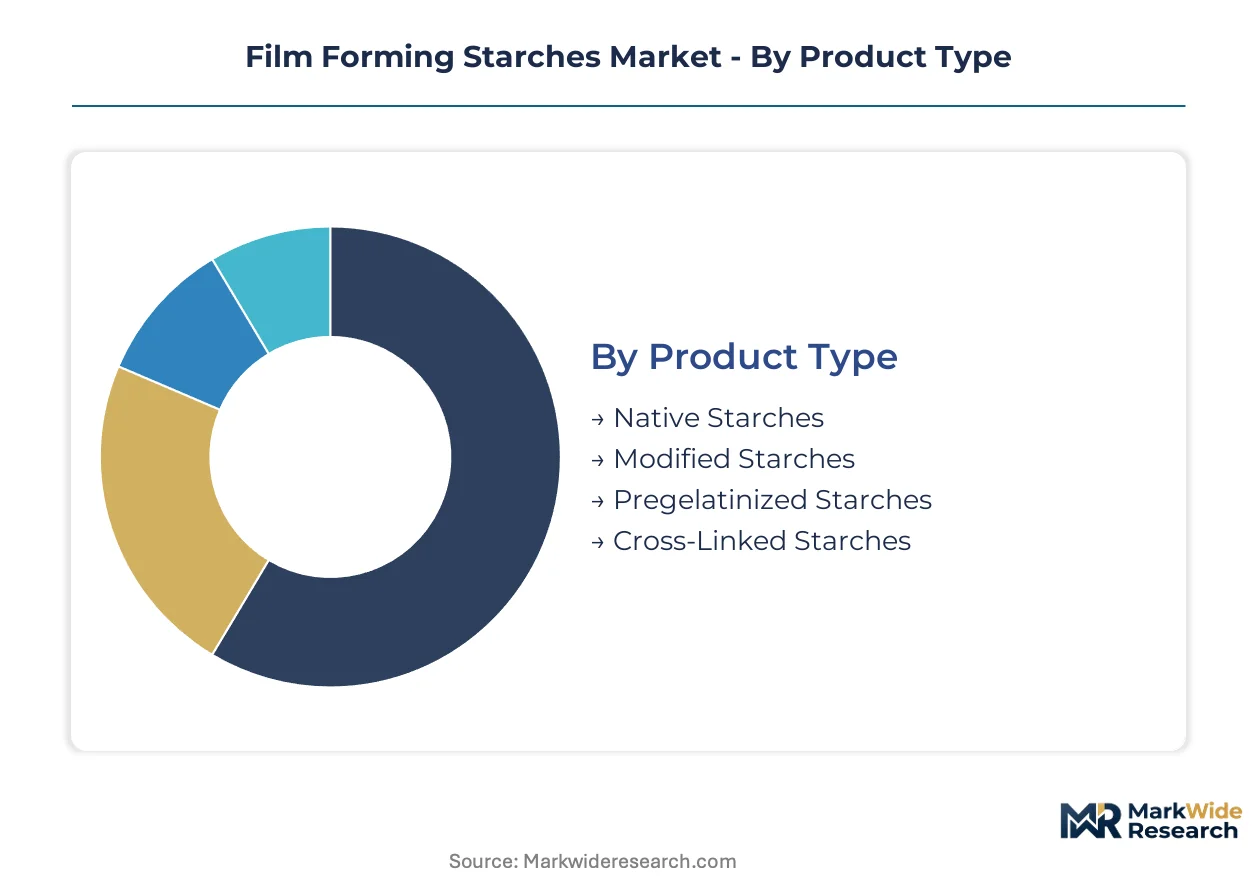
Segmentation in film forming starches reveals how functional requirements and regulatory compliance reshape procurement patterns across pharmaceutical, food, and industrial applications. Each dimension exposes distinct margin structures and qualification barriers that determine supplier viability.
Product Type:
Modified starches capture the deepest margin pools due to pharmaceutical-grade customization and enzymatic processing premiums.
- Modified Starches:Chemical or enzymatic alteration tunes amylose-amylopectin ratios for controlled-release tablet coatings. Pharmaceutical coaters in Germany and Switzerland prioritize these variants for EMA-compliant nitrosamine documentation. REACH restrictions on acid-thinning pathways are accelerating enzymatic substitution.
- Pregelatinized Starches:Cold-water solubility eliminates heat-processing steps for energy-sensitive formulators. Cosmetic manufacturers in France specify these for clean-label hair fixative applications. Dual-enzyme hydrolysis platforms are compressing traditional premium tiers against chemically modified alternatives.
- Native Starches:Unmodified corn and tapioca extracts serve cost-minimized paper coating applications.
- Cross-Linked Starches:Phosphate or adipate esterification enhances shear stability for high-speed coating lines.
The dominant share belongs to modified starches, while pregelatinized variants are gaining share fastest.
Application:
Pharmaceutical applications concentrate value where excipient qualification creates supplier stickiness and multi-year contract lock-in.
- Pharmaceuticals:Film coatings for controlled-release tablets demand amylose content precision between 50-70%. CDSCO's streamlined approval pathways in India accelerate domestic sourcing mandates. FDA and EMA purity documentation requirements compress competitive response windows for new entrants.
- Food & Beverage:Edible packaging and moisture barriers leverage food-grade starch films with oxygen-scavenging functionality. Japanese food processors pilot antimicrobial coatings for shelf-life extension.
- Personal Care:Non-GMO tapioca starches displace synthetic film formers in French and German cosmetic formulations.
- Paper Coatings:Surface sizing and printability enhancement prioritize cost minimization over performance premiums.
Pharmaceutical applications command the highest margins, though food-grade edible packaging is expanding most quickly.
End User:
Pharmaceutical firms generate the most demanding specification requirements, filtering supplier bases through GMP audits and pharmacopeial compliance.
- Pharmaceutical Firms:Tablet manufacturers in India and the United States substitute synthetic polymers with modified starches for tunable dissolution profiles. CDSCO mandates BIS-compliant excipient testing for imported and domestic materials.
- Food Manufacturers:Clean-label positioning drives rejection of synthetic barriers in favor of non-GMO starch alternatives.
- Cosmetic Companies:Ingredient transparency demands in France and Germany translate into specification changes at contract manufacturers.
- Textile Industries:Warp sizing applications require film flexibility under high-speed weaving stress.
Pharmaceutical firms anchor premium demand, while cosmetic companies are adopting starch alternatives at the steepest rate.
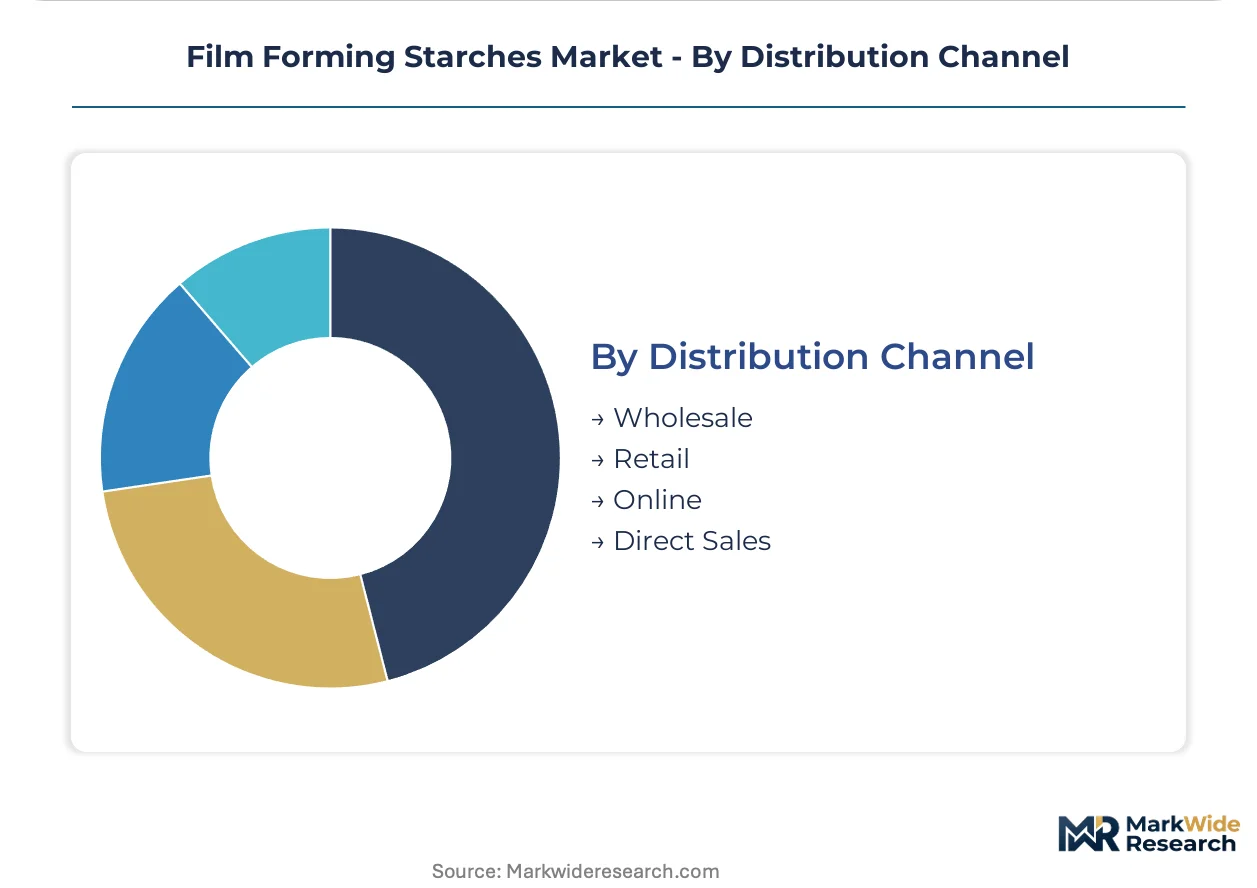
Distribution Channel:
Direct sales relationships concentrate where regulatory submission assistance and batch-level documentation justify bypassing intermediaries.
- Direct Sales:Mumbai and Hyderabad coaters contract directly with starch processors offering CDSCO submission support. Channel compression eliminates multi-supplier price arbitrage in favor of single-source accountability.
- Wholesale:Volume paper coating applications rely on distributor inventory pooling for cost-sensitive native starch procurement.
- Online:Small-batch cosmetic formulators source specialty pregelatinized grades through B2B platforms.
- Retail:Limited to artisanal food producers and research-scale pharmaceutical development.
Direct sales dominate pharmaceutical-grade transactions, while wholesale retains volume leadership in industrial coatings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
CDSCO's domestic sourcing mandates and ANVISA's import substitution programs are redirecting pharmaceutical-grade starch procurement toward localized supply chains across India and Brazil. REACH substitution timelines in Europe and FDA excipient documentation requirements in the United States compress competitive response windows for film-forming starch suppliers.
United States
Tablet manufacturers in New Jersey and North Carolina substitute synthetic polymers with modified starches for controlled-release formulations. FDA excipient guidelines govern pharmaceutical-grade starch qualification with tightening purity documentation requirements. The Midwest corn belt concentrates high-amylose germplasm supply, creating single-source vulnerability for barrier-coating applications.
Germany
Pharmaceutical coaters in Frankfurt and Leverkusen adopt dual-enzyme hydrolysis systems for EMA-compliant nitrosamine documentation. REACH restrictions on acid-thinning pathways accelerate enzymatic modification substitution. The Rhine-Ruhr industrial cluster hosts contract manufacturers rejecting synthetic film formers in favor of clean-label starch alternatives.
India
Domestic tablet manufacturers in Mumbai and Hyderabad contract directly with starch processors offering CDSCO submission assistance. BIS-compliant excipient testing mandates for imported and domestic materials create compliance thresholds favoring established multinationals. The phased procurement preferences for BIS-certified local excipients generate captive demand for indigenous potato and tapioca starch processors.
Brazil
ANVISA's import substitution incentives for excipient manufacturing create first-mover advantages for starch processors establishing Brazilian wet-milling capacity. Domestic production avoids currency volatility and import documentation delays. São Paulo's pharmaceutical manufacturing corridor concentrates demand for localized film-forming starch supply.
Switzerland
Swissmedic's stringent excipient quality standards filter supplier bases through GMP audits and pharmacopeial compliance verification. Basel's pharmaceutical innovation cluster pilots enzymatically modified starches for premium controlled-release applications. Swiss contract manufacturers require batch-level nitrosamine testing certificates from film-forming starch vendors.
Film Forming Starches Market Competitive Landscape
Player mix skews toward integrated agricultural processors with captive grain procurement networks and dedicated regulatory affairs capacity. Market structure concentrates around multinational starch specialists with pharmaceutical-grade certification and regional agricultural processors serving cost-sensitive industrial coatings. Two strategic archetypes dominate: global grain-trading conglomerates leveraging procurement scale, and European non-GMO specialists differentiating on clean-label positioning. Competitive moves center on enzymatic modification platform licensing and CDSCO/EMA regulatory submission partnerships.
Within the integrated agricultural processor tier, Cargill Incorporated and Ingredion Incorporated exemplify procurement-scale archetypes with North American corn wet-milling infrastructure. Roquette Frères occupies a position representing European non-GMO differentiation through pea starch origins. These three anchors illustrate how regulatory compliance capacity and feedstock access determine supplier viability across pharmaceutical-grade film-forming starch segments.
| Leading Market Players |
|---|
| Cargill, Incorporated |
| Ingredion Incorporated |
| Archer Daniels Midland Company |
| Tate & Lyle PLC |
| AGRANA Beteiligungs-AG |
| Roquette Frères |
| AVEBE |
| Grain Processing Corporation |
| Emsland Group |
| Others |
Supply & Pricing Matrix
Enzymatic modification's displacement of acid-thinning pathways simultaneously redraws supply geography toward European enzyme suppliers and compresses pricing economics for REACH-compliant starch grades. This substitution dynamic concentrates cost premia in enzymatically processed tiers while fragmenting procurement across dual qualification standards.
Pricing Analysis
Certification level creates the primary spread across pharmaceutical-grade tiers, with FDA and EMA documentation packages commanding substantial premia over industrial native starches. Three-tier pricing structure across premium, standard, and economy levels separates enzymatically modified excipients from chemically processed alternatives and unmodified native grades. Pricing pressure stems from REACH-mandated enzymatic conversion costs that lack offsetting recovery mechanisms in contract negotiations. Paper coating buyers exhibit highest price sensitivity, while pharmaceutical formulators prioritize qualification security over unit cost arbitrage.
Supply Chain Analysis
Inventory carrying costs inflate substantially where pharmacopeial harmonization delays force separate production campaigns for USP, EP, and IP specifications. Supply concentrates in the United States Midwest for high-amylose corn genetics, India for tapioca and potato processing, and Europe for pea starch extraction. Enzyme inputs for modification draw from Danish and Dutch specialist suppliers, creating tethered dependencies. Single-source vulnerability in high-amylose germplasm represents the dominant structural risk. Distribution runs through direct sales relationships for pharmaceutical grades and wholesale channels for industrial coatings.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Pharmaceutical excipient demand cycles track patent cliff recoveries and generic formulation ramp-ups, positioning the market for sustained expansion as controlled-release tablet volumes rebound. This cyclical recovery justifies capacity commitments ahead of qualification window compression.
For Market Incumbents: Consolidate regulatory affairs capacity through dedicated CDSCO and EMA submission teams that accelerate excipient qualification timelines. Deepen backward integration into high-amylose germplasm breeding programs to mitigate single-source concentration risk. Lock in multi-year offtake agreements with Indian tablet manufacturers before domestic sourcing mandates fully mature.
For New Entrants and Emerging Players: Anchor in Brazilian pharmaceutical manufacturing corridors where ANVISA import substitution incentives create first-mover wet-milling advantages. Target edible packaging applications in Japanese food processing as the most penetrable convergence segment. Pursue joint venture structures with established agricultural processors to bypass standalone qualification barriers.
For Investors and Strategic Acquirers: EMA's revised nitrosamine risk assessment guidelines reshape the acquisition landscape toward enzymatic modification platforms with pre-validated documentation packages. Five-to-ten year viability favors processors with dedicated regulatory affairs infrastructure over commodity native starch operators. Monitor CDSCO approval velocity for Indian domestic manufacturers as the primary inflection signal.
| Strategic Initiative | Industry Significance |
|---|---|
| Enzymatic Modification Platform Licensing | REACH compliance accelerates technology transfer to European pharmaceutical coaters in Frankfurt and Leverkusen. |
| CDSCO Regulatory Submission Partnership | Mumbai and Hyderabad coaters prioritize single-source accountability with dedicated compliance support. |
| Backward Integration into Germplasm | Midwest corn belt concentration creates captive supply security for high-amylose barrier coating applications. |
| Brazilian Wet-Milling Capacity Buildout | ANVISA incentives enable domestic production avoiding currency volatility and import documentation delays. |
| Dual-Function Edible Packaging Development | Japanese food processors pilot antimicrobial and oxygen-scavenging coatings for shelf-life extension. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of FDA excipient filings, EMA quality standard revisions, CDSCO approval databases, and REACH registration documentation. Interviews with pharmaceutical formulation scientists, regulatory affairs directors at starch processors, contract manufacturing procurement leads, and enzyme supplier technical specialists inform qualification timeline and substitution pattern assessments. Customs data on modified starch trade flows and SEC filings from integrated agricultural processors provide volume and margin validation. Bottom-up excipient demand modeling triangulates against top-down pharmaceutical production forecasts.
Segmentation dimensions modeled include product modification type, application end-use, and regional regulatory cluster across the projection horizon. CAGRs derive from elasticity-adjusted demand projections incorporating enzymatic conversion cost trajectories and pharmacopeial harmonization probability. Industry-specific inputs encompass CDSCO approval velocity indices and EMA nitrosamine documentation burden estimates.
Decision-makers should treat outputs as directional under assumptions of sustained REACH enforcement and stable pharmaceutical excipient qualification standards; material deviation in regulatory timelines or substitution incentives would warrant model refresh. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Additives and Ingredients
Emulsifiers Market
Food Additives and Ingredients
Alcohol Additives Market
Food Additives and Ingredients
Octadecanedioic Acid (ODDA) Market
Food Additives and Ingredients
Bakery Release Agents Market
Food Additives and Ingredients
Sri Lanka Starch and Starch Derivative Market
Food Additives and Ingredients
Natural Food Color Ingredients Market
Food Additives and Ingredients
Australia Food Acidulants Market
Food Additives and Ingredients
Lycopene Food Colors Market
Food Additives and Ingredients
Mexico Food Preservatives Market
Food Additives and Ingredients
Italy Food Preservatives Market
Food Additives and Ingredients
Starch-Based Edible Coatings Market
Food Additives and Ingredients
China Food Emulsifiers Market
Food Additives and Ingredients
Acidity Regulators Market
Food Additives and Ingredients
Food Grade Potassium Sorbate Market
Food Additives and Ingredients
Bread Emulsifier Market
Food Additives and Ingredients
North America Food Additives Market