
 Protein Films Market | 2026-2036
Protein Films Market Size, Share, and Industry Trends Forecast 2026-2036
Protein Films Market Outlook
Modular packaging configurations is pivoting buyer procurement patterns as food brands unbundle film layers to swap petroleum barriers for single-material protein films. Cargill leverages its agricultural supply base to secure feedstock cost advantages for soy-derived film substrates. Monosol, LLC anchors North American capacity for water-soluble protein film formats used in portion-control packaging. Tate & Lyle differentiates through R&D intensity in modified whey protein isolates with enhanced oxygen barrier performance.
Protein films constitute thin, continuous matrices formed from denatured or cross-linked plant and animal proteins, typically ranging from 20 to 150 micrometers in thickness, engineered to provide moisture and gas barrier protection for perishable goods. Their primary commercial purpose centers on replacing conventional polyethylene and polypropylene layers in food contact applications with compostable alternatives. Gelatin films sustain the largest installed base due to decades of pharmaceutical and confectionery coating heritage, while soy protein formats represent the fastest-expanding product category as oilseed processors seek higher-value outlets for meal fractions. Medical applications concentrate margin pools where pharmaceutical-grade certification commands premium pricing over standard food-grade specifications.
The EU Green Deal and REACH frameworks restrict persistent synthetic polymers in food contact materials, directly expanding addressable demand for certified biodegradable protein barriers. FDA food contact notification requirements and USDA bio-based procurement preferences shape product development roadmaps and facility qualification timelines for suppliers targeting North American accounts. ISO 17088 compostability certification and emerging state-level extended producer responsibility statutes in California and New York will determine which film formats achieve scaled commercial deployment. Stakeholders must monitor regulatory divergence between jurisdictions to avoid stranded formulation investments as compliance thresholds tighten asymmetrically.
Market Dynamics
Modular packaging configurations are forcing film converters to unbundle multilayer structures and substitute single-material protein barriers for petroleum-derived laminates, compressing equipment utilization rates while expanding addressable substrate volumes.
Growth Catalysts
- EU Green Deal packaging mandates:The framework's 2030 reduction targets for persistent plastics are compelling food processors in Germany, France, and Italy to certify compostable protein barriers for ready-meal applications.
- Oilseed meal valorization:Soy protein isolate extraction from crushing byproducts is redirecting agricultural waste streams into film-grade raw material pools at descending marginal cost curves.
- Pharmaceutical coating heritage:Decades of gelatin film production for capsule shells has cultivated process knowledge and quality systems that now transfer to high-oxygen-barrier food packaging formats.
Market Restraints
- Feedstock cost volatility:Soybean meal prices fluctuate with drought cycles in Argentina and Brazil, compressing margin stability for film extruders lacking long-term agricultural supply contracts.
- Moisture sensitivity limitations:Unmodified protein matrices lose structural integrity above 65% relative humidity, restricting deployment to dry or intermediate-moisture food categories without expensive cross-linking treatments.
- Composting infrastructure gaps:Industrial composting facility coverage remains sparse in Eastern European member states, stranding biodegradable certification value for brands distributing across heterogeneous waste management zones.
Strategic Opportunities
- Medical device packaging white space:Sterile barrier applications for surgical kits and implantable devices command pharmaceutical-grade pricing premiums over food-contact specifications.
- California extended producer responsibility:The state's 2032 plastic reduction mandates are creating first-mover advantages for protein film suppliers achieving SB 54 compliance certification ahead of enforcement deadlines.
- Active packaging convergence:Integration of antioxidant-releasing protein layers with intelligent freshness indicators is opening premium shelf-life extension contracts with protein-rich food processors.
Industry Challenges
- ISO 17088 certification timelines:Compostability validation requires 180-day industrial and home composting trials, delaying product launches and freezing working capital in inventory.
- Extrusion equipment reconfiguration:Legacy blown film lines designed for polyethylene require screw geometry modifications and die gap adjustments to process heat-sensitive protein melts without denaturation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Protein Films Market |
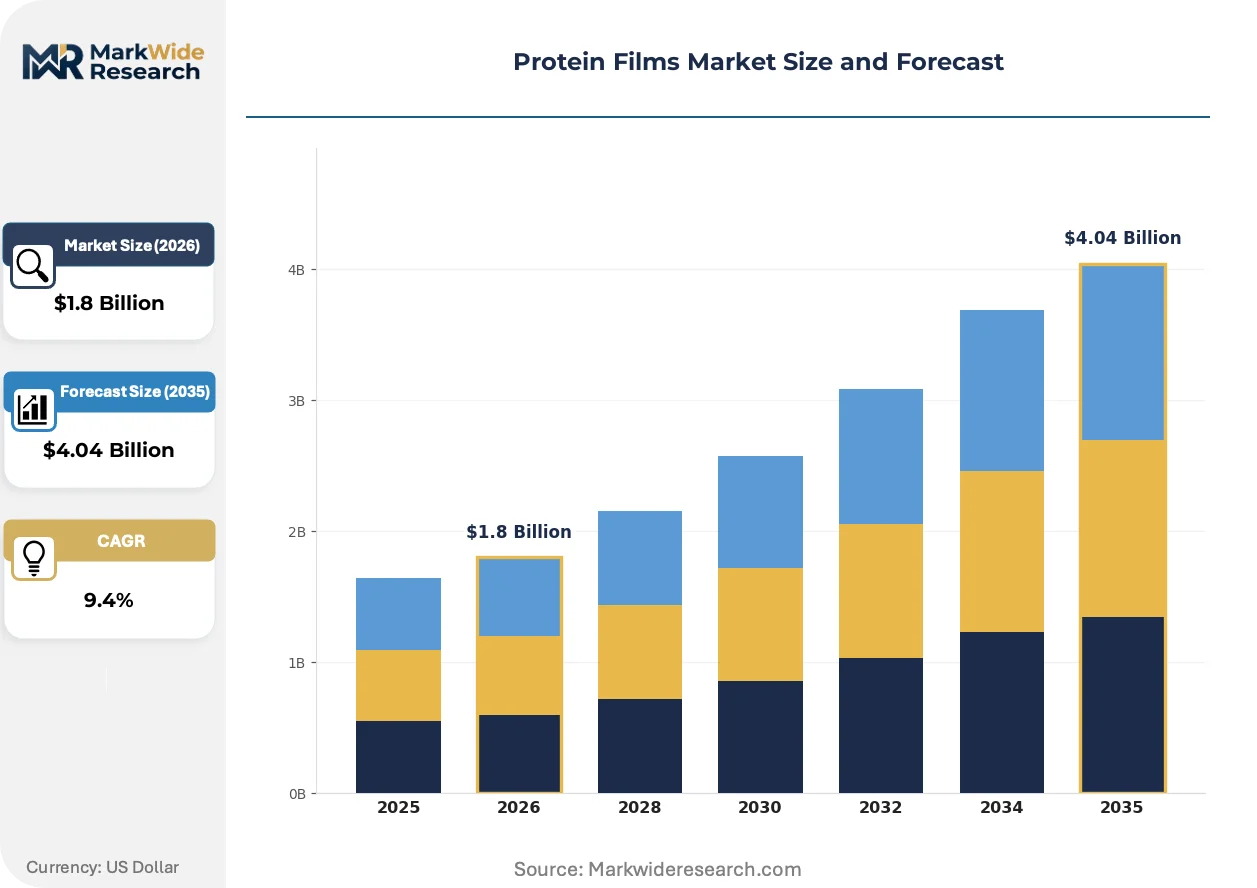
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $4.04 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Gelatin, Casein, Whey Protein, Soy Protein Application: Food Packaging, Biodegradable Materials, Medical Applications, Edible Coatings End User: Food Industry, Healthcare Sector, Consumer Goods, Research Institutions Grade: Food Grade, Pharmaceutical Grade, Industrial Grade, Technical Grade |
| Companies Covered | Cargill, Fonterra, Tate & Lyle, Davisco, Proliant Inc., Monosol, LLC, Watson Inc., AMETEK MOCON Inc., The Solae Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Protein Films Market Strategic Shifts
Electrospinning and layer-by-layer assembly techniques are compressing barrier thickness thresholds while expanding functional surface area, enabling protein films to displace synthetic nanolaminates in precision packaging applications.
Cross-linking chemistry via transglutaminase enzymatic treatment and genipin natural cross-linkers is decentralizing moisture resistance enhancement from centralized chemical additive suppliers to in-house formulation laboratories at film converters. Food brands in Scandinavia are piloting these modified whey protein formats for fermented dairy packaging. The shift is compressing reliance on synthetic ethylene vinyl alcohol copolymers for oxygen scavenging layers.
REACH Annex XVII restrictions on microplastics in consumer products are compelling EU-based film converters to eliminate synthetic polymer coatings from barrier substrates. The industrial consequence is accelerated qualification of zein and gluten protein coatings for paperboard food service applications. German quick-service restaurant chains are responding with 2025 procurement tenders specifying certified biodegradable barrier specifications.
Direct-to-brand specification engineering is displacing distributor-mediated film sales in North American fresh produce packaging. Large berry marketers in California's Central Valley now contract directly with protein film developers for custom oxygen transmission rate matching. This channel compression is most visible in organic produce verticals where compostable claims support retail premium positioning.
Protein Films Market Segmentation
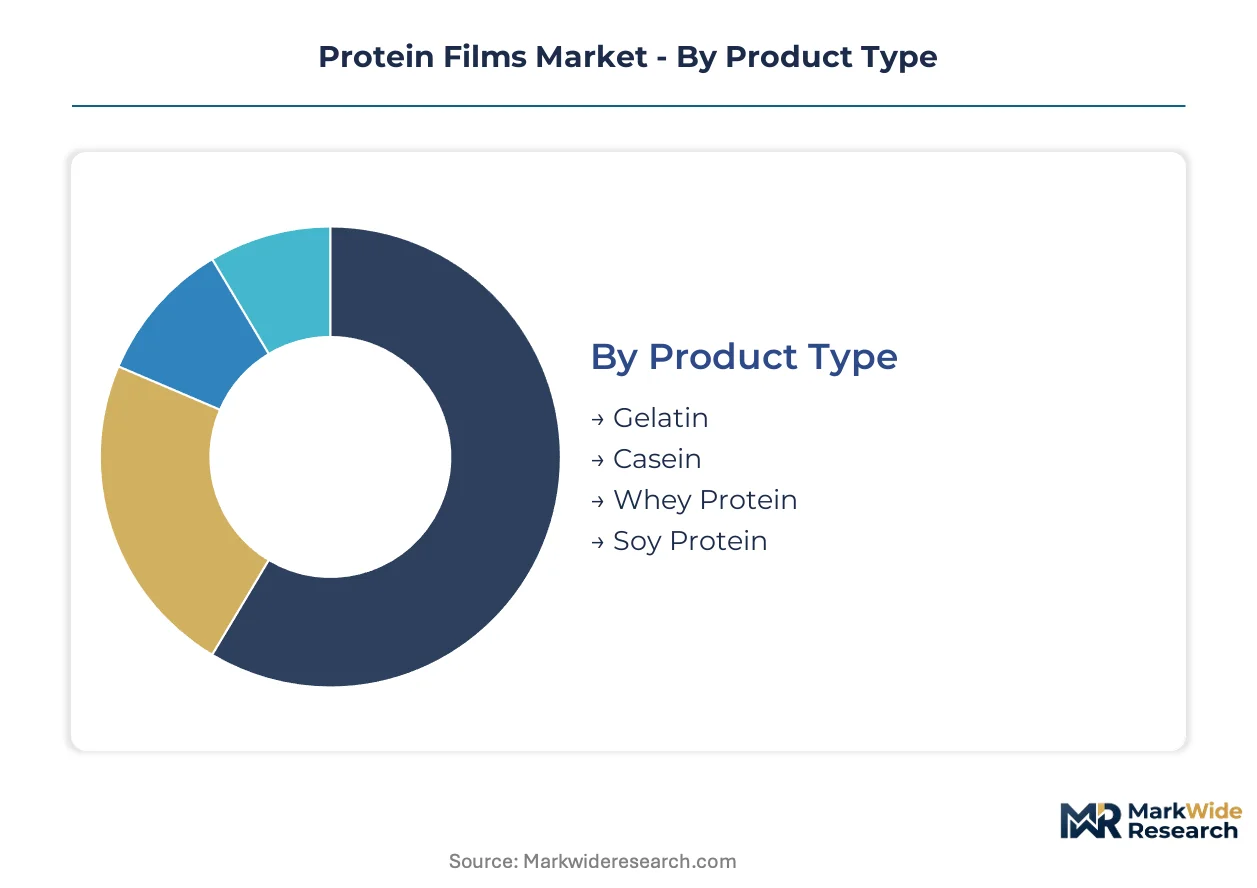
Protein film manufacturers configure production assets around distinct technical specifications and certification requirements. Segmentation reveals where margin pools concentrate and which customer procurement patterns drive capacity allocation decisions.
Product Type:
Supply concentration tilts toward gelatin and soy protein formats where agricultural feedstock access and decades of process knowledge create defensible cost positions.
- Gelatin:Collagen-derived films formed through acid or alkaline hydrolysis of animal byproducts, typically exhibiting 50-100 micrometer thickness ranges with established oxygen barrier performance. Pharmaceutical capsule coating heritage in Germany and France sustains demand concentration for high-clarity food packaging laminates where EFSA compliance documentation already exists.
- Soy Protein:Oilseed meal isolates processed through alkaline extraction and film-forming precipitation, offering the lowest feedstock cost base among plant-derived alternatives. Crushing cooperatives in Argentina and Brazil are directing surplus meal fractions toward film-grade specifications as renewable diesel expansion absorbs edible oil streams.
- Whey Protein:Dairy processing byproduct recovered through membrane filtration, valued for superior emulsion stability in edible coating applications.
- Casein:Milk protein fractions with inherent water resistance from hydrophobic amino acid clustering, limited by dairy commodity price volatility.
Gelatin absorbs the bulk of installed capacity; soy protein is expanding most quickly.
Application:
Customer procurement patterns diverge sharply between commodity food packaging tenders and certified medical barrier contracts.
- Food Packaging:Oxygen and moisture barrier layers for meat, dairy, and bakery products, typically requiring 20-80 micrometer thickness with heat-seal compatibility. Quick-service restaurant chains in Germany specified compostable protein barriers for sandwich wrap applications following EU Green Deal procurement guidelines.
- Medical Applications:Sterile barrier systems for surgical kits and implantable devices demanding pharmaceutical-grade certification with extractables testing protocols. ISO 13485 quality systems and FDA 510(k) pathway experience concentrate supplier qualification among gelatin specialists with decades of capsule manufacturing heritage.
- Biodegradable Materials:Compostable alternatives to synthetic mulch films and agricultural ground cover, constrained by soil moisture sensitivity.
- Edible Coatings:Direct food-contact surface treatments for fresh produce shelf-life extension, requiring GRAS self-determination or FDA food contact notification.
Food packaging commands the majority of production volume; medical applications capture the steepest margin premiums.
End User:
Procurement sophistication varies from technical specification teams at multinational food processors to exploratory pilots at research consortia.
- Food Industry:Ready-meal manufacturers and fresh produce packagers seeking compostable certification for retail premium positioning. Berry marketers in California's Central Valley contract directly with film developers for custom oxygen transmission rate matching rather than distributor-mediated purchasing.
- Healthcare Sector:Medical device OEMs and hospital supply chains requiring sterile barrier validation with ISO 11607 compliance documentation.
- Consumer Goods:Personal care and household product brands testing water-soluble packaging for single-use detergent applications.
- Research Institutions:Universities and national laboratories characterizing novel protein cross-linking chemistries and active packaging integrations.
The food industry drives volume absorption; healthcare sector procurement is climbing the fastest as sterilization validation protocols mature.
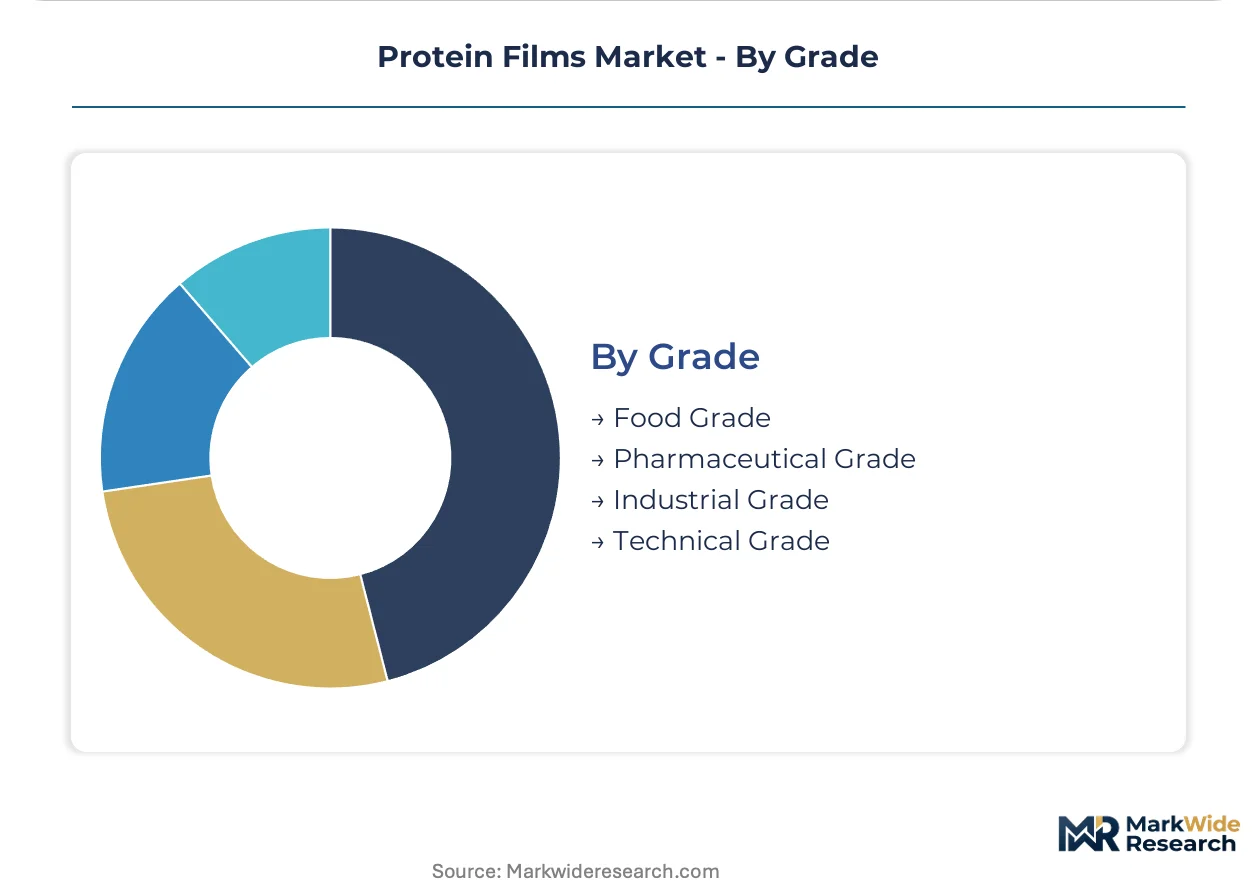
Grade:
Certification tier determines facility qualification timelines and pricing power across customer segments.
- Food Grade:Compliant with FDA 21 CFR and EU 10/2011 food contact regulations, permitting use in direct and indirect food contact applications. Film converters in Italy and Spain maintain dual-use production lines certifiable to both regulatory frameworks for pan-European distribution.
- Pharmaceutical Grade:Manufactured under IPEC-PQG GMP guidelines with elemental impurity testing per ICH Q3D, commanding 3-5x pricing multiples over food-grade equivalents. USP-NF monograph compliance for gelatin enables capsule shell suppliers to extend quality systems into high-barrier food packaging without redundant facility investment.
- Industrial Grade:Uncertified technical specifications for non-food applications including adhesive tapes and textile sizing.
- Technical Grade:Experimental or developmental batches for R&D characterization without commercial regulatory filing.
Food grade absorbs dominant production share; pharmaceutical grade is gaining share fastest as medical device packaging applications scale.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Production capacity clusters in agricultural processing regions while consumption concentrates in industrial packaging corridors. Germany and the United States host the largest installed manufacturing bases. Demand absorption tilts toward food processing clusters in Western Europe and North American fresh produce belts.
Germany
EU Green Deal packaging mandates drive processor procurement of compostable barriers for ready-meal applications. ECHA REACH compliance frameworks restrict petroleum-derived substrates in food contact materials. The Rhine-Ruhr industrial corridor hosts film converters clustering around biopolymer research centers in Düsseldorf and Cologne.
United States
California berry marketers contract directly with protein film developers for custom oxygen transmission specifications. FDA food contact notification requirements shape product development roadmaps for suppliers targeting North American accounts. The Central Valley fresh produce belt anchors direct-to-brand specification engineering for organic retail positioning.
France
Pharmaceutical-grade gelatin demand sustains capsule coating heritage extending into high-clarity food packaging. EFSA compliance documentation enables rapid qualification for food-contact laminates. Lyon and Paris basin facilities leverage decades of quality systems for premium barrier production.
Argentina
Oilseed crushing cooperatives redirect surplus soy meal fractions toward film-grade specifications. Drought cycles in the Pampas agricultural belt compress feedstock cost stability for extruders lacking long-term supply contracts. Buenos Aires province anchors soy protein isolate extraction capacity serving export markets.
China
Domestic food processors pilot modified whey protein formats for fermented dairy packaging under tightening environmental enforcement. SAMR food contact regulations and dual carbon goals accelerate substitution of synthetic laminates. Yangtze River Delta packaging clusters in Shanghai and Jiangsu province trial active packaging integrations.
Protein Films Market Competitive Environment
The competitive structure tilts toward agricultural supply chain integrators with captive feedstock access. Consolidation pressures concentrate among oilseed processors and dairy cooperatives seeking higher-value outlets for protein fractions. Two strategic archetypes dominate: agribusiness conglomerates with backward integration into crushing byproducts, and pharmaceutical-grade specialists leveraging capsule manufacturing heritage. Capacity expansion and strategic partnerships represent the dominant competitive moves as firms secure long-term raw material contracts.
Within the agribusiness integrator tier, Cargill and Fonterra occupy positions shaped by agricultural supply base control. Tate & Lyle exemplifies the R&D-intensive specialist archetype through modified protein isolate development. Monosol, LLC anchors North American positioning for water-soluble format production. These three firms represent distinct competitive vectors: feedstock security, technical differentiation, and regional format specialization.
| Leading Market Players |
|---|
| Cargill |
| Fonterra |
| Tate & Lyle |
| Davisco |
| Proliant Inc. |
| Monosol, LLC |
| Watson Inc. |
| AMETEK MOCON Inc. |
| The Solae Company |
| Others |
Value Chain & Pricing Dynamics
Quick-service restaurant procurement teams in Germany anchor pricing power for compostable protein barriers, compressing margin structures through high-volume tender specifications tied to EU Green Deal compliance deadlines.
Pricing Analysis
Cost-down pressure on food-grade formats accelerates as crushing cooperatives in Argentina redirect surplus soy meal fractions into film-grade specifications, expanding raw material availability. Pricing stratifies across pharmaceutical-grade, food-grade, and industrial-grade certification tiers, with ISO 13485 quality systems commanding three-to-five-fold premiums over standard food-contact equivalents. Margin tightening in unmodified protein matrices reflects expensive cross-linking treatments required for humidity resistance above sixty-five percent relative humidity. Small-scale film converters exhibit highest price sensitivity due to working capital constraints from one-hundred-eighty-day ISO 17088 compostability certification timelines.
Supply Chain Analysis
Freight costs from Buenos Aires province extraction facilities to European extrusion plants compress margin stability for suppliers lacking long-term agricultural supply contracts. Feedstock concentration centers on Argentina, Brazil, and Germany, with oilseed meal valorization drawing from crushing byproducts and collagen-derived gelatin sourcing from pharmaceutical capsule manufacturing heritage. Supply chain risk hinges on drought cycles in the Pampas agricultural belt disrupting soybean meal price stability. Distribution runs through direct-to-brand specification engineering channels in California's Central Valley and distributor-mediated sales for standardized food packaging formats.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The protein films sector sits in a technology-transition phase as enzymatic cross-linking chemistries displace synthetic ethylene vinyl alcohol copolymers for oxygen scavenging layers.
For Market Incumbents: To counter moisture sensitivity limitations in unmodified protein matrices, invest in transglutaminase enzymatic treatment capabilities and secure long-term soy meal supply contracts with Argentine crushing cooperatives. Backward integration into oilseed processing insulates margin stability from feedstock cost volatility. For New Entrants and Emerging Players: Film converters in Scandinavia present the most penetrable channel partner type for modified whey protein formats targeting fermented dairy packaging. Pursue active packaging convergence opportunities with antioxidant-releasing protein layers and intelligent freshness indicators. For Investors and Strategic Acquirers: The window for entry favors pharmaceutical-grade specialists with decades of capsule manufacturing heritage extending quality systems into high-barrier food packaging. Monitor California SB 54 compliance certification achievements as the inflection indicator for scaled commercial deployment timing.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Oilseed Processing | Cargill leverages its agricultural supply base to secure captive feedstock cost advantages for soy-derived film substrates. |
| Pharmaceutical-Grade Certification Investment | Tate & Lyle differentiates through IPEC-PQG GMP guidelines compliance commanding premium pricing multiples over food-grade equivalents. |
| Direct-to-Brand Specification Engineering | Monosol, LLC anchors North American positioning by contracting directly with California berry marketers for custom oxygen transmission rate matching. |
| Active Packaging R&D Partnership | Food brands in Scandinavia pilot modified whey protein formats integrating antioxidant-releasing layers with intelligent freshness indicators. |
| ISO 17088 Compostability Certification | German quick-service restaurant chains specify certified biodegradable barrier specifications in 2025 procurement tenders following EU Green Deal mandates. |
Study Parameters
Independent corroboration across film converter procurement directors, oilseed crushing cooperative managers, and pharmaceutical capsule manufacturing quality officers underwrites the qualitative findings. Secondary validation draws from EFSA compliance documentation, FDA food contact notification filings, EU Green Deal regulatory texts, and SEC filings of listed agribusiness conglomerates. Bottom-up volume estimates from extrusion line capacity and top-down demand absorption from food processor tender data were triangulated.
Comparable historical periods anchored the projection horizon to established gelatin film production trajectories and soy protein isolate adoption curves. Segmentation dimensions modeled include product type, application, end user, and grade tier across the analysis window. CAGRs were derived from feedstock cost curve projections, regulatory enforcement timeline assumptions, and composting infrastructure rollout schedules.
Caveats apply where drought cycles in Argentina and Brazil, REACH Annex XVII enforcement intensity, or industrial composting facility coverage gaps in Eastern Europe could materially shift the outlook. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Additives and Ingredients
Bread Emulsifier Market
Food Additives and Ingredients
France Food Additives Market
Food Additives and Ingredients
United Kingdom Food Additives Market
Food Additives and Ingredients
Lake Food Colors Market
Food Additives and Ingredients
Bakery Release Agents Market
Food Additives and Ingredients
Salatrim Market
Food Additives and Ingredients
Egg Stabilizer Market
Food Additives and Ingredients
India Food Enzymes Market
Food Additives and Ingredients
Mexico Anti Caking Market
Food Additives and Ingredients
Dairy Starter Culture Market
Food Additives and Ingredients
Egg Emulsifier Market
Food Additives and Ingredients
Neohesperidin Market
Food Additives and Ingredients
Octadecanedioic Acid (ODDA) Market
Food Additives and Ingredients
Europe Feed Anti-Caking Agents Market
Food Additives and Ingredients
Lime Oil Market
Food Additives and Ingredients
Canada Food Emulsifiers Market