
 Mexico Food Preservatives Market | 2026-2036
Mexico Food Preservatives Market Size, Share, and Industry Trends Forecast 2026-2036
Mexico Food Preservatives Market Foresight
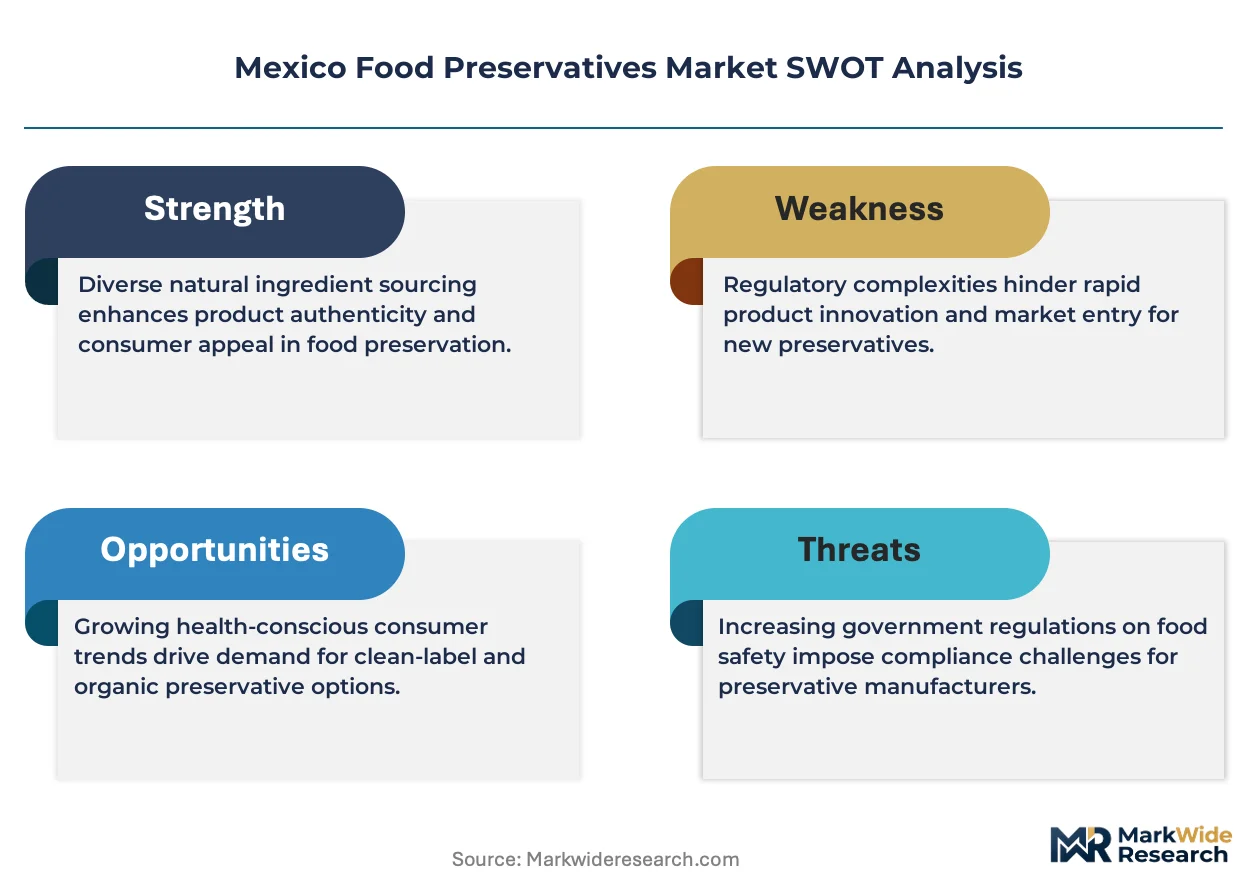
COFEPRIS updated food additive registration protocols is repositioning the cost-of-entry calculus for foreign suppliers seeking Mexican market access. Kerry Group plc leverages its regional application labs to sustain formulation partnerships with domestic processors. Cargill anchors its position through backward integration into citric acid supply chains serving central Mexico. BASF SE competes on synthetic preservative purity grades aligned with export-oriented customer specifications.
Food preservatives encompass chemical and natural substances added to inhibit microbial spoilage, enzymatic degradation, and oxidative rancidity in processed foods, typically dosed at parts-per-million to percentage levels depending on matrix acidity and water activity. Sorbates dominate volume in high-moisture applications such as beverages and dairy, while nitrites retain irreplaceable functionality in cured meat color stabilization despite health scrutiny shifting procurement toward phosphate blends. Benzoates face contraction in acidified beverages as label-conscious food manufacturers explore cultured dextrose alternatives, concentrating margin pools in clean-label phosphates for refrigerated dough systems.
COFEPRIS maintains primary jurisdiction over additive safety assessments and maximum permitted levels, while NOM-051-SCFI/SSA1-2010 front-of-pack labeling rules reshape preservative demand by penalizing synthetic additive declarations with warning octagons. SEDENA and SEMARNAT jointly oversee biocidal substance environmental discharge permits affecting production facility siting. Stakeholders must monitor pending NOM revisions on nitrite reduction timelines and decide between reformulation R&D commitments or portfolio exits before compliance deadlines harden.
Market Dynamics
COFEPRIS regulatory tightening on additive approvals is compressing supplier timelines while simultaneously forcing domestic processors into accelerated reformulation cycles. This structural pressure is redistributing margin pools toward technical service providers capable of navigating compliance bottlenecks.
Growth Catalysts
- Retail network expansion:Modern grocery formats penetrating secondary Mexican cities are extending cold-chain reach, creating pull for shelf-life extension chemistry in dairy and prepared meals.
- NOM-051-SCFI/SSA1-2010 enforcement:Front-of-pack warning octagons for synthetic additives are accelerating clean-label R&D commitments among Jalisco-based food manufacturers.
- Export-oriented processing:USMCA-aligned meat processors are upgrading preservative specifications to meet FDA import tolerances, upgrading demand for high-purity phosphate blends.
Market Restraints
- Citric acid feedstock volatility:Fermentation substrate cost swings constrain margin stability for acidulant-dependent formulations across central Mexico production corridors.
- Single-source import dependence:Sorbic acid supply concentrates through Veracruz port infrastructure, exposing formulators to customs clearance bottlenecks and inventory carrying cost spikes.
- Nitrite functionality ceiling:Cured meat color stabilization retains irreplaceable chemistry despite health-driven reduction mandates, trapping processors between compliance and product integrity.
Strategic Opportunities
- Yucatán Peninsula underpenetration:Merida-centered food manufacturing growth lags national average, offering first-mover positioning for preservative distributors establishing regional blending facilities.
- Cultured dextrose substitution wave:Fermentation-derived clean-label inhibitors are capturing share in acidified beverages as benzoate alternatives, opening formulation partnership revenue streams.
- SEMARNAT discharge permit optimization:Environmental compliance infrastructure investments unlock biocidal substance production licensing in Queretaro industrial parks.
Industry Challenges
- Reformulation technical talent scarcity:Food chemistry specialists capable of bridging clean-label efficacy with COFEPRIS documentation requirements command premium compensation in Guadalajara corridor.
- Legacy equipment retrofitting costs:Aseptic processing lines require capital deployment to handle pH-sensitive natural preservative systems without synthetic backstops.
- Dual certification timeline compression:Simultaneous COFEPRIS registration and US FDA GRAS affirmation processes strain regulatory affairs bandwidth at mid-scale processors.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Mexico Food Preservatives Market |
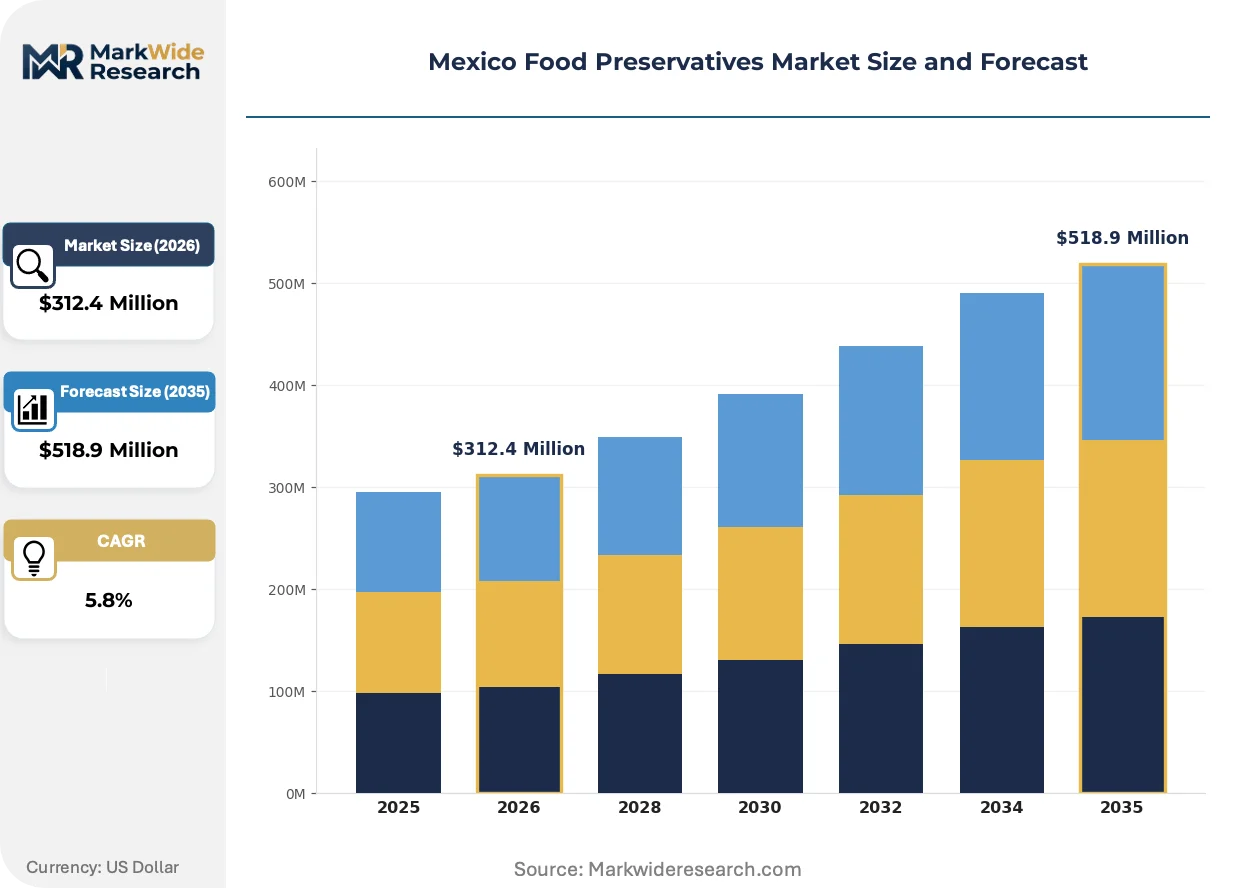
| Market Size in 2026 | $312.4 Million |
| Market Size in 2035 | $518.9 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Sorbates, Benzoates, Nitrites, Phosphates Application: Meat Products, Beverages, Dairy Products, Baked Goods End User: Food Manufacturers, Retailers, Restaurants, Caterers Form: Liquid, Powder, Granular, Spray |
| Companies Covered | Kerry Group plc, DuPont de Nemours, Inc., BASF SE, Cargill, Jungbunzlauer AG, Archer Daniels Midland Company, Koninklijke DSM N.V., Kemin Industries, Brenntag AG, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Mexico Food Preservatives Market Shifts & Advancements
Clean-label chemistry is displacing legacy synthetic systems across Mexican food manufacturing, with regulatory pressure and export compliance requirements converging to reshape technical specifications. Three developments are commanding strategic attention.
Encapsulated essential oil formulations are absorbing antimicrobial functionality previously delivered by benzoates and sorbates in high-acid applications. Beverage processors in Jalisco are piloting rosemary and oregano extract microemulsions at commercial scale. The technology is absorbing margin compression from longer ingredient lists while enabling warning-octagon avoidance on retail packaging.
NOM-051-SCFI/SSA1-2010 front-of-pack labeling rules are penalizing synthetic additive declarations with mandatory warning octagons. Reformulation investments are concentrating in refrigerated dough and processed meat categories where visual shelf presence drives purchase decisions. Export-oriented processors are dual-certifying formulations to preempt USMCA technical barrier disputes.
Buyer concentration among national retail chains is compressing supplier negotiation cycles from annual to quarterly frameworks. Category managers at Soriana and Chedraui are unbundling technical service from ingredient supply, forcing preservative vendors to price commodity chemistry separately from formulation support. This pattern is most visible in Guadalajara's food manufacturing corridor where procurement centralization has outpaced national averages.
Mexico Food Preservatives Market Segmentation
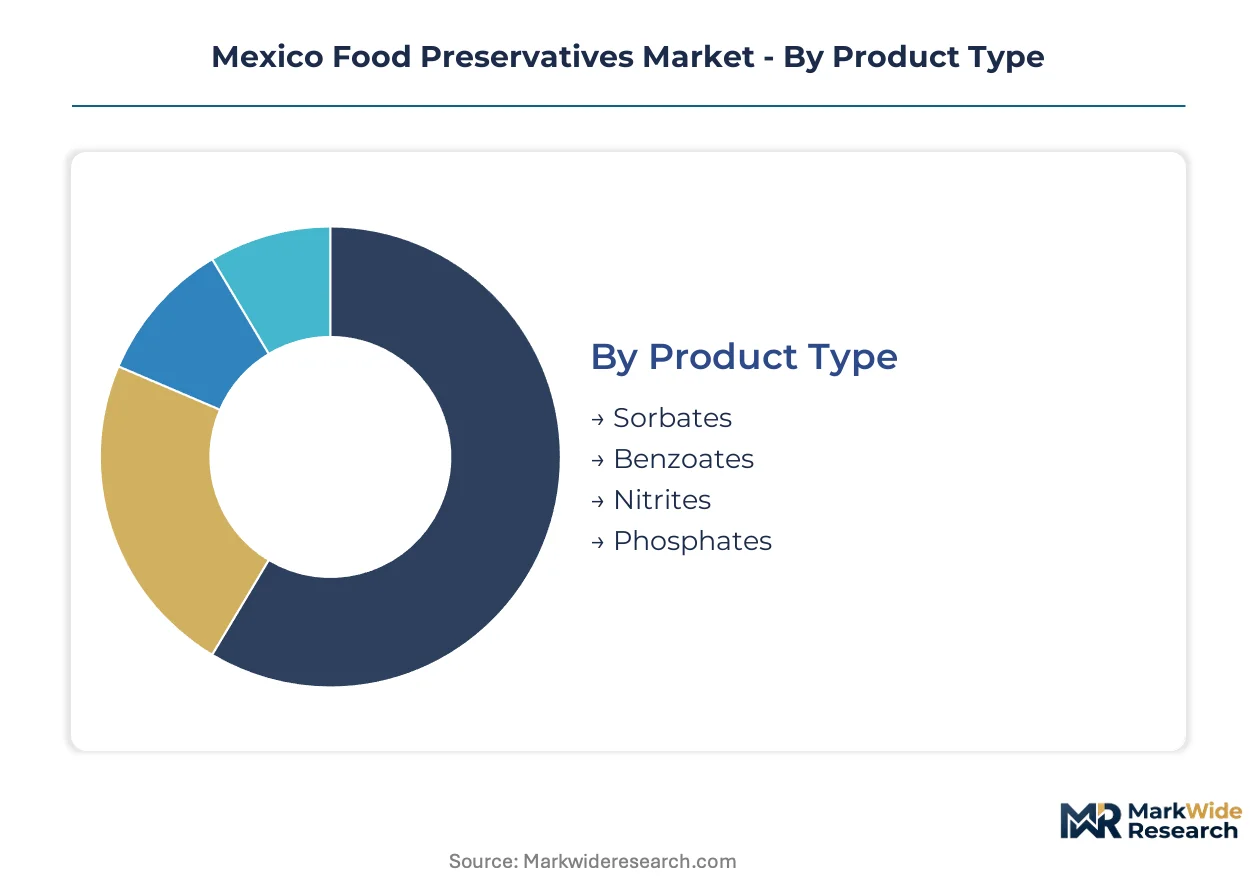
Preservative selection in Mexico hinges on matrix compatibility, regulatory clearance velocity, and reformulation cost amortization across product portfolios. Segmentation reveals where capital deployment concentrates and which chemistry platforms capture margin expansion under COFEPRIS tightening.
Product Type:
Sorbates and phosphates demand the heaviest upfront investment in fermentation capacity and backward integration into phosphate rock sourcing, respectively.
- Sorbates:Potassium sorbate dominates high-moisture matrices through yeast and mold inhibition at pH ranges below 6.5. Jalisco beverage processors are expanding procurement as acidified ready-to-drink categories penetrate secondary cities. Reformulation from benzoate systems is accelerating sorbate demand, though Veracruz port congestion strains inventory cycles.
- Phosphates:Sodium and potassium phosphate blends deliver moisture retention and antimicrobial synergy in processed meats. USMCA-aligned export processors in Guanajuato are upgrading to high-purity grades meeting FDA import tolerances, concentrating margin pools in dual-certified supply chains.
- Nitrites:Irreplaceable for cured meat color stabilization despite health-driven reduction mandates; processors face trapped demand between COFEPRIS compliance timelines and product integrity requirements.
- Benzoates:Sodium benzoate faces contraction in acidified beverages as NOM-051 warning octagons penalize synthetic declarations; surviving demand concentrates in low-visibility industrial applications.
Most installed capacity flows through phosphates. Expansion is steepest in sorbates.
Application:
Meat products and beverages absorb the bulk of technical service investment due to reformulation complexity and shelf-life extension economics.
- Meat Products:Cured, emulsified, and fresh meat categories drive phosphate and nitrite consumption. COFEPRIS nitrite reduction timelines are forcing accelerated R&D into cultured dextrose and plant-extract alternatives among Jalisco processors.
- Beverages:High-acid soft drinks and functional waters are pivoting from benzoates to sorbates and encapsulated essential oil systems to avoid front-of-pack warning labels.
- Dairy Products:Yogurt and flavored milk applications favor sorbate-potassium blends; cold-chain expansion into secondary cities is extending demand geography.
- Baked Goods:Propionate and sorbate combinations dominate mold inhibition in extended-shelf-life bread; margin compression from commodity flour costs limits preservative premium capture.
Reformulation spending concentrates in meat products. Clean-label substitution is advancing most quickly in beverages.
End User:
Food manufacturers shoulder the highest compliance and technical talent costs, while retailers are unbundling procurement from formulation support.
- Food Manufacturers:National processors in Guadalajara corridor centralize preservative procurement across multiple brands; quarterly negotiation cycles with suppliers are replacing annual frameworks.
- Retailers:Soriana and Chedraui category managers are demanding ingredient transparency documentation to preempt NOM-051 enforcement actions on private-label products.
- Restaurants:Chain operators prioritize shelf-stable sauce and marinade concentrates; volume scale remains fragmented relative to manufacturing sector.
- Caterers:Institutional foodservice relies on prepared meal suppliers for preservative-treated components; direct procurement remains minimal.
Specification authority rests with food manufacturers. Retailer influence is expanding fastest through private-label quality mandates.
Form:
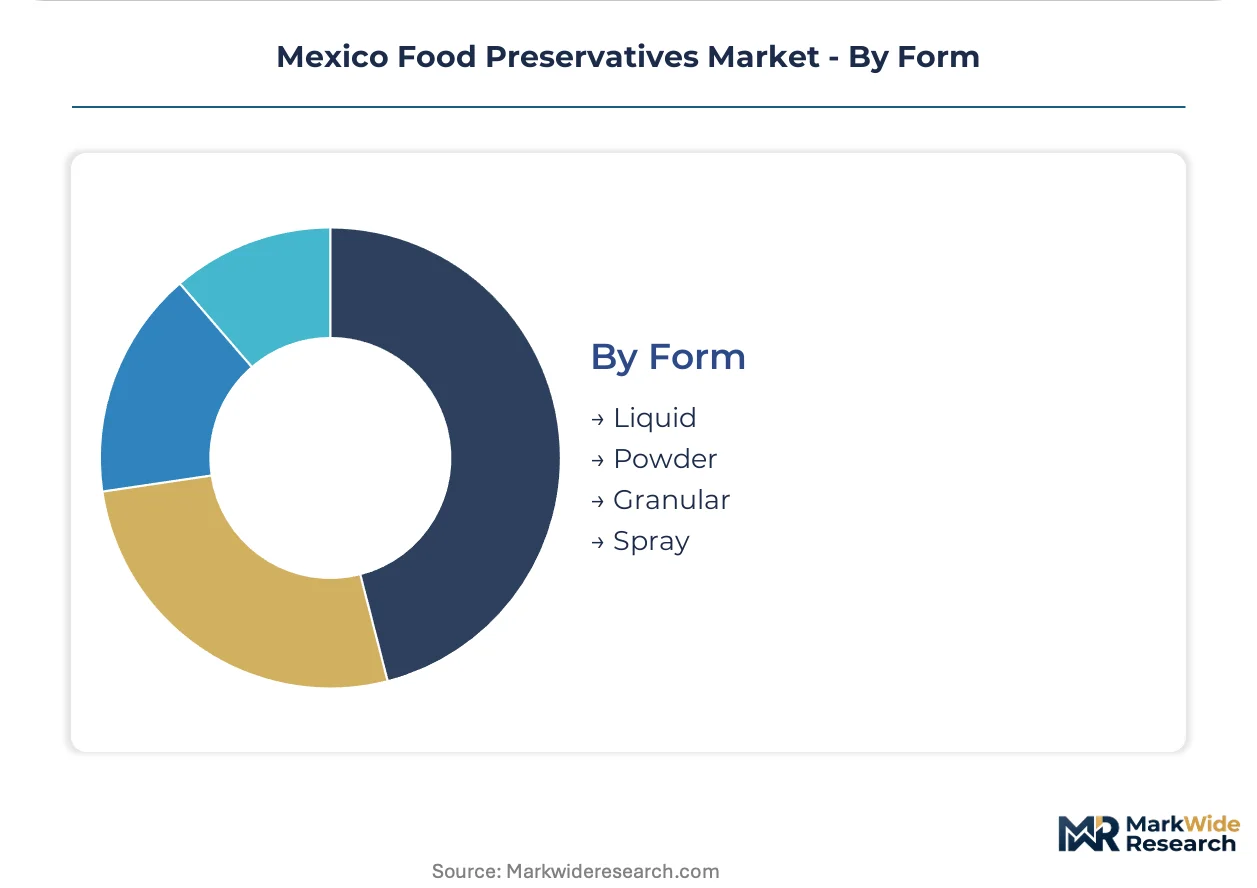
Liquid and powder formats require differentiated production infrastructure, with liquid systems demanding aseptic handling investments.
- Liquid:Preferred for high-volume beverage dosing and automated meat brine injection; Queretaro blending facilities are expanding tank farm capacity.
- Powder:Dominates bakery premixes and dry seasoning applications; handling efficiency favors central Mexico distribution hubs.
- Granular:Selected for controlled dissolution in meat curing operations; niche relative to powder and liquid alternatives.
- Spray:Surface application systems for post-bake bread treatment; equipment retrofit costs constrain adoption outside large bakeries.
Production volume flows predominantly through liquid systems. Granular capacity is gaining share fastest in specialty cured meat operations.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Food chemistry specialists cluster in the Guadalajara corridor, anchoring formulation expertise that radiates across central Mexico's manufacturing belt. This talent concentration shapes regional procurement patterns and compliance navigation capabilities.
Jalisco
Beverage processors in the Guadalajara corridor are expanding sorbate procurement for acidified ready-to-drink categories penetrating secondary cities. COFEPRIS maintains regional enforcement offices here, accelerating additive registration timelines for local formulators. The metropolitan area hosts Kerry Group plc's application labs, sustaining technical service partnerships with domestic meat and dairy processors.
Nuevo León
Monterrey-centered meat processors drive phosphate blend demand for USMCA-aligned export specifications to United States markets. SEDENA oversight of biocidal discharge permits affects production facility siting in the metropolitan industrial parks. Cargill's backward integration into citric acid supply chains serves this northern corridor through captive distribution infrastructure.
Bajío Region
Guanajuato's processed meat upgrading to high-purity phosphate grades concentrates margin pools in dual-certified supply chains. SEMARNAT environmental discharge regulations constrain biocidal substance licensing in Queretaro industrial parks. The region's aseptic processing line investments accommodate pH-sensitive natural preservative systems without synthetic backstops.
Mexico City Metro
National retail chain procurement centralization at Soriana and Chedraui headquarters compresses supplier negotiation cycles from annual to quarterly frameworks. NOM-051-SCFI/SSA1-2010 front-of-pack labeling enforcement originates from federal regulatory offices here. Category managers unbundle technical service from ingredient supply, forcing preservative vendors to price commodity chemistry separately.
Yucatán Peninsula
Merida-centered food manufacturing growth lags national averages, offering first-mover positioning for preservative distributors establishing regional blending facilities. The region's underpenetration relative to Jalisco and Nuevo León creates inventory carrying cost advantages for early entrants. Cultured dextrose substitution partnerships are capturing share in local acidified beverage production.
Mexico Food Preservatives Market Competitive Landscape
The competitive structure tilts toward multinational chemical conglomerates with fermentation capacity and regional application infrastructure. Tier-one positions concentrate among European and North American suppliers possessing COFEPRIS registration expertise and backward integration into acidulant feedstocks. Three archetypes dominate: integrated fermentation specialists, synthetic purity-grade suppliers, and technical service-forward ingredient platforms. Capacity expansion and portfolio diversification toward clean-label alternatives represent the dominant competitive vectors as reformulation demand accelerates.
Among Ireland and Switzerland-based specialists, Kerry Group plc and Jungbunzlauer AG exemplify the technical service-forward archetype, occupying positions defined by regional application lab networks and fermentation-derived clean-label capabilities. Germany's BASF SE anchors the synthetic purity-grade segment, while Cargill represents the integrated agribusiness model with upstream control over citric acid supply chains. These three entities collectively illustrate how competitive positioning stratifies across service intensity, feedstock integration, and regulatory navigation bandwidth.
| Leading Market Players |
|---|
| Kerry Group plc |
| DuPont de Nemours, Inc. |
| BASF SE |
| Cargill |
| Jungbunzlauer AG |
| Archer Daniels Midland Company |
| Koninklijke DSM N.V. |
| Kemin Industries |
| Brenntag AG |
| Others |
Supply & Pricing Matrix
Citric acid futures volatility at the Veracruz port entry point cascades through Mexican preservative markets into three distinct pricing tiers. Fermentation substrate cost swings compress margins for acidulant-dependent formulators while rewarding suppliers with captive phosphate rock sourcing.
Pricing Analysis
Commodity chemistry and technical service unbundling separates premium formulation partnerships from standard ingredient supply. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade differentiation and volume scale. Pricing pressure stems from retailer quarterly negotiation compression at Soriana and Chedraui headquarters. Mid-scale processors exhibit highest price sensitivity due to dual certification bandwidth constraints, while export-oriented meat processors absorb premium grades for FDA-aligned specifications.
Supply Chain Analysis
Reverse-logistics flows for expired preservative batches and reformulation scrap are minimal given chemical stability and low per-unit value. Sorbic acid supply concentrates through China and Germany fermentation capacity, with Veracruz port infrastructure creating single-source vulnerability. Raw material dependencies rest on molasses feedstock, phosphate rock, and petroleum-derived synthetic precursors. Distribution runs through Queretaro blending facilities and Guadalajara corridor distribution hubs serving central Mexico manufacturing.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Mexico's food preservatives market functions as a geographic-arbitrage play between COFEPRIS regulatory tightening and USMCA export compliance requirements, where dual-certification capability commands premium positioning.
For Market Incumbents: Hedge nitrite reduction mandates by accelerating cultured dextrose R&D partnerships before compliance deadlines harden. Secure backward integration into citric acid supply chains to defend margin position against fermentation substrate volatility. Kerry Group plc's regional application lab model demonstrates how technical service density retains procurement relationships amid retailer unbundling pressures. For New Entrants and Emerging Players: E-commerce platform routes into Merida-centered Yucatán Peninsula manufacturing offer first-mover positioning with inventory carrying cost advantages. Target underpenetrated regional blending facility demand where Jalisco and Nuevo León concentration has outpaced local supply. Partner with Jalisco beverage processors on encapsulated essential oil pilot programs to bypass NOM-051 warning octagon requirements. For Investors and Strategic Acquirers: Consolidation pressure builds where technical talent scarcity intersects with reformulation R&D commitment requirements. Five-to-ten year viability favors acquisition targets possessing COFEPRIS registration expertise and clean-label fermentation capabilities. Watch for SEMARNAT discharge permit approvals in Queretaro industrial parks as inflection indicator for biocidal substance production licensing velocity.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Phosphate Rock | Captive supply secures margin stability for USMCA-aligned meat processors in Guanajuato. |
| Regional Application Lab Expansion | Kerry Group plc's Guadalajara facility demonstrates technical service density retaining procurement relationships. |
| Cultured Dextrose Partnership Programs | Fermentation-derived clean-label inhibitors capture share from benzoate contraction in acidified beverages. |
| Dual-Certification Investment | Simultaneous COFEPRIS and FDA GRAS processes unlock export-oriented processor premium capture. |
| Yucatán Blending Facility Establishment | Merida-centered underpenetration offers inventory carrying cost advantages for early entrants. |
Research Methodology
Coverage spans Jalisco, Nuevo León, Bajío Region, Mexico City Metro, and Yucatán Peninsula, with primary inputs from each. Research combines interviews with COFEPRIS regulatory affairs specialists, procurement directors at national food manufacturers, technical service managers at preservative suppliers, and category buyers at Soriana and Chedraui. Secondary validation draws from COFEPRIS additive registration databases, NOM-051 enforcement bulletins, SEC filings of listed chemical suppliers, and Veracruz port customs records. Bottom-up demand modeling and top-down supply capacity assessments triangulate market sizing.
Granularity-level modeling operates at product type, application, end user, and form dimensions across the projection horizon. Sorbate, phosphate, nitrite, and benzoate chemistry platforms were modeled separately with matrix-specific dosage assumptions. Meat products, beverages, dairy, and baked goods applications incorporate reformulation cost amortization curves. CAGRs derive from segment-level volume buildups adjusted for COFEPRIS regulatory timeline uncertainty. Forecast inputs include cold-chain expansion trajectories into secondary cities and NOM-051 warning octagon avoidance R&D spending patterns.
Regulatory timeline delays, fermentation substrate price spikes, and retailer procurement centralization acceleration are the dominant revision risks. Forecasts reflect assumptions about COFEPRIS enforcement consistency and USMCA technical barrier stability. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Additives and Ingredients
Phytogenic Feed Additives Market
Food Additives and Ingredients
Food Grade Carrageenan Market
Food Additives and Ingredients
Asia- Pacific Food Micronized Salt Market
Food Additives and Ingredients
Europe Food Acidulants Market
Food Additives and Ingredients
Brazil Food Enzymes Market
Food Additives and Ingredients
Curcumin Food Color Market
Food Additives and Ingredients
Food and Beverage Additives Market
Food Additives and Ingredients
UK Food Enzymes Market
Food Additives and Ingredients
Cook-Up Starch Market
Food Additives and Ingredients
Canada Food Preservatives Market
Food Additives and Ingredients
Non-PHO Emulsifiers Market
Food Additives and Ingredients
Africa Feed Additives Market
Food Additives and Ingredients
Sunset Yellow FCF Market
Food Additives and Ingredients
Germany Food Additives Market
Food Additives and Ingredients
Acidity Regulators Market
Food Additives and Ingredients
Instant Fat Powder Market