
 Alcohol Additives Market | 2026-2036
Alcohol Additives Market Size, Share, and Industry Trends Forecast 2026-2036
Alcohol Additives Market Analysis
Direct-to-manufacturer supply contracts is reshaping how alcohol additive producers reach end-users, bypassing traditional chemical distributors in North America and Western Europe. Chr. Hansen Holding A/S leverages its fermentation-derived specialty ingredient portfolio to anchor relationships with premium distillers. Cargill competes through backward integration into corn and wheat feedstocks for natural flavor precursors. Kerry Group differentiates by offering integrated taste and nutrition systems that bundle multiple additive functions for beverage clients.
Alcohol additives comprise functional substances formulated to modify sensory properties, extend shelf stability, or standardize appearance in ethanol-containing products, typically dosed at parts-per-million to low-percentage concentrations depending on regulatory limits and desired effect. These formulations serve primarily to ensure batch consistency, mask off-notes from distillation, and meet consumer expectations for color and sweetness across commercial beverage production. Flavoring agents command the largest share of product type revenue, driven by proliferation of flavored vodkas, whiskeys, and botanical gins, while preservatives represent the fastest-expanding category as producers seek clean-label alternatives to synthetic stabilizers. Colorants concentrate margin pools in caramel and spirit-based hues where certification requirements limit supplier pools.
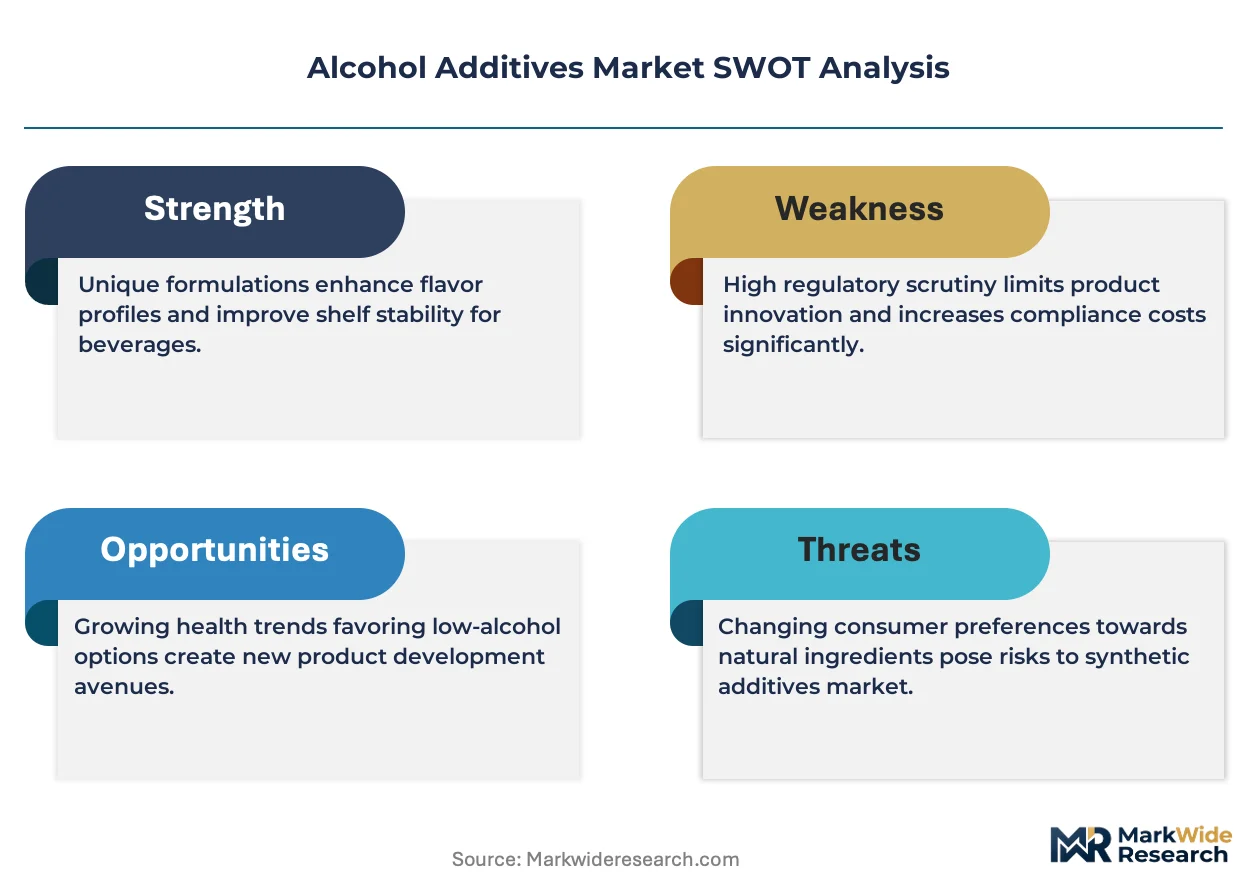
FDA GRAS determinations and TTB formulation approvals govern market access for alcohol additives in the United States, with the European Food Safety Authority (EFSA) and EMA frameworks applying parallel scrutiny to products entering EU beverage and pharmaceutical channels. REACH compliance for synthetic colorants and flavoring substances restricts supplier eligibility and extends registration costs for non-European manufacturers. Stakeholders must monitor evolving clean-label definitions across FDA, EFSA, and Health Canada guidance documents, as these determinations will dictate which additive chemistries retain commercial viability without reformulation investment.
Market Dynamics
Clean-label mandates from FDA, EFSA, and Health Canada are compressing formulation timelines as distillers reformulate synthetic preservatives and colorants ahead of guidance finalization.
Growth Catalysts
- Ready-to-drink cocktail proliferation:Premium beverage manufacturers in the United States are expanding additive procurement for shelf-stable, pre-mixed spirits requiring specialized stabilizers and flavor masking agents.
- REACH compliance barriers:Registration costs for synthetic colorants and flavoring substances restrict supplier eligibility, concentrating margin pools among pre-registered European manufacturers.
- Fermentation-derived specialty ingredients:Bioprocess advances enable natural preservative alternatives that satisfy clean-label definitions without sacrificing shelf stability.
Market Restraints
- Feedstock volatility:Corn and wheat price swings directly impact natural flavor precursor economics for producers lacking backward integration into agricultural supply.
- Supplier concentration in Germany:Distilleries and brewing conglomerates drive bulk orders that lock capacity at specialized preservative and colorant manufacturers, limiting spot availability.
- GRAS notification bottlenecks:FDA's updated Generally Recognized as Safe requirements for flavoring substances extend compliance timelines by 12-18 months for new market entrants.
Strategic Opportunities
- Direct-to-manufacturer contracting:North American additive producers are bypassing traditional chemical distributors to capture margin and secure volume commitments from craft distillers.
- Botanical gin flavor systems:Complex botanical formulations requiring integrated taste and color stabilization create demand for bundled additive functions.
- EMA pharmaceutical-grade crossover:European distillers leveraging EMA-compliant manufacturing infrastructure can access premium-priced pharmaceutical ethanol channels.
Industry Challenges
- TTB formulation approval delays:Alcohol and Tobacco Tax and Trade Bureau review cycles for novel additives stretch 24-36 months, freezing product launch schedules.
- Clean-label definition fragmentation:Divergent FDA, EFSA, and Health Canada guidance documents force parallel reformulation tracks, multiplying R&D expenditure.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Alcohol Additives Market |
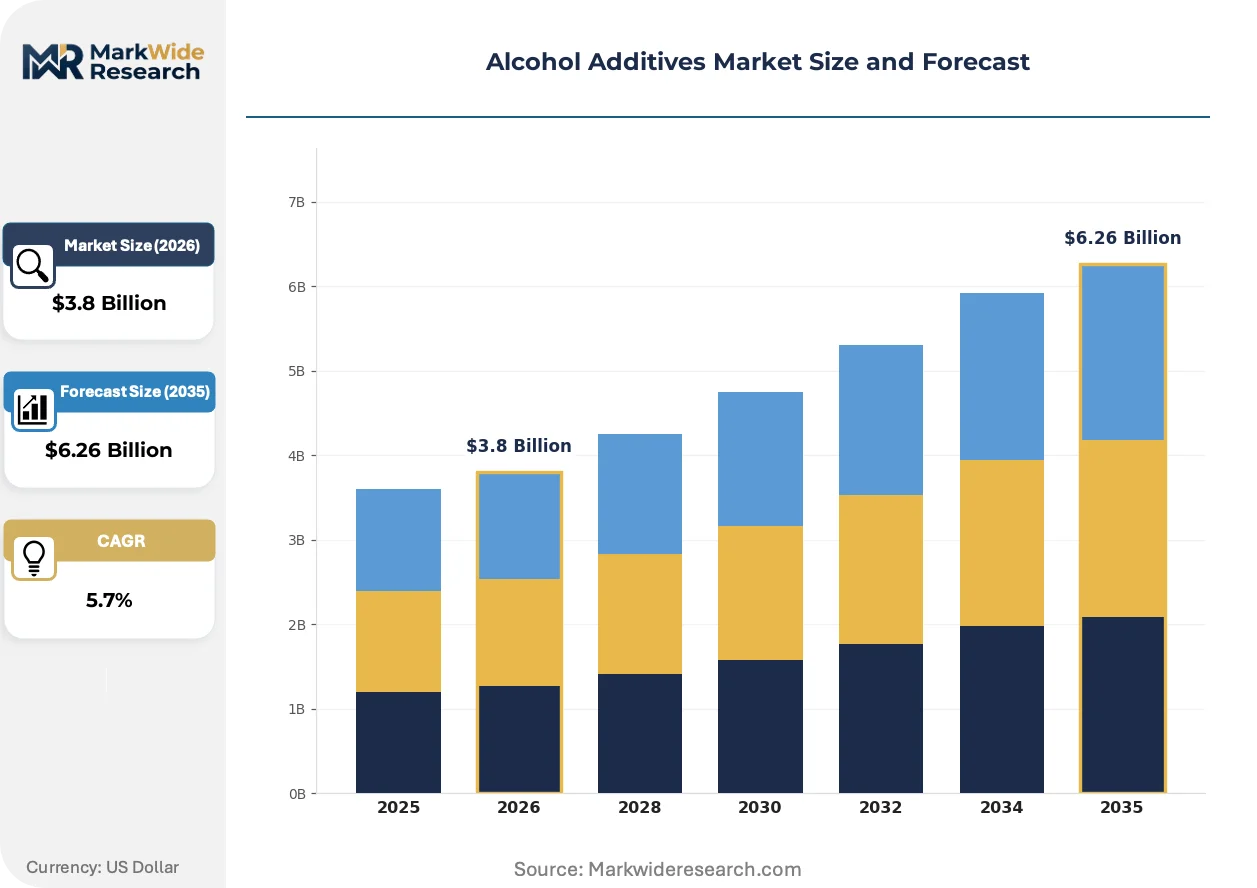
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.26 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Flavoring Agents, Preservatives, Sweeteners, Colorants Application: Beverages, Food Preparation, Pharmaceuticals, Cosmetics End User: Manufacturers, Distributors, Retailers, Consumers Form: Liquid, Powder, Granular, Paste |
| Companies Covered | Chr. Hansen Holding A/S, Cargill, Archer Daniels Midland Company, Kerry Group, BASF SE, Sensient Technologies Corporation, Givaudan, Koninklijke DSM N.V., International Flavors & Fragrances Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Alcohol Additives Market Emerging Trajectories
Digital formulation platforms and bioprocess engineering are compressing development cycles while regulatory harmonization efforts struggle to keep pace with clean-label chemistry advances.
Precision fermentation for natural flavor precursors is virtualizing traditional extraction supply chains. Craft distillers in Oregon and Scotland are adopting cell-cultured botanical compounds at pilot scale. This technology is virtualizing geographic dependence on tropical and Mediterranean botanical harvests, collapsing seasonality constraints and certificate-of-origin documentation burdens.
EFSA's revised exposure assessment methodology for flavoring substances is tightening safety factor calculations. The framework now requires cumulative intake modeling across beverage categories, forcing reformulation of high-dose caramel colorants and vanilla substitutes. Southern European producers dependent on traditional extraction methods face disproportionate compliance costs versus bioprocess competitors.
Beverage manufacturers are consolidating additive procurement under integrated taste and nutrition system contracts. Premium distillers in Germany and the United States now specify performance outcomes—shelf stability duration, color consistency across batch sizes—rather than ingredient specifications. This specification shift transfers formulation risk to additive suppliers while compressing supplier rosters to those with integrated R&D and manufacturing capabilities.
Alcohol Additives Market Segmentation
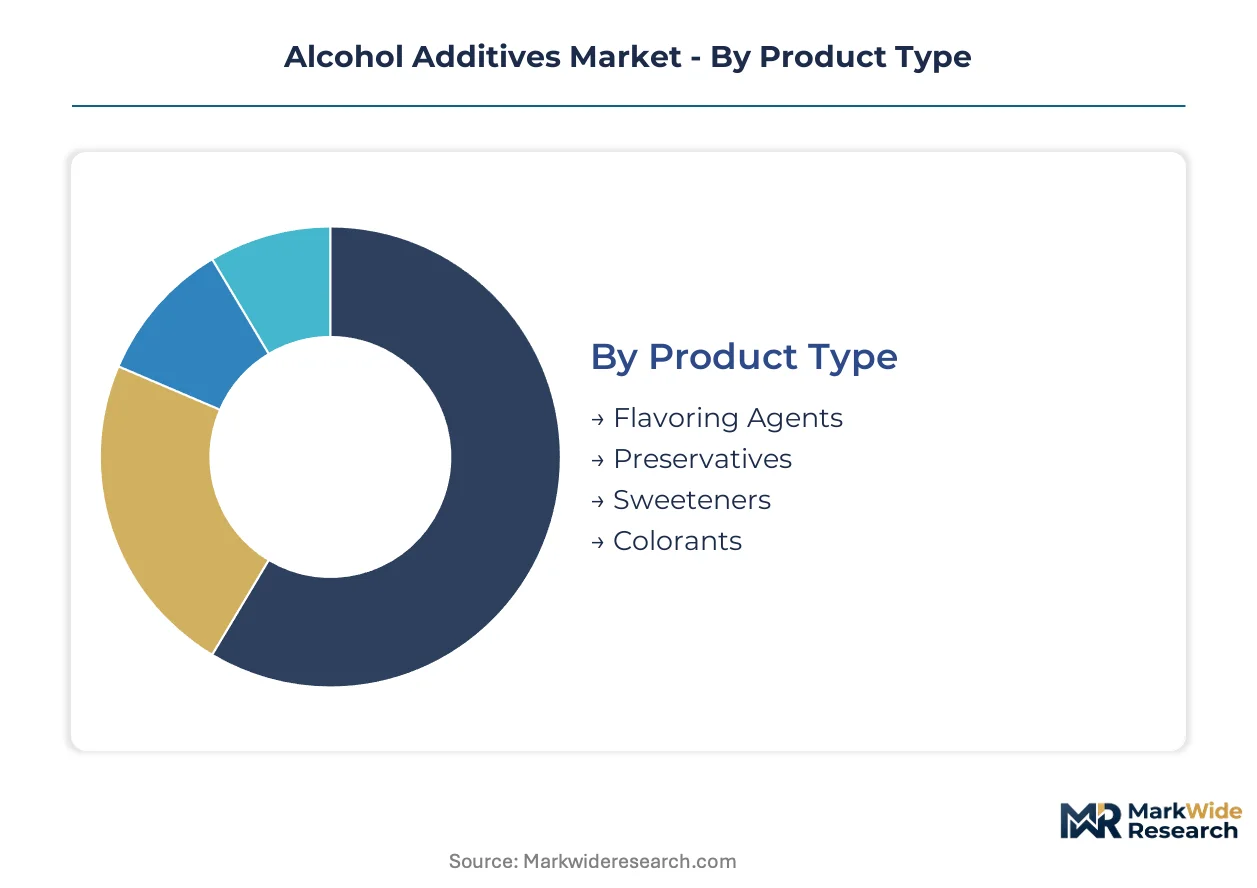
Segmentation in alcohol additives separates procurement cycles measured in months from those extending across years. Technical specification requirements and regulatory approval timelines vary dramatically across these divisions, dictating supplier relationship structures and inventory strategies.
Product Type:
Flavoring agents turn inventory fastest with quarterly reformulation cycles, while preservatives and colorants lock in annual supply agreements due to regulatory certification requirements.
- Flavoring Agents:Complex volatile compounds and botanical extracts formulated at parts-per-million concentrations to modify aroma and taste profiles. Demand concentrates in flavored vodka and botanical gin production in Germany and the United States, driven by ready-to-drink cocktail proliferation requiring precise flavor masking of base spirits.
- Preservatives:Antimicrobial and antioxidant formulations extending shelf stability through synthetic or fermentation-derived chemistries. Clean-label mandates from FDA and EFSA are compressing formulation timelines as distillers replace traditional stabilizers with natural alternatives in North American and European facilities.
- Sweeteners:Caloric and non-caloric carbohydrate additives adjusting perceived sweetness in liqueurs and cordials.
- Colorants:Caramel, spirit-based, and synthetic hues achieving visual standardization across batches.
Flavoring agents dominate installed base. Preservatives are where expansion concentrates.
Application:
Volume scales separate pharmaceutical-grade requirements from commodity beverage production, with certification tiers creating distinct margin pools.
- Beverages:Ethanol-containing products spanning spirits, wines, beers, and ready-to-drink formulations. Procurement concentrates in premium craft distilleries across Oregon and Scotland, where batch consistency requirements drive additive specification at low-percentage concentrations.
- Pharmaceuticals:EMA-compliant manufacturing infrastructure enabling crossover into pharmaceutical ethanol channels. European distillers leverage this certification to access premium-priced medical applications, with REACH compliance for synthetic colorants restricting supplier eligibility.
- Food Preparation:Culinary extracts and cooking alcohols requiring flavor standardization.
- Cosmetics:Alcohol-based personal care products utilizing similar preservative and fragrance technologies.
Beverage applications command volume leadership. Pharmaceuticals are climbing the fastest.
End User:
Supply chain position determines whether buyers specify ingredient chemistries or performance outcomes.
- Manufacturers:Distilleries, breweries, and beverage conglomerates integrating additives directly into production. German brewing conglomerates and U.S. craft distillers now specify shelf stability duration and color consistency rather than ingredient specifications, transferring formulation risk to additive suppliers.
- Distributors:Traditional chemical distributors being bypassed in North America and Western Europe as additive producers pursue direct-to-manufacturer contracting.
- Retailers:Private-label beverage programs requiring additive procurement for contract manufacturing arrangements.
- Consumers:Home distillation and craft cocktail enthusiasts purchasing small-format additive supplies.
Manufacturers anchor procurement volume. Direct contracting with producers is gaining share fastest.
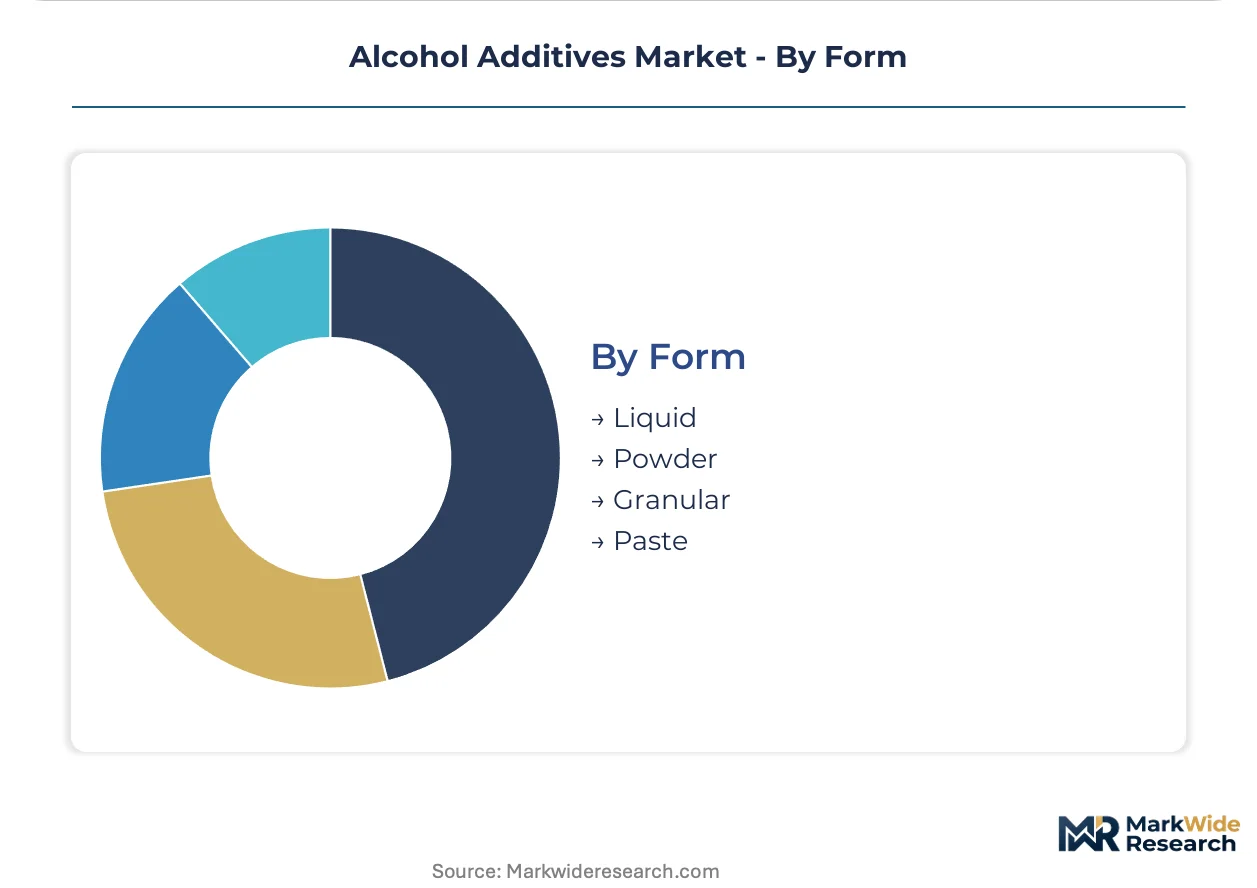
Form:
Physical state dictates handling infrastructure and dosing precision requirements across production scales.
- Liquid:Ready-to-dose solutions enabling precise metering in continuous production lines. Precision fermentation advances are virtualizing traditional extraction supply chains, with Oregon and Scotland craft distillers adopting cell-cultured botanical compounds at pilot scale.
- Powder:Spray-dried and crystallized formulations offering extended shelf life and reduced shipping costs.
- Granular:Free-flowing particulates for bulk handling systems in high-volume facilities.
- Paste:High-viscosity concentrates requiring heated transfer equipment but enabling maximal active ingredient density.
Liquid forms dominate current installed capacity. Powder is where capacity expansion concentrates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Port of Rotterdam's liquid bulk handling infrastructure underwrites Europe's dominance in alcohol additive distribution, connecting German distillation clusters to Atlantic trade lanes while FDA-regulated U.S. facilities serve craft spirit innovation corridors.
United States
Craft distilleries in Oregon and Kentucky drive procurement of fermentation-derived preservatives and botanical flavor systems. FDA's updated GRAS notification requirements extend compliance timelines for new flavoring substances entering the market. Portland's precision fermentation pilot facilities are adopting cell-cultured botanical compounds to collapse traditional extraction supply chains.
Germany
Bavarian brewing conglomerates and Baden-Württemberg distilleries anchor bulk orders of specialized caramel colorants and clean-label stabilizers. REACH compliance for synthetic additives restricts supplier eligibility to pre-registered European manufacturers. Hamburg's port infrastructure concentrates import logistics for tropical botanical extracts serving premium gin producers.
United Kingdom
Scottish whisky distillers and London-based ready-to-drink cocktail manufacturers demand integrated taste and color stabilization systems. EFSA's revised exposure assessment methodology tightens safety factor calculations for high-dose flavoring substances. Speyside's concentration of malt whisky production drives additive specification at parts-per-million precision.
France
Cognac houses and botanical gin distillers in Île-de-France procure natural preservative alternatives ahead of clean-label guidance finalization. ANSM oversight of pharmaceutical-grade ethanol channels creates crossover opportunities for EMA-compliant facilities. Reims' Champagne production infrastructure shares preservative qualification protocols with adjacent spirit manufacturers.
Canada
Health Canada's evolving clean-label definitions are compressing formulation timelines for synthetic colorant replacement. British Columbia's craft distillation corridor and Ontario's beverage manufacturing base specify shelf stability performance outcomes rather than ingredient chemistries. Toronto's food technology clusters are piloting precision fermentation for domestic botanical supply.
Alcohol Additives Market Vendor Landscape
On the supply side, the industry is consolidating around integrated taste and nutrition system providers capable of bundling multiple additive functions. The vendor base spans fermentation-derived specialty ingredient specialists, agricultural feedstock integrators, and diversified flavor houses. Three strategic archetypes dominate: backward-integrated agricultural processors, bioprocess technology platforms, and integrated formulation service providers. Capacity expansion in precision fermentation infrastructure and direct-to-manufacturer contracting represent the dominant competitive moves reshaping channel access.
Within the fermentation-derived specialty ingredient tier, Chr. Hansen Holding A/S occupies a position exemplifying bioprocess-based natural preservative alternatives. Cargill represents the agricultural integration archetype through captive corn and wheat feedstock control for natural flavor precursors. Kerry Group anchors the integrated formulation service model, bundling taste, color, and stability functions under performance-based contracts with beverage manufacturers.
| Leading Market Players |
|---|
| Chr. Hansen Holding A/S |
| Cargill |
| Archer Daniels Midland Company |
| Kerry Group |
| BASF SE |
| Sensient Technologies Corporation |
| Givaudan |
| Koninklijke DSM N.V. |
| International Flavors & Fragrances Inc. |
| Others |
Supply Flow & Price Mechanics
The Port of Rotterdam's liquid bulk handling infrastructure compresses freight economics for German distillers while amplifying price differentiation between REACH-registered European suppliers and non-compliant importers facing extended certification timelines. Corn and wheat feedstock volatility propagates directly into natural flavor precursor costs, squeezing margins for additive producers lacking backward integration into agricultural supply.
Pricing Analysis
Volume-discount tiering structures separate bulk procurement by German brewing conglomerates from spot purchases by Oregon craft distillers, with three-tier pricing stratification across premium fermentation-derived ingredients, standard synthetic formulations, and economy-grade commodity additives. Certification grade under REACH and FDA GRAS status creates price premiums of 15-30% for pre-registered suppliers versus new market entrants facing 12-18 month compliance delays. Cost compression in synthetic colorants is intensifying because EFSA's revised exposure assessment methodology forces reformulation investment. Small-batch craft distillers exhibit highest price sensitivity, while pharmaceutical-grade ethanol channels show lowest elasticity due to EMA compliance requirements.
Supply Chain Analysis
Tariff exposure between the United States and European Union member states dominates supply chain risk planning for flavoring substance distributors navigating trans-Atlantic regulatory divergence. Manufacturing concentrates in Germany, the United States, and France, with Hamburg's port infrastructure anchoring tropical botanical extract imports for premium gin producers. Feedstock dependencies center on corn and wheat for natural flavor precursors, tropical botanicals for complex volatile compounds, and petroleum derivatives for synthetic colorant bases. Single-source vulnerability persists in fermentation-derived specialty ingredients where Chr. Hansen and DSM anchor capacity. Distribution runs through direct-to-manufacturer contracting that bypasses traditional chemical distributors in North America and Western Europe.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The alcohol additives market functions as a service-attach opportunity where formulation risk transfer and performance-based shelf stability guarantees generate recurring revenue streams expanding faster than commodity additive sales. Integrated taste and nutrition systems that bundle multiple additive functions now command contract premiums versus standalone ingredient supply.
For Market Incumbents: Entrench market position by deepening backward integration into corn and wheat feedstocks to insulate margin from agricultural price volatility, while accelerating precision fermentation capacity expansion ahead of clean-label mandate finalization. Cargill's captive agricultural supply and Kerry Group's integrated formulation service model demonstrate defensive positioning against bioprocess technology platforms eroding traditional extraction economics. Priority lever: direct-to-manufacturer contracting to lock volume commitments and capture distributor margin. For New Entrants and Emerging Players: Pursue white-space opportunities in cell-cultured botanical compounds serving Oregon and Scotland craft distillers, where precision fermentation pilots are collapsing traditional extraction supply chains and certificate-of-origin documentation burdens. The most penetrable segment is botanical gin flavor systems requiring integrated taste and color stabilization that incumbent synthetic suppliers cannot readily reformulate. Go-to-market angle: performance-outcome contracts specifying shelf stability duration rather than ingredient specifications. For Investors and Strategic Acquirers: Fermentation-derived specialty ingredient platforms with EMA-compliant manufacturing infrastructure represent the priority acquisition archetype, enabling crossover into premium-priced pharmaceutical ethanol channels. Long-term viability hinges on clean-label chemistry advances outpacing regulatory harmonization efforts across FDA, EFSA, and Health Canada guidance documents. Signal to watch: TTB formulation approval cycle compression indicating regulatory pathway efficiency gains for novel additives.| Strategic Initiative | Industry Significance |
|---|---|
| Precision Fermentation Scale-Up | Cell-cultured botanical compounds collapse seasonality constraints for Oregon distillers. |
| Direct-to-Manufacturer Contracting | Bypassing chemical distributors captures 8-12 point margin improvement in North America. |
| REACH Pre-Registration Investment | Synthetic colorant eligibility restriction concentrates supplier pools to European incumbents. |
| EMA Compliance Infrastructure | Pharmaceutical-grade ethanol channel access unlocks premium pricing for European distillers. |
| Integrated Formulation Systems | Bundled taste-color-stability functions transfer formulation risk from German brewers to suppliers. |
Methodological Framework
Cross-validation between primary interviews with fermentation technology directors and regulatory affairs specialists and secondary validation against FDA GRAS notification databases and EFSA flavoring substance exposure assessments anchors the qualitative findings. Plant managers at German distillation facilities, procurement leads at U.S. craft beverage conglomerates, distribution channel partners in Rotterdam's liquid bulk terminals, and technical R&D directors at precision fermentation pilot facilities provided operational perspective. Secondary sources included customs and trade data for corn and wheat feedstock flows, TTB formulation approval tracking databases, REACH registration dossiers, and SEC 10-K filings from publicly traded additive suppliers. Bottom-up demand modeling triangulated against top-down market sizing from industry association reports.
Calibration against historical price elasticity patterns for natural versus synthetic preservatives and colorants shaped the analytical framework across the projection horizon. Segmentation dimensions modeled include product type tier, application certification grade, end-user supply chain position, and physical form handling infrastructure. CAGRs derived from regression analysis of procurement volume trends and regulatory approval velocity. Industry-specific forecast inputs incorporated EFSA's revised exposure assessment methodology implementation timeline and precision fermentation capacity buildout announcements.
Sensitivities concentrate around clean-label definition finalization timelines across FDA, EFSA, and Health Canada, feedstock price volatility in agricultural commodities, and TTB formulation approval cycle duration. Forecasts reflect assumptions regarding regulatory harmonization progress and bioprocess technology cost curves. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Additives and Ingredients
AKD Emulsifier Market
Food Additives and Ingredients
France Food Acidulants Market
Food Additives and Ingredients
Global Gamma Linolenic Acid Market
Food Additives and Ingredients
Microencapsulated Phytosterols Market
Food Additives and Ingredients
Carrageenan Market
Food Additives and Ingredients
Global Fatty Acids Market
Food Additives and Ingredients
Food Acidulants Market
Food Additives and Ingredients
Carob Bean Gum Market
Food Additives and Ingredients
Neohesperidin Market
Food Additives and Ingredients
Bulking Agents Market
Food Additives and Ingredients
Allulose for Food Market
Food Additives and Ingredients
Acetylated Monoglycerides (AMG) Market
Food Additives and Ingredients
Australia Anti Caking Market
Food Additives and Ingredients
North America Microencapsulation Market
Food Additives and Ingredients
Food Texturing Agents Market
Food Additives and Ingredients
Global Organic Feed Additives Market