
 Food Binders Market | 2026-2036
Food Binders Market Size, Share, and Industry Trends Forecast 2026-2036
Food Binders Market Analysis
A capital-intensity divergence between integrated starch processors and specialty hydrocolloid developers is reorganizing competitive tiers in food binders. Cargill, Incorporated leverages its North American grain supply base to sustain cost leadership in native and modified starches. Ingredion Incorporated anchors its position through R&D intensity in clean-label texturizing systems for meat alternatives. Kerry Group PLC differentiates via flavor-binding integration that extends beyond commodity hydrocolloids into functional premixes.
Food binders comprise hydrocolloids, proteins, and starches that form viscoelastic networks through hydration, gelatinization, or cross-linking, typically functioning at concentrations of 0.5% to 5% by weight to confer cohesion, moisture retention, and sliceability in processed foods. Starch variants dominate volume due to cost-performance ratios in battered and breaded applications, while cellulose derivatives capture margin pools in gluten-free bakery where thermal stability requirements command premium positioning. Pectin competes in confectionery and fruit-based systems where acid-set gelling creates formulation lock-in with specific fruit solids and pH windows.
EFSA novel food assessments, FDA GRAS self-affirmation pathways, and USDA organic certification standards collectively shape market access timelines and label claim permissibility for new binding ingredients. REACH compliance in Europe and evolving EPA bio-based substance designations in the United States add testing cost layers that favor larger players with dedicated regulatory affairs capacity. Stakeholders must monitor fermentation-derived binding proteins as these platforms approach commercial scale and challenge established extraction-based supply chains.
Market Dynamics
Clean-label reformulation mandates from EFSA and FDA are forcing ingredient substitution across processed meat, bakery, and confectionery segments, compressing demand for chemically modified binders while expanding fermentation-derived and minimally processed alternatives.
Growth Catalysts
- Plant-based meat analogue expansion:Food manufacturers in Germany and China are scaling extrusion-compatible binding systems to replicate muscle fiber texture in alternative proteins.
- REACH compliance differentiation:ECHA registration requirements for novel hydrocolloids create competitive moats for European producers with established toxicology dossiers.
- Fermentation platform maturation:Precision fermentation of binding proteins is nearing commercial scale, offering supply security independent of agricultural commodity cycles.
Market Restraints
- Guar gum price volatility:Indian monsoon dependency and speculative trading in Rajasthan processing clusters create input cost instability for texture-modified systems.
- Carrageenan substitution pressure:Consumer advocacy campaigns linking degraded carrageenan to inflammation are accelerating pectin and gellan gum adoption in dairy alternatives.
- Modified starch technical ceiling:Cross-linked starches face performance limits in retort applications above 121°C, restricting penetration into shelf-stable ready meals.
Strategic Opportunities
- Brazilian processing capacity expansion:JBS and BRF vertical integration into ingredient premixes creates captive demand for clean-label binders in South American export operations.
- Cell-cultured meat scaffolding:Edible hydrogel networks for structured protein cultivation represent an emerging application with formulation lock-in potential.
- USDA organic certification arbitrage:Certified organic hydrocolloids command 40-60% price premiums in North American natural channel distribution.
Industry Challenges
- Fermentation scale-up talent scarcity:Bioprocess engineering expertise for food-grade protein production concentrates in Boston and Copenhagen clusters, constraining facility deployment timelines.
- Dual-label compliance complexity:Simultaneous organic and non-GMO verification requirements extend certification timelines by 8-14 months for new ingredient introductions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Food Binders Market |
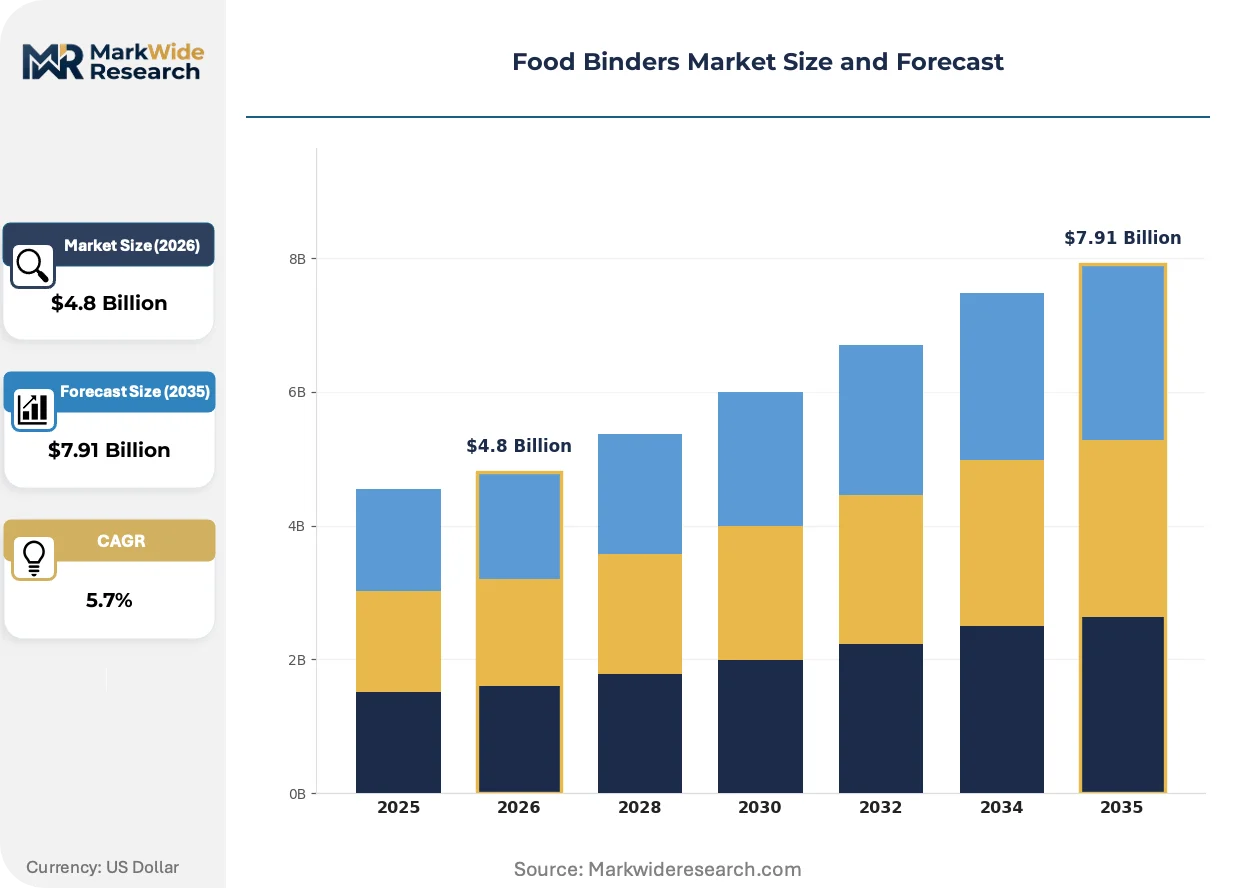
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $7.91 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Starch, Gelatin, Pectin, Cellulose Form: Powder, Granules, Liquid, Paste End User: Food Manufacturing, Confectionery, Bakery, Meat Processing Application: Thickening Agent, Coating, Stabilizer, Filler |
| Companies Covered | Tate & Lyle PLC, Archer Daniels Midland Company, Ingredion Incorporated, CP Kelco U.S., Inc., Koninklijke DSM N.V., Cargill, Incorporated, Kerry Group PLC, Ashland Global Holdings, Inc., DuPont de Nemours, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Food Binders Market Emerging Trajectories
Fermentation-derived binding platforms are disrupting extraction-based supply chains, while regulatory scrutiny of chemical modification intensifies. These forces are compressing traditional hydrocolloid margins and rewarding biotech-enabled ingredient developers.
Precision fermentation of collagen and elastin analogues is displacing animal-derived gelatin in confectionery and pharmaceutical capsule applications. European and North American clean-label confectioners are adopting these platforms at pilot scale. The technology is displacing established gelatin supply relationships by eliminating religious dietary restrictions and supply chain traceability concerns.
EFSA's 2023 updated guidance on novel food assessments requires extended 90-day toxicology studies for enzymatically modified starches. Industrial consequence includes 18-24 month approval timelines and seven-figure dossier preparation costs. Gluten-free bakery manufacturers are responding by accelerating native starch and hydrocolloid blend development to bypass novel food classification.
Direct procurement relationships between plant-based meat startups and fermentation ingredient developers are compressing traditional distributor margins. Specialty ingredient distributors in California and Netherlands are losing volume to platform-to-brand supply contracts. This channel disintermediation is most visible in North American alternative protein clusters where vertical integration accelerates formulation co-development cycles.
Food Binders Market Segmentation
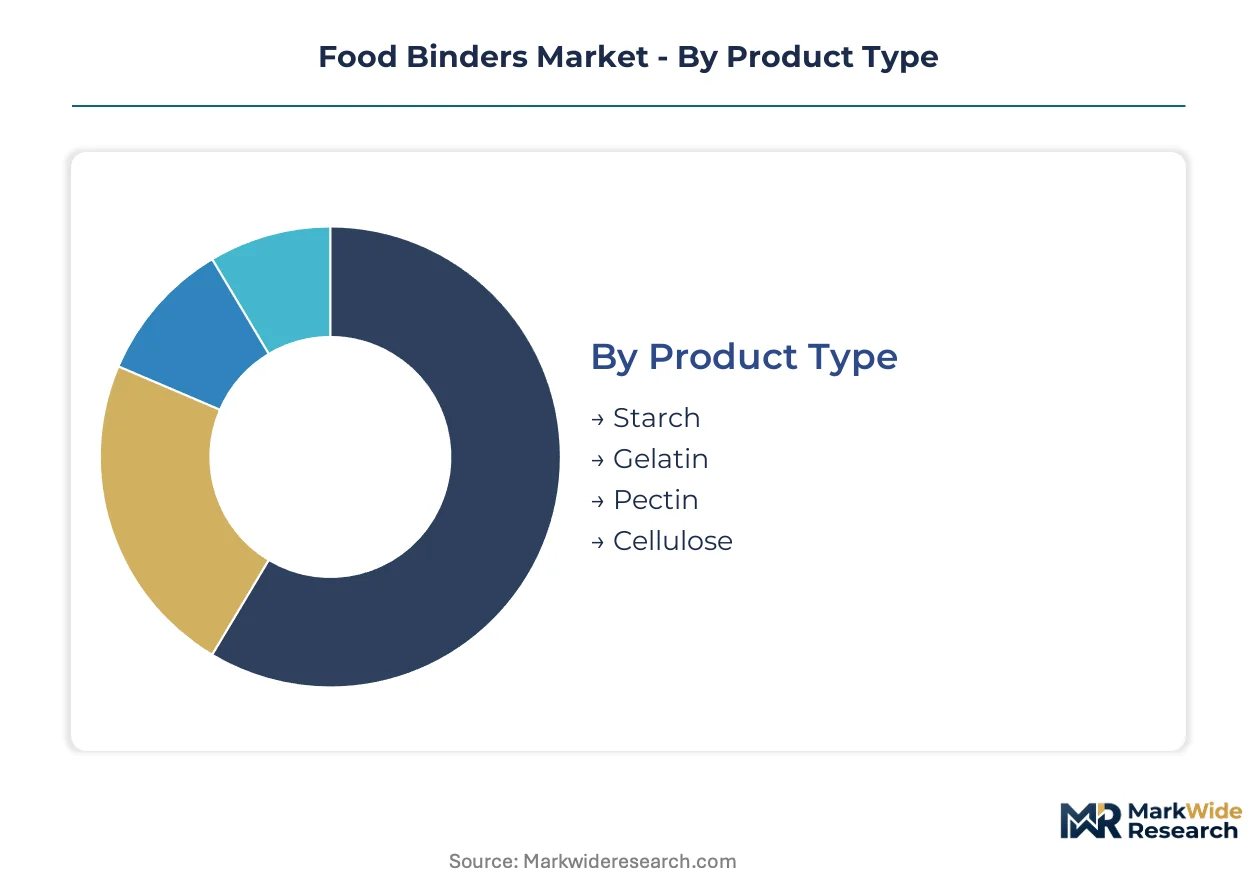
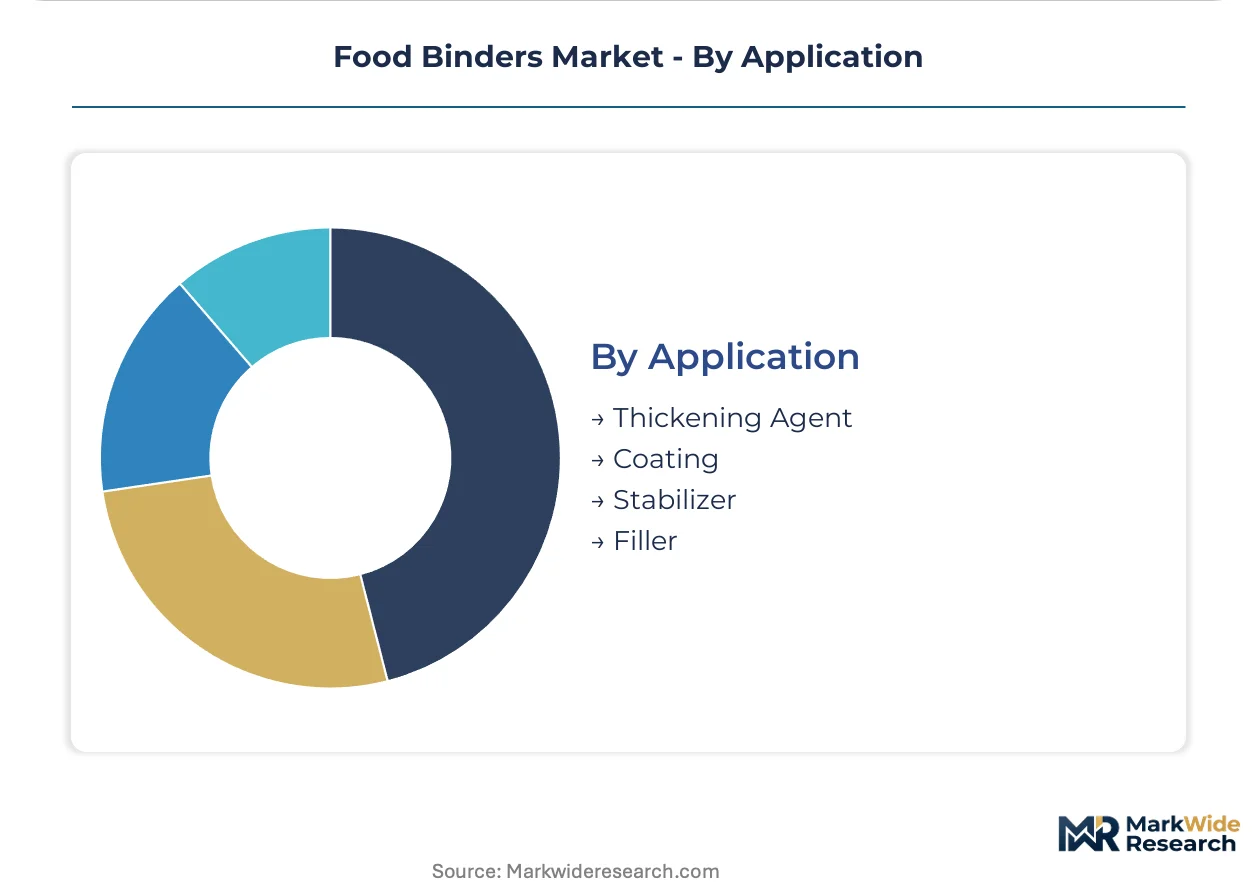
Food binders serve distinct functional roles across processing stages, with product chemistry and physical form determining compatibility with extrusion, thermal processing, and clean-label positioning requirements. Segmentation reveals how ingredient suppliers align technical specifications with channel-specific demands in meat alternatives, gluten-free bakery, and confectionery systems.
Product Type:
Channel distribution varies sharply by binder chemistry, with commodity starches flowing through broadline distributors while specialty hydrocolloids move via technical ingredient specialists.
- Starch:Native and modified starches from corn, tapioca, and potato sources provide cost-efficient viscosity building through gelatinization. Demand concentrates in Germany and China for battered and breaded applications where shear-thinning behavior controls coating adhesion during high-speed processing lines.
- Gelatin:Collagen-derived protein binders form thermoreversible gels through triple-helix renaturation. Pharmaceutical capsule and premium confectionery manufacturers in Switzerland and Japan source bovine and porcine variants, though religious dietary restrictions are accelerating precision-fermentation substitution.
- Pectin:Citrus and apple-derived polysaccharides create acid-set gels in low-pH confectionery and fruit preparations.
- Cellulose:Microcrystalline and carboxymethyl derivatives deliver thermal stability in gluten-free bakery and reduced-fat meat systems.
By volume, starch leads. By growth pace, cellulose is gaining share fastest amid clean-label bakery expansion.
Form:
Physical state selection tracks processing equipment requirements, with powder dominating dry-mix applications and liquid concentrates serving continuous-process lines.
- Powder:Spray-dried and agglomerated particles ensure dispersion uniformity in dry-blend premixes. Meat processing facilities in Brazil and US Midwest regions specify powder grades for injection brines where complete hydration prior to thermal treatment prevents texture defects.
- Granules:Coarse-particle binders control dusting and improve flowability in high-shear mixing environments. Industrial bakeries in Italy and Mexico specify granulated cellulose for dusting applications where fine particles create respiratory exposure concerns.
- Liquid:Pre-hydrated colloidal suspensions eliminate dispersion time in continuous-process lines.
- Paste:High-solids preparations serve specialized coating and binding operations.
By operational simplicity, powder dominates. By line-speed optimization, liquid is climbing the fastest.
End User:
Customer scale and technical sophistication determine service intensity, with multinational manufacturers demanding formulation co-development and regional processors prioritizing cost stability.
- Food Manufacturing:Broad category spanning sauce, dressing, and prepared meal producers requiring multi-functional binders. Retort-stable systems for shelf-stable ready meals in Thailand and Spain face technical ceilings with modified starches above 121°C, driving hydrocolloid blend adoption.
- Confectionery:Gummy, jelly, and aerated candy producers demand precise gel strength and melt-point control. EFSA novel food assessments for enzymatically modified starches are extending approval timelines, pushing European confectioners toward pectin and established gelatin alternatives.
- Bakery:Gluten-free and clean-label bread producers require moisture retention without wheat protein networks.
- Meat Processing:Commuted and restructured meat systems depend on cold-binding proteins and starches.
By procurement volume, food manufacturing leads. By formulation complexity, confectionery shows steepest expansion trajectory.
Application:
Functional role determines performance specifications, with thickening and stabilization commanding premium pricing over filler applications.
- Thickening Agent:Viscosity-building binders control flow and mouthfeel in sauces, soups, and dairy alternatives. Plant-based milk startups in California and Netherlands specify gellan gum and locust bean gum combinations for suspension stability without homogenization dependency.
- Coating:Adhesive binders ensure batter and breading adhesion through freeze-thaw cycles. Poultry processors in China and Germany are scaling extrusion-compatible binding systems to replicate muscle fiber texture in alternative protein coatings.
- Stabilizer:Emulsion and foam preservation across frozen and ambient distribution.
- Filler:Cost-driven bulking with minimal functional contribution.
By value concentration, thickening leads. By clean-label substitution urgency, stabilizer is expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Price elasticity varies sharply across geographies. Brazilian meat processors absorb guar gum volatility through vertical sourcing arrangements, while German confectioners pay premiums for EFSA-compliant clean-label systems. Chinese manufacturers prioritize cost-performance ratios in starch procurement.
Germany
EFSA novel food assessments drive reformulation timelines for enzymatically modified starches. REACH compliance creates competitive moats for domestic hydrocolloid developers with established toxicology dossiers. Processing clusters in North Rhine-Westphalia concentrate extrusion-compatible binding systems for plant-based meat analogues.
China
SAMR food safety standards accelerate substitution of chemically modified binders in bakery and confectionery segments. Dual carbon goals pressure processors toward fermentation-derived alternatives with lower agricultural input intensity. Yangtze River Delta facilities scale gellan gum and locust bean gum production for dairy alternative suspension systems.
Brazil
JBS and BRF captive demand for clean-label binders expands as vertical integration into ingredient premixes deepens. ANVISA regulatory harmonization with Mercosur standards streamlines cross-border formulation approvals. São Paulo state processing corridors concentrate pectin and native starch blending operations for export-oriented meat processing.
United States
FDA GRAS self-affirmation pathways shape market access timelines for new binding ingredients, favoring larger players with dedicated regulatory affairs capacity. USDA organic certification commands 40-60% price premiums in natural channel distribution. California alternative protein clusters drive direct procurement relationships that compress traditional distributor margins.
India
FSSAI clean-label mandates accelerate carrageenan substitution in dairy alternatives despite guar gum price volatility from Rajasthan monsoon dependency. PLI scheme incentives attract fermentation platform investments for food-grade protein production. Gujarat processing hubs concentrate guar gum refinement for global texture-modified system supply.
Food Binders Market Vendor Landscape
A small set of integrated leaders sits above a broader specialist tier in food binders. Cargill leverages North American grain supply bases to sustain cost leadership in native and modified starches, while Ingredion anchors positions through R&D intensity in clean-label texturizing systems. Kerry Group differentiates via flavor-binding integration extending beyond commodity hydrocolloids. Strategic moves concentrate on backward integration into captive supply chains and fermentation platform licensing to secure supply independent of agricultural commodity cycles.
Within the integrated grain-processor archetype, Cargill, Incorporated and Archer Daniels Midland Company exemplify scale-driven positions leveraging continental supply bases. Among specialty hydrocolloid developers, CP Kelco U.S., Inc. occupies a position representing fermentation-derived and extraction-based gellan gum supply. Tate & Lyle PLC sits within the texturizing systems tier, exemplifying reformulation service capabilities that extend beyond commodity ingredient supply. These anchors illustrate how competitive positioning stratifies across cost leadership, technical specialization, and integrated formulation partnerships.
| Leading Market Players |
|---|
| Tate & Lyle PLC |
| Archer Daniels Midland Company |
| Ingredion Incorporated |
| CP Kelco U.S., Inc. |
| Koninklijke DSM N.V. |
| Cargill, Incorporated |
| Kerry Group PLC |
| Ashland Global Holdings, Inc. |
| DuPont de Nemours, Inc. |
| Others |
Supply Flow & Price Mechanics
Grain-milling capacity utilization in the North American corn belt shapes cost floors for native starch derivatives, concentrating supply leverage among integrated processors while forcing specialty hydrocolloid developers to defend margins through certification premiums and technical service bundling.
Pricing Analysis
After-sales formulation support and extended technical service contracts drive lifetime value in specialty hydrocolloids, distinguishing premium suppliers from commodity starch vendors. The market operates on a hybrid structure combining contract-based long-term offtake for bulk starches with project-based pricing for custom texturizing systems. Price differentiation rests on organic certification grade and volume scale, with USDA-certified organic hydrocolloids commanding substantial premiums over conventional grades. Cost compression in modified starches is intensifying because EFSA novel food assessments extend approval timelines and inflate compliance costs. Small regional meat processors show highest price sensitivity, while multinational confectioners prioritize performance consistency over unit economics.
Supply Chain Analysis
Inventory buffers and extended lead times for Indian guar gum refinement create working capital intensity that favors larger buyers with balance sheet capacity to absorb monsoon-driven supply disruptions. Geographic supply concentration centers on the United States for corn and potato starches, India for guar gum refinement, and Brazil for pectin and native starch blending operations. Raw material dependencies draw from agricultural commodity harvests, fermentation feedstocks, and citrus peel waste streams for pectin extraction. Single-source vulnerability in Rajasthan guar gum processing clusters exposes texture-modified system manufacturers to weather-induced supply interruptions. Distribution runs through technical ingredient specialists for specialty hydrocolloids and broadline distributors for commodity starches.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation across clean-label reformulation requirements creates niche opportunities for targeted players, as divergent EFSA and FDA timelines force manufacturers to maintain parallel ingredient portfolios.
For Market Incumbents: Secure fermentation platform licensing agreements to reduce dependency on agricultural commodity cycles, while consolidating backward integration into captive guar gum processing in Rajasthan to buffer against Indian monsoon volatility. Precision-fermentation startups threaten established gelatin supply relationships in pharmaceutical and confectionery segments. R&D intensity in clean-label texturizing systems represents the critical defensive lever for starch processors facing enzymatic modification scrutiny. For New Entrants and Emerging Players: FDA GRAS self-affirmation fast-tracks offer regulatory arbitrage against EFSA's extended novel food timelines, enabling quicker market access for fermentation-derived binding proteins. White-space targets include Brazilian meat processing corridors where JBS and BRF captive demand for clean-label premixes outpaces domestic supply, and gluten-free bakery applications where thermal-stable cellulose derivatives displace modified starches. A direct procurement platform-to-brand model bypasses traditional distributor margins in North American alternative protein clusters. For Investors and Strategic Acquirers: Regional hydrocolloid specialists with established REACH dossiers and EFSA-compliant toxicology packages represent acquisition targets with defensive moats against regulatory escalation. Long-term viability over the coming decade hinges on bioprocess engineering talent concentration and fermentation scale-up execution rather than extraction-based asset bases. Monitor precision-fermentation platform commercialization announcements from Boston and Copenhagen clusters as the key inflection signal for supply chain displacement timelines.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Fermentation Feedstocks | Captive supply of glucose and nitrogen sources insulates bioprocess operations from agricultural commodity price swings. |
| REACH Dossier Acquisition | Established ECHA toxicology packages compress market access timelines for novel hydrocolloid introductions. |
| Direct Platform-to-Brand Supply Contracts | Channel disintermediation in California alternative protein clusters accelerates formulation co-development cycles. |
| Organic Certification Investment | USDA-certified hydrocolloids capture 40-60% price premiums in North American natural channel distribution. |
| Bioprocess Engineering Talent Cluster Expansion | Boston and Copenhagen concentration constrains facility deployment timelines for fermentation scale-up. |
Methodological Framework
The analysis maps hydrocolloid, protein, and starch sub-sectors, each validated through formulation scientists at multinational food manufacturers, procurement leads at meat processing facilities, regulatory affairs directors navigating EFSA and FDA pathways, and technical service heads at specialty ingredient distributors. Primary interview insights triangulate against secondary sources including EFSA novel food assessment databases, FDA GRAS notification filings, USDA organic certification records, and customs trade data for guar gum and pectin flows. Bottom-up volume builds from application-specific consumption rates cross-check against top-down market sizing from processor capacity and utilization estimates.
Consistency checks against external benchmarks validate volume and value outputs across the projection horizon. The analytical framework models segmentation dimensions spanning binder chemistry, physical form, end-user scale, and functional application role, with regional regulatory clusters as an additional cross-cutting dimension. CAGRs derive from trend extrapolation of plant-based meat analogue adoption curves, clean-label reformulation penetration rates, and fermentation platform maturation timelines. Industry-specific forecast inputs include extrusion-compatible binding system deployment in German and Chinese alternative protein facilities, and retort-stable hydrocolloid blend substitution patterns in Thai and Spanish ready meal production.
Underlying assumptions cover sustained clean-label regulatory pressure from EFSA and FDA, continued fermentation platform cost reduction, and stable Indian monsoon patterns for guar gum supply, with deviation risk concentrated in novel food assessment timeline extensions and bioprocess engineering talent scarcity. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Additives and Ingredients
Food Protein Ingredient Market
Food Additives and Ingredients
Spain Food Emulsifiers Market
Food Additives and Ingredients
Phosphated Distarch Phosphate Market
Food Additives and Ingredients
Russia Food Additives Market
Food Additives and Ingredients
Food Starch Market
Food Additives and Ingredients
Beverage Clouding Agent Market
Food Additives and Ingredients
Chocolate Wax Market
Food Additives and Ingredients
Japan Food Enzymes Market
Food Additives and Ingredients
Carmine Alternatives Market
Food Additives and Ingredients
Australia Feed Additives Market
Food Additives and Ingredients
Neohesperidine DC Market
Food Additives and Ingredients
Acetylated Monoglycerides (AMG) Market
Food Additives and Ingredients
Africa Feed Additives Market
Food Additives and Ingredients
Modified Milk Ingredients Market
Food Additives and Ingredients
Starch-Based Texturizing Agents Market
Food Additives and Ingredients
Non-PHO Emulsifiers Market