
 Food Phosphate Market | 2026-2036
Food Phosphate Market Size, Share, and Industry Trends Forecast 2026-2036
Food Phosphate Market Analysis
Meat product applications are restructuring demand patterns across the food phosphate landscape. Poultry and processed red meat sectors in emerging economies now absorb larger phosphate volumes than traditional bakery end uses. Israel Chemicals Limited leverages integrated phosphate rock mining to sustain cost advantages across multiple food-grade derivatives. Chemische Fabrik Budenheim KG anchors European supply through specialized purifications for sodium and potassium phosphates. Prayon SA differentiates via technical service partnerships with industrial meat processors.
Food phosphates comprise mineral salts derived from phosphoric acid, classified by their degree of neutralization into mono-, di-, and tri-phosphate forms with specific pH buffering capacities and ionic charges that determine functionality in protein systems. These compounds serve primarily as moisture-retention agents, emulsifiers, and stabilizers in processed protein matrices and leavening systems. Mono phosphates dominate current volume due to established bakery and beverage applications, while blended phosphates represent the fastest-expanding category as formulators seek multifunctional additives that reduce label complexity. Di phosphates concentrate margin pools in premium meat processing segments where performance specifications are tightest.
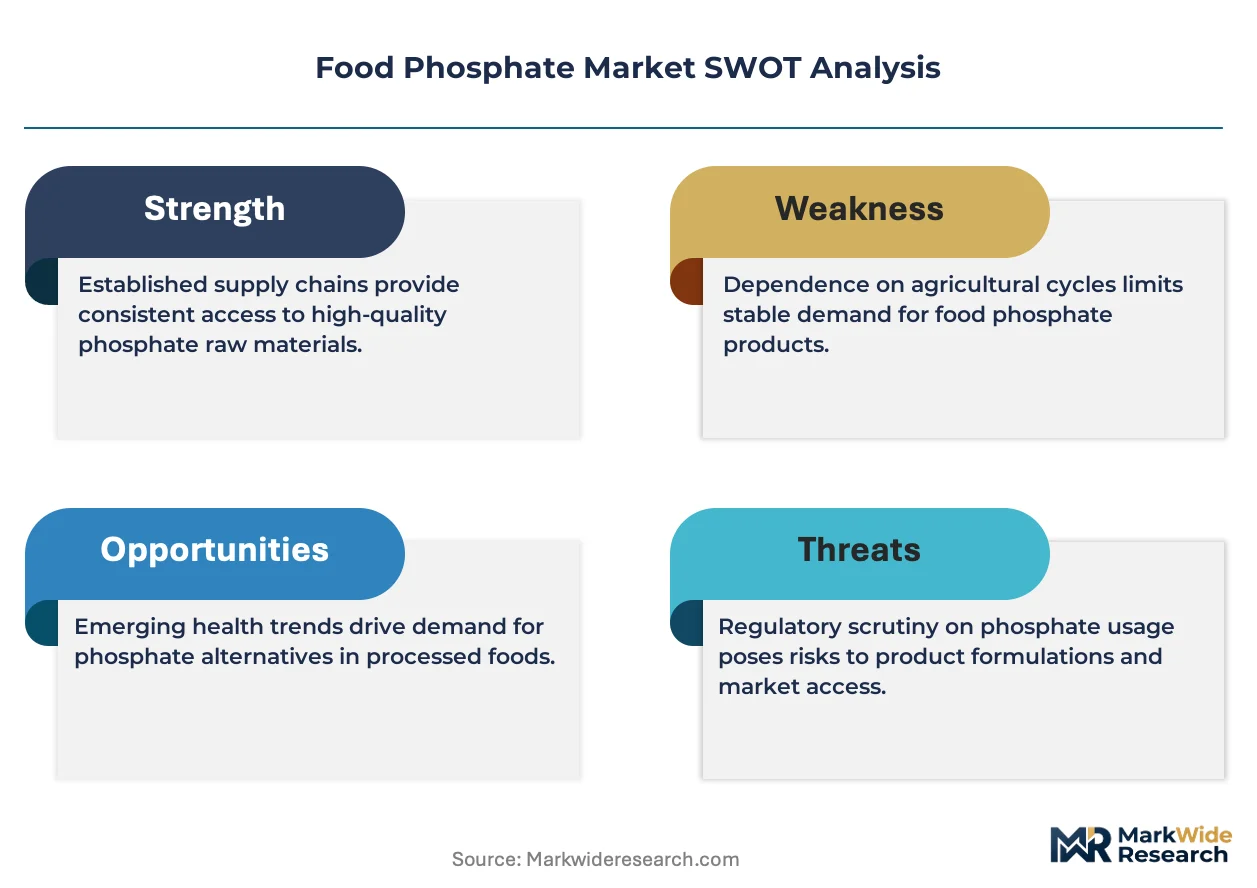
The FDA maintains Generally Recognized As Safe listings for specific phosphate salts while reviewing cumulative dietary exposure thresholds, compelling suppliers to document usage rates across customer portfolios. EFSA evaluates phosphate additive intake through total diet studies, influencing reformulation decisions by pan-European food manufacturers. China's SAMR enforces GB standards for food-grade phosphate purity that determine import eligibility and domestic production licensing. Stakeholders must monitor regulatory accumulation limits in major consuming jurisdictions while assessing captive phosphate integration versus merchant supply strategies.
Market Dynamics
Meat processors across Southeast Asia are consolidating phosphate sourcing around integrated suppliers who control both phosphate rock extraction and food-grade purification, compressing merchant margins and favoring backward-integrated producers with captive technical-grade capacity.
Growth Catalysts
- Processed Protein Expansion:Poultry and red meat processing sectors in Vietnam, Thailand, and Indonesia absorb rising phosphate volumes for moisture retention and shelf-life extension applications.
- REACH Compliance Migration:European formulators under ECHA oversight are reformulating toward cleaner-label phosphate blends that meet cumulative exposure thresholds while maintaining functionality.
- Domestic Capacity Buildout:China's SAMR licensing framework for food-grade phosphate purity is enabling local producers to displace imports as processed food output climbs.
Market Restraints
- Phosphate Rock Concentration:Morocco, Jordan, and Saudi Arabia control roughly three-quarters of global phosphate rock reserves, creating supply vulnerability for non-integrated food-grade producers.
- Clean-Label Substitution:Plant-based hydrocolloids and fermented protein stabilizers are capturing share in premium meat segments where phosphate-free positioning commands retail shelf space.
- EFSA Intake Ceilings:The European regulator's tightening additive exposure limits are forcing reformulation costs onto manufacturers serving pan-European retail chains.
Strategic Opportunities
- Blended Phosphate White Space:Multifunctional additive systems that combine mono-, di-, and tri-phosphate forms in single formulations reduce label complexity for clean-label-conscious processors.
- India Processing Infrastructure:Cold chain expansion and organized retail penetration in Maharashtra and Gujarat create first-mover advantages for phosphate suppliers establishing technical service partnerships.
- Dual Carbon Alignment:China's MEE emissions frameworks and carbon intensity targets favor phosphate producers with energy-efficient thermal processing and captive renewable power.
Industry Challenges
- Food-Grade Certification Timelines:GB standard compliance for SAMR licensing requires 18-24 month validation cycles that delay market entry for new phosphate derivatives.
- Protein Matrix Expertise Scarcity:Formulation chemists who understand phosphate-protein interactions in complex meat systems command premium compensation and limited talent pools.
- Legacy Equipment Retrofit Costs:Southeast Asian processors running 1990s-era injection and tumbling systems face capital barriers to optimizing phosphate uptake efficiency.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Food Phosphate Market |
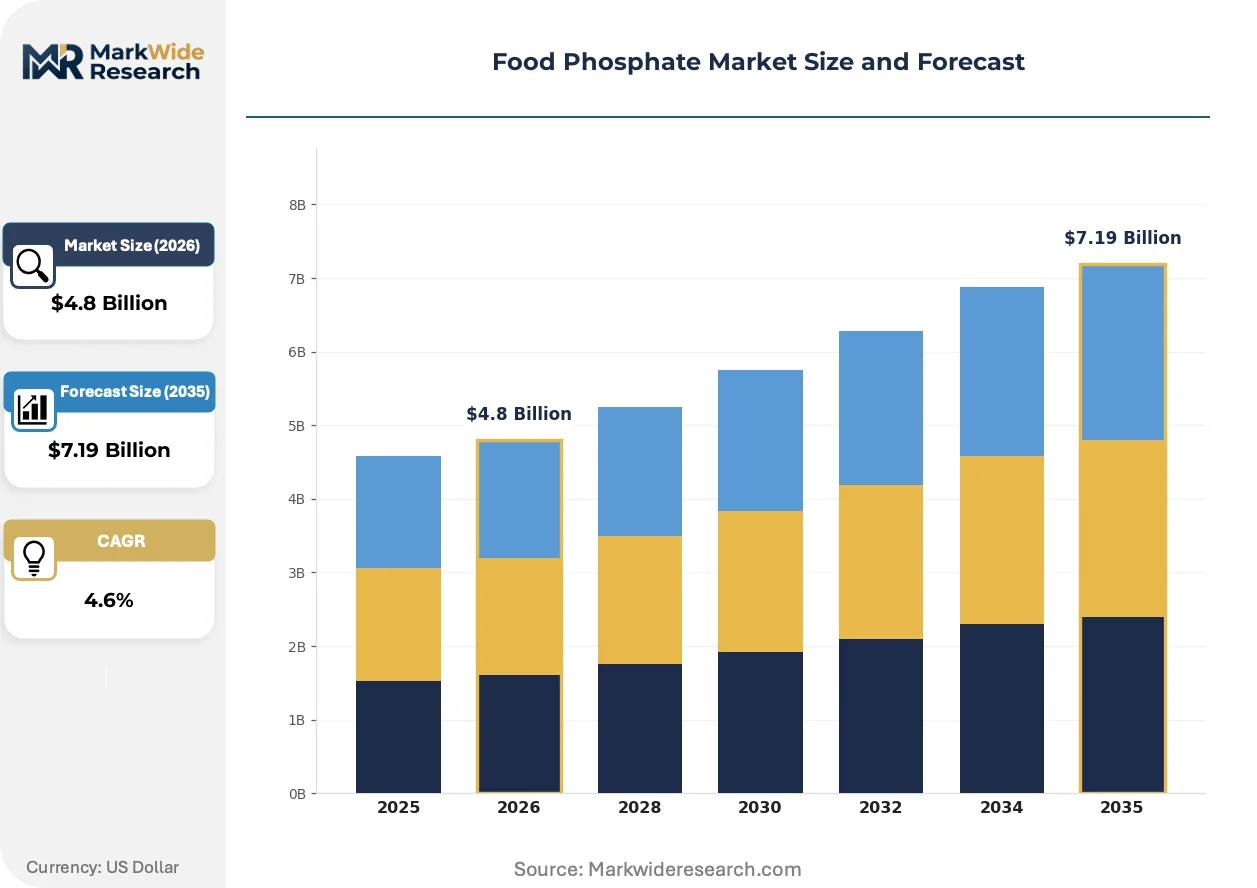
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $7.19 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Mono Phosphates, Di Phosphates, Tri Phosphates, Blended Phosphates End Use: Beverages, Meat Products, Dairy Products, Bakery Form: Powder, Granular, Liquid, Tablets Packaging Type: Bulk Bags, Drum Packaging, Sachets, Tote Bags |
| Companies Covered | Israel Chemicals Limited, Chemische Fabrik Budenheim KG, Solvay SA, Fosfa Inc., Prayon SA, The Mosaic Company, Innophos Holdings Inc., Yara International, OCP Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Food Phosphate Market Emerging Trajectories
Formulation science and regulatory compliance frameworks are converging to reshape how phosphate suppliers design, position, and deliver functional ingredients to protein processors and bakery manufacturers.
Encapsulated phosphate systems are modularizing delivery architectures for moisture retention. Meat processors in Brazil and Mexico are piloting time-release phosphate coatings that activate during thermal processing rather than raw storage. This technology is modularizing the traditional separation between pre-rigor and post-rigor application stages, enabling single-dose formulations that previously required multi-step addition protocols.
EFSA's 2023-2024 total diet study recalibration is compressing acceptable daily intake assumptions for phosphate additives across European markets. Manufacturers serving pan-European retail chains are accelerating reformulation timelines to maintain shelf placement under revised exposure models. Bakery applications face the steepest adjustment curves given historical reliance on mono-phosphate leavening systems.
Direct technical service engagement is displacing traditional distributor-led selling in premium meat processing segments. Brazilian and Argentine beef processors now expect on-site formulation support, application trials, and label claim documentation as standard procurement prerequisites. This behavioral shift concentrates contract value with suppliers maintaining regional technical laboratories and trained protein application specialists.
Food Phosphate Market Segmentation
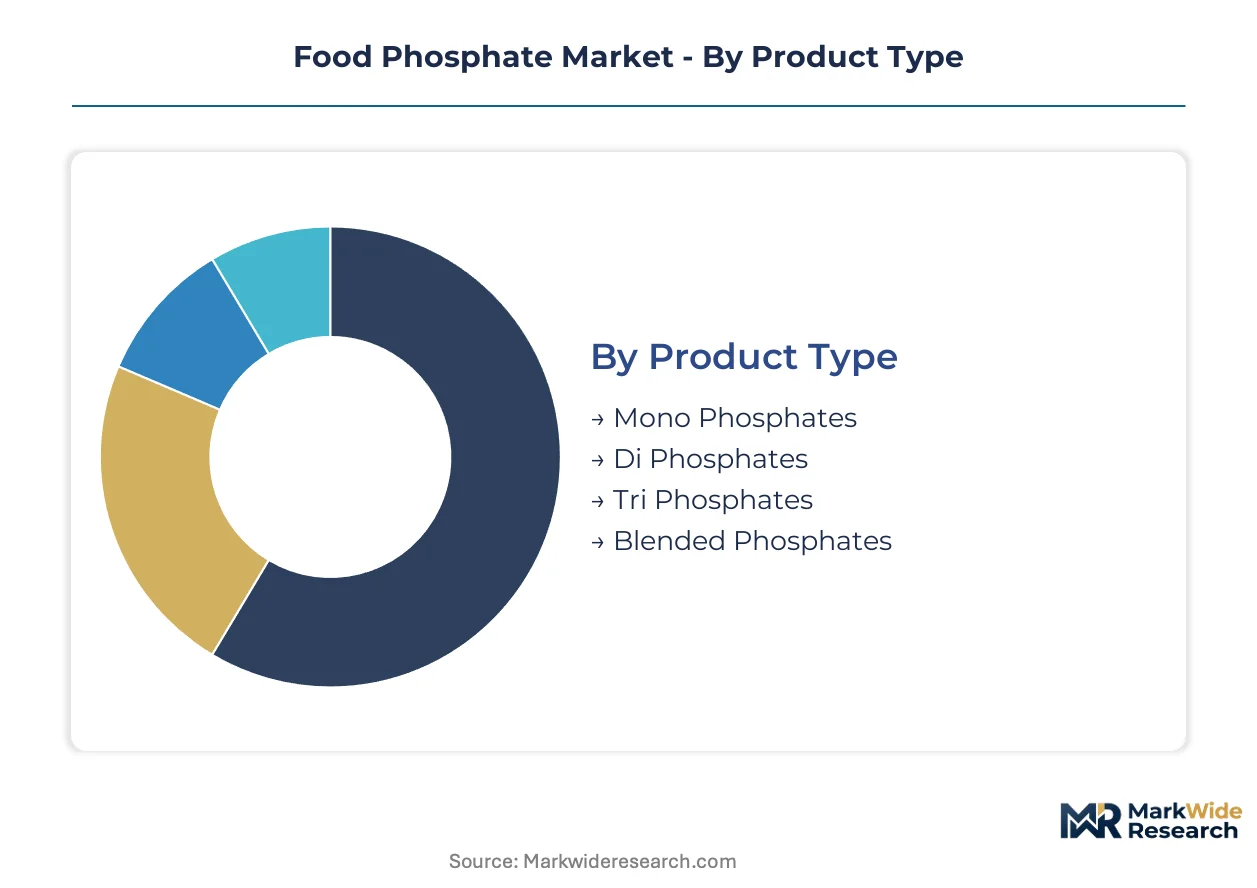
Food phosphate suppliers segment their portfolios across four dimensions to align technical specifications with processing requirements and regulatory constraints. Product type determines pH buffering capacity and ionic charge for protein interaction. End-use segmentation directs formulation science toward moisture retention, emulsification, or leavening functions.
Product Type:
Upgrade cycles in meat processing equipment are accelerating demand shifts between phosphate forms as injection and tumbling systems modernize.
- Mono Phosphates:These singly-neutralized salts exhibit acidic pH profiles and rapid solubility, making them indispensable in bakery leavening systems and acidified beverages. Vietnamese poultry processors specify mono phosphates for marinades requiring immediate ionic dispersion in high-speed injection lines.
- Blended Phosphates:Multifunctional formulations combine mono-, di-, and tri-phosphate forms to deliver sequential pH buffering and protein stabilization. Thai red meat processors favor blended systems that reduce label complexity while meeting EFSA cumulative exposure thresholds under reformulated recipes.
- Di Phosphates:Doubly-neutralized salts with alkaline characteristics serve premium meat segments demanding tight moisture retention specifications.
- Tri Phosphates:Fully neutralized forms provide maximum alkalinity for specific emulsification requirements in processed protein matrices.
Mono phosphates sit at the top of the volume ranking, with blended phosphates climbing the fastest as clean-label formulation pressures intensify.
End Use:
Application-driven procurement patterns concentrate contract value with suppliers maintaining segment-specific technical service capabilities.
- Meat Products:Processed poultry and red meat sectors absorb phosphate volumes for moisture retention, shelf-life extension, and yield improvement. Indonesian processors running modernized injection systems specify food-grade di phosphates for post-rigor applications in export-oriented facilities.
- Beverages:Acidified drinks and dairy alternatives employ mono phosphates for pH stabilization and mineral fortification. Chinese functional beverage manufacturers source technical-grade phosphates under SAMR GB standards for electrolyte replacement formulations.
- Bakery:Leavening acid applications face reformulation pressure from EFSA intake ceiling revisions across European markets.
- Dairy Products:Processed cheese and dairy-based desserts utilize phosphate emulsifying salts for texture modification and protein stability.
Meat products command the largest share of phosphate volume, though beverages are expanding most quickly as functional hydration categories proliferate.
Form:
Dosage precision requirements and dissolution kinetics determine form selection across processing environments.
- Powder:Fine particulate phosphates dominate high-volume meat processing for rapid dispersion in brine solutions. Brazilian beef processors specify powder forms for tumbling applications requiring uniform protein matrix penetration.
- Liquid:Pre-dissolved phosphate systems eliminate hydration steps in continuous processing lines. Mexican poultry facilities with automated injection equipment specify liquid concentrates to reduce batch-to-batch variability.
- Granular:Coarse particulate forms suit dry blending operations in bakery premix manufacturing.
- Tablets:Compressed forms serve niche laboratory and quality control applications requiring precise unit dosing.
Powder maintains volume leadership, while liquid formats are gaining share fastest among processors automating continuous production lines.
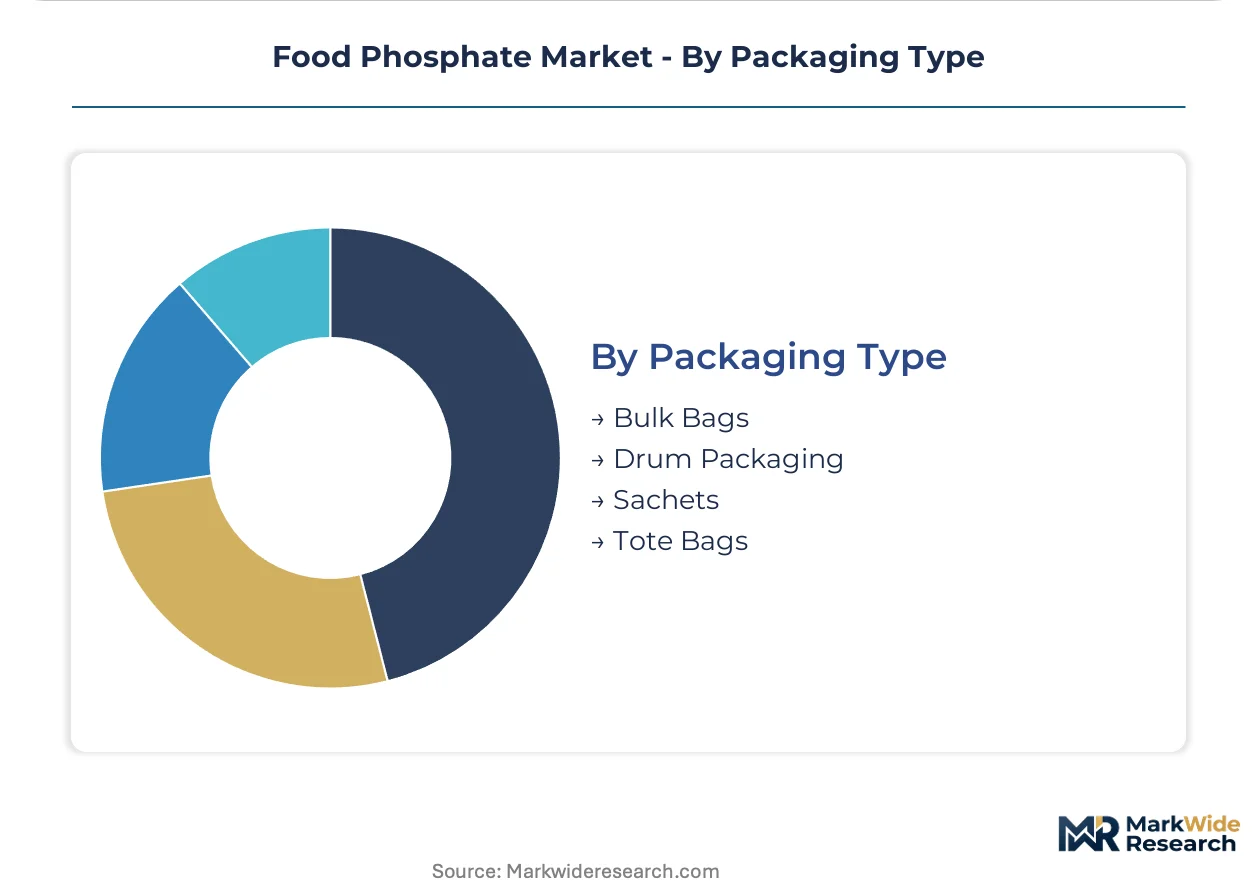
Packaging Type:
Supply chain configuration and handling infrastructure dictate packaging economics for phosphate distribution.
- Bulk Bags:Flexible intermediate bulk containers serve high-volume meat processors with pneumatic conveying systems. Argentine beef processors receiving phosphate shipments via Rosario port specify bulk bags for direct-to-silo transfer.
- Drum Packaging:Steel and fiber drums protect hygroscopic phosphate powders in humid climates. Indonesian processors in Surabaya specify drum packaging to counter tropical moisture exposure during storage.
- Sachets:Pre-weighed unit doses support small-scale bakery operations and foodservice distribution.
- Tote Bags:Intermediate rigid containers bridge bulk and drum formats for mid-scale processors.
Bulk bags lead volume rankings, with drum packaging expanding fastest in Southeast Asian markets lacking climate-controlled warehousing infrastructure.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory arbitrage is redirecting food phosphate production toward jurisdictions where compliance costs and certification timelines compress operational advantages. Producers in China and Southeast Asia leverage shorter SAMR licensing cycles and integrated phosphate rock access to capture share from European suppliers burdened by REACH documentation and EFSA exposure threshold revisions.
China
Domestic processed meat output expansion and functional beverage proliferation are absorbing technical-grade phosphate volumes at unprecedented rates. SAMR enforces GB standards for food-grade purity that determine both import eligibility and domestic production licensing, creating a protected market for local refiners. Yangtze River Delta clusters around Shanghai and Jiangsu province concentrate phosphate purification capacity serving pan-Asian export markets.
United States
Poultry processors in the Southeast and beef packers in the Midwest specify phosphate blends for moisture retention in export-grade products. FDA maintains Generally Recognized As Safe listings for specific phosphate salts while reviewing cumulative dietary exposure thresholds, compelling suppliers to document usage rates across customer portfolios. Chicago and Omaha serve as procurement hubs where technical service teams embed directly with meat processing R&D facilities.
Germany
EFSA intake ceiling revisions are forcing reformulation costs onto bakery manufacturers historically reliant on mono-phosphate leavening systems. ECHA REACH compliance requirements favor suppliers with pre-registered substance dossiers and documented exposure assessments. North Rhine-Westphalia chemical parks host specialized phosphate purification operations supplying pan-European meat processors with sodium and potassium derivatives.
Brazil
Beef and poultry export facilities in São Paulo and Paraná states specify phosphate systems meeting EU and Chinese import standards simultaneously. ANVISA regulates food additive purity thresholds that align with Mercosur technical barriers to trade agreements. Campinas and Londrina industrial corridors concentrate technical service partnerships where suppliers maintain regional protein application laboratories.
Vietnam
Poultry processing expansion around Ho Chi Minh City and Hanoi absorbs rising phosphate volumes for moisture retention in export-oriented facilities. The country's national food safety authority enforces additive purity standards that determine import eligibility for Chinese and Thai suppliers. Mekong Delta processing zones are modernizing injection and tumbling systems to optimize phosphate uptake efficiency in high-speed production lines.
Food Phosphate Market Vendor Landscape
Branded specialists and contract manufacturers split share differently across segments, with backward-integrated mining operations commanding premium positions in raw material-constrained environments. The vendor base concentrates around phosphate rock controllers and specialized purification houses, compressing margins for merchant traders lacking captive technical-grade capacity. Three archetypes dominate: integrated mining-to-derivatives conglomerates, regional purification specialists with SAMR or FDA dossier libraries, and technical service-forward partnerships embedding formulation chemists directly at meat processing R&D centers. Competitive moves center on capacity expansion in Yangtze River Delta and Mekong Delta corridors, plus strategic partnerships with Brazilian and Argentine beef processors requiring on-site application trials.
Among integrated mining conglomerates, Israel Chemicals Limited and OCP Group exemplify archetypes leveraging phosphate rock extraction to sustain cost advantages across multiple food-grade derivatives. Chemische Fabrik Budenheim KG represents the regional purification specialist model, anchoring European supply through specialized operations for sodium and potassium phosphates. These three occupy positions where regulatory dossier depth and captive raw material access determine contract viability in an environment where merchant supply strategies face compression.
| Leading Market Players |
|---|
| Israel Chemicals Limited |
| Chemische Fabrik Budenheim KG |
| Solvay SA |
| Fosfa Inc. |
| Prayon SA |
| The Mosaic Company |
| Innophos Holdings Inc. |
| Yara International |
| OCP Group |
| Others |
Supply Flow & Price Mechanics
EFSA's tightening additive exposure thresholds are compelling European meat processors to reformulate toward cleaner-label phosphate blends, forcing suppliers to absorb certification costs while maintaining technical-grade purity margins. This specification shift concentrates procurement power with backward-integrated producers who control captive phosphate rock extraction and food-grade purification capacity.
Pricing Analysis
Distributor margins in Southeast Asian markets compress as meat processors consolidate sourcing around integrated suppliers with direct technical service capabilities. Three-tier pricing structure across pharmaceutical-grade, food-grade, and technical-grade purity levels separates premium di-phosphate formulations for export-certified meat facilities from standard mono-phosphate offerings for domestic bakery applications. Cost compression in technical-grade segments is intensifying because Chinese producers are expanding SAMR-licensed capacity and displacing import volumes. Mid-scale Vietnamese poultry processors exhibit highest price sensitivity due to legacy equipment inefficiencies, while Brazilian beef exporters prioritize performance specifications over unit cost.
Supply Chain Analysis
Direct-to-processor channels handle hyperscale demand from integrated meatpacking facilities in Brazil, Thailand, and Vietnam, bypassing traditional distributor layers. Geographic supply concentration centers on Morocco, Jordan, and Saudi Arabia for phosphate rock extraction, with downstream purification clustering in China's Yangtze River Delta and Germany's North Rhine-Westphalia chemical parks. Raw material dependencies draw from sulfuric acid for wet-process phosphoric acid production, sodium carbonate for neutralization reactions, and potassium hydroxide for specialty salt derivatives. Single-source vulnerability runs through Moroccan phosphate rock dominance, where OCP Group controls roughly one-third of global reserves. Distribution runs through bulk bag and drum formats for high-volume meat processors, with liquid concentrate systems gaining share in automated injection lines.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The food phosphate market functions as a stable compounder anchored by irreversible processed protein expansion across emerging economies, where cold chain infrastructure buildout sustains additive demand irrespective of cyclical commodity swings.
For Market Incumbents: Deepen technical service embedding at Brazilian and Argentine beef processing R&D centers to defend against emerging plant-based hydrocolloid substitutes capturing premium shelf space. Prioritize capacity addition in Mekong Delta corridors where Vietnamese poultry modernization is accelerating phosphate uptake efficiency. Invest in SAMR GB standard certification libraries to maintain import eligibility as Chinese domestic producers expand food-grade purification capacity. For New Entrants and Emerging Players: E-commerce technical ingredient platforms offer low-friction entry routes to small-scale Indonesian bakery manufacturers lacking direct supplier relationships. Target India's Maharashtra and Gujarat cold chain expansion zones where organized retail penetration is creating first-mover advantages for phosphate suppliers establishing formulation partnerships. Pursue white-label blended phosphate manufacturing for regional meat processors seeking reduced label complexity under EFSA cumulative exposure thresholds. For Investors and Strategic Acquirers: Asymmetric upside sits with regional purification specialists possessing SAMR or FDA dossier libraries and established technical service laboratories in protein processing corridors. Five-to-ten-year viability rests on captive phosphate rock access or exclusive offtake arrangements with Moroccan or Jordanian mining operations. Monitor EFSA total diet study recalibrations as inflection indicators for reformulation-driven demand shifts between mono-phosphate and blended phosphate categories.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Phosphate Rock Mining | Captive ore access insulates margin compression from Moroccan supply concentration. |
| SAMR GB Standard Certification Investment | Chinese regulatory licensing determines import eligibility and domestic production rights. |
| Technical Service Laboratory Expansion | On-site formulation support embeds suppliers at Brazilian beef processor R&D facilities. |
| Encapsulated Phosphate System Development | Time-release coatings modularize moisture retention for single-dose meat processing protocols. |
| Clean-Label Blended Phosphate Formulation | Multifunctional additive systems reduce label complexity under EFSA exposure thresholds. |
Methodological Framework
Bottom-up meat processing and bakery application modeling reconciled against top-down phosphate rock extraction and purification capacity tracking forms the analytical core of this study. Primary interviews with meat processing R&D directors, phosphate plant managers, SAMR regulatory consultants, and Southeast Asian distribution channel partners combined with secondary validation from customs trade databases, EFSA additive exposure assessments, FDA GRAS filings, and Chinese GB standard documentation. Triangulation across stakeholder inputs and published regulatory determinations ensures segmentation integrity across mono-phosphate, di-phosphate, tri-phosphate, and blended product categories.
Input-output matrices map phosphate rock mining volumes through sulfuric acid conversion, phosphoric acid purification, and salt neutralization stages to end-use consumption in poultry, red meat, bakery, and beverage applications across the analysis window. Segmentation dimensions include product type by neutralization degree, end-use industry by protein matrix requirements, form by dissolution kinetics, and packaging by supply chain infrastructure. CAGRs derive from installed meat processing capacity expansion, EFSA reformulation timelines, and SAMR licensing velocity. Forecast inputs incorporate injection and tumbling equipment upgrade cycles, cold chain penetration rates, and cumulative dietary exposure threshold revisions.
The model assumes a particular technology adoption path; alternative pathways for encapsulated phosphate delivery systems or fermented protein stabilizers would alter the outlook. Forecasts reflect base-case assumptions regarding EFSA enforcement consistency, SAMR licensing timeline stability, and Moroccan phosphate rock export continuity. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Additives and Ingredients
France Food Enzymes Market
Food Additives and Ingredients
Food Grade Ammonium Bicarbonate Market
Food Additives and Ingredients
Italy Food Acidulants Market
Food Additives and Ingredients
Egg Wash Substitute Market
Food Additives and Ingredients
Africa Food Enzymes Market
Food Additives and Ingredients
Food Clarifiers Market
Food Additives and Ingredients
Beverage Encapsulants Market
Food Additives and Ingredients
Mexico Food Emulsifiers Market
Food Additives and Ingredients
Fish Tank Water Additives Market
Food Additives and Ingredients
China Emulsifiers Market
Food Additives and Ingredients
South Africa Food Colorants Market
Food Additives and Ingredients
Sri Lanka Starch and Starch Derivative Market
Food Additives and Ingredients
Italy Food Emulsifier Market
Food Additives and Ingredients
Fruit Ripening Agents Market
Food Additives and Ingredients
Dairy Enzymes Market
Food Additives and Ingredients
Mexico Food Enzymes Market