
 Africa Food Acidulants Market | 2026-2036
Africa Food Acidulants Market Size, Share, and Industry Trends Forecast 2026-2036
Africa Food Acidulants Market Outlook
Market Context
Modular acidulant blending kits—pre-measured citric-lactic combinations for small-batch beverage production—is realigning purchasing patterns among mid-sized African processors. Cargill Inc leverages its regional distribution hubs to supply standardized acidulant grades across multiple African markets. Jungbunzlauer AG anchors its position through specialized citric acid formulations tailored to tropical climate stability requirements. Isegen South Africa Pty Ltd dominates local blending operations with backward integration into fermentation-derived acid production.
Technical Definition and Segment Structure
Africa food acidulants comprise organic and inorganic compounds—primarily citric, lactic, acetic, and phosphoric acids—used to regulate pH, enhance flavor profiles, and extend shelf stability in processed foods, typically dosed between 0.1% and 2.0% by weight depending on application. These substances function as preservatives, leavening reactants, and taste modulators across thermal and ambient processing environments. Citric acid occupies the largest volume share given its versatility across beverage and dairy applications, while phosphoric acid concentrates margin pools in cola-type carbonated drinks where specialized grades command technical premiums. Powder and granular forms are gaining traction in inland markets where cold-chain logistics for liquid alternatives remain underdeveloped.
Regulatory Framework and Outlook
South Africa's Department of Health enforces additive maximum limits under foodstuffs regulations, while Nigeria's National Agency for Food and Drug Administration and Control (NAFDAC) mandates pre-market safety assessments for imported acidulant consignments. Kenya's Bureau of Standards (KEBS) applies East African Community harmonized codes for acidulant labeling and purity thresholds. Stakeholders must monitor evolving national standards and certification reciprocity agreements to secure uninterrupted market access across Africa's fragmented regulatory landscape.
Market Dynamics
Beverage manufacturers in Nigeria's Lagos-Ibadan corridor are scaling acidulant volumes aggressively, pulling procurement patterns toward bulk citric acid contracts and away from spot-market purchasing.
Growth Catalysts
- Carbonated beverage expansion:Soft drink bottling clusters across East and West Africa are locking in multi-year acidulant supply agreements to secure volume for fruit-based formulations.
- NAFDAC pre-market assessments:Nigeria's safety clearance mandates for imported acidulant consignments are professionalizing supplier qualification, filtering out informal traders.
- Powder format preference:Inland markets lacking cold-chain infrastructure are driving granular citric acid adoption over liquid alternatives.
Market Restraints
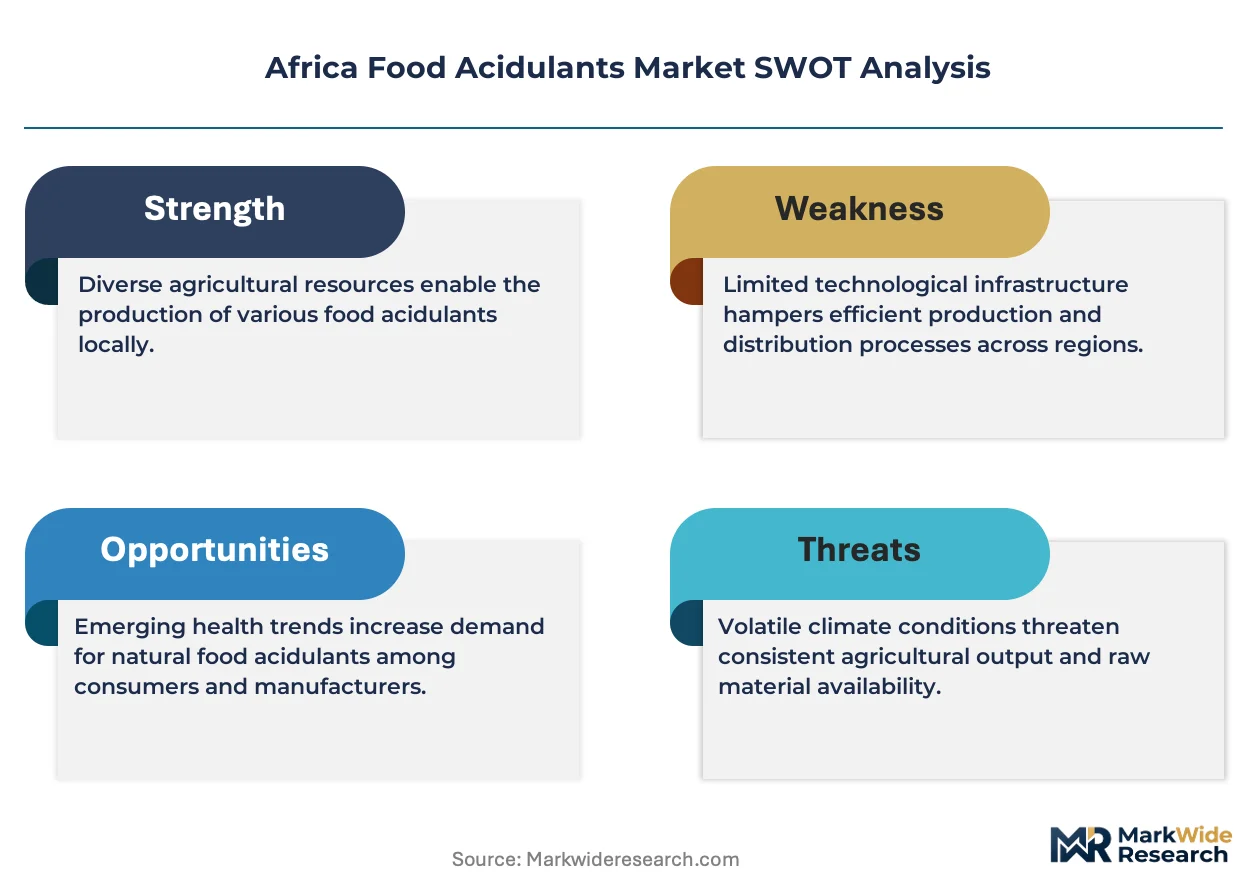
- Fermentation input volatility:Molasses and corn starch price swings directly compress margins for citric acid producers dependent on carbohydrate feedstocks.
- Import concentration risk:Overreliance on Asian fermentation-derived acid supplies exposes African processors to shipping cost spikes and currency mismatch.
- Phosphoric acid substitution ceiling:Cola-type carbonated drinks maintain locked-in phosphoric acid specifications, blocking citric acid penetration in this high-margin segment.
Strategic Opportunities
- Kenya dairy acidification:Underpenetrated yogurt and cheese processing in East Africa offers white space for lactic acid formulations tailored to ambient distribution.
- KEBS harmonized labeling:East African Community standardization creates regulatory tailwind for acidulant suppliers qualifying once for multiple national markets.
- Modular blending kit channels:Direct-to-processor distribution bypassing traditional chemical distributors is opening mid-sized processor access.
Industry Challenges
- Fermentation technologist scarcity:Local production of organic acids requires specialized biochemical engineering talent that African universities graduate insufficiently.
- Multi-jurisdiction certification timelines:Separate NAFDAC, KEBS, and South African Department of Health approvals extend product launch cycles by 18-24 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Africa Food Acidulants Market |
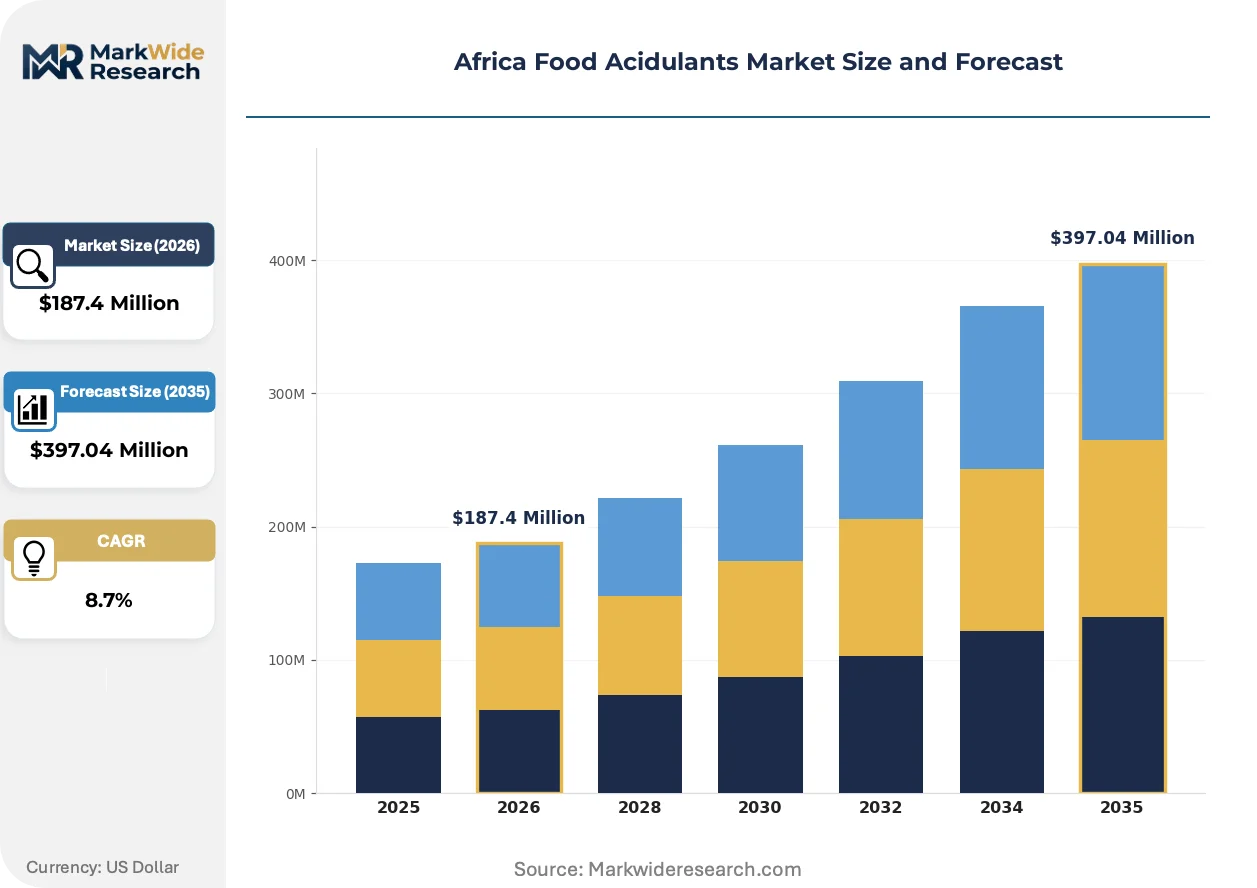
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $397.04 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Citric Acid, Lactic Acid, Acetic Acid, Phosphoric Acid Application: Beverages, Dairy Products, Condiments, Bakery End User: Food Producers, Beverage Manufacturers, Ingredient Suppliers, Retailers Form: Liquid, Powder, Granular, Crystalline |
| Companies Covered | Tate & Lyle, Jungbunzlauer AG, Cargill Inc, Isegen South Africa Pty Ltd, Hawkins Watts Limited, Brenntag, Archer Daniels Midland Company, Megachem Limited, Corboin, Others |
| Regions Covered | Africa: South Africa, Nigeria, Egypt, Kenya, Morocco, Ethiopia, Ghana, Algeria, Rest of Africa |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Africa Food Acidulants Market Strategic Shifts
Acidulant procurement and formulation technology are converging around climate-stability requirements and modular supply models that reduce working capital burdens for processors.
Encapsulated citric acid with tropical climate coatings is integrating into beverage formulations to prevent caking and degradation during ambient storage. Mid-sized Nigerian and Ghanaian processors are adopting this technology fastest, moving away from unprotected bulk acid. The shift is integrating moisture-resistant acidulant grades into standard procurement specifications, compressing demand for conventional uncoated powders.
South Africa's Department of Health updated food additive labeling rules are tightening maximum limit disclosures and origin documentation for imported acidulant blends. Industrial consequence includes mandatory reformulation of multi-acid blends to meet stricter purity thresholds. Cola-type carbonated drink manufacturers importing phosphoric acid are responding by pre-qualifying suppliers against revised analytical certificate requirements.
Buyer concentration among Lagos-Ibadan bottling clusters is compressing supplier negotiation leverage and lengthening payment terms to 90-120 days. Traditional chemical distributors are losing share to direct mill relationships and regional hub contracts. This pattern is most visible in Nigeria's soft drink sector, where Cargill's regional distribution hubs have displaced multiple layers of import intermediaries.
Africa Food Acidulants Market Segmentation
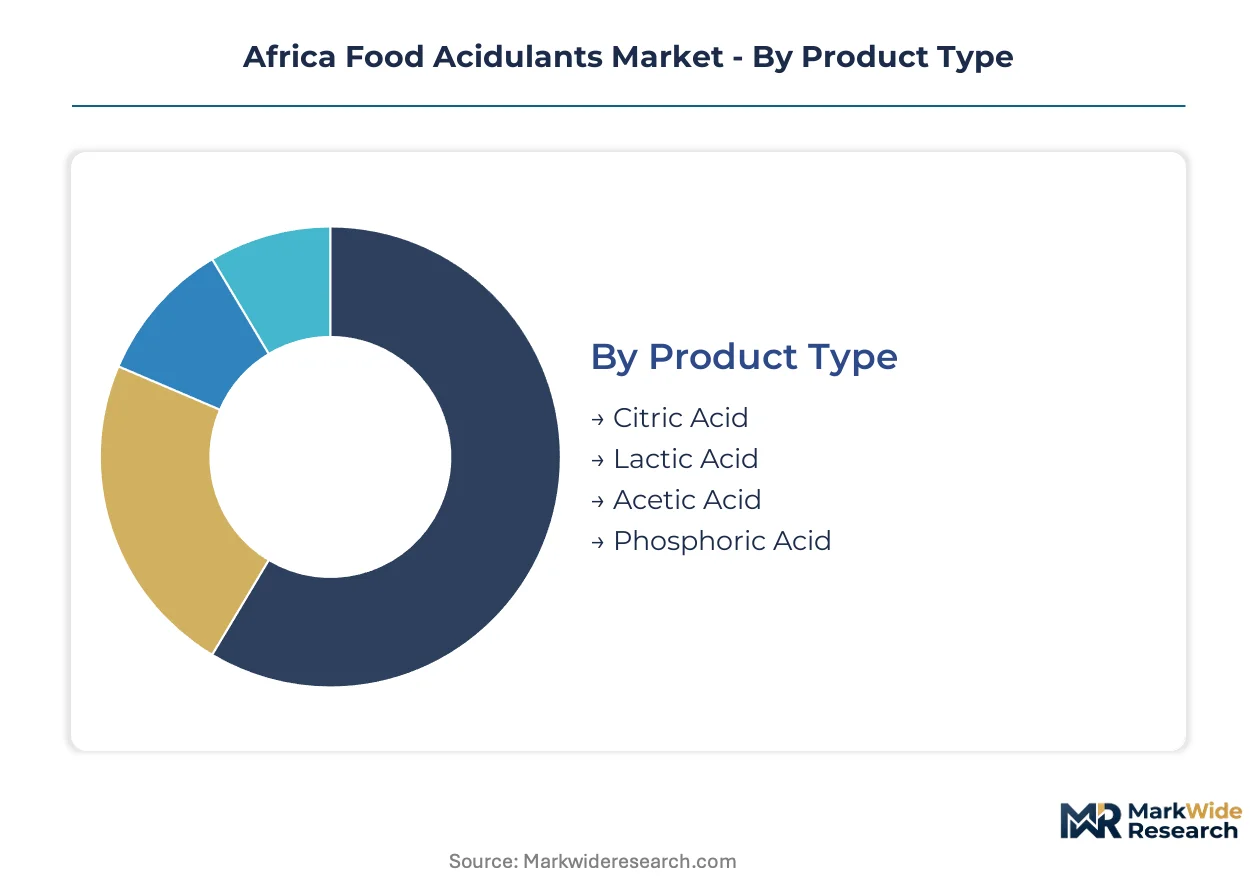
Acidulant purchasing patterns across Africa diverge sharply between multinational bottlers demanding pharmaceutical-grade consistency and informal processors tolerating wider specification bands. Segmentation clarity enables suppliers to match formulation services, logistics modes, and certification tiers to actual buyer capabilities rather than defaulting to export-grade specifications.
Product Type:
Standardization dominates commodity acids while specialty grades command formulation partnerships and technical service premiums.
- Citric Acid:Fermentation-derived tricarboxylic acid functioning as the workhorse pH regulator across beverage and dairy matrices. Demand concentrates in Nigeria's Lagos-Ibadan bottling corridor where soft drink manufacturers are locking in multi-year supply contracts to secure volume for fruit-based formulations.
- Phosphoric Acid:Inorganic acid specified exclusively for cola-type carbonated drinks where sharp, dry taste profiles are non-negotiable. South Africa's Department of Health updated labeling rules are tightening purity thresholds for imported phosphoric acid, forcing pre-qualification of suppliers against revised analytical certificate requirements.
- Lactic Acid:Fermentation-produced hydroxy acid preserving yogurt and cheese in ambient distribution chains. Kenya's underpenetrated dairy processing sector drives uptake.
- Acetic Acid:Vinegar-derived acidulant for condiment and pickling applications. West African sauce manufacturers represent primary demand nodes.
Most installed capacity flows through Citric Acid. Expansion is steepest in Lactic Acid as East African dairy processors professionalize.
Application:
Volume scale and margin capture separate mass-market beverage dosing from precision-dependent dairy acidification.
- Beverages:Carbonated soft drinks, fruit juices, and nectars consuming acidulants for pH stabilization, microbial inhibition, and taste modulation. East and West African bottling clusters are scaling acidulant volumes aggressively, pulling procurement toward bulk contracts and away from spot-market purchasing.
- Dairy Products:Yogurt, cheese, and fermented milk applications requiring precise acidification kinetics for texture development. Kenya's Bureau of Standards applies East African Community harmonized codes that ease multi-country qualification for acidulant suppliers targeting this segment.
- Condiments:Sauces, dressings, and pickled vegetables relying on acetic and citric acid blends for preservation and flavor balance. Nigeria's National Agency for Food and Drug Administration and Control mandates pre-market safety assessments that filter informal suppliers from this category.
- Bakery:Leavening acidulants reacting with carbonates to control rise and crumb structure. South African commercial bakeries anchor regional demand.
Beverages concentrate procurement volumes. Dairy Products are climbing the fastest as ambient distribution infrastructure spreads.
End User:
Direct mill relationships are displacing distributor layers as buyer scale and technical sophistication increase.
- Food Producers:Processed food manufacturers integrating acidulants into sauces, dressings, and preserved products. Mid-sized Nigerian and Ghanaian processors are adopting encapsulated citric acid with tropical climate coatings fastest, moving procurement specifications toward moisture-resistant grades.
- Beverage Manufacturers:Soft drink bottlers and juice processors commanding the largest acidulant offtake volumes. Buyer concentration among Lagos-Ibadan clusters is compressing supplier negotiation leverage and lengthening payment terms to 90-120 days.
- Ingredient Suppliers:Blending houses and compounders formulating multi-acid premixes for downstream processors. Isegen South Africa Pty Ltd dominates this tier through backward integration into fermentation-derived acid production.
- Retailers:Private-label and own-brand food operations sourcing acidulants through ingredient suppliers rather than direct import.
Most technical service investment targets Beverage Manufacturers. Ingredient Suppliers are gaining share fastest as modular blending kit channels open mid-sized processor access.
Form:
Logistics infrastructure availability determines format preference between coastal liquid terminals and inland powder handling.
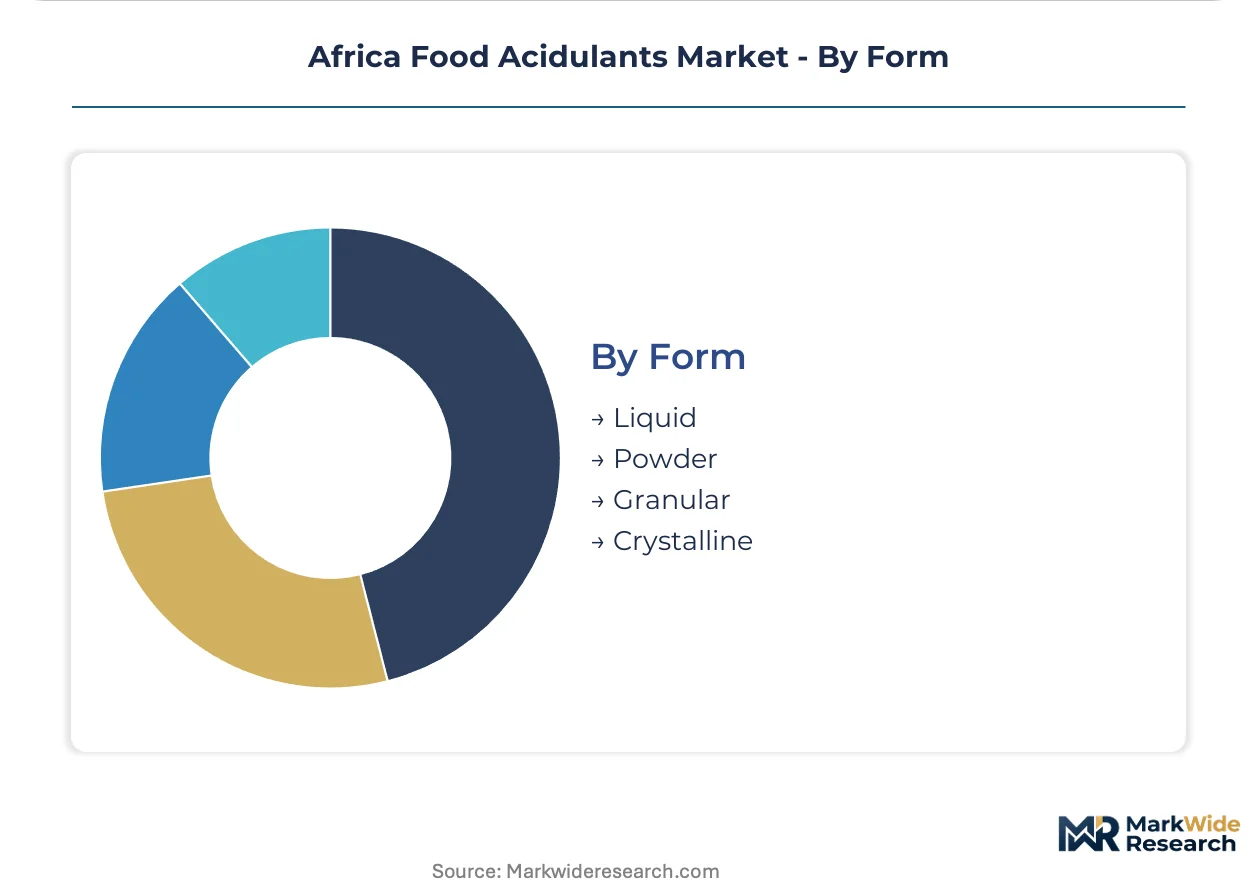
- Powder:Anhydrous citric acid and blended acidulants in free-flowing particulate form. Inland markets lacking cold-chain infrastructure are driving granular citric acid adoption over liquid alternatives.
- Liquid:Aqueous solutions and concentrated acid slurries suited to high-volume continuous dosing. Coastal bottling plants with tank farm access prefer this format for operational efficiency.
- Granular:Sized particulate acidulants with controlled dissolution rates for dry-mix applications. Encapsulated variants with tropical climate coatings are integrating fastest into beverage formulations to prevent caking during ambient storage.
- Crystalline:High-purity acid crystals for pharmaceutical-adjacent food applications and precise laboratory-scale formulation.
Most warehouse stock rotates through Powder. Granular is expanding most quickly as moisture-resistant coating technology diffuses.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Food acidulant manufacturing first scaled in European fermentation facilities during the early twentieth century, with citric acid production pioneering industrial biotechnology. African demand emerged later through colonial trade routes, accelerating after independence as local beverage bottling took root.
Nigeria
Lagos-Ibadan bottling clusters drive acidulant offtake for carbonated drinks and fruit nectars. NAFDAC mandates pre-market safety assessments for all imported acidulant consignments, filtering informal suppliers from formal procurement channels. Kano and Onitsha processors are adopting encapsulated citric acid with tropical climate coatings to prevent ambient storage degradation.
South Africa
The Department of Health enforces updated food additive labeling rules that tighten maximum limit disclosures and origin documentation requirements. Johannesburg blending houses and Cape Town beverage plants anchor regional acidulant consumption. Port Elizabeth chemical distributors are losing share to direct mill relationships as buyer concentration increases.
Kenya
Underpenetrated yogurt and cheese processing creates white space for lactic acid formulations suited to ambient distribution chains. KEBS applies East African Community harmonized codes that ease multi-country qualification for acidulant suppliers. Nairobi dairy processors and Mombasa coastal bottling plants represent primary demand nodes.
Ghana
Mid-sized processors are migrating procurement specifications toward moisture-resistant granular acidulants over conventional uncoated powders. The national food and drugs regulator maintains safety clearance protocols for imported consignments. Accra-Tema manufacturing corridor beverage producers are scaling acidulant volumes through modular blending kit channels.
Egypt
Condiment and sauce manufacturers represent steady acetic acid demand for pickling and preservation applications. The national standards body applies purity thresholds for food-grade acidulant imports. Alexandria and Cairo processing clusters are professionalizing supplier qualification as informal trading loses regulatory tolerance.
Africa Food Acidulants Market Competitive Environment
The competitive structure tilts toward multinational chemical distributors with regional hub infrastructure. Three player tiers operate: fermentation-integrated specialists controlling backward supply chains, diversified agricultural processors leveraging commodity sourcing scale, and regional blending houses serving formulation-sensitive mid-market accounts. Dominant competitive moves include direct-to-processor distribution bypassing traditional chemical intermediaries, and pre-qualification against tightening analytical certificate requirements.
Within the fermentation-specialist tier, Jungbunzlauer AG and Isegen South Africa Pty Ltd exemplify divergent geographic anchoring strategies. Cargill Inc occupies a position representing diversified agricultural processors with regional distribution hub infrastructure. These three companies illustrate how competitive positioning separates European-heritage fermentation technology from Africa-based backward integration into carbohydrate feedstock processing.
| Leading Market Players |
|---|
| Tate & Lyle |
| Jungbunzlauer AG |
| Cargill Inc |
| Isegen South Africa Pty Ltd |
| Hawkins Watts Limited |
| Brenntag |
| Archer Daniels Midland Company |
| Megachem Limited |
| Corboin |
| Others |
Value Chain & Pricing Dynamics
Pharmaceutical-grade citric acid commands a 40-60% premium over technical-grade alternatives, a divergence that manifests in both procurement contract structures and the geographic reach of supplier qualification programs. NAFDAC's pre-market safety assessments filter informal traders from premium-tier supply channels, while bulk spot-market purchases concentrate among inland processors tolerating wider specification bands. Payment terms stretch to 90-120 days for Lagos-Ibadan bottling clusters, compressing working capital for distributors locked out of direct mill relationships.
Pricing Analysis
Three-tier pricing structure across pharmaceutical-grade, food-grade, and technical-grade levels dominates African acidulant procurement, with certification tier and volume scale as primary differentiation drivers. Cost compression in technical-grade citric acid is intensifying because molasses and corn starch feedstock volatility transmits directly from Asian fermentation facilities. Mid-sized Nigerian processors exhibit highest price sensitivity, while South African pharmaceutical-adjacent buyers prioritize analytical certificate compliance over unit cost.
Supply Chain Analysis
Domestic-content mandates are absent across African acidulant markets, leaving sourcing decisions shaped entirely by import logistics and supplier qualification burdens rather than local production requirements. Supply concentrates in Chinese, Thai, and Indian fermentation facilities, with carbohydrate feedstocks drawing from regional corn starch and molasses surpluses. Single-source vulnerability runs through Lagos-Apapa port congestion, where clearing delays cascade to inland bottling plants. Distribution runs through Cargill's regional hub infrastructure and direct mill contracts displacing traditional chemical distributors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in African food acidulants rests on encapsulated citric acid formulations capturing premium-tier pricing from mid-sized processors upgrading ambient storage specifications.
For Market Incumbents: Acquire fermentation-integrated production assets to secure captive molasses supply and insulate margin from Asian feedstock volatility. Defend against Jungbunzlauer's climate-stability formulation patents by accelerating R&D investment in tropical-coating technology. Lock in multi-year offtake agreements with Lagos-Ibadan bottling clusters before payment terms deteriorate further. For New Entrants and Emerging Players: Begin with Kenya's underpenetrated dairy acidification segment, where lactic acid demand outpaces qualified supplier presence. Target Mombasa-Nairobi corridor yogurt processors lacking technical service support from incumbent distributors. Lead with modular blending kit channels that bypass traditional chemical intermediary layers and compress customer acquisition cost. For Investors and Strategic Acquirers: Consolidation pressure builds where fermentation technologist scarcity constrains local organic acid production capacity expansion. Long-term viability favors backward-integrated specialists controlling carbohydrate feedstock sourcing rather than pure-play distributors. Watch NAFDAC approval timeline compression as inflection signal—accelerated clearance protocols would validate premium-tier supplier qualification investments.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Fermentation Feedstocks | Captive molasses supply insulates margin from Asian corn starch price volatility. |
| Encapsulated Acidulant Product Launch | Tropical climate coatings command premium pricing from Nigerian mid-sized processors. |
| Direct-to-Processor Distribution Channel | Bypassing Lagos chemical distributors captures margin lost to 90-120 day payment terms. |
| KEBS Harmonized Certification Investment | Single qualification unlocks Kenya, Tanzania, Uganda dairy acidification markets. |
| Long-term Supply Agreement with Bottling Clusters | Volume commitments secure offtake before buyer concentration erodes supplier leverage. |
Study Parameters
Direct dialogue with beverage formulation chemists, dairy processing plant managers, NAFDAC regulatory affairs officers, and Lagos-based chemical distributors grounded demand-side assumptions in operational reality. Secondary validation drew from KEBS harmonized standard publications, NAFDAC pre-market assessment guidelines, South African Department of Health labeling rule updates, and customs import records for citric acid consignments. Bottom-up processor interviews triangulated against top-down fermentation capacity estimates from Asian supplier disclosures.
Bottom-up modeling built volume projections from individual bottling cluster expansion plans and dairy processor acidification intensity benchmarks, cross-checked against top-down African beverage production growth trajectories. Segmentation dimensions spanned acid type, application matrix, end-user scale tier, and coastal versus inland logistics configuration. CAGRs derived from weighted average of processor procurement intention surveys and historical import volume trends, with currency mismatch risk and feedstock cost pass-through as industry-specific sensitivity inputs.
Caveats apply where NAFDAC approval timeline shifts, Lagos port congestion spikes, or Asian fermentation capacity rationalization could materially shift the outlook. Forecasts embed assumptions regarding continued EAC regulatory harmonization and stable carbohydrate feedstock pricing from Thai and Indian suppliers. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Additives and Ingredients
South Africa Food Colorants Market
Food Additives and Ingredients
Non-GMO Citric Acid Market
Food Additives and Ingredients
Edible and Soluble Films Market
Food Additives and Ingredients
Acetylated Monoglycerides (AMG) Market
Food Additives and Ingredients
Canada Food Emulsifiers Market
Food Additives and Ingredients
Australia Anti Caking Market
Food Additives and Ingredients
Food Bleaching Agents Market
Food Additives and Ingredients
Distilled Monoglycerides Market
Food Additives and Ingredients
Protein Films Market
Food Additives and Ingredients
Fruit Ripening Agents Market
Food Additives and Ingredients
United Kingdom Food Emulsifier Market
Food Additives and Ingredients
Monoglyceride Market
Food Additives and Ingredients
Gardenia Food Color Market
Food Additives and Ingredients
Asia Pacific Food Acidulants Market
Food Additives and Ingredients
Food Grade Glycerin Market
Food Additives and Ingredients
Food Protein Ingredient Market