
 Citrus Fruit Coatings Market | 2026-2036
Citrus Fruit Coatings Market Size, Share, and Industry Trends Forecast 2026-2036
Citrus Fruit Coatings Market Analysis
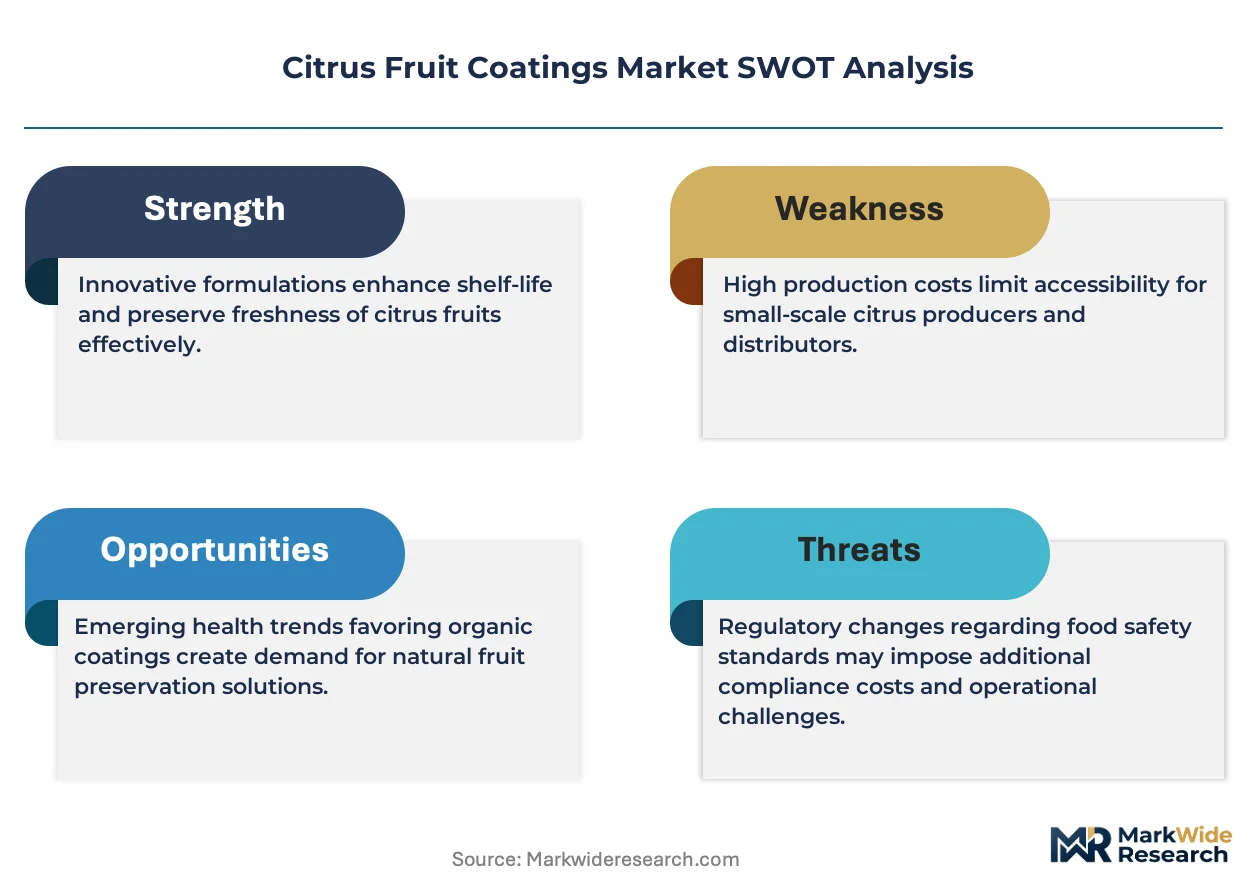
REACH compliance is repositioning the cost-of-entry calculus for European coating suppliers, forcing reformulation investments that favor established technical players. Fomesa Fruitech leverages its Spanish manufacturing base to dominate Mediterranean supply corridors. Pace International anchors North American packer relationships through localized technical service networks. AgroFresh differentiates with integrated post-harvest platforms spanning coatings, ethylene management, and storage diagnostics.
Citrus fruit coatings comprise emulsion-based or solvent-deposited barrier layers—typically incorporating carnauba, shellac, or polyethylene-derived polymers at 0.5–2.0% weight-to-fruit ratios—to retard moisture loss, reduce gas exchange, and inhibit microbial colonization during cold-chain distribution. Synthetic wax formulations occupy the largest volume share due to cost efficiency and application consistency on high-speed pack lines, though edible coating segments are gaining structural attention as clean-label procurement standards tighten across European and North American retail channels. Shellac-based coatings retain premium positioning in export citrus bound for distant Asian markets where extended transit times demand superior gloss retention and barrier performance.
EPA registration requirements govern active and inert ingredients in coatings applied to US citrus, while EFSA evaluates food-contact safety and migration limits for European-bound fruit; India's FSSAI and BIS standards increasingly shape formulation acceptability for export-oriented Indian packers. These layered regulatory frameworks compel manufacturers to maintain multi-jurisdiction dossiers, raising fixed compliance costs that favor scaled suppliers over regional formulators. Stakeholders must monitor evolving residue tolerance harmonization between CODEX-aligned and national-standard regimes to anticipate reformulation cycles and sourcing geography shifts.
Market Dynamics
REACH compliance is forcing European coating suppliers into costly reformulation cycles, compressing margins for regional formulators while rewarding scaled technical players with established multi-jurisdiction dossiers. This regulatory pressure is reshaping competitive positioning across Mediterranean and North American supply corridors.
Growth Catalysts
- EU Farm to Fork Strategy:Mandates biodegradable chemistries, accelerating demand for carnauba and shellac-based formulations in export-oriented Spanish and Italian packhouses.
- Extended transit corridors:Asian-bound citrus from South Africa and California requires superior moisture barriers, driving specification upgrades to high-gloss shellac coatings.
- High-speed pack line automation:Synthetic wax emulsions integrate seamlessly with automated fruit handling systems, reducing application variability in large-scale California operations.
Market Restraints
- Carnauba supply concentration:Brazilian harvest volatility constrains natural wax availability, creating input cost instability for premium coating formulations.
- Multi-jurisdiction compliance costs:EPA registration, EFSA migration limits, and India's FSSAI standards force parallel dossier maintenance that disadvantages smaller formulators.
- Polyethylene regulatory pressure:Synthetic polymer coatings face scrutiny under EU single-use plastics directives, threatening volume-share positions in European-bound fruit.
Strategic Opportunities
- Clean-label retail procurement:Edible coating segments gain structural attention as European and North American supermarkets tighten additive disclosure requirements.
- Integrated post-harvest platforms:Convergence of coatings with ethylene management and storage diagnostics creates bundled service models for large packer accounts.
- Indian export expansion:FSSAI and BIS standard harmonization enables formulation acceptance for export-oriented domestic packers serving Middle Eastern corridors.
Industry Challenges
- Reformulation timeline compression:REACH substance evaluation cycles force accelerated R&D cadences that strain technical staffing in mid-tier suppliers.
- Cold-chain integration complexity:Coating performance validation across variable temperature regimes requires extended field trials that delay commercialization.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Citrus Fruit Coatings Market |
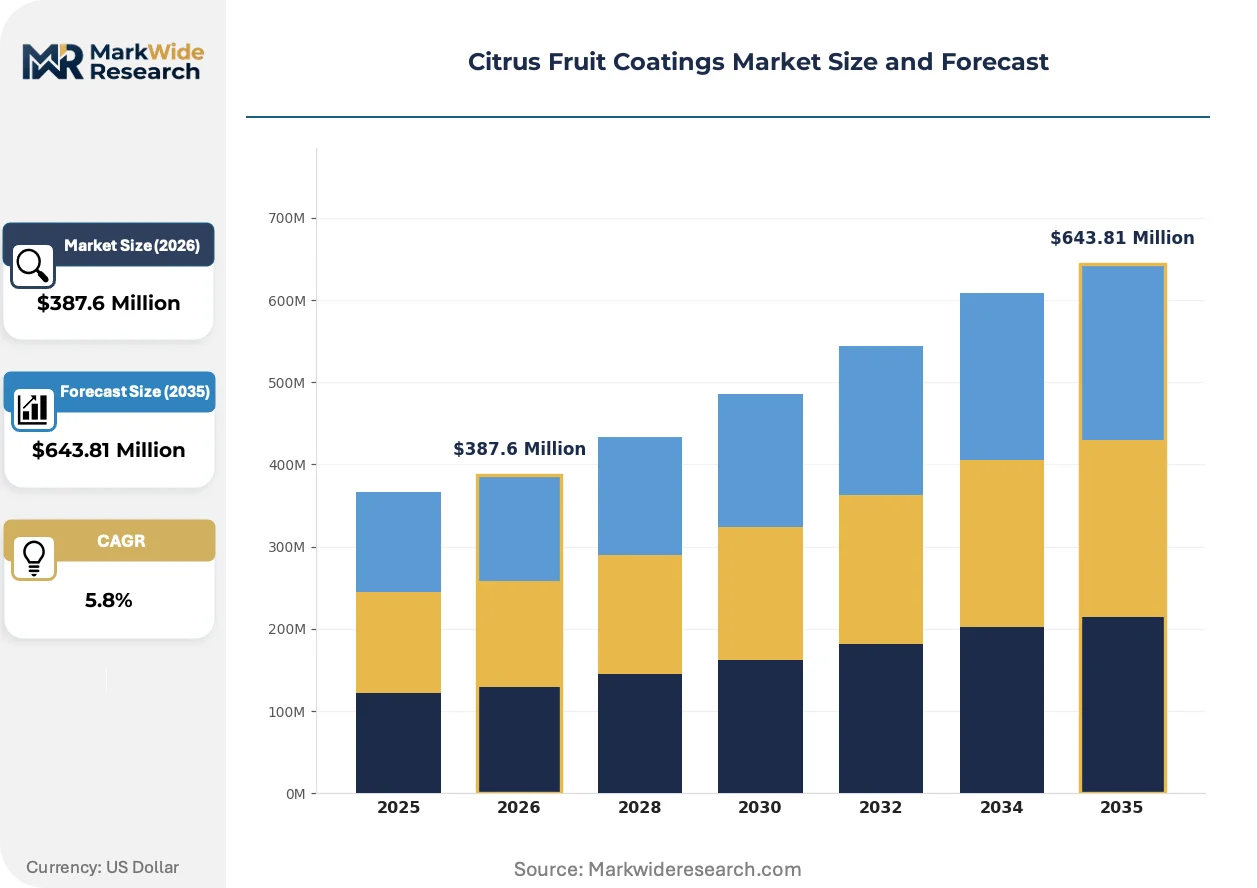
| Market Size in 2026 | $387.6 Million |
| Market Size in 2035 | $643.81 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Coating Type: Natural Wax, Synthetic Wax, Shellac, Edible Coating Application: Fresh Citrus, Processed Citrus, Citrus Juice, Export Citrus Distribution Channel: Online Retail, Offline Retail, Foodservice, Direct Sales End User: Packers, Distributors, Retailers, Food Manufacturers |
| Companies Covered | Fomesa Fruitech, Pace International, AgroFresh, Nipro Fresh, Productos Citrosol, John Bean Technologies, Valent BioSciences Corporation, Citrashine, Xeda International, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Citrus Fruit Coatings Market Emerging Trajectories
Active reformulation is reshaping competitive positioning as suppliers race to meet biodegradable mandates while preserving barrier performance. Three distinct movements are compressing development cycles and redrawing procurement criteria.
Edible biopolymer coatings derived from chitosan and alginate are integrating antimicrobial and moisture-retention functions into single-layer applications. Premium European retailers are specifying these formulations for organic citrus lines. The technology is integrating clean-label compliance with extended shelf-life performance, compressing the traditional trade-off between natural positioning and functional efficacy.
REACH substance authorization is restricting polyethylene-derived polymers in food-contact applications, forcing European suppliers toward carnauba-shellac blends. EFSA migration limit evaluations now govern formulation acceptability for fruit bound for German and French supermarkets. Mediterranean packhouses are responding by qualifying alternative wax chemistries ahead of sunset dates for restricted substances.
Supermarket technical buyers are consolidating coating procurement under integrated post-harvest service contracts that bundle application equipment, chemical supply, and quality monitoring. Large Spanish and California packers are displacing transactional chemical purchasing with multi-year performance agreements. This pattern is most visible in mandarin export corridors where shelf-life guarantees determine contract renewal.
Citrus Fruit Coatings Market Segmentation
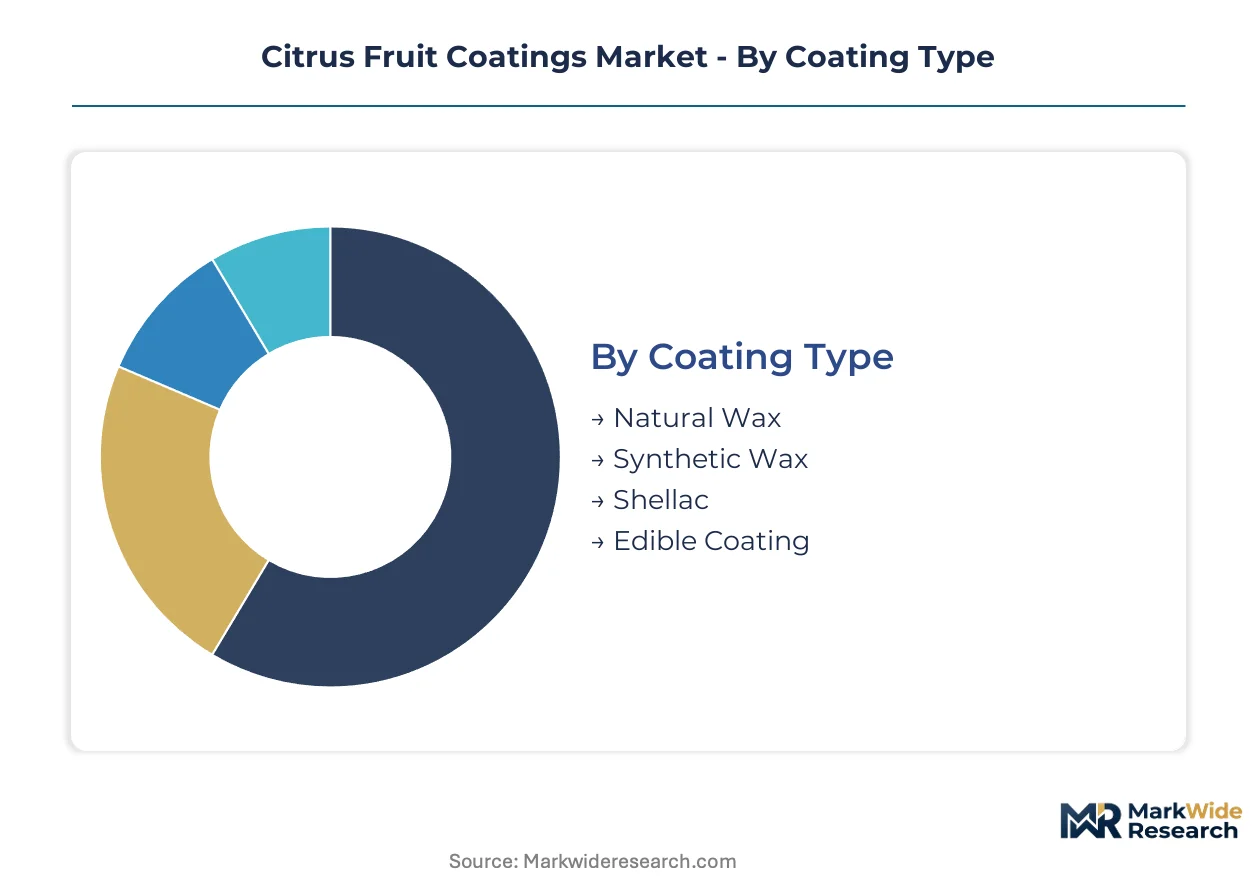
Citrus fruit coatings serve divergent functional requirements across export logistics, retail shelf-life extension, and processing durability. Segmentation reveals how formulation chemistry, application setting, and buyer procurement power reshape supplier priorities and margin structures.
Coating Type:
Buyers in this category separate by barrier performance needs against natural wax supply constraints and regulatory pressure on synthetics.
- Synthetic Wax:Polyethylene-derived emulsions deliver consistent film formation at high-speed pack line velocities. California packhouses specify these formulations for domestic mandarin and orange distribution where cost efficiency outweighs biodegradability mandates.
- Natural Wax:Carnauba and candelilla formulations command premium positioning in EU-bound export corridors where Farm to Fork Strategy compliance determines supermarket procurement eligibility. Brazilian harvest volatility creates input cost instability that compresses margins for formulators lacking long-term supply contracts.
- Shellac:Superior gloss retention and gas barrier properties serve extended transit corridors to Asian markets from South Africa and California operations.
- Edible Coating:Chitosan and alginate biopolymers integrate antimicrobial functions for organic citrus lines specified by premium European retailers.
Volume sits with Synthetic Wax; growth tilts toward Edible Coating.
Application:
Application setting determines coating specification through transit duration, temperature exposure, and downstream processing intensity.
- Export Citrus:Shellac and high-grade carnauba formulations withstand multi-week cold-chain journeys to distant markets. South African and Spanish packers invest in coating qualification programs that guarantee arrival condition for supermarket technical buyers.
- Fresh Citrus:Synthetic wax emulsions dominate high-volume domestic distribution where pack line speed and application consistency override extended barrier requirements.
- Processed Citrus:Modified coatings tolerate peeling, segmenting, and minimal processing without film fracture or residue transfer.
- Citrus Juice:Specialized barrier chemistries protect fruit integrity through extraction delays and buffer storage prior to pressing operations.
Export Citrus commands premium pricing; Fresh Citrus absorbs volume concentration.
Distribution Channel:
Channel structure shapes buyer power, contract duration, and technical service intensity for coating suppliers.
- Direct Sales:Large Spanish and California packers negotiate multi-year performance agreements bundling chemical supply, application equipment, and quality monitoring. These contracts displace transactional purchasing in mandarin export corridors where shelf-life guarantees determine renewal.
- Offline Retail:Regional distributors serve mid-tier packhouses with standardized wax formulations and limited technical support.
- Foodservice:Institutional buyers prioritize cost minimization over barrier performance for fruit destined for immediate processing or short-hold display.
- Online Retail:Emerging procurement channel for specialty edible coatings serving organic and clean-label citrus operations.
Direct Sales captures margin concentration; Online Retail shows steepest expansion trajectory.
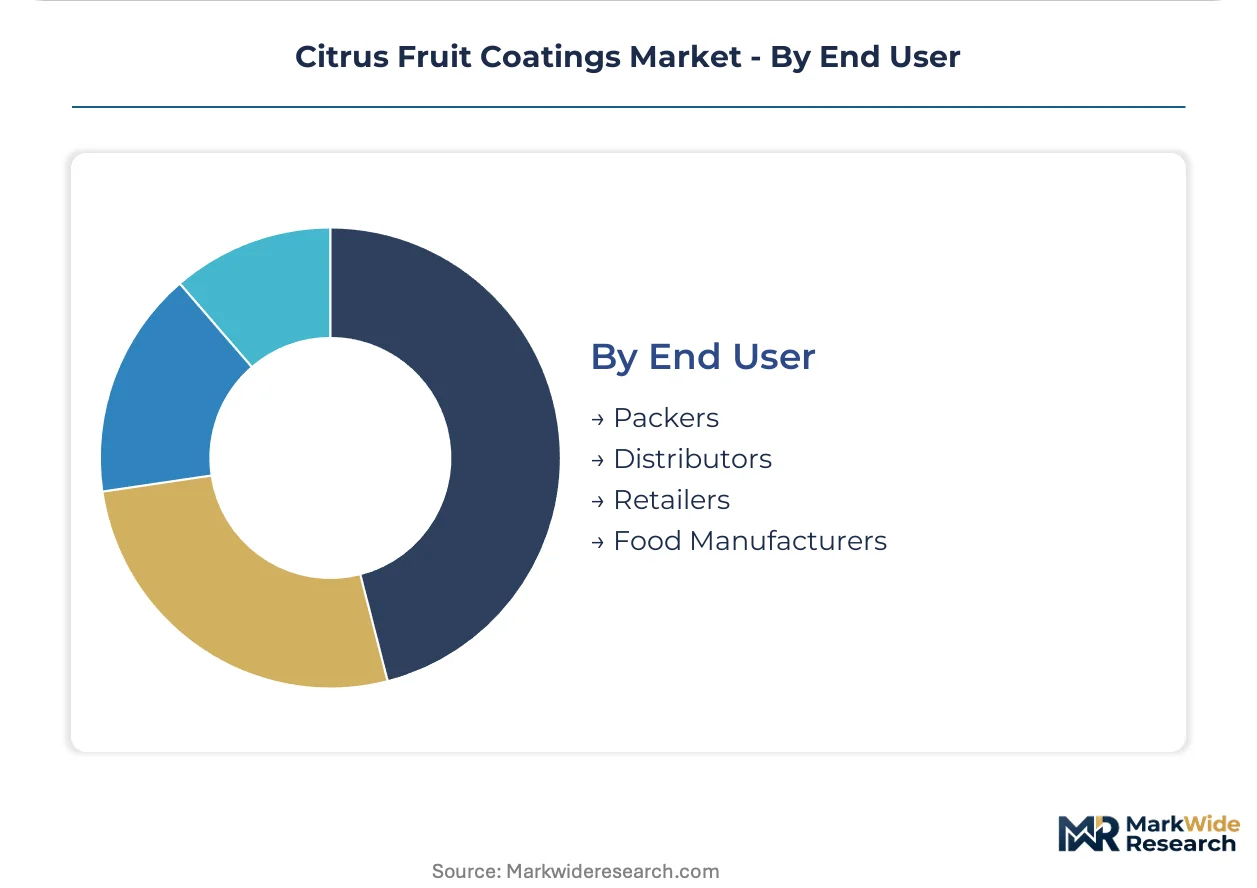
End User:
End-user scale and technical capability determine coating specification complexity and supplier relationship depth.
- Packers:Integrated post-harvest operations in California, Spain, and South Africa drive formulation innovation through performance-based contracting and cold-chain validation requirements.
- Distributors:Intermediate buyers consolidate procurement across smaller packhouses, favoring standardized synthetic wax formulations with predictable supply security.
- Retailers:Supermarket technical buyers specify coating chemistry through clean-label procurement standards that cascade to packer formulation choices.
- Food Manufacturers:Processing operations require coatings compatible with industrial peeling and segmenting equipment without residue contamination.
Packers anchor volume demand; Retailers are reshaping specification standards fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Spain's Valencia citrus belt operates as Europe's dominant post-harvest processing zone, drawing coating suppliers into concentrated technical service networks around Mediterranean export corridors.
Spain
Valencia and Murcia packhouses drive carnauba-shellac formulation demand for EU supermarket compliance. EFSA migration limit evaluations govern coating acceptability under REACH substance authorization timelines. Fomesa Fruitech anchors Mediterranean supply from its Castellón manufacturing base.
United States
California's Central Valley mandarin and orange operations specify synthetic wax emulsions for high-speed domestic pack lines. EPA registration requirements govern active and inert ingredients in coatings applied to US citrus. Fresno and Tulare County packers integrate coating application with automated fruit handling systems.
South Africa
Citrusdal and Limpopo packhouses invest in shellac-based coatings for extended Asian transit corridors. The country's national agricultural export regulator enforces residue tolerance standards for fruit bound for Middle Eastern and East Asian markets. Durban cold-chain infrastructure supports coating performance validation programs.
Brazil
São Paulo state citrus processors face carnauba harvest volatility that constrains natural wax input supply. ANVISA evaluates food-contact safety for coatings applied to export-bound fruit. The Triângulo Mineiro region concentrates coating formulation demand from integrated juice and fresh fruit operations.
India
Maharashtra and Telangana packers scale coating programs for Middle Eastern export expansion. FSSAI and BIS standards increasingly shape formulation acceptability for export-oriented domestic operations. Nagpur's orange processing cluster drives technical qualification of biodegradable coating alternatives.
Citrus Fruit Coatings Market Vendor Landscape
Mediterranean producers anchor the formulation tier; North American specialists hold integrated service positions. The supplier base stratifies between scaled technical players with multi-jurisdiction dossiers and regional formulators facing margin compression from compliance costs. Three archetypes dominate: wax chemistry specialists, integrated post-harvest platforms, and equipment-chemical bundlers. Geographic expansion and portfolio diversification represent the dominant competitive vectors as suppliers chase supermarket procurement consolidation.
Within the integrated platform tier, AgroFresh exemplifies convergence of coatings with ethylene management and storage diagnostics. Among Mediterranean-based formulators, Fomesa Fruitech and Productos Citrosol occupy positions anchored to Spanish citrus export infrastructure. Pace International represents the North American service-intensive archetype through localized technical networks.
| Leading Market Players |
|---|
| Fomesa Fruitech |
| Pace International |
| AgroFresh |
| Nipro Fresh |
| Productos Citrosol |
| John Bean Technologies |
| Valent BioSciences Corporation |
| Citrashine |
| Xeda International |
| Others |
Supply Flow & Price Mechanics
Carnauba wax harvest volatility in Brazil's Ceará and Piauí states transmits directly through coating formulation tiers, with premium natural wax coatings absorbing input spikes while synthetic polyethylene emulsions anchor economy positioning for California domestic pack lines.
Pricing Analysis
Short lead-time premiums for certified biodegradable formulations command pricing separation from spot-market synthetic wax inventories. Three-tier pricing structure across premium shellac, standard carnauba, and economy synthetic levels reflects certification grade and volume scale differentiation. Pricing pressure stems from REACH-driven reformulation cycles that compress margins for regional formulators lacking multi-jurisdiction dossiers. Mid-tier Mediterranean packers exhibit highest price sensitivity, while integrated Spanish and California packers prioritize performance guarantees over unit cost.
Supply Chain Analysis
Carnauba wax supply rests on Brazilian northeast harvest cycles that face climate-induced yield variability, while shellac feedstock draws from Indian forest lac cultivation. Synthetic polymer inputs source from petrochemical complexes in the United States, Germany, and South Korea. Single-source vulnerability concentrates in Brazilian natural wax supply, where harvest shortfalls cascade through EU-bound export coating specifications. Distribution runs through integrated packer-direct contracts displacing regional distributor networks in premium mandarin corridors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Edible biopolymer coatings derived from chitosan and alginate are displacing legacy shellac and synthetic wax formulations as European clean-label procurement standards tighten across supermarket technical specifications.
For Market Incumbents: Anticipate REACH substance authorization timelines accelerating reformulation R&D demands that strain technical staffing at mid-tier suppliers. Defensive consolidation through backward integration into carnauba supply contracts secures input cost stability against Brazilian harvest volatility. Certification investment in EFSA migration compliance preserves supermarket procurement eligibility for EU-bound fruit. For New Entrants and Emerging Players: Organic citrus packers in premium European retail channels represent the most penetrable white-space segment, with chitosan-based edible coatings specified for clean-label mandarin lines. Indian export-oriented packhouses serving Middle Eastern corridors offer second-entry positioning as FSSAI standard harmonization enables formulation acceptance. Technical service partnerships with automated pack line equipment providers accelerate qualification timelines. For Investors and Strategic Acquirers: Multi-year performance agreement signings between large Spanish packers and coating suppliers is the leading indicator that integrated post-harvest platform models are consolidating procurement power. Long-term viability favors scaled technical players with established EPA-EFSA-ANVISA dossier portfolios over regional formulators facing compliance cost compression. Watch for carnauba supply contract renewals as inflection signals for input cost trajectory and margin structure shifts.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Carnauba Supply | Long-term wax supply contracts with Brazilian harvest cooperatives lock in formulation cost stability. |
| EFSA Migration Compliance Certification | REACH-aligned dossier completion secures supermarket procurement eligibility for EU-bound citrus exports. |
| Edible Coating R&D Partnership | Chitosan-alginate biopolymer development with European organic retailers accelerates clean-label qualification. |
| Integrated Post-Harvest Platform Expansion | Bundled coatings-ethylene-diagnostics contracts with California packers displace transactional chemical purchasing. |
| Indian Export Corridor Technical Qualification | FSSAI-compliant formulation validation enables Middle Eastern market access for domestic packers. |
Methodological Framework
Trade flow databases, EFSA substance authorization registries, and Brazilian agricultural harvest statistics formed the secondary backbone, cross-referenced with primary interviews spanning coating formulation chemists, Spanish packhouse operations managers, supermarket technical buyers, and cold-chain logistics coordinators. Bottom-up triangulation against top-down export volume estimates validated segmentation splits across coating chemistry tiers and application settings.
Bottom-up modeling anchored projections, with top-down export corridor analysis cross-checking citrus trade flows from Valencia, California, and Citrusdal through destination market regulatory clusters. Segmentation dimensions spanned coating type, application setting, distribution channel, and end-user scale, with CAGRs derived from volume trajectory analysis across the projection horizon. Forecast inputs incorporated REACH sunset date timelines and carnauba harvest yield variability assumptions.
Several conditions sit outside the modeled scope, including unforeseen regulatory acceleration in polyethylene-derived polymer restrictions and catastrophic climate events disrupting Brazilian wax harvests. Forecasts reflect documented assumptions on supermarket procurement standard adoption rates and cold-chain infrastructure expansion. A small set of named triggers warrants ongoing watch: EFSA migration limit revisions, ANVISA food-contact rulings, and carnauba supply contract renegotiation cycles.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Additives and Ingredients
Food Grade Calcium Lactate Market
Food Additives and Ingredients
United Kingdom Food Colorants Market
Food Additives and Ingredients
Asia-Pacific Malt Ingredient Market
Food Additives and Ingredients
Synthetic Food Preservatives Market
Food Additives and Ingredients
Global Canthaxanthin Market
Food Additives and Ingredients
Sodium Propionate Market
Food Additives and Ingredients
Hydrocolloids Market
Food Additives and Ingredients
Anti-Caking Market
Food Additives and Ingredients
North America Food Emulsifiers Market
Food Additives and Ingredients
Brazil Feed Additives Market
Food Additives and Ingredients
France Food Emulsifiers Market
Food Additives and Ingredients
Ellagic Acid Market
Food Additives and Ingredients
Cocoglycerides Market
Food Additives and Ingredients
China Monosodium Glutamate (MSG) Market
Food Additives and Ingredients
Soft Drink Ingredients Market
Food Additives and Ingredients
Coconut Fatty Acids Market