
 Carrageenan Gum Market | 2026-2036
Carrageenan Gum Market Size, Share, and Industry Trends Forecast 2026-2036
Carrageenan Gum Market Analysis
Plant-based dairy alternatives is expanding its share of carrageenan gum offtake as oat and almond milk processors thicken formulations without animal-derived ingredients. CP Kelco U.S., Inc. leverages its vertically integrated seaweed supply chain from the Philippines to secure raw material consistency. FMC Corporation anchors its position through specialized kappa carrageenan extraction technology for meat-binding applications.
Carrageenan gum comprises sulfated galactans extracted from red seaweed (Rhodophyceae), with kappa, iota, and lambda variants distinguished by their sulfate content and calcium sensitivity; the hydrocolloid functions primarily as a gelling, thickening, and stabilizing agent across food and personal care systems. Kappa carrageenan dominates dairy applications where potassium-induced gelation provides firm, brittle textures in cheese analogs, while iota leads premium meat processing for its freeze-thaw stability and elastic gel structure. Lambda, non-gelling and highly viscous, occupies beverage and personal care segments where pourable consistency matters more than set strength.
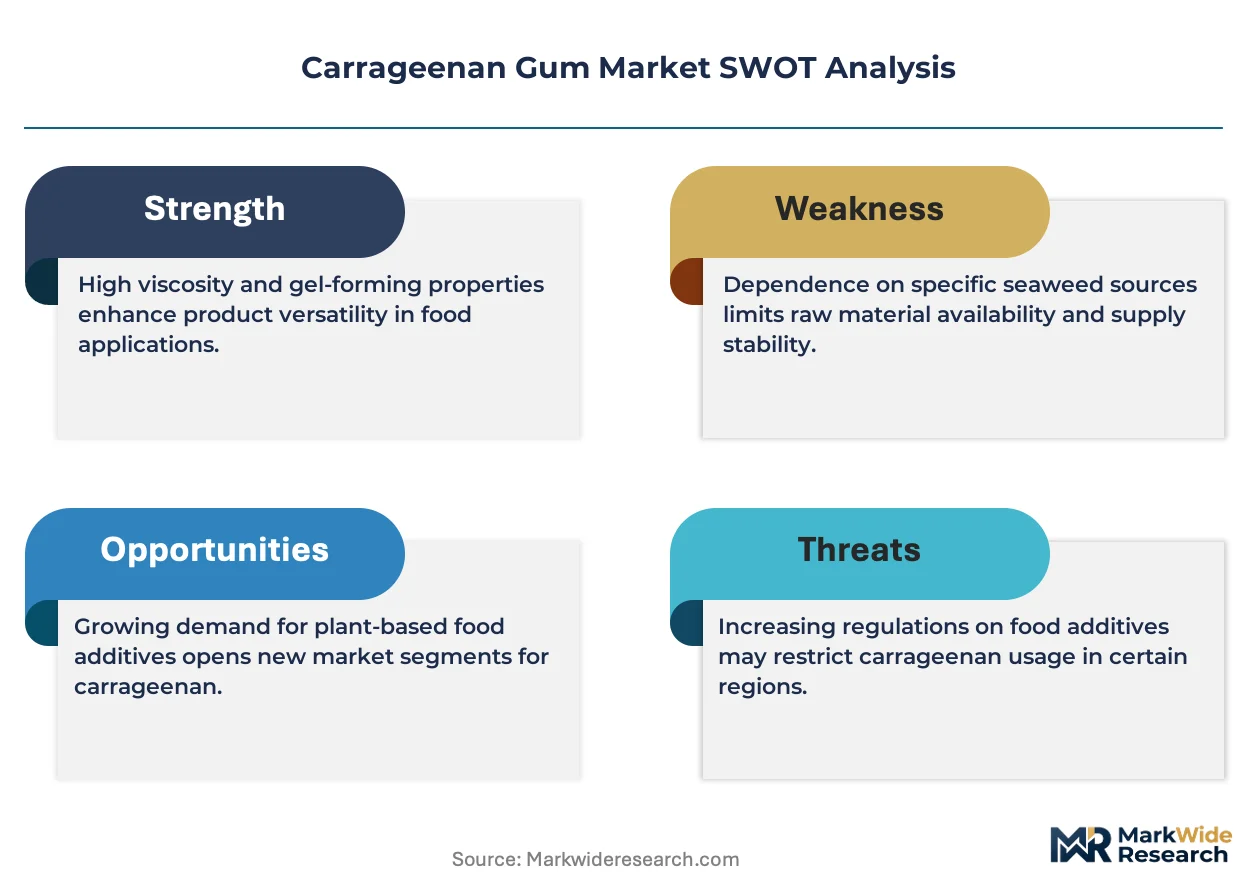
FDA food additive regulations and EFSA purity standards govern carrageenan gum inclusion levels and degradation limits in human food, directly shaping processor formulation ceilings and labeling requirements in the United States and European markets. The National Organic Standards Board deliberations on carrageenan status in organic products create ongoing uncertainty for certified food manufacturers. Stakeholders must monitor regulatory divergence between jurisdictions and seaweed supply volatility to align capacity investments with shifting clean-label expectations.
Market Dynamics
Seaweed supply concentration in Philippine and Indonesian coastal zones creates persistent raw material bottlenecks that force processors to secure multi-year harvesting contracts or develop alternative Rhodophyceae cultivation methods.
Growth Catalysts
- EFSA Purity Standards:European food additive regulations mandate specific carrageenan degradation limits, compelling reformulation investments that upgrade technical grade material into premium food-grade supply.
- Oat Milk Processing:Plant-based dairy alternatives require potassium-reactive hydrocolloids for texture stability, expanding kappa carrageenan offtake from specialty cheese analog producers into mainstream beverage manufacturing.
- Southeast Asian Seaweed Corridors:Philippine and Indonesian harvesting cooperatives now supply over seventy percent of raw red algae feedstock, anchoring regional processing clusters with cost-advantaged logistics.
Market Restraints
- Input Cost Volatility:Wild seaweed harvests fluctuate with El Niño cycles and coastal pollution events, creating eighteen-month price swings that compress processor margins.
- Substitution Threat:Locust bean gum and xanthan gum formulations displace carrageenan in clean-label beverage applications where sulfate content triggers consumer avoidance.
- Regulatory Friction:National Organic Standards Board deliberations on carrageenan status in certified organic products generate compliance uncertainty for US-based food manufacturers.
Strategic Opportunities
- Cellular Agriculture:Cultivated meat startups require iota carrageenan for scaffold elasticity and serum-free media stabilization, opening premium pricing tiers unavailable in commodity food applications.
- Personal Care Formulation:Lambda variant viscosity profiles suit sulfate-free shampoo and lotion systems where pourable rheology replaces traditional petrochemical thickeners.
- Indian PLI Scheme:India's production-linked incentive framework for food processing infrastructure attracts seaweed extraction investments targeting domestic hydrocolloid demand.
Industry Challenges
- Specialized Extraction Expertise:Kappa-iota-lambda separation requires precise calcium and potassium ion control, creating talent scarcity for operators capable of maintaining EFSA-compliant purity thresholds.
- Legacy Equipment Retrofit:Batch processing systems designed for agar extraction demand capital-intensive reconfiguration to achieve carrageenan-specific temperature and pH parameters.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Carrageenan Gum Market |
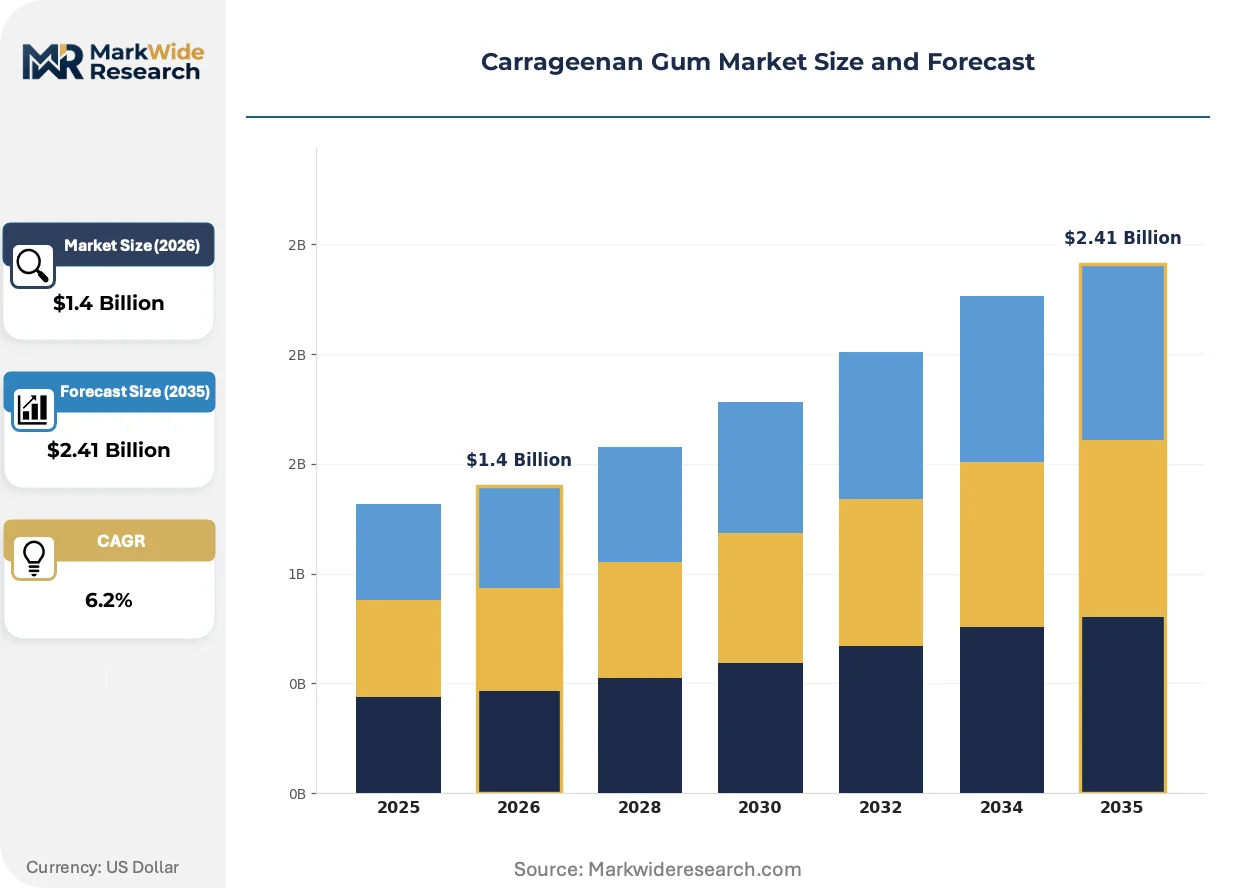
| Market Size in 2026 | $1.4 Billion |
| Market Size in 2035 | $2.41 Billion |
| CAGR (2026 – 2036) | 6.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Kappa, Iota, Lambda, Blends Application: Dairy, Meat, Beverage, Personal Care End User: Food Industry, Pharmaceutical, Cosmetics, Pet Food Form: Powder, Granules, Liquid, Flakes |
| Companies Covered | CP Kelco U.S., Inc., FMC Corporation, Cargill, Incorporated, Ingredion Incorporated, DuPont de Nemours, Inc., Gelymar S.A., Marcel Carrageenan Corporation, TIC Gums, Inc., Shemberg Marketing Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Carrageenan Gum Market Emerging Trajectories
Processing technology and regulatory classification debates are compressing traditional supply hierarchies while opening premium tiers for certified-purity grades. Equipment automation and cultivation science convergence are reshaping competitive positioning.
Membrane filtration technology is automating the separation of kappa, iota, and lambda fractions during alkaline extraction, reducing solvent waste and labor intensity. Mid-tier Philippine processors are adopting these systems to bypass traditional centrifuge-based methods. The shift is automating quality consistency previously achievable only through manual batch oversight, compressing the premium attached to established European suppliers.
EFSA's ongoing re-evaluation of carrageenan molecular weight specifications is tightening permissible poligeenan contamination thresholds. Food manufacturers across Germany, France, and Italy must reformulate or source pharmaceutical-grade material to maintain clean-label positioning. Dairy analog producers in the Netherlands are responding by demanding batch-specific molecular weight certificates from their Philippine suppliers.
Direct contracting between end-users and seaweed harvesting cooperatives is displacing multi-layered trader networks that historically aggregated raw material. Oat milk processors in Denmark and Sweden now negotiate seasonal harvest commitments directly with Indonesian farmer associations. This pattern is most visible in Nordic markets where sustainability certification requirements exceed standard commercial specifications.
Carrageenan Gum Market Segmentation
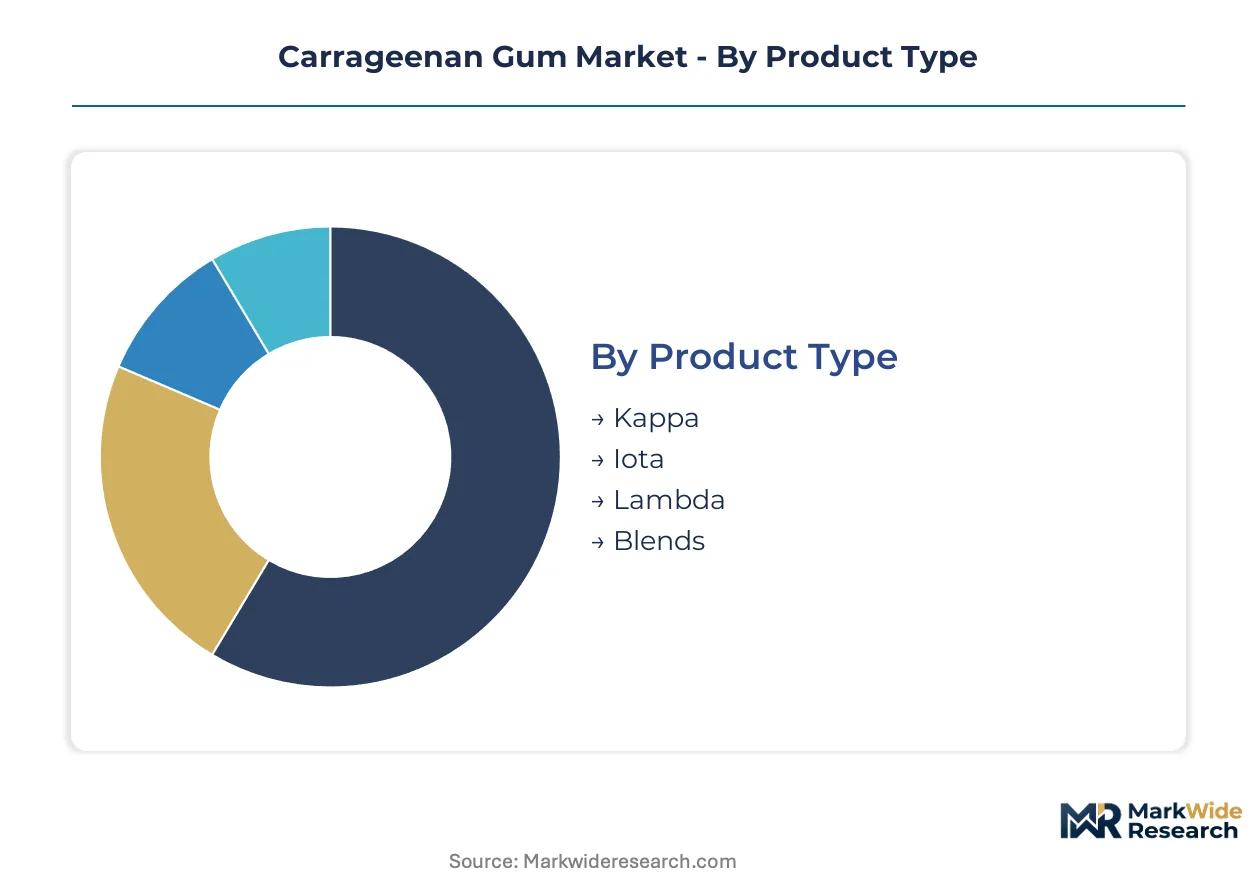
Carrageenan gum variants differ sharply in gelation chemistry and calcium sensitivity, creating divergent integration paths across food systems and industrial formulations. Processors select grades based on whether the hydrocolloid functions as a standalone texture agent or embeds within complex stabilizer blends.
Product Type:
Kappa and iota variants dominate standalone applications where ion-specific gelation delivers precise texture control, while lambda and blended grades embed predominantly within multi-hydrocolloid systems.
- Kappa:Potassium-reactive sulfated galactan extracted from Kappaphycus alvarezii forms firm, brittle gels ideal for dairy analogs. Demand concentrates in oat milk processors across Denmark and Sweden where clean-label positioning requires animal-free firming agents.
- Iota:Calcium-sensitive variant from Eucheuma denticulatum produces elastic, thermo-reversible gels with superior freeze-thaw stability. Premium meat processors in Germany leverage this property for injected brine systems in poultry and seafood applications.
- Lambda:Non-gelling, highly viscous fraction serves beverage and personal care systems where pourable rheology replaces set strength. Cold-soluble properties suit ready-to-drink formulations.
- Blends:Synergistic combinations with locust bean gum or konjac optimize cost-performance ratios in processed cheese and dessert gels.
Volume placements concentrate in Kappa; the faster expansion belongs to Iota.
Application:
Cost tier stratification separates premium positioning in personal care from commodity-scale food manufacturing where formulation economics dictate grade selection.
- Dairy:Cheese analogs, ice cream stabilization, and plant-based milk systems represent the largest consumption block. EFSA purity requirements in Germany, France, and Italy force batch-specific molecular weight certification from Philippine suppliers.
- Meat:Injected brines and restructured products utilize iota's water-binding capacity. Processors face substitution pressure from phosphate-free clean-label alternatives.
- Beverage:Lambda suspends cocoa in chocolate milk and stabilizes protein drinks. Susceptibility to locust bean gum displacement in sulfate-avoidant formulations.
- Personal Care:Sulfate-free shampoo and lotion systems command premium pricing for pharmaceutical-grade lambda with documented poligeenan limits below EFSA thresholds.
Revenue margins peak in Personal Care; steepest expansion trajectory runs through Beverage as protein-fortified drinks proliferate.
End User:
Customer type determines certification burden and contract structure, with pharmaceutical and cosmetic buyers imposing documentation requirements that food-grade purchasers rarely match.
- Food Industry:Dairy, meat, and beverage manufacturers drive aggregate tonnage. Direct contracting with Indonesian and Philippine harvesting cooperatives is displacing multi-layered trader networks.
- Pharmaceutical:Excipient-grade material for tablet binding and sustained-release matrices demands USP-NF compliance with validated degradation limits.
- Cosmetics:Rinse-off and leave-on formulations require microbial specifications stricter than food-grade standards. Lambda viscosity profiles suit sulfate-free positioning.
- Pet Food:Canned gravy systems and extruded kibble binding represent price-sensitive offtake with minimal regulatory scrutiny.
Contract values concentrate in Food Industry; premium pricing expansion belongs to Pharmaceutical.
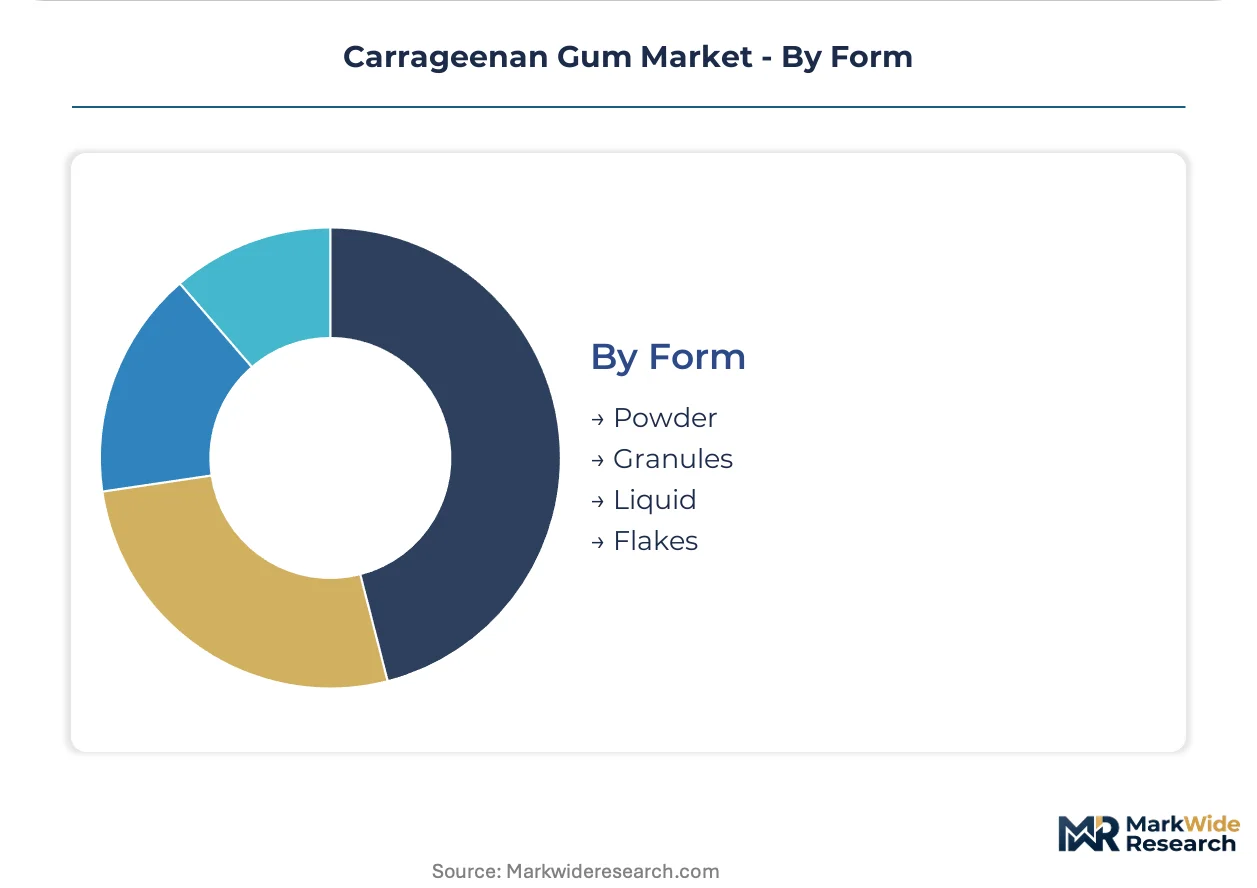
Form:
Supply concentration in Southeast Asian processing clusters favors powder and granule output, while liquid and flake formats require specialized equipment less common outside European facilities.
- Powder:Spray-dried standard grade dominates bulk dairy and meat applications. Philippine processors achieve EFSA-compliant purity through membrane filtration automation.
- Granules:Agglomerated particles improve dispersibility in high-solids beverage systems. Preferred by oat milk manufacturers for reduced lumping during high-shear mixing.
- Liquid:Pre-hydrated dispersions eliminate dust handling and reduce batch cycle times. Personal care formulators in the Netherlands value ready-to-use viscosity.
- Flakes:Semi-refined grades retain higher mineral content for specific regional applications with less stringent purity requirements.
Processing capacity concentrates in Powder; value-added growth belongs to Liquid as formulation houses seek operational efficiency.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Special economic zones in the Philippines and Indonesia concentrate seaweed processing capacity, attracting downstream hydrocolloid investments through tariff exemptions and streamlined customs procedures.
Philippines
Oat milk manufacturers in Denmark and Sweden source kappa carrageenan directly from Mindanao harvesting cooperatives, bypassing traditional trader networks. The Philippine Economic Zone Authority grants income tax holidays to seaweed processors meeting EFSA purity benchmarks. Cebu-based extraction facilities now supply batch-specific molecular weight certificates to Dutch dairy analog producers.
Indonesia
Indonesian farmer associations in Sulawesi and Nusa Tenggara negotiate seasonal harvest commitments with Nordic beverage processors seeking sustainability certification. The Ministry of Marine Affairs and Fisheries regulates wild harvest quotas to prevent coastal ecosystem degradation. Makassar processing clusters export semi-refined grades to Indian food manufacturers participating in the PLI scheme.
Germany
Premium meat processors in Lower Saxony utilize iota carrageenan for injected brine systems in poultry and seafood applications. EFSA's tightened poligeenan contamination thresholds force reformulation investments or pharmaceutical-grade material sourcing. Hamburg-based distributors demand documented degradation limits from Southeast Asian suppliers to maintain clean-label positioning.
United States
Plant-based dairy startups in California and Oregon formulate oat and almond milk with potassium-reactive hydrocolloids for texture stability. FDA food additive regulations and National Organic Standards Board deliberations create compliance uncertainty for certified organic manufacturers. Pacific Northwest formulation houses seek pre-hydrated liquid dispersions to eliminate dust handling.
India
Domestic hydrocolloid demand from processed cheese and dessert gel manufacturers attracts seaweed extraction investments under the PLI scheme for food processing infrastructure. FSSAI standards govern food additive inclusion levels and labeling requirements. Gujarat-based dairy processors experiment with kappa-locust bean gum blends to optimize cost-performance ratios.
Carrageenan Gum Market Vendor Landscape
Branded specialists and contract manufacturers split share differently across segments, with integrated seaweed processors commanding premium pricing in pharmaceutical-grade supply while toll extractors serve commodity food applications. The vendor base organizes around three strategic archetypes: vertically integrated harvest-to-powder operators, regional extraction specialists with captive raw material agreements, and formulation houses blending carrageenan into multi-hydrocolloid stabilizer systems. Capacity expansion and direct contracting with harvesting cooperatives constitute the dominant competitive moves, displacing multi-layered trader networks.
Within the integrated processor tier, CP Kelco U.S., Inc. and FMC Corporation exemplify archetypes built on upstream control over Southeast Asian seaweed supply. Cargill, Incorporated represents the diversified agricultural conglomerate model, leveraging existing food ingredient distribution infrastructure. Gelymar S.A. and Marcel Carrageenan Corporation occupy positions as regional specialists with concentrated geographic footprints in South American and Southeast Asian markets respectively. These named entities anchor industry-level commentary on competitive positioning without implying specific strategic actions or market shares.
| Leading Market Players |
|---|
| CP Kelco U.S., Inc. |
| FMC Corporation |
| Cargill, Incorporated |
| Ingredion Incorporated |
| DuPont de Nemours, Inc. |
| Gelymar S.A. |
| Marcel Carrageenan Corporation |
| TIC Gums, Inc. |
| Shemberg Marketing Corporation |
| Others |
Supply Flow & Price Mechanics
EFSA's tightened poligeenan contamination thresholds gate qualified supply for premium-tier pricing access, forcing Dutch dairy analog producers to demand batch-specific molecular weight certificates from Philippine suppliers while excluding semi-refined grades from clean-label formulations.
Pricing Analysis
Short lead-time premiums dominate contract negotiations, with Nordic oat milk processors paying above-spot rates for seasonal harvest commitments secured directly with Indonesian farmer associations. Three-tier pricing structure across pharmaceutical-grade, food-grade, and technical-grade levels reflects certification burden and purity thresholds. Cost compression in standard food-grade tiers is intensifying because membrane filtration automation enables mid-tier Philippine processors to bypass European quality premiums. Pet food manufacturers exhibit highest price sensitivity, while pharmaceutical excipient buyers absorb premiums for USP-NF validated degradation limits.
Supply Chain Analysis
Dual-sourcing requirements now mandate multi-supplier qualification for EFSA-compliant material, with Hamburg-based distributors documenting degradation limits from both Philippine and Indonesian extraction facilities simultaneously. Raw material supply concentrates in the Philippines, Indonesia, and emerging Indian processing clusters under the PLI scheme. Wild Kappaphycus alvarezii and Eucheuma denticulatum harvests draw from coastal zones vulnerable to El Niño cycles and pollution events. Single-source vulnerability persists in specialized kappa-iota-lambda separation expertise. Distribution runs through direct contracting between end-users and harvesting cooperatives, displacing multi-layered trader networks historically aggregating raw material.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Membrane filtration automation is replacing legacy centrifuge-based extraction methods, compressing quality premiums and reshaping competitive positioning across Southeast Asian processing clusters.
For Market Incumbents: To counter displacement by locust bean gum and xanthan gum in clean-label beverage applications, secure multi-year harvesting contracts with Philippine and Indonesian cooperatives and invest in pharmaceutical-grade certification infrastructure to capture premium pricing tiers unavailable to commodity processors. For New Entrants and Emerging Players: Cultivated meat scaffold applications represent the most penetrable white-space target, requiring iota carrageenan for serum-free media stabilization where premium pricing tolerates new supplier qualification; pursue direct partnerships with cellular agriculture startups in California and the Netherlands bypassing established distributor networks. For Investors and Strategic Acquirers: National Organic Standards Board deliberations on carrageenan status in certified organic products are the leading indicator that regulatory clarity will trigger consolidation among US-based food manufacturers seeking compliant supply chains; target extraction specialists with captive raw material agreements and validated EFSA purity thresholds as acquisition candidates over a five-to-ten year viability window.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Seaweed Cultivation | CP Kelco's captive supply from Philippine cooperatives secures raw material consistency against El Niño volatility. |
| Pharmaceutical-Grade Certification Investment | EFSA's tightened molecular weight specifications force Dutch dairy analog producers to source validated degradation limits. |
| Direct Contracting with Harvesting Cooperatives | Nordic oat milk processors in Denmark negotiate seasonal commitments with Indonesian farmer associations. |
| Membrane Filtration Automation Adoption | Mid-tier Philippine processors bypass European quality premiums through automated kappa-iota-lambda separation. |
| Cellular Agriculture Partnership Development | Cultivated meat startups require iota carrageenan for scaffold elasticity at pricing tiers above commodity food applications. |
Methodological Framework
Trade association data, regulatory filings, and customs records anchored secondary inputs, combined with primary interviews involving extraction plant managers, procurement leads at downstream dairy and meat processors, distribution channel partners, and technical R&D directors at hydrocolloid formulation houses. Secondary sources included EFSA additive re-evaluations, FDA food additive regulations, FSSAI standards, Philippine Economic Zone Authority incentive disclosures, and Indonesian Ministry of Marine Affairs harvest quota records. Bottom-up tonnage estimates from end-use applications triangulated against top-down trade flow analysis.
Granularity-level modeling operated at product variant, application, end-user, and form dimensions, with additional disaggregation by regional regulatory cluster reflecting EFSA, FDA, and FSSAI divergence. Volume and value outputs across the projection horizon applied category-specific growth assumptions derived from oat milk processing expansion, cellular agriculture emergence, and personal care sulfate-free formulation trends. CAGRs were computed from segmented baseline placements and normalized against historical trade data volatility.
Several conditions sit outside the modeled scope, including sudden National Organic Standards Board reclassification decisions, extreme El Niño events exceeding historical coastal harvest disruption patterns, and breakthrough cultivated meat scaffold technologies eliminating hydrocolloid requirements. Forecasts reflect assumptions about regulatory stability and seaweed supply continuity. Deviation in EFSA poligeenan threshold tightening or Philippine coastal ecosystem degradation would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Additives and Ingredients
France Anti Caking Market
Food Additives and Ingredients
Clean Labelled Food Additives Market
Food Additives and Ingredients
Aluminum-Free Natural Food Color Market
Food Additives and Ingredients
Russia Anti Caking Market
Food Additives and Ingredients
Lime Oil Market
Food Additives and Ingredients
Trans Fatty Acids Market
Food Additives and Ingredients
India Food Enzymes Market
Food Additives and Ingredients
Acrylamide Reduction Market
Food Additives and Ingredients
Annatto Food Colors Market
Food Additives and Ingredients
North America Food Anti Caking Agents Market
Food Additives and Ingredients
Disodium Cocoamphodiacetate Market
Food Additives and Ingredients
Global Organic Feed Additives Market
Food Additives and Ingredients
Food Grade Ammonium Bicarbonate Market
Food Additives and Ingredients
India Food Emulsifiers Market
Food Additives and Ingredients
Quillaja Saponaria Ingredient Market
Food Additives and Ingredients
Global Gamma Linolenic Acid Market