
 Soft Drink Ingredients Market | 2026-2036
Soft Drink Ingredients Market Size, Share, and Industry Trends Forecast 2026-2036
Soft Drink Ingredients Market Analytics
Multi-ingredient concentrate bundling is consolidating procurement decisions among mid-sized beverage manufacturers. Cargill, Incorporated leverages its corn-based sweetener infrastructure to anchor North American supply relationships. Kerry Group plc specializes in integrated flavor systems that reduce formulation complexity for clients. Tate & Lyle differentiates through rare sugar alternatives that command premium positioning in reduced-calorie segments.
Soft drink ingredients comprise functional additives—sweeteners, acidulants, preservatives, and flavor compounds—typically dosed at 0.1% to 15% by finished beverage weight to achieve taste stability, microbial safety, and shelf-life extension. Ingredient type segmentation shows sweeteners and flavorings capturing the dominant margin pools, while acid and preservervative categories face pricing pressure from natural replacement trends. Application segmentation reveals energy drinks and flavored water outpacing carbonated beverages in growth velocity, driven by health-positioned formulation demands.
FDA GRAS determinations, EU EFSA additive evaluations, and India's FSSAI ingredient approvals collectively govern market access and reformulation timelines across major supply corridors. Compliance with evolving sugar taxation frameworks and front-of-pack labeling mandates in multiple jurisdictions is forcing ingredient suppliers to revalidate product portfolios. Stakeholders must monitor regulatory divergence between permissive and restrictive additive jurisdictions to anticipate reformulation investment cycles.
Market Dynamics
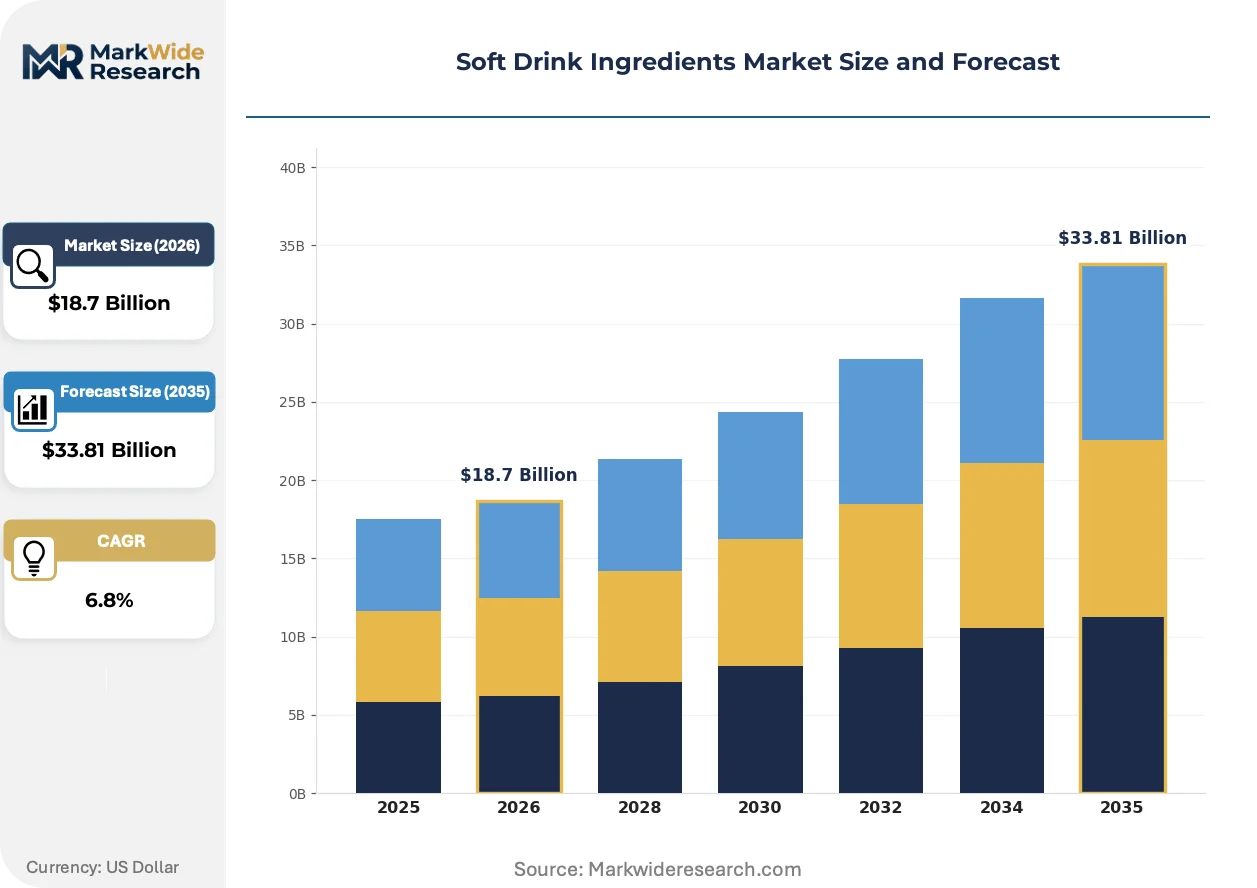
Clean-label mandates and sugar taxation frameworks are compressing formulation timelines while fragmenting procurement across natural sweetener categories, forcing ingredient suppliers to revalidate portfolios against divergent national additive standards.
Growth Catalysts
- EU F-Gas Regulation:Phasedown of hydrofluorocarbon cooling in beverage processing plants is accelerating demand for ambient-stable concentrate formulations that reduce cold-chain dependency.
- Energy drink manufacturers:These end-users are expanding procurement of functional acidulants and natural caffeine alternatives to differentiate health-positioned product lines.
- Stevia-leaf extraction:Enzymatic bioconversion processes are unlocking Reb M and Reb D glycosides at commercial scale, broadening natural high-intensity sweetener availability.
Market Restraints
- Corn price volatility:Input cost swings for high-fructose corn syrup concentrate producers in the US Midwest are compressing margin stability for North American sweetener suppliers.
- Supply concentration in Brazil:ANVISA-registered natural flavor extraction facilities cluster in São Paulo state, creating geographic single-point vulnerability for tropical fruit essence supply.
- Technical limitation:Natural preservatives such as cultured dextrose and rosemary extract deliver shorter shelf-life extension than synthetic benzoates, constraining reformulation options for ambient distribution.
Strategic Opportunities
- India:FSSAI's streamlined novel food ingredient approval pathway is opening white space for rare sugar entrants targeting the country's expanding middle-class beverage consumption.
- Regulatory tailwind:Front-of-pack Nutri-Score mandates across France, Belgium and Germany are creating formulation service demand for sugar-reduction technical support.
- Direct-to-manufacturer digital platforms:These channels are disintermediating traditional flavor house relationships, enabling mid-sized beverage brands to access custom concentrate development.
Industry Challenges
- Reformulation chemist shortage:Competency gaps in natural-synthetic ingredient interaction modeling are extending product development cycles for clean-label transitions.
- Multi-jurisdiction GRAS dossier preparation:FDA notification timelines averaging 180 days are misaligning with beverage brand launch windows, forcing parallel regulatory investment.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Soft Drink Ingredients Market |
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $33.81 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Ingredient Type: Sweeteners, Flavorings, Acids, Preservatives Form: Liquid, Powder, Concentrate, Granular Application: Carbonated Beverages, Juice Drinks, Flavored Water, Energy Drinks End User: Beverage Manufacturers, Food Service Operators, Retailers, Distributors |
| Companies Covered | Cargill, Incorporated, Archer Daniels Midland Company, Kerry Group plc, Tate & Lyle, Ingredion, DuPont, Novozymes A/S, Mevive International, Symega Food Ingredients, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Soft Drink Ingredients Market Evolving Landscape
Biotechnology-enabled ingredient production and algorithmic flavor matching are compressing the gap between concept and commercial formulation, while regulatory divergence between permissive and restrictive additive jurisdictions is fragmenting global product architectures.
Precision fermentation for rare sugar production is decentralizing supply relationships between ingredient suppliers and beverage manufacturers. Startups deploying yeast-cell factories for allulose and tagatose are securing offtake agreements directly with mid-sized brands, bypassing traditional distributor networks. This technology is decentralizing procurement decision-making from centralized commodity exchanges toward bilateral supply contracts with biotech specialists.
EU REACH authorization requirements for flavoring substances are forcing systematic substance-by-substance safety dossier resubmission. The industrial consequence is portfolio pruning among smaller European flavor houses lacking toxicology investment capacity. Carbonated beverage categories with complex flavor layering are most affected, driving consolidation toward integrated suppliers with in-house regulatory science functions.
Beverage manufacturers are unbundling after-sales technical service from ingredient supply contracts, treating formulation support as a separately procured capability. Mid-sized brands in Germany and the Netherlands are engaging independent flavor consultants rather than accepting bundled technical service from incumbent suppliers. This pattern is most visible in reduced-sugar sparkling water development, where brands seek external validation of sensory equivalence claims.
Soft Drink Ingredients Market Segmentation
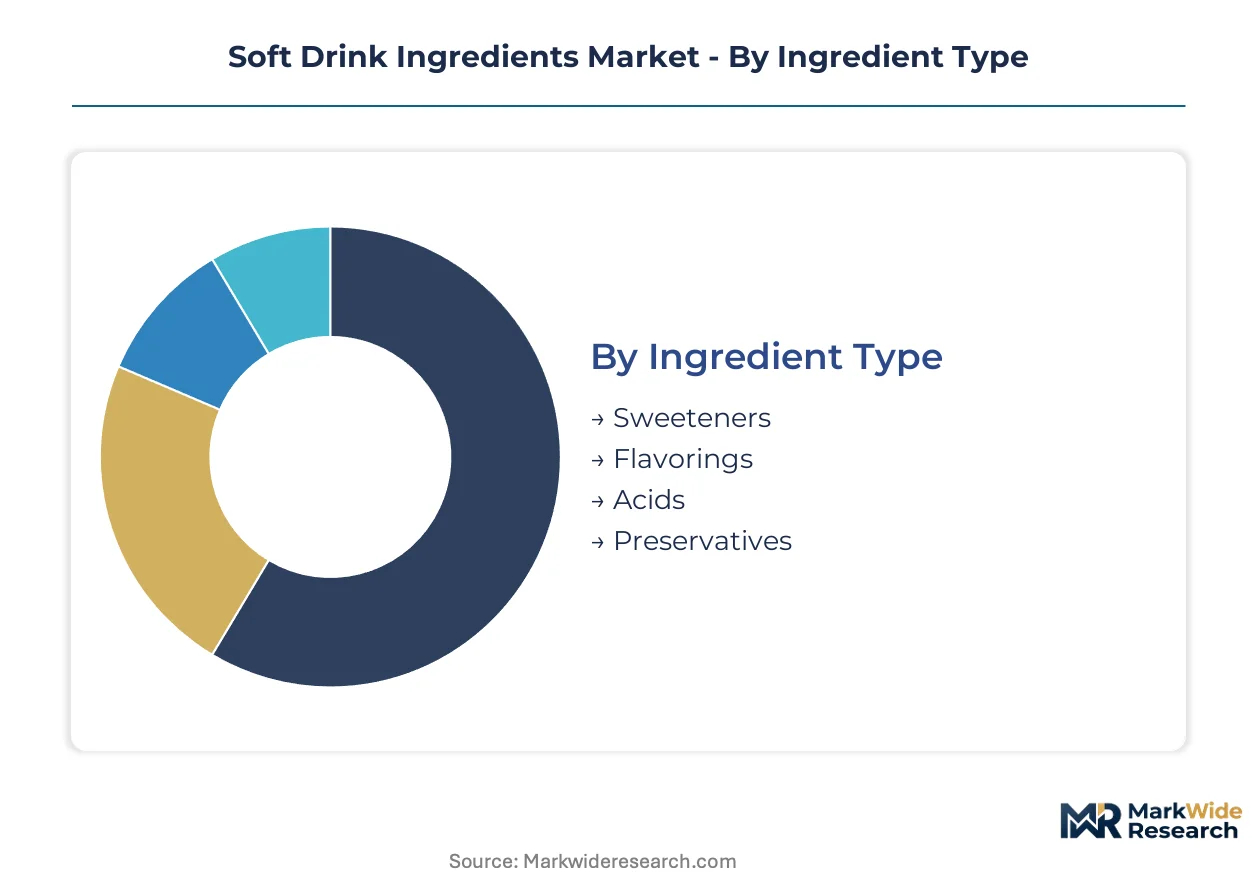
Ingredient suppliers configure production lines around formulation flexibility rather than commodity scale. Segmentation reveals where procurement premiums attach to customization capabilities versus standard specification bulk.
Ingredient Type:
Customization intensity varies sharply across this category, from bespoke flavor compounding to specification-grade acidulants.
- Sweeteners:High-intensity variants including steviol glycosides and rare sugars require enzymatic bioconversion infrastructure. Procurement concentrates among reduced-calorie sparkling water developers in Germany seeking Nutri-Score optimization. Synthetic alternatives face reformulation pressure from sugar taxation frameworks.
- Flavorings:Natural extracts and clean-label compounds demand tropical sourcing relationships and REACH-compliant safety dossiers. ANVISA-registered extraction facilities in São Paulo state anchor supply for Brazil's beverage manufacturers. EU flavoring substance authorization timelines are compressing smaller house portfolios.
- Acids:Citric, malic, and phosphoric acidulants serve functional pH adjustment with limited differentiation margin. Specification-grade material flows through carbonated beverage bottlers seeking consistent carbonation stability.
- Preservatives:Natural alternatives including cultured dextrose and rosemary extract deliver shorter shelf-life extension than synthetic benzoates. Ambient distribution constraints limit adoption in markets with underdeveloped cold-chain infrastructure.
Most installed capacity flows through Sweeteners. Expansion is steepest in Flavorings.
Form:
Transport economics and dosing precision divide this category between bulk liquid handlers and precision powder users.
- Liquid:Bulk tanker delivery suits high-volume carbonated beverage plants with integrated batching systems. Cargill's corn-based syrup infrastructure anchors North American supply relationships through pipeline-connected facilities.
- Powder:Spray-dried and agglomerated formats enable precise dosing in smaller batch operations. Mid-sized energy drink manufacturers in the Netherlands prefer powder flexibility for rapid formulation iteration.
- Concentrate:Multi-ingredient bundling reduces procurement transaction costs for beverage manufacturers with limited technical service capacity. Kerry Group's integrated flavor systems target this efficiency-seeking segment.
- Granular:Free-flowing crystalline formats suit automated dispensing equipment in food service fountain operations. Uniform particle size distribution prevents bridging in hopper-fed systems.
Volume concentrates in Liquid. Value capture is expanding most quickly in Concentrate.
Application:
Health-positioning intensity separates high-growth formulation complexity from mature specification stability.
- Carbonated Beverages:Traditional cola and lemon-lime categories face volume pressure from sugar taxation. Reformulation cycles extend development timelines as brands seek sensory equivalence in reduced-sugar variants.
- Juice Drinks:Nectar and still juice formulations require acidulant balancing for microbial stability without synthetic preservative labeling. Clean-label mandates compress acceptable ingredient lists.
- Flavored Water:Reduced-sugar and zero-calorie positioning drives natural sweetener adoption. France, Belgium, and Germany's Nutri-Score mandates accelerate sugar-reduction technical service demand.
- Energy Drinks:Functional acidulants and natural caffeine alternatives differentiate health-positioned product lines. India's expanding middle-class beverage consumption attracts rare sugar entrants through FSSAI's streamlined approval pathway.
Revenue generation concentrates in Carbonated Beverages. Climbing the fastest is Flavored Water.
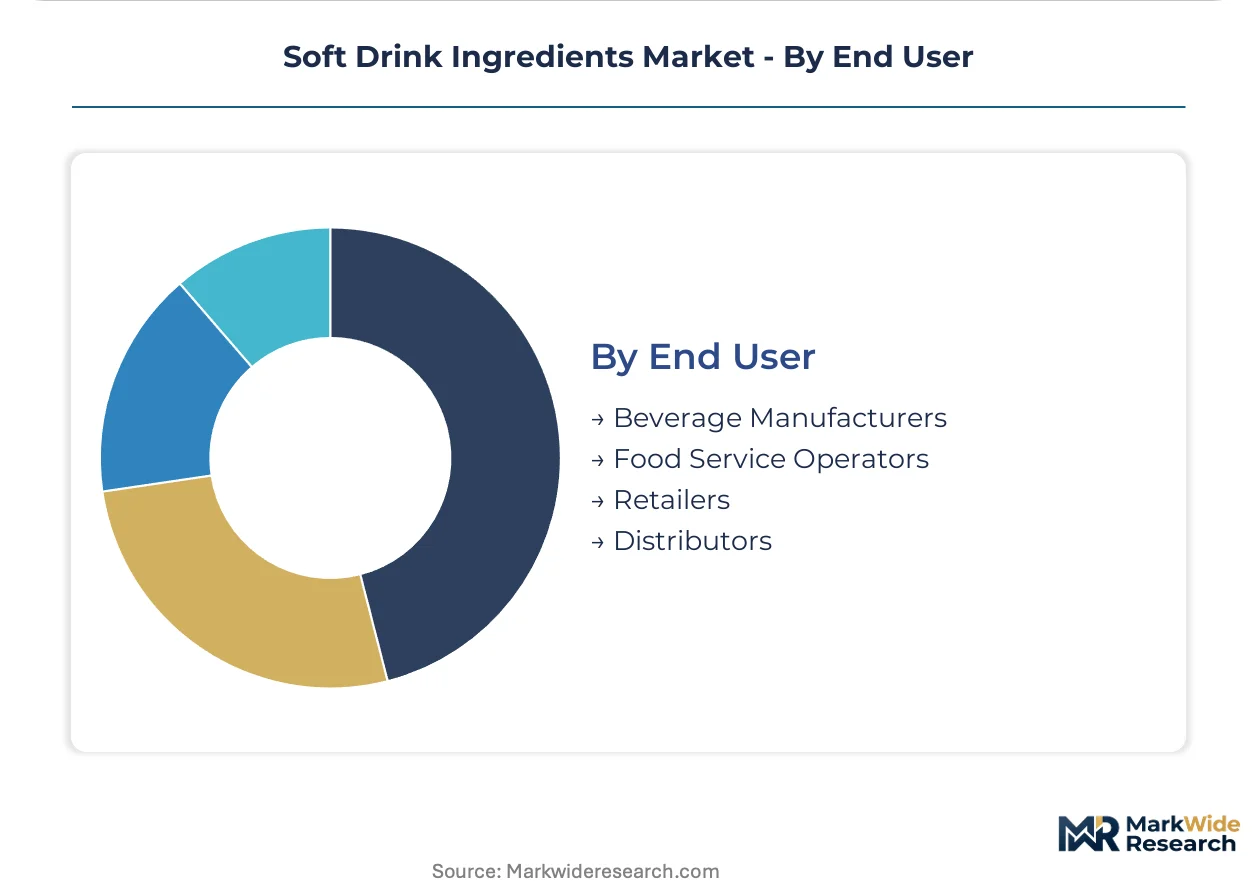
End User:
Technical sophistication and procurement scale determine service bundling expectations across this category.
- Beverage Manufacturers:Integrated production facilities demand formulation support, regulatory dossier management, and inventory financing. Tate & Lyle's rare sugar alternatives command premium positioning through technical partnership models.
- Food Service Operators:Fountain and dispensed beverage systems prioritize consistent syrup brix and equipment compatibility. Simplified specification requirements reduce supplier qualification burden.
- Retailers:Private-label development programs seek direct ingredient sourcing to capture margin from branded alternatives. Limited formulation expertise drives demand for turnkey concentrate supply.
- Distributors:Inventory aggregation and logistics services bridge fragmented regional beverage production. Geographic coverage requirements favor multi-category chemical handlers over specialized flavor houses.
Procurement volume concentrates in Beverage Manufacturers. Gaining share fastest is Food Service Operators.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The soft drink ingredients industry traces its modern scale to post-war American bottling automation and European flavor house consolidation, with subsequent dispersion into tropical sourcing corridors and Asian manufacturing hubs reshaping procurement geography.
United States
High-fructose corn syrup infrastructure anchors sweetener supply through Midwest corn belt processing clusters. FDA GRAS notification timelines averaging 180 days force parallel regulatory investment for clean-label reformulation cycles. Chicago-area ingredient distributors service carbonated beverage bottlers with integrated batching systems and pipeline-connected syrup facilities.
Germany
Reduced-calorie sparkling water developers drive Nutri-Score optimization demand for rare sugar technical support. EU REACH authorization requirements for flavoring substances compress smaller house portfolios lacking toxicology investment capacity. Bavaria-based formulation consultants unbundle after-sales technical service from incumbent supplier contracts.
Brazil
Tropical fruit essence extraction concentrates in São Paulo state ANVISA-registered facilities serving regional formulation specialization. Front-of-pack labeling mandates and sugar taxation frameworks accelerate natural sweetener procurement validation. Campinas cluster houses natural flavor extraction infrastructure vulnerable to geographic single-point supply risk.
India
Expanding middle-class beverage consumption attracts rare sugar entrants through FSSAI's streamlined novel food ingredient approval pathway. Energy drink manufacturers procure functional acidulants and natural caffeine alternatives for health-positioned product lines. Maharashtra-based mid-sized brands engage independent flavor consultants for reduced-sugar sparkling water development.
China
Precision fermentation startups deploy yeast-cell factories for allulose production, securing direct offtake agreements with mid-sized beverage brands. SAMR additive standards govern market access timelines diverging from Western regulatory frameworks. Yangtze River Delta biotech specialists bypass traditional distributor networks through bilateral supply contracts.
Soft Drink Ingredients Market Competitive Landscape
Premium-margin players sit above commodity-margin players across technical service bundling and regulatory dossier capabilities, with integrated flavor systems commanding procurement consolidation among efficiency-seeking mid-sized manufacturers. The vendor base stratifies between corn-based sweetener infrastructure operators, enzymatic bioconversion specialists, and rare sugar alternative developers. Three archetypes dominate: commodity-scale agricultural processors, integrated flavor system providers, and biotechnology-enabled ingredient innovators. Capacity expansion in precision fermentation capacity and M&A-driven regulatory science function acquisition represent the dominant competitive vectors.
Within the integrated flavor system tier, Kerry Group plc and Tate & Lyle occupy positions exemplifying technical partnership models that reduce formulation complexity for clients. Among agricultural processing specialists, Cargill, Incorporated anchors North American supply relationships through infrastructure scale. These three entities represent the structural spectrum from commodity-margin bulk handling through premium-margin customization capabilities.
| Leading Market Players |
|---|
| Cargill, Incorporated |
| Archer Daniels Midland Company |
| Kerry Group plc |
| Tate & Lyle |
| Ingredion |
| DuPont |
| Novozymes A/S |
| Mevive International |
| Symega Food Ingredients |
| Others |
Value Network & Pricing Analysis
Enzymatic bioconversion specialists cluster in Germany's Bavaria region and China's Yangtze River Delta, where labor-cost differentials between precision fermentation PhDs and commodity syrup plant operators widen pricing spreads across premium rare sugars and standard high-fructose corn syrup tiers.
Pricing Analysis
Contract-based long-term offtake agreements dominate procurement relationships between beverage manufacturers and sweetener suppliers, with price differentiation hinging on enzymatic conversion certification tiers and bundled technical service levels. Cost compression in synthetic high-intensity sweeteners is intensifying because stevia-leaf extraction yields are improving through Reb M bioconversion. Mid-sized energy drink manufacturers exhibit highest price sensitivity, while reduced-calorie sparkling water developers in Nutri-Score jurisdictions accept premium positioning for rare sugar alternatives.
Supply Chain Analysis
Direct-to-manufacturer digital platforms are disintermediating traditional flavor house relationships for mid-sized beverage brands seeking custom concentrate development. Geographic supply concentration centers on the United States for corn-based syrup infrastructure, Brazil for ANVISA-registered tropical fruit extraction, and China for precision fermentation capacity. Raw material dependencies include Midwest corn belt harvests, São Paulo state citrus and passion fruit harvests, and yeast-cell factory feedstocks. Single-source vulnerability in Campinas cluster natural flavor extraction creates geographic concentration risk. Distribution runs through integrated tanker delivery for bulk liquid handlers and bilateral contracts for biotech-enabled ingredient innovators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The soft drink ingredients market functions as a stable compounder, with clean-label reformulation mandates driving steady ingredient portfolio revalidation cycles across beverage manufacturers.
For Market Incumbents: Lock in rare sugar supply relationships through captive offtake agreements with precision fermentation startups before bilateral contracts displace traditional distributor networks. Deepen backward integration into enzymatic bioconversion infrastructure to defend margin position against commodity sweetener price volatility. Prioritize regulatory science function acquisition to manage EU REACH authorization timelines that compress smaller competitor portfolios. For New Entrants and Emerging Players: Launch via direct-to-manufacturer digital platforms targeting mid-sized beverage brands in India and Germany with limited in-house formulation expertise. India's FSSAI streamlined approval pathway for novel food ingredients represents the most penetrable geography for rare sugar market entry. Lead with turnkey concentrate bundling that reduces procurement transaction costs for efficiency-seeking manufacturers. For Investors and Strategic Acquirers: Integrated beverage conglomerates are the most active acquirer in this space, seeking flavor system capabilities that reduce formulation complexity for their brand portfolios. Over a multi-year holding period, target European flavor houses with REACH-compliant safety dossiers but lacking toxicology investment capacity for portfolio pruning consolidation. Monitor EU F-Gas Regulation phasedown implementation as inflection indicator for ambient-stable concentrate formulation demand acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Precision Fermentation Capacity Expansion | Yeast-cell factories for allulose production decentralize procurement from commodity exchanges toward bilateral contracts. |
| Regulatory Science Function Acquisition | In-house toxicology capabilities protect REACH-compliant flavor portfolios against smaller house compression. |
| Direct-to-Manufacturer Platform Launch | Digital channels disintermediate traditional flavor house relationships for mid-sized brand technical service access. |
| Multi-Ingredient Concentrate Bundling | Kerry Group's integrated flavor systems reduce procurement transaction costs for limited technical service capacity buyers. |
| Rare Sugar Technical Partnership Models | Tate & Lyle's premium positioning commands formulation support bundling in Nutri-Score optimization markets. |
Research Methodology
Direct dialogue with beverage formulation chemists, procurement directors at mid-sized manufacturers, ANVISA-registered extraction facility managers, and FSSAI regulatory consultants grounded qualitative insights. Secondary validation drew from FDA GRAS notification databases, EU EFSA additive evaluation registers, customs and trade flow records for corn syrup and tropical fruit essence, and SEC filings from publicly traded ingredient suppliers. Bottom-up volume modeling across enzymatic bioconversion capacity installations and top-down macroeconomic triangulation ensured cross-verification.
Segmented projections across ingredient type, form, application, and end-user dimensions over the projection horizon produced volume and value estimates. CAGRs were derived from historical capacity expansion rates, regulatory approval timeline trajectories, and substitution elasticity modeling between natural and synthetic sweetener categories. Forecast inputs included corn price volatility indices, stevia-leaf extraction yield improvements, and Nutri-Score mandate adoption curves across France, Belgium, and Germany.
Forecast precision tightens around the base case; tail outcomes carry wider variance under abrupt sugar taxation framework implementations or ANVISA facility disruption scenarios. Projections reflect assumptions around enzymatic bioconversion scale-up timelines and EU REACH authorization throughput rates. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Additives and Ingredients
Canada Food Emulsifiers Market
Food Additives and Ingredients
Russia Food Enzymes Market
Food Additives and Ingredients
Western Europe Food Phosphate Market
Food Additives and Ingredients
Spain Food Colorants Market
Food Additives and Ingredients
Acetylated Distarch Adipate Market
Food Additives and Ingredients
Global Organic Food Preservatives Market
Food Additives and Ingredients
Oxygen Absorbers Market
Food Additives and Ingredients
Annatto Food Colors Market
Food Additives and Ingredients
Ascorbyl Palmitate Market
Food Additives and Ingredients
Food Antimicrobial Additives Market
Food Additives and Ingredients
Emulsifiers Market
Food Additives and Ingredients
Wine Fining Agent Market
Food Additives and Ingredients
Spain Food Preservatives Market
Food Additives and Ingredients
Alcohol Additives Market
Food Additives and Ingredients
Neohesperidin Market
Food Additives and Ingredients
Salatrim Market